
 Luxury Car Market | 2026-2036
Luxury Car Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Car Market Intelligence
Software-defined vehicle architecture is rewriting how luxury automakers design, update, and monetize their products over the ownership lifecycle. BMW leverages over-the-air capability to sustain recurring revenue streams through feature subscriptions. Mercedes-Benz anchors its premium positioning with Level 3 autonomous drive systems in select markets. Porsche differentiates through performance-oriented electric platforms that preserve brand DNA while eliminating tailpipe emissions.
A luxury car denotes a passenger vehicle engineered with superior materials, advanced powertrain performance, and refined ride dynamics, typically priced above mass-market equivalents and incorporating hand-finished interior surfaces, active noise cancellation, and adaptive chassis systems for occupant comfort and status signaling. Sedans retain the largest revenue pool among vehicle types due to their historical association with executive transport and chauffeur use, though SUVs are capturing incremental volume as family-oriented buyers prioritize cabin space and commanding road presence. Electric powertrains represent the fastest-expanding segment within powertrain categories, driven by zero-emission mandates and the technical feasibility of instant torque delivery that aligns with luxury performance expectations.
China's MIIT enforces stringent new energy vehicle quotas that push luxury manufacturers toward electrified lineups, while the EU Green Deal and F-Gas Regulation constrain refrigerant choices and manufacturing emissions across European production networks. The EPA and NHTSA in the United States impose divergent fleet efficiency and safety standards that fragment platform engineering budgets. Stakeholders must monitor how regulatory fragmentation between Beijing, Brussels, and Washington shapes powertrain investment timelines and factory allocation decisions without assuming policy convergence.
Market Dynamics
Software-defined vehicle architecture is compressing traditional engineering cycles while forcing luxury marques to build recurring revenue models atop hardware platforms designed for decade-long lifespans. This shift restructures capital allocation, talent recruitment, and supplier relationships across the value chain.
Growth Catalysts
- MIIT NEV Quotas:China's mandatory new energy vehicle production thresholds compel luxury manufacturers to electrify entire lineups ahead of consumer pull.
- Solid-State Battery Development:Advances in energy density and thermal stability enable extended-range electric powertrains that match combustion-era performance expectations.
- High-Net-Worth Expansion:Wealth concentration in emerging economies generates first-time luxury buyers seeking status differentiation through premium automotive purchases.
Market Restraints
- Lithium Supply Concentration:Processing capacity clusters in specific geographies, exposing battery cost structures to geopolitical friction and export restriction risk.
- EU F-Gas Regulation:Refrigerant phase-down mandates force costly redesign of thermal management systems across European production networks.
- Semiconductor Fab Bottlenecks:Advanced node capacity constraints limit output of the high-compute chips required for autonomous and infotainment systems.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for advanced automotive technology attract local assembly investment and reduce import duty exposure.
- Feature Subscription Models:Over-the-air capability enables unbundling of comfort and performance functions into recurring revenue streams.
- Urban Air Quality Mandates:Zero-emission zones in European city centers accelerate demand for battery-electric chauffeur and executive transport vehicles.
Industry Challenges
- Embedded Software Talent Scarcity:Legacy powertrain engineers lack systems architecture skills for vehicle operating system development.
- Homologation Timeline Compression:Divergent autonomous vehicle certification pathways across jurisdictions fragment validation budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Car Market |
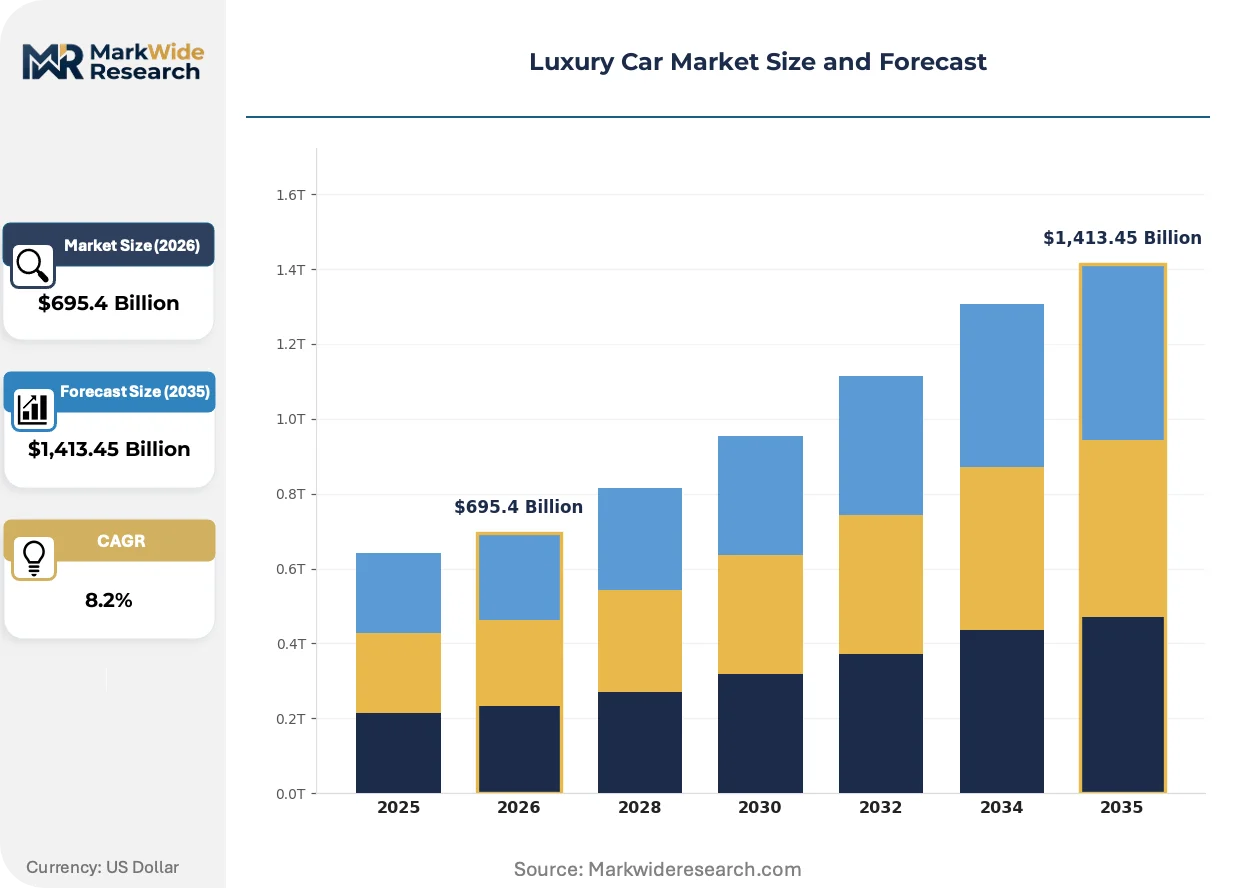
| Market Size in 2026 | $695.4 Billion |
| Market Size in 2035 | $1,413.45 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedans, SUVs, Coupes, Convertibles Powertrain: Electric, Hybrid, Gasoline, Diesel Drivetrain: AWD, RWD, FWD, 4WD Customization Option: Interior Finish, Performance Parts, Tech Upgrades, Color Options |
| Companies Covered | Genesis, Audi, BMW, Acura, Ferrari, Mercedes-Benz, Porsche, Cadillac, Lexus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Car Market Strategic Shifts & Innovations
Electrification is rewriting material science priorities and regulatory compliance frameworks while simultaneously enabling new ownership and usage models that decouple prestige from mechanical complexity.
Solid-state battery chemistry is migrating from laboratory validation to pilot production lines. Luxury manufacturers with internal cell development programs are securing offtake agreements for sulfide-based electrolyte formulations. This technology is migrating from niche concept vehicles to series-production electric flagships within the forecast window, compressing the performance gap between established and challenger marques.
REACH substance restrictions and the EU AI Act impose dual compliance burdens on interior materials and automated driving systems. Manufacturers must document supply chain chemistry while establishing algorithmic transparency for Level 3 functionality. European premium sedans face the steepest certification cost inflation as regulators demand granular disclosure of training data and decision logic.
Direct-to-consumer configuration platforms are displacing traditional dealership inventory models. Younger buyers in urban China and coastal United States markets expect factory-order personalization with compressed delivery windows. This pattern concentrates in metropolitan clusters where digital-native purchasing behavior intersects with high discretionary spending on mobility status markers.
Luxury Car Market Segmentation
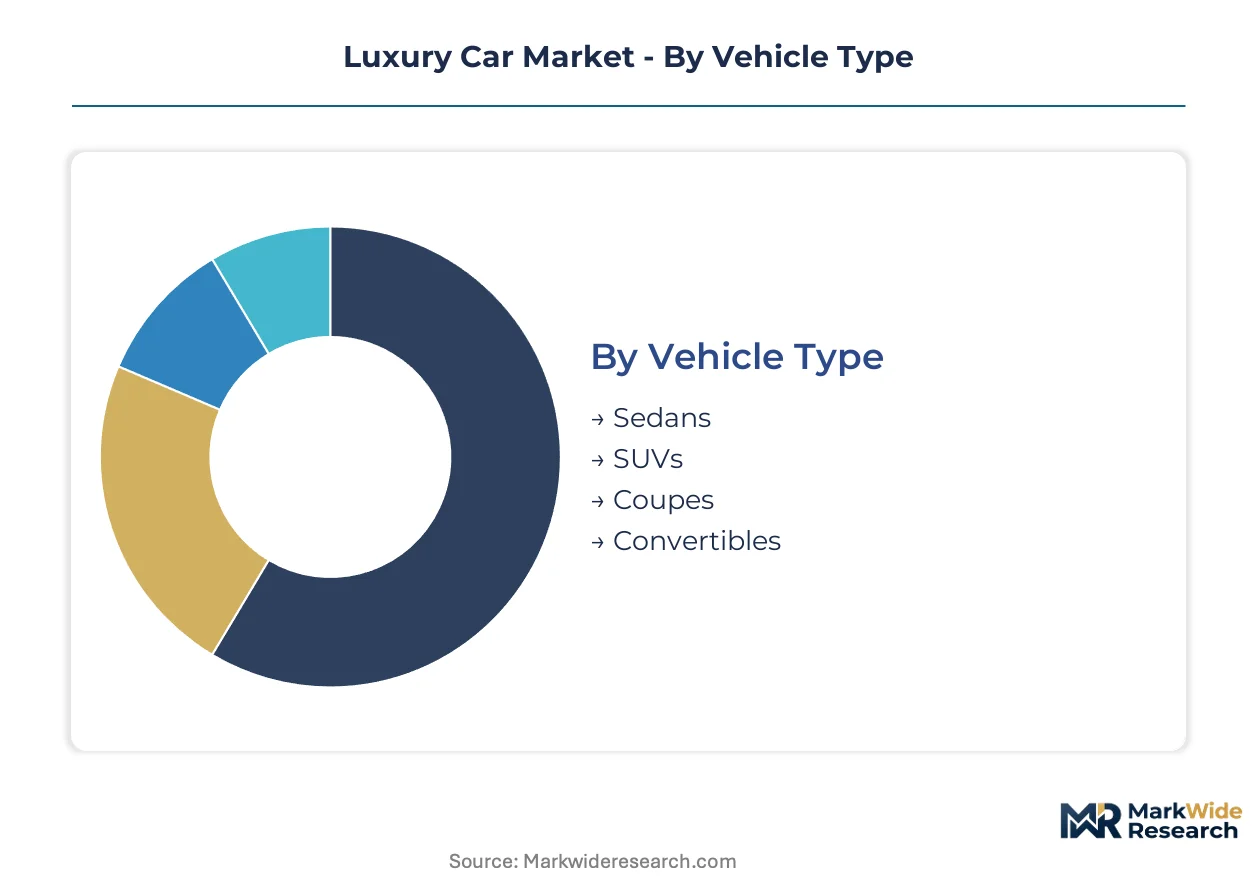
Segmentation in luxury automotive markets determines warranty cost structures, residual value trajectories, and service bay utilization patterns across dealership networks. Distinct vehicle configurations carry radically different after-sales intensity profiles, from battery thermal management schedules to bespoke interior refurbishment cycles.
Vehicle Type:
After-sales service intensity varies dramatically by body style, with chauffeur-operated sedans demanding continuous cosmetic maintenance while family-oriented SUVs concentrate wear on suspension and drivetrain components.
- Sedans:Long-wheelbase executive configurations sustain premium pricing through rear-occupant comfort systems requiring specialized technician certification. Demand concentrates in Chinese metropolitan corridors where corporate fleet procurement favors discrete, chauffeur-driven transport for senior executives navigating stringent urban emissions protocols enforced by MIIT.
- SUVs:Elevated ride heights and expanded cabin volumes accommodate battery packaging without compromising ground clearance, making this architecture preferred for electric powertrain integration. Demand clusters in suburban United States markets where driveway presence and child-safety accessibility drive purchase decisions.
- Coupes:Two-door silhouettes retain collector-market durability and lower production volumes that sustain exclusivity premiums through constrained supply.
- Convertibles:Soft-top and retractable hardtop mechanisms introduce weather-sealing complexity and seasonal usage patterns that compress annual mileage and extend ownership horizons.
By volume, SUVs lead. By growth pace, electric SUVs are climbing the fastest.
Powertrain:
Powertrain selection now determines regulatory compliance pathways rather than merely performance characteristics, with zero-emission mandates in Beijing and Brussels restructuring factory allocation decisions.
- Electric:Battery-electric architectures eliminate thermal management fluids while introducing cell degradation monitoring and high-voltage safety protocols into service operations. Demand concentrates in European urban centers where municipal zero-emission zones restrict combustion vehicle access during business hours.
- Hybrid:Plug-in and mild-hybrid configurations bridge infrastructure gaps in markets with uneven charging network density, particularly Indian metropolitan clusters where grid reliability concerns delay full electrification commitments.
- Gasoline:High-output turbocharged engines retain relevance in markets with limited charging infrastructure and in performance sub-segments where acoustic character sustains brand differentiation.
- Diesel:Compression-ignition powertrains persist in long-distance executive transport applications where thermal efficiency and refueling speed outweigh emissions scrutiny.
By installed base, gasoline retains dominance. By factory allocation shifts, electric powertrains are gaining share fastest.
Drivetrain:
Torque distribution architecture influences tire wear patterns, insurance classification, and all-weather capability positioning across climate-diverse markets.
- AWD:Full-time all-wheel-drive systems command price premiums in snow-belt United States regions and Alpine European corridors where traction confidence justifies fuel economy penalties.
- RWD:Rear-wheel-drive layouts preserve handling balance signatures favored by enthusiast segments and enable packaging efficiencies for long-hood proportions associated with traditional luxury aesthetics.
- FWD:Front-wheel-drive configurations concentrate in entry-luxury segments where cabin space maximization and production cost discipline outweigh dynamic performance priorities.
- 4WD:Part-time four-wheel-drive with low-range gearing addresses emerging market terrain requirements and recreational towing applications in Australian and Middle Eastern markets.
By production volume, AWD leads. By technology transition, integrated electric torque vectoring systems are expanding most quickly.
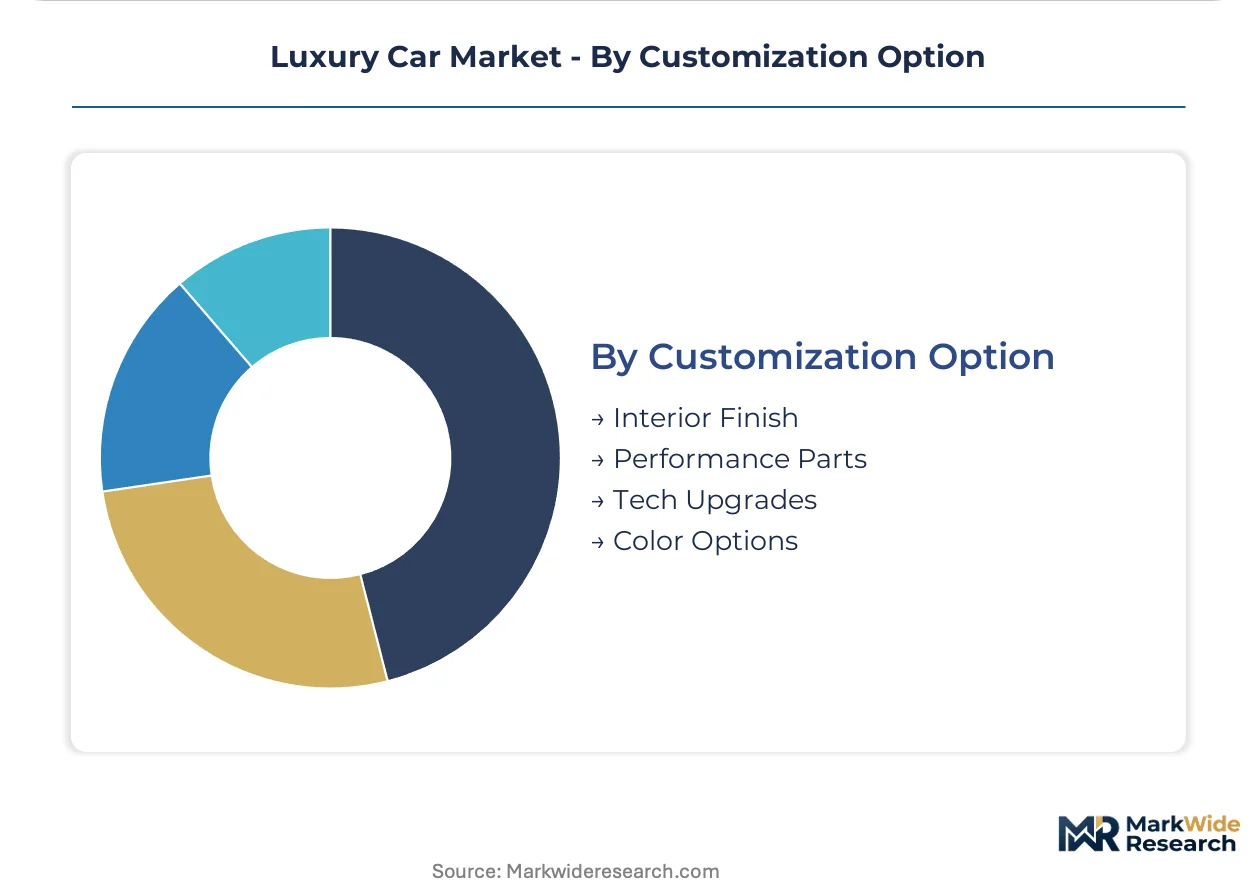
Customization Option:
Bespoke configuration intensity directly correlates with margin extraction and customer lifetime value, with factory personalization programs now extending to over-the-air feature activation post-delivery.
- Interior Finish:Hand-stitched leather grades, open-pore wood veneers, and metal inlay options extend assembly timelines while creating aftermarket refurbishment revenue streams.
- Performance Parts:Factory-approved brake, suspension, and aerodynamic upgrades preserve warranty coverage while capturing enthusiast spending that would otherwise migrate to third-party suppliers.
- Tech Upgrades:Software-defined feature subscriptions for autonomous assistance, augmented navigation, and entertainment packages convert capital expenditure into recurring revenue.
- Color Options:Extended palette selections and matte finish treatments sustain exclusivity signaling while introducing specialized repair complexity for collision networks.
By revenue contribution, interior finish leads. By margin expansion trajectory, tech upgrades are ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China runs the world's largest trade surplus in luxury vehicles, exporting battery-electric flagships while importing combustion-engine heritage marques. Germany and Japan maintain export-oriented production bases serving premium demand across emerging and mature economies. The United States absorbs substantial import volumes while cultivating domestic electrification capacity.
China
Shanghai and Beijing metropolitan clusters concentrate high-net-worth buyers seeking chauffeur-driven electric sedans for executive transport. MIIT enforces escalating new energy vehicle production quotas that compel local assembly of battery-electric lineups. Domestic manufacturers in the Yangtze River Delta region are scaling solid-state battery pilot lines to capture technology leadership.
Germany
Stuttgart and Munich anchor premium manufacturing networks where heritage marques balance combustion heritage with electrified platform development. The EU Green Deal and F-Gas Regulation constrain refrigerant choices and manufacturing emissions across production networks. Bavarian engineering centers prioritize Level 3 autonomous certification for executive sedan deployments.
United States
California and the Northeast Corridor drive battery-electric adoption among technology-sector executives and urban professionals. EPA and NHTSA impose divergent fleet efficiency standards that fragment platform engineering budgets. Detroit-area manufacturers are retooling assembly capacity toward electric SUV architectures targeting suburban family segments.
Japan
Tokyo and Osaka metropolitan areas sustain demand for precision-engineered hybrid systems bridging infrastructure gaps. METI coordinates industrial policy supporting solid-state battery research and autonomous vehicle validation. Nagoya-centered manufacturing clusters specialize in compact luxury powertrains for Asian export markets.
India
Maharashtra and Delhi-NCR generate first-time luxury purchases from expanding high-net-worth cohorts in financial services and technology sectors. The PLI scheme for advanced automotive technology attracts local assembly investment and reduces import duty exposure. Karnataka-based engineering centers develop software-defined vehicle architectures for cost-optimized premium platforms.
Luxury Car Market Key Industry Players
On the supply side, the industry is consolidating around heritage marques with century-old brand equity and emerging challengers leveraging electrification to reset competitive hierarchies. Established European and Japanese manufacturers defend position through software-defined architectures and recurring revenue models. Three archetypes dominate: heritage combustion-era marques transitioning powertrains, technology-native challengers, and conglomerate-backed volume-luxury hybrids. Competitive intensity centers on M&A activity securing battery supply chains and strategic partnerships for autonomous system development.
Within the heritage European tier, Mercedes-Benz, BMW, and Porsche exemplify the engineering-intensive archetype balancing performance DNA with electrification mandates. These Stuttgart and Munich-based manufacturers occupy positions where software subscription revenue and Level 3 autonomous certification differentiate premium positioning. Ferrari represents the ultra-exclusive volume-constrained archetype where collector-market durability sustains pricing power independent of powertrain technology transitions.
| Leading Market Players |
|---|
| Genesis |
| Audi |
| BMW |
| Acura |
| Ferrari |
| Mercedes-Benz |
| Porsche |
| Cadillac |
| Lexus |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta battery manufacturing cluster commands decisive leverage over luxury electric vehicle pricing through its dominance of cathode active material processing and cell assembly capacity. OEM procurement teams face compressed negotiation margins as this concentration enables tier-one suppliers to enforce take-or-pay contracts for high-nickel chemistry formulations.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by solid-state battery certification status and software-defined feature activation bundles. Price compression in the standard tier intensifies as Chinese domestic brands escalate specification-for-specification competition against established European marques. Fleet procurement divisions demonstrate highest price sensitivity, while individual collectors of limited-production coupes exhibit near-zero elasticity.
Supply Chain Analysis
US semiconductor export controls on advanced-node GPU and AI accelerator chips constrain autonomous driving system development timelines for European and Asian manufacturers dependent on NVIDIA and Qualcomm silicon. Lithium hydroxide processing concentrates in China, South Korea, and Australia, while cobalt sulfate supply draws from the DRC and Indonesian integrated operations. Single-source vulnerability in solid-state electrolyte precursor chemicals threatens platform launch schedules. Distribution runs through franchised dealership networks transitioning to agency-model direct sales in metropolitan China and coastal United States markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The luxury automotive sector faces high-growth disruption as solid-state battery commercialization and Level 3 autonomous certification rewrite engineering investment priorities and margin structures.
For Market Incumbents: Harden software-defined vehicle architecture defenses by securing exclusive semiconductor foundry capacity for autonomous compute chips and accelerating in-house operating system development. Threats from technology-native challengers leveraging direct-to-consumer distribution models demand immediate channel control investments in China and California. Vertical integration into solid-state cell production represents the critical lever for sustaining battery cost parity. For New Entrants and Emerging Players: Chauffeur-driven electric sedans in tier-two Chinese metropolitan clusters represent the most penetrable entry point, with underserved demand from provincial enterprise executives seeking status differentiation below flagship European pricing. Battery-electric performance SUVs for suburban United States families present secondary white-space opportunity. Go-to-market execution should emphasize factory-direct configuration platforms with sub-90-day delivery commitments. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because recurring software revenue streams and battery supply chain captivity will determine enterprise valuations rather than unit production scale. Acquisition targets should display proven over-the-air monetization infrastructure and secured lithium offtake agreements. The signal to watch is MIIT NEV quota enforcement intensity and its acceleration of domestic brand share capture.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures cathode material offtake from Yangtze River Delta processors for platform scale-up. |
| Software-Defined Vehicle Investment | Enables subscription revenue extraction through Mercedes-Benz-style feature unbundling architecture. |
| Geographic Manufacturing Footprint | Localizes assembly in Maharashtra under India's PLI scheme to neutralize import duty exposure. |
| Charging Infrastructure Partnership | Integrates with State Grid Corporation networks across Beijing-Shanghai corridor for fleet accessibility. |
| Platform Standardization | Consolidates electric architectures across Porsche and Audi lineups to amortize R&D across volume. |
Research Approach
Findings reconcile primary fieldwork against secondary review of MIIT production filings, EU vehicle registration databases, and OEM financial disclosures. Interviews with Tier 1 supplier procurement directors, OEM platform engineering leads, dealership operations managers, and aftermarket service heads informed demand-side validation. Trade flow analysis, IHS Markit production data, and customs records provided supply-side triangulation through bottom-up and top-down reconciliation.
Forecast inputs span vehicle class segmentation, propulsion architecture transitions, content-per-vehicle trajectories, and regional production cluster capacity allocation. CAGRs derive from modeled adoption curves for solid-state battery integration and autonomous feature penetration. Battery cost decline trajectories, MIIT quota enforcement schedules, and charging infrastructure density projections anchor the analytical framework across the projection horizon.
Stress conditions across lithium price volatility, semiconductor export restriction escalation, and EU F-Gas Regulation compliance cost inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on technology readiness timelines and regulatory enforcement intensity. Material shifts in solid-state battery mass-production yields or Level 3 autonomous certification pathway divergence would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
Lightweight Cars Market
Passenger Vehicles
Microcars Market
Passenger Vehicles
Passenger Vehicle Market
Passenger Vehicles
Russia Light Vehicle Market
Passenger Vehicles
Sports Utility Vehicles (Suvs) Market
Passenger Vehicles
India Automotive Market
Passenger Vehicles
Family Car Market
Passenger Vehicles
Latin America Passenger Car Market
Passenger Vehicles
Europe Luxury Car Market
Passenger Vehicles
Large Suvs Market
Passenger Vehicles
Train Market
Passenger Vehicles
Automotive Luxury Vehicle Market
Passenger Vehicles
Inland Water Passenger Transport Market
Passenger Vehicles
Three-Wheeler Vehicle Market
Passenger Vehicles
Compact Cars Market
Passenger Vehicles
North America Automotive Market