
 Quadricycle and Tricycle Market | 2026-2036
Quadricycle and Tricycle Market Size, Share, and Industry Trends Forecast 2026-2036
Quadricycle and Tricycle Market Intelligence
The EU Green Deal is restructuring demand patterns for low-speed urban mobility vehicles across European municipalities. Ligier Group leverages its Aixam acquisition to dominate the European electric quadricycle segment with dedicated manufacturing in France. Piaggio & C. S.p.A. sustains competitive positioning through its Porter platform, which competes in both commercial tricycle and light quadricycle categories. Groupe Renault anchors its mobility division around the Twizy architecture, specializing in battery-integrated chassis designs for urban car-sharing operators.
Quadricycles and tricycles comprise three- and four-wheeled motorized or human-powered vehicles with maximum design speeds typically capped below 45 km/h and unladen weights under 400 kg for quadricycles; these specifications position them between bicycles and full passenger cars for urban freight and personal transport. Electric quadricycles capture the fastest-growing segment as municipal low-emission zones expand across European cities, while motorized tricycles occupy the largest volume pool due to entrenched last-mile delivery dependence in South Asian markets. Manual tricycles retain stable demand among recreational users and rental operators in North American coastal cities, though this tier commands thinner margins than electrified alternatives.
The EU F-Gas Regulation and CE marking requirements shape powertrain and refrigerant choices for electric quadricycles sold in Europe, while India's CEA and BIS standards govern battery safety and motor efficiency for motorized tricycles deployed in commercial fleets. The US NHTSA and EPA maintain distinct classification thresholds that determine whether imported quadricycles face motorcycle or automobile compliance burdens, directly affecting market access costs for foreign manufacturers. Stakeholders must monitor how evolving national type-approval frameworks reconcile micro-mobility innovation with occupant safety mandates.
Market Dynamics
Urban congestion and municipal low-emission zone expansion are forcing fleet operators to recalibrate last-mile vehicle procurement toward sub-45 km/h electrified platforms. This structural pressure is compressing the traditional cost advantage of internal-combustion tricycles in dense metropolitan corridors.
Growth Catalysts
- EU Green Deal vehicle reclassification:The framework accelerates type-approval pathways for electric quadricycles in French and Italian urban centers, reducing homologation timelines for municipal car-sharing tenders.
- Last-mile delivery fleet densification:Indian e-commerce logistics operators are expanding motorized tricycle deployment as traffic velocity in Bengaluru, Mumbai, and Delhi falls below 15 km/h during peak hours.
- Battery energy density improvements:Lithium-iron-phosphate cell chemistry advances are extending electric quadricycle range without exceeding 400 kg unladen weight thresholds, preserving L6e classification benefits.
Market Restraints
- Lithium supply concentration:Cathode material processing dependence on Chinese refining capacity exposes European electric quadricycle assemblers to input cost volatility and tariff exposure.
- CE marking complexity:The EU F-Gas Regulation refrigerant mandates and electromagnetic compatibility testing create multi-month certification delays for battery thermal management system redesigns.
- Two-wheeler substitution:Electric scooters and cargo bicycles capture overlapping urban freight missions at lower capital outlay, pressuring motorized tricycle volume in price-sensitive segments.
Strategic Opportunities
- Indian commercial fleet electrification:The country's PLI scheme for automotive manufacturing offers cell production incentives that could localize battery supply for motorized tricycle OEMs serving Swiggy and Zomato logistics networks.
- Intermodal freight integration:Electric quadricycles are penetrating rail-adjacent micro-hubs in German and Dutch cities, bridging final-100-meter gaps from transit stations to residential addresses.
- Subscription mobility platforms:Tiered access models for urban car-sharing operators in Paris and Milan reduce consumer ownership burdens while locking in manufacturer service revenue streams.
Industry Challenges
- Battery thermal management engineering:OEMs face skill scarcity in integrating active cooling systems that satisfy CEA safety standards for Indian tropical operating conditions without breaching weight limits.
- Homologation timeline compression:Divergent national type-approval frameworks between EU member states and India's BIS certification requirements force parallel testing tracks that strain R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quadricycle and Tricycle Market |
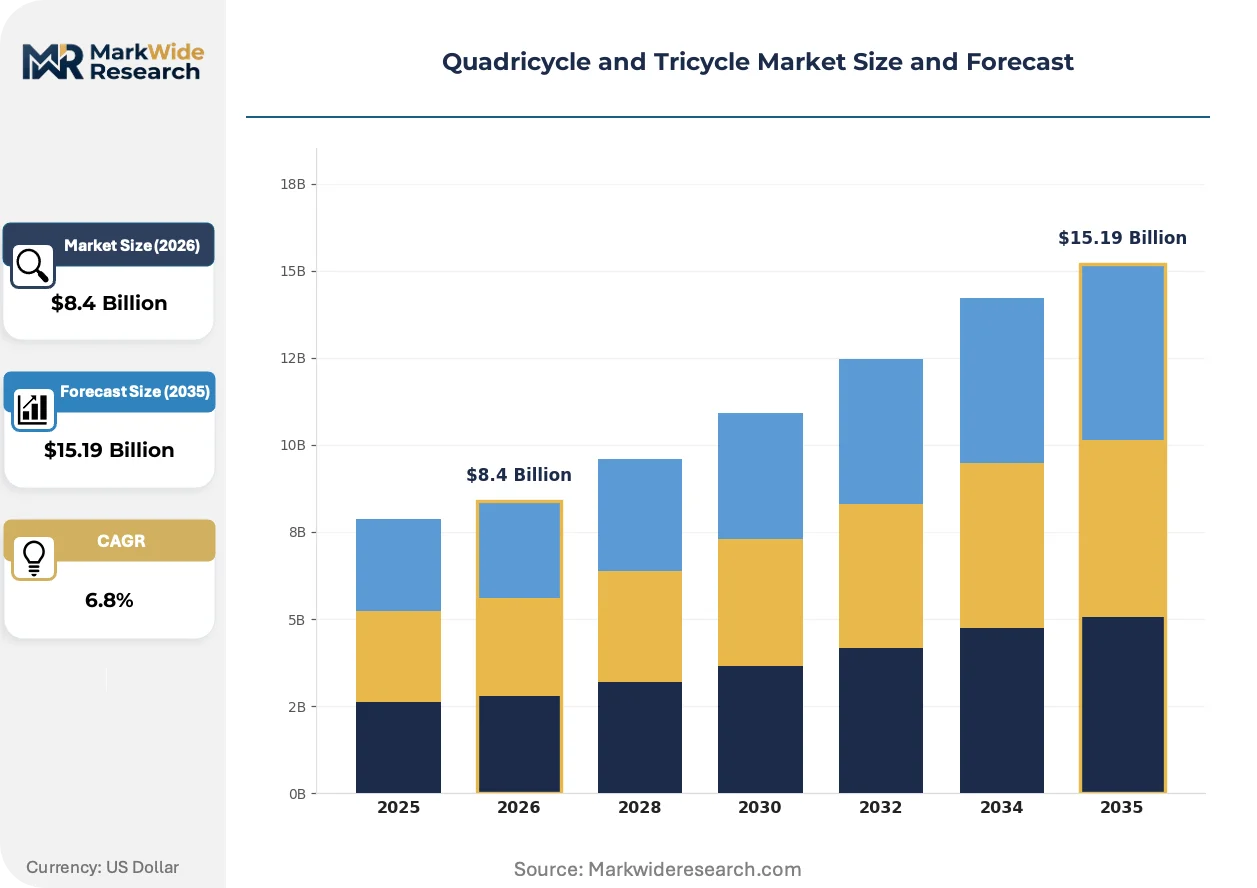
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Quadricycles, Gasoline Quadricycles, Manual Tricycles, Motorized Tricycles End User: Urban Commuters, Rental Operators, Delivery Services, Recreational Users Distribution Channel: Online Retailers, Dealerships, Direct Sales, Rental Agencies Price Tier: Affordable, Mid-Range, Premium, Luxury |
| Companies Covered | Ligier Group, Piaggio & C. S.p.A., Groupe Renault, TVS Motor Company Ltd., Polaris Inc., Bajaj Auto Ltd., Aixam-Mega SAS, Worksman Cycles, Mahindra and Mahindra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quadricycle and Tricycle Market Strategic Shifts & Innovations
Electrification is penetrating vehicle architectures previously optimized for mechanical simplicity, while regulatory fragmentation accelerates regional specialization in powertrain design. These forces are compressing product development cycles and rewarding modular platform strategies.
Modular battery-swapping architectures are integrating into commercial tricycle fleets serving Indian food-delivery aggregators. Sun Mobility and similar infrastructure operators deploy automated exchange stations across Hyderabad and Chennai, enabling 24-hour utilization rates without depot charging downtime. This architecture is integrating asset-light fleet economics by transferring battery capital burden from logistics operators to energy service providers.
The EU F-Gas Regulation is prohibiting high-global-warming-potential refrigerants in electric quadricycle climate systems from 2025. Manufacturers must redesign thermal loops using CO2 or hydrocarbon alternatives, adding engineering cost but creating regulatory moats against non-compliant imports. French and Italian municipal procurement tenders now embed refrigerant compliance as a mandatory evaluation criterion.
Fleet managers are consolidating vendor relationships around vertically integrated platform providers capable of delivering vehicle, battery, and telematics bundles under unified service contracts. This pattern displaces the historical fragmentation between chassis assemblers, motor suppliers, and aftermarket maintenance networks. German urban logistics operators exhibit the most pronounced concentration, with DHL and Amazon Fresh standardizing on single-source electric quadricycle configurations for Berlin and Hamburg depots.
Quadricycle and Tricycle Market Segmentation
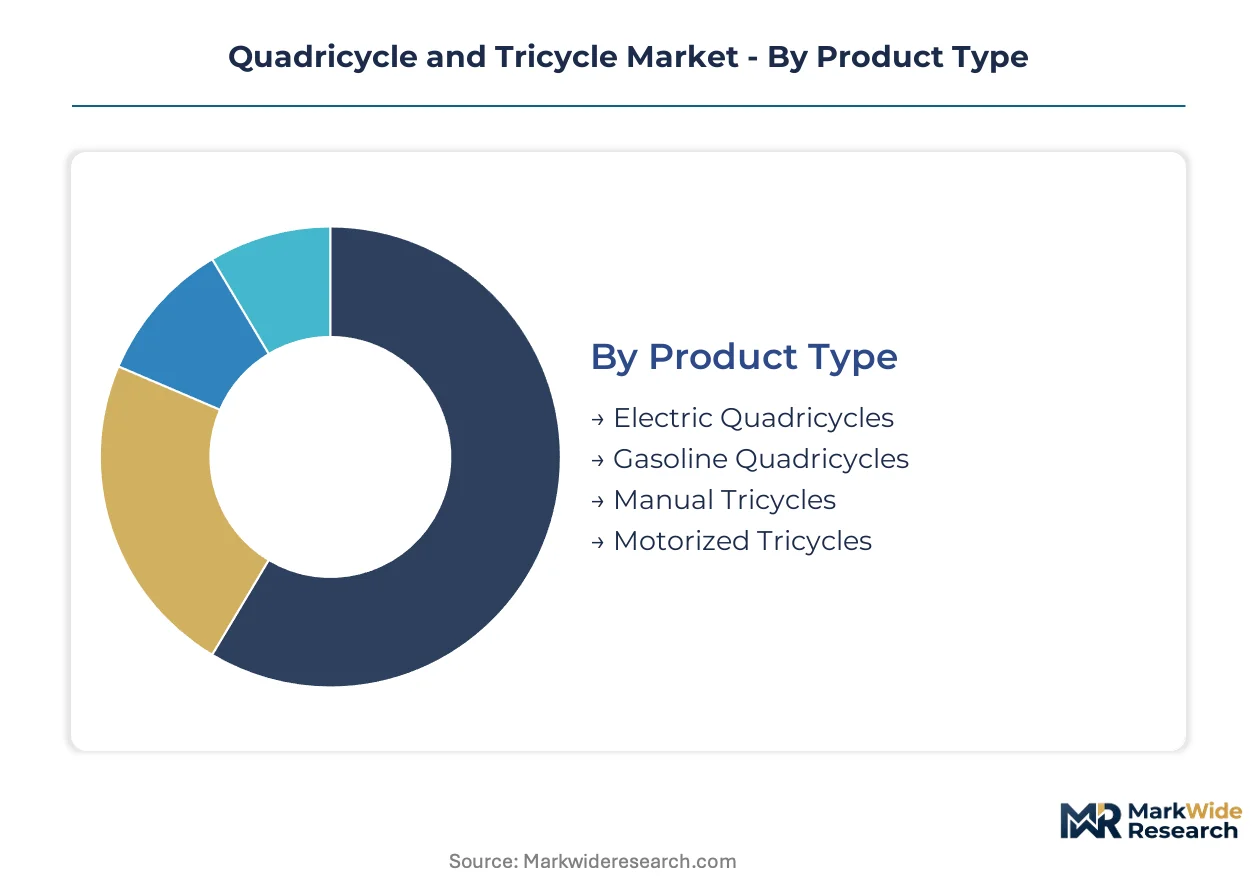
Segmentation in the Quadricycle and Tricycle Market reveals how powertrain economics, fleet procurement patterns, and municipal procurement frameworks partition demand across distinct customer archetypes. Understanding these divides exposes where margin pools concentrate versus where volume saturates.
Product Type:
Motorized tricycles dominate unit volumes while electric quadricycles command premium pricing and fastest growth trajectories in European urban centers.
- Electric Quadricycles:Battery-powered four-wheeled vehicles capped at 45 km/h, integrating L6e-compliant chassis designs with lithium-iron-phosphate packs. Demand concentrates in French and Italian municipal car-sharing tenders where EU Green Deal funding subsidizes fleet procurement and dedicated micro-mobility lanes reduce collision risk.
- Motorized Tricycles:Three-wheeled internal-combustion or electric platforms optimized for 150-500 kg cargo capacity. Indian e-commerce logistics operators in Bengaluru and Mumbai deploy these for last-mile delivery as traffic velocity drops below 15 km/h during peak congestion windows.
- Manual Tricycles:Human-powered three-wheelers serving recreational and short-haul freight applications.
- Gasoline Quadricycles:Internal-combustion four-wheelers facing structural decline as low-emission zones expand across European cities.
Today's leader: Motorized Tricycles. Tomorrow's challenger: Electric Quadricycles.
End User:
Fleet operators drive commercial procurement while individual ownership patterns diverge sharply between European subscription users and South Asian independent contractors.
- Delivery Services:Logistics aggregators and food-delivery platforms operating centralized procurement for 500+ vehicle depots. Swiggy and Zomato networks in India standardize on motorized tricycle configurations with modular battery-swapping compatibility, transferring capital burden to Sun Mobility infrastructure providers.
- Rental Operators:Urban car-sharing platforms and tourist-cycle fleets purchasing vehicles under multi-year service contracts. Paris and Milan operators prioritize electric quadricycles with telematics integration for real-time utilization tracking and dynamic pricing optimization.
- Urban Commuters:Individual purchasers seeking personal mobility solutions for sub-10 km daily trips.
- Recreational Users:Coastal tourism markets and leisure cyclists in North American cities.
Delivery Services extract maximum utilization rates. Rental Operators capture highest per-trip margins.
Distribution Channel:
Channel selection tracks customer scale and service intensity requirements, with fleet sales bypassing traditional retail entirely.
- Direct Sales:OEM-to-fleet transactions for 50+ unit orders, bundling vehicles with maintenance contracts and telematics subscriptions. DHL and Amazon Fresh in Berlin and Hamburg standardize on single-source electric quadricycle configurations through direct procurement agreements.
- Dealerships:Franchise and independent retailers serving individual purchasers and small commercial operators in secondary cities.
- Online Retailers:Digital platforms facilitating specification comparison and financing for dispersed individual buyers.
- Rental Agencies:Specialized lessors providing vehicle-as-a-service models for seasonal or trial usage.
Direct Sales lock in manufacturer service revenue. Dealerships retain relevance where post-sale maintenance infrastructure remains fragmented.
Price Tier:
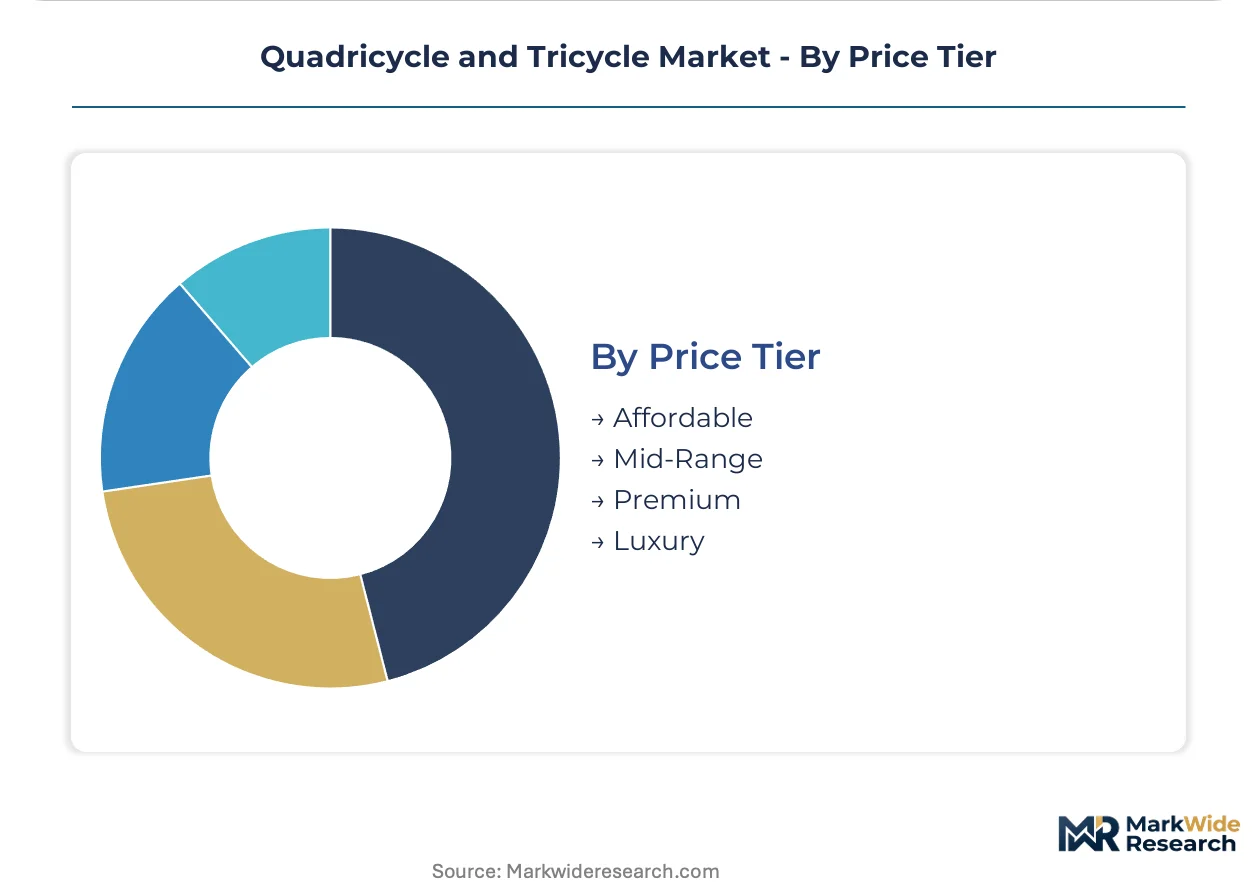
Pricing stratification reflects powertrain complexity, certification grade, and bundled service intensity rather than raw materials alone.
- Premium:Electric quadricycles with active thermal management, CO2-based climate systems, and integrated telematics platforms. EU F-Gas Regulation compliance and CE marking certification elevate engineering costs, creating regulatory moats against non-compliant imports in French municipal tenders.
- Mid-Range:Simplified electric architectures and upgraded gasoline platforms targeting small fleet operators.
- Affordable:Basic motorized tricycles with lead-acid or entry-level lithium batteries for price-sensitive Indian independent contractors.
- Luxury:Bespoke configurations with extended-range battery packs and custom chassis finishes for European private collectors.
Premium tier commands widest manufacturer margins. Affordable tier absorbs maximum competitive pressure from electric two-wheeler substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France pioneered the modern quadricycle category through Aixam's commercialization of L6e-class vehicles in the 1990s, establishing regulatory templates that Italy and Germany later adapted. This Franco-Italian axis now concentrates electric micro-mobility manufacturing and municipal procurement standard-setting.
France
Municipal car-sharing operators in Paris and Lyon drive electric quadricycle procurement through EU Green Deal subsidized tenders. The EU F-Gas Regulation mandates CO2-based climate systems from 2025, elevating engineering requirements for domestic assemblers. Ligier Group maintains dedicated manufacturing in Aix-les-Bains, supplying chassis-integrated battery platforms to urban logistics fleets.
Italy
Piaggio & C. S.p.A. anchors commercial tricycle production in Pontedera, exporting Porter-platform vehicles to Indian and Southeast Asian markets. The country's national automotive regulator enforces CE marking protocols that align with EU type-approval frameworks for low-speed electric vehicles. Milan's micro-mobility infrastructure investments concentrate rental operator demand for telematics-integrated quadricycles.
India
Swiggy and Zomato logistics networks in Bengaluru, Mumbai, and Delhi procure motorized tricycles as traffic velocity drops below 15 km/h during peak congestion. The CEA and BIS standards govern battery safety and motor efficiency for commercial fleet deployment. Sun Mobility operates automated battery-swapping stations across Hyderabad and Chennai, enabling 24-hour utilization rates for food-delivery aggregators.
Germany
DHL and Amazon Fresh standardize on single-source electric quadricycle configurations for Berlin and Hamburg depots, consolidating vendor relationships around unified service contracts. The KBA administers type-approval pathways that interface with EU L6e classification thresholds. Rail-adjacent micro-hubs in Frankfurt and Munich deploy quadricycles for final-100-meter freight bridging from transit stations.
United States
Recreational manual tricycle demand concentrates in North American coastal cities, though this segment commands thinner margins than electrified alternatives. The NHTSA and EPA maintain distinct classification thresholds determining whether imported quadricycles face motorcycle or automobile compliance burdens. Polaris Inc. and Worksman Cycles serve rental operators and leisure cyclists through differentiated channel strategies.
Quadricycle and Tricycle Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification-grade and thermal-management sophistication, with regulatory compliance creating defendable tier separation. The vendor base stratifies between integrated platform providers and component assemblers dependent on third-party battery and motor supply. Three archetypes dominate: European electric quadricycle specialists with captive L6e homologation expertise, Indian motorized tricycle fabricators serving price-sensitive logistics networks, and diversified automotive conglomerates leveraging passenger-car component economies. Competitive moves concentrate on backward integration into battery cell supply and geographic licensing partnerships that transfer homologation burden to local joint-venture partners.
Among European specialists, Ligier Group, Aixam-Mega SAS, and Piaggio & C. S.p.A. exemplify the platform-integrated archetype, occupying positions where EU regulatory moats intersect with municipal procurement concentration. These France and Italy-based entities represent the premium-tier vector through their historical participation in L6e-class vehicle standard-setting and sustained relationships with urban car-sharing operators. TVS Motor Company Ltd. and Bajaj Auto Ltd. sit within the volume-driven motorized tricycle segment, anchoring supply to Indian commercial fleet operators through cost-optimized architectures. Mahindra and Mahindra occupies a diversified position spanning both agricultural equipment heritage and emerging electric mobility portfolios.
| Leading Market Players |
|---|
| Ligier Group |
| Piaggio & C. S.p.A. |
| Groupe Renault |
| TVS Motor Company Ltd. |
| Polaris Inc. |
| Bajaj Auto Ltd. |
| Aixam-Mega SAS |
| Worksman Cycles |
| Mahindra and Mahindra |
| Others |
Cost & Logistics Intelligence
Lithium-iron-phosphate cell costs cascade through electric quadricycle pricing tiers from French L6e-certified platforms down to Indian motorized tricycle battery packs, with cathode material processing concentration in Chinese refining capacity transmitting volatility downstream to fleet procurement budgets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs the market, with EU F-Gas Regulation compliance and CE marking certification elevating premium-tier engineering costs while volume-scale procurement compresses economy-tier margins. Price differentiation hinges on thermal management sophistication and telematics bundling intensity. Pricing pressure stems from electric two-wheeler substitution in Indian last-mile logistics. Fleet operators exhibit lowest price sensitivity; independent contractors face acute cost compression.
Supply Chain Analysis
Skilled thermal systems engineers concentrate in France and Italy, where Aix-les-Bains and Pontedera manufacturing clusters anchor L6e-platform production, while Indian Chennai and Pune hubs supply motorized tricycle fabricators. Battery cell supply draws from Chinese cathode processing, South Korean electrolyte production, and Japanese separator technology. Single-source vulnerability in lithium refining exposes assemblers to tariff exposure. Distribution runs through OEM-direct fleet contracts for 50-plus unit orders, bypassing traditional retail channels entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Quadricycle and Tricycle Market reads as a late-cycle quality story where municipal procurement tenders in France and Italy now embed refrigerant compliance and telematics integration as mandatory evaluation criteria, shifting demand toward premium specifications.
For Market Incumbents: Anticipate margin compression from electric cargo bicycle substitution by deepening backward integration into battery thermal management engineering and securing captive L6e homologation expertise through certification-track R&D investment. Prioritize channel control via unified service contracts bundling vehicle, battery, and telematics for German logistics operators. For New Entrants and Emerging Players: Enter via battery-swapping infrastructure partnerships with Indian food-delivery aggregators, where asset-light fleet economics transfer capital burden from operators to energy service providers. Target rail-adjacent micro-hub deployments in Dutch and German cities for final-100-meter freight bridging. Pursue municipal car-sharing tender participation in Milan and Paris with CO2-compliant climate system configurations. For Investors and Strategic Acquirers: Consolidation pressure builds where homologation timeline compression strains R&D budgets and parallel EU-India certification tracks fragment vendor economics. Long-term viability favors integrated platform providers with captive battery supply and geographic licensing partnerships. Monitor lithium supply concentration and CE marking delay patterns as inflection indicators for margin trajectory shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Ligier Group leverages Aixam chassis architectures across multiple municipal tender specifications in France. |
| Battery Supply Agreement | Indian OEMs secure cell procurement under PLI scheme incentives serving Swiggy and Zomato networks. |
| Software-Defined Vehicle Investment | Telematics integration enables real-time utilization tracking for Paris and Milan rental operators. |
| Geographic Manufacturing Footprint | Piaggio anchors Porter-platform production in Pontedera for Indian and Southeast Asian export markets. |
| Charging Infrastructure Partnership | Sun Mobility deploys automated exchange stations across Hyderabad and Chennai for 24-hour fleet utilization. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM platform engineers, fleet procurement managers at DHL and Amazon Fresh, municipal tender administrators in Paris and Milan, and battery systems specialists at Sun Mobility with secondary validation from EU type-approval databases, Indian CEA safety filings, vehicle production registries, and customs trade records. Bottom-up segment sizing and top-down macro anchoring were cross-checked for consistency.
Comparable historical periods anchored the projection horizon across powertrain technology transitions and regulatory phase-in schedules. The analytical framework modeled demand by product type, end-user archetype, distribution channel intensity, and price tier certification grade. CAGRs were derived from segment-level growth trajectory analysis. Forecast inputs incorporated battery energy density improvement curves and municipal low-emission zone expansion schedules.
The model holds under stable lithium supply conditions and consistent EU-India regulatory divergence; deviation in cathode material processing tariffs or accelerated F-Gas Regulation enforcement would shift volume trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
Sports Utility Vehicles (Suvs) Market
Passenger Vehicles
India Automotive Market
Passenger Vehicles
Luxury Car Market
Passenger Vehicles
Medium Cars Market
Passenger Vehicles
North American Lightweight Car Market
Passenger Vehicles
Train Seat Market
Passenger Vehicles
India Luxury Car Market
Passenger Vehicles
Inland Water Passenger Transport Market
Passenger Vehicles
Lightweight Cars Market
Passenger Vehicles
Small Suvs Market
Passenger Vehicles
Compact Cars Market
Passenger Vehicles
Passenger Vehicle Market
Passenger Vehicles
South America Passenger Cars Market
Passenger Vehicles
Limousines Market
Passenger Vehicles
Automotive Passenger Vehicle Sensor Market
Passenger Vehicles
China Luxury Car Market