
 India Automotive Market | 2026-2036
India Automotive Market Size, Share, and Industry Trends Forecast 2026-2036
India Automotive Market Insights
Fleet operator demand is broadening beyond traditional logistics into ride-sharing and last-mile delivery segments. Tata Motors anchors its position through in-house battery production and electric platform development. Mahindra & Mahindra dominates rural and semi-urban utility vehicle demand with its Bolero and Scorpio franchises. Maruti Suzuki India leverages its unmatched dealership density to sustain volume leadership across entry-level passenger cars.
India automotive encompasses the design, manufacture, and sale of passenger cars, commercial vehicles, two-wheelers, and three-wheelers powered by internal combustion, electric, or alternative fuel systems, with gross vehicle weights ranging from under 100 kg for mopeds to over 40 tonnes for heavy trucks. The sector serves personal mobility, goods transport, public transit, and agricultural applications across a population exceeding 1.4 billion. Two-wheelers occupy the largest volume tier, reflecting affordability constraints and congested urban infrastructure. Electric drivetrains within the fuel type segment attract capital allocation fastest, though penetration remains nascent outside premium urban pockets. Connected vehicle technology lags hybrid adoption but offers higher software-margin potential as 4G and eventual 5G coverage deepens.
BIS mandates crash-test and emission standards that OEMs must satisfy for type approval, while CEA regulations shape charging infrastructure interconnection for electric variants. The PLI scheme administered by DPIIT conditions subsidy disbursement on domestic value-addition thresholds, redirecting supplier investment from imports to local forging, casting, and electronics assembly. Stakeholders must weigh whether to commit capital to Maharashtra-Tamil Nadu-Gujarat manufacturing corridors or pursue greenfield capacity in emerging industrial zones as state-level incentive competition intensifies.
Market Dynamics
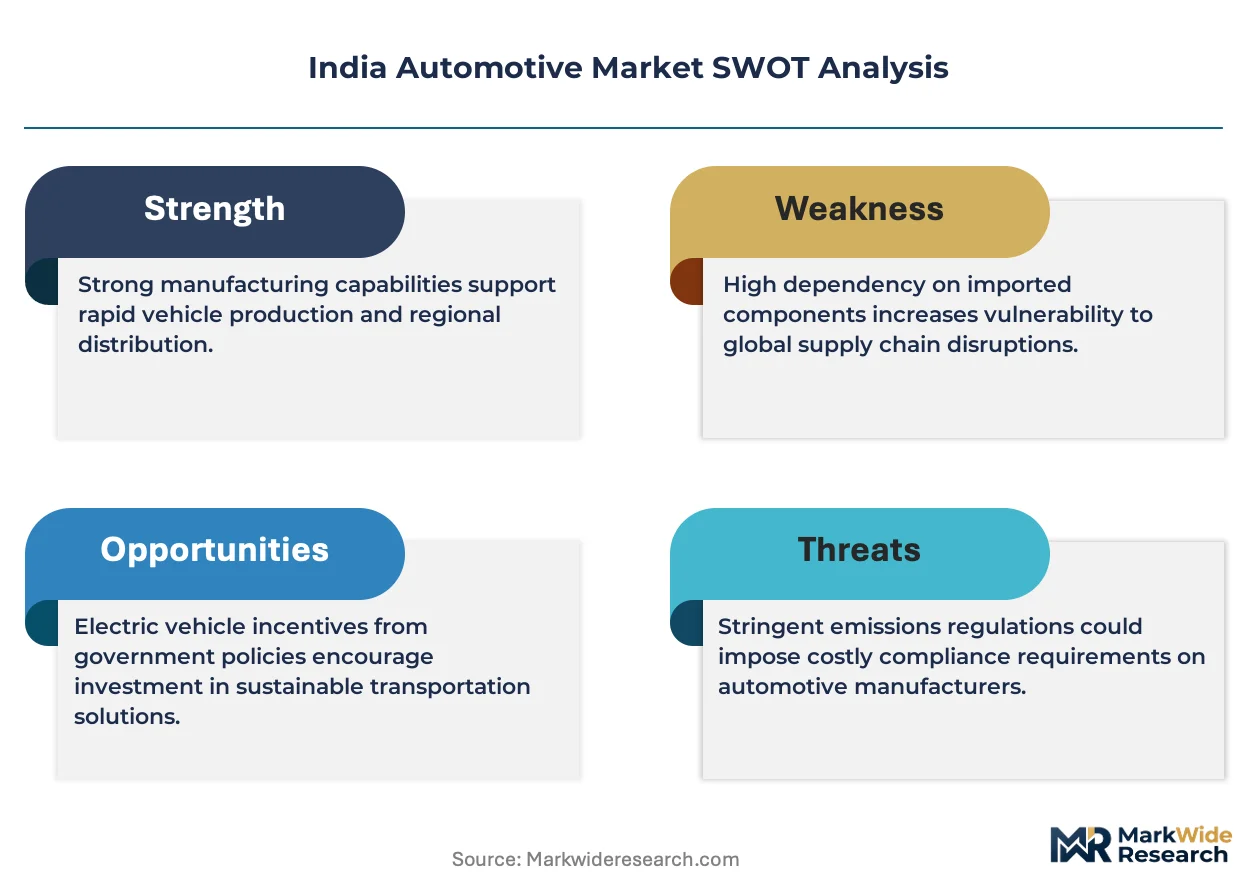
The PLI scheme administered by DPIIT is redirecting supplier investment from imports toward domestic forging, casting, and electronics assembly, compressing lead times for electric drivetrain components while intensifying state-level incentive competition for manufacturing corridors.
Growth Catalysts
- Fleet operator procurement:Commercial mobility demand is pulling fresh vehicle orders across ride-sharing and last-mile delivery segments, with logistics operators expanding contract terms.
- CEA charging infrastructure rules:Grid interconnection standards for electric variants are clarifying capital deployment timelines for charging network operators.
- Maharashtra-Tamil Nadu-Gujarat clustering:OEM assembly plants and supplier parks around Chennai, Pune, and Ahmedabad are concentrating component ecosystem density.
Market Restraints
- Lithium-ion cell import dependence:Domestic battery manufacturing lacks upstream cathode and electrolyte supply, exposing assemblers to raw material volatility.
- BIS crash-test compliance costs:Type approval mandates for passenger vehicles require capital-intensive testing infrastructure that excludes smaller assemblers.
- Semi-urban charging deserts:Electric drivetrain penetration stalls outside premium urban pockets where grid reliability and service networks thin.
Strategic Opportunities
- Semi-urban utility vehicle gaps:Rural and semi-urban demand for ruggedized transport remains underserved by current electric platform offerings.
- Connected vehicle software stacks:4G and eventual 5G coverage deepening enables over-the-air update revenue models previously captured by hardware margins.
- State-level greenfield zones:Emerging industrial corridors outside Maharashtra-Tamil Nadu-Gujarat are offering competitive land and power tariffs to attract supplier migration.
Industry Challenges
- Power electronics engineering scarcity:Inverter and motor control design talent concentrates with established Tier 1 suppliers, constraining new entrant ramp speed.
- PLI domestic value-addition thresholds:Subsidy disbursement conditions require rapid localization of forging, casting, and electronics assembly with compressed supplier qualification windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Automotive Market |
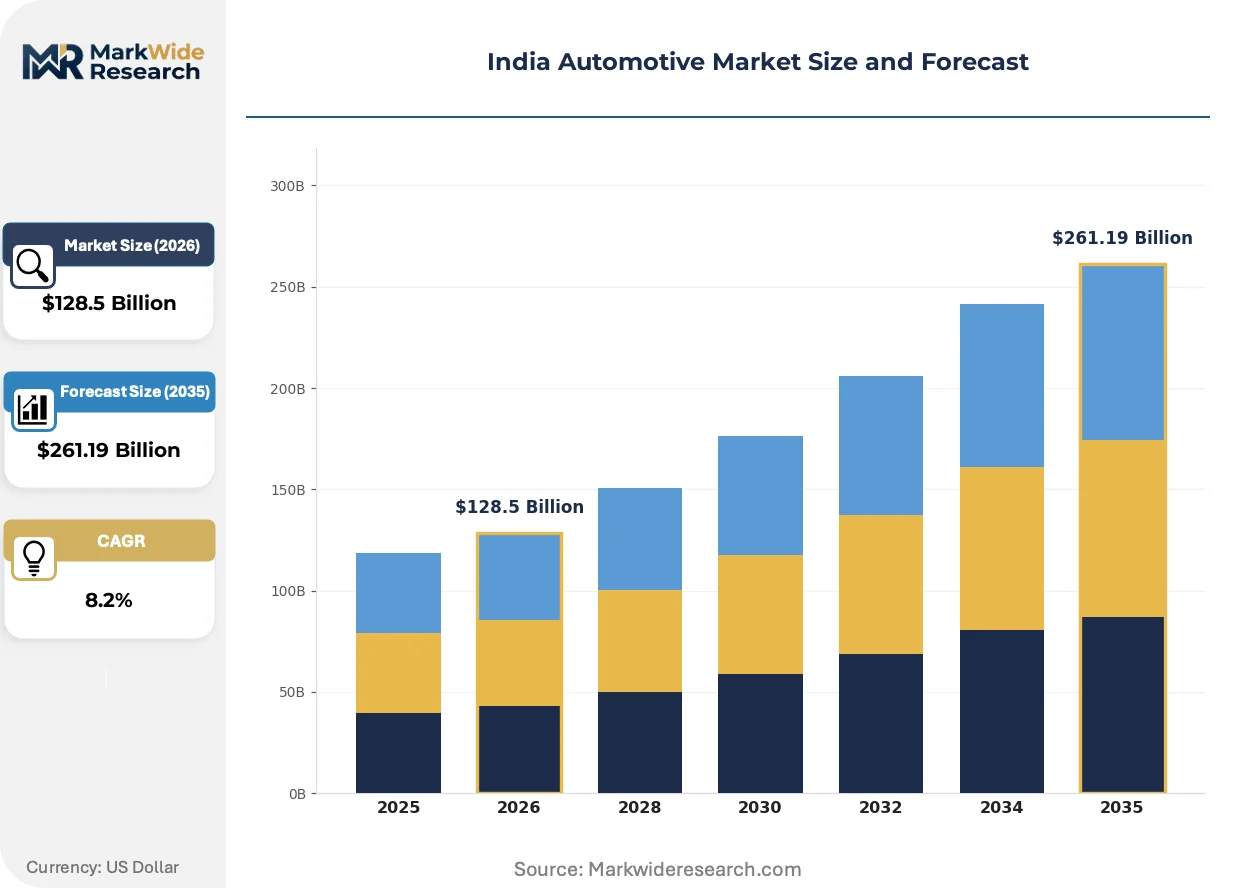
| Market Size in 2026 | $128.5 Billion |
| Market Size in 2035 | $261.19 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Cars, Commercial Vehicles, Two-Wheelers, Three-Wheelers End User: Individual Consumers, Fleet Operators, Government Agencies, Ride-Sharing Services Fuel Type: Petrol, Diesel, Electric, CNG Technology: Hybrid, Autonomous, Connected, Traditional |
| Companies Covered | Maruti Suzuki India, Hyundai Motor India, Tata Motors, Mahindra & Mahindra, Toyota Kirloskar Motor, Kia India, Honda Cars India, Bajaj Auto, Hero MotoCorp, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Automotive Market Trends and Innovations
Electric drivetrain localization and connected vehicle architecture are converging to reshape component sourcing patterns and aftermarket revenue models across passenger and commercial vehicle segments.
Battery pack assembly with locally produced cells is expanding into mid-range passenger cars and light commercial vehicles as DPIIT localization mandates harden. Fleet operators and shared mobility platforms are adopting these packs faster than retail buyers due to total-cost-of-ownership visibility. This technology shift is compressing import dependence for energy storage systems while elevating domestic cell manufacturing as a strategic priority.
BIS emission and safety standards are tightening type approval timelines for new vehicle introductions, forcing OEMs to front-load regulatory testing budgets. The industrial consequence is a winnowing of model variants as compliance costs concentrate development resources. Two-wheeler and three-wheeler assemblers face the steepest adaptation curve, with many pursuing platform consolidation to amortize certification overhead.
Subscription-based vehicle access models are displacing outright ownership among urban millennials and gig economy drivers, altering residual value calculations for fleet operators. Traditional dealer networks are ceding ground to direct-to-consumer digital channels and embedded finance partnerships. This behavioral pivot is most visible in Bengaluru, Hyderabad, and Pune, where technology sector employment density supports flexible mobility budgeting.
India Automotive Market Segmentation
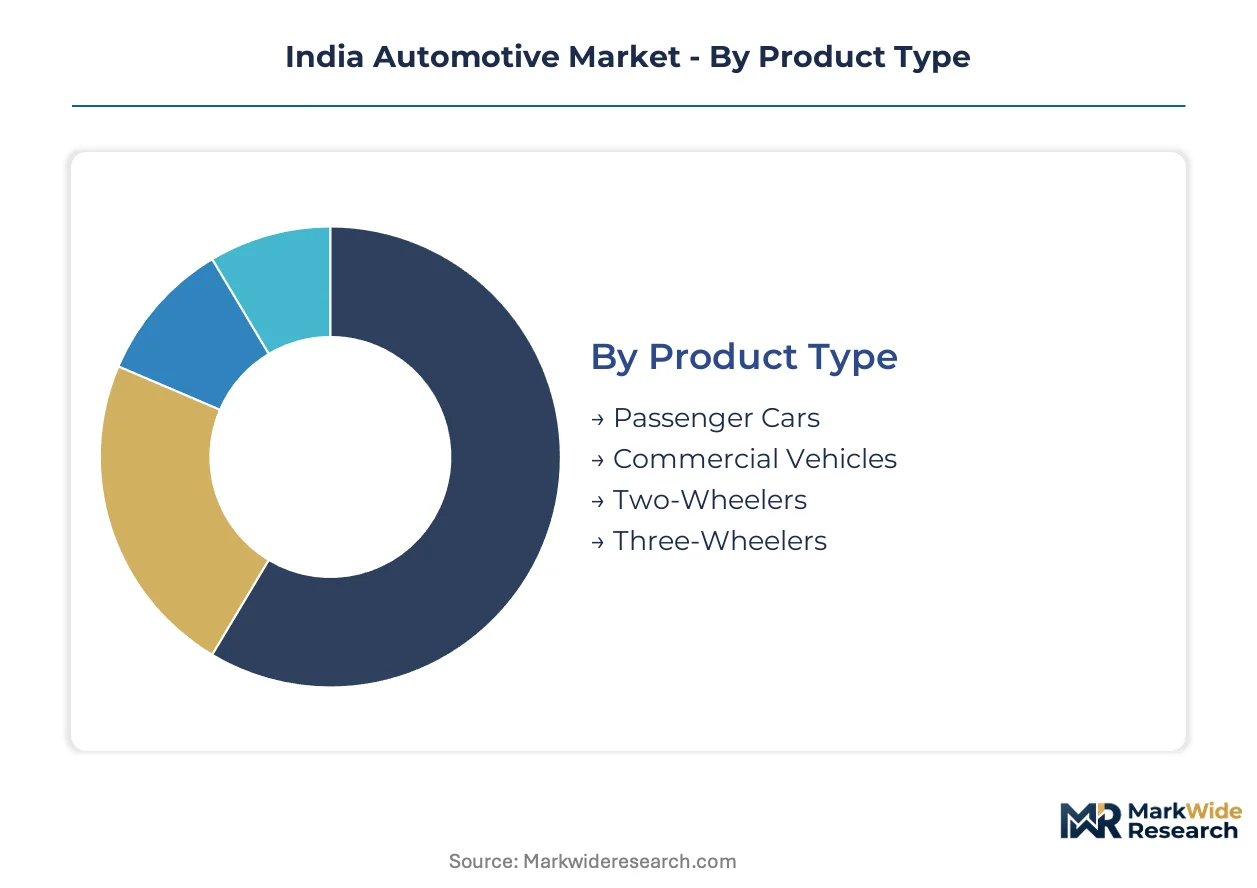
Segmentation in the India automotive market reveals how capital, policy, and infrastructure interact across distinct product and customer configurations. Understanding these divides clarifies where PLI subsidies concentrate, where charging networks face deployment urgency, and where BIS compliance costs fall heaviest.
Product Type:
Assembly plant clustering around Chennai, Pune, and Ahmedabad concentrates supplier ecosystems differently across vehicle categories, compressing procurement lead times for some segments while leaving others exposed to logistics fragmentation.
- Passenger Cars:Sedans, hatchbacks, and SUVs span gross vehicle weights from 800 kg to 2,500 kg, with unibody construction dominating below 1,800 kg and ladder-frame architectures anchoring larger SUVs. Demand concentrates in Maharashtra and Gujarat where Maruti Suzuki and Tata Motors maintain their densest dealership networks, though BIS crash-test compliance costs are forcing platform consolidation that reduces model variant diversity.
- Commercial Vehicles:Light, medium, and heavy trucks plus buses range from 3.5 tonnes to over 40 tonnes GVW, with cab-over-engine designs prevalent in urban distribution and conventional hooded trucks dominating long-haul routes. Fleet operators in Tamil Nadu's manufacturing corridors are expanding procurement most aggressively, pulled by last-mile delivery growth and ride-sharing platform contracts.
- Two-Wheelers:Motorcycles and scooters under 150 kg GVW constitute the volume anchor of the Indian market, reflecting affordability constraints and congested urban infrastructure.
- Three-Wheelers:Auto-rickshaws and goods carriers bridge passenger and cargo applications, with CNG conversion rates highest in Delhi-NCR due to air quality mandates.
Two-Wheelers absorb the bulk of installed capacity; Passenger Cars are expanding most quickly as electric drivetrain localization accelerates.
End User:
Customer type determines financing structures, service network density requirements, and vehicle utilization intensity, with fleet-based procurement now outpacing retail growth in several metropolitan corridors.
- Individual Consumers:Private ownership spans first-time buyers in tier-2 cities upgrading from two-wheelers and replacement demand in established urban households. Maharashtra and Gujarat concentrate this segment's purchasing power, where embedded finance partnerships with digital lenders are displacing traditional dealer-arranged loans.
- Fleet Operators:Logistics companies, corporate transport pools, and delivery platforms manage vehicle assets across fixed contract terms with total-cost-of-ownership visibility. Tamil Nadu's manufacturing belt hosts the densest concentration, with shared mobility platforms in Bengaluru and Hyderabad adopting electric variants faster than retail channels.
- Government Agencies:Municipal buses, police vehicles, and administrative fleets operate under public procurement rules with domestic content requirements.
- Ride-Sharing Services:Platform-mediated driver-owners and leased-vehicle operators prioritize acquisition cost minimization and residual value certainty.
Individual Consumers absorb the bulk of installed capacity; Fleet Operators are climbing the fastest as commercial mobility demand intensifies.
Fuel Type:
Energy source selection tracks infrastructure availability, total-cost-of-ownership calculations, and regulatory pressure gradients across state boundaries.
- Petrol:Spark-ignition engines dominate entry-level passenger cars and two-wheelers, with port fuel injection giving way to direct injection in higher-compression designs. Demand remains heaviest in semi-urban markets where CNG infrastructure is sparse and electric charging networks nonexistent.
- Diesel:Compression-ignition powertrains anchor commercial vehicles and larger SUVs, with Bharat Stage VI emission standards forcing costly exhaust after-treatment systems. Fleet operators in long-haul trucking continue specifying diesel despite narrowing fuel price differentials, driven by range anxiety and payload sensitivity.
- Electric:Battery-electric drivetrains span two-wheelers through buses, with lithium-ion cell import dependence constraining domestic pack assembly scale.
- CNG:Compressed natural gas conversions and factory-fit systems concentrate in Delhi, Mumbai, and Gujarat where pipeline distribution exists.
Petrol absorbs the bulk of installed capacity; Electric is gaining share fastest as CEA charging infrastructure rules clarify capital deployment timelines.
Technology:
Technology tier determines software-margin potential, supplier qualification complexity, and the engineering talent density required for platform development.
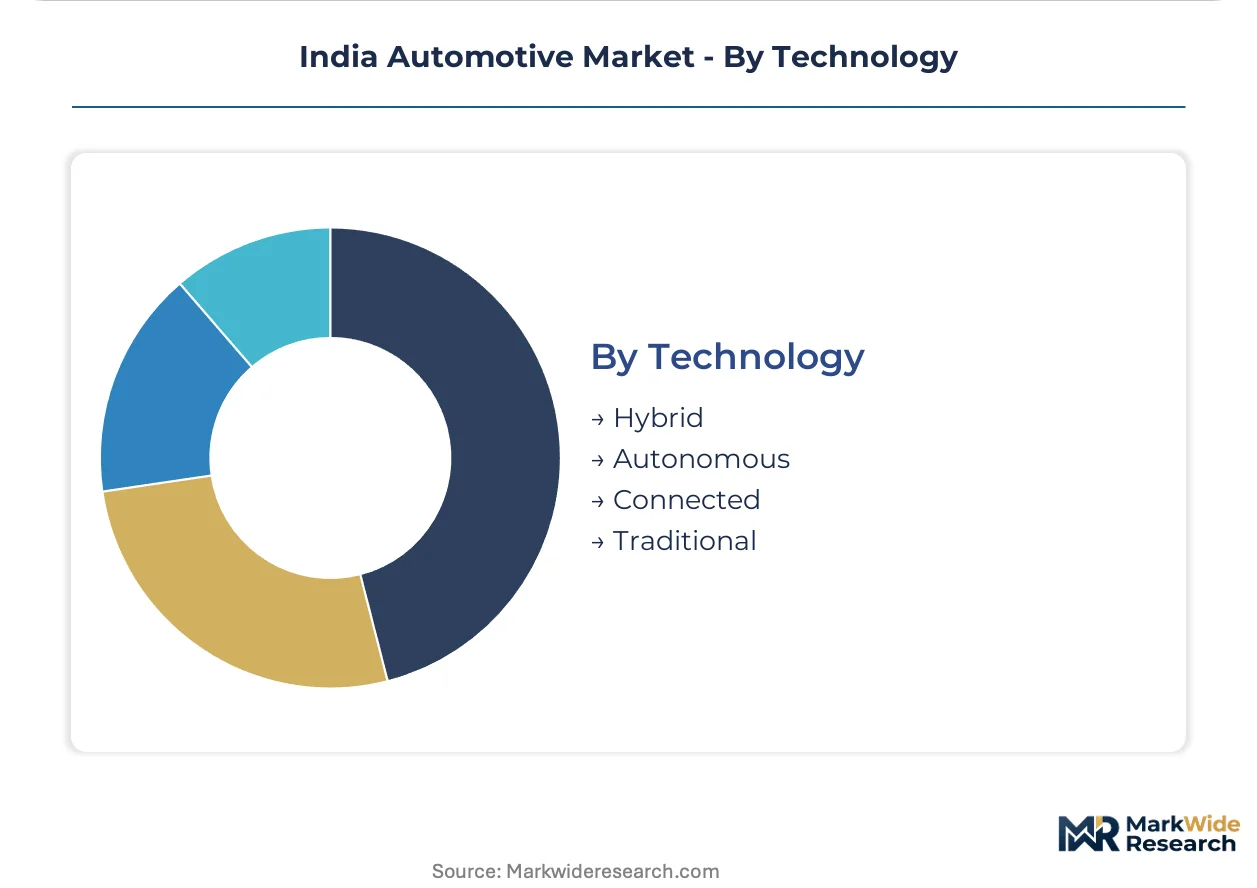
- Hybrid:Parallel and series-parallel architectures combine internal combustion with electric assist, offering emission reduction without charging infrastructure dependence. Toyota and Maruti Suzuki dominate this space, with mild-hybrid systems penetrating mid-range passenger cars where full-electric platforms remain cost-prohibitive.
- Autonomous:Advanced driver assistance systems span Level 1 lane-keeping through Level 3 conditional automation, with sensor fusion and mapping requirements concentrating development in Bengaluru's technology corridor. Regulatory frameworks from the Ministry of Road Transport remain permissive for testing but restrictive for commercial deployment.
- Connected:Telematics-enabled vehicles with over-the-air update capability are reshaping aftermarket revenue models.
- Traditional:Mechanical systems without embedded connectivity or electrification continue serving price-sensitive segments.
Traditional technology absorbs the bulk of installed capacity; Connected architectures are expanding most quickly as 4G coverage deepens and OEMs pursue recurring software revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Maharashtra, Tamil Nadu, and Gujarat where OEM assembly plants and supplier parks cluster around Chennai, Pune, and Ahmedabad. State-level incentive competition for manufacturing corridors is intensifying as the PLI scheme administered by DPIIT redirects supplier investment toward domestic value-addition.
Maharashtra
Pune's automotive belt hosts Maruti Suzuki and Tata Motors assembly operations alongside dense forging and casting supplier networks. The state's industrial promotion policies offer competitive land and power tariffs to anchor electric drivetrain localization. Mumbai and Pune corridor demand pulls premium passenger car and commercial vehicle procurement from fleet operators expanding contract terms.
Tamil Nadu
Chennai's Sriperumbudur-Oragadam belt concentrates Hyundai, Kia, and Renault-Nissan manufacturing with integrated supplier parks compressing component lead times. The state's EV policy mandates charging infrastructure deployment along industrial corridors. Fleet operators in Bengaluru-Hyderabad adjacency are adopting electric variants faster than retail channels, pulling procurement through Tamil Nadu assembly capacity.
Gujarat
Sanand and Halol industrial zones anchor Tata Motors and MG Motor operations with port access for component import and vehicle export. The state's single-window clearance mechanism accelerates supplier qualification under PLI domestic value-addition thresholds. Ahmedabad-Surat corridor demand concentrates in entry-level passenger cars and light commercial vehicles serving logistics networks.
Karnataka
Bengaluru's technology corridor concentrates connected vehicle software engineering and ADAS development talent. The state's EV policy exempts electric vehicles from road tax and registration fees through 2027. Toyota Kirloskar and Mahindra maintain assembly presence in Bidadi while supplier parks around Hoskote expand electronics assembly capacity.
Haryana
Gurugram-Manesar belt hosts Maruti Suzuki's largest manufacturing complex with integrated stamping and engine operations. The state's industrial infrastructure supports Hero MotoCorp's two-wheeler dominance and Honda's motorcycle assembly. Delhi-NCR air quality mandates are accelerating CNG and electric conversion rates for commercial fleets operating across the national capital region.
India Automotive Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue electric platform specialization and connected vehicle software stacks. The market structures around three concentration nodes: volume passenger car assemblers with dealership density advantages, utility vehicle specialists with rural distribution networks, and two-wheeler manufacturers with tier-2 city penetration. Three archetypes dominate: legacy OEMs with backward integration into powertrain components, technology-led entrants with software-first architectures, and diversified conglomerates with cross-sector manufacturing expertise. Competitive moves concentrate on capacity expansion in Maharashtra-Tamil Nadu-Gujarat corridors and strategic partnerships for battery cell sourcing.
Within the legacy OEM tier, Maruti Suzuki India and Tata Motors anchor volume leadership through distinct positioning—Maruti Suzuki leveraging unmatched dealership density across entry-level segments, Tata Motors pursuing in-house battery production and electric platform development. Mahindra & Mahindra occupies the utility vehicle specialist position with rural and semi-urban demand concentration. Hyundai Motor India and Kia India represent the Korean manufacturing archetype with rapid product refresh cycles and premium feature penetration. Among two-wheeler specialists, Hero MotoCorp and Bajaj Auto exemplify scale-driven cost structures with extensive tier-2 and tier-3 distribution reach.
| Leading Market Players |
|---|
| Maruti Suzuki India |
| Hyundai Motor India |
| Tata Motors |
| Mahindra & Mahindra |
| Toyota Kirloskar Motor |
| Kia India |
| Honda Cars India |
| Bajaj Auto |
| Hero MotoCorp |
| Others |
Pricing and Supply Chain Analysis
Fleet operator concentration in Tamil Nadu and Maharashtra manufacturing corridors anchors contract-based long-term offtake pricing for commercial vehicles, with procurement scale compressing per-unit acquisition costs while BIS compliance investments widen spreads between organized OEM tiers and smaller assemblers.
Pricing Analysis
Volume leadership in two-wheelers and entry-level passenger cars runs on thin per-unit margins offset by dealership density economies, while premium SUV and electric drivetrain segments capture wider spreads through technology differentiation and battery pack localization. Price differentiation centers on Bharat Stage VI certification grade and PLI-linked domestic value-addition thresholds, with subsidy-eligible variants commanding acquisition premiums. Cost compression in lithium-ion cell sourcing is intensifying because import dependence exposes assemblers to raw material volatility. Fleet operators exhibit lowest price sensitivity due to total-cost-of-ownership visibility, while rural individual buyers in semi-urban markets remain most price-constrained.
Supply Chain Analysis
PLI scheme domestic value-addition thresholds administered by DPIIT are redirecting forging, casting, and electronics assembly investment toward Maharashtra, Tamil Nadu, and Gujarat supplier parks. Battery pack assembly draws from China, South Korea, and Japan for cathode and electrolyte inputs, while semiconductor content rests on Taiwan and South Korea for power electronics. Single-source vulnerability in lithium-ion cell supply creates exposure to commodity price volatility and logistics chokepoints at Indian ports. Distribution runs through OEM-controlled dealer networks for passenger vehicles and direct fleet procurement contracts for commercial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India automotive is navigating a technology-transition phase where battery-electric drivetrains displace internal combustion platforms across passenger and commercial segments, reshaping supplier qualification requirements and capital allocation priorities.
For Market Incumbents: Cement platform standardization across electric variants to amortize BIS certification costs and compress supplier qualification overhead. Deepen backward integration into battery pack assembly before PLI localization thresholds harden, defending margin position against technology-led entrants with software-first architectures. For New Entrants and Emerging Players: The mid-tier price gap between Maruti Suzuki's entry-level dominance and Tata Motors' electric premium positioning offers white-space targeting for ruggedized semi-urban utility vehicles with localized drivetrains. Karnataka and Telangana charging infrastructure corridors present the most penetrable geographic entry points, with embedded finance partnerships as the critical go-to-market angle for fleet operator acquisition. For Investors and Strategic Acquirers: Distressed-cycle entries favor power electronics engineering specialists in Bengaluru-Hyderabad corridor with captive inverter and motor control design talent. Long-term viability hinges on 5-10 year localization trajectories under PLI scheme disbursement conditions. Watch DPIIT subsidy release timelines as the inflection signal for supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Locks lithium-ion cell procurement under PLI localization mandates with CEA grid interconnection compliance. |
| Software-Defined Vehicle Investment | Enables over-the-air update revenue models through 4G-enabled connected architectures in passenger segments. |
| Geographic Manufacturing Footprint | Expands assembly presence in emerging state greenfield zones beyond Maharashtra-Tamil Nadu-Gujarat corridors. |
| Platform Standardization | Reduces BIS crash-test compliance costs across model variants while concentrating R&D spend on electric drivetrains. |
| Charging Infrastructure Partnership | Accelerates CEA-mandated grid interconnection deployment along Tamil Nadu industrial belts for fleet electrification. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, triangulated with primary interviews across OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and dealership operations heads. BIS type approval databases, DPIIT PLI scheme disbursement records, SIAM production statistics, and CEA charging infrastructure filings supplied quantitative validation. Bottom-up vehicle registration analysis and top-down macroeconomic modeling converged on segment-level demand estimates.
Granularity-level modeling operated at vehicle class, propulsion architecture, and regional production cluster dimensions throughout the forecast period. CAGRs derived from production capacity expansion schedules, fleet operator procurement contract visibility, and electric drivetrain penetration curves across urban and semi-urban geographies. Battery pack localization timelines and PLI subsidy disbursement trajectories informed electric segment trajectory assumptions.
Underlying measurement precision varies by segment; electric drivetrain and connected vehicle forecasts carry tighter precision than traditional internal combustion projections given policy visibility. Forecasts reflect assumptions on PLI scheme continuity, lithium-ion cell import cost trajectories, and CEA charging infrastructure deployment pace. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
Automotive Luxury Vehicle Market
Passenger Vehicles
Latin America Passenger Car Market
Passenger Vehicles
Minivans Market
Passenger Vehicles
Luxury Vehicles Market
Passenger Vehicles
Global Luxury SUV Market
Passenger Vehicles
Indonesia Passenger Car Market
Passenger Vehicles
Family Car Market
Passenger Vehicles
North America Automotive Market
Passenger Vehicles
India Passenger Car Market
Passenger Vehicles
Luxury Car Market
Passenger Vehicles
South America Passenger Cars Market
Passenger Vehicles
Train Market
Passenger Vehicles
Lightweight Cars Market
Passenger Vehicles
Limousines Market
Passenger Vehicles
Passenger Vehicle Market
Passenger Vehicles
Electric Sports Car Market