
 Solar Passenger Car Market | 2026-2036
Solar Passenger Car Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Passenger Car Market Insights
Photovoltaic conversion efficiency above 26 percent is collapsing the cost-per-kilometer gap between solar-supplemented and conventional battery electric vehicles. Lightyear leverages in-house solar cell production to sustain margin control across its supply chain. Aptera Motors anchors its position through extreme aerodynamic specialization, while Toyota Motor Corporation extends its hybrid expertise into solar-assisted architectures.
A solar passenger car integrates photovoltaic panels into body panels, roofs, or hood surfaces to generate supplementary electrical energy for propulsion or auxiliary systems, typically achieving 15-45 kilometers of daily range extension under optimal solar irradiance conditions. Monocrystalline silicon technology dominates current production due to its superior energy density per unit area, while thin-film variants represent the fastest-growing technology segment as manufacturers seek curved-surface integration and reduced weight penalties. Fleet operators constitute the most structurally attractive end-user segment, locking in multi-year procurement contracts that stabilize revenue visibility for producers.
The EU Green Deal and CE marking requirements shape product certification pathways for solar-integrated vehicles entering European markets, while EPA fuel economy standards and NHTSA safety regulations govern US market access and design parameters. China's MIIT establishes GB standards for new energy vehicle classifications that determine subsidy eligibility for solar-assisted platforms. Stakeholders must monitor how regulatory definitions of "solar-assisted" versus "solar-primary" propulsion classification affect incentive structures and consumer qualification thresholds.
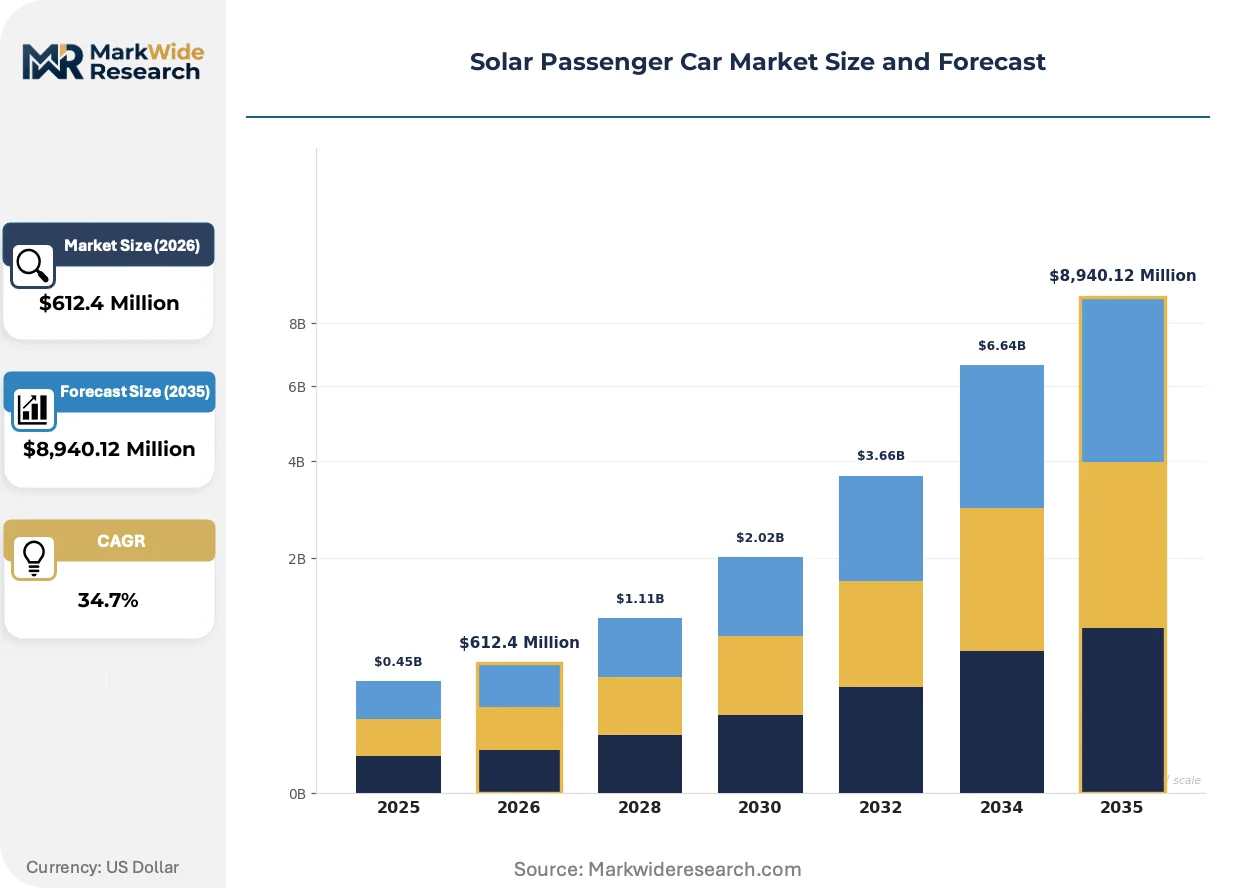
Market Dynamics
Photovoltaic conversion efficiency breakthroughs above 26 percent are collapsing the cost-per-kilometer gap between solar-supplemented and conventional battery electric vehicles, fundamentally restructuring procurement economics for fleet operators.
Growth Catalysts
- EU Green Deal vehicle emission benchmarks:These binding targets force automotive OEMs to integrate renewable energy capture systems into passenger vehicle architectures, accelerating R&D allocation toward solar-assisted platforms.
- Fleet operator procurement centralization:Urban logistics providers are locking multi-year contracts for light solar-integrated vehicles, creating revenue visibility that attracts component suppliers and manufacturing investment.
- Thin-film photovoltaic efficiency gains:Curved-surface integration capabilities enable panel placement on hood and door surfaces previously inaccessible to rigid monocrystalline cells, expanding energy harvest potential.
Market Restraints
- Silicon wafer supply concentration:Upstream polysilicon refining capacity clusters in specific Asian manufacturing corridors, exposing solar cell producers to input cost volatility and geopolitical supply disruptions.
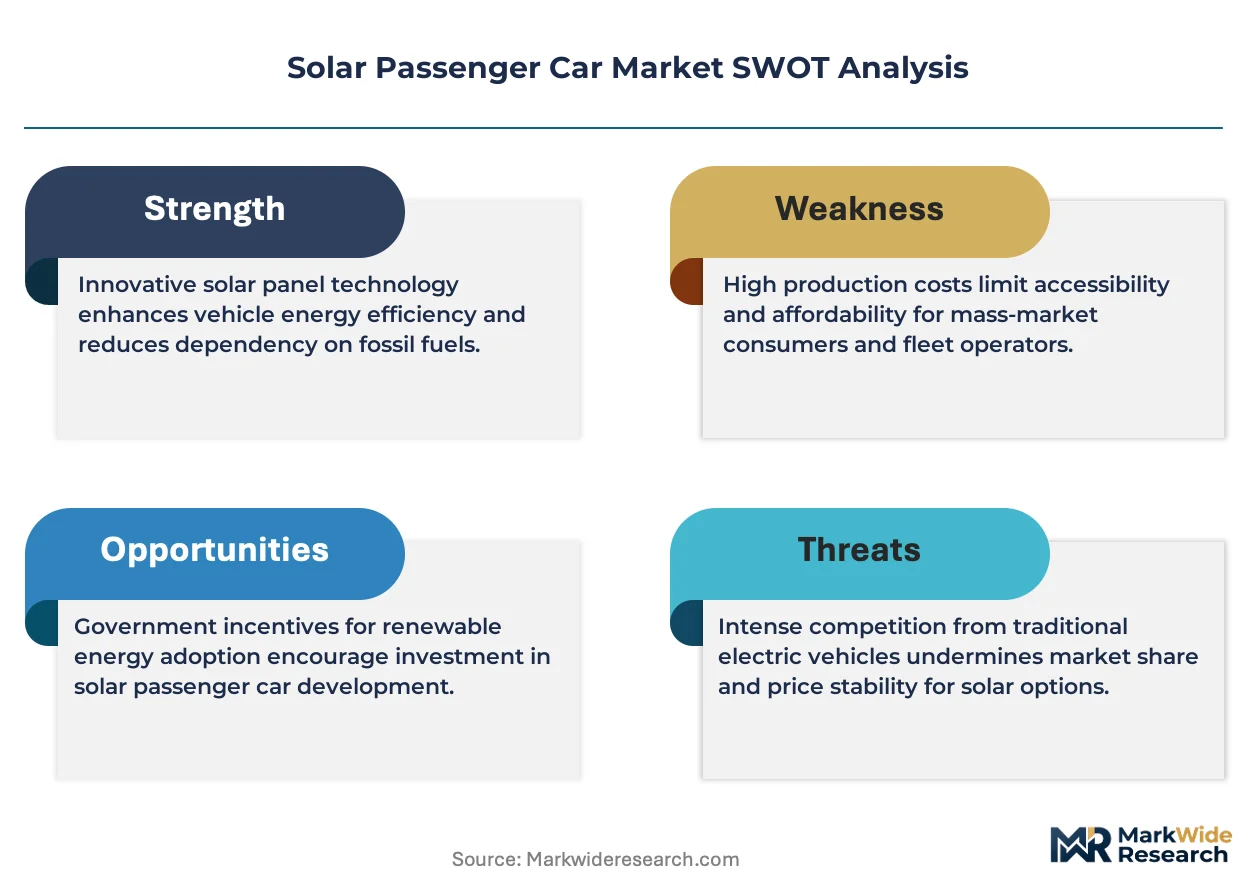
- Energy density physics:Current photovoltaic surface area on passenger vehicle bodies delivers 15-45 kilometers of daily range extension under optimal irradiance, limiting pure solar propulsion viability without battery supplementation.
- NHTSA safety regulation friction:Crashworthiness testing protocols for vehicles with integrated glass and semiconductor body panels create extended certification timelines and redesign costs for US market entry.
Strategic Opportunities
- German automotive engineering cluster leverage:Stuttgart's concentrated supplier ecosystem and Berlin-based fleet electrification mandates create a testbed market for solar-integrated vehicle validation before broader European rollout.
- Monocrystalline-thin-film technology convergence:Hybrid panel configurations combining energy density with form-factor flexibility enable aesthetic integration on premium vehicle segments previously resistant to visible solar hardware.
- CE marking pathway expansion:Evolving EU certification frameworks for solar-assisted propulsion classification create first-mover advantage for manufacturers achieving compliant product definitions ahead of subsidy eligibility determinations.
Industry Challenges
- Photovoltaic-vehicle systems integration talent scarcity:The intersection of automotive lightweighting engineering and semiconductor thermal management requires skill profiles rarely co-located in traditional OEM or solar industry workforces.
- Dual certification timeline compression:Manufacturers must simultaneously satisfy automotive safety standards and electrical component electromagnetic compatibility testing, creating parallel approval bottlenecks.
- Supply chain reconfiguration friction:Solar cell production scale-up for automotive-grade quality and volume requires capital deployment ahead of confirmed fleet procurement commitments, straining balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Passenger Car Market |
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $8,940.12 Million |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PHEV, BEV, Solar Panel Integration, Hybrid Solar Technology: Thin-Film, Monocrystalline, Polycrystalline, Bifacial End User: Consumers, Fleet Operators, Rental Services, Corporates Distribution Channel: Online Sales, Dealerships, Direct Sales, Partnerships |
| Companies Covered | Lightyear, Aptera Motors, Sono Motors, Toyota Motor Corporation, Volkswagen Group, Ford Motor Company, Venturi Automobiles, Mahindra & Mahindra, Hyundai Motor Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Passenger Car Market Trends and Innovations
Thin-film photovoltaic architectures are displacing conventional panel mounting approaches across passenger vehicle platforms, enabling energy capture on curved surfaces while reducing weight penalties that previously constrained range economics.
Perovskite-silicon tandem cell development is displacing single-junction photovoltaic designs in automotive applications. Tier 1 suppliers are sampling these configurations for hood and roof integration on 2026-2028 vehicle programs. The technology is displacing incumbent monocrystalline dominance in premium segments where surface-area-to-energy-yield ratios justify higher unit costs.
EU Green Deal emission benchmarks are tightening fleet-average CO2 obligations for passenger vehicle manufacturers. OEMs face penalty structures that make solar range extension economically rational even at current photovoltaic costs. German and French regulators are interpreting these benchmarks most aggressively, accelerating solar integration timelines for vehicles sold in those markets.
Fleet procurement is consolidating around multi-year service contracts that bundle vehicle supply with energy yield guarantees. Leasing intermediaries are displacing direct OEM sales in urban logistics segments, assuming solar performance risk in exchange for predictable per-kilometer pricing. This model is concentrating most visibly in German metropolitan fleet electrification programs where municipal mandates drive standardized procurement specifications.
Solar Passenger Car Market Segmentation
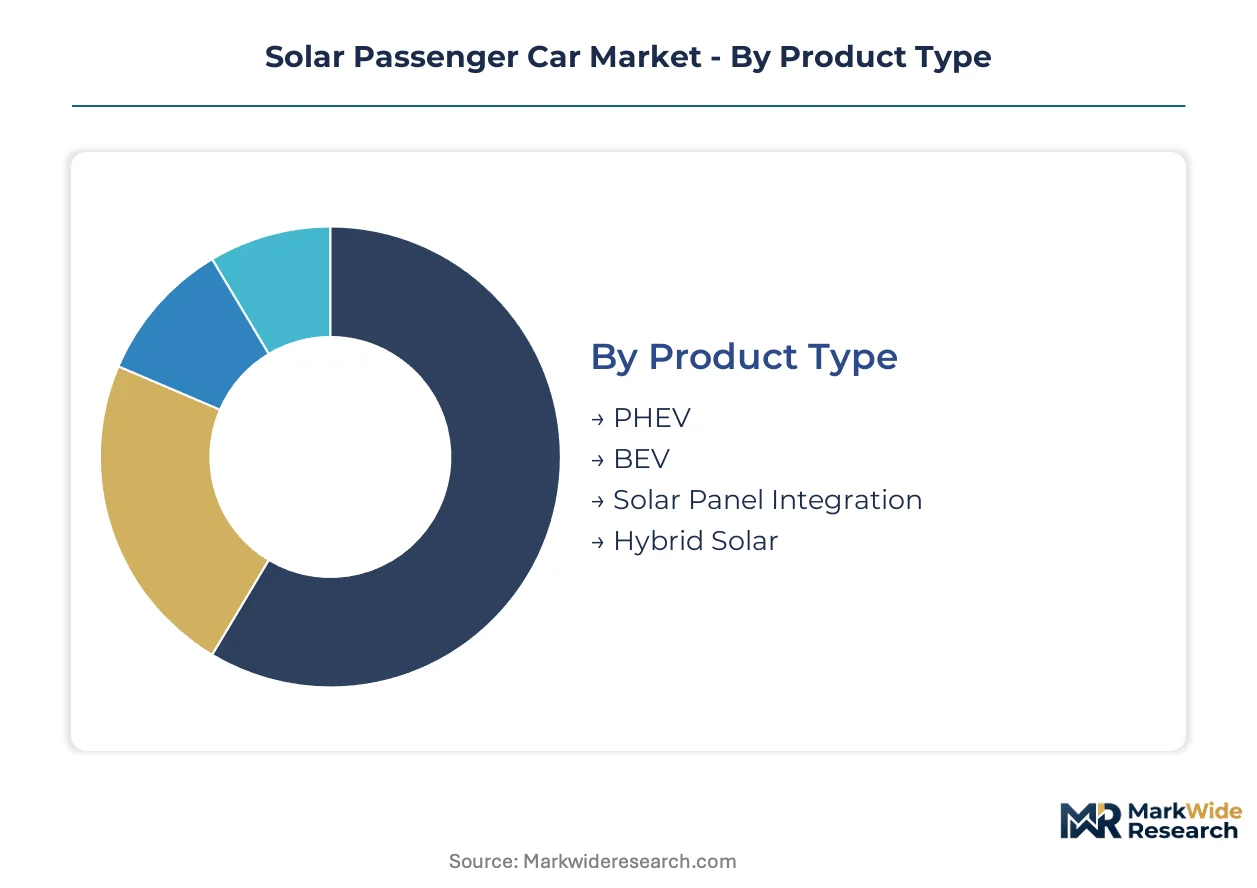
Solar passenger car segmentation reveals divergent commercialization paths across propulsion architectures and photovoltaic integration strategies. Procurement patterns split between consumer retail channels and fleet operator bulk contracting, each demanding distinct pricing and service configurations.
Product Type:
Domestic demand concentrates on plug-in hybrid architectures with solar supplementation, while export-led growth centers on pure battery electric platforms with integrated photovoltaics targeting premium European markets.
- BEV:Pure battery electric vehicles with roof-integrated solar panels achieve 15-45 kilometers of daily range extension under optimal irradiance. German fleet operators in Stuttgart and Berlin are locking multi-year procurement contracts for urban logistics applications, driven by municipal electrification mandates and EU Green Deal emission benchmarks.
- PHEV:Plug-in hybrid electric vehicles combine combustion range extenders with modest solar roof supplementation for auxiliary power. Consumer demand clusters in suburban markets across France and the Netherlands where charging infrastructure gaps persist and solar range extension provides psychological reassurance.
- Solar Panel Integration:Aftermarket retrofit systems enable photovoltaic addition to existing electric vehicle platforms. Italian and Spanish specialist installers dominate this fragmented segment serving price-sensitive consumers outside OEM warranty coverage.
- Hybrid Solar:Dedicated solar-primary architectures with minimal battery buffers represent an emerging experimental category. Australian and UAE test programs evaluate these configurations for high-irradiance environments where daily solar yield can satisfy short-distance commuting needs.
BEV commands the established base. The steepest expansion runs through PHEV.
Technology:
Cost tier differentiation separates premium monocrystalline deployments from emerging thin-film alternatives targeting curved-surface integration on mass-market vehicle programs.
- Monocrystalline:Single-crystal silicon cells deliver superior energy density per unit area at 20-22% conversion efficiency. Lightyear and premium European OEMs specify these for flat roof applications where space constraints prioritize yield maximization over form factor flexibility.
- Thin-Film:Cadmium telluride and copper indium gallium selenide layers enable conformal mounting on hood and door curves previously inaccessible to rigid cells. Stuttgart engineering clusters are sampling these configurations for 2026-2028 vehicle programs seeking aesthetic integration without visible panel hardware.
- Polycrystalline:Multi-crystal silicon offers moderate efficiency at reduced unit costs for price-sensitive fleet specifications. Eastern European logistics providers specify these for depot-based vehicles with predictable daily range requirements.
- Bifacial:Dual-sided cells capture reflected and diffuse light from vehicle underbody and surrounding surfaces. Nordic test programs evaluate these for extended summer daylight conditions where albedo reflection from light road surfaces boosts effective yield.
Monocrystalline dominates current revenue. Thin-film gains share fastest.
End User:
Customer type determines contract structure, with fleet operators demanding performance guarantees and consumers prioritizing purchase price and aesthetic integration.
- Fleet Operators:Urban logistics providers and municipal service fleets lock multi-year service contracts bundling vehicle supply with energy yield guarantees. German metropolitan electrification programs in Berlin and Hamburg drive standardized procurement specifications with predictable per-kilometer pricing.
- Consumers:Individual purchasers prioritize visible solar integration as sustainability signaling and range anxiety mitigation. Dutch and Belgian early adopters show highest willingness-to-pay premiums for factory-integrated photovoltaic systems over aftermarket alternatives.
- Corporates:Employee fleet and executive vehicle programs specify solar-equipped models for ESG reporting and brand alignment. French corporate sustainability mandates accelerate adoption in Paris and Lyon metropolitan areas.
- Rental Services:Short-term mobility providers test solar-supplemented vehicles for tourist and airport segments. Portuguese and Greek island operators evaluate these for high-irradiance seasonal demand with limited charging infrastructure.
Fleet operators command the established base. Corporate procurement shows the steepest expansion trajectory.
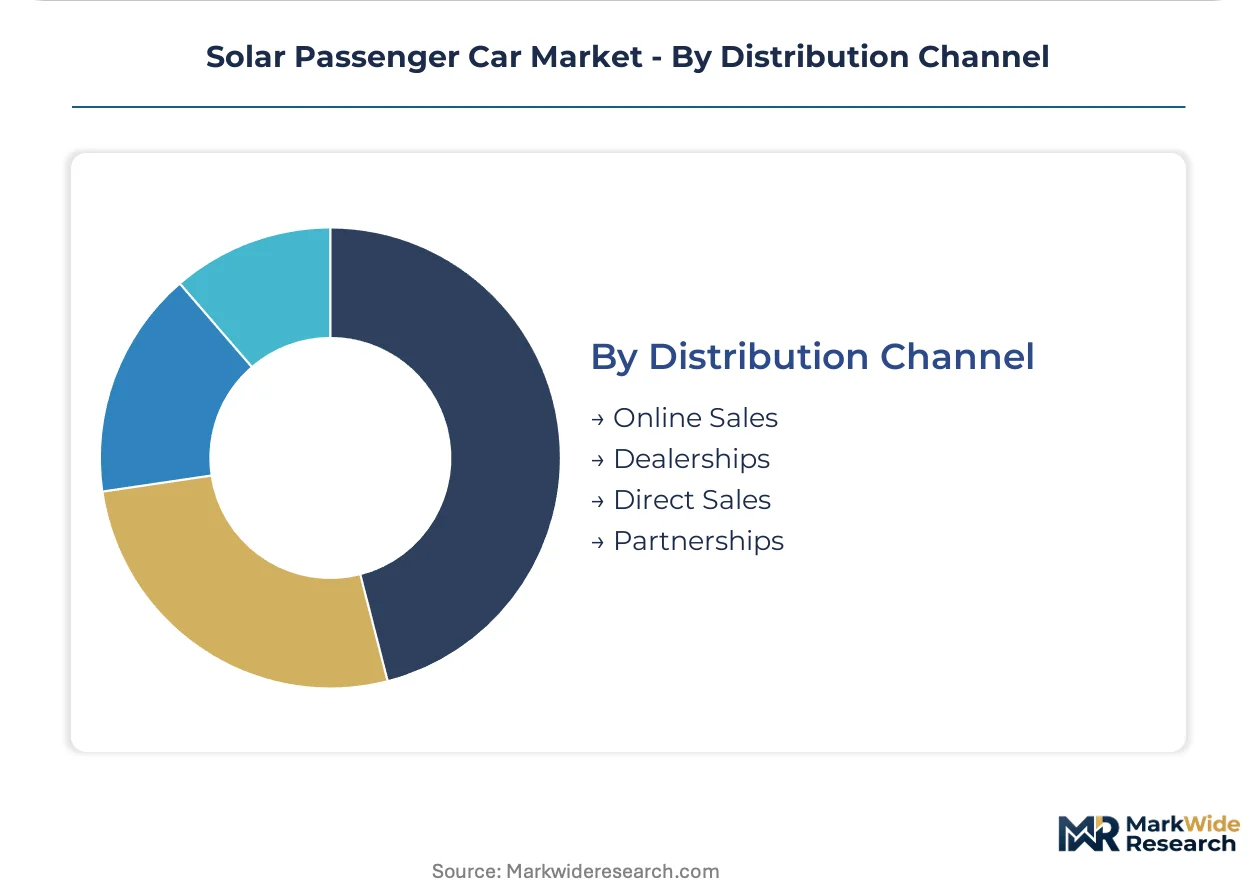
Distribution Channel:
Channel selection correlates with customer sophistication, with direct sales capturing technically informed buyers and dealerships serving mainstream market education needs.
- Direct Sales:OEM-owned channels enable technical consultation on solar yield expectations and integration trade-offs. Lightyear and Aptera leverage this model to control margin and customer education for novel propulsion architectures.
- Dealerships:Franchise networks provide physical inspection and local service infrastructure for skeptical mainstream buyers. Traditional automotive retail in Germany and France requires significant staff retraining to communicate solar performance variables effectively.
- Online Sales:Digital channels with configurators and yield estimation tools attract technically confident early adopters. Nordic markets show highest digital purchase completion rates for solar-equipped vehicles.
- Partnerships:Utility and energy retailer collaborations bundle solar vehicle supply with home photovoltaic and charging infrastructure. E.ON and Enel pilot programs in Germany and Italy test this integrated energy-as-a-service model.
Dealerships command the established base. Direct sales channels climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering clusters export solar-integrated vehicle platforms to Dutch and Belgian fleet operators, establishing a concentrated procurement corridor that channels Stuttgart-developed technology into Benelux urban logistics networks.
Germany
Berlin-based municipal electrification mandates and Stuttgart's automotive supplier density drive concentrated fleet procurement. KBA vehicle certification requirements shape homologation pathways for solar-assisted architectures entering commercial service. The Baden-Württemberg engineering corridor hosts validation programs for thin-film curved-surface integration on 2026-2028 vehicle programs.
Netherlands
Consumer willingness-to-pay premiums for factory-integrated photovoltaic systems exceeds European benchmarks, particularly in suburban Amsterdam and Utrecht corridors. National charging infrastructure gaps sustain demand for solar range extension as psychological reassurance. Eindhoven-based technical universities collaborate with German OEMs on perovskite-silicon tandem cell sampling for premium segments.
France
Corporate sustainability mandates accelerate Paris and Lyon metropolitan procurement for ESG reporting alignment. ANSM interpretations of CE marking requirements for solar-assisted propulsion classification create first-mover certification advantages. The Auvergne-Rhône-Alpes industrial cluster concentrates aftermarket retrofit specialist activity serving price-sensitive consumers outside OEM warranty networks.
China
MIIT GB standards for new energy vehicle classifications determine subsidy eligibility thresholds for solar-assisted platforms entering domestic fleet service. Yangtze River Delta manufacturing corridors concentrate polysilicon refining capacity upstream of cell production. Shenzhen-based battery-electric OEMs evaluate solar supplementation for export-oriented premium vehicle programs targeting European emission benchmarks.
United States
EPA fuel economy standards and NHTSA crashworthiness protocols govern design parameters for solar-integrated body panels seeking market entry. California Air Resources Board zero-emission vehicle mandates create concentrated demand pull in Bay Area and Los Angeles metropolitan logistics networks. Aptera Motors anchors development activity in Southern California's aerospace-adjacent engineering labor markets.
Solar Passenger Car Market Competitive Landscape
Listed automotive conglomerates compete with private specialists across photovoltaic integration depth, creating a tiered structure where capital-scale advantages confront agility-driven innovation cycles. Toyota Motor Corporation and Volkswagen Group leverage existing electrification platforms for solar supplementation, while venture-backed entities pursue dedicated solar-primary architectures. Three archetypes dominate: incumbent OEM extenders, solar-native specialists, and component-integrated Tier 1 suppliers. Competitive moves concentrate on strategic partnerships with photovoltaic cell producers and in-house production of solar body panels to capture margin.
Among solar-native specialists, Lightyear and Aptera Motors occupy positions exemplifying divergent technical philosophies. Lightyear represents the integrated-manufacturing archetype through captive solar cell production. Aptera Motors anchors the aerodynamic-optimization vector with extreme drag-coefficient specialization. Toyota Motor Corporation sits within the incumbent-extender tier, translating hybrid system expertise into solar-assisted battery electric architectures. These three entities collectively illustrate the competitive tension between purpose-built solar platforms and adapted conventional vehicle structures.
| Leading Market Players |
|---|
| Lightyear |
| Aptera Motors |
| Sono Motors |
| Toyota Motor Corporation |
| Volkswagen Group |
| Ford Motor Company |
| Venturi Automobiles |
| Mahindra & Mahindra |
| Hyundai Motor Group |
| Others |
Pricing and Supply Chain Analysis
CE marking pathways for solar-assisted propulsion classification simultaneously gate supplier qualification tiers and enable price stratification between certified and uncertified photovoltaic-vehicle platforms entering European markets.
Pricing Analysis
Fleet operators anchor contract structures around performance-guaranteed service agreements rather than capital expenditure models. Three-tier pricing separates premium monocrystalline-integrated vehicles from standard thin-film configurations and economy-grade polycrystalline fleet specifications. Price differentiation hinges on certification tier and volume scale, with CE-marked platforms commanding substantial premiums over aftermarket retrofit alternatives. Cost compression in the economy tier is intensifying because Eastern European logistics providers are consolidating procurement volumes and demanding standardized depot-based vehicle specifications.
Supply Chain Analysis
Strategic stockpiling of polysilicon feedstock dominates inventory strategy as manufacturers buffer against Yangtze River Delta refining concentration. Supply draws from China for upstream polysilicon, Germany for automotive-grade cell fabrication, and South Korea for semiconductor thermal management components. Raw material dependencies rest on high-purity silicon metal, cadmium telluride layers, and copper indium gallium selenide precursors. Single-source vulnerability in Asian polysilicon refining exposes producers to geopolitical disruption. Distribution runs through OEM direct channels for premium segments and leasing intermediaries for fleet bulk contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet procurement consolidation across German metropolitan electrification programs has shifted negotiating leverage toward buyers, compressing margin structures for solar-vehicle producers dependent on multi-year contract visibility.
For Market Incumbents: Fortify captive solar cell production capabilities to defend margin erosion from photovoltaic commodity cycles. Secure KBA certification ahead of evolving EU Green Deal vehicle emission benchmarks to maintain subsidy eligibility gates against emerging thin-film specialists. Prioritize backward integration into polysilicon refining partnerships that reduce exposure to Yangtze River Delta supply concentration.
For New Entrants and Emerging Players: Lead with curved-surface thin-film integration targeting premium consumer segments in the Netherlands and Belgium where willingness-to-pay premiums exceed European benchmarks. Exploit white-space in French corporate sustainability mandates by positioning solar-equipped vehicles as ESG reporting instruments. Deploy utility partnership models bundling home photovoltaic and charging infrastructure to differentiate from direct OEM sales channels.
For Investors and Strategic Acquirers: EU Green Deal fleet-average CO2 penalty structures reshape the acquisition landscape by making solar range extension economically rational even at current photovoltaic costs. Long-term viability centers on manufacturers achieving compliant solar-assisted propulsion definitions ahead of subsidy eligibility determinations. Target acquisition archetypes include Stuttgart-engineering-cluster specialists with validated thin-film curved-surface programs. Watch for NHTSA crashworthiness protocol revisions as signal for US market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Photovoltaic Cell Production Scale-Up | Captive manufacturing secures margin control against polysilicon volatility for Lightyear and integrated OEMs. |
| CE Marking Pathway Expansion | First-mover certification advantage locks subsidy eligibility ahead of ANSM interpretation deadlines in France. |
| Fleet Service Contract Bundling | Leasing intermediaries assume solar performance risk for German municipal electrification programs in Berlin and Hamburg. |
| Perovskite-Silicon Tandem Cell Sampling | Eindhoven technical university collaboration positions premium European OEMs for 2026-2028 vehicle program integration. |
| Aerodynamic Platform Specialization | Extreme drag-coefficient optimization enables Aptera Motors to maximize solar yield per surface area in Southern California development. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet procurement managers at German urban logistics providers, photovoltaic cell production engineers in Stuttgart engineering clusters, OEM platform architects at Toyota and Volkswagen Group, and CE marking compliance specialists at notified bodies. Secondary validation drew from KBA vehicle registration databases, EU Green Deal legislative tracking, MIIT GB standard publications, and NHTSA crashworthiness protocol documentation. Bottom-up fleet procurement volume estimates triangulated against top-down photovoltaic capacity deployment projections across the analysis window.
Across the modeling period, the analytical framework segmented volume and value outputs by propulsion architecture, photovoltaic technology tier, end-user contract structure, and regional regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to fleet electrification mandate timelines and photovoltaic efficiency improvement trajectories. Industry-specific forecast inputs incorporated EU Green Deal penalty structure phase-ins and thin-film manufacturing yield ramp assumptions.
Underlying assumptions cover continued polysilicon refining capacity expansion, stable CE marking interpretation frameworks, and fleet operator procurement centralization trajectories, with deviation risk concentrated in NHTSA regulatory friction extending US certification timelines. Revision becomes warranted when photovoltaic conversion efficiency breakthroughs collapse cost-per-kilometer gaps faster than modeled or when silicon wafer supply disruptions exceed six-month durations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
India Automotive Market
Passenger Vehicles
Asia Pacific Luxury Cars Market
Passenger Vehicles
China Luxury Car Market
Passenger Vehicles
Train Market
Passenger Vehicles
South America Passenger Cars Market
Passenger Vehicles
Global SUV Market
Passenger Vehicles
Convertible Vehicles Market
Passenger Vehicles
Europe Luxury Car Market
Passenger Vehicles
Automotive Passenger Vehicle Sensor Market
Passenger Vehicles
India Luxury Car Market
Passenger Vehicles
Compact Cars Market
Passenger Vehicles
North America MUV Rental Market
Passenger Vehicles
Lightweight Cars Market
Passenger Vehicles
Latin America Passenger Car Market
Passenger Vehicles
Microcars Market
Passenger Vehicles
North America Automotive Market