
 Automotive Luxury Vehicle Market | 2026-2036
Automotive Luxury Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Luxury Vehicle Market Analysis
The EU Green Deal is realigning powertrain investment across European luxury marques. Mercedes-Benz leverages its EQ platform to sustain technology leadership in battery-electric drivetrains. BMW anchors its position through vertical integration into cell manufacturing and proprietary operating systems. Porsche differentiates via performance-oriented hybrid architectures that bridge regulatory thresholds and driver expectations.
Automotive luxury vehicles denote passenger automobiles engineered with superior materials, advanced powertrains, and refined craftsmanship, typically priced above mass-market equivalents by a substantial margin. These vehicles incorporate aluminum-intensive body structures, multi-chamber air suspension systems, and bespoke interior configurations to deliver elevated comfort, performance, and status signaling for discerning buyers. SUV configurations now dominate volume across premium portfolios, absorbing engineering resources and factory capacity from shrinking sedan lines. Electric technology represents the fastest-expanding powertrain category, though gasoline variants retain margin density in emerging markets where charging infrastructure remains sparse. Corporate fleet end users command distinct service and financing arrangements, creating separate channel economics from retail transactions.
The EPA tailpipe standards and California Air Resources Board mandates shape product availability across United States showrooms, while China's MIIT new-energy vehicle quotas dictate local production requirements for imported brands. The EU AI Act and forthcoming cybersecurity frameworks will impose additional compliance layers on autonomous driving features and connected-car architectures. Stakeholders must monitor regulatory divergence between Brussels and Beijing as dual certification paths threaten to fragment development budgets and extend model cycles.
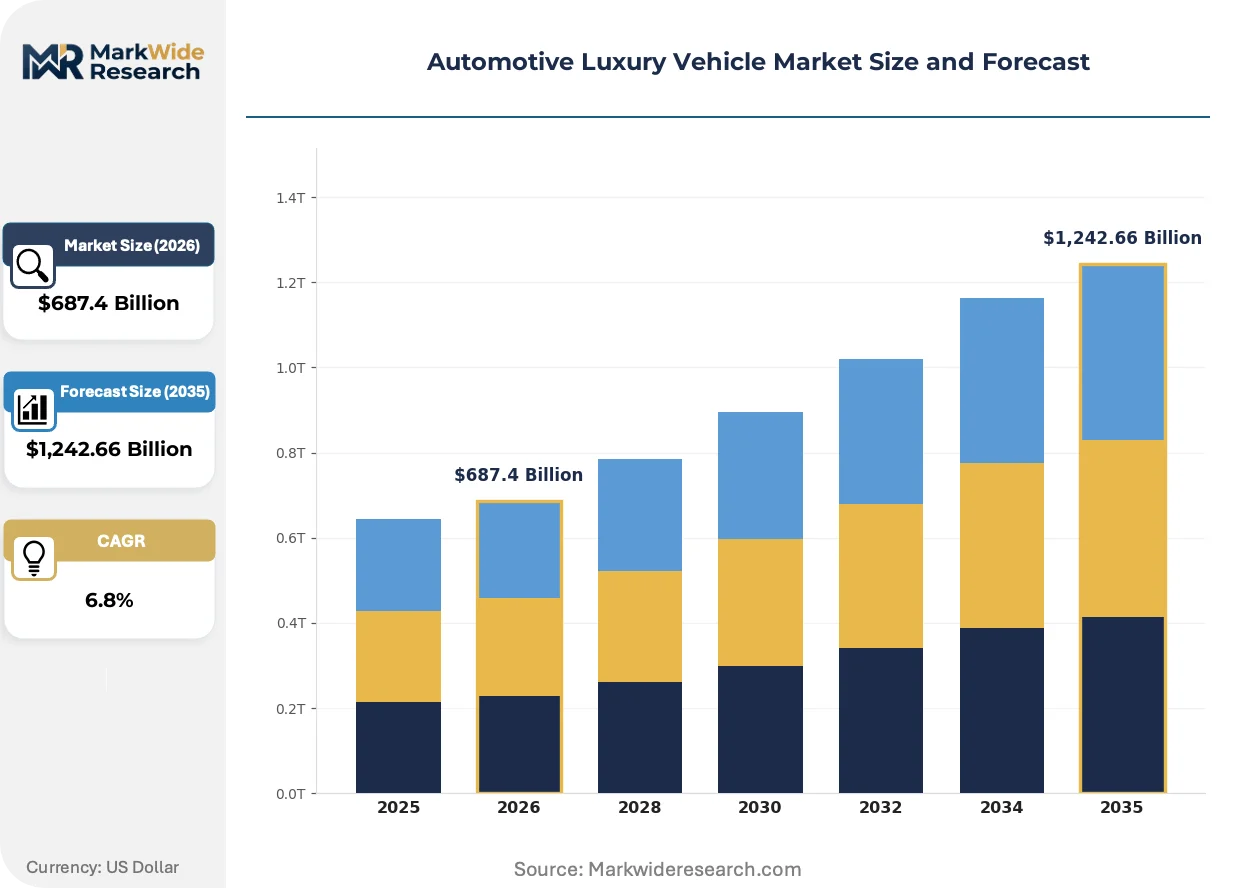
Market Dynamics
The EU Green Deal and China's MIIT new-energy vehicle quotas are forcing simultaneous powertrain transitions across all price tiers, compressing development cycles while demanding dual-certification investments for European and Asian markets.
Growth Catalysts
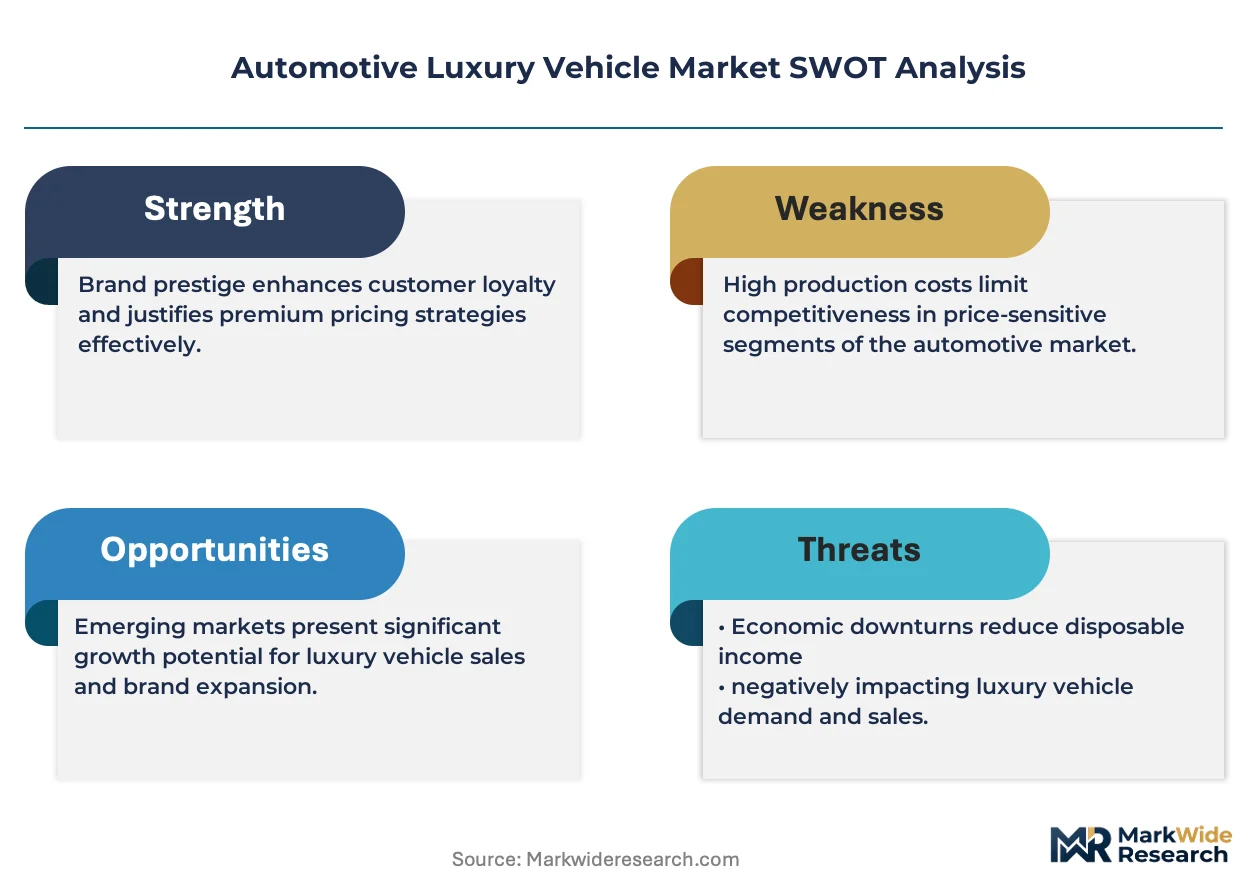
- EU Green Deal fleet standards:Binding CO2 reduction targets for 2035 are redirecting R&D budgets toward battery-electric architectures and expanding compliant model availability.
- Ultra-high-net-worth private buyers:Concentrated wealth formation in China's tier-one cities and surrounding economic corridors is sustaining order backlogs for bespoke configurations.
- Cell chemistry advances:Silicon-anode and solid-state prototypes are extending range thresholds and reducing charging anxiety among first-time electric adopters.
Market Restraints
- Lithium and cobalt price volatility:Concentrated upstream mining in the Democratic Republic of Congo and South America creates input cost instability for battery pack assembly.
- Semiconductor supply concentration:Advanced node fabrication for autonomous driving chips remains concentrated in Taiwan, exposing production schedules to single-point disruption.
- Charging infrastructure gaps:Sparse fast-charging networks across India's highway corridors and Southeast Asian secondary cities limit electric variant penetration outside urban cores.
Strategic Opportunities
- Subscription and mobility-as-a-service models:Fleet operators in Germany and the United Kingdom are piloting flexible tenure arrangements that decouple asset ownership from usage rights.
- Hydrogen fuel-cell integration:Long-haul luxury coaches and executive shuttles are testing proton-exchange-membrane stacks for routes exceeding battery-electric practical range.
- Software-defined vehicle architectures:Over-the-air feature activation and tiered capability unlocking are creating recurring revenue streams independent of initial transaction value.
Industry Challenges
- Embedded systems cybersecurity certification:The EU AI Act and forthcoming UN R155/R156 compliance timelines are extending validation cycles for autonomous features by 8-14 months.
- Powertrain engineering talent scarcity:Competition for battery thermal management specialists and motor control firmware engineers is inflating compensation premiums across OEMs and tier-one suppliers.
- Legacy dealership network reconfiguration:Direct-to-consumer sales mandates in select US states and European markets are forcing arbitration with franchise holders holding territorial exclusivity contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Luxury Vehicle Market |
| Market Size in 2026 | $687.4 Billion |
| Market Size in 2035 | $1,242.66 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SUV, Sedan, Coupe, Convertible Technology: Hybrid, Electric, Gasoline, Diesel End User: Corporate Fleet, Private Buyers, Luxury Rental Services, Government Officials Features: Advanced Safety, High-Performance, Customization Options, Smart Connectivity |
| Companies Covered | Mercedes-Benz, BMW, Audi, Lexus, Porsche, Infiniti, Acura, Cadillac, Jaguar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Luxury Vehicle Market Emerging Trajectories
Powertrain electrification is rewriting vehicle architecture fundamentals while software monetization and sustainable materials procurement are establishing new competitive battlegrounds beyond traditional manufacturing excellence.
Solid-state battery prototyping is rewriting range and safety benchmarks for premium electric vehicles. Ultra-high-net-worth buyers in China's tier-one cities are pre-ordering vehicles equipped with pilot production cells despite 18-24 month delivery windows. This technology is compressing the performance gap between electric and internal-combustion grand touring capabilities.
The EU AI Act's risk-classification framework for autonomous driving systems is mandating formal conformity assessments before market deployment. European luxury marques are restructuring validation workflows to document algorithmic transparency and fail-safe protocols. Battery-electric flagships with Level 3 highway automation are absorbing the heaviest compliance burden and delaying launch schedules.
Direct-to-consumer digital retail is displacing traditional dealership intermediaries in permitted jurisdictions. Younger ultra-high-net-worth buyers in Germany and California are completing entire transactions through configurators and virtual consultations. This channel shift is most visible in bespoke electric SUV segments where factory allocation scarcity supports waiting-list management without floorplan financing.
Automotive Luxury Vehicle Market Segmentation
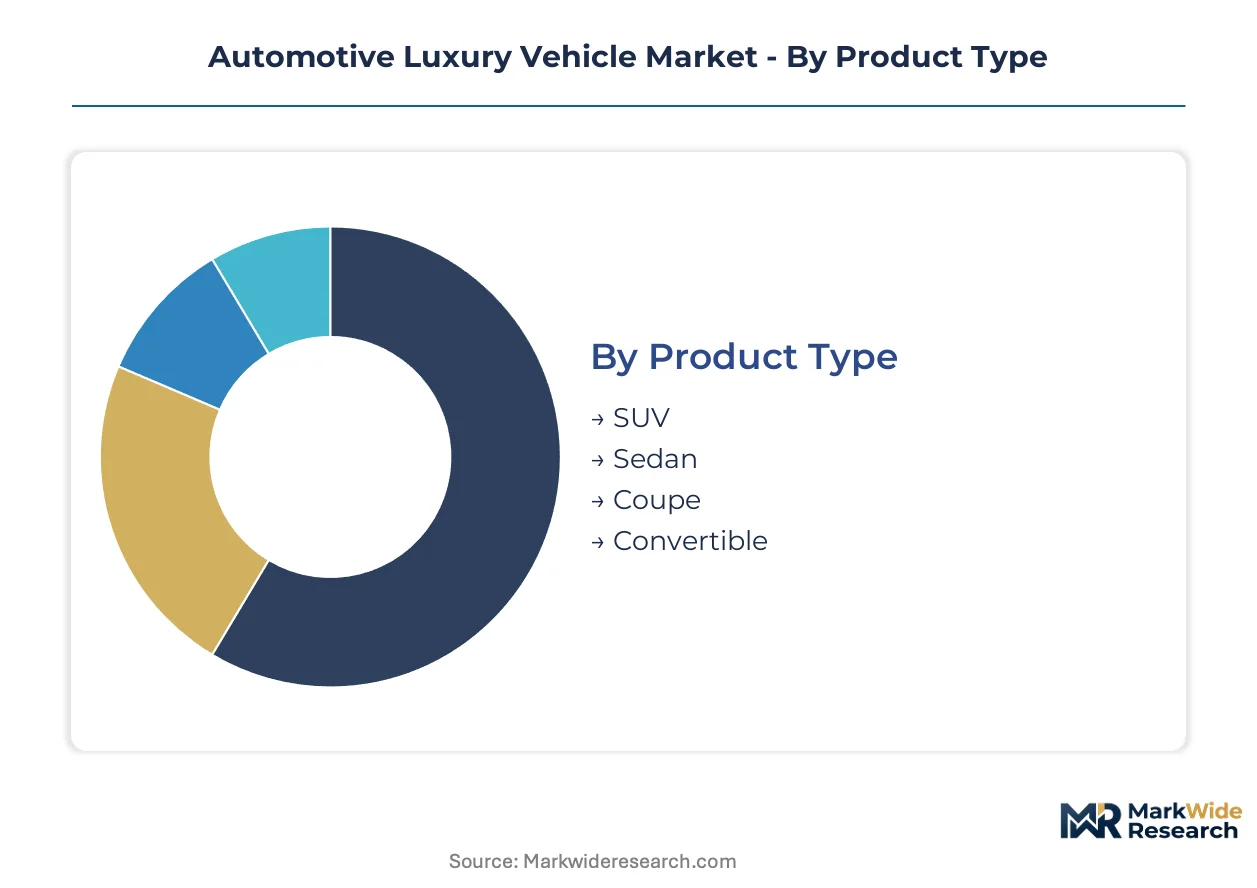
Luxury vehicle purchasing decisions cascade through multiple decision layers. Body style selection determines engineering platform allocation. Powertrain choice reflects regulatory exposure and infrastructure maturity. End-user category shapes financing structures and service expectations.
Product Type:
Body architecture selection now hinges on cabin flexibility and ground clearance expectations rather than traditional status signaling.
- SUV:Aluminum-intensive unibodies and adaptive air suspension deliver commanding driving positions and three-row versatility. China's tier-one cities and surrounding economic corridors absorb the majority of flagship SUV production, driven by road quality variability and multi-generational household transport needs.
- Sedan:Long-wheelbase configurations with rear-executive seating packages preserve formal transport protocols for government and corporate protocol. European fleet operators in Germany and the United Kingdom maintain sedan preferences for chauffeured executive services where trunk accessibility and step-in height matter.
- Coupe:Two-door silhouettes with frameless glass and sport-tuned chassis prioritize aesthetic purity over utility. Manufacturing volumes concentrate in Stuttgart and Munich production facilities serving aesthetic-driven private collectors.
- Convertible:Multi-layer acoustic soft-tops and reinforced A-pillars balance open-air driving with structural rigidity. Mediterranean coastal markets and California coastal counties sustain residual demand despite weather-dependent utilization patterns.
SUV leads on scale; Electric powertrain variants within SUV architecture gain share fastest.
Technology:
Powertrain selection now reflects regulatory compliance calendars and charging infrastructure density rather than performance preferences alone.
- Electric:Silicon-anode battery packs and 800-volt electrical architectures enable sub-20-minute charging protocols. China's MIIT new-energy vehicle quotas mandate local production requirements, accelerating factory retooling in Shanghai and Beijing manufacturing zones.
- Hybrid:Performance-oriented plug-in systems with thermal-optimized internal combustion bridges bridge regulatory thresholds and driver range expectations. Porsche and BMW deploy these architectures for customers traversing European highway corridors with inconsistent fast-charging coverage.
- Gasoline:Twin-turbo V8 and V12 configurations retain margin density in Middle Eastern markets and Southeast Asian secondary cities where charging infrastructure remains sparse.
- Diesel:Compression-ignition six-cylinder engines with selective catalytic reduction persist in long-distance executive transport and luxury coach applications across German Autobahn networks.
Electric climbs the fastest; Hybrid retains the broadest geographic coverage.
End User:
Customer category determines warranty structures, financing instruments, and residual value management approaches.
- Corporate Fleet:Multi-year lease arrangements with bundled maintenance and telematics reporting serve executive mobility programs. German and UK fleet operators pilot subscription models that decouple asset ownership from usage rights.
- Private Buyers:Ultra-high-net-worth individuals in China's tier-one cities sustain order backlogs for bespoke configurations with extended delivery windows.
- Luxury Rental Services:Short-term tenure operators in Dubai, Miami, and Monaco prioritize rapid depreciation schedules and standardized service protocols.
- Government Officials:Protocol-driven procurement with domestic content requirements shapes availability in Beijing, New Delhi, and Riyadh.
Private buyers lead on absolute transaction value; Corporate fleet represents the steepest expansion trajectory for mobility-as-a-service pilots.
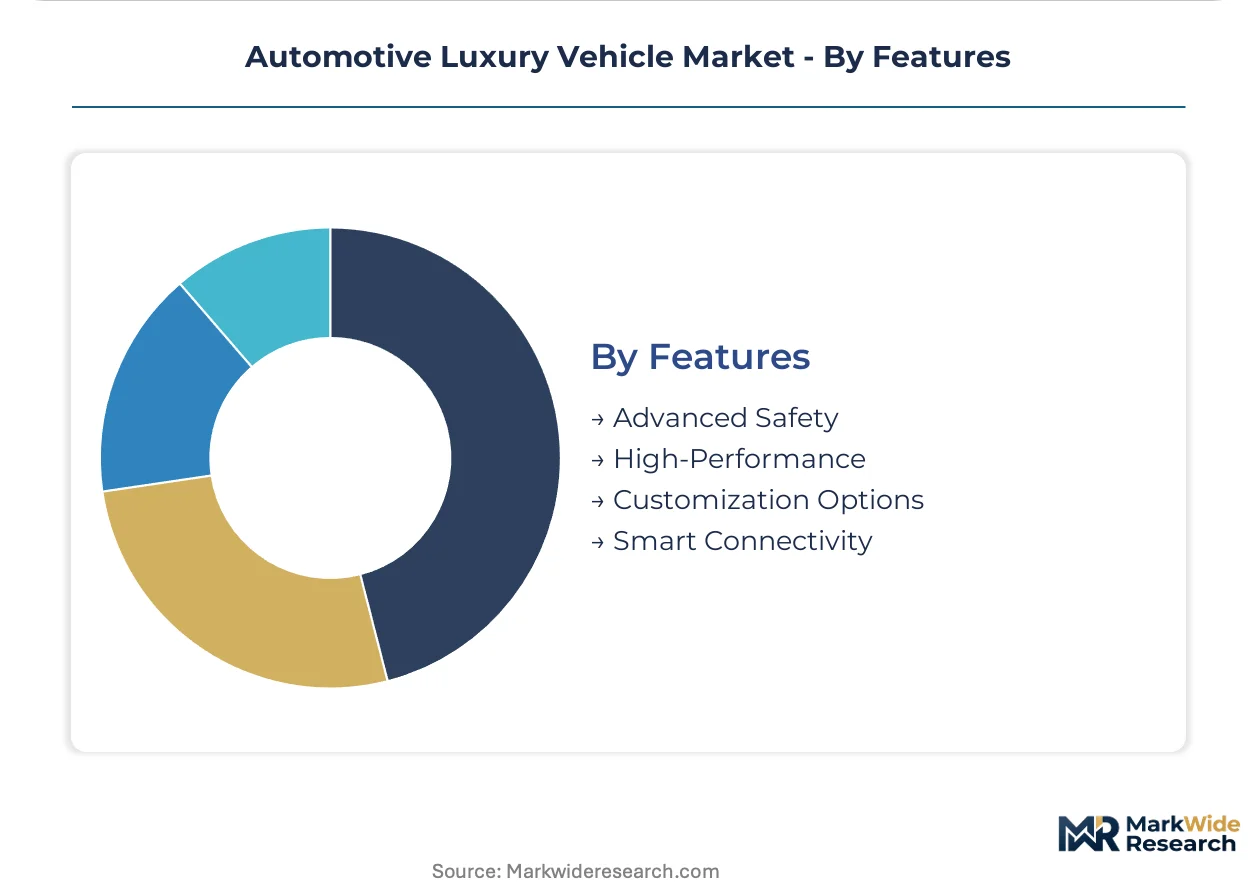
Features:
Capability bundling now follows software-defined vehicle architectures enabling over-the-air activation rather than factory-locked configurations.
- Advanced Safety:LiDAR fusion and redundant braking systems for Level 3 highway automation. EU AI Act compliance timelines extend validation cycles for these configurations.
- High-Performance:Carbon-ceramic braking, torque-vectoring differentials, and track-calibrated suspension modes.
- Customization Options:Bespoke interior materials, individual exterior color matching, and monogrammed componentry.
- Smart Connectivity:Proprietary operating systems with tiered capability unlocking and recurring revenue streams.
Smart connectivity leads on margin expansion potential; Advanced safety carries the heaviest regulatory compliance burden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Powertrain engineering talent clusters in Stuttgart, Munich, and Shanghai anchor the industry's geographic footprint. Battery thermal management specialists command premium compensation across these manufacturing zones. Regulatory divergence between Brussels and Beijing forces dual-certification investments that reshape factory allocation decisions.
China
Ultra-high-net-worth private buyers in Shanghai, Beijing, and Shenzhen sustain order backlogs for bespoke configurations with 18-24 month delivery windows. MIIT new-energy vehicle quotas mandate local production requirements for imported brands, accelerating retooling in Shanghai and Beijing manufacturing zones. The Yangtze River Delta absorbs the majority of flagship SUV production serving tier-one cities and surrounding economic corridors.
Germany
Corporate fleet operators in Berlin and Munich pilot subscription models that decouple asset ownership from usage rights. The EU Green Deal's binding CO2 reduction targets for 2035 redirect R&D budgets toward battery-electric architectures. Stuttgart and Munich production facilities concentrate manufacturing volumes for aesthetic-driven private collectors seeking coupe configurations.
United States
EPA tailpipe standards and California Air Resources Board mandates shape product availability across showrooms in Los Angeles, San Francisco, and New York. Younger ultra-high-net-worth buyers in California complete entire transactions through configurators and virtual consultations. Direct-to-consumer sales mandates in select states force arbitration with franchise holders holding territorial exclusivity contracts.
United Kingdom
Chauffeured executive services in London maintain sedan preferences where trunk accessibility and step-in height matter for protocol-driven transport. German Autobahn networks sustain diesel compression-ignition demand for long-distance executive transport. The EU AI Act's risk-classification framework mandates formal conformity assessments before market deployment of autonomous features.
Japan
Silicon-anode and solid-state battery prototyping extends range thresholds for premium electric vehicles targeting first-time adopters. METI industrial policy supports domestic cell chemistry advances and manufacturing equipment exports. The Kanto region around Tokyo concentrates validation workflows for algorithmic transparency and fail-safe protocols under tightening cybersecurity frameworks.
Automotive Luxury Vehicle Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across divergent capability requirements. The vendor base concentrates around integrated manufacturing groups with captive powertrain development against specialist coachbuilders relying on contracted component supply. Three archetypes dominate: vertically integrated OEMs controlling cell manufacturing and proprietary operating systems; performance-focused marques bridging hybrid architectures; and technology-licensing specialists supplying autonomous driving platforms. M&A activity targets battery thermal management engineering teams, while strategic partnerships secure silicon-anode and solid-state cell supply.
Within the integrated OEM tier, Mercedes-Benz and BMW anchor positions through upstream control over critical component supply and in-house software development. Porsche occupies a distinctive position bridging performance-oriented hybrid architectures with regulatory compliance thresholds. These three German marques exemplify the capital-intensive archetype that dominates engineering resource allocation and factory capacity planning across the industry's premium segments.
| Leading Market Players |
|---|
| Mercedes-Benz |
| BMW |
| Audi |
| Lexus |
| Porsche |
| Infiniti |
| Acura |
| Cadillac |
| Jaguar |
| Others |
Supply Flow & Price Mechanics
Lithium carbonate price indices cascading through cathode active material contracts are compressing battery pack costs and enabling tiered pricing stratification across electric, hybrid, and gasoline powertrain variants. This commodity-driven cost architecture feeds into manufacturer pricing power, with captive cell production anchoring margin retention for vertically integrated OEMs while contract-dependent assemblers absorb volatility.
Pricing Analysis
Bundled subscription services decoupling asset ownership from usage rights are displacing traditional transaction-based pricing in German and UK corporate fleet channels. Price differentiation rests on powertrain certification tier and after-sales service bundling, with battery-electric flagships commanding premiums for silicon-anode configurations. Pricing pressure stems from lithium and cobalt input volatility, though ultra-high-net-worth private buyers in China's tier-one cities exhibit minimal sensitivity compared to fleet operators negotiating multi-year lease terms.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based advanced node fabrication for autonomous driving chips and Democratic Republic of Congo cobalt concentrate. Geographic supply concentration centers on China for cell manufacturing equipment, South Korea for cathode materials, and Germany for powertrain engineering talent. Raw material dependencies span lithium spodumene, rare earth permanent magnets, and high-purity silicon anode feedstock. Tariff exposure on battery components imported into the European Union threatens production schedules. Distribution runs through franchised dealership networks facing direct-to-consumer displacement mandates in select US states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive luxury vehicle market functions as a stable compounder anchored by ultra-high-net-worth wealth formation in Asia-Pacific economic corridors that sustains order backlogs regardless of cyclical pressure.
For Market Incumbents: Lock in proprietary operating system development and captive cell manufacturing capacity to defend against technology-licensing specialists encroaching on software monetization. Prioritize backward integration into silicon-anode supply agreements to neutralize lithium price volatility exposure. Arbitration with franchise holders over direct-to-consumer sales mandates demands immediate legal resource allocation. For New Entrants and Emerging Players: The price-point gap between bespoke electric SUVs and mass-market electric crossovers offers white-space capture in China's tier-two cities where charging infrastructure is maturing. Target corporate fleet subscription pilots in Germany and the United Kingdom where asset-light mobility-as-a-service models decouple ownership from usage. A software-defined vehicle architecture with over-the-air capability unlocking provides the cleanest go-to-market angle against capital-intensive manufacturing incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with battery thermal management engineering teams and solid-state cell prototyping specialists given powertrain talent scarcity. The five-to-ten year viability window favors acquisition targets with MIIT quota-compliant production footprints in Shanghai or Beijing manufacturing zones. Monitor EU AI Act validation cycle extensions as the inflection signal for autonomous feature deployment delays that would compress valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Silicon-anode cell contracts with South Korean suppliers secure range thresholds for flagship electric SUVs. |
| Software-Defined Vehicle Investment | Proprietary operating systems enable recurring revenue through over-the-air feature activation tiers. |
| Charging Infrastructure Partnership | Fast-charging network alliances in India's highway corridors address penetration barriers outside urban cores. |
| Geographic Manufacturing Footprint | Shanghai and Beijing zone retooling satisfies MIIT new-energy vehicle quotas for imported brands. |
| Platform Standardization | EQ-architecture sharing across Mercedes-Benz electric variants amortizes battery-electric R&D across volume. |
Methodological Framework
Multiple input streams — OEM platform engineering disclosures, Tier 1 supplier procurement data, and vehicle registration databases — were reconciled through bottom-up and top-down triangulation. Primary interviews with battery thermal management specialists, motor control firmware engineers, dealership operations heads, and corporate fleet procurement managers were validated against secondary sources including IHS Markit registration data, MIIT production filings, and EU Green Deal compliance disclosures. Cross-referencing production volumes with cathode material trade flows anchored cost structure assumptions.
Data-stream reconciliation across vehicle class, propulsion architecture, and regional production cluster dimensions generated volume and value outputs throughout the forecast period. CAGRs were derived from segment-level growth trajectory modeling incorporating powertrain transition timelines, regulatory compliance calendars, and infrastructure buildout assumptions. Forecast inputs included silicon-anode cell chemistry maturation curves and EU AI Act validation burden estimates for Level 3 highway automation systems.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook for electric variant penetration timelines. Forecasts reflect assumptions regarding lithium supply elasticity, semiconductor fabrication capacity expansion, and charging infrastructure deployment cadence across Southeast Asian secondary cities. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
China Luxury Car Market
Passenger Vehicles
Indonesia Passenger Car Market
Passenger Vehicles
Family Car Market
Passenger Vehicles
Minivans Market
Passenger Vehicles
Russia Light Vehicle Market
Passenger Vehicles
North American Lightweight Car Market
Passenger Vehicles
Convertible Vehicles Market
Passenger Vehicles
Sports Utility Vehicles (Suvs) Market
Passenger Vehicles
North America Automotive Market
Passenger Vehicles
South America Passenger Cars Market
Passenger Vehicles
Passenger Vehicle Market
Passenger Vehicles
Compact Cars Market
Passenger Vehicles
Luxury Car Market
Passenger Vehicles
India Automotive Market
Passenger Vehicles
Electric Passenger Car MRO Market
Passenger Vehicles
Quadricycle and Tricycle Market