
 Automotive Passenger Vehicle Sensor Market | 2026-2036
Automotive Passenger Vehicle Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Passenger Vehicle Sensor Market Outlook
A capital-intensity divergence between integrated semiconductor foundries and fabless sensor designers is reorganizing competitive tiers in automotive sensing. Robert Bosch GmbH leverages in-house MEMS fabrication to control cost structures across radar and ultrasonic modules. Infineon Technologies AG anchors its position through SiGe-based radar chipsets that supply multiple tier-1 module makers. Allegro MicroSystems LLC specializes in magnetic position sensing for electric powertrain applications, occupying a narrow but defensible niche.
Automotive passenger vehicle sensors are electromechanical or solid-state devices that detect physical parameters including proximity, velocity, optical flow, or magnetic field orientation, converting these inputs into electrical signals processed by vehicle control units. These components typically operate across temperature ranges from minus forty to one hundred fifty degrees Celsius and must satisfy ISO 26262 functional safety integrity levels for deployment in braking and steering systems. Camera-based segments lead installed value due to multi-lens front-facing arrays for collision avoidance, while radar sustains the largest unit volumes across adaptive cruise control applications. Ultrasonic modules dominate parking assistance with mature, low-cost implementations, though lidar adoption in electric vehicles is accelerating as OEMs pursue higher automation classifications.
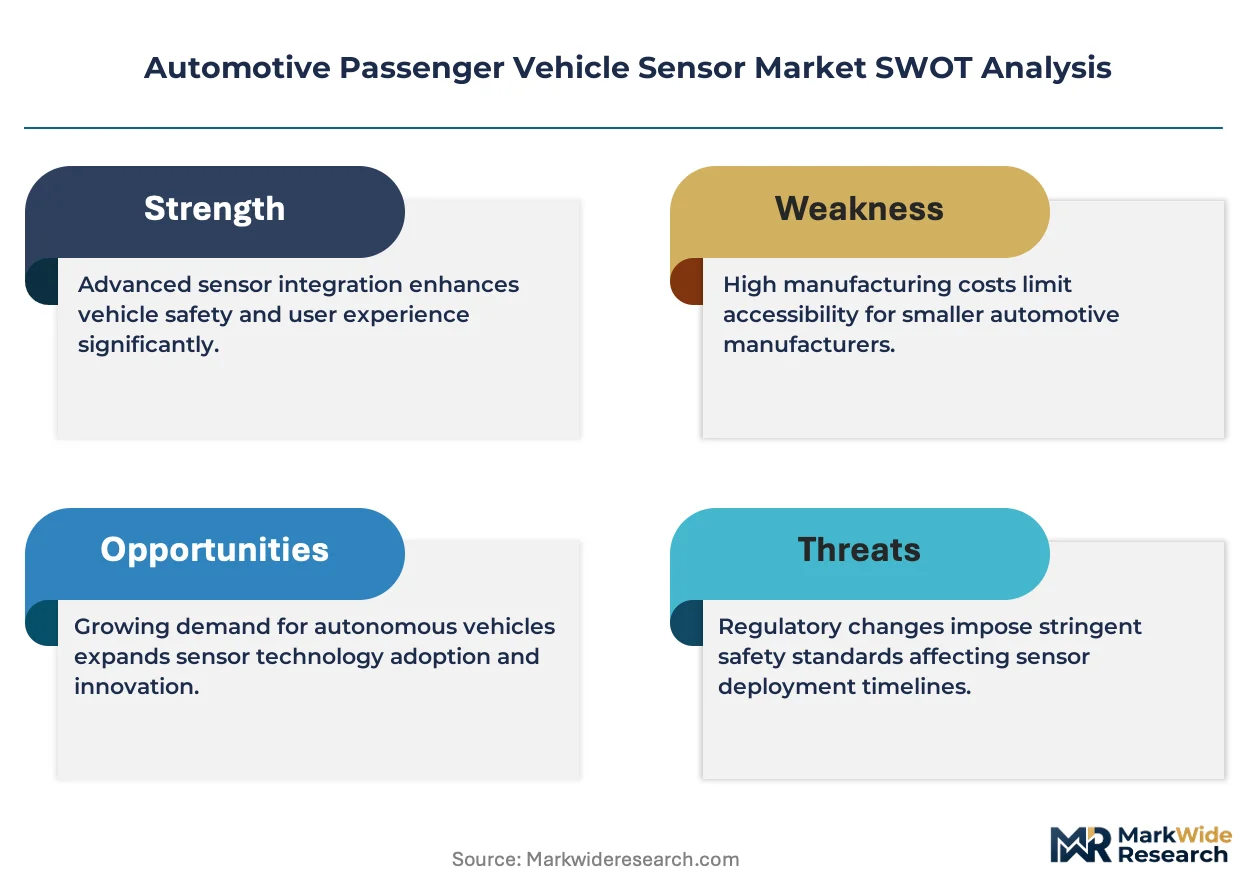
NHTSA in the United States, Euro NCAP in Europe, and MIIT in China each mandate specific sensor redundancy levels for automatic emergency braking and lane-keeping systems, directly dictating per-vehicle sensor counts and certification costs. REACH and RoHS compliance in Europe plus China's GB standards for electromagnetic compatibility constrain material selection and design architectures for suppliers seeking multi-region eligibility. Stakeholders must monitor divergence between NHTSA's pending pedestrian AEB rules and Euro NCAP's evolving scoring protocols, as misaligned timelines could fragment platform development budgets across regulatory zones.
Market Dynamics
Sensor fusion architectures are compressing module counts per vehicle while elevating per-unit performance thresholds, forcing suppliers to consolidate discrete functions into integrated SoC platforms that satisfy ISO 26262 ASIL-D requirements for autonomous braking and steering domains.
Growth Catalysts
- Euro NCAP 2026 protocols:Mandated sensor redundancy for automatic emergency braking and vulnerable road user detection is expanding per-vehicle camera and radar counts across European OEM platforms.
- Silicon carbide power electronics:Adoption in electric drivetrains is generating demand for high-temperature magnetic position sensors capable of operating above 150°C in motor control applications.
- MIIT intelligent vehicle standards:China's classification framework for conditional automation is accelerating lidar procurement cycles among domestic electric vehicle manufacturers.
Market Restraints
- Advanced packaging substrates:Supply constraints on ABF and glass core materials for high-density interposers are extending lead times for radar and lidar signal processing chips.
- Wafer-level MEMS fabrication:Concentration of 8-inch MEMS foundry capacity in Germany and Japan creates geographic vulnerability for ultrasonic and pressure sensor supply.
- Functional safety certification:ISO 26262 ASIL-D validation cycles consume 18-24 months, freezing design architectures and limiting mid-cycle technology refresh options.
Strategic Opportunities
- India PLI scheme for automotive components:Localized sensor manufacturing incentives are opening production footholds for export-oriented suppliers targeting Middle Eastern and African markets.
- 4D imaging radar:Convergence of MIMO antenna arrays and machine learning-based point cloud processing is enabling elevation detection without lidar cost structures.
- Over-the-air calibration:Cloud-based sensor alignment services are creating recurring revenue streams independent of hardware replacement cycles.
Industry Challenges
- Embedded software talent:Shortage of engineers proficient in AUTOSAR Adaptive and functional safety verification is constraining Tier-1 development bandwidth for domain controller integration.
- Multi-protocol validation:Simultaneous compliance with NHTSA, Euro NCAP, and MIIT test protocols is fragmentating engineering resources and diluting platform commonality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Passenger Vehicle Sensor Market |
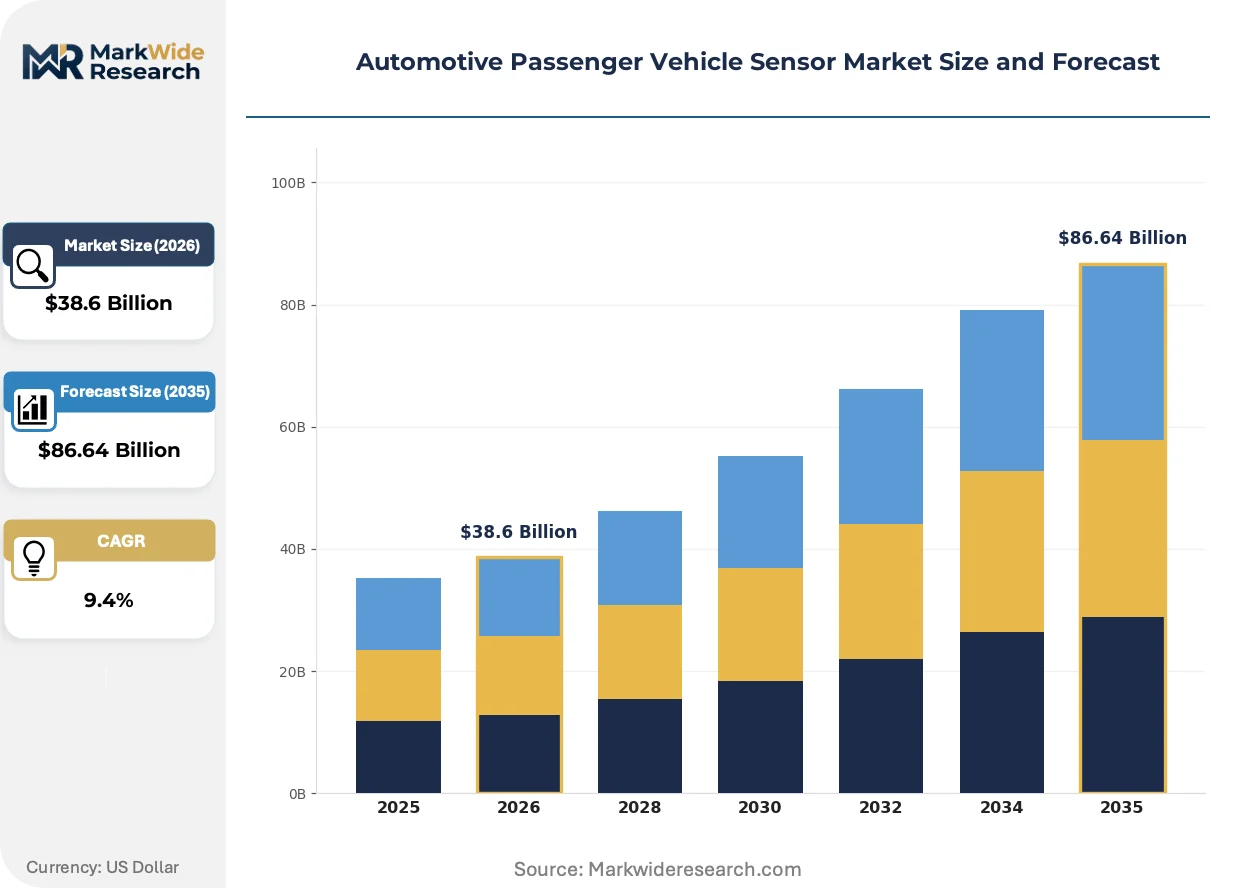
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $86.64 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: Radar, Lidar, Camera, Ultrasonic Application: Adaptive Cruise Control, Collision Avoidance, Lane Departure Warning, Parking Assistance Vehicle Type: Electric Vehicles, SUVs, Sedans, Hatchbacks End User: OEMs, Aftermarket, Fleet Operators, Ride-Sharing Services |
| Companies Covered | Continental AG, Allegro MicroSystems LLC, Robert Bosch GmbH, Aptiv PLC, Melexis NV, Infineon Technologies AG, DENSO Corporation, Honeywell International Inc., NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Passenger Vehicle Sensor Market Strategic Shifts
Solid-state technologies are displacing electromechanical architectures across proximity and motion detection applications, compressing form factors while expanding operational temperature envelopes. Three developments are restructuring competitive positioning.
Silicon photonics-based frequency-modulated continuous wave lidar is miniaturizing optical phased arrays onto CMOS-compatible substrates. Automotive OEMs in premium electric segments are qualifying these devices for highway pilot functions. The technology is compressing mechanical beam-steering component counts from hundreds to single-digit solid-state elements.
REACH substance restrictions on PFAS and certain flame retardants are forcing material substitutions in sensor housings and cable assemblies. European suppliers are reformulating polymer compounds to maintain IP ratings without restricted additives. Camera module manufacturers are accelerating validation of alternative potting compounds to preserve supply eligibility.
Fleet operators and mobility service providers are consolidating sensor procurement through direct tier-2 relationships, bypassing traditional module integrators. This disintermediation is most visible in North American autonomous shuttle deployments, where end-users specify chip-level performance requirements and manage integration in-house. Tier-1 suppliers are responding with unbundled software licensing to preserve margin contribution.
Automotive Passenger Vehicle Sensor Market Segmentation
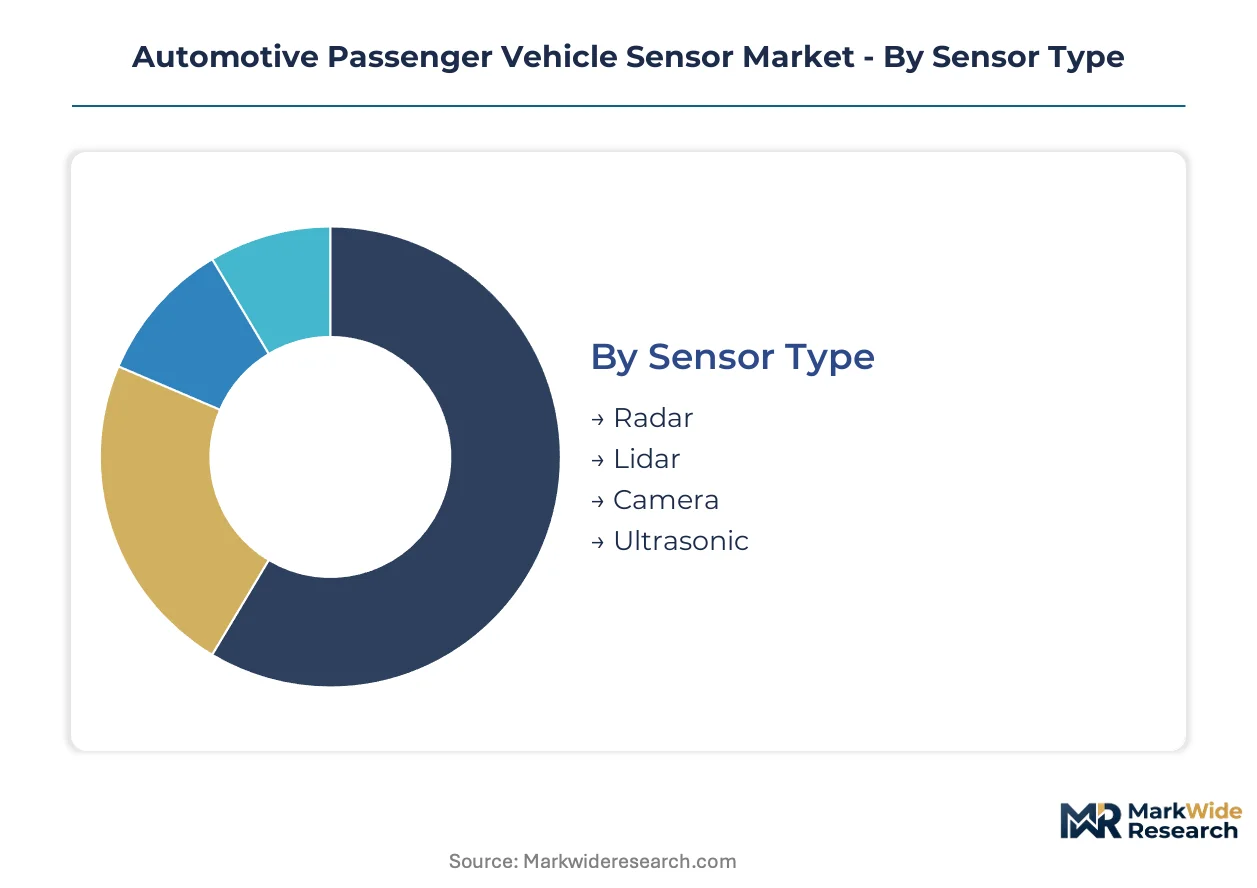
Sensor procurement patterns diverge sharply across vehicle electrification levels and automation tiers. Tier-1 suppliers configure module portfolios differently for mass-market internal combustion platforms versus premium electric architectures with redundant sensing stacks.
Sensor Type:
Domestic consumption in Germany and Japan absorbs the majority of radar and ultrasonic output, while lidar and advanced camera arrays ship disproportionately to Chinese electric vehicle assembly plants.
- Radar:Frequency-modulated continuous wave architectures dominate adaptive cruise control implementations. German OEMs anchor procurement volumes for 77 GHz front-facing modules, though Chinese manufacturers are scaling 4D imaging variants for highway pilot functions.
- Camera:Multi-lens front-facing arrays process optical flow for collision avoidance and traffic sign recognition. Japanese tier-1 suppliers concentrate production of 8-megapixel modules for Euro NCAP-compliant platforms.
- Lidar:Solid-state frequency-modulated continuous wave devices are qualifying for premium electric vehicle highway automation.
- Ultrasonic:Mature piezoelectric designs saturate parking assistance with minimal cost erosion.
Radar commands the established base. The steepest expansion runs through camera arrays.
Application:
Cost tier stratification separates mandated safety functions from discretionary convenience features, with regulatory compliance driving premium module specifications.
- Collision Avoidance:Multi-sensor fusion architectures combine camera, radar, and lidar inputs for automatic emergency braking. NHTSA pending rules and Euro NCAP protocols mandate redundant detection layers, elevating per-vehicle sensor counts.
- Adaptive Cruise Control:Long-range radar modules maintain following distances at highway speeds. German autobahn-capable platforms specify 250-meter detection ranges with weather-resistant waveforms.
- Lane Departure Warning:Camera-based edge detection algorithms process road markings with sub-degree accuracy.
- Parking Assistance:Ultrasonic ring arrays dominate low-speed maneuvering with mature cost structures.
Collision avoidance absorbs the highest module value per vehicle. Adaptive cruise control delivers the broadest installed base penetration.
Vehicle Type:
Application intensity varies by platform architecture, with electric vehicles integrating substantially higher sensor counts for automation and powertrain management.
- Electric Vehicles:Battery management and motor control demand magnetic position sensors operating above 150°C. Silicon carbide inverters drive procurement of high-temperature capable Hall-effect devices.
- SUVs:Higher belt lines and larger frontal areas necessitate extended-range radar for pedestrian detection. Premium segments qualify lidar for urban automation.
- Sedans:Cost-optimized sensor suites prioritize camera and radar combinations for lane-keeping and adaptive cruise.
- Hatchbacks:Entry-level platforms rely on ultrasonic parking assistance with single-camera forward collision warning.
SUVs carry the highest per-unit sensor value. Electric vehicles are climbing the fastest.
End User:
Procurement authority is shifting from traditional tier-1 module integrators toward direct OEM and fleet operator relationships.
- OEMs:Platform engineering teams specify sensor performance thresholds and functional safety integrity levels. Vertical integration into in-house perception software is compressing tier-1 margin capture.
- Fleet Operators:Autonomous shuttle deployments in North America bypass module integrators for direct chip-level procurement. End-users manage sensor fusion integration internally.
- Aftermarket:Retrofit advanced driver-assistance systems face calibration complexity and warranty liability constraints.
- Ride-Sharing Services:Mobility providers consolidate sensor procurement across vehicle pools with standardized maintenance protocols.
OEMs retain volume dominance. Fleet operators are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese production clusters while Chinese electric vehicle platforms command volume premiums. Module procurement costs diverge by fifteen to twenty percent between European premium tier-1 supply and Asia-Pacific scale manufacturing.
United States
NHTSA pending pedestrian automatic emergency braking rules and domestic electric vehicle tax credits expand per-vehicle sensor counts. The Inflation Reduction Act localizes content requirements for battery management magnetic sensors. Detroit-Warren-Dearborn anchors radar module assembly for North American OEM platforms.
Germany
Autobahn-capable adaptive cruise control specifications and Euro NCAP 2026 vulnerable road user mandates drive 77 GHz radar demand. KBA type approval processes enforce ISO 26262 functional safety certification timelines. Stuttgart and Ingolstadt production corridors concentrate MEMS fabrication for ultrasonic and pressure sensing.
China
MIIT intelligent vehicle classification for conditional automation accelerates lidar procurement among domestic electric vehicle manufacturers. GB standards for electromagnetic compatibility constrain multi-region platform designs. Shenzhen and Shanghai assembly plants absorb disproportionate volumes of solid-state optical phased arrays.
Japan
METI carbon neutrality roadmaps and domestic OEM autonomous driving timelines sustain camera and radar module demand. JIS standards for automotive electromagnetic immunity shape sensor housing material selection. Nagoya and Tokyo-Yokohama corridors anchor 8-megapixel camera production for Euro NCAP-compliant exports.
India
PLI scheme incentives for automotive components open localized manufacturing footholds for export-oriented suppliers. BIS certification requirements for electronic subassemblies extend validation timelines for temperature-resilient designs. Pune and Chennai industrial belts concentrate magnetic position sensor assembly for electric two-wheeler and passenger vehicle powertrains.
Automotive Passenger Vehicle Sensor Market Competitive Environment
Concentration sits with diversified semiconductor conglomerates and specialized magnetic sensing houses. Tier-1 module integrators face margin compression as OEMs internalize perception software and fleet operators disintermediate procurement channels. Two archetypes dominate: captive foundry operators controlling MEMS cost structures, and fabless designers licensing signal processing IP. Competitive moves center on backward integration into wafer-level fabrication and unbundled software licensing to preserve recurring revenue.
Among German diversified industrials, Robert Bosch GmbH and Infineon Technologies AG exemplify the captive foundry archetype through in-house MEMS and SiGe-based radar chipset production respectively. Allegro MicroSystems LLC occupies a position within the specialized magnetic sensing tier, anchoring narrow but defensible positioning in electric powertrain applications. These three entities represent the structural divergence between integrated fabrication and focused design specialization reshaping competitive tiers in automotive sensing.
| Leading Market Players |
|---|
| Continental AG |
| Allegro MicroSystems LLC |
| Robert Bosch GmbH |
| Aptiv PLC |
| Melexis NV |
| Infineon Technologies AG |
| DENSO Corporation |
| Honeywell International Inc. |
| NXP Semiconductors |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation agreements between German tier-1 suppliers and 8-inch MEMS foundries lock in wafer access while stabilizing unit cost projections for radar and ultrasonic modules across Euro NCAP-mandated platform cycles.
Pricing Analysis
The customization-premium spread between ASIL-D certified modules and standard-grade sensors runs 40-60 percent, with ISO 26262 validation tiers driving the primary wedge. Three-tier pricing structure across premium, standard, and economy levels separates safety-critical braking domain sensors from convenience-tier parking assistance. Cost compression in ultrasonic modules is intensifying because Chinese electric vehicle manufacturers are internalizing ring-array production. Fleet operators deploying autonomous shuttles exhibit the lowest price sensitivity due to total-cost-of-ownership framing, while aftermarket retrofit installers face acute margin pressure from calibration complexity.
Supply Chain Analysis
Strategic stockpile preferences among Japanese tier-1 suppliers contrast with just-in-time inventory models prevalent in European module assembly, reflecting divergent risk tolerances for 8-inch MEMS wafer availability. Geographic concentration centers on Germany for radar chipset fabrication, Taiwan for advanced packaging substrates, and Japan for camera module optics. Raw material dependencies include silicon carbide substrates for high-temperature magnetic sensors, ABF laminate for radar signal processing interposers, and rare-earth elements for lidar beam-steering actuators. Single-source vulnerability in solid-state lidar optical phased arrays poses structural risk. Distribution runs through captive tier-1 module integrators toward OEM platform engineering teams, with fleet operators increasingly disintermediating direct chip procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around OEM platform engineering teams and North American fleet operators, fragmenting traditional tier-1 margin capture as direct procurement relationships bypass module integrators.
For Market Incumbents: Secure captive MEMS foundry capacity or binding long-term offtake agreements with German and Japanese wafer suppliers to defend against fabless entrants exploiting ABF substrate constraints. Deepen backward integration into SiGe radar chipset production, mirroring Infineon Technologies AG's supply architecture. Invest in unbundled software licensing for sensor fusion algorithms to preserve recurring revenue as hardware margins compress from OEM vertical integration into perception stacks.
For New Entrants and Emerging Players: Over-the-air calibration service gaps where incumbent tier-1 suppliers under-serve fleet operators and mobility providers present immediate white-space opportunity. Target India's PLI scheme manufacturing incentives for magnetic position sensor assembly serving Middle Eastern and African electric vehicle export markets. Pursue direct relationships with autonomous shuttle deployers in North America, specifying chip-level performance thresholds and managing sensor fusion integration in-house rather than through traditional module channels.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized magnetic sensing houses with proven 150°C+ temperature resilience for silicon carbide powertrain applications, offering narrow but defensible positioning against diversified semiconductor conglomerates. Long-term viability hinges on differentiation through functional safety certification depth rather than commodity scale. Watch for inflection when MIIT intelligent vehicle classification revisions accelerate lidar procurement minimums beyond current conditional automation tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | OEM consolidation of sensor fusion architectures reduces module count while elevating per-unit ASIL-D performance thresholds. |
| Battery Supply Agreement | Long-term offtake for silicon carbide inverters drives correlated demand for high-temperature magnetic position sensors. |
| Software-Defined Vehicle Investment | Cloud-based sensor calibration services create recurring revenue independent of hardware replacement cycles. |
| Geographic Manufacturing Footprint | India PLI scheme localization opens export-oriented production footholds for Middle Eastern and African markets. |
| Charging Infrastructure Partnership | Electric vehicle platform scale effects accelerate lidar and 4D imaging radar procurement for highway automation. |
Study Parameters
Cross-validation between OEM platform engineering interviews and tier-1 supplier procurement disclosures anchors the qualitative findings on sensor fusion architecture roadmaps. Primary fieldwork engaged Tier 1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and fleet operator technology officers across Germany, Japan, the United States, and China. Secondary sources included vehicle production databases, IHS Markit registration data, NHTSA rulemaking dockets, Euro NCAP protocol documentation, and MIIT intelligent vehicle classification frameworks. Bottom-up sensor unit economics triangulated against top-down OEM platform content forecasts.
Sensitivity analysis on electric vehicle penetration rates and automation classification timelines shapes the projection framework across the analysis window. Segmentation dimensions modeled include vehicle propulsion architecture, automation tier, sensor modality, functional safety integrity level, and regional regulatory cluster. CAGRs derive from installed base growth, content-per-vehicle expansion, and technology substitution effects. Industry-specific inputs encompass Euro NCAP 2026 protocol sensor redundancy minimums, silicon carbide inverter adoption curves, and solid-state lidar cost-down trajectories.
Forecasts assume regulatory continuity in NHTSA pedestrian AEB rulemaking, Euro NCAP vulnerable road user detection protocols, and MIIT conditional automation classifications; material policy shifts would require re-modeling sensor count minimums and certification cost structures. Revision becomes warranted when ABF substrate lead times or 8-inch MEMS foundry utilization rates cross thresholds that disrupt tier-1 module delivery commitments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
Electric Passenger Car MRO Market
Passenger Vehicles
Solar Passenger Car Market
Passenger Vehicles
Luxury Vehicles Market
Passenger Vehicles
Inland Water Passenger Transport Market
Passenger Vehicles
Ghana Automobile Market
Passenger Vehicles
Sports Utility Vehicles (Suvs) Market
Passenger Vehicles
Lightweight Cars Market
Passenger Vehicles
South America Passenger Cars Market
Passenger Vehicles
Asia Pacific Luxury Cars Market
Passenger Vehicles
China Luxury Car Market
Passenger Vehicles
Electric Sports Car Market
Passenger Vehicles
North America MUV Rental Market
Passenger Vehicles
Indonesia Passenger Car Market
Passenger Vehicles
India Luxury Car Market
Passenger Vehicles
Global Passenger Cars Market
Passenger Vehicles
Global Luxury SUV Market