
 Three-Wheeler Vehicle Market | 2026-2036
Three-Wheeler Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Three-Wheeler Vehicle Market Outlook
Dealer-financing networks across South Asia and Africa are reshaping how three-wheelers reach end users, with micro-lending institutions now originating a rising share of vehicle sales. Bajaj Auto leverages its captive finance arm to sustain dominance in India's rural hinterlands, while TVS Motor Company competes through dense service-station footprints that reduce downtime for commercial operators. Piaggio Group anchors European demand with premium gasoline models that command higher per-unit margins.
A three-wheeler vehicle is a motorized conveyance with one front steering wheel and two rear drive wheels, typically powered by internal combustion engines of 150–600cc displacement or lithium-ion battery packs of 3–10 kWh capacity, designed for short-haul passenger transport or light-cargo movement in congested urban environments. Passenger carriers retain the largest volume share across developing economies, though E-rickshaw variants are recording the fastest growth trajectory as fleet operators phase out pedal-powered alternatives. Electric powertrains concentrate margin pools in battery-pack and motor-controller supply chains, while gasoline models remain entrenched in regions with unreliable grid infrastructure.
India's Ministry of Road Transport and Highways enforces BS-VI emission standards that have eliminated two-stroke engine production, while the Automotive Research Association of India certifies electric range and safety protocols under FAME-II guidelines. Bangladesh's Road Transport Authority imposes fitness-certification requirements that accelerate fleet turnover toward CNG and electric platforms. Stakeholders must monitor subsidy-renewal timelines and charging-infrastructure deployment rates to calibrate production mix between powertrain technologies.
Market Dynamics
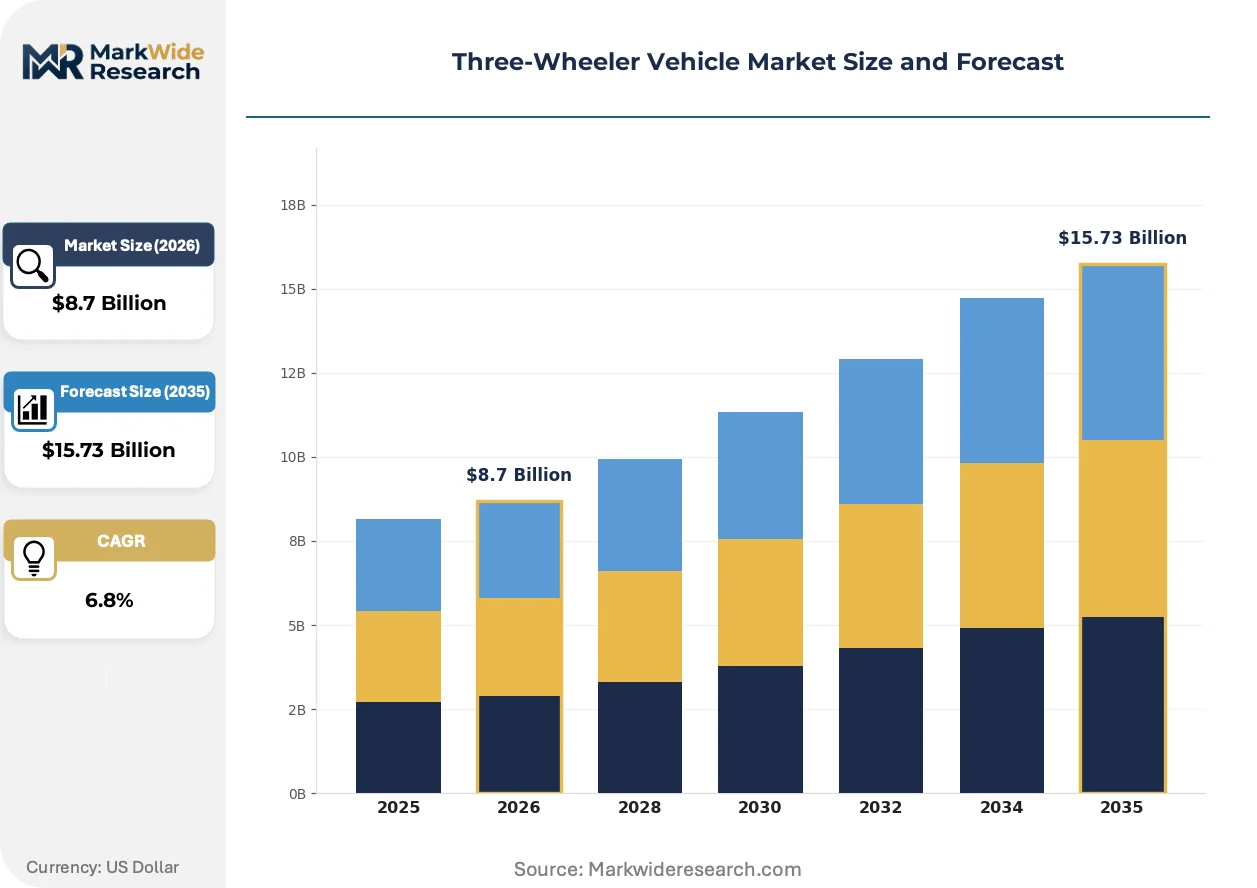
The three-wheeler vehicle market is undergoing a fundamental powertrain transition as FAME-II subsidies in India and CNG conversion mandates in Bangladesh accelerate displacement of gasoline-dominant fleets. Battery-electric platforms are capturing procurement preference among organized fleet operators, while informal para-transit segments lag due to charging infrastructure gaps.
Growth Catalysts
- India's FAME-II subsidy framework:The incentive structure covers 20% of vehicle cost for electric three-wheelers, redirecting manufacturer R&D toward lithium-ion platforms and motor-controller integration.
- Last-mile e-commerce logistics:Delivery aggregators across South Asia are consolidating vehicle procurement under centralized fleet managers who specify electric powertrains for TCO optimization.
- Bangladesh's urban corridor conversion:Unregulated para-transit operators in Dhaka and Chittagong are retrofitting gasoline engines to compressed natural gas systems ahead of pending emissions enforcement.
Market Restraints
- Lithium cell import concentration:Battery pack assembly depends on cylindrical and prismatic cells sourced predominantly from Chinese suppliers, exposing margins to raw material volatility and tariff friction.
- Grid reliability deficits:Rural and semi-urban areas across South Asia experience 8-12 hour daily power outages, rendering overnight charging uneconomical for commercial operators dependent on vehicle utilization rates.
- BS-VI compliance costs:India's emission standards eliminated two-stroke engine production, forcing gasoline manufacturers to absorb catalytic converter and fuel injection system cost premiums without commensurate pricing power.
Strategic Opportunities
- Battery swapping infrastructure:Station-based exchange networks eliminate range anxiety and asset downtime for commercial operators, with pilot deployments active in Delhi and Bangalore.
- East African urban corridors:Kenya and Tanzania's motorcycle-taxi economies present conversion potential as regulatory pressure mounts on two-stroke boda-boda emissions.
- Dealer-financing micro-lending convergence:Captive finance arms and rural banking cooperatives are originating vehicle loans at sub-14% interest rates, expanding addressable buyer pools beyond cash-purchase segments.
Industry Challenges
- Power electronics skill scarcity:Motor controller diagnostics and battery management system calibration require technician training that existing service networks have not systematically deployed.
- Homologation timeline compression:India's Automotive Research Association of India certification cycles for electric range validation and thermal runaway testing extend product launch schedules by 6-9 months versus gasoline equivalents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Three-Wheeler Vehicle Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger, Cargo, Utility, E-rickshaw Engine Type: Electric, Gasoline, Diesel, Hybrid Application: Public Transport, Goods Delivery, Recreational, Last-Mile Connectivity End User: Individual Users, Fleet Operators, Logistic Companies, Vendors |
| Companies Covered | Bajaj Auto, Mahindra & Mahindra, Piaggio Group, Tata Motors, TVS Motor Company, Atul Auto Limited, Terra Motors, Ashok Leyland, Lohia Auto Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Three-Wheeler Vehicle Market Strategic Shifts
Powertrain architecture is fragmenting across multiple fuel pathways as regulatory timelines diverge across South Asian markets. Manufacturers are hedging platform investments across electric, CNG, and advanced gasoline configurations rather than committing to single-technology dominance.
Lithium-iron-phosphate chemistry is migrating from premium passenger carriers to entry-level cargo variants as cell costs compress and thermal stability advantages outweigh energy density tradeoffs for short-haul duty cycles. Fleet operators in India's organized logistics segment are specifying LFP packs for 5,000-cycle durability guarantees. This chemistry migration from is compressing nickel-manganese-cobalt cell demand in the sub-10 kWh category.
Bangladesh's Road Transport Authority fitness-certification requirements are accelerating fleet turnover toward factory-built CNG and electric platforms rather than retrofitted conversions. The industrial consequence is a supply shortage of OEM-certified alternative-fuel vehicles relative to conversion workshop capacity. Commercial operators in Dhaka's formal para-transit cooperatives are absorbing 15-20% vehicle cost premiums to secure compliant factory builds ahead of enforcement deadlines.
Centralized procurement by e-commerce logistics platforms is displacing individual owner-operator purchasing across South Asian urban markets. Amazon India and Flipkart are consolidating three-wheeler sourcing under dedicated fleet management subsidiaries that specify standardized electric platforms with telematics integration. This concentration is most visible in Bangalore and Hyderabad, where dedicated dark-store delivery corridors operate 200+ vehicle electric fleets under single maintenance contracts.
Three-Wheeler Vehicle Market Segmentation
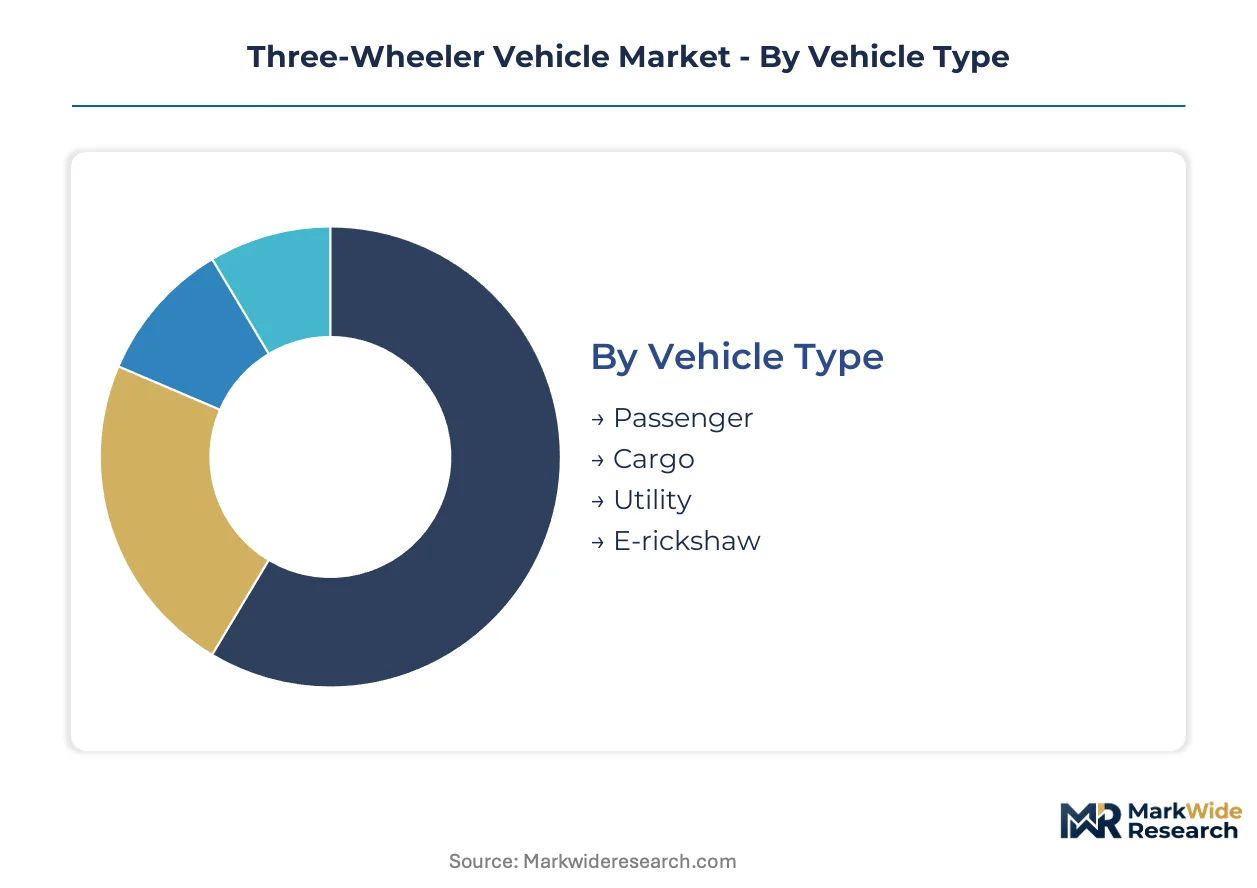
Three-wheeler segmentation tracks divergent powertrain economics and duty-cycle requirements across South Asian commercial fleets. Procurement patterns split sharply between informal owner-operators prioritizing acquisition cost and organized logistics platforms optimizing total cost of ownership.
Vehicle Type:
Cost tier determines platform selection across South Asian urban corridors, with passenger variants commanding premium positioning and cargo units absorbing volume concentration.
- Passenger:Configured with bench seating for 4-6 occupants and weather protection canopies, these units dominate Bangladesh's para-transit cooperatives and India's urban feeder routes. Dhaka's unregulated operators absorb 15-20% cost premiums for factory-built CNG compliance ahead of enforcement deadlines.
- E-rickshaw:Battery-powered platforms with 3-10 kWh lithium-ion packs displace pedal-powered alternatives across North Indian cities. Amazon India and Flipkart specify standardized electric variants with telematics integration for dedicated dark-store delivery corridors in Bangalore and Hyderabad.
- Cargo:Open-bed or enclosed-box configurations serve light-freight movement with 150-400 kg payload ratings.
- Utility:Modular platforms accommodate passenger-to-cargo conversion for seasonal demand fluctuations.
Passenger carriers command the established base. The steepest expansion runs through E-rickshaw platforms.
Engine Type:
Application requirements dictate powertrain selection, with commercial operators balancing acquisition cost against fuel access and regulatory compliance timelines.
- Electric:Lithium-iron-phosphate chemistry migrates from premium passenger carriers to entry-level cargo variants as cell costs compress. Fleet operators in India's organized logistics segment specify LFP packs for 5,000-cycle durability guarantees, compressing nickel-manganese-cobalt demand in the sub-10 kWh category.
- Gasoline:BS-VI compliant four-stroke engines with catalytic converters and fuel injection systems retain dominance in regions with unreliable grid infrastructure. Rural and semi-urban areas across South Asia experience 8-12 hour daily power outages, rendering overnight charging uneconomical for commercial operators.
- Diesel:Compression-ignition variants persist in heavy-load cargo applications requiring sustained torque output.
- Hybrid:Range-extender configurations with small gasoline generators address range anxiety without full grid dependency.
Gasoline powertrains anchor current fleet composition. Electric platforms are gaining share fastest among organized procurement channels.
Application:
Customer type segments procurement behavior, with individual operators selecting proven technologies and fleet managers specifying standardized platforms.
- Public Transport:Fixed-route and hail-ride passenger services in dense urban environments prioritize durability and passenger capacity over speed.
- Goods Delivery:E-commerce logistics platforms consolidate vehicle procurement under centralized fleet managers who specify electric powertrains for total cost optimization across last-mile networks.
- Last-Mile Connectivity:Feeder services connecting residential clusters to mass transit nodes concentrate demand in Indian metro peripheries.
- Recreational:Tourism and leisure applications in coastal and heritage districts represent niche demand with seasonal fluctuation.
Public transport absorbs the deepest fleet penetration. Goods delivery demonstrates the most rapid procurement consolidation.
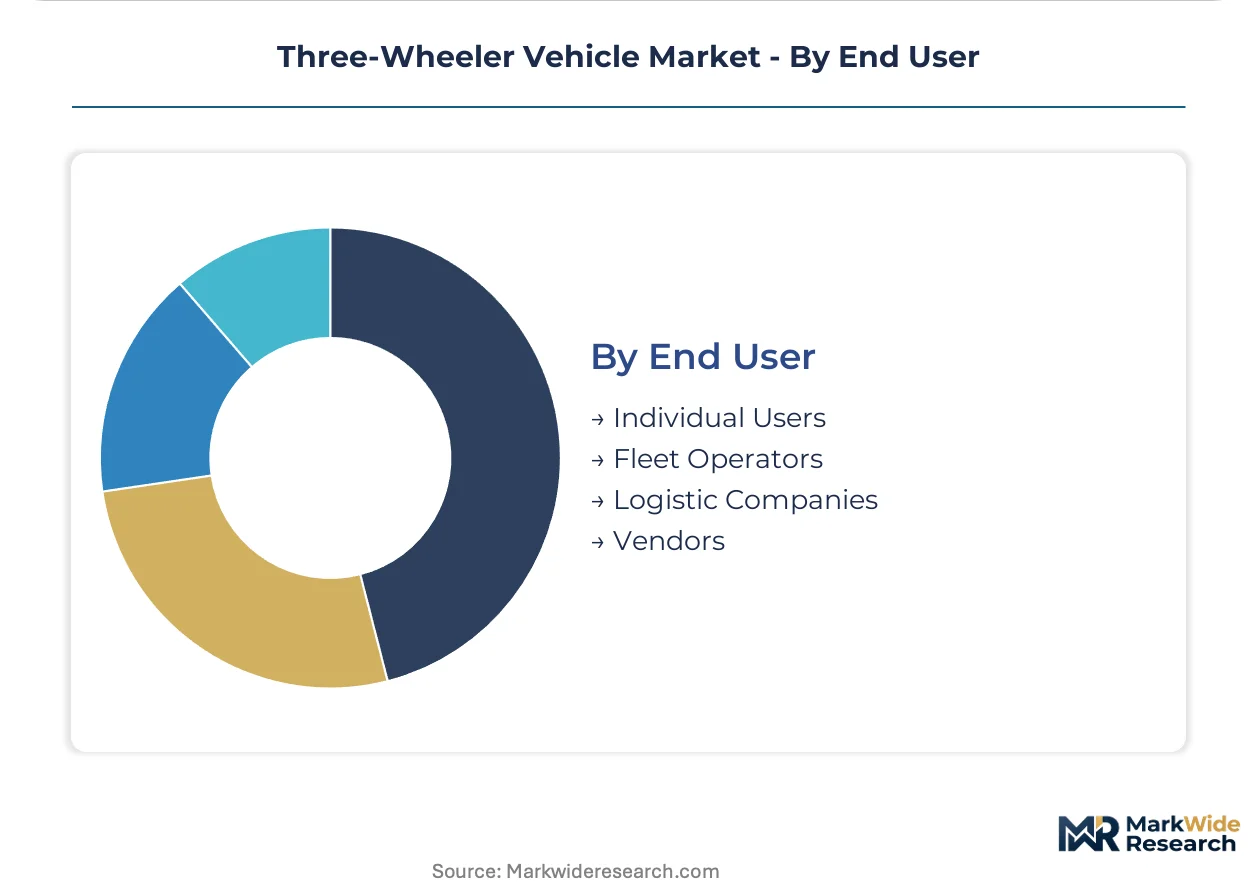
End User:
Volume concentration varies sharply by buyer sophistication, with micro-lending expansion extending addressable pools beyond cash-purchase segments.
- Fleet Operators:Centralized procurement by organized logistics platforms displaces individual owner-operator purchasing across South Asian urban markets. Dedicated fleet management subsidiaries specify standardized electric platforms with telematics integration and single maintenance contracts.
- Individual Users:Owner-operators in Bangladesh's unregulated para-transit segments lag electric adoption due to charging infrastructure gaps and limited access to formal credit.
- Logistic Companies:Third-party delivery providers balance platform standardization against route-specific range requirements.
- Vendors:Small-scale merchants utilize three-wheelers for mobile retail and distribution in dense urban cores.
Individual users represent the broadest installed base. Fleet operators drive the fastest technology transition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Bangladesh's unregulated para-transit corridors runs 15-20% above comparable Indian markets due to conversion workshop bottlenecks. Indian manufacturers absorb thinner margins as FAME-II subsidies compress end-user prices and intensify procurement competition among fleet operators.
India
FAME-II subsidies covering 20% of electric three-wheeler costs redirect manufacturer R&D toward lithium-ion platforms. The Ministry of Road Transport and Highways enforces BS-VI emission standards that eliminated two-stroke engine production entirely. Bangalore and Hyderabad host dedicated dark-store delivery corridors where Amazon India and Flipkart operate 200+ vehicle electric fleets under single maintenance contracts.
Bangladesh
Dhaka's unregulated para-transit operators absorb 15-20% vehicle cost premiums for factory-built CNG compliance ahead of enforcement deadlines. The Road Transport Authority imposes fitness-certification requirements that accelerate fleet turnover toward alternative-fuel platforms. Chittagong's conversion workshops face supply shortages of OEM-certified CNG and electric vehicles relative to retrofit demand.
Sri Lanka
Import restrictions on fossil-fuel vehicles create captive demand for electric three-wheelers among urban taxi operators. The country's national transport regulator imposes permit caps that concentrate fleet ownership among established cooperative structures. Colombo's metropolitan corridor records the densest concentration of battery-swapping pilot deployments outside mainland South Asia.
Pakistan
CNG infrastructure legacy from compressed natural gas vehicle programs creates conversion pathway familiarity among commercial operators. Provincial transport authorities maintain fragmented regulatory frameworks that delay unified emissions standards implementation. Karachi's informal goods transport sector utilizes gasoline-powered cargo three-wheelers for last-mile connectivity to container terminals.
Myanmar
Border trade logistics generate demand for low-cost motorized transport connecting Yangon to Thai and Chinese supply corridors. The country's central automotive regulator maintains limited enforcement capacity outside major urban centers. Mandalay's industrial zones absorb second-hand Indian and Chinese three-wheelers through informal cross-border channels.
Three-Wheeler Vehicle Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in battery-pack assembly and motor-controller calibration. Market structure concentrates among four domestic Indian conglomerates with captive finance arms and dense rural distribution networks. Two strategic archetypes dominate: vertically integrated manufacturers controlling powertrain-to-chassis production, and assembly-focused operators sourcing imported lithium cells and drive motors. Competitive moves center on dealer-financing micro-lending convergence and battery-swapping infrastructure partnerships with charging network operators.
Among Indian-based platform integrators, Bajaj Auto, Mahindra & Mahindra, and TVS Motor Company exemplify the vertically integrated archetype with captive finance operations and rural service footprints. Piaggio Group occupies a position representing European premium gasoline specialization. These anchors illustrate how geographic origin and corporate structure map to divergent competitive positioning across subsidy-dependent and margin-focused market segments.
| Leading Market Players |
|---|
| Bajaj Auto |
| Mahindra & Mahindra |
| Piaggio Group |
| Tata Motors |
| TVS Motor Company |
| Atul Auto Limited |
| Terra Motors |
| Ashok Leyland |
| Lohia Auto Industries |
| Others |
Value Chain & Pricing Dynamics
Dhaka's conversion workshop cluster shapes downstream pricing power across South Asian three-wheeler corridors. Factory-built CNG and electric platforms command 15-20% premiums over retrofitted equivalents as Bangladesh's Road Transport Authority fitness-certification deadlines compress compliant vehicle availability. Indian manufacturers absorb thinner margins under FAME-II subsidy compression, while informal para-transit operators in grid-deficient rural hinterlands retain gasoline-dominant procurement patterns.
Pricing Analysis
Configured-to-order pricing spreads 15-20% above standard fleet specifications as Bangladeshi operators absorb factory-build premiums for regulatory compliance. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade, volume scale, and after-sales service bundling. Cost compression in entry-level electric variants is intensifying because lithium-iron-phosphate cell costs are compressing faster than motor-controller integration expenses. Individual owner-operators in unregulated para-transit segments exhibit highest price sensitivity; organized e-commerce fleet managers demonstrate lowest sensitivity due to total-cost-of-ownership optimization.
Supply Chain Analysis
Tariff exposure between India and China dominates supply chain risk calculations for battery-pack assemblers. Lithium cell sourcing concentrates in China, South Korea, and Japan; motor-controller production anchors in China and Taiwan. Battery pack assembly draws from cylindrical and prismatic cells, copper winding substrates, and silicon-carbide power semiconductors. Single-source vulnerability in lithium cell supply exposes margins to raw material volatility and tariff friction. Distribution runs through captive finance arms, micro-lending cooperatives, and dense rural dealership networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Three-wheeler electrification sits in early-cycle expansion as FAME-II subsidies and CNG conversion mandates accelerate powertrain displacement across South Asian urban corridors. Last-mile logistics consolidation and battery-swapping pilot deployments signal penetration inflection ahead of grid infrastructure maturation.
For Market Incumbents: Insulate core revenue streams by deepening backward integration into lithium-iron-phosphate cell sourcing and motor-controller calibration capabilities. Expand captive finance penetration in Bangladesh's unregulated para-transit corridors ahead of enforcement deadline clustering. Defensive positioning requires preemptive certification investment under India's Automotive Research Association of India protocols to compress homologation timelines versus emerging competitors.
For New Entrants and Emerging Players: Build out battery-swapping infrastructure partnerships in Delhi and Bangalore before network-effect consolidation locks incumbent advantage. Kenya and Tanzania's motorcycle-taxi economies represent the most penetrable geography as regulatory pressure mounts on two-stroke boda-boda emissions. Go-to-market execution should anchor on dealer-financing micro-lending convergence at sub-14% interest rates to expand addressable buyer pools beyond cash-purchase segments.
For Investors and Strategic Acquirers: Long-term, this sits as a platform-integrator consolidation play because battery-pack assembly and motor-controller supply chains concentrate margin pools upstream of vehicle assembly. Acquisition targets should screen for captive finance operations and dense rural service footprints. The signal to watch is charging-infrastructure deployment rates relative to fleet operator electric procurement commitments.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Swapping Infrastructure Partnership | Station-based exchange networks eliminate range anxiety for commercial operators in Delhi and Bangalore corridors. |
| Backward Integration into LFP Cell Sourcing | In-house lithium-iron-phosphate procurement compresses nickel-manganese-cobalt dependency and insulates margin exposure. |
| Captive Finance Arm Expansion | Bajaj Auto's rural micro-lending model demonstrates channel control through sub-14% interest rate origination. |
| ARAI Certification Pre-Investment | Early thermal runaway and range validation testing compresses product launch schedules versus gasoline equivalents. |
| East African Geographic Expansion | Kenya and Tanzania's boda-boda conversion potential opens white-space before regulatory enforcement tightens. |
Study Parameters
A spread of perspectives from fleet procurement managers, captive finance executives, battery-pack assembly engineers, and para-transit cooperative operators converged on the working assumptions. Primary interviews combined with secondary validation from Automotive Research Association of India certification records, Bangladesh Road Transport Authority fitness-certification databases, FAME-II subsidy disbursement filings, and customs trade data for lithium cell imports. Bottom-up vehicle production estimates triangulated against top-down logistics fleet procurement surveys.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include vehicle type, powertrain architecture, application duty cycle, and end-user procurement sophistication. CAGRs derived from production volume trajectories, fleet replacement rates, and subsidy-renewal timeline scenarios. Industry-specific forecast inputs incorporated charging-infrastructure deployment curves and battery-swapping network expansion rates.
Stress conditions across grid reliability deficits, lithium cell tariff exposure, and FAME-II subsidy renewal uncertainty were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding powertrain transition pace and regulatory enforcement timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
Electric Sports Car Market
Passenger Vehicles
Large Suvs Market
Passenger Vehicles
Wheelchair Accessible Vehicle Market
Passenger Vehicles
Global Passenger Cars Market
Passenger Vehicles
Global Luxury SUV Market
Passenger Vehicles
Inland Water Passenger Transport Market
Passenger Vehicles
Ghana Automobile Market
Passenger Vehicles
Europe Luxury Car Market
Passenger Vehicles
India Luxury Car Market
Passenger Vehicles
Family Car Market
Passenger Vehicles
Global SUV Market
Passenger Vehicles
Sports Utility Vehicles (Suvs) Market
Passenger Vehicles
Russia Light Vehicle Market
Passenger Vehicles
Compact Cars Market
Passenger Vehicles
Convertible Vehicles Market
Passenger Vehicles
Luxury Vehicles Market