
 Electric Sports Car Market | 2026-2036
Electric Sports Car Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Sports Car Market Analysis
Track day enthusiasts and luxury lifestyle buyers are restructuring the end-use profile of electric sports cars, shifting volume away from traditional commuter EVs toward weekend performance machines. Tesla sustains technology leadership through proprietary drivetrain architecture and over-the-air performance upgrades. Porsche anchors its position with the Taycan platform and motorsport-derived thermal management. Rimac specializes in hypercar-grade battery systems and supplies powertrain components to legacy OEMs seeking electrification credibility.
An electric sports car is a battery-powered passenger vehicle engineered for high-speed stability, sub-four-second acceleration, and sustained track performance, typically featuring dual or triple motor layouts, carbon-fiber monocoque construction, and active aerodynamic elements. Its commercial purpose centers on delivering zero-emission driving exhilaration to affluent consumers while serving as a technology halo for broader brand electrification. Coupe configurations dominate current production volumes due to structural rigidity advantages and aerodynamic efficiency. Solid-state battery technology represents the fastest-growing segment as manufacturers chase energy density above 400 Wh/kg and reduced thermal runaway risk. The luxury market segment captures the deepest margin pools, with entry-level electric sports cars struggling to justify premium pricing against competent internal-combustion alternatives.
EPA tailpipe regulations and California Air Resources Board zero-emission mandates are compressing the development timeline for combustion-dependent performance brands. NHTSA crashworthiness standards for high-voltage battery enclosures add engineering cost but create compliance barriers against low-volume entrants. EU Green Deal vehicle CO2 targets and Euro 7 emission rules are accelerating European OEM electrification commitments. Stakeholders must monitor solid-state battery manufacturing yields and charging infrastructure buildout rates as the twin determinants of mass-market viability.
Market Dynamics
Solid-state battery chemistry is compressing development cycles for electric sports car platforms, forcing legacy performance brands to accelerate electrification roadmaps or surrender technology leadership to battery-native entrants.
Growth Catalysts
- EU Green Deal vehicle CO2 targets:European OEMs face binding fleet-average emissions mandates that eliminate combustion-only compliance pathways, redirecting R&D budgets toward high-margin electric performance architectures.
- Track day enthusiast demand:Weekend motorsport participants are migrating from gasoline-powered garage queens to battery-electric alternatives with instant torque delivery and reduced maintenance burdens.
- Silicon carbide power electronics:Wide-bandgap semiconductor integration is shrinking inverter packaging and cutting switching losses, enabling sustained high-output operation without thermal derating.
Market Restraints
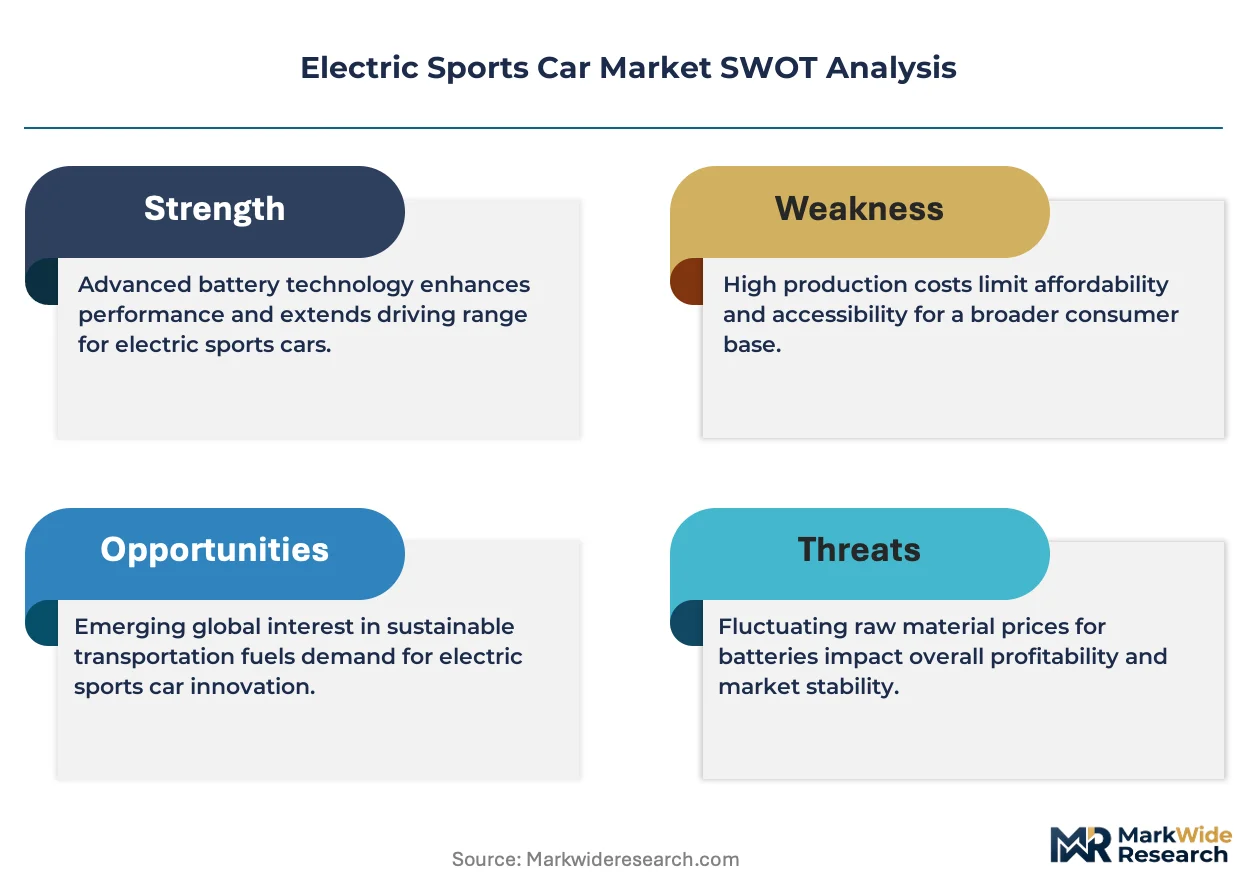
- Lithium supply concentration:Spodumene and brine extraction dominates in Australia, Chile, and Argentina, creating price volatility exposure and geopolitical supply risk for battery pack producers.
- NHTSA high-voltage enclosure standards:Crashworthiness certification for battery protection systems adds engineering validation cycles and tooling costs that disproportionately burden low-volume manufacturers.
- Internal combustion heritage substitution:Enthusiast collectors retain strong preference for acoustic character and mechanical engagement, slowing defection rates among traditional sports car loyalists.
Strategic Opportunities
- India PLI scheme for advanced chemistry cells:Domestic battery manufacturing incentives are attracting component suppliers to establish localized assembly for emerging luxury vehicle demand in Mumbai and Delhi.
- Vehicle-to-grid integration:Bidirectional charging capability transforms parked sports cars into grid-stabilization assets, unlocking new revenue streams for owners in markets with time-of-use electricity pricing.
- Solid-state electrolyte manufacturing:Dry electrode coating and ceramic separator production techniques promise 40% energy density gains, enabling range parity with combustion equivalents in coupe form factors.
Industry Challenges
- High-voltage systems engineering talent:Scarce expertise in 800V+ architecture design and thermal runaway mitigation is constraining platform development velocity at smaller manufacturers.
- Homologation timeline compression:Simultaneous pursuit of EPA certification, Euro NCAP ratings, and China MIIT type approval is stretching validation resources across incompatible test protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Sports Car Market |
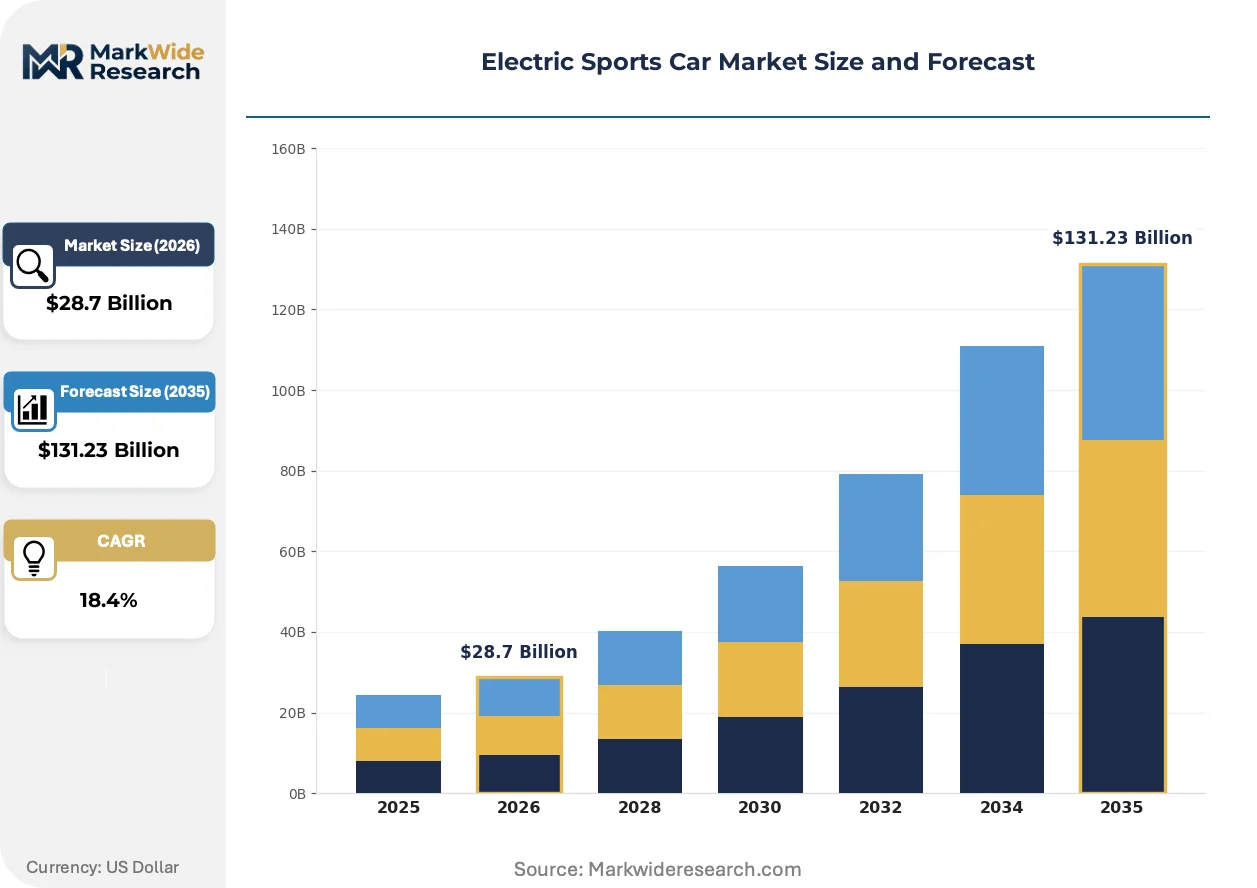
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $131.23 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Coupe, Convertible, Roadster, Hatchback Battery Technology: Lithium-Ion, Solid-State, Fast Charge, Swappable Market Segment: Luxury, Performance, Entry-Level, Niche Distribution Channel: Direct Sales, Online, Dealerships, Showrooms |
| Companies Covered | Lucid, Kia, Tesla, Lotus, Audi, Porsche, Hyundai, Polestar, Rimac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Sports Car Market Emerging Trajectories
Powertrain electrification is rewriting the engineering specifications that define sports car legitimacy, replacing displacement and exhaust tuning with thermal management sophistication and software-defined performance envelopes.
Silicon-anode lithium-ion cells are absorbing incremental energy density gains from traditional graphite substrates while preserving manufacturing compatibility with existing electrode coating lines. Track-focused buyers in Germany and California are specifying these packs for extended lapping sessions without power fade. The technology is absorbing market share from nickel-cobalt-manganese alternatives in applications where gravimetric density outweighs absolute cost minimization.
California Air Resources Board zero-emission mandates are eliminating combustion engine grandfathering provisions for 2035 model-year vehicles, forcing Ferrari, Lamborghini, and McLaren to abandon hybrid bridge strategies. The regulatory pressure is accelerating dedicated EV platform investments that were previously scheduled for 2040 horizons. European Union Euro 7 emission rules are producing parallel compliance burdens for remaining combustion sports car production, compressing the economic viability window for ICE heritage models.
Direct-to-consumer configuration tools are displacing traditional dealership inventory models for limited-production electric hypercars. Rimac, Lucid, and Tesla operate reservation-based allocation systems that capture buyer commitment 18-24 months ahead of delivery, eliminating carrying costs and enabling build-to-order manufacturing. This channel transformation is most advanced in Norway and the Netherlands, where digital-native buyer demographics and streamlined registration processes support frictionless remote transactions.
Electric Sports Car Market Segmentation
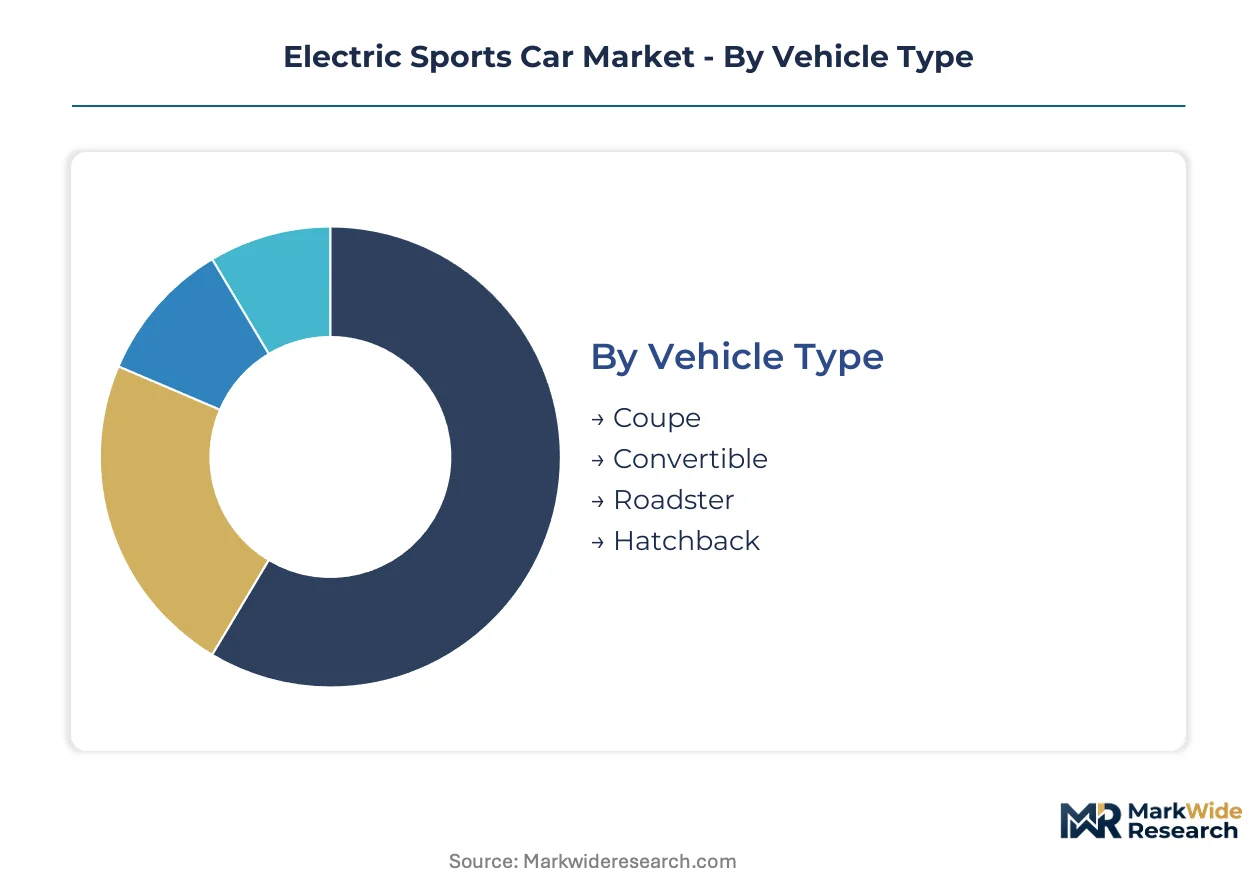
Electric sports car manufacturers calibrate platform architectures and pricing architectures around distinct buyer psychographics and use-case intensity. Segment boundaries determine battery pack sizing, thermal management investment, and channel economics across the value chain.
Vehicle Type:
Volume production concentrates in fixed-roof configurations where structural rigidity supports sustained high-speed operation. Premium positioning gravitates toward open-top variants that sacrifice aerodynamic efficiency for sensory engagement.
- Coupe:Fixed-roof two-door architecture with carbon-fiber monocoque construction dominates current assembly lines. Germany and California buyers specify these for track-day durability and torsional stiffness during high-G cornering. The segment absorbs the majority of silicon-carbide inverter deployment.
- Convertible:Retractable hardtop or soft-top mechanisms add mass and compromise battery packaging flexibility. Demand clusters in Mediterranean coastal markets where climate supports open-air touring. Porsche and Ferrari allocate convertible variants to halo positioning rather than volume.
- Roadster:Strict two-seat open-cockpit layouts prioritize minimal mass over practicality. Production volumes remain constrained by crash structure complexity and weather sealing requirements.
- Hatchback:Rear cargo access compromises aerodynamic profiles but improves daily usability. European urban buyers in London and Amsterdam favor these for parking efficiency and load flexibility.
Mature deployment sits with Coupe. Newer deployment is concentrated in Hatchback.
Battery Technology:
Energy density thresholds determine range credibility against combustion benchmarks. Cost per kilowatt-hour and charging velocity now outweigh cycle-life longevity as primary purchase criteria.
- Lithium-Ion:Nickel-cobalt-manganese cathode chemistries deliver proven manufacturing scale and thermal stability. Current production lines in Nevada and Hungary optimize these packs for 800V architectures. The technology retains cost advantages for entry-performance positioning.
- Solid-State:Ceramic electrolyte separators promise 400+ Wh/kg density and reduced fire risk. Toyota and QuantumScape pilot lines target track-focused applications where energy density outweighs absolute cost. Manufacturing yields remain the gating factor for mass deployment.
- Fast Charge:Cell formulations optimized for 350kW+ input rates sacrifice some cycle life for thermal tolerance. Highway corridor buyers in Germany and California specify these for route flexibility.
- Swappable:Standardized pack geometry enables automated exchange infrastructure. Chinese operators NIO and Geely pilot networks in Shanghai and Shenzhen for fleet applications.
Established volume sits with Lithium-Ion. Steepest expansion trajectory belongs to Solid-State.
Market Segment:
Margin capture stratifies sharply across price tiers, with technology transfer from halo products subsidizing development amortization downstream.
- Luxury:Six-figure price points fund bespoke interior craftsmanship and concierge ownership programs. Buyers in Munich, Beverly Hills, and Shanghai demand individualized configuration and exclusive allocation. This tier generates disproportionate profit contribution per unit.
- Performance:Sub-four-second acceleration targets with track-capable thermal management. Porsche Taycan and Tesla Model S Plaid anchor this tier with motorsport-derived validation. Weekend enthusiast demand in Germany and California drives specification intensity.
- Entry-Level:Price positioning against hot-hatch combustion alternatives struggles to justify battery cost premiums. Younger buyers in urban India and Brazil show interest pending localized production.
- Niche:Ultra-limited production runs below 500 units annually with seven-figure pricing. Rimac and Koenigsegg target collector investors seeking appreciation potential alongside driving experience.
Revenue concentration rests with Luxury. Volume scaling depends on Performance.
Distribution Channel:
Channel economics shift as direct reservation models eliminate inventory carrying costs and enable build-to-order manufacturing.
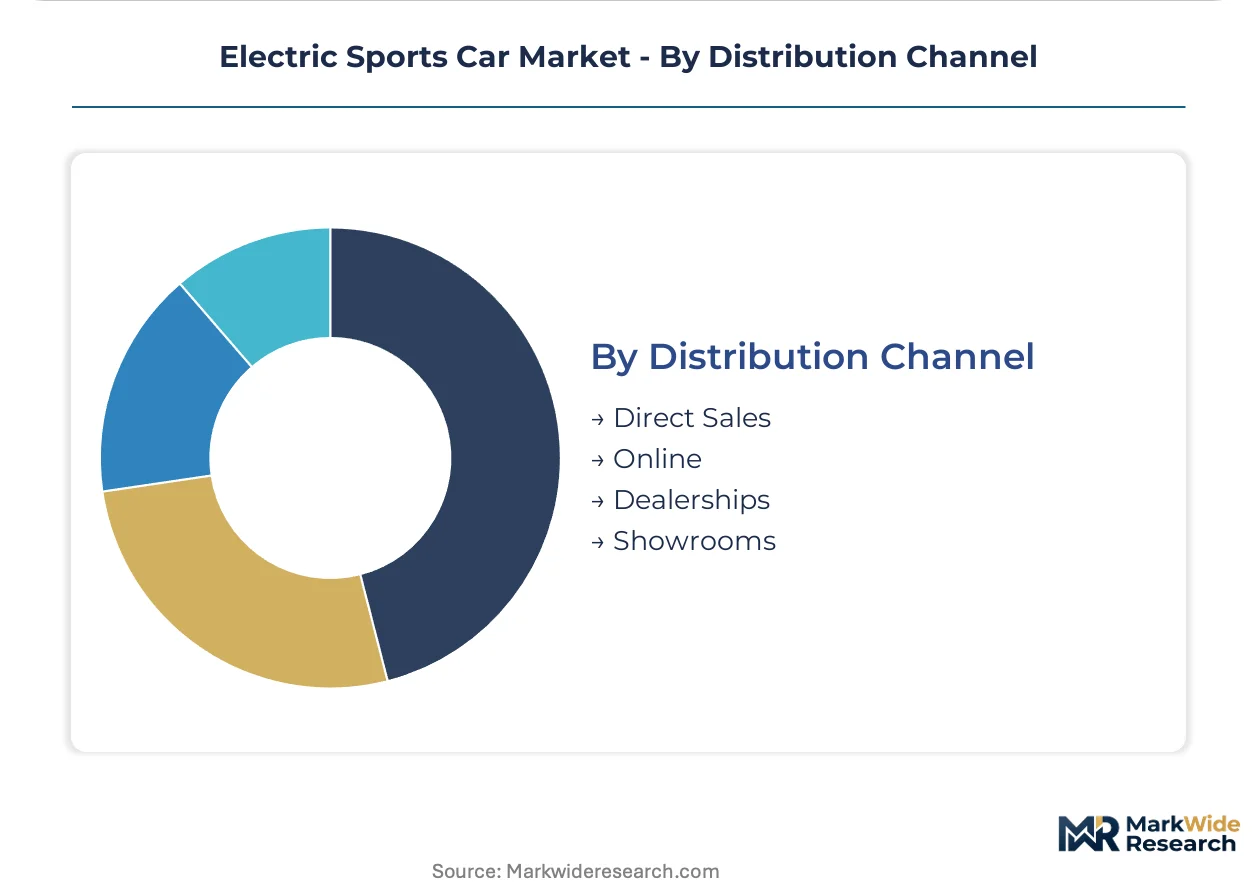
- Direct Sales:Manufacturer-owned stores and online configuration tools capture full margin and buyer data. Tesla and Lucid operate this model exclusively in Norway and the Netherlands. Elimination of dealer markups supports price competitiveness.
- Online:Digital-native reservation systems with 18-24 month delivery horizons reduce working capital requirements. Rimac and Pininfarina deploy this for limited-production hypercars. Frictionless transaction flow appeals to tech-sector buyers.
- Dealerships:Franchise networks retain relevance for test-drive access and service infrastructure in secondary markets. Legacy OEMs maintain these relationships for buyer segments requiring physical interaction.
- Showrooms:Experience centers in premium retail locations emphasize brand immersion over immediate transaction. Munich, Dubai, and Tokyo host flagship installations withConfigurator technology and lifestyle merchandising.
Legacy infrastructure remains with Dealerships. Capability investment flows toward Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in Shanghai and Shenzhen concentrate battery cell assembly and drivetrain component sourcing for performance EV architectures. These designated areas offer tariff exemptions on imported cathode materials and reduced corporate tax rates for advanced chemistry cell production.
United States
Track day enthusiasts in California and Texas drive specification intensity for sub-three-second acceleration platforms. The EPA tailpipe regulations and California Air Resources Board zero-emission mandates eliminate combustion-only compliance pathways for 2035 model years. Manufacturing clusters in Fremont and Austin host vertically integrated assembly for motorsport-derived thermal management systems.
Germany
Luxury collectors in Munich and Stuttgart demand bespoke configuration and exclusive allocation for six-figure performance vehicles. The EU Green Deal vehicle CO2 targets and Euro 7 emission rules redirect R&D budgets toward high-margin electric architectures. Industrial concentration in Baden-Württemberg centers on silicon-carbide inverter production and 800V charging infrastructure.
China
High-net-worth buyers in Shanghai and Beijing prioritize vehicle-to-grid integration and bidirectional charging capability. The MIIT type approval process and dual carbon goals accelerate domestic OEM electrification commitments. The Yangtze River Delta hosts pilot solid-state electrolyte manufacturing lines targeting 400 Wh/kg energy density thresholds.
United Kingdom
Motorsport heritage brands in Oxfordshire and Northamptonshire pivot from combustion engineering to battery-native platform development. The UK's 2030 ban on new petrol and diesel vehicle sales compresses development timelines for legacy performance marques. Silverstone Technology Cluster anchors powertrain electrification R&D for track-focused applications.
Japan
Silicon-anode cell research in Nagoya and Tokyo targets gravimetric density gains for extended lapping sessions. METI funding programs support solid-state battery pilot lines with ceramic separator production techniques. Toyota's Aichi Prefecture facilities lead dry electrode coating development for next-generation performance packs.
Electric Sports Car Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with heritage marques defending margin pools against battery-native entrants. The vendor base concentrates around three strategic tiers: luxury incumbents with motorsport pedigree, technology-forward disruptors with proprietary drivetrain architectures, and component suppliers licensing powertrain systems to legacy OEMs. Competitive positioning hardens through exclusive battery supply agreements and track-homologation partnerships. M&A activity targets solid-state electrolyte startups and silicon-carbide foundry capacity.
Among technology-forward specialists, Tesla and Rimac exemplify divergent paths to electrification credibility. Tesla anchors the mass-premium tier with over-the-air performance upgrade architectures and vertical integration into cell manufacturing. Rimac occupies the hypercar-component supplier niche, licensing battery systems to heritage brands seeking electrification legitimacy without captive R&D investment. Lotus represents the heritage-transition archetype, repurposing lightweight chassis expertise for battery-native platforms.
| Leading Market Players |
|---|
| Lucid |
| Kia |
| Tesla |
| Lotus |
| Audi |
| Porsche |
| Hyundai |
| Polestar |
| Rimac |
| Others |
Supply Flow & Price Mechanics
Solid-state electrolyte manufacturing transitions are compressing cost curves for next-generation battery packs while concentrating supply leverage among ceramic separator specialists in Japan and South Korea. This dual effect simultaneously erodes legacy lithium-ion pricing power and elevates procurement risk for OEMs without captive chemistry partnerships.
Pricing Analysis
Reservation-based allocation commands substantial premiums for sub-12-month delivery windows against standard 18-24 month lead times. Three-tier pricing structure across luxury, performance, and entry-level tiers separates track-homologated variants from touring configurations. Pricing pressure stems from silicon-carbide inverter cost compression as Chinese foundry capacity expands. Entry-level buyers exhibit acute price sensitivity, while niche collectors tolerate seven-figure thresholds for allocation exclusivity.
Supply Chain Analysis
Spodumene concentrate supply rests on Australian hard-rock mining operations and Chilean-Argentine brine evaporation ponds. Cathode precursor processing draws from Chinese metallurgical refineries, while German silicon-carbide wafer production feeds power electronics assembly. Single-source vulnerability concentrates in ceramic electrolyte sintering equipment. Distribution runs through vertically integrated OEM captive networks and specialist battery pack assemblers in Nevada and Hungary.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NHTSA high-voltage enclosure standards and EPA tailpipe regulations construct formidable compliance moats that favor incumbents with established certification infrastructure and capital reserves.
For Market Incumbents: Hedge technology obsolescence risk by securing exclusive solid-state electrolyte offtake agreements with QuantumScape and Toyota pilot lines. Defend margin pools through backward integration into silicon-carbide foundry partnerships in Germany and Texas, insulating against wide-bandgap semiconductor supply volatility from emerging Asian entrants. For New Entrants and Emerging Players: Silicon-anode cell formulations offer a technology-first wedge into track-day enthusiast segments where gravimetric density outweighs absolute cost minimization. Target white-space in Indian PLI scheme jurisdictions for localized battery assembly serving Mumbai and Delhi luxury demand. Deploy direct-to-consumer reservation systems with 18-24 month horizons to eliminate dealer network capital requirements. For Investors and Strategic Acquirers: Exit pathways concentrate in component supplier acquisitions by legacy OEMs seeking electrification credibility without captive R&D investment. Long-term viability favors targets with validated 800V+ architecture expertise and established MIIT type approval relationships. Watch solid-state manufacturing yield inflections as the signal separating scalable platforms from laboratory curiosities.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures ceramic electrolyte volumes from Toyota Aichi facilities for track-focused platforms. |
| Software-Defined Vehicle Investment | Enables over-the-air performance upgrades that sustain technology differentiation against Rimac. |
| Charging Infrastructure Partnership | Integrates 350kW+ highway corridor access for California and German Autobahn buyers. |
| Geographic Manufacturing Footprint | Establishes localized assembly in Shanghai Free Trade Zones for MIIT compliance acceleration. |
| Platform Standardization | Spreads 800V thermal management R&D across Porsche Taycan-derived volume variants. |
Methodological Framework
Independent corroboration across OEM platform engineers, Tier 1 battery procurement leads, and NHTSA certification specialists underwrites the qualitative findings. Primary fieldwork incorporated aftermarket distributor operations, dealership network managers, and solid-state electrolyte R&D directors. Secondary validation drew from EPA certification databases, MIIT type approval registries, IHS Markit vehicle production data, and EU Green Deal compliance filings. Bottom-up segment sizing triangulated against top-down OEM revenue attribution.
Rate-of-change decomposition across the analysis window isolates volume drivers from pricing dynamics. The modeling framework segments by vehicle type, battery technology, market tier, and distribution channel, with regional production cluster overlays. CAGRs derive from segment-level growth rate blending. Forecast inputs incorporate silicon-carbide inverter deployment trajectories and solid-state manufacturing yield curves without year-specific milestones.
Several conditions sit outside the modeled scope, including unannounced regulatory accelerations, geopolitical lithium export restrictions, and breakthrough solid-state chemistry transitions. Forecasts reflect documented assumptions about charging infrastructure buildout rates and high-voltage systems engineering talent availability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
Passenger Vehicle Market
Passenger Vehicles
Luxury Vehicles Market
Passenger Vehicles
Train Market
Passenger Vehicles
Microcars Market
Passenger Vehicles
Global Passenger Cars Market
Passenger Vehicles
Quadricycle and Tricycle Market
Passenger Vehicles
Luxury Car Market
Passenger Vehicles
North American Lightweight Car Market
Passenger Vehicles
Electric Passenger Car MRO Market
Passenger Vehicles
Compact Cars Market
Passenger Vehicles
Medium Cars Market
Passenger Vehicles
Europe Luxury Car Market
Passenger Vehicles
Solar Passenger Car Market
Passenger Vehicles
Lightweight Cars Market
Passenger Vehicles
India Automotive Market
Passenger Vehicles
Global SUV Market