
 Convertible Vehicles Market | 2026-2036
Convertible Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Convertible Vehicles Market Outlook
Multi-source to dual-source convertible roof supply is rebalancing procurement risk across European and North American assembly plants. BMW Group leverages captive textile and electro-hydraulic actuator production to sustain margin control on hardtop mechanisms. Mercedes-Benz anchors its convertible lineup through in-house development of acoustic folding roof systems. Porsche differentiates via motorsport-derived carbon-fiber reinforced polymer structural reinforcements that compensate for open-body rigidity loss.
A convertible vehicle is a passenger automobile engineered with a retractable roof system—fabric soft-top, multi-panel hardtop, or removable targa panel—that enables open-air cabin operation while maintaining crashworthiness through reinforced A-pillars, side sills, and supplemental roll protection. Primary commercial purpose centers on delivering differentiated driving experience for premium consumer segments where tactile engagement and aesthetic distinction command price premiums above fixed-roof equivalents. Hardtop convertibles occupy the highest margin pool due to complex electro-mechanical latching and sealing architectures, while electric powertrain variants represent the fastest-expanding segment as battery packaging engineers resolve center-of-gravity penalties inherent to roof mechanism mass. Soft-top configurations retain volume leadership in entry-luxury roadster categories where weight minimization preserves handling fidelity.
NHTSA roof crush resistance standards and EPA fleet emissions frameworks shape convertible engineering investments in the United States, while EU type-approval regulations under the European Commission govern pedestrian protection and active rollover protection deployment timing. Japan's Ministry of Land, Infrastructure, Transport and Tourism enforces distinct collision safety criteria that influence JDM-specification body reinforcement strategies. Stakeholders must monitor how divergent crashworthiness testing protocols across these jurisdictions affect platform commonality decisions and localization economics for roof system suppliers.
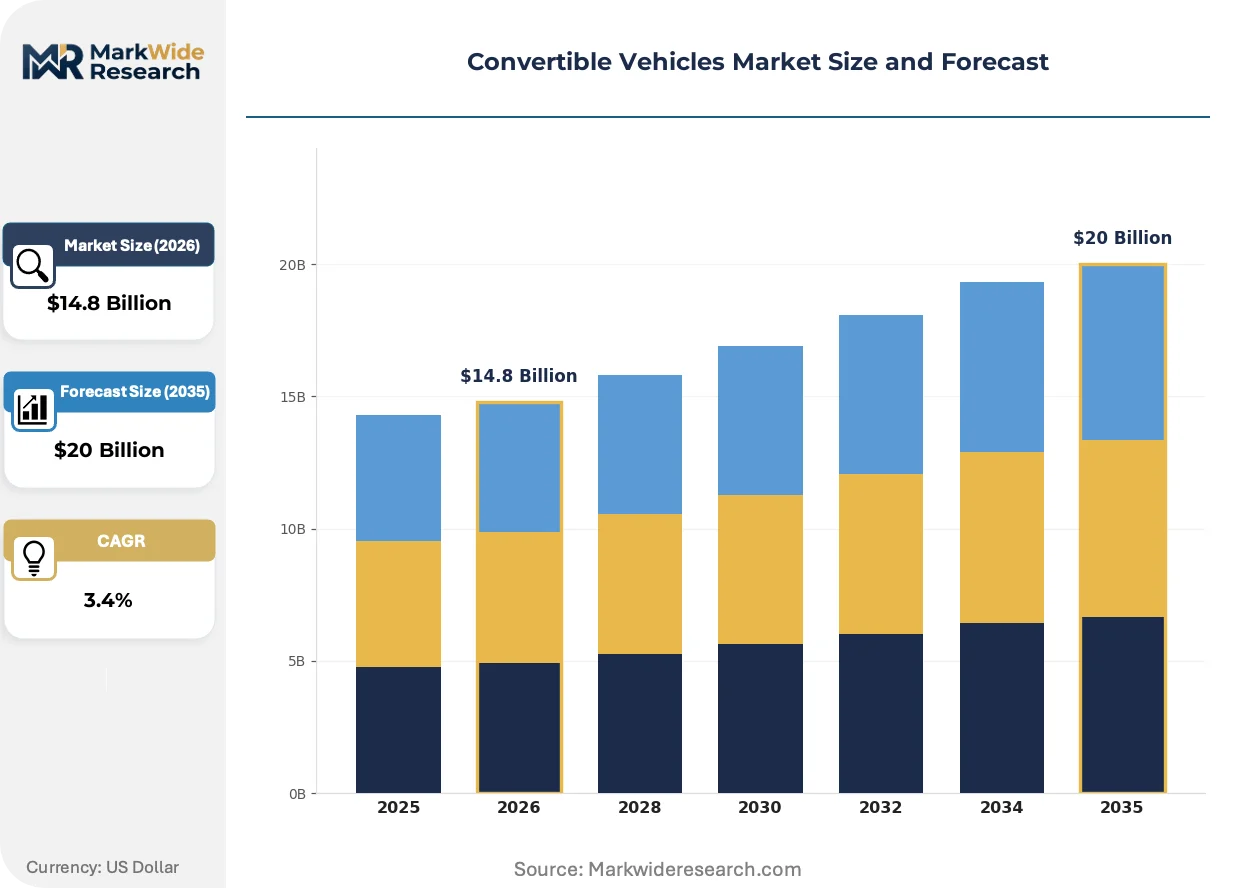
Market Dynamics
Electrification of powertrains is compressing convertible development cycles as battery packaging engineers resolve center-of-gravity penalties from roof mechanism mass, while Europe's F-Gas Regulation forces refrigerant system redesigns in climate-controlled soft-top architectures.
Growth Catalysts
- EU F-Gas Regulation:Low-GWP refrigerant mandates in climate-controlled convertible roofs are accelerating supplier investment in next-generation thermal management systems for premium soft-top configurations.
- Experiential automotive consumption:Luxury car enthusiasts are prioritizing tactile driving engagement over utility, expanding the addressable base for roadster and cabriolet variants across mature automotive markets.
- Carbon-fiber structural reinforcements:Motorsport-derived CFRP A-pillar and side-sill inserts are enabling open-body rigidity without the mass penalty of traditional steel reinforcements.
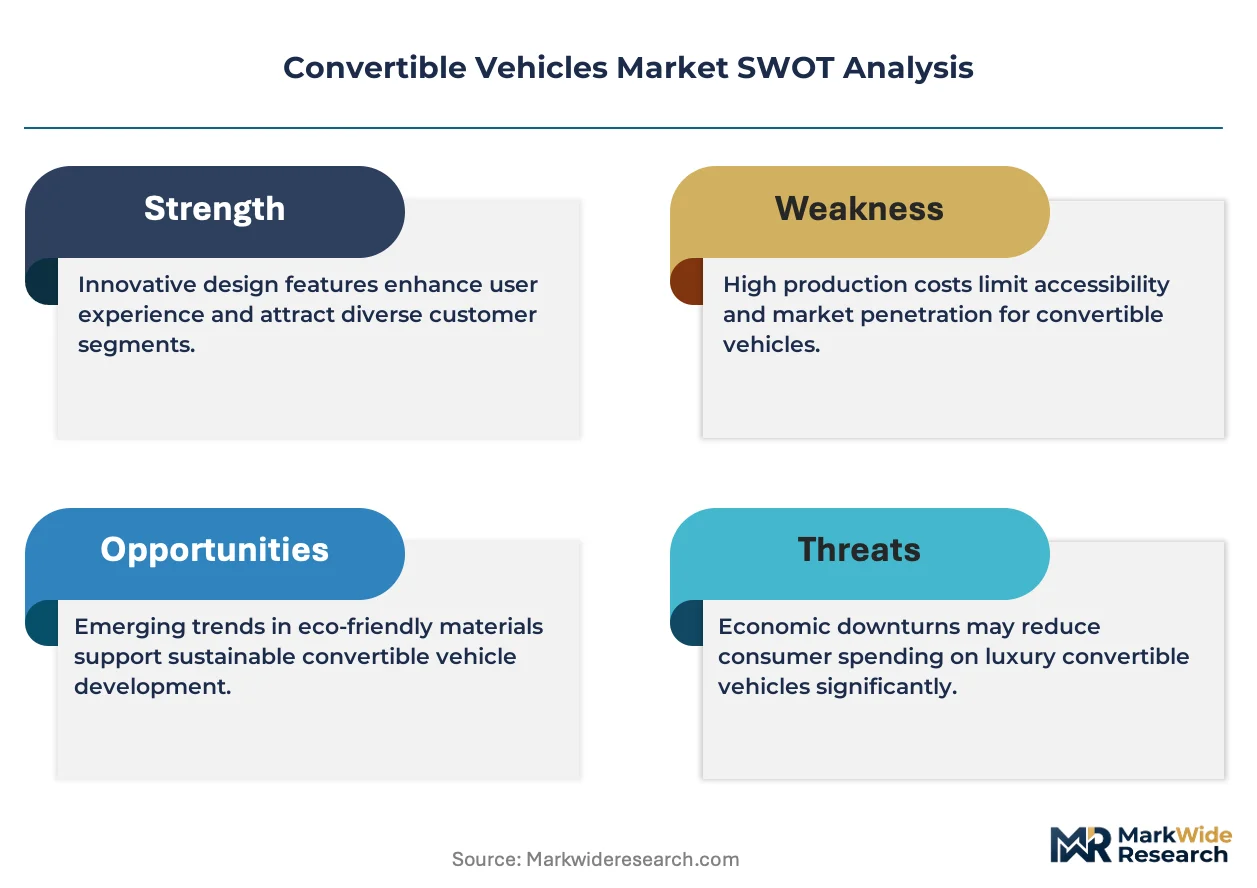
Market Restraints
- Electro-hydraulic actuator supply concentration:Captive production at German premium OEMs limits third-party supplier viability and raises barriers for new convertible program entrants.
- Hardtop mechanism cost structure:Complex multi-panel latching and sealing architectures carry 40-60% higher bill-of-materials than soft-top equivalents, compressing margins at volume price points.
- Crossover SUV substitution:Fixed-roof coupe-SUV body styles with panoramic glass roofs are capturing buyers seeking open-cabin ambience without convertible structural compromise.
Strategic Opportunities
- India's PLI scheme for automotive:Import substitution incentives for advanced manufacturing equipment create localization pathways for electro-hydraulic roof system suppliers serving emerging luxury demand.
- Active rollover protection convergence:Integration of pyrotechnic roll-bar deployment with ADAS collision prediction algorithms enables safety certification for four-seat convertible architectures previously restricted to two-seat roadsters.
- Direct-to-consumer configuration platforms:Online roof material and color personalization tools are capturing reservation deposits before assembly allocation, improving demand visibility for build-to-order convertible programs.
Industry Challenges
- Acoustic engineering talent scarcity:Folding roof wind-noise suppression requires specialized simulation expertise that concentrates at Stuttgart and Munich engineering clusters, constraining supplier scaling.
- Dual-homologation compliance timelines:Divergent NHTSA roof crush and EU pedestrian protection testing protocols force platform-specific reinforcement strategies that fragment economies of scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Convertible Vehicles Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $20 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Hardtop Convertible, Soft-top Convertible, Semi-convertible, Targa Top Powertrain: Gasoline, Diesel, Electric, Hybrid, Hydrogen Fuel Cell Body Style: Roadster, Coupe Convertible, SUV Convertible, Pickup Convertible End User: Luxury Car Enthusiasts, Sports Car Buyers, Rental Services, Auto Dealerships |
| Companies Covered | Ford Motor Company, Chevrolet (General Motors), Mazda Motor Corporation, BMW Group, Mercedes-Benz, Lexus (Toyota Motor Corporation), Ferrari, MINI (BMW Group), Porsche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Convertible Vehicles Market Strategic Shifts
Convertible roof engineering is bifurcating toward lightweight fabric architectures for electric roadsters and complex retractable hardtops for internal-combustion grand tourers, with material science and regulatory pressure as the twin forcing functions.
Multi-layer acoustic soft-top fabrics with integrated thermal and noise insulation layers are overtaking traditional single-layer PVC constructions in premium roadster applications. BMW and Mercedes-Benz procurement specifications now mandate these composites for all four-seat cabriolet programs. The shift is compressing demand for conventional textile suppliers while elevating specialized laminate converters with aerospace composite experience.
Europe's F-Gas Regulation is prohibiting hydrofluorocarbon refrigerants with GWP above 150 in new vehicle climate systems from 2025. Convertible soft-top HVAC architectures, which face higher thermal loads than fixed-roof equivalents, must adopt CO2 or HFO-1234yf alternatives with redesigned compressor displacement and heat exchanger surface area. German KBA type-approval timelines have extended 4-6 months for climate-intensive convertible variants as manufacturers validate low-GWP system durability.
Configuration-driven purchasing is displacing traditional dealer inventory stocking for convertible vehicles. Buyers in Germany and the United States are reserving build slots through OEM digital platforms with non-refundable deposits, selecting roof colors, interior materials, and performance packages before assembly allocation. This pattern is most pronounced in Porsche and Mercedes-AMG roadster segments, where average order-to-delivery intervals now exceed 90 days and pre-configuration rates top 70% of transactions.
Convertible Vehicles Market Segmentation
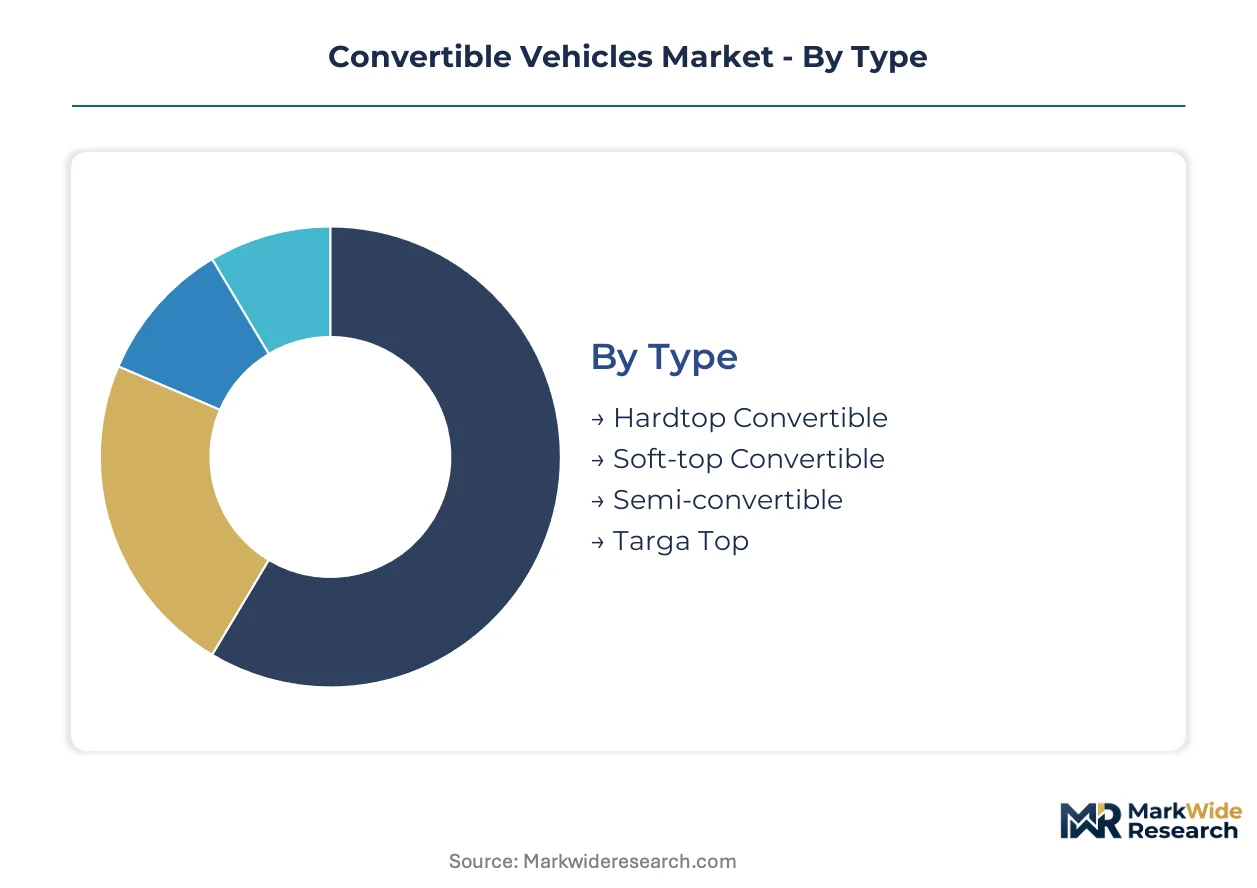
Convertible vehicle procurement decisions hinge on the tension between experiential customization and manufacturing standardization. Roof mechanism complexity, powertrain packaging constraints, and end-user usage patterns fragment the addressable market into sharply differentiated configuration tiers with divergent margin profiles.
Type:
Roof architecture spans a customization-vs-standardization spectrum from hand-finished soft-tops to robot-assembled hardtop modules.
- Hardtop Convertible:Multi-panel electro-mechanical latching systems with acoustic sealing layers deliver cabin refinement matching fixed-roof coupes. German premium OEMs concentrate procurement specifications here, driven by buyer willingness to absorb 40-60% bill-of-materials premiums for weather security and theft resistance.
- Soft-top Convertible:Fabric multi-layer laminates with integrated thermal barriers minimize mass and preserve electric range. Demand clusters in Stuttgart and Munich engineering corridors where acoustic simulation expertise enables wind-noise suppression without hardtop mechanism penalty.
- Semi-convertible:Fixed side rails with retractable center panel balance structural rigidity and open-air access.
- Targa Top:Removable roof panel with fixed roll hoop delivers motorsport-derived aesthetics for niche performance segments.
Leading the category by volume: Soft-top Convertible. Expanding most quickly: Hardtop Convertible.
Powertrain:
Propulsion system selection tracks cost tier progression from established internal combustion to emerging electrified architectures with distinct battery packaging challenges.
- Gasoline:Turbocharged four-cylinder and six-cylinder configurations dominate established roadster segments with proven power-to-weight ratios and minimal thermal management complexity.
- Diesel:Torque-rich compression-ignition variants serve European grand touring applications where highway efficiency outweighs NVH penalties.
- Electric:Battery-electric powertrains with floor-mounted cell packs are resolving center-of-gravity penalties from roof mechanism mass through structural battery enclosures that reinforce open-body torsion resistance. This segment gains share fastest as thermal management engineers adapt low-GWP refrigerant systems to convertible HVAC loads.
- Hybrid:Plug-in architectures with electric-only urban range appeal to regulatory-conscious buyers in emissions-restricted city centers.
- Hydrogen Fuel Cell:Fuel-cell electric variants with roof-integrated hydrogen storage remain experimental, constrained by tank packaging and refueling infrastructure gaps.
Dominant by transaction volume: Gasoline. Steepest expansion trajectory: Electric.
Body Style:
Platform architecture distributes across application types from pure driver-focused roadsters to utility-ambiguous SUV derivatives.
- Roadster:Two-seat, front-engine or mid-engine layouts with minimal weather protection prioritize handling fidelity and power-to-weight ratio. This configuration anchors convertible volume in Germany and the United States where tactile driving engagement commands sustained demand.
- Coupe Convertible:Four-seat cabriolet architectures with 2+2 seating balance open-air aesthetics with occasional rear passenger utility, requiring complex active rollover protection systems for regulatory compliance.
- SUV Convertible:High-riding soft-top derivatives with reinforced B-pillars target lifestyle buyers seeking open-cabin ambience without roadster practicality constraints.
- Pickup Convertible:Open-bed configurations with retractable roof panels serve niche commercial and recreational segments with cargo-carrying requirements.
Highest volume concentration: Roadster. Fastest-growing configuration: Coupe Convertible.
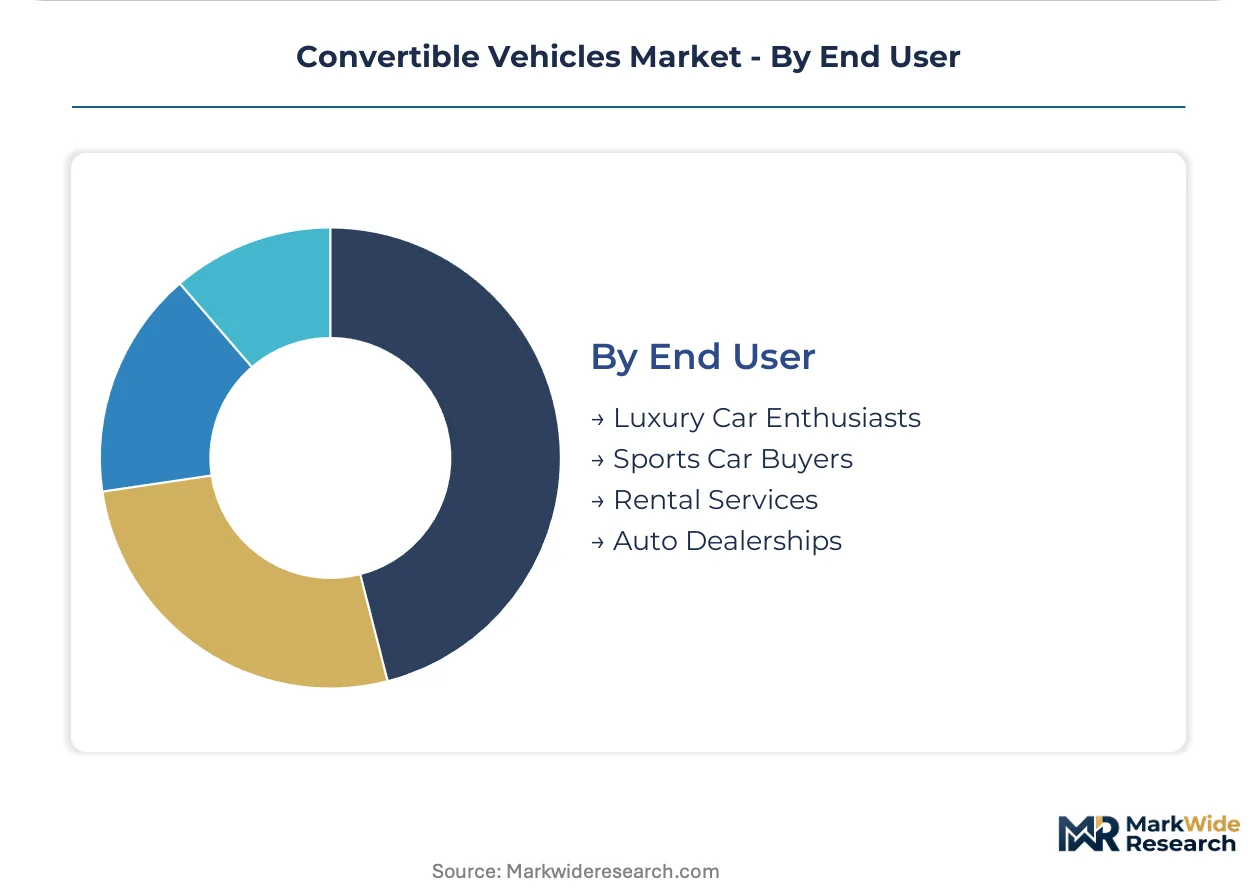
End User:
Customer type stratifies across ownership models from individual experiential consumption to fleet-based rental utilization with divergent depreciation tolerance.
- Luxury Car Enthusiasts:Affluent individual buyers prioritizing tactile engagement, aesthetic distinction, and configuration personalization through direct-to-consumer reservation platforms. This segment drives pre-configuration rates exceeding 70% of transactions in premium German roadster programs.
- Sports Car Buyers:Performance-oriented purchasers valuing track capability and motorsport-derived engineering, accepting structural compromise for weight minimization and chassis communication.
- Rental Services:Fleet operators in coastal tourism markets seeking high-depreciation, high-visibility vehicles for vacation destination deployment.
- Auto Dealerships:Franchise and independent retailers carrying limited inventory for immediate delivery to buyers unwilling to accept build-to-order intervals exceeding 90 days.
Primary volume driver: Luxury Car Enthusiasts. Gaining share fastest: Rental Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German aluminum and steel feedstock corridors anchor convertible vehicle manufacturing, with Stuttgart and Munich engineering clusters supplying precision electro-hydraulic roof mechanisms to assembly plants across three continents.
United States
Coastal tourism markets in California and Florida sustain rental fleet demand for open-air vehicles. NHTSA roof crush resistance standards mandate reinforced A-pillar engineering for all domestic-market cabriolets. Detroit's engineering centers concentrate powertrain packaging expertise for V8 roadster architectures.
Germany
Affluent individual buyers in Bavaria and Baden-Württemberg drive 70% pre-configuration rates through direct-to-consumer reservation platforms. KBA type-approval timelines extended 4-6 months under F-Gas Regulation low-GWP refrigerant mandates. Stuttgart hosts captive textile and electro-hydraulic actuator production for premium hardtop programs.
China
Shanghai and Beijing luxury consumers are adopting electric roadsters as battery packaging engineers resolve center-of-gravity penalties. MIIT new energy vehicle certification requirements shape thermal management system designs for climate-controlled soft-tops. Yangtze River Delta suppliers specialize in multi-layer acoustic fabric laminates.
Japan
MLIT collision safety criteria influence JDM-specification body reinforcement strategies distinct from export variants. Tokyo and Osaka metropolitan areas concentrate demand for compact roadster configurations prioritizing urban maneuverability. Nagoya engineering clusters develop active rollover protection systems for four-seat convertible architectures.
United Kingdom
London and Southeast England luxury buyers favor bespoke configuration platforms with extended order-to-delivery intervals. DVSA type-approval alignment with EU pedestrian protection protocols maintains regulatory continuity post-Brexit. Midlands manufacturing corridors supply specialized hinge and latching components to German OEM assembly networks.
Convertible Vehicles Market Competitive Environment
Global majors compete with regional champions across roof mechanism technology tiers, with German premium OEMs maintaining captive production advantages while third-party suppliers face elevated barriers to entry. The vendor base clusters around electro-hydraulic actuator and acoustic textile specializations, creating distinct capability moats. Three archetypes dominate: vertically integrated German luxury manufacturers, Japanese precision engineering houses, and American volume-scale producers. Competitive moves concentrate on backward integration into textile supply and strategic partnerships for low-GWP HVAC system development.
Among German-based manufacturers, BMW Group, Mercedes-Benz, and Porsche exemplify the captive-production archetype, each anchoring distinct positioning within premium convertible engineering. BMW Group represents integrated textile and actuator manufacturing control. Mercedes-Benz occupies a position centered on in-house acoustic folding roof development. Porsche sits within the motorsport-derived structural reinforcement tier, leveraging carbon-fiber expertise to compensate for open-body rigidity compromises.
| Leading Market Players |
|---|
| Ford Motor Company |
| Chevrolet (General Motors) |
| Mazda Motor Corporation |
| BMW Group |
| Mercedes-Benz |
| Lexus (Toyota Motor Corporation) |
| Ferrari |
| MINI (BMW Group) |
| Porsche |
| Others |
Value Chain & Pricing Dynamics
Low-GWP refrigerant system redesigns under Europe's F-Gas Regulation are compressing cost structures for climate-controlled soft-top architectures while concentrating procurement leverage among German OEMs with captive electro-hydraulic actuator production.
Pricing Analysis
Warranty bundling separates premium convertible programs from volume offerings, with German manufacturers including extended acoustic textile coverage and roof mechanism service plans in hardtop transactions. Three-tier pricing structure across premium, standard, and economy levels tracks roof complexity, with hardtop mechanisms commanding substantial bill-of-materials premiums over soft-top equivalents. Price differentiation hinges on certification tier for rollover protection systems and the extent of after-sales service inclusion. Cost compression in entry-luxury soft-tops is intensifying because textile suppliers face laminate conversion investments without scale offset. Fleet rental buyers exhibit highest price sensitivity, while individual enthusiasts accepting 90-day order-to-delivery intervals show lowest.
Supply Chain Analysis
Electro-hydraulic actuator supply rests on German captive production clusters in Stuttgart and Munich, with secondary sourcing from Japanese precision engineering houses. Aluminum structural feedstock draws from German and Austrian rolling mills, while multi-layer acoustic textiles source from Yangtze River Delta laminate converters. Carbon-fiber reinforced polymer inserts for structural reinforcement hinge on motorsport supplier networks in Japan and Italy. Single-source vulnerability concentrates in specialized hinge and latching component production. Distribution runs through OEM captive assembly plants with direct-to-consumer configuration platforms displacing traditional dealer inventory stocking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Convertible vehicle engineering sits at a powertrain transition inflection, with battery-electric architectures displacing internal-combustion roadster platforms as thermal management engineers resolve HVAC packaging constraints.
For Market Incumbents: To counter crossover SUV substitution threatening open-body volume, BMW Group and Mercedes-Benz should deepen captive textile supply control while accelerating low-GWP refrigerant system certification timelines. Active rollover protection integration with ADAS collision prediction represents the priority R&D lever for expanding four-seat cabriolet architectures beyond traditional two-seat roadster restrictions. For New Entrants and Emerging Players: Rental fleet operators in coastal tourism markets represent the most penetrable buyer archetype, with depreciation-tolerant procurement patterns and standardized specification requirements that bypass configuration complexity barriers. India's PLI scheme for automotive manufacturing equipment creates localization pathways for electro-hydraulic roof system suppliers serving emerging luxury demand. Direct-to-consumer reservation platform partnerships offer the most viable go-to-market angle for bypassing established OEM dealer networks. For Investors and Strategic Acquirers: Re-rating potential sits with specialized acoustic textile converters given laminate expertise scarcity and BMW-Mercedes procurement specification convergence. Long-term viability over the next decade favors suppliers with aerospace composite experience transitioning into automotive multi-layer fabric production. Regulatory certification completion timelines for F-Gas-compliant HVAC systems serve as the critical signal to watch for demand inflection in climate-controlled soft-top segments.| Strategic Initiative | Industry Significance |
|---|---|
| Low-GWP HVAC System Certification | KBA type-approval acceleration unlocks European market access for climate-intensive convertible variants. |
| Captive Textile Production Expansion | Backward integration into multi-layer acoustic fabric laminates secures margin control against specialized converter scarcity. |
| Active Rollover Protection Convergence | Pyrotechnic roll-bar integration with ADAS algorithms enables four-seat cabriolet regulatory compliance expansion. |
| Direct-to-Consumer Configuration Platform | Pre-assembly reservation deposits improve demand visibility and reduce finished goods inventory carrying costs. |
| India PLI Scheme Localization | Import substitution incentives for advanced manufacturing equipment create electro-hydraulic actuator supply diversification. |
Study Parameters
Document review covered vehicle production databases, IHS Markit registration data, KBA type-approval filings, and EU regulatory impact assessments, complemented by interviews with OEM platform engineers, Tier 1 supplier procurement leads, acoustic textile technical directors, and rental fleet operations managers. Bottom-up triangulation across powertrain segmentation and roof architecture categories was validated against top-down macroeconomic demand indicators and regional luxury consumer spending patterns.
Unit shipment and value projections across the analysis window were derived from modeling roof mechanism adoption rates by propulsion type, content-per-vehicle trajectories for structural reinforcement materials, and regional regulatory compliance timelines. CAGR derivation incorporated battery packaging engineering resolution curves, F-Gas Regulation implementation phase-ins, and configuration-driven purchasing pattern shifts. Primary inputs included OEM capital expenditure disclosures for captive production facilities and supplier contract visibility into electro-hydraulic actuator allocation.
Revisions become necessary when battery thermal management breakthroughs accelerate electric roadster center-of-gravity resolution, or when NHTSA roof crush standard harmonization with EU protocols alters platform commonality economics. A small set of triggers—low-GWP refrigerant system durability validation, active rollover protection algorithm certification, and India PLI scheme equipment localization thresholds—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
Global SUV Market
Passenger Vehicles
North America Automotive Market
Passenger Vehicles
China Luxury Car Market
Passenger Vehicles
Microcars Market
Passenger Vehicles
Latin America Passenger Car Market
Passenger Vehicles
North America MUV Rental Market
Passenger Vehicles
Small Suvs Market
Passenger Vehicles
India Automotive Market
Passenger Vehicles
Asia Pacific Luxury Cars Market
Passenger Vehicles
Train Seat Market
Passenger Vehicles
Russia Light Vehicle Market
Passenger Vehicles
North American Lightweight Car Market
Passenger Vehicles
Sports Utility Vehicles (Suvs) Market
Passenger Vehicles
Automotive Luxury Vehicle Market
Passenger Vehicles
Lightweight Cars Market
Passenger Vehicles
Quadricycle and Tricycle Market