
 Global Luxury SUV Market | 2026-2036
Global Luxury SUV Market Size, Share, and Industry Trends Forecast 2026-2036
Global Luxury SUV Market Outlook
Corporate fleet procurement is recalibrating toward electrified full-size SUVs as executive mobility programs prioritize sustainability metrics alongside prestige. BMW Group leverages its iX platform to anchor premium electric positioning across European and Asian markets. Mercedes-Benz Group AG sustains dominance in the V8-powered full-size segment through its S-Class SUV derivatives while navigating tighter emissions protocols.
A luxury SUV denotes a high-ground-clearance passenger vehicle engineered with premium materials, advanced all-wheel-drive architecture, and output thresholds typically exceeding 300 horsepower, designed to deliver superior occupant comfort and status signaling for private and executive transport. The midsize SUV category leads absolute volume as it balances cabin utility with urban maneuverability, while the electric fuel type segment captures the fastest expansion as battery architecture and charging infrastructure mature. Compact SUVs concentrate margin pools through higher production volumes and broader demographic accessibility across Asian metropolitan markets.
The EPA enforces Corporate Average Fuel Economy standards that compel powertrain diversification, while China's MIIT imposes NEV credit mandates requiring escalating zero-emission production ratios. The EU Green Deal's phased combustion restrictions through 2035 will force portfolio restructuring across all manufacturers serving European markets. Stakeholders must monitor regulatory divergence between jurisdictions to calibrate powertrain investment timelines and avoid stranded asset exposure in non-compliant architectures.
Market Dynamics
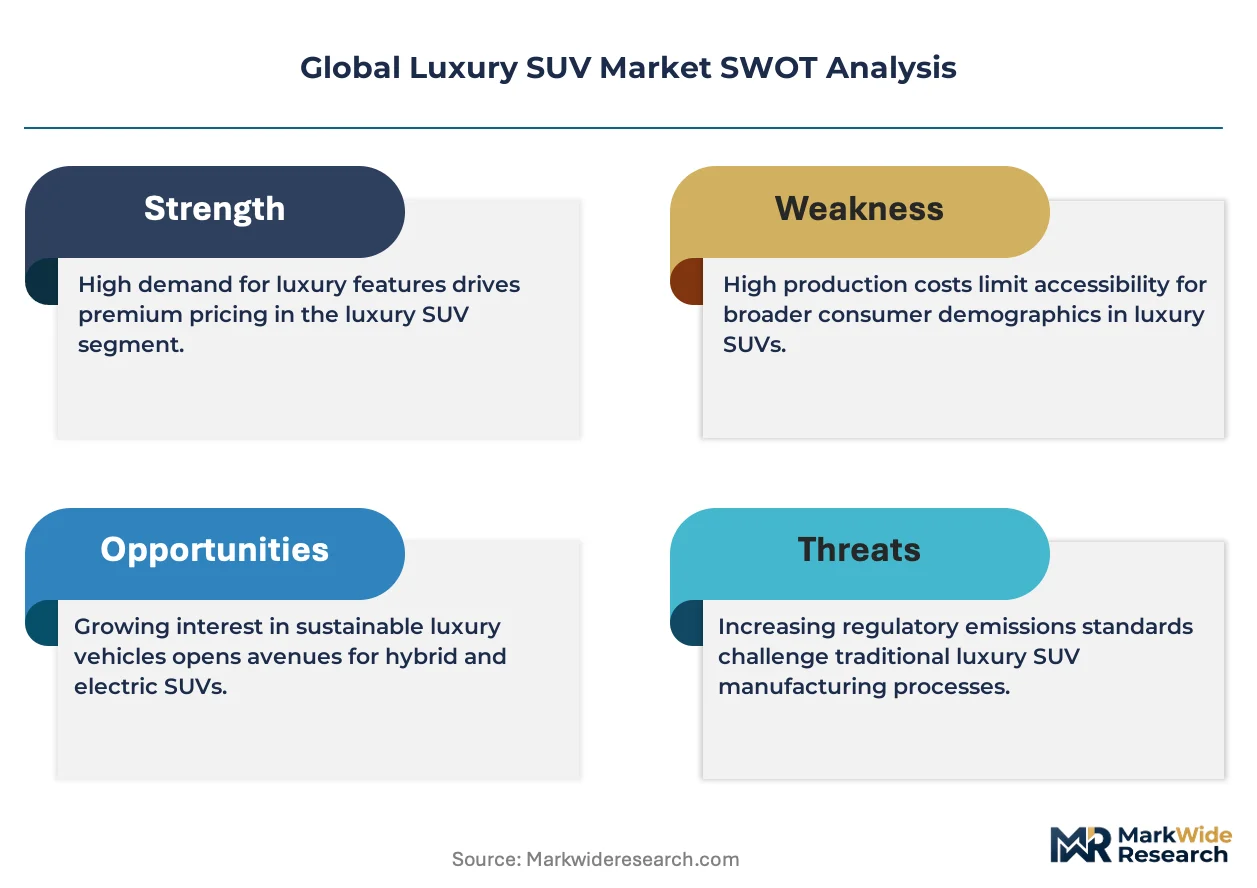
Electrification mandates across China, the United States, and Germany are forcing simultaneous powertrain portfolio restructuring while legacy combustion architectures retain residual demand in executive fleet segments.
Growth Catalysts
- EU Green Deal Phase-Out:The 2035 combustion engine prohibition accelerates manufacturer investment into dedicated electric SUV platforms and battery supply chain localization across European production hubs.
- China NEV Credit Mandates:MIIT's escalating zero-emission production ratios compel luxury marques to prioritize electric variants for the world's largest premium vehicle market.
- Lithium-Ion Pack Cost Curves:Cell chemistry advances and gigafactory scale economics compress battery costs, narrowing the upfront price gap between electric and combustion powertrains.
Market Restraints
- Cobalt Supply Concentration:DRC-dominant raw material sourcing exposes battery supply chains to geopolitical disruption and ESG compliance costs.
- Charging Infrastructure Asymmetry:Uneven fast-charging network density across secondary Chinese cities and US heartland states constrains electric SUV adoption velocity.
- EPA CAFE Stringency:Corporate Average Fuel Economy standards impose fleet-wide penalties that compress margin flexibility for V8-powered full-size derivatives.
Strategic Opportunities
- India Premium Electrification:PLI scheme incentives for domestic battery manufacturing create entry pathways for luxury electric SUVs in an underpenetrated market.
- Solid-State Battery Convergence:Solid-state electrolyte technology paired with silicon-anode architectures promises energy density breakthroughs for extended-range electric flagships.
- Subscription Mobility Channels:Flexible-term vehicle access models displace traditional ownership in urban European and Chinese metropolitan clusters.
Industry Challenges
- Powertrain Engineering Talent Scarcity:Competition for battery thermal management and electric drivetrain calibration expertise strains recruitment pipelines.
- Homologation Timeline Compression:Divergent certification requirements between EPA, MIIT, and KBA approval processes extend model launch cycles.
- Legacy Platform Integration:Hybrid electric architectures must accommodate existing supplier contracts and manufacturing footprints during transition phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Luxury SUV Market |
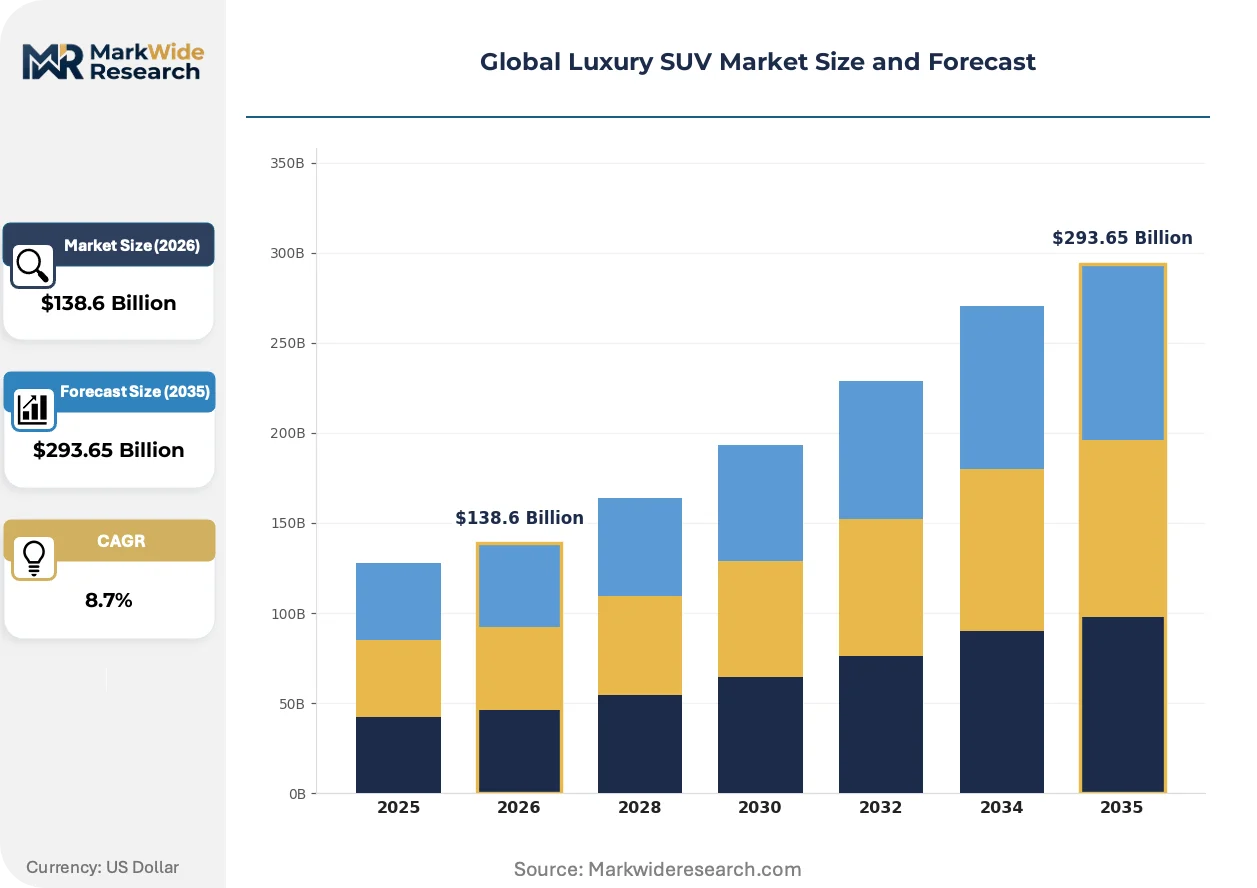
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $293.65 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact SUV, Midsize SUV, Full-size SUV, Crossover End User: Affluent Consumers, Corporation Executives, Rental Agencies, Families Fuel Type: Petrol, Diesel, Hybrid, Electric Size: Large, Medium, Small, Compact |
| Companies Covered | Mercedes-Benz Group AG, BMW Group, Audi AG, Jaguar Land Rover, Lexus, Porsche AG, Volvo Car Corporation, Bentley Motors, Tesla Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Luxury SUV Market Strategic Shifts
Software-defined vehicle architectures are redefining competitive differentiation as over-the-air capability becomes the primary vector for post-sale revenue generation and customer retention.
800-volt electrical architectures are consolidating as the dominant high-performance charging standard. Premium manufacturers specify these systems for flagship electric SUVs, enabling 10-80% charge cycles below 20 minutes. The technology is consolidating charging infrastructure investment toward compatible networks and marginalizing 400-volt platforms in the luxury segment.
The EU Green Deal's phased combustion restrictions through 2035 are forcing powertrain portfolio rationalization. Manufacturers must balance R&D allocation between compliant electric platforms and residual combustion demand in non-European markets. Full-size SUV derivatives face the steepest compliance costs, accelerating platform consolidation decisions.
Fleet procurement departments now embed sustainability metrics alongside total cost of ownership calculations. Corporate mobility programs in Germany and the United States prioritize electric SUVs for executive transport, displacing traditional diesel and petrol allocations. This specification shift concentrates volume with manufacturers offering certified carbon-neutral supply chains and renewable energy charging partnerships.
Global Luxury SUV Market Segmentation
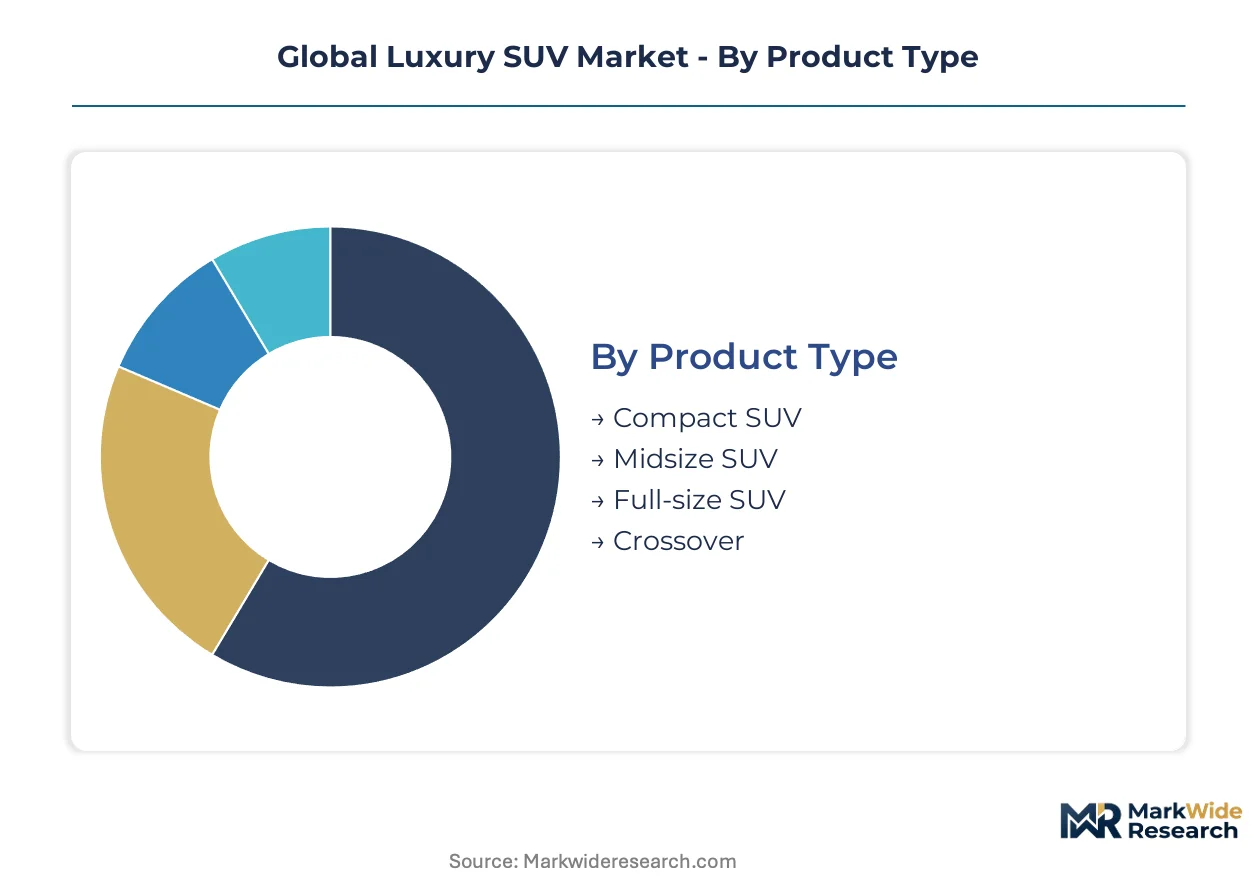
Luxury SUV segmentation reveals divergent engineering priorities across buyer archetypes. Product dimensions determine powertrain packaging constraints, while end-use profiles dictate feature calibration and distribution channel selection.
Product Type:
Vehicle footprint separates urban maneuverability requirements from long-haul comfort specifications.
- Midsize SUV:Wheelbase configurations between 110-120 inches balance three-row seating with garage accessibility. Fleet procurement in Germany and the United States concentrates here for executive shuttle programs, driven by parking infrastructure constraints in metropolitan cores.
- Compact SUV:Sub-105-inch wheelbase architectures prioritize Asian metropolitan density. Chinese affluent consumers in Shanghai and Shenzhen accelerate adoption as primary household vehicles, constrained by license plate rationing favoring smaller footprints.
- Full-size SUV:Body-on-frame construction exceeds 130 inches wheelbase for towing capacity and cabin volume.
- Crossover:Unibody construction merges car-like handling with elevated seating position.
Volume sits with Midsize SUV; growth tilts toward Compact SUV.
End User:
Purchase authority determines specification complexity and sales cycle duration.
- Corporation Executives:Mobility program administrators specify vehicles through centralized procurement with sustainability compliance mandates. EU Green Deal reporting requirements in Germany and France displace diesel allocations with electric alternatives, constrained by charging infrastructure verification protocols.
- Affluent Consumers:High-net-worth individuals in China and the United States configure through retail channels with personalization options. Beijing and Los Angeles metropolitan clusters concentrate demand, driven by brand heritage signaling and technology feature differentiation.
- Families:Multi-child households prioritize safety ratings and cargo flexibility.
- Rental Agencies:Fleet turnover economics dominate acquisition decisions.
Corporation Executives anchor volume stability; Affluent Consumers drive specification escalation.
Fuel Type:
Powertrain selection reflects regulatory compliance timelines and infrastructure maturity.
- Electric:Dedicated skateboard platforms with 800-volt architectures enable sub-20-minute fast-charging cycles. MIIT NEV credit mandates in China and EPA fleet standards in the United States accelerate manufacturer prioritization, constrained by cobalt supply chain concentration in the DRC.
- Hybrid:Parallel powertrain configurations bridge range anxiety and emissions compliance. German KBA certification processes favor plug-in variants for corporate fleet tax treatment, driven by EU Green Deal interim targets.
- Petrol:Turbocharged six-cylinder configurations retain residual demand in markets with limited charging infrastructure.
- Diesel:Compression-ignition architectures face phased combustion restrictions across European markets.
Hybrid maintains current volume leadership; electric gains share fastest.
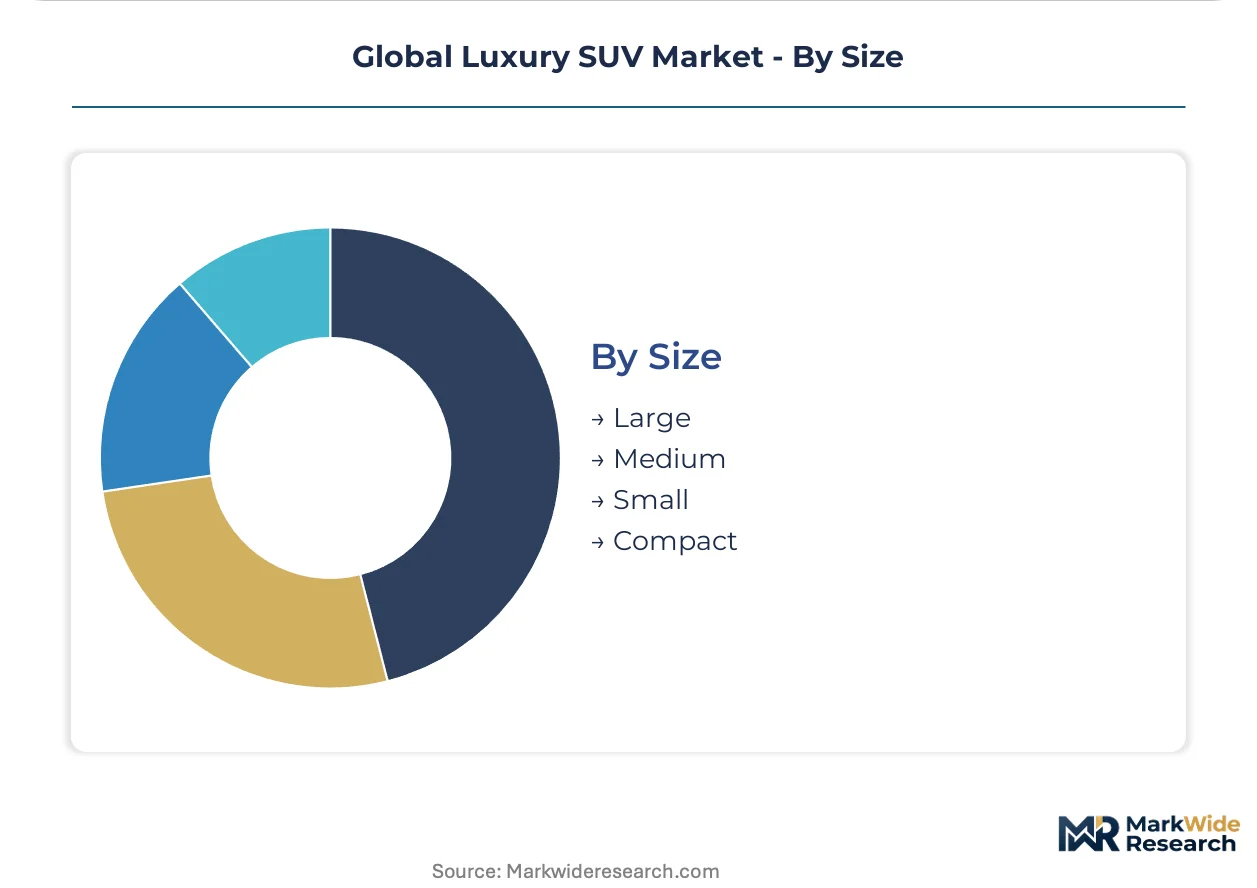
Size:
Dimensional classification determines platform engineering investment and manufacturing flexibility.
- Medium:C-segment platforms support modular powertrain integration across petrol, hybrid, and electric variants. Chinese MIIT production quotas and US EPA CAFE calculations concentrate manufacturer investment here, driven by volume scalability across multiple markets.
- Large:E-segment architectures accommodate full-size SUV proportions with V8 or dual-motor electric configurations. German autobahn cruising requirements and American towing specifications sustain demand, constrained by escalating compliance costs under EU Green Deal phase-out schedules.
- Small:B-segment entries target emerging market premiumization.
- Compact:A-segment urban runabouts with luxury branding.
Medium size captures manufacturing scale; Large size faces steepest regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Hainan Free Trade Port and Germany's Saxony EV cluster concentrate battery supply chain investment, anchoring regional production gravity for luxury electric SUV assembly.
China
Affluent consumers in Shanghai and Shenzhen accelerate electric SUV adoption as primary household vehicles, constrained by license plate rationing favoring NEVs. MIIT's escalating NEV credit mandates compel luxury marques to prioritize zero-emission variants. The Yangtze River Delta manufacturing corridor concentrates BMW Group and Mercedes-Benz Group AG joint-venture production for domestic and export markets.
Germany
Corporate fleet procurement in Munich and Stuttgart prioritizes electric SUVs for executive mobility programs under EU Green Deal reporting requirements. KBA certification processes favor plug-in hybrid variants for tax treatment advantages. The Saxony-Anhalt battery belt anchors CATL and Farasis gigafactory investment, securing localized cell supply for premium electric platforms.
United States
EPA CAFE standards impose fleet-wide compliance costs that compress margin flexibility for V8-powered full-size derivatives in Texas and California markets. The Inflation Reduction Act's domestic content bonuses reshape battery sourcing decisions for luxury assemblers. Southeast manufacturing corridors in South Carolina and Alabama concentrate BMW and Mercedes-Benz assembly operations serving Eastern seaboard demand clusters.
India
PLI scheme incentives for domestic battery manufacturing create entry pathways for luxury electric SUVs in underpenetrated Mumbai and Delhi-NCR markets. BIS certification timelines and state-level EV policies fragment homologation requirements across Maharashtra and Gujarat. The Tamil Nadu industrial corridor hosts premium component suppliers positioning for electrification transitions.
United Kingdom
Corporate sustainability mandates in London's financial district displace diesel allocations with electric alternatives for executive transport programs. CSRD disclosure requirements intensify supply chain carbon accounting for luxury marques. The West Midlands manufacturing cluster sustains Jaguar Land Rover assembly operations amid powertrain portfolio restructuring pressures.
Global Luxury SUV Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with established German luxury marques commanding premium positioning while technology entrants reshape electric powertrain expectations. The market structure concentrates around heritage automotive groups with multi-brand portfolios, tiered by electrification maturity and platform scale. Three archetypes dominate: legacy premium conglomerates with combustion-to-electric transitions, dedicated electric technology specialists, and ultra-luxury coachbuilders with low-volume craftsmanship positioning. Competitive intensity centers on battery supply chain partnerships and software-defined vehicle capability differentiation.
Within the legacy premium tier, Mercedes-Benz Group AG, BMW Group, and Tesla Inc. occupy distinct positioning vectors that exemplify divergent electrification strategies. Mercedes-Benz Group AG represents heritage luxury consolidation with S-Class SUV derivatives sustaining V8 demand alongside EQ electric sub-brand expansion. BMW Group anchors its position through iX platform architecture spanning European and Asian volume markets. Tesla Inc. exemplifies technology-native market entry with software-centric differentiation and direct distribution models that bypass traditional retail channels.
| Leading Market Players |
|---|
| Mercedes-Benz Group AG |
| BMW Group |
| Audi AG |
| Jaguar Land Rover |
| Lexus |
| Porsche AG |
| Volvo Car Corporation |
| Bentley Motors |
| Tesla Inc. |
| Others |
Value Chain & Pricing Dynamics
Powertrain certification divergence between EU Green Deal-compliant electric platforms and residual combustion architectures manifests in divergent pricing power and supply chain localization strategies across German, Chinese, and US manufacturing corridors. Premium electric SUVs command price premiums through 800-volt architecture exclusivity and battery supply chain traceability, while V8-powered full-size derivatives face margin compression from EPA CAFE penalty exposure and cobalt price volatility.
Pricing Analysis
Short lead-time premiums for certified carbon-neutral supply chains and renewable energy charging partnerships command pricing power in German corporate fleet procurement, while spot inventory of combustion-powered derivatives trades at discount to move aging stock. Three-tier pricing structure across flagship electric, plug-in hybrid bridge, and residual combustion levels differentiates on MIIT NEV credit compliance and KBA tax treatment certification. Pricing pressure stems from lithium-ion pack cost curves compressing battery premiums and cobalt supply concentration in the DRC amplifying input volatility. Corporate mobility programs show lowest price sensitivity due to sustainability mandate embedding, while affluent retail consumers in Asian metropolitan markets demonstrate highest elasticity to upfront capital outlay.
Supply Chain Analysis
Regional distribution centers in Germany's Saxony-Anhalt battery belt and China's Yangtze River Delta manufacturing corridor anchor hub-and-spoke patterns for cell-to-vehicle assembly. Battery cell production concentrates in China, South Korea, and Germany, drawing from cobalt feedstock in the Democratic Republic of Congo, lithium brine in Chile, and nickel laterite in Indonesia. Single-source vulnerability in DRC-dominant cobalt sourcing exposes tier-one suppliers to geopolitical disruption and ESG compliance cost escalation. Distribution runs through OEM captive logistics for finished vehicles and independent battery component distributors for aftermarket service parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's 2035 combustion prohibition creates a barrier-to-entry moat for manufacturers with certified electric platforms and localized battery supply chains, compressing margin flexibility for non-compliant legacy architectures.
For Market Incumbents: Hedge regulatory exposure by accelerating platform standardization across midsize and compact electric SUVs while maintaining residual V8 production capacity for US heartland and Middle East markets. Prioritize backward integration into cathode active material production through joint ventures with Chinese and South Korean cell suppliers to secure cobalt-free chemistry access. Battery thermal management engineering talent scarcity represents the critical constraint for execution velocity. For New Entrants and Emerging Players: Launch via direct-to-consumer digital channels targeting affluent consumers in India's Mumbai and Delhi-NCR metropolitan clusters, where PLI scheme incentives reduce capital barriers for domestic assembly. The underpenetrated premium electric SUV segment in secondary Chinese cities offers white-space expansion as charging infrastructure density matures. Solid-state battery technology partnerships with Japanese and US research institutes provide differentiation leverage against incumbent lithium-ion scale advantages. For Investors and Strategic Acquirers: Re-rating potential sits with technology-native electric specialists given software-defined vehicle capability differentiation and direct distribution margin capture. Long-term viability over the next decade hinges on battery supply chain sovereignty and 800-volt platform scalability across multiple vehicle classes. Monitor solid-state battery pilot production timelines as the inflection signal for next-generation energy density leadership.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | CATL and Farasis gigafactory partnerships in Germany's Saxony belt secure localized cell supply for EU Green Deal compliance. |
| Software-Defined Vehicle Investment | Over-the-air capability development enables post-sale revenue streams and customer retention in corporate fleet segments. |
| Platform Standardization | Modular skateboard architectures spanning midsize and compact segments compress R&D allocation per vehicle variant. |
| Charging Infrastructure Partnership | Renewable energy charging alliances with utility operators satisfy CSRD disclosure requirements for German corporate mobility programs. |
| Geographic Manufacturing Footprint | Southeast US corridor expansion in South Carolina and Alabama captures Inflation Reduction Act domestic content bonuses. |
Study Parameters
Document review covered SEC 10-K filings, EPA CAFE compliance disclosures, MIIT NEV credit quota publications, and IHS Markit vehicle registration databases, complemented by interviews with OEM platform engineers, Tier 1 supplier procurement directors, corporate fleet mobility administrators, and battery cell manufacturing executives. Secondary validation drew from EU Green Deal implementation guidance, KBA type-approval records, and customs trade data for lithium and cobalt feedstock flows. Bottom-up production volume estimates triangulated against top-down market value projections across the analysis window.
Historical production trajectories cross-referenced against expert panel input from automotive engineering and battery chemistry specialists shaped the analytical framework. Segmentation dimensions modeled include vehicle class, propulsion architecture, OEM tier, and regional production cluster. CAGRs derived from regression analysis of powertrain transition curves and regulatory compliance timeline phasing. Industry-specific forecast inputs encompassed battery pack cost decline trajectories and charging infrastructure deployment density curves.
Regulatory enforcement variance between EPA, MIIT, and KBA approval processes, cobalt supply disruption events, and solid-state battery commercialization delays are the dominant revision risks to projection accuracy. Forecasts reflect documented assumptions regarding emissions standard stringency and infrastructure investment continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
South America Passenger Cars Market
Passenger Vehicles
Convertible Vehicles Market
Passenger Vehicles
Automotive Passenger Vehicle Sensor Market
Passenger Vehicles
Luxury Car Market
Passenger Vehicles
Electric Passenger Car MRO Market
Passenger Vehicles
Limousines Market
Passenger Vehicles
Lightweight Cars Market
Passenger Vehicles
Global SUV Market
Passenger Vehicles
India Luxury Car Market
Passenger Vehicles
Train Seat Market
Passenger Vehicles
China Luxury Car Market
Passenger Vehicles
Compact Cars Market
Passenger Vehicles
Asia Pacific Luxury Cars Market
Passenger Vehicles
Passenger Vehicle Market
Passenger Vehicles
Small Suvs Market
Passenger Vehicles
India Automotive Market