
 Egypt Automotive Engine Oils Market | 2026-2036
Egypt Automotive Engine Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Automotive Engine Oils Market Foresight
Aftermarket service revenue is tilting from basic oil changes toward extended-drain premium formulations. Shell Egypt leverages its global blending technology leadership to capture margin in synthetic grades. Misr Petroleum anchors its position through state-linked distribution networks spanning Upper Egypt. TotalEnergies Marketing Egypt competes on fleet-contract bundling with integrated maintenance services.
Automotive engine oils are formulated lubricants comprising base oils and additive packages designed to reduce friction, dissipate heat, and suspend combustion byproducts in internal combustion engines, with viscosity grades such as SAE 5W-30 and 10W-40 defining cold-start and operating-temperature performance. Synthetic formulations command expanding shelf space as thermal stability requirements intensify under Egyptian summer operating conditions. Service centers represent the dominant distribution channel by volume, though online retail is gaining traction among younger vehicle owners in metropolitan areas. Fleet operators constitute the fastest-growing end-user segment as logistics companies professionalize maintenance schedules.
Egypt's General Authority for Petroleum and the Egyptian Organization for Standardization and Quality enforce lubricant labeling and performance claims, while API and ACEA specifications serve as de facto import benchmarks for multinational suppliers. Compliance with tightening emission norms is pushing reformulation toward lower SAPS oils compatible with after-treatment systems. Stakeholders must monitor how fuel subsidy restructuring affects vehicle utilization patterns and oil change intervals.
Market Dynamics
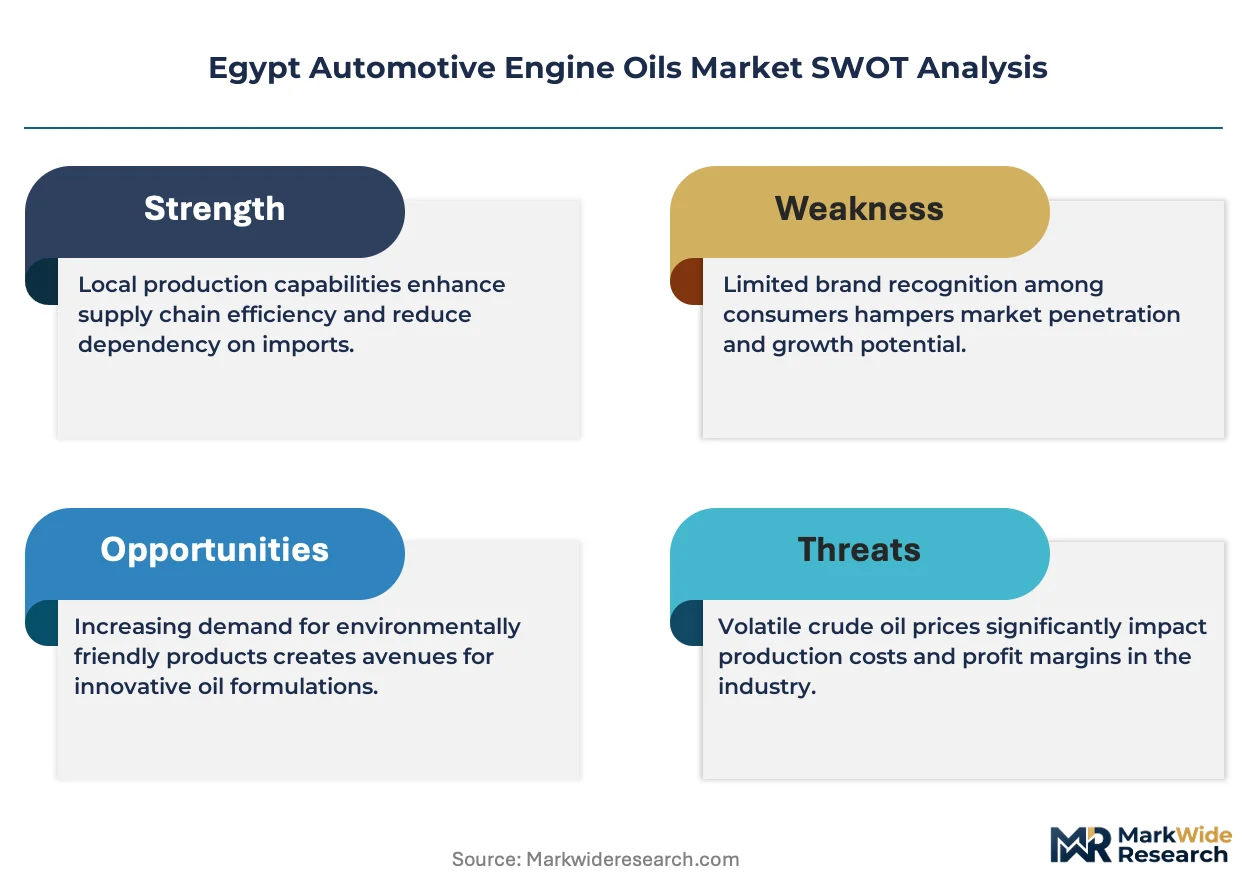
Egypt's mandatory Euro 5 emission transition is compressing formulation cycles as lubricant suppliers must certify lower SAPS oils compatible with exhaust after-treatment systems before the enforcement deadline.
Growth Catalysts
- Commercial vehicle utilization:Fleet operators in Alexandria's port corridors are extending service contracts as logistics volumes rise, pulling premium drain-interval formulations into procurement schedules.
- Egyptian Organization for Standardization and Quality labeling mandates:Tightened performance claim verification is filtering counterfeit lubricants from circulation, consolidating volume toward certified suppliers.
- Synthetic base oil technology:Thermal stability improvements under summer operating conditions are expanding addressable service intervals for high-temperature engine architectures.
Market Restraints
- Base oil import dependency:Egypt's limited domestic Group II/III production concentrates supply risk on Mediterranean refinery throughput fluctuations.
- Price elasticity in informal service channels:Unlicensed workshops in Upper Egypt undercut certified pricing with unverified bulk oils, compressing margin in price-sensitive segments.
- After-treatment system compatibility:Legacy diesel fleets without diesel particulate filters face premature catalyst poisoning if misfueled with incorrect SAPS grades, creating liability exposure for distributors.
Strategic Opportunities
- Upper Egypt service network penetration:Sparse certified distribution in Minya and Assiut governorates offers first-mover positioning as vehicle ownership rises in these corridors.
- Digital fleet maintenance platforms:Telematics-integrated oil monitoring is opening subscription-based lubricant replenishment contracts with logistics operators.
- Egypt General Authority for Petroleum subsidy restructuring:Fuel price rationalization is extending vehicle replacement cycles, increasing lubricant consumption per fleet asset over ownership lifespan.
Industry Challenges
- Blending technician certification:Shortage of personnel trained in API/ACEA specification matching slows product line expansion for mid-tier distributors.
- Reformulation capex cycles:Accelerated emission standard transitions require repeated additive package redevelopment before amortization of prior investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Automotive Engine Oils Market |
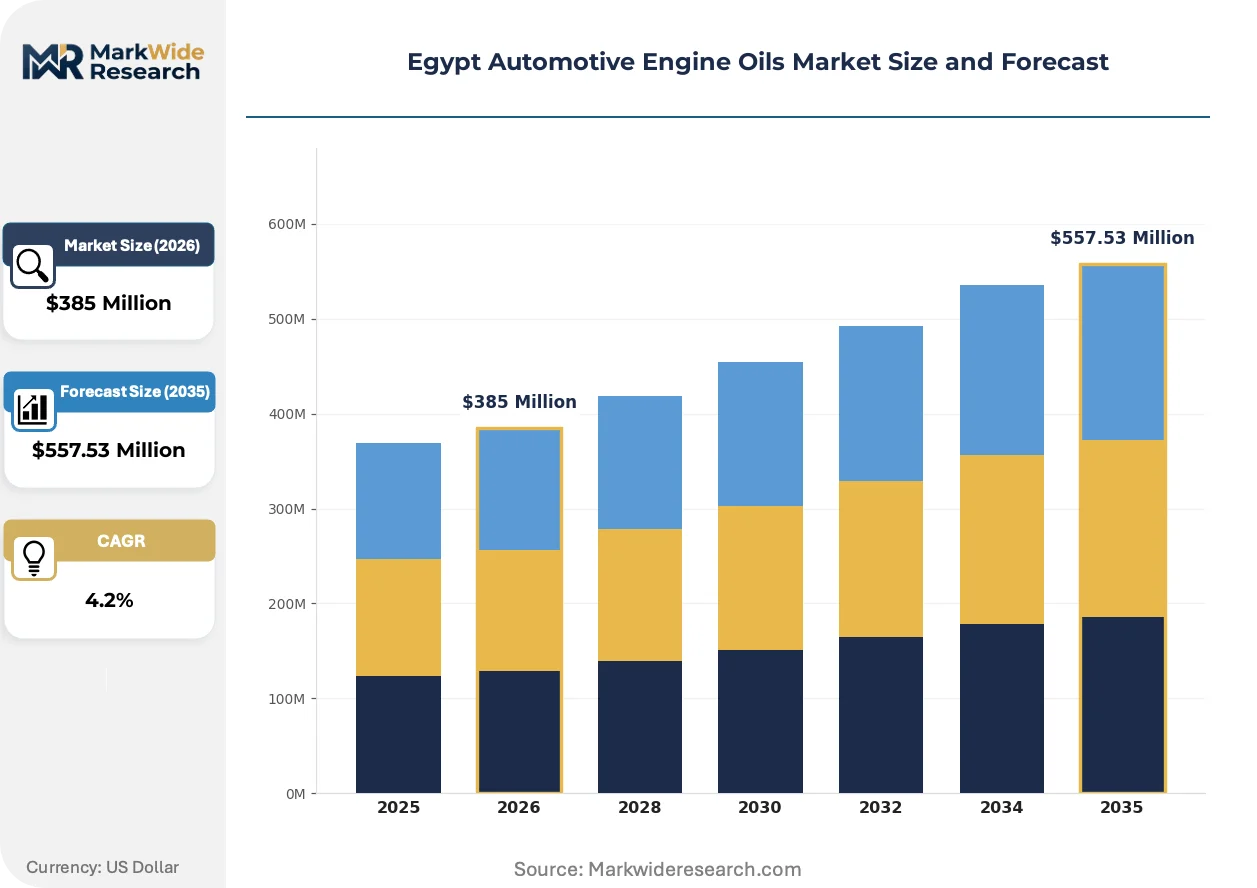
| Market Size in 2026 | $385 Million |
| Market Size in 2035 | $557.53 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Semi-Synthetic, Mineral, High Mileage End User: Personal Vehicles, Commercial Vehicles, Fleet Operators, Service Stations Performance Level: API, ACEA, JASO, ILSAC Distribution Channel: Online Retail, Auto Parts Stores, Dealerships, Service Centers |
| Companies Covered | BP Egypt, Misr Petroleum, Shell Egypt, Arabian Oil Company, Castrol Egypt, TotalEnergies Marketing Egypt, Chevron Egypt, Fuchs Petrolub SE, ExxonMobil Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Automotive Engine Oils Market Shifts & Advancements
Formulation science and distribution architecture are diverging sharply as thermal performance requirements intensify and buyer procurement preferences fragment across channel types.
Low-viscosity 0W-20 and 5W-30 synthetic blends engineered for turbocharged gasoline direct injection engines are rendering obsolete conventional mineral 15W-40 grades in Greater Cairo's newer vehicle parc. Premium service centers in New Cairo and 6th of October City are adopting these formulations at pace as OEM warranty requirements tighten. The shift is compressing shelf space for mid-tier mineral products and reallocating distributor working capital toward API SP-licensed synthetics.
Egypt's Environmental Affairs Agency is aligning national emission enforcement timelines with Euro 5 standards, mandating exhaust after-treatment compatibility for all new commercial vehicle registrations from 2025. The regulation is forcing lubricant suppliers to accelerate lower SAPS certification programs ahead of the compliance window. Heavy-duty fleet operators in Alexandria and Suez are pre-emptively switching to CK-4/FA-4 categories to avoid warranty voidance risks.
Younger vehicle owners in metropolitan areas are migrating lubricant purchasing to e-commerce platforms and manufacturer-direct mobile applications, bypassing traditional service center bundling. This channel disintermediation is fragmenting volume concentration and forcing legacy distributors to build last-mile fulfillment capabilities. The pattern is most visible in Cairo's eastern districts where digital payment penetration and smartphone ownership rates exceed national averages.
Egypt Automotive Engine Oils Market Segmentation
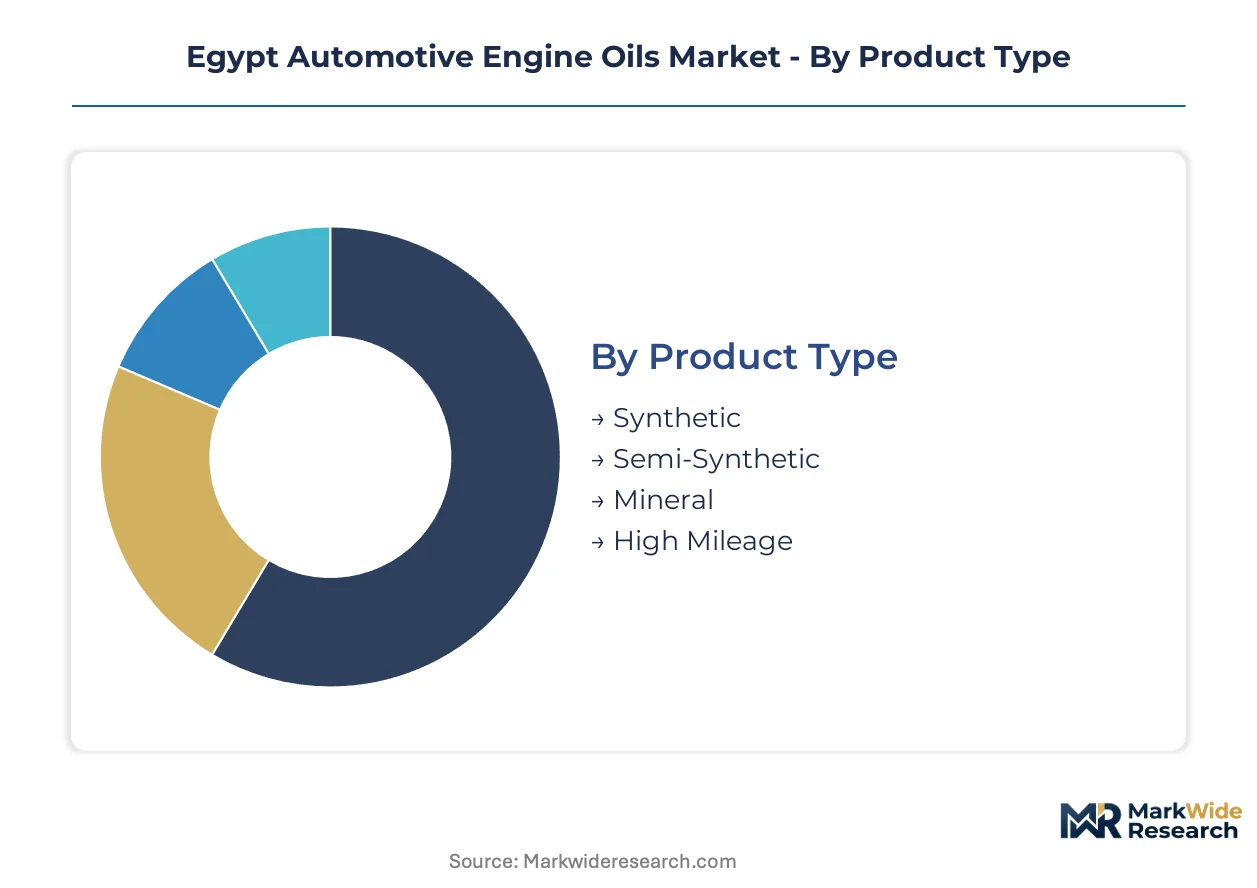
Automotive engine oils in Egypt fragment across lubricant chemistry, vehicle ownership patterns, certification standards, and channel architecture. Each dimension shapes procurement economics and margin capture differently across Greater Cairo's dense service networks and Alexandria's logistics corridors.
Product Type:
After-sales service intensity varies sharply by lubricant chemistry, with synthetic formulations demanding specialized dispensing equipment and technical consultation that mineral grades rarely require.
- Synthetic:Group III and PAO base stocks deliver thermal stability exceeding 150°C operating temperatures common in Egyptian summer traffic conditions. Demand concentrates in New Cairo and 6th of October City service centers serving turbocharged gasoline direct injection engines under OEM warranty requirements.
- Semi-Synthetic:Blended formulations balance cost and performance for mid-life vehicle parc. Fleet operators in Alexandria's port corridors are adopting these for mixed-age commercial assets where drain interval extension justifies modest premium over mineral grades.
- Mineral:Group I base oils dominate price-sensitive replacement demand in Upper Egypt's informal service channels.
- High Mileage:Seal conditioners and anti-wear additives target vehicles exceeding 100,000 kilometers on Egyptian roads.
Mineral formulations hold the largest share; momentum sits with synthetic grades as thermal requirements intensify.
End User:
Cost tier stratification separates warranty-bound professional maintenance from discretionary consumer spending across Egypt's vehicle population.
- Personal Vehicles:Individual owners in metropolitan Cairo exhibit rising synthetic adoption driven by OEM service schedule compliance and resale value preservation.
- Commercial Vehicles:Heavy-duty diesel operators face Euro 5 after-treatment compatibility mandates accelerating lower SAPS oil procurement.
- Fleet Operators:Logistics companies professionalizing maintenance schedules represent the steepest expansion trajectory as telematics enable predictive oil monitoring and contracted replenishment.
- Service Stations:Branded fuel retail networks bundle lubricant sales with convenience positioning, capturing impulse purchases during refueling stops.
Personal vehicles dominate volume; fleet operators are climbing the fastest as logistics professionalization accelerates.
Performance Level:
Application severity and engine architecture dictate certification requirements across Egyptian operating conditions.
- API:SP and CK-4 categories are displacing older specifications as turbocharged direct injection and heavy-duty diesel after-treatment systems proliferate in the vehicle parc.
- ACEA:European sequences gain traction among premium European OEM service centers in Cairo's eastern districts where C-class and E-class Mercedes-Benz volumes concentrate.
- JASO:Motorcycle-specific friction certification addresses two-wheeler lubricant demand in dense urban mobility corridors.
- ILSAC:Fuel economy-focused specifications align with gasoline passenger car requirements in Egypt's import-dependent vehicle fleet.
API specifications anchor volume; ACEA sequences gain share fastest among premium service networks.
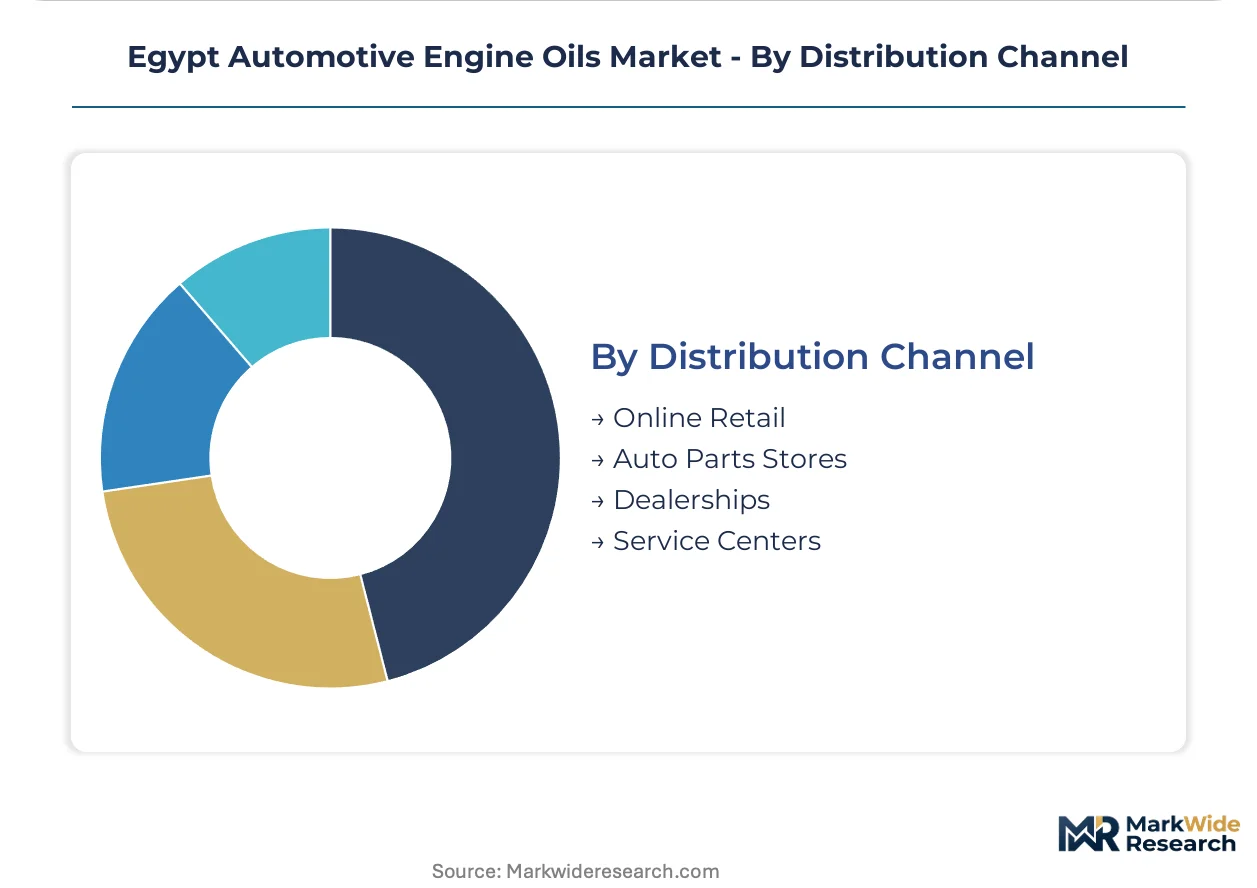
Distribution Channel:
Customer type and purchase urgency determine channel selection across Egypt's fragmented retail landscape.
- Online Retail:E-commerce platforms and manufacturer-direct applications attract younger vehicle owners in Cairo's eastern districts where digital payment penetration exceeds national averages.
- Auto Parts Stores:Independent retailers in industrial zones serve price-conscious DIY maintainers and small independent workshops.
- Dealerships:Authorized service networks enforce OEM-specified lubricant grades to preserve warranty coverage, capturing premium pricing.
- Service Centers:Technical labor bundling with oil changes dominates volume as Egyptian consumers prefer outsourced maintenance despite higher per-liter lubricant costs.
Service centers command the largest share; online retail is expanding most quickly among metropolitan younger owners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across Egypt's governorates, with informal channels in Upper Egypt undercutting certified pricing while Greater Cairo's warranty-bound service centers absorb synthetic premiums without volume loss.
Greater Cairo
New Cairo and 6th of October City service centers drive synthetic-grade demand as OEM warranty compliance tightens. The Egyptian Environmental Affairs Agency enforces Euro 5 alignment timelines that accelerate lower SAPS certification. Cairo's eastern districts concentrate telematics-integrated fleet operators professionalizing predictive maintenance schedules.
Alexandria
Port-linked logistics corridors pull premium drain-interval formulations as commercial vehicle kilometers rise on Mediterranean trade routes. The General Authority for Petroleum monitors fuel subsidy restructuring effects on fleet utilization patterns. Alexandria's industrial zones host dense service networks serving heavy-duty diesel operators pre-emptively switching to CK-4 categories.
Suez Canal Zone
Transit corridor logistics operators extend service contracts as international shipping volumes recover post-2023. The Suez Canal Authority coordinates with environmental regulators on commercial vehicle emission enforcement timelines. Port Said and Ismailia service centers capture cross-border fleet maintenance demand from Sinai-based operators.
Upper Egypt
Sparse certified distribution in Minya and Assiut governorates concentrates volume in unlicensed workshops using unverified bulk oils. The Egyptian Organization for Standardization and Quality labeling mandates filter slower into these corridors due to enforcement gaps. Vehicle ownership rises in these governorates without matching service network density, creating first-mover positioning opportunities.
Delta Region
Agricultural equipment and light commercial vehicle parc in Mansoura and Tanta sustain mineral-grade demand despite synthetic penetration in metropolitan areas. The Ministry of Agriculture's mechanization programs indirectly affect lubricant consumption patterns through tractor fleet expansion. Delta industrial cities show emerging synthetic adoption among younger vehicle owners migrating from inherited maintenance habits.
Egypt Automotive Engine Oils Market Competitive Landscape
Capability concentration sits with multinational blenders possessing API-licensed formulation science; scale advantage sits with state-linked distributors commanding Upper Egypt's sparse retail networks. The market structures around three tiers: global majors with proprietary additive packages, national champions leveraging fuel station real estate, and regional specialists serving price-sensitive informal channels. Strategic moves center on fleet-contract bundling and synthetic-grade portfolio expansion rather than capacity-led volume plays.
Within the multinational tier, Shell Egypt and TotalEnergies Marketing Egypt occupy positions defined by global blending technology access and integrated maintenance service bundling. BP Egypt and Castrol Egypt anchor the premium synthetic vector through OEM partnership architectures. Misr Petroleum exemplifies the state-linked national champion archetype, its distribution network spanning governorates where informal channels otherwise dominate. Chevron Egypt and ExxonMobil Corporation represent the American major positioning, while Fuchs Petrolub SE anchors German specialized lubricant expertise. Arabian Oil Company sits within the regional specialist tier serving price-sensitive segments outside metropolitan certification requirements.
| Leading Market Players |
|---|
| BP Egypt |
| Misr Petroleum |
| Shell Egypt |
| Arabian Oil Company |
| Castrol Egypt |
| TotalEnergies Marketing Egypt |
| Chevron Egypt |
| Fuchs Petrolub SE |
| ExxonMobil Corporation |
| Others |
Supply & Pricing Matrix
Alexandria's port-linked logistics corridors transmit Mediterranean refinery cost volatility directly into Egyptian lubricant pricing, concentrating supply risk among a handful of Group II/III base oil importers while fragmenting downstream price differentiation across certified service centers and informal Upper Egypt workshops.
Pricing Analysis
Long-term offtake contracts between multinational blenders and Mediterranean refineries dominate procurement, insulating Shell Egypt and TotalEnergies Marketing Egypt from spot price spikes while exposing smaller distributors to Group I base oil volatility. Price differentiation separates API SP-licensed synthetics from unverified bulk oils through certification grade and after-sales technical consultation. Cost compression in mineral grades is intensifying because unlicensed workshops in Minya and Assiut undercut certified pricing. Fleet operators exhibit lowest price sensitivity due to warranty compliance requirements; individual consumers in Upper Egypt remain most elastic.
Supply Chain Analysis
Tariff exposure between Egypt and European Union additive package suppliers dominates supply chain risk planning for reformulation cycles ahead of Euro 5 enforcement. Base oil production concentrates in Italy, Spain, and Greece, with Egyptian blenders drawing from Mediterranean refinery output. The supply chain rests on polyalphaolefin synthetic base stocks, detergent-dispersant additive packages, and viscosity index improvers. Single-source vulnerability sits with specialized low-SAPS additive suppliers serving CK-4/FA-4 certification requirements. Distribution runs through Misr Petroleum's state-linked fuel station networks and independent service centers in parallel channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across Egypt's lubricant market creates positioning niches as digital procurement patterns split metropolitan younger owners from legacy service center loyalists and informal channel price hunters.
For Market Incumbents: Pre-empt synthetic-grade shelf space compression by accelerating API SP-licensed portfolio expansion before smaller distributors complete technician certification. Secure backward integration into additive package sourcing to reduce European supplier dependency as reformulation cycles accelerate. Channel control through telematics-integrated fleet contracts represents the critical defensive lever against e-commerce disintermediation. For New Entrants and Emerging Players: Establish a beachhead in Upper Egypt's certified distribution gap, where rising vehicle ownership in Assiut and Minya governorates outpaces service network density. Target fleet operators with subscription-based lubricant replenishment contracts leveraging predictive oil monitoring technology. A direct-to-workshop mobile application bypassing traditional distributor markups offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from state-linked petroleum holding companies seeking to monetize non-core lubricant blending assets ahead of subsidy restructuring. Long-term viability centers on synthetic-grade margin capture and fleet-contract recurring revenue rather than mineral volume plays. Watch for inflection when the Egyptian Environmental Affairs Agency accelerates Euro 5 enforcement timelines, forcing legacy distributor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Sourcing | Reduces European supplier dependency as SAPS reformulation cycles compress. |
| Telematics-Integrated Fleet Contracts | Locks in logistics operators through predictive oil monitoring subscriptions. |
| Upper Egypt Service Network Expansion | Captures first-mover positioning in Minya and Assiut governorates. |
| API SP Synthetic Portfolio Acceleration | Aligns with New Cairo OEM warranty requirements displacing mineral grades. |
| E-Commerce Platform Development | Addresses Cairo eastern districts where digital payment penetration exceeds national averages. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with lubricant blending plant managers, fleet procurement officers at Alexandria port logistics operators, aftermarket service center owners, and Egyptian Organization for Standardization and Quality regulatory officials; and secondary validation through customs import records, API licensing databases, Egyptian General Authority for Petroleum subsidy filings, and vehicle registration data from the Egyptian Automobile Manufacturers Association. Bottom-up volume modeling triangulated against top-down market sizing across product chemistry, end-user type, and distribution channel dimensions.
Forecast inputs considered base oil import cost trajectories, Euro 5 enforcement timeline scenarios, and fleet telematics penetration rates across the analysis window. Segmentation modeling captured lubricant chemistry tier, vehicle ownership archetype, performance certification standard, and channel architecture variations. CAGRs were derived from elasticity-adjusted volume projections incorporating fuel subsidy restructuring effects on vehicle utilization patterns. Industry-specific inputs included summer operating temperature severity indices and after-treatment system penetration rates in commercial vehicle parc.
Stress conditions across Mediterranean refinery throughput fluctuations, Egyptian pound volatility against euro-denominated additive imports, and Euro 5 enforcement acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about fleet professionalization rates and digital channel migration speed. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
North America Automotive Parts Zinc Die Casting Market
Automotive Parts
South America Automotive Engine Oils Market
Automotive Parts
Italy Automotive Parts Zinc Die Casting Market
Automotive Parts
Resin Silencer Market
Automotive Parts
Automotive Hydraulic Filter System Market
Automotive Parts
Global Automotive Timing Belt Market
Automotive Parts
Automotive Power Window Regulator Market
Automotive Parts
Latin America Automotive Airfilters Market
Automotive Parts
Europe Automotive Engine Oils Market
Automotive Parts
Global Automotive Plastic Fuel Tank Market
Automotive Parts
Air Filter Cartridges Market
Automotive Parts
Automotive Seat Track Market
Automotive Parts
South Africa Automotive Parts Aluminium Die Casting Market
Automotive Parts
Automotive Canister Market
Automotive Parts
Automotive Exhaust System Market
Automotive Parts
Automotive Spring Market