
 Compact Cars Market | 2026-2036
Compact Cars Market Size, Share, and Industry Trends Forecast 2026-2036
Compact Cars Market Intelligence
Euro 7 emission standards is restructuring the engineering cost base for internal combustion compact cars, forcing suppliers to integrate advanced exhaust after-treatment and real-driving emissions monitoring. Toyota sustains hybrid leadership through dedicated compact platforms that span Corolla and Prius nameplates across multiple continents. Volkswagen anchors European volume with its MQB-A0 architecture, while Hyundai competes aggressively on price-equipment ratios in emerging economies.
Compact cars are passenger vehicles with wheelbases typically spanning 2,500 to 2,700 millimeters and overall length below 4,500 millimeters, engineered for urban maneuverability and fuel efficiency through unibody steel construction and front-wheel-drive layouts. Their primary commercial purpose is delivering affordable personal mobility to dense metropolitan populations and cost-sensitive fleet operators. The fuel type dimension shows electric powertrains capturing engineering investment despite petrol retaining volume leadership in price-sensitive regions, while the body type split favors hatchbacks in Europe and India where parking scarcity and taxation by length shape purchasing behavior. The end user segment reveals fleet operators and ride-sharing services as the fastest-growing demand pool, extracting higher utilization rates per vehicle than individual ownership models.
The US EPA and NHTSA coordinate Corporate Average Fuel Economy standards that push Detroit Three compact offerings toward electrification, while India's BIS enforces crash-test protocols under Bharat NCAP that raise structural steel grades and safety equipment costs. China's MIIT administers dual carbon goals that accelerate local OEM transitions from pure internal combustion to plug-in hybrid compact architectures. Stakeholders must monitor how divergent regulatory stringency across these jurisdictions fragments platform economics and forces region-specific powertrain portfolios rather than globally unified compact car lines.
Market Dynamics
Euro 7 emission standards are compressing the engineering runway for internal combustion compact cars, forcing simultaneous investment in exhaust after-treatment, real-driving emissions monitoring, and electrified alternatives across European assembly plants.
Growth Catalysts
- Urban fleet electrification mandates:São Paulo and Mexico City regulators are accelerating procurement deadlines for zero-emission ride-sharing vehicles, pulling forward compact hatchback demand from fleet operators.
- Bharat NCAP safety protocols:India's BIS enforcement of structural crash-test requirements is normalizing higher-margin safety equipment packages across sub-four-meter sedan configurations.
- Hybrid powertrain maturation:Dedicated compact hybrid platforms spanning multiple nameplates are achieving cost parity with pure internal combustion in high-volume manufacturing configurations.
Market Restraints
- Advanced steel grade cost inflation:High-strength automotive steel specifications required for Bharat NCAP compliance are raising structural material costs for entry-level compact variants.
- Powertrain portfolio fragmentation:Divergent regulatory stringency across US EPA, EU Euro 7, and China MIIT dual carbon goals is preventing globally unified compact car platform economics.
- Battery supply concentration:Lithium-ion cell production for compact electric variants remains concentrated in a limited supplier base, exposing OEMs to input volatility and allocation constraints.
Strategic Opportunities
- Plug-in hybrid architecture transition:China's MIIT dual carbon goals are creating regulatory headroom for compact PHEV variants that bridge emission compliance and consumer range anxiety.
- Ride-sharing fleet specialization:Dedicated compact vehicle configurations optimized for high-utilization urban fleet operators represent an underpenetrated demand pool distinct from retail ownership patterns.
- After-sales service digitization:Connected vehicle telematics integration is enabling predictive maintenance revenue streams and direct-to-fleet software subscription models.
Industry Challenges
- Embedded software integration complexity:Real-driving emissions monitoring systems and over-the-air update architectures require new competencies in automotive firmware development that legacy powertrain engineering teams lack.
- Multi-jurisdiction homologation timelines:Simultaneous compliance with US EPA Corporate Average Fuel Economy, EU Euro 7, and India BIS certification protocols is extending product launch cycles and engineering validation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compact Cars Market |
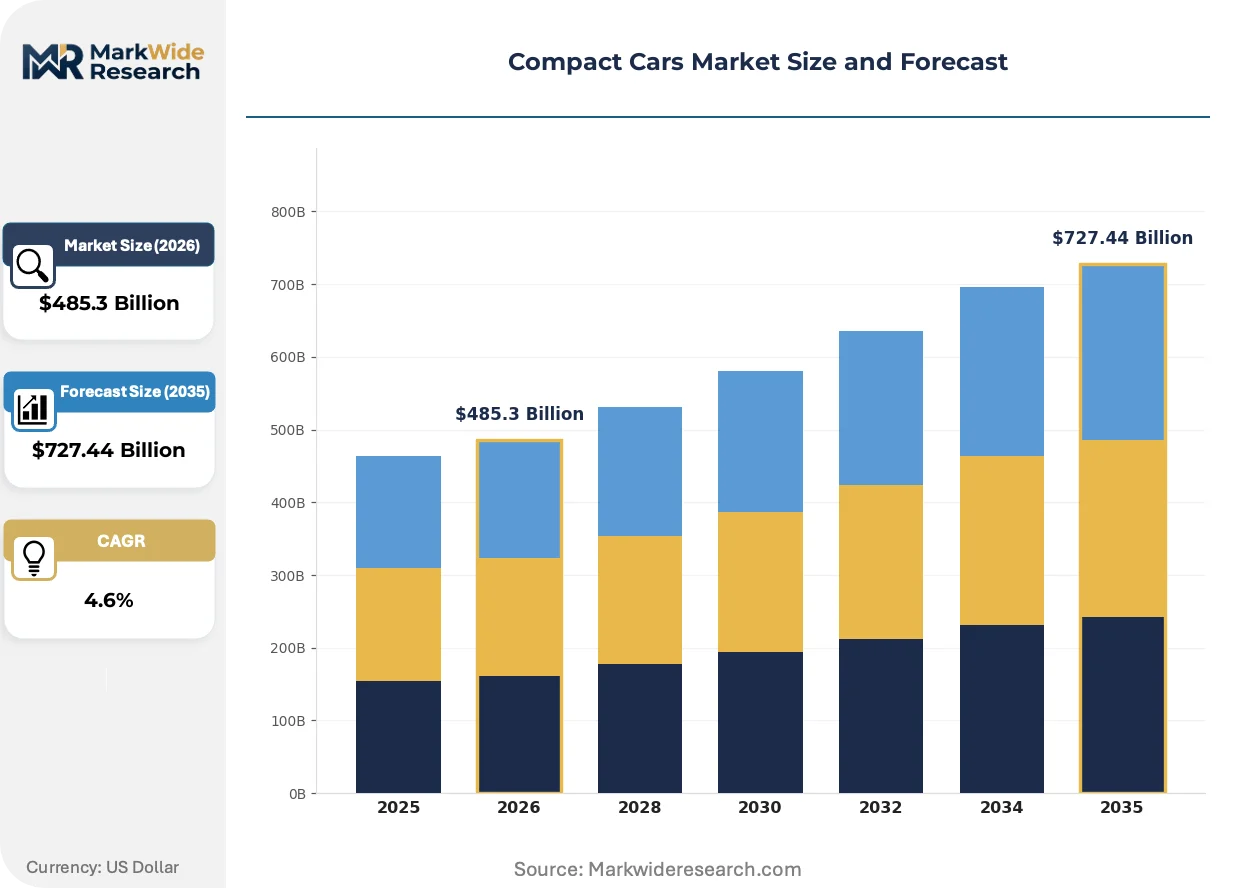
| Market Size in 2026 | $485.3 Billion |
| Market Size in 2035 | $727.44 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Body Type: Sedan, Hatchback, Coupe, Convertible Fuel Type: Petrol, Diesel, Electric, Hybrid Transmission: Manual, Automatic, CVT, Dual-Clutch End User: Individual Consumers, Fleet Operators, Ride-Sharing Services, Car Rentals |
| Companies Covered | Kia, Mazda, Honda, Subaru, Nissan, Toyota, Volkswagen, Chevrolet, Hyundai, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compact Cars Market Strategic Shifts & Innovations
Powertrain electrification is fragmenting compact car platform strategies, with divergent regional regulatory pressures forcing parallel development tracks rather than globally scalable architectures.
Modular electric vehicle platforms with standardized battery pack formats and scalable motor configurations are overtaking adapted internal combustion architectures in new compact car development programs. European and Chinese OEMs are prioritizing ground-up electric designs for their next-generation compact offerings. This technology shift is compressing the engineering cost advantage historically held by legacy internal combustion platforms.
EPA and NHTSA coordination on Corporate Average Fuel Economy standards is tightening fleet emission thresholds for Detroit Three compact lineups, accelerating powertrain electrification commitments. The industrial consequence is redirected capital from internal combustion refinement to hybrid and battery-electric compact variants. US-market compact sedans and hatchbacks are responding with expanded hybrid powertrain availability across trim levels.
Fleet procurement departments at urban ride-sharing operators are consolidating vehicle sourcing around standardized compact hatchback specifications with interchangeable components and extended service intervals. Traditional dealer networks are losing volume to direct fleet supply agreements with embedded maintenance contracts. Brazil and Mexico exhibit the most visible concentration of this procurement pattern, with São Paulo-based operators leading contract restructuring.
Compact Cars Market Segmentation
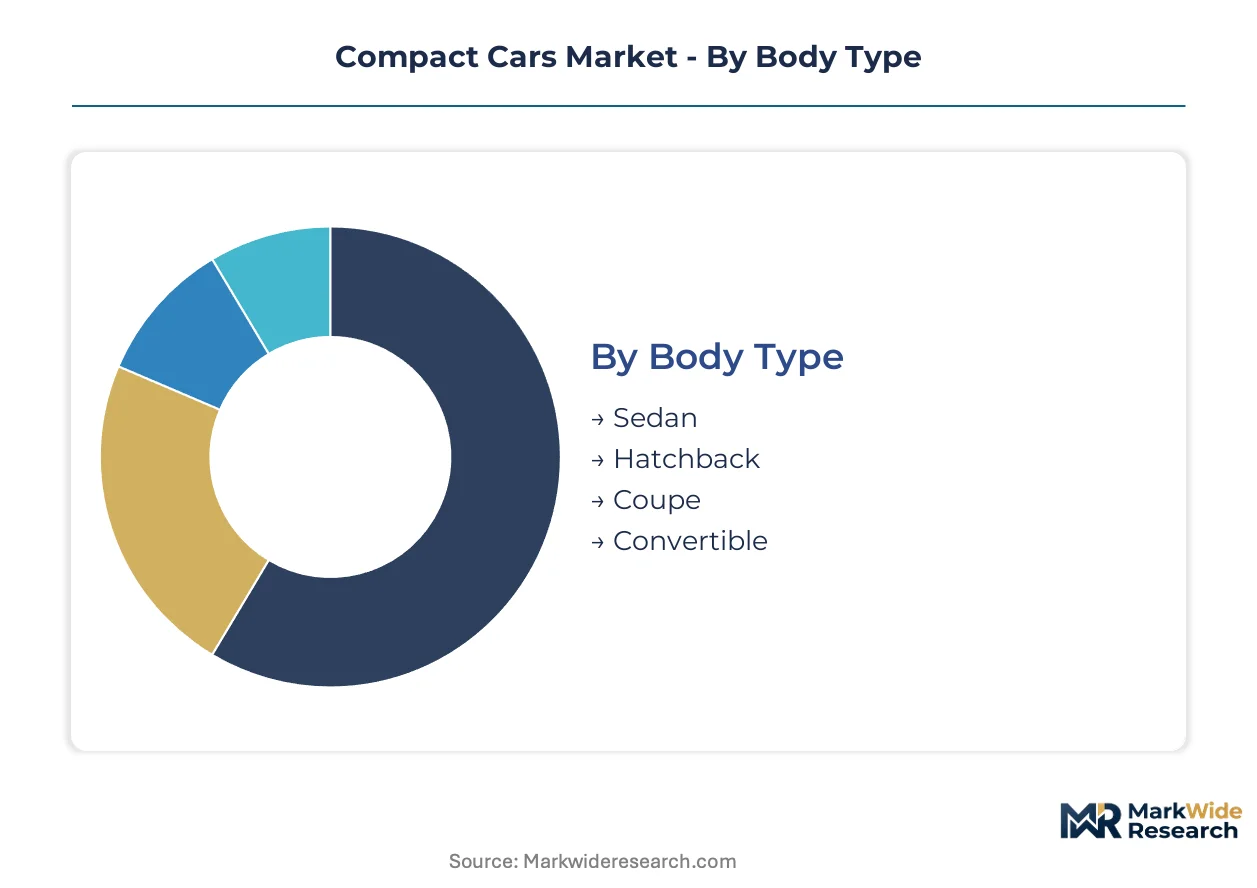
Compact car manufacturers engineer platform variants to capture divergent demand pools across parking-constrained urban centers and high-utilization fleet operations. Segmentation discipline separates volume-driven hatchback configurations from premium sedan derivatives, while powertrain portfolios must satisfy both emission-stringent European cities and price-sensitive emerging markets.
Body Type:
Volume concentration favors shorter overhangs and vertical space efficiency, while premium positioning exploits elongated silhouettes and aerodynamic refinement.
- Sedan:Three-box architecture with dedicated trunk compartments dominates Indian sub-four-meter taxation brackets and Chinese family mobility preferences. Maruti Suzuki and Hyundai anchor manufacturing scale in this configuration, though parking scarcity in São Paulo and Mexico City constrains urban penetration.
- Hatchback:Two-box designs with integrated cargo access maximize interior volume per exterior footprint, capturing European and Latin American fleet procurement for ride-sharing services. Euro 7 packaging requirements for exhaust after-treatment systems are compressing rear cargo dimensions in this segment.
- Coupe:Sloping rooflines and frameless door configurations occupy niche positioning above mainstream hatchback pricing, appealing to individual consumers in developed Asian markets seeking stylistic differentiation from fleet-dominated segments.
- Convertible:Retractable roof mechanisms add structural reinforcement mass that conflicts with compact-class efficiency mandates, limiting deployment to Mediterranean climate zones and leisure-rental fleets.
Today's leader: Hatchback. Tomorrow's challenger: Sedan.
Fuel Type:
Regulatory stringency fragments powertrain economics across jurisdictions, forcing parallel development tracks rather than globally scalable architectures.
- Petrol:Turbocharged direct-injection variants retain cost leadership in India, Brazil, and Southeast Asia where refueling infrastructure and consumer price sensitivity outweigh emission advantages. Bharat NCAP compliance costs are eroding the historical margin gap versus hybrid alternatives.
- Diesel:Compression-ignition powertrains face accelerating phase-out in European urban centers under Euro 7 real-driving emissions protocols, though Indian commercial fleet operators continue procurement for highway fuel economy.
- Electric:Battery-electric architectures with dedicated skateboard platforms are gaining engineering investment priority in China under MIIT dual carbon goals, with cell cost trajectories approaching parity in high-volume manufacturing configurations.
- Hybrid:Toyota's dedicated compact hybrid platforms spanning Corolla and Prius nameplates achieve cost parity with pure internal combustion in factory utilization above threshold volumes, climbing the fastest in markets with fuel taxation and congestion charging.
Hybrid systems are consolidating manufacturing scale. Battery-electric platforms are capturing capital allocation.
Transmission:
Automation divides markets by traffic density and driver licensing patterns, with manual retention correlating to emerging economy penetration.
- Manual:Synchronized gearboxes with clutch pedal control dominate Indian and Brazilian entry-level variants where labor cost arbitrage favors driver operation over hardware complexity, though urban congestion is accelerating automatic preference in São Paulo and Mexico City.
- Automatic:Torque-converter and automated manual configurations command premium positioning in North American and Chinese retail markets, with EPA Corporate Average Fuel Economy standards pushing multi-speed ratios for efficiency compliance.
- CVT:Continuously variable ratio systems optimize engine operating points for hybrid integration, finding application in Japanese and Southeast Asian markets where smoothness and fuel economy outweigh drivetrain character preferences.
- Dual-Clutch:Wet and dry clutch automated manuals deliver shift speed advantages for performance-oriented variants, though thermal management complexity and urban low-speed refinement challenges constrain deployment in price-sensitive segments.
Automatic transmissions hold retail preference. CVT architectures are displacing conventional automatics in efficiency-focused lineups.
End User:
Utilization intensity separates procurement economics, with fleet operators extracting higher annual mileage per unit than individual ownership models.
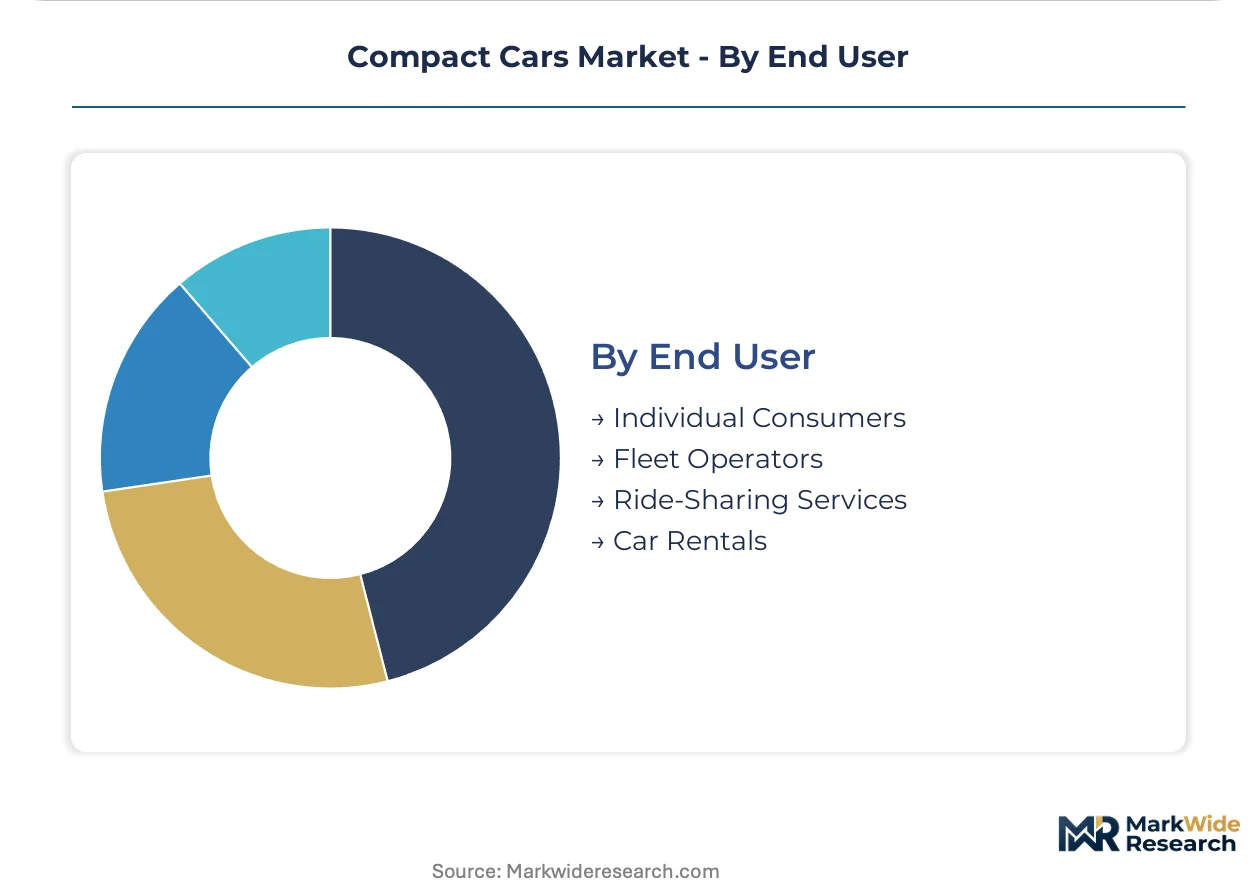
- Individual Consumers:Private purchasers prioritize initial acquisition cost, warranty coverage, and resale value stability, concentrating demand in established hatchback and sedan configurations with proven reliability records.
- Fleet Operators:Corporate and government procurement departments standardize specifications across vehicle pools, negotiating embedded maintenance contracts and extended service intervals that favor simplified powertrain architectures.
- Ride-Sharing Services:Urban mobility platforms in São Paulo and Mexico City are consolidating sourcing around compact hatchbacks with interchangeable components, pulling forward electrification timelines through regulatory mandate compliance.
- Car Rentals:Airport and urban short-term leasing operations demand rapid turnaround capability and broad appeal across unscreened drivers, favoring automatic transmission availability and damage-resistant interior materials.
Ride-sharing services are expanding procurement fastest. Individual consumers remain the volume anchor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compact car manufacturing originated in post-war Europe and Japan, where dense urban centers and fuel scarcity demanded efficient personal mobility solutions. These origins established engineering priorities—small footprints, lightweight construction, and cost minimization—that continue shaping regional market development today.
United States
EPA and NHTSA Corporate Average Fuel Economy standards are tightening fleet emission thresholds for Detroit Three compact lineups. The regulatory pressure redirects capital from internal combustion refinement toward hybrid and battery-electric variants. Michigan and Ohio assembly plants are retooling for electrified compact production as compliance deadlines approach.
Germany
Euro 7 emission standards are compressing engineering runways for internal combustion compacts across European assembly plants. Exhaust after-treatment and real-driving emissions monitoring requirements raise development costs. Volkswagen anchors volume through MQB-A0 architecture deployment from Wolfsburg and Zwickau facilities.
China
MIIT dual carbon goals are accelerating local OEM transitions from pure internal combustion to plug-in hybrid compact architectures. Battery-electric platforms with dedicated skateboard designs capture engineering investment priority. Yangtze River Delta manufacturing clusters around Shanghai lead ground-up electric compact development programs.
India
BIS Bharat NCAP crash-test protocols are normalizing higher-margin safety equipment packages across sub-four-meter sedan configurations. Maruti Suzuki and Hyundai dominate manufacturing scale in this taxation-optimized segment. Gujarat and Haryana assembly corridors concentrate capacity expansion for domestic and export markets.
Brazil
Urban fleet operators in São Paulo are consolidating procurement around standardized compact hatchback specifications for ride-sharing services. ANVISA automotive standards intersect with municipal zero-emission mandates to reshape fleet sourcing patterns. São Paulo-based operators are restructuring contracts toward embedded maintenance and extended service intervals.
Compact Cars Market Key Industry Players
The competitive structure tilts toward scale-driven volume manufacturers with dedicated compact platforms spanning multiple nameplates. Market concentration favors established OEMs with hybrid powertrain maturity and emerging economy distribution density. Two strategic archetypes dominate: dedicated hybrid platform specialists and modular architecture generalists. Competitive moves center on powertrain portfolio diversification and direct fleet supply agreements bypassing traditional dealer networks.
Among Asian volume manufacturers, Toyota, Hyundai, and Kia occupy positions reflecting divergent electrification strategies. Toyota exemplifies hybrid-first platform dedication through Corolla and Prius nameplates. Hyundai and Kia represent aggressive price-equipment positioning in emerging economy markets. Volkswagen anchors the European archetype with architecture standardization across multiple body styles. Chevrolet and Nissan sit within the North American volume tier responding to EPA compliance pressures. Mazda and Subaru occupy specialist positions emphasizing drivetrain character differentiation. Honda bridges archetypes with dual-market hybrid and internal combustion portfolios.
| Leading Market Players |
|---|
| Kia |
| Mazda |
| Honda |
| Subaru |
| Nissan |
| Toyota |
| Volkswagen |
| Chevrolet |
| Hyundai |
| Others |
Cost & Logistics Intelligence
Powertrain engineering talent concentration in Stuttgart and Wolfsburg drives labor-cost differentials that widen pricing-tier spreads between European premium compacts and mass-market variants sourced from lower-cost manufacturing corridors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified Euro 7-compliant variants from Bharat NCAP-optimized configurations and entry-level manual-transmission fleet specifications. Price differentiation centers on emission certification grade and safety equipment bundling. Pricing pressure stems from high-strength steel grade cost inflation eroding margins in entry-level tiers. Fleet operators in São Paulo exhibit highest price sensitivity, while individual consumers in developed Asian markets show lowest elasticity.
Supply Chain Analysis
Workforce availability in powertrain engineering and battery cell manufacturing concentrates supply chain decisions around Germany, China, and South Korea. Lithium-ion cell production draws from concentrated supplier bases in these geographies, with cathode active materials and semiconductor power modules as critical dependencies. Single-source vulnerability in battery cell allocation poses structural risk. Distribution runs through direct fleet supply agreements bypassing traditional dealer networks in Brazil and Mexico.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The compact car market operates as a geographic-arbitrage play where Euro 7 compliance costs in European assembly plants run three to four times higher than Bharat NCAP adaptation expenses in Indian manufacturing corridors.
For Market Incumbents: Anchor hybrid platform scale through dedicated compact architectures spanning multiple nameplates to deflect pure electric entrants. Defend against battery supply concentration risk by securing long-term cathode material offtake agreements. Prioritize vertical integration into power electronics manufacturing to protect margin position. For New Entrants and Emerging Players: Euro 7 emission standards in Germany and the broader European Union open a window for plug-in hybrid variants that bridge compliance requirements and consumer range anxiety. Target ride-sharing fleet procurement in São Paulo and Mexico City where standardization contracts favor new suppliers. Pursue direct fleet supply agreements with embedded maintenance contracts as the primary go-to-market angle. For Investors and Strategic Acquirers: Automotive Tier 1 suppliers with powertrain electrification capabilities are the most active acquirer in this space, consolidating battery management system and thermal management specialists. Long-term viability favors targets with established OEM qualification status and regional regulatory certification expertise. Monitor lithium carbonate price volatility as the inflection indicator for battery-electric platform economics.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-ion cell allocation from Korean or Chinese suppliers for compact electric variants. |
| Platform Standardization | Volkswagen's MQB-A0 architecture demonstrates multi-body-style manufacturing scale across Wolfsburg and Zwickau. |
| Software-Defined Vehicle Investment | Enables over-the-air emissions monitoring updates required under Euro 7 real-driving protocols. |
| Geographic Manufacturing Footprint | Toyota's hybrid platform deployment across multiple continents achieves cost parity at threshold volumes. |
| Charging Infrastructure Partnership | Supports fleet electrification mandates from São Paulo regulators for ride-sharing vehicle procurement. |
Research Approach
Multiple input streams — OEM platform engineering disclosures, Tier 1 supplier procurement patterns, and regulatory filing databases — were reconciled through structured primary interviews with powertrain development directors, fleet procurement managers, and automotive regulatory affairs leads. Secondary validation drew from EPA certification records, EU type-approval documentation, and MIIT production bulletins. Bottom-up vehicle production estimates and top-down market sizing triangulated volume figures.
Historical registration data from IHS Markit and government motor vehicle departments were cross-referenced against panel input from OEM planning executives across the analysis window. Segmentation modeling incorporated vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs were derived from regression analysis of production trajectory and powertrain mix assumptions, with battery cost curves and steel price indices as key forecast inputs.
Revisions become necessary when Euro 7 implementation timelines shift, Bharat NCAP protocols expand to additional test categories, or lithium supply disruptions materialize. Forecasts reflect documented assumptions regarding regulatory stringency and commodity input stability. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
Russia Light Vehicle Market
Passenger Vehicles
South America Passenger Cars Market
Passenger Vehicles
Passenger Vehicle Market
Passenger Vehicles
Convertible Vehicles Market
Passenger Vehicles
Automotive Passenger Vehicle Sensor Market
Passenger Vehicles
Medium Cars Market
Passenger Vehicles
Asia Pacific Luxury Cars Market
Passenger Vehicles
India Automotive Market
Passenger Vehicles
Minivans Market
Passenger Vehicles
Ghana Automobile Market
Passenger Vehicles
Small Suvs Market
Passenger Vehicles
Three-Wheeler Vehicle Market
Passenger Vehicles
Automotive Luxury Vehicle Market
Passenger Vehicles
Limousines Market
Passenger Vehicles
North American Lightweight Car Market
Passenger Vehicles
Luxury Vehicles Market