
 Automotive and Off-Road Vehicle Hoses Market | 2026-2036
Automotive and Off-Road Vehicle Hoses Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive and Off-Road Vehicle Hoses Market Analytics
Buyer concentration among heavy equipment OEMs is pivoting as mining and construction fleet operators consolidate procurement under fewer national distributors. Parker Hannifin leverages its fluid power integration to control channel access for hydraulic hose assemblies in North American off-road markets. Continental AG anchors European demand through captive supply relationships with German commercial truck manufacturers. Gates Corporation differentiates via specialized elastomer compounding for coolant systems operating under sustained thermal stress.
Automotive and off-road vehicle hoses are reinforced tubular conduits manufactured from vulcanized rubber, silicone, or extruded thermoplastic compounds, typically engineered to withstand internal pressures exceeding 10 bar and continuous operating temperatures ranging from minus forty to plus one hundred fifty degrees Celsius. These components route fluids, gases, and vacuum signals between engine, braking, climate control, and hydraulic subsystems while resisting ozone degradation, chemical attack, and mechanical fatigue. Brake hoses and fuel hoses represent mature margin pools where specification intensity and certification barriers protect incumbent positions, while thermoplastic vacuum hoses represent the fastest-expanding material-application intersection as engine downsizing multiplies auxiliary system complexity. Silicone radiator hoses command premium positioning in performance and commercial segments where replacement cycles compress under thermal loading extremes.
EPA, NHTSA, and EU REACH frameworks collectively tighten permissible compound chemistries and permeation rates for fuel and coolant hoses, forcing reformulation investments that favor suppliers with in-house polymer laboratories. The EU F-Gas Regulation and parallel EPA Section 608 amendments extend these constraints to climate system hoses carrying low-global-warming-potential refrigerants. Stakeholders must monitor regulatory divergence between California Air Resources Board zero-emission mandates and federal standards, as this friction will determine which hose technologies achieve scale in the largest North American vehicle market.
Market Dynamics
EPA Tier 4 Final and Euro Stage V emissions mandates are compressing replacement cycles for heavy equipment fleets while forcing material upgrades from conventional rubber to silicone and thermoplastic compounds in high-temperature engine bays.
Growth Catalysts
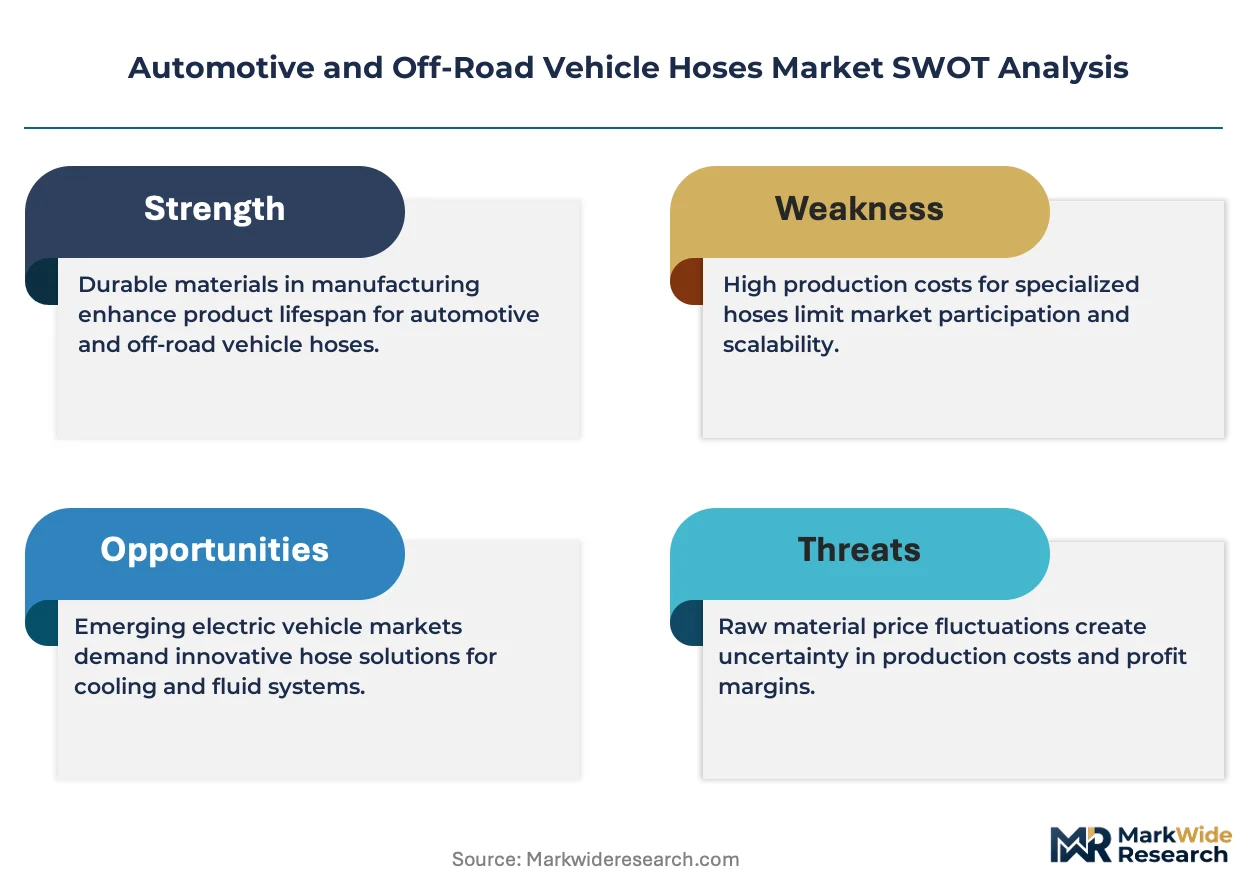
- Emissions Compliance Deadlines:EPA Tier 4 Final and Euro Stage V regulations are accelerating fleet modernization among mining and construction operators, creating synchronized demand spikes for coolant and fuel hose replacements.
- Material Substitution in Engine Bays:Silicone compounds are capturing share in radiator applications where sustained thermal loading above 150°C degrades conventional EPDM formulations.
- United States Production Clustering:Domestic supply concentration around Detroit and the Southeast is shortening lead times for North American heavy equipment OEMs.
Market Restraints
- Petrochemical Feedstock Volatility:EPDM and synthetic rubber compounds face margin pressure from propylene and ethylene price swings tied to crude oil fluctuations.
- Single-Source Concentration Risk:German and Chinese suppliers dominate high-performance aramid reinforcement fiber, creating vulnerability for North American hose manufacturers.
- REACH Chemical Restrictions:ECHA's evolving substance candidate list is forcing reformulation of plasticizers and curing agents, extending R&D timelines.
Strategic Opportunities
- Indian Commercial Vehicle Expansion:Bharat Stage VI implementation is creating demand for emission-compliant fuel and SCR hoses as domestic truck production scales.
- Low-GWP Refrigerant Transition:EU F-Gas Regulation and EPA Section 608 amendments are mandating barrier hose constructions for R-1234yf climate systems.
- Thermoplastic-Metal Hybrid Bonding:Laser-assisted joining of PEEK liners to stainless steel end fittings is opening weight-reduction pathways for electric vehicle thermal management.
Industry Challenges
- Compounder Chemist Shortage:Formulation expertise for fluoroelastomer and HNBR blends is concentrated among retiring specialists, constraining new product development.
- Synchronized OEM Validation Timelines:Heavy equipment manufacturers require 18-24 month qualification cycles for safety-critical brake and steering hoses, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive and Off-Road Vehicle Hoses Market |
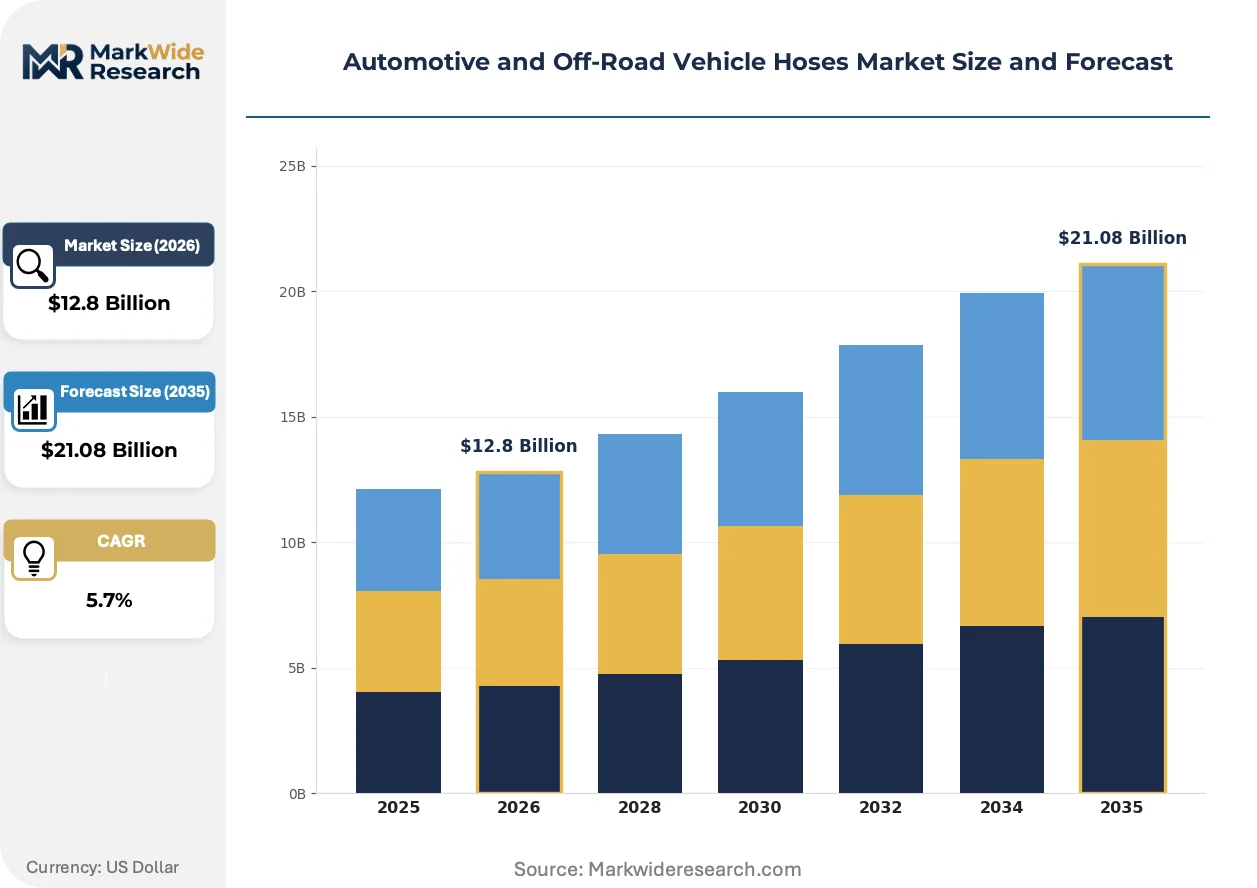
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiator Hoses, Fuel Hoses, Brake Hoses, Vacuum Hoses Material: Rubber, Silicone, Thermoplastic, PVC Application: Passenger Vehicles, Commercial Trucks, Heavy Equipment, Off-Road Vehicles End User: OEMs, Aftermarket Suppliers, Distributors, Vehicle Assemblers |
| Companies Covered | Manuli Hydraulics, Trelleborg, Parker Hannifin, Bridgestone, Continental AG, Gates Corporation, Alfagomma, Semperit, Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive and Off-Road Vehicle Hoses Market Evolving Landscape
Thermoplastic elastomers are absorbing functional roles once reserved for vulcanized rubber, while regulatory chemistry constraints and consolidated procurement models are restructuring how specifications propagate through supply tiers.
Multi-layer thermoplastic vacuum hoses are absorbing routing complexity from engine downsizing and auxiliary system proliferation. Tier 1 suppliers are specifying these constructions for turbocharger control circuits and evaporative emission systems. The technology is absorbing margin from conventional molded rubber assemblies by eliminating curing cycles and enabling color-coding for assembly-line error reduction.
REACH Annex XVII restrictions on phthalate plasticizers and EU F-Gas Regulation limits on refrigerant permeation are mandating barrier layer architectures. Hose manufacturers must validate co-extruded nylon or EVOH liners that add material cost but ensure compliance. Commercial vehicle climate systems face the steepest reformulation burden, with German OEMs leading specification changes that cascade to Tier 2 suppliers.
Fleet operators are consolidating hose procurement under national distributors with integrated inventory management. Mining and construction buyers in Australia and Canada are shifting from direct OEM parts purchasing to contracted maintenance providers who specify aftermarket brands. This channel compression rewards suppliers with diagnostic tooling and field service capabilities over catalog-only competitors.
Automotive and Off-Road Vehicle Hoses Market Segmentation
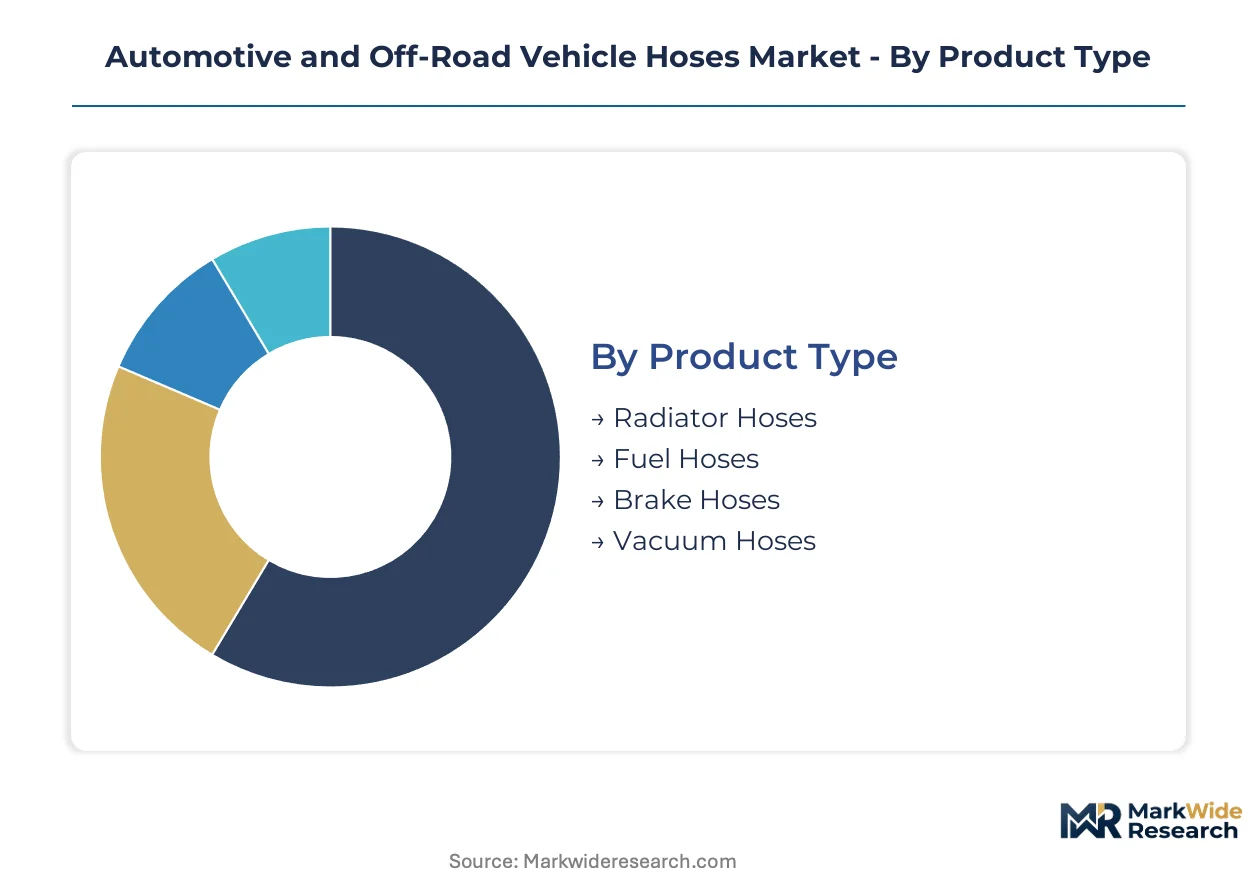
Segmentation in the Automotive and Off-Road Vehicle Hoses Market exposes divergent capital requirements and margin structures across product architectures. Material selection and application intensity create distinct investment profiles that separate commodity volume plays from specification-intensive premium positions.
Product Type:
Capital intensity peaks in safety-critical segments where certification infrastructure and testing protocols demand dedicated facilities.
- Brake Hoses:Steel-reinforced elastomeric assemblies engineered to DOT FMVSS 106 and SAE J1401 burst-pressure specifications. Demand concentrates in North American commercial truck OEMs as NHTSA enforcement tightens. Synchronized OEM validation timelines extending 18-24 months protect incumbent positions.
- Radiator Hoses:Multi-layer EPDM or silicone constructions routing coolant between engine blocks, heaters, and radiators. Heavy equipment fleets in mining and construction drive replacement volume under EPA Tier 4 Final thermal loading. Fleet consolidation under national distributors is compressing margin capture.
- Fuel Hoses:Barrier-layer constructions containing aromatic hydrocarbon permeation under EPA and CARB evaporative emission limits.
- Vacuum Hoses:Thin-wall thermoplastic tubing for turbocharger control and evaporative emission circuits.
Most installed capacity flows through Radiator Hoses. Expansion is steepest in Vacuum Hoses.
Material:
Reformulation investment intensity separates in-house polymer laboratories from toll-compounding dependencies.
- Silicone:Platinum-cured VMQ compounds sustaining continuous operation above 150°C in performance and commercial engine bays. German commercial truck manufacturers specify silicone for extended service intervals. REACH Annex XVII restrictions on conventional plasticizers accelerate substitution.
- Thermoplastic:TPV and TPE alloys enabling color-coded assembly-line routing without vulcanization cycles. Passenger vehicle OEMs in the United States specify these for turbocharger control circuits. Engine downsizing multiplies auxiliary system complexity.
- Rubber:EPDM and NBR formulations dominating mature coolant and fuel applications.
- PVC:Cost-positioned compounds for non-critical vacuum and drainage functions.
Volume leadership sits with Rubber. The steepest expansion trajectory belongs to Thermoplastic.
Application:
Specification intensity scales with vehicle mass and duty cycle severity.
- Heavy Equipment:Large-bore hydraulic and coolant hoses for mining excavators, construction dozers, and agricultural combines. Australian and Canadian fleet operators consolidate procurement under contracted maintenance providers. Bharat Stage VI implementation in India creates parallel demand for emission-compliant SCR hoses.
- Commercial Trucks:Bundled hose assemblies for powertrain, braking, and climate systems. German OEMs lead specification changes that cascade to Tier 2 suppliers. EU F-Gas Regulation mandates barrier constructions for R-1234yf refrigerant circuits.
- Passenger Vehicles:High-volume, standardized specifications for engine bay and climate routing.
- Off-Road Vehicles:Recreational and utility segment with seasonal demand patterns.
Revenue concentration favors Commercial Trucks. Gaining share fastest is Heavy Equipment.
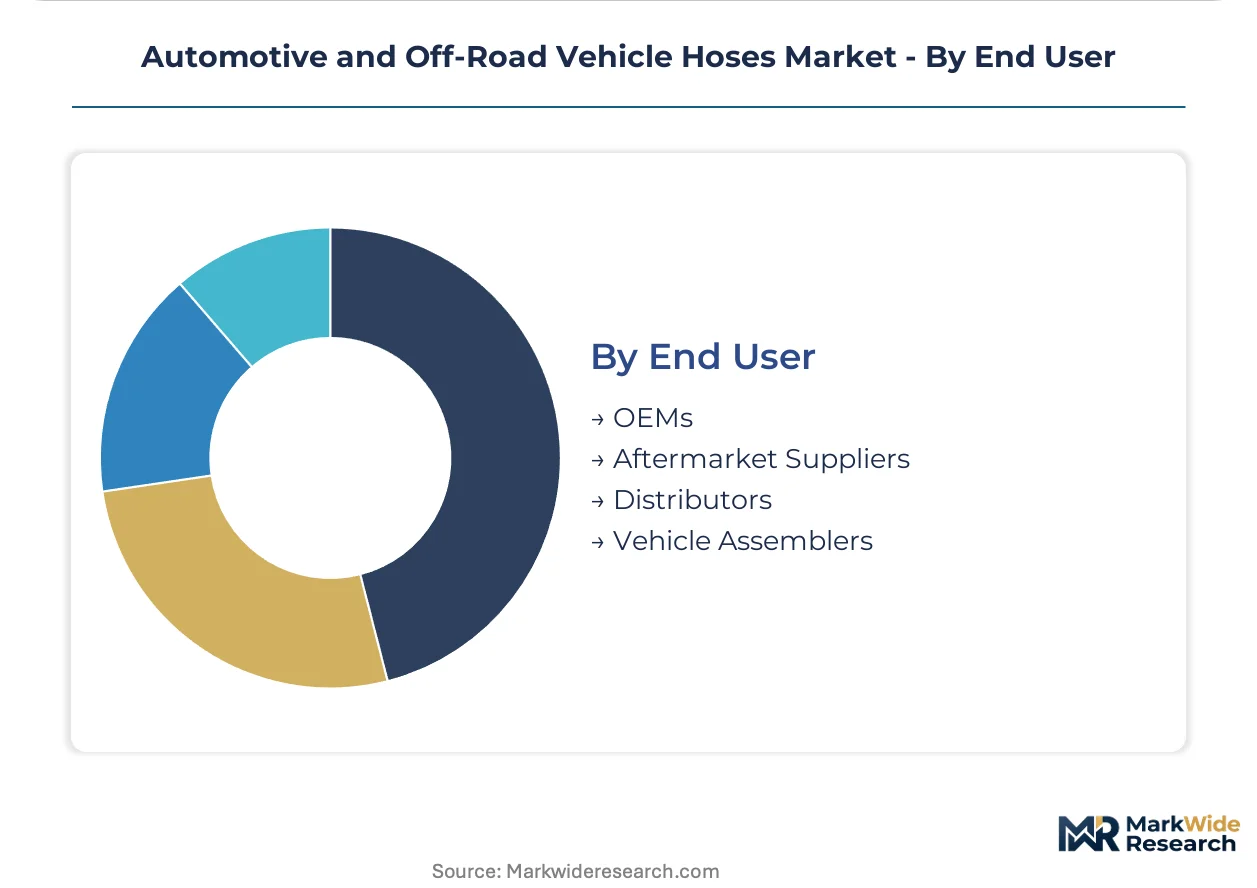
End User:
Channel access determines margin capture more than manufacturing scale.
- OEMs:Captive supply relationships with multi-year program commitments and integrated design collaboration. Parker Hannifin leverages fluid power integration to control hydraulic hose assembly access. Synchronized validation timelines delay revenue recognition.
- Aftermarket Suppliers:Independent brands competing on availability and field service capabilities. Mining and construction buyers shift from direct OEM parts purchasing to contracted maintenance providers. Diagnostic tooling and inventory management separate winners.
- Distributors:National inventory consolidators with integrated logistics networks.
- Vehicle Assemblers:Contract manufacturers with limited specification authority.
Procurement volume concentrates in OEMs. Channel compression is accelerating fastest in Aftermarket Suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates specification authority for commercial vehicle climate systems, while the United States anchors heavy equipment demand through fleet modernization mandates. China scales thermoplastic production for passenger vehicle turbocharger circuits. India and Australia round out the analysis as emerging demand centers with distinct regulatory trajectories.
United States
Heavy equipment fleets in mining and construction drive synchronized replacement demand under EPA Tier 4 Final thermal loading requirements. NHTSA enforces DOT FMVSS 106 burst-pressure specifications for safety-critical brake hose assemblies. Production clusters around Detroit and the Southeast shorten lead times for domestic OEMs while consolidating procurement under national distributors with integrated inventory management.
Germany
German commercial truck manufacturers specify silicone radiator compounds for extended service intervals in high-temperature engine bays. EU F-Gas Regulation mandates barrier-layer constructions for R-1234yf refrigerant circuits in climate systems. The Baden-Württemberg and Bavaria industrial corridors anchor captive supply relationships that cascade specification changes to Tier 2 suppliers across Central Europe.
China
Passenger vehicle OEMs specify thermoplastic elastomers for turbocharger control circuits as engine downsizing multiplies auxiliary system complexity. MIIT oversees GB standards compliance for domestic automotive component manufacturing. The Yangtze River Delta and Pearl River Delta production basins concentrate extrusion capacity for color-coded vacuum hose assemblies serving assembly-line error reduction protocols.
India
Bharat Stage VI implementation creates demand for emission-compliant fuel and SCR hoses as domestic truck production scales. The Central Pollution Control Board enforces particulate matter and nitrogen oxide limits that compress replacement cycles for commercial vehicle fleets. Manufacturing concentrates in Maharashtra and Gujarat where Tier 1 suppliers localize barrier-layer fuel hose production for Maruti Suzuki and Tata Motors programs.
Australia
Mining fleet operators consolidate procurement under contracted maintenance providers who specify aftermarket brands over direct OEM parts purchasing. The country's national environmental regulator oversees diesel particulate emission standards for off-road equipment in Western Australia and Queensland extraction zones. Perth and Brisbane anchor distribution networks with diagnostic tooling capabilities that separate winners from catalog-only competitors in the aftermarket channel.
Automotive and Off-Road Vehicle Hoses Market Competitive Landscape
United States producers anchor one tier; German and Japanese specialists hold specification-intensive positions in commercial vehicle and industrial hydraulics. The vendor base splits between diversified industrial conglomerates with captive polymer laboratories and focused hose fabricators dependent on toll-compounding relationships. Three archetypes dominate: fluid power integrators controlling channel access, elastomer compounders with in-house formulation expertise, and thermoplastic specialists capturing passenger vehicle auxiliary system growth. Competitive moves concentrate on backward integration into aramid reinforcement fiber sourcing and strategic partnerships with heavy equipment OEMs for 18-24 month validation programs.
Among diversified industrial conglomerates, Parker Hannifin Corporation, Continental AG, and Gates Corporation exemplify distinct strategic positioning archetypes. Parker Hannifin leverages fluid power integration to control hydraulic hose assembly access in North American off-road markets. Continental AG anchors European demand through captive supply relationships with German commercial vehicle manufacturers. Gates Corporation occupies a position differentiated via specialized elastomer compounding expertise for thermal management applications. These three entities represent the spectrum from systems integration to materials science specialization that defines competitive differentiation in specification-intensive segments.
| Leading Market Players |
|---|
| Manuli Hydraulics |
| Trelleborg |
| Parker Hannifin |
| Bridgestone |
| Continental AG |
| Gates Corporation |
| Alfagomma |
| Semperit |
| Eaton |
| Others |
Value Network & Pricing Analysis
Propylene price indices on the Gulf Coast cascade through EPDM compounder margins into three-tier pricing structures across premium silicone, standard rubber, and economy PVC hose tiers. Heavy equipment OEMs with 18-24 month validation cycles capture cost pass-through protections unavailable to aftermarket distributors facing spot-market volatility.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for thermoplastic vacuum hose assemblies serving turbocharger circuits. Three-tier pricing structure across premium silicone, standard rubber, and economy PVC levels differentiates by certification grade and thermal performance tier. Cost compression in standard rubber grades intensifies because propylene feedstock volatility outpaces compounder hedging capacity. Fleet operators consolidating under national distributors exhibit highest price sensitivity; German commercial truck OEMs with captive supply agreements show lowest.
Supply Chain Analysis
Core exchange programs for mining excavator hydraulic assemblies are extending hose life cycles through remanufactured fittings and reclaimed aramid reinforcement. Manufacturing concentrates in the United States, Germany, and China, with extrusion capacity clustering around Detroit, Stuttgart, and Shanghai. Raw material supply draws from Saudi ethylene crackers, German aramid fiber producers, and Japanese fluoroelastomer compounders. Single-source vulnerability in high-performance aramid reinforcement threatens North American fabricators. Distribution runs through national distributors with integrated inventory management for heavy equipment fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as EPA Tier 4 Final and Euro Stage V thermal loading mandates shift procurement toward premium silicone formulations with extended service intervals.
For Market Incumbents: Anticipate margin compression from thermoplastic substitution in passenger vehicle auxiliary circuits by accelerating backward integration into aramid reinforcement fiber sourcing. Defend specification control through 18-24 month OEM validation program partnerships that lock out toll-compounding dependent competitors. Prioritize captive polymer laboratory investments to meet REACH Annex XVII plasticizer reformulation timelines. For New Entrants and Emerging Players: Launch via contracted maintenance provider networks serving Australian and Canadian mining fleets shifting from direct OEM parts purchasing. Target thermoplastic vacuum hose white space in Indian commercial vehicle production scaling under Bharat Stage VI. Penetrate through diagnostic tooling bundling that separates winners from catalog-only competitors in aftermarket channel compression. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap elastomer compounders possessing in-house formulation expertise for HNBR and fluoroelastomer blends. Five-to-ten year viability hinges on regulatory chemistry constraint adaptation rather than volume scale. Monitor ECHA substance candidate list expansions as inflection indicators for reformulation investment intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aramid Fiber | Reduces single-source dependency on German and Chinese reinforcement suppliers for North American fabricators. |
| Platinum-Cured Silicone Capacity Expansion | Captures premium positioning as German commercial truck OEMs specify extended service interval compounds. |
| Thermoplastic-Metal Hybrid Bonding Investment | Opens weight-reduction pathways for electric vehicle thermal management through laser-assisted PEEK joining. |
| REACH-Compliant Plasticizer Reformulation | Preserves European market access as ECHA restrictions eliminate conventional phthalate curing agents. |
| Diagnostic Tooling Platform Development | Separates winners from catalog-only competitors as mining fleets consolidate procurement under maintenance providers. |
Research Methodology
Direct dialogue with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributor operations heads, and compounder R&D directors grounded qualitative findings in operational reality. Secondary validation drew from EPA enforcement databases, NHTSA FMVSS 106 certification records, ECHA substance candidate list updates, and vehicle production registries. Bottom-up segment modeling and top-down macroeconomic triangulation reconciled volume estimates across material, product, and application dimensions.
Bottom-up demand modeling aggregated content-per-vehicle assumptions by propulsion architecture and thermal management complexity, while top-down analysis anchored total market scale to heavy equipment fleet modernization cycles and commercial vehicle production trajectories. Segmentation across material type, product architecture, application intensity, and end-user channel captured divergence in capital requirements and margin structures. CAGRs derived from regression analysis of historical replacement cycle compression under emissions mandate thermal loading.
Forecast precision tightens around the base case; tail outcomes carry wider variance under propylene price spike scenarios or accelerated REACH chemical restrictions. Forecasts reflect documented assumptions regarding OEM validation timeline stability and fleet procurement consolidation velocity. Practitioners should monitor ECHA substance candidate list cadence and German commercial truck OEM specification changes for early signals of reformulation investment intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Off Road Vehicles
Off Road Motorcycles Market
Off Road Vehicles
Off-Highway Vehicle HVAC Market
Off Road Vehicles
Off-Highway Vehicle Market
Off Road Vehicles
Snowmobile Market
Off Road Vehicles
Global Off-Road Trailers Market
Off Road Vehicles
Off-Highway Electric Vehicle Market
Off Road Vehicles
Off-Highway Engine Market
Off Road Vehicles
Off-Road Vehicle Market
Off Road Vehicles
Europe Off-Highway Vehicle HVAC Market
Off Road Vehicles
Amphibious ATV Market
Off Road Vehicles
Off Road All Terrain E-Scooter Market
Off Road Vehicles
Off-Road Equipment Market
Off Road Vehicles
Off Highway Hybrid Vehicles Market
Off Road Vehicles
Utility Terrain Vehicles (UTV) Market
Off Road Vehicles
Off-Highway Diesel Common Rail Injection System Market
Off Road Vehicles
Global Automotive Off Highway Engine Market