
 Automotive Ignition Box Market | 2026-2036
Automotive Ignition Box Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Ignition Box Market Analytics
ISO 26262 functional safety certification is bifurcating the supplier base into qualified tier-one electronics houses and legacy component makers. Robert Bosch leverages captive semiconductor fabrication to sustain module cost leadership across European OEM programs. Denso Corporation anchors Asian supply chains through integrated ignition coil-box assemblies. Continental AG competes on systems-level integration with engine control units.
An automotive ignition box is an electronic control module that manages spark timing, dwell, and energy delivery to ignition coils, typically operating at 12-14V input with microprocessor-driven timing resolution below one crankshaft degree. Its primary purpose is optimizing combustion efficiency while enabling diagnostic feedback to powertrain controllers. Digital product types now command the dominant margin pool as OEMs phase out mechanical distributors. Electronic technology variants lead volume shipment while smart ignition systems with cylinder-pressure feedback represent the fastest-expanding segment. Aftermarket vendors occupy a mature, price-sensitive channel distinct from OEM-directed module supply.
NHTSA safety standards, EPA emissions certification, and Euro 7 protocols collectively mandate onboard diagnostics and precise misfire detection that only advanced ignition boxes deliver. These regulations elevate hardware complexity and exclude non-compliant suppliers from platform bids. Stakeholders must weigh R&D allocation between incremental combustion optimization and full electrification transition strategies.
Market Dynamics
EPA tailpipe standards and Euro 7 emissions protocols are forcing ignition module suppliers to deliver crankshaft-degree timing precision, compressing development cycles and elevating certification barriers for tier-two electronics houses.
Growth Catalysts
- EPA Tier 3 Standards:US passenger vehicle OEMs now require onboard misfire detection that only microprocessor-driven ignition boxes deliver, expanding module complexity per vehicle.
- China ICE Optimization:Domestic automakers in Shanghai and Guangzhou are extending internal combustion engine production timelines, sustaining procurement of advanced ignition management systems.
- Cylinder-Pressure Feedback Integration:Smart ignition systems with real-time combustion chamber sensing enable closed-loop spark timing, creating premium module demand.
Market Restraints
- Silicon Wafer Cost Volatility:Foundry capacity constraints for automotive-grade microcontrollers inflate BOM costs, pressuring margin structures at non-captive suppliers.
- Powertrain Electrification Trajectory:Battery-electric vehicle platforms eliminate spark ignition entirely, capping long-term addressable volume for dedicated ignition box manufacturers.
- ISO 26262 Certification Burden:ASIL-D functional safety compliance requires 18-24 month validation cycles, excluding capital-constrained suppliers from OEM platform bids.
Strategic Opportunities
- India Commercial Vehicle Retrofit:BS-VI compliance deadlines for heavy-duty fleets create aftermarket demand for electronic ignition conversions in Delhi-Mumbai corridors.
- Hybrid Powertrain Convergence:Plug-in hybrid architectures require sophisticated spark management during mode transitions, opening specialized module categories.
- Over-the-Air Calibration Channels:Cloud-based spark map updates enable recurring revenue models, shifting value capture from hardware shipment to software-enabled service tiers.
Industry Challenges
- Embedded Software Talent Scarcity:Functional safety firmware development for ASIL-rated ignition control requires specialized automotive electronics engineers concentrated in Stuttgart, Detroit, and Nagoya.
- Legacy ECU Integration Friction:Backward compatibility with 1990s-era engine management protocols complicates module architecture, extending validation timelines for multi-generational vehicle platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Ignition Box Market |
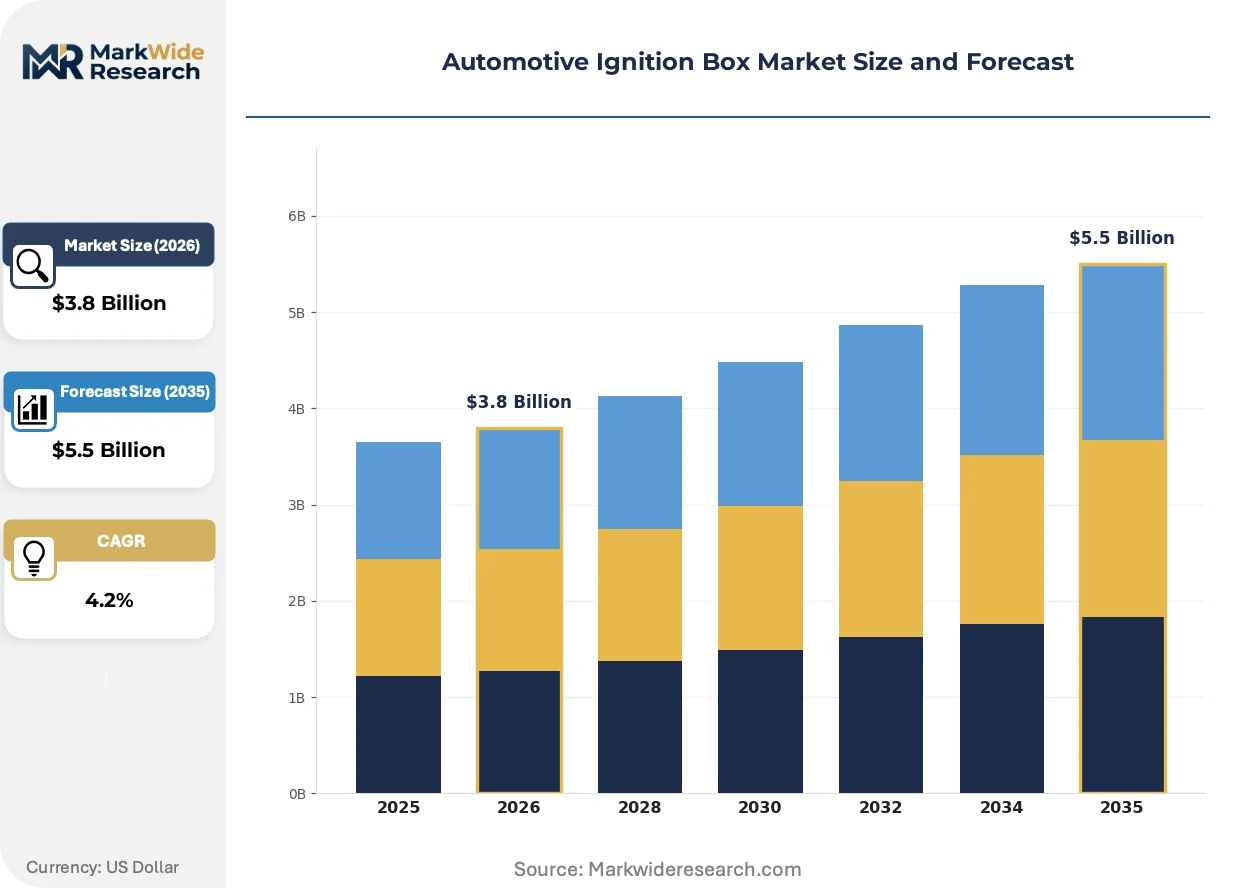
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional, Digital, Performance, Racing End User: OEMs, Aftermarket Vendors, Vehicle Assemblers, Distributors Technology: Electronic, Smart, Hybrid, Ignition Coil Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, All-Terrain Vehicles |
| Companies Covered | Robert Bosch, Denso Corporation, BorgWarner, Delphi Technologies, NGK Spark Plug, Hitachi Automotive Systems, Mitsubishi Electric, Diamond Electric, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Ignition Box Market Evolving Landscape
Digital ignition architectures are decomposing the traditional distributor-amplifier-coil signal chain, compressing component counts while elevating software-defined control authority over combustion events.
Smart ignition systems with integrated cylinder-pressure sensing is decomposing the conventional open-loop spark timing paradigm. Tier-one suppliers in Germany and Japan are deploying piezoelectric transducers directly into spark plug housings for real-time knock detection and adaptive ignition advance. This sensor fusion is decomposing the historical separation between ignition hardware and engine control strategy, forcing module suppliers to deliver combustion analytics rather than simple timing pulses.
REACH substance restrictions and RoHS recast directives in Europe are phasing out lead-based solder and hexavalent chromium coatings from ignition module substrates. Component manufacturers in the Czech Republic and Hungary are transitioning to silver-sintered die-attach processes and tin-bismuth plating chemistries. The regulatory pressure is compressing supplier qualification windows, favoring vertically integrated electronics houses with in-house materials laboratories over outsourced assembly operations.
Fleet operators and commercial vehicle leasing companies are consolidating procurement authority for ignition system maintenance into centralized technical centers, bypassing traditional aftermarket distributors. Large logistics operators in the US Great Lakes region and Germany's Ruhr corridor now specify module brands directly, conditioning workshop compliance on diagnostic data transparency. This buyer concentration is compressing price realization for independent service channels while elevating contract terms for OEM-authorized module suppliers with telematics integration capabilities.
Automotive Ignition Box Market Segmentation
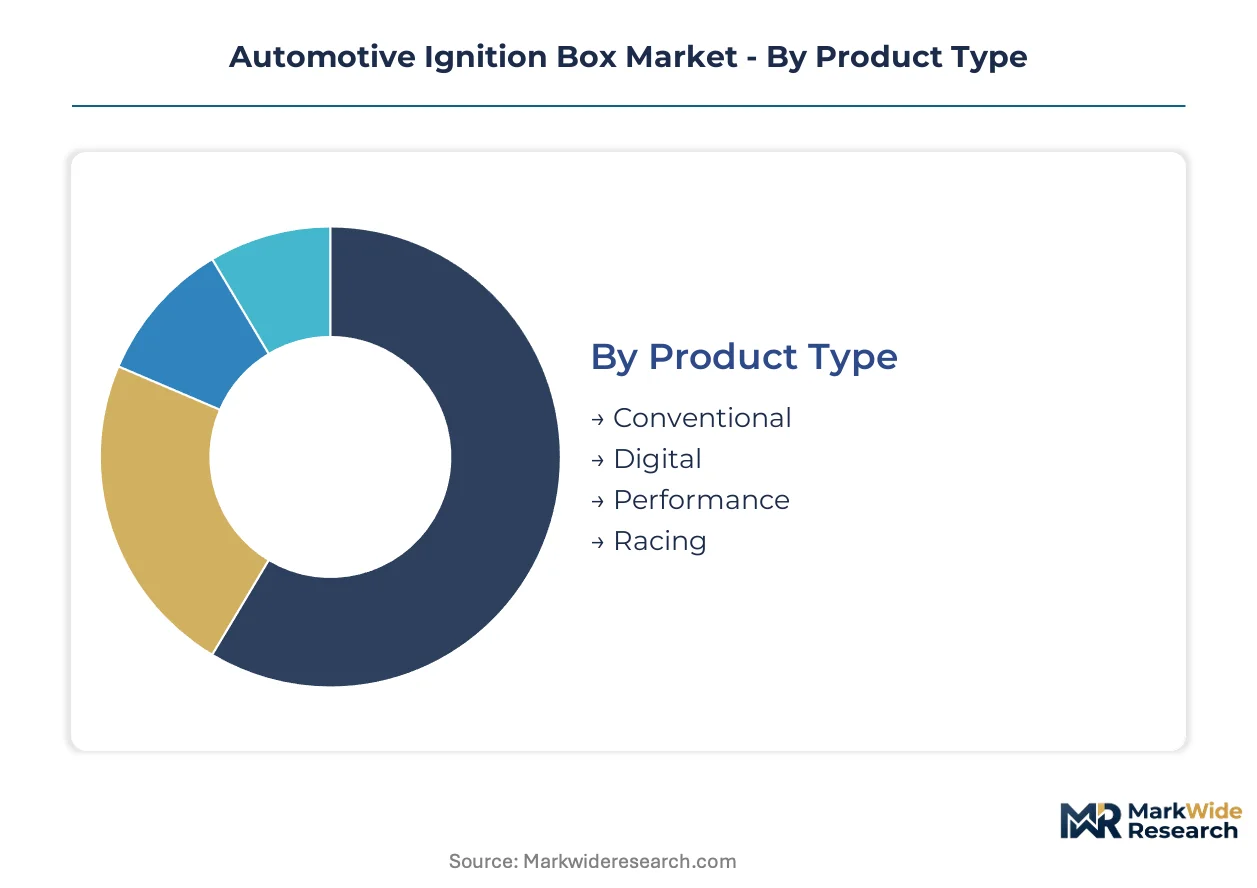
Ignition box procurement patterns diverge sharply between OEM platform integration and aftermarket replacement cycles, with technology tiers separating compliance-driven volume from performance-premium niches. Each segmentation axis reveals distinct margin structures, certification requirements, and supplier qualification barriers that shape competitive positioning across the value chain.
Product Type:
EPA Tier 3 and Euro 7 protocols have created a regulatory wedge between certified digital architectures and legacy conventional modules, with performance variants occupying a specialty tier governed by motorsport federations rather than road-vehicle regulators.
- Conventional:Mechanical distributor-based systems with fixed advance curves and breaker-point triggering persist in vintage vehicle restoration and developing-market commercial fleets where diagnostic mandates remain unenforced. Demand concentrates in India's heavy-duty retrofit segment and Latin American agricultural equipment where cost minimization overrides precision requirements.
- Digital:Microprocessor-controlled modules with crankshaft-degree timing resolution and onboard misfire detection now dominate OEM procurement for light-duty vehicles in Germany, China, and the United States. EPA and Euro 7 compliance deadlines are accelerating phase-out of analog alternatives across these markets.
- Performance:Programmable ignition controllers with user-definable spark maps serve enthusiast vehicle modifications and amateur motorsport categories. Demand clusters in California's aftermarket tuning corridor and Japan's domestic specialty vehicle scene.
- Racing:FIA-homologated systems with data logging and telemetry integration for professional motorsport series. FIA technical regulations and NHRA safety standards govern specification rather than road-vehicle emissions protocols.
Digital modules handle the majority of throughput; Racing systems are expanding most quickly on share as telemetry integration penetrates professional motorsport categories.
End User:
Customer concentration patterns split between consolidated OEM platform procurement with multi-year supply agreements and fragmented aftermarket channels where diagnostic capability determines vendor selection.
- OEMs:Vehicle manufacturers in Stuttgart, Detroit, and Nagoya specify ignition modules at the powertrain platform level, integrating suppliers into engine control unit architecture during pre-production phases. ISO 26262 ASIL-D certification and captive semiconductor supply chains determine competitive access.
- Aftermarket Vendors:Independent distributors and service chains procure replacement modules for vehicle parc maintenance, with price sensitivity highest in channels lacking diagnostic equipment. India's BS-VI retrofit deadlines and Brazil's Proconve P8 enforcement are redirecting some volume toward certified electronic conversions.
- Vehicle Assemblers:Contract manufacturers and regional assembly operations in Thailand, Mexico, and Eastern Europe source modules under OEM-directed supply arrangements with limited independent procurement authority.
- Distributors:National and regional parts wholesalers consolidate inventory for workshop networks, with fleet operator direct procurement in the US Great Lakes and Germany's Ruhr corridor compressing traditional distributor margins.
OEMs command the dominant procurement volume; Aftermarket Vendors are gaining share fastest as emerging-market emission deadlines force electronic conversion demand.
Technology:
Technology tiers separate basic timing pulse generation from closed-loop combustion control, with hybrid architectures bridging spark-ignition and electrified powertrain modes.
- Electronic:Transistorized switching circuits with dwell control and timing advance maps represent the baseline technology for mass-market light-duty vehicles. Cost-optimized variants from Chinese suppliers dominate domestic OEM programs while European and Japanese manufacturers emphasize functional safety integration.
- Smart:Cylinder-pressure feedback systems with piezoelectric sensors integrated into spark plug housings enable real-time knock detection and adaptive ignition advance. Tier-one suppliers in Germany and Japan are deploying these for premium passenger vehicle platforms where combustion efficiency maximization justifies module cost premiums.
- Hybrid:Dual-mode ignition controllers managing spark timing during internal combustion operation and coordinating shutdown sequences during electric mode transitions. Plug-in hybrid architectures from Shanghai and California OEMs are creating specialized demand for these transitional technologies.
- Ignition Coil:Coil-on-plug and coil-near-plug integrated assemblies combining switching electronics and inductive energy storage in single housings. Asian supply chains favor these for packaging efficiency in compact engine bays.
Electronic technology anchors current shipment volumes; Smart systems are climbing the fastest as cylinder-pressure sensing penetrates premium powertrain platforms.
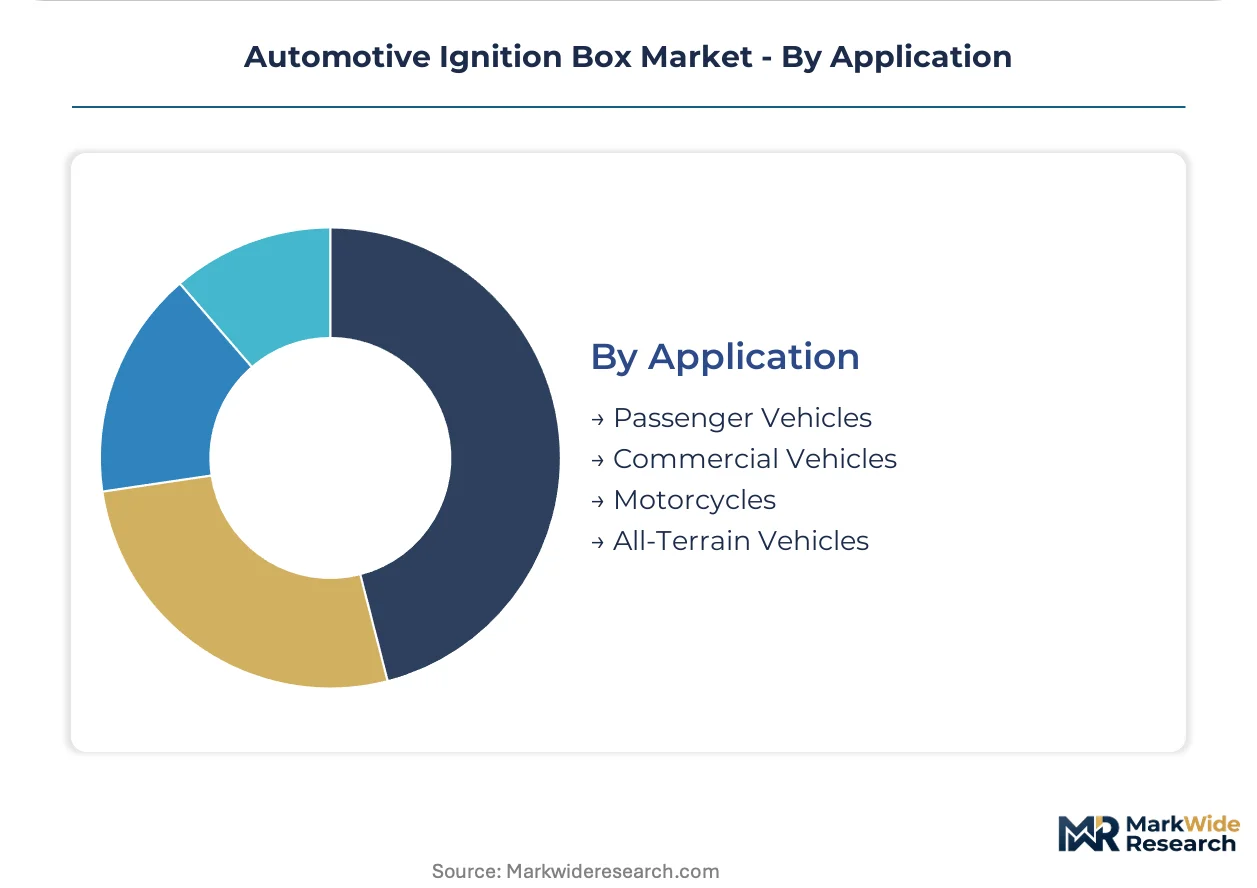
Application:
Application segmentation tracks powertrain duty cycles and regulatory exposure, with commercial vehicle emission enforcement creating retrofit demand distinct from new vehicle platform supply.
- Passenger Vehicles:Light-duty cars and SUVs with four to eight cylinder engines represent the core volume segment, with module specification tied to EPA Tier 3 and Euro 7 certification timelines. OEM integration depth is highest in German and Japanese premium segments where engine management system architecture is most sophisticated.
- Commercial Vehicles:Heavy-duty trucks and buses face accelerated emission compliance deadlines in India (BS-VI), China (China VI), and Brazil (Proconve P8), driving aftermarket electronic ignition conversions in Delhi-Mumbai and São Paulo freight corridors. Fleet operator procurement consolidation is reshaping supplier access.
- Motorcycles:Two and three-wheeler applications in Southeast Asia and India operate under distinct regulatory frameworks with cost-optimized electronic modules displacing magneto systems. India's OBD-II mandate for two-wheelers is accelerating technology transition.
- All-Terrain Vehicles:Recreational off-highway vehicles and utility task vehicles operate under less stringent emission protocols, with durability and moisture resistance specifications outweighing precision timing requirements. Demand concentrates in US Midwest manufacturing clusters and Japanese specialty vehicle exporters.
Passenger Vehicles absorb the dominant module volume; Commercial Vehicles are gaining share fastest as emerging-market fleet retrofit deadlines compress replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet procurement consolidation concentrates buyer power in Stuttgart, Detroit, and Nagoya, while emerging-market emission deadlines redirect aftermarket demand toward electronic conversion channels in Delhi-Mumbai and São Paulo freight corridors.
China
Domestic automakers in Shanghai and Guangzhou extend internal combustion engine production timelines, sustaining procurement of advanced ignition management systems. MIIT fuel consumption standards and China VI emission protocols mandate onboard diagnostics integration. Yangtze River Delta electronics clusters supply microprocessor-controlled modules to BYD and Geely powertrain platforms.
Germany
Premium OEMs in Stuttgart and Munich specify ignition modules at the powertrain platform level with ISO 26262 ASIL-D certification requirements. Euro 7 protocols tighten spark timing precision mandates. Bavarian and Baden-Württemberg engineering centers coordinate Continental AG and Robert Bosch module integration with engine control unit architecture.
United States
EPA Tier 3 standards require onboard misfire detection that only microprocessor-driven ignition boxes deliver. NHTSA safety standards elevate hardware complexity for platform bids. Detroit Three powertrain engineering and Great Lakes fleet operators consolidate procurement authority, conditioning workshop compliance on diagnostic data transparency.
India
BS-VI compliance deadlines for heavy-duty fleets create aftermarket demand for electronic ignition conversions. ARAI certification requirements accelerate technology transition for two-wheeler OBD-II mandates. Delhi-Mumbai and Chennai-Bengaluru freight corridors concentrate retrofit activity as fleet operators bypass traditional aftermarket distributors.
Japan
Denso Corporation and Hitachi Automotive Systems anchor Asian supply chains through integrated ignition coil-box assemblies. METI carbon neutrality roadmaps shape hybrid powertrain investment priorities. Nagoya and Tokyo-Yokohama engineering clusters specialize in cylinder-pressure feedback systems for premium passenger vehicle platforms.
Automotive Ignition Box Market Competitive Landscape
Player mix skews toward integrated tier-one electronics houses with captive semiconductor fabrication and functional safety certification capabilities. Market structure concentrates around three strategic archetypes: vertically integrated automotive suppliers with in-house microcontroller production, specialized ignition component manufacturers serving regional assembly operations, and diversified industrial electronics houses leveraging cross-sector safety certification. Dominant competitive moves include backward integration into automotive-grade semiconductor supply and strategic partnerships for cylinder-pressure sensing technology.
Within the tier-one integrated supplier tier, Robert Bosch, Denso Corporation, and Continental AG exemplify the archetype of electronics houses leveraging functional safety certification and systems-level integration to secure multi-year OEM platform agreements. Robert Bosch represents European-based fabrication with captive semiconductor supply chains. Denso Corporation anchors Asian market positioning through integrated assembly capabilities. Continental AG occupies a position emphasizing engine control unit coordination and combustion analytics rather than standalone module supply.
| Leading Market Players |
|---|
| Robert Bosch |
| Denso Corporation |
| BorgWarner |
| Delphi Technologies |
| NGK Spark Plug |
| Hitachi Automotive Systems |
| Mitsubishi Electric |
| Diamond Electric |
| Continental AG |
| Others |
Value Network & Pricing Analysis
ISO 26262 ASIL-D certification gates both supplier qualification and price stratification simultaneously, bifurcating the market between certified tier-one electronics houses commanding premium contract terms and legacy component makers relegated to price-sensitive aftermarket channels. This functional safety mandate compresses procurement options for OEMs while elevating margin capture for qualified suppliers with captive semiconductor fabrication.
Pricing Analysis
Long-term cost-plus contracts with silicon wafer indexation dominate OEM procurement, insulating Robert Bosch and Denso Corporation from spot market volatility while exposing non-captive suppliers to margin compression. Price differentiation separates ASIL-D certified modules from uncertified alternatives, with certification grade and volume scale as primary levers. Pricing pressure stems from foundry capacity constraints inflating microcontroller BOM costs. Aftermarket vendors exhibit highest price sensitivity, while premium OEM platform procurement tolerates cost premiums for systems-level integration.
Supply Chain Analysis
China and Germany anchor ignition module production, with Yangtze River Delta electronics clusters supplying domestic OEM programs and Bavarian engineering centers serving Stuttgart and Munich premium platforms. Raw material dependencies center on automotive-grade silicon wafers, rare-earth magnet alloys for ignition coils, and lead-free solder chemistries under REACH compliance. Single-source vulnerability concentrates in foundry capacity for ASIL-rated microcontrollers. Distribution runs through OEM-directed supply arrangements with limited independent procurement authority for regional assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive ignition box market tracks a cyclical recovery pattern as ICE optimization investments counterbalance electrification headwinds, with emission compliance deadlines in India and Brazil sustaining replacement demand through the mid-2020s.
For Market Incumbents: Compound defensive positioning through backward integration into automotive-grade semiconductor supply and ASIL-D certification depth. Battery-electric platform proliferation threatens long-term volume; prioritize hybrid powertrain module development and over-the-air calibration service tiers to capture recurring revenue.
For New Entrants and Emerging Players: Cloud-based spark map update services represent an under-served layer where incumbents under-serve independent aftermarket channels. Target India's BS-VI retrofit corridor with diagnostic-integrated electronic conversion kits. Pursue fleet operator direct procurement relationships bypassing traditional distributor networks.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive electronics specialists lacking ISO 26262 certification depth. Five-to-ten year viability hinges on hybrid powertrain transition duration rather than pure ICE preservation. Monitor cylinder-pressure feedback penetration rates in German and Japanese premium platforms as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Cylinder-Pressure Sensor Integration | Enables closed-loop combustion control for Euro 7 compliance in Stuttgart premium platforms. |
| Over-the-Air Calibration Capability | Shifts value capture from hardware shipment to software-enabled service tiers for fleet operators. |
| ASIL-D Certification Investment | Gates access to OEM platform bids from Detroit and Nagoya powertrain engineering centers. |
| Hybrid Powertrain Module Development | Addresses plug-in hybrid spark management during mode transitions for Shanghai OEMs. |
| Aftermarket Diagnostic Integration | Captures BS-VI retrofit demand in Delhi-Mumbai freight corridors bypassing distributors. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations; and secondary validation against vehicle production databases, IHS Markit registration data, EPA certification filings, and Euro 7 technical documentation. Bottom-up module shipment estimates triangulated with top-down powertrain production forecasts across vehicle class, propulsion architecture, and regional production cluster dimensions.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation by technology tier, end-user procurement channel, application duty cycle, and OEM integration depth. CAGRs derived from regression analysis of historical platform adoption curves and regulatory compliance timelines. Key inputs included MIIT fuel consumption standard trajectories, BS-VI enforcement schedules, and silicon wafer capacity expansion announcements from foundry operators.
Underlying assumptions cover ICE production timeline extensions in China and hybrid powertrain convergence rates, with deviation risk concentrated in battery-electric platform acceleration and foundry capacity allocation shifts toward automotive-grade microcontrollers. Recalibration cycles align with material shifts in emission protocol enforcement deadlines and semiconductor supply availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Europe and North Africa Automotive Window Regulator Market
Automotive Components
Global Automotive Plastic Compounding Market
Automotive Components
Automotive Mobile Accessories Market
Automotive Components
Polyamide in E-Mobility Market
Automotive Components
Automotive Spray Guns Market
Automotive Components
United States Automotive Pneumatic Actuators Market
Automotive Components
Automotive Stamped Component Market
Automotive Components
Global Automotive Noise Filter Market
Automotive Components
Automotive Metal Timing Chain Market
Automotive Components
Automotive Lightweighting Market
Automotive Components
Automotive Brake Pads Market
Automotive Components
North America Automotive Heat Shield Market
Automotive Components
Asia Pacific Automotive Actuators Market
Automotive Components
Sheet Molding Compound (SMC) for Automotive Market
Automotive Components
Global Automotive Water Valve Market
Automotive Components
Automotive Towbar Market