
 Train Seat Market | 2026-2036
Train Seat Market Size, Share, and Industry Trends Forecast 2026-2036
Train Seat Market Analysis
Leasing-based fleet procurement is reshaping competitive dynamics in rail seating, lowering capital barriers for mid-tier suppliers. Compin-Fainsa leverages its European manufacturing footprint to anchor premium contracts with state-owned rail operators. GRAMMER sustains R&D intensity in vibration-dampening seat structures for high-speed applications. Freedman Seating dominates the North American commuter retrofit segment through specialized lightweight designs.
A train seat is a structurally engineered passenger support system comprising metal frames, polyurethane foam cores, and textile or leather coverings, designed to withstand cyclic loading under dynamic rail conditions while meeting fire safety and ergonomic standards. Its primary purpose is to maximize passenger capacity per car length while minimizing fatigue over extended journeys. Recliner seats command margin pools in luxury and long-distance segments where rail operators compete with aviation comfort benchmarks. Upholstered materials lead volume across commuter and regional fleets, though leather variants are gaining share in premium intercity services where cleaning protocols and durability justify higher unit costs.
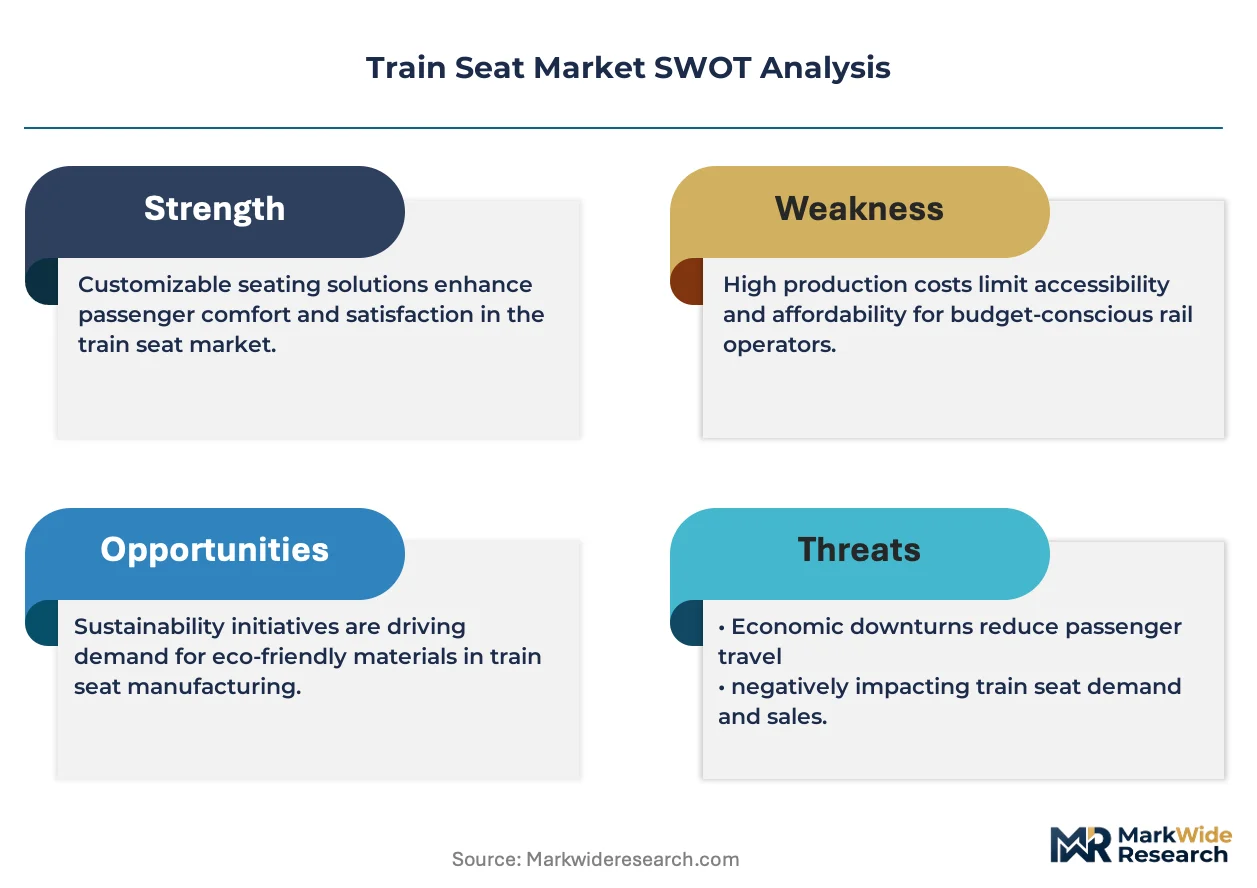
The US Federal Railroad Administration (FRA) mandates crashworthiness and fire-resistance standards that directly determine foam chemistry and frame design choices for seats entering domestic service. European ECHA enforcement of REACH restrictions on halogenated flame retardants is forcing reformulation of upholstery layers, while CE marking under the EU Rail System Directive governs interoperability compliance for cross-border rolling stock. Stakeholders must monitor how diverging transatlantic chemical regulations affect component sourcing flexibility and aftermarket replacement economics.
Market Dynamics
REACH-mandated flame-retardant reformulation is compressing foam chemistry options while fleet electrification programs in China and India are accelerating seat replacement cycles across high-speed and freight corridors.
Growth Catalysts
- High-speed rail expansion:China's CRRC and India's Dedicated Freight Corporation are placing multi-year fleet orders that prioritize ergonomic density optimization.
- REACH compliance deadlines:ECHA enforcement of halogenated flame-retardant restrictions is compelling upholstery layer reformulation, opening specification windows for compliant foam suppliers.
- Leasing-based procurement:Rolling stock lessors are lowering capital barriers for mid-tier seat manufacturers to access state-owned operator contracts.
Market Restraints
- Polyol feedstock volatility:Polyurethane foam cores face input cost pressure from propylene oxide supply concentration in Gulf Coast petrochemical clusters.
- Frame metallurgy constraints:High-strength aluminum extrusion capacity concentrates among European and East Asian mills, limiting geographic diversification.
- Aviation comfort benchmarking:Long-distance rail segments compete against airline flat-bed seating, compressing margin recovery on recliner mechanisms.
Strategic Opportunities
- Southeast Asia corridor development:Vietnam and Indonesia are initiating intercity rail modernization with limited incumbent supplier relationships.
- Modular seat platforms:Standardized frame architectures enabling rapid configuration swaps between commuter and regional service profiles.
- EU Green Deal procurement incentives:Carbon footprint disclosure requirements favor seat manufacturers with low-emission foam production and regional textile sourcing.
Industry Challenges
- Fire safety certification timelines:EN 45545-2 testing protocols for rail vehicle materials extend product validation cycles by 8-14 months.
- Vibration-dampening integration:High-speed applications require seat-structure isolation engineering that conflicts with weight reduction targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Train Seat Market |
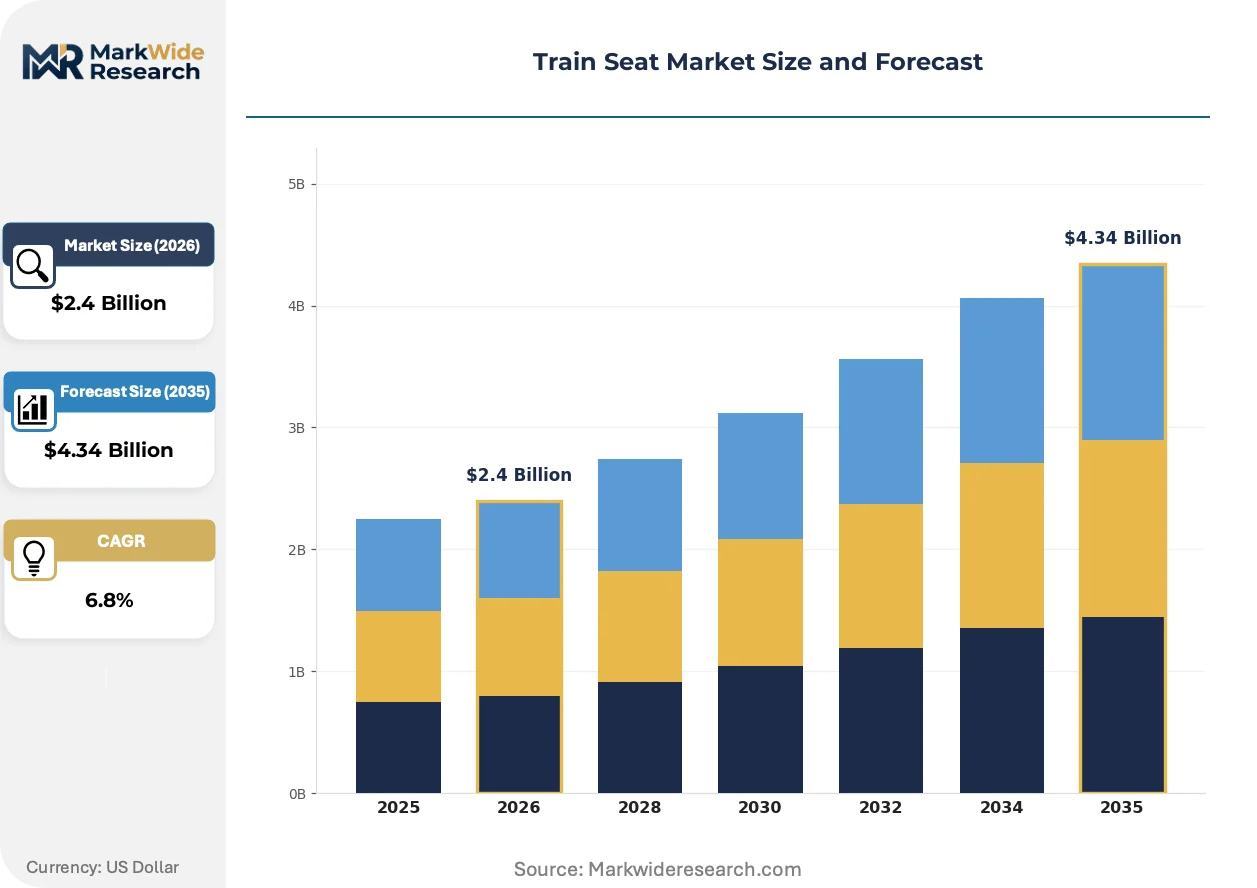
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
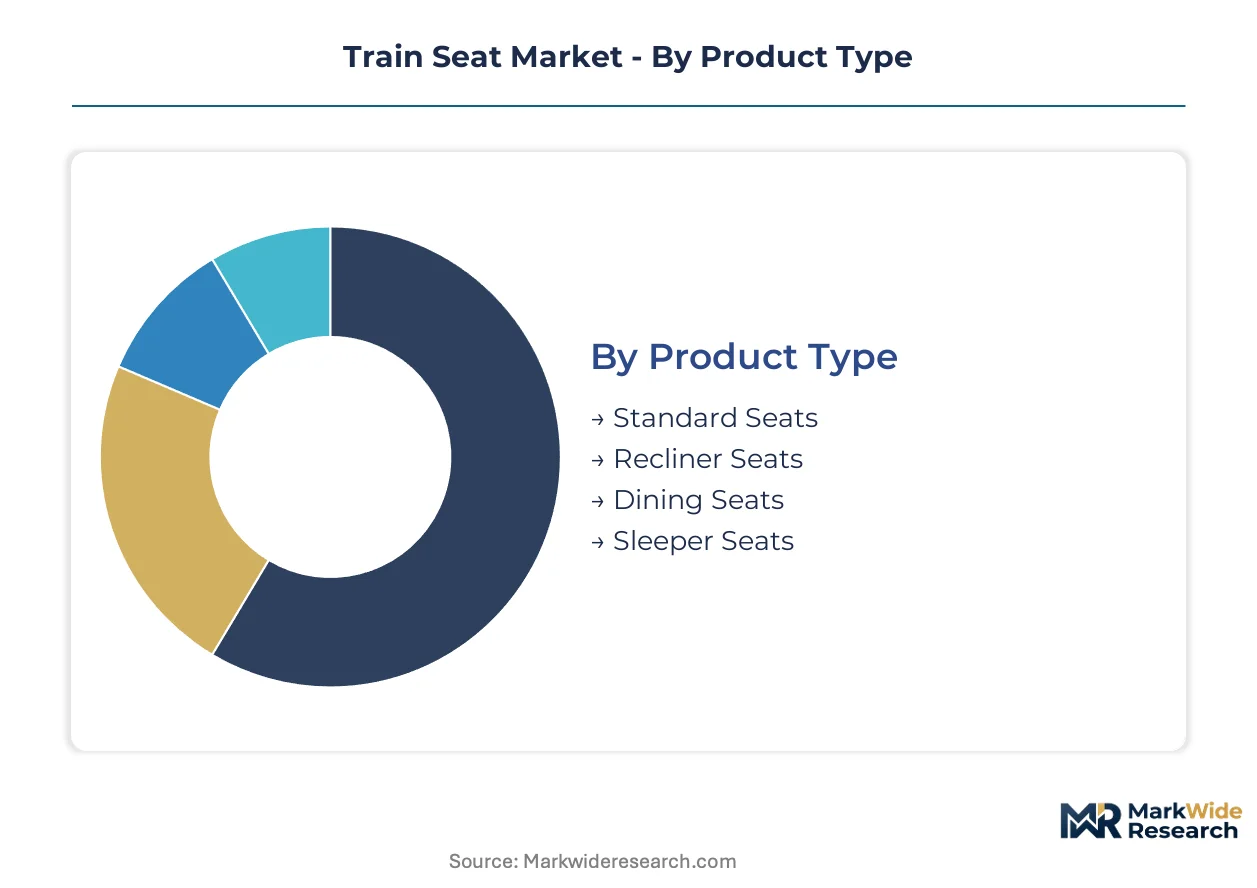
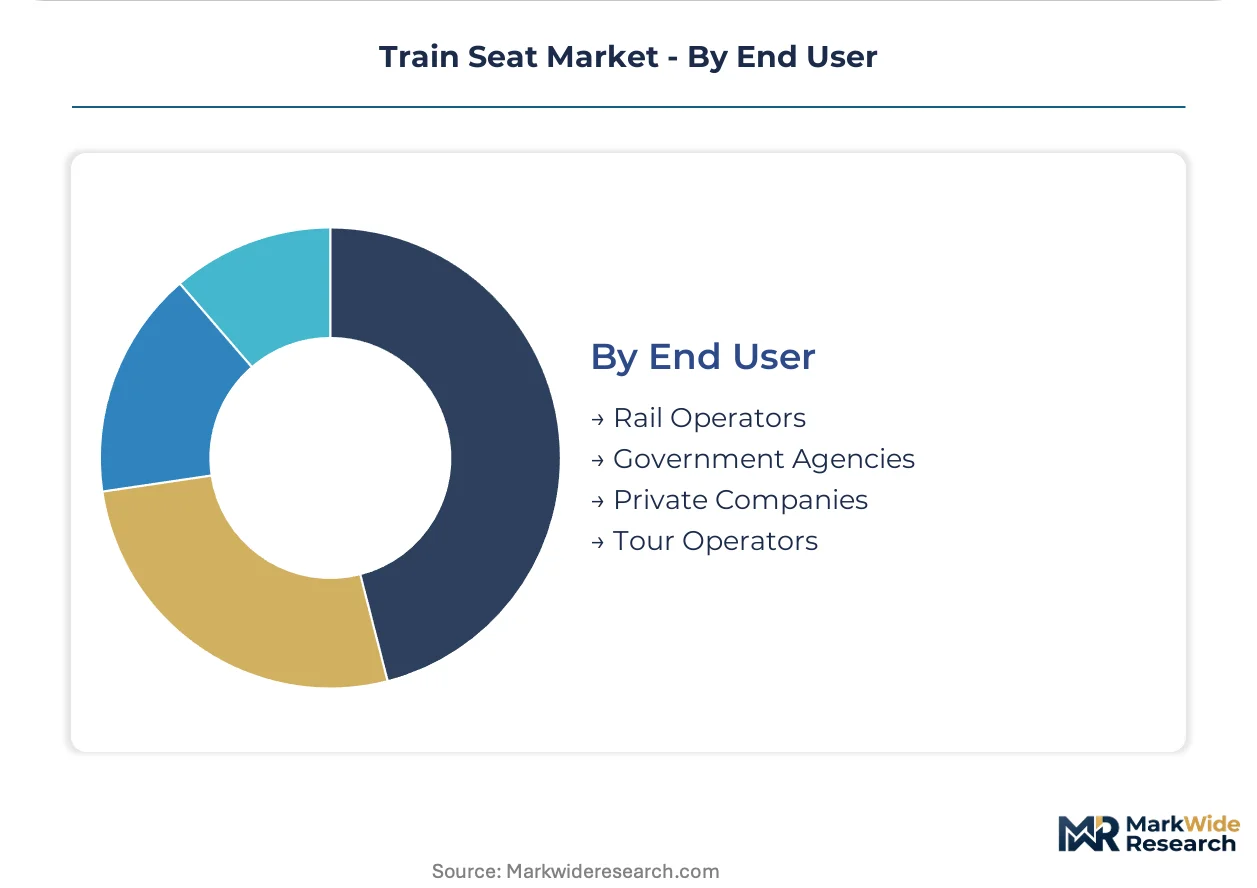
| Segmentation | Product Type: Standard Seats, Recliner Seats, Dining Seats, Sleeper Seats Material: Upholstered, Leather, Plastic, Metal Application: Passenger Trains, Freight Trains, Luxury Trains, Commuter Trains End User: Rail Operators, Government Agencies, Private Companies, Tour Operators |
| Companies Covered | Compin-Fainsa, Freedman Seating, GRAMMER, Saira Seats, Shanghai Tanda, Magna International, Kiel, Transcal, Seats Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Train Seat Market Emerging Trajectories
Seat architecture is converging around modularity mandates and fire-safety chemistry shifts, with procurement leverage migrating toward fleet lessors and away from direct operator specification.
Recycled-content polyurethane foam is collapsing virgin material demand in commuter fleet upholstery. Deutsche Bahn and SNCF are mandating minimum recycled polyol percentages in new tenders. This chemistry transition is compressing incumbent foam suppliers' petroleum-based product lines while creating specification advantages for vertically integrated chemical processors.
REACH Annex XVII restrictions on halogenated flame retardants are forcing upholstery layer redesigns across European rolling stock. Foam formulators must achieve EN 45545-2 HL3 ratings using phosphorus or nitrogen-based alternatives. Premium intercity segments absorb reformulation costs more readily than price-sensitive regional operators.
Rolling stock lessors are capturing specification authority previously held by national operators. Mitsui Rail Capital and Akiem now dictate seat platform standards across leased fleets. This buyer consolidation is most advanced in Western Europe, where cross-border interoperability requirements amplify lessor influence over component standardization.
Train Seat Market Segmentation
Seat replacement cycles vary dramatically across rail service types, with commuter fleets turning over every 7-10 years while luxury configurations persist for 15-20 years. Understanding these differential velocities shapes inventory positioning and R&D allocation for component suppliers.
Product Type:
Recliner mechanisms and sleeper berths command extended engineering cycles, while standard fixed seats rotate through procurement windows most frequently.
- Standard Seats:Fixed-back configurations with polyurethane foam cores and fire-retardant textile coverings dominate high-density commuter deployments. China's CRRC and India's Dedicated Freight Corporation specify these for maximum passenger throughput per car length, with EN 45545-2 compliance now mandatory for European tenders.
- Recliner Seats:Articulating backrest mechanisms with reinforced aluminum frames and enhanced cushioning layers address long-distance comfort benchmarks set by aviation competitors. Premium intercity operators in Germany and France absorb higher unit costs to capture business travelers from short-haul airlines.
- Dining Seats:Fixed-table companion seating with stain-resistant upholstery and compact footprints for meal service cars.
- Sleeper Seats:Convertible berth configurations with integrated restraint systems and enhanced fire barriers for overnight routes.
Standard seats dominate installed base across all geographies. Recliner seats are where expansion concentrates as high-speed rail extends journey lengths.
Material:
Cost structures stratify sharply between petroleum-derived synthetics and natural leather, with recycled-content mandates rewriting supplier qualification criteria.
- Upholstered:Woven textile or vinyl coverings over polyurethane foam cores, specified for 80% of commuter and regional fleet volumes. Deutsche Bahn and SNCF now mandate minimum recycled polyol percentages, compressing margins for virgin-material foam producers.
- Leather:Full-grain or corrected-grain hides with enhanced durability coatings for premium intercity and luxury segments. Cleaning protocol requirements and extended service life justify 3-4x unit cost premiums over upholstered alternatives in British and Italian premium services.
- Plastic:Injection-molded polypropylene shells for high-abuse environments and rapid replacement cycles.
- Metal:Bare or powder-coated steel frames for standing-area perch seating and minimal-cost deployments.
Upholstered materials anchor volume procurement. Leather variants are climbing the fastest as premium service differentiation intensifies.
Application:
Passenger density requirements and journey duration determine structural specifications, with freight applications introducing entirely different durability standards.
- Passenger Trains:Ergonomically optimized seating for intercity and regional services with fire safety and crashworthiness certifications. East Asian high-speed expansion programs prioritize vibration-dampening frame engineering for passenger comfort at 300+ km/h operations.
- Freight Trains:Minimal-occupancy crew seating with extreme durability specifications for irregular maintenance access. India's Dedicated Freight Corridor expansions specify heavy-duty configurations withstandng harsh environmental exposure.
- Luxury Trains:Custom-crafted interiors with artisan upholstery and extended recline ranges for tourism-oriented services.
- Commuter Trains:Maximum-density fixed seating with rapid-clean surfaces and 15-year replacement cycles for urban transit authorities.
Commuter trains dominate unit volume. Luxury trains are expanding most quickly as experiential tourism recovers.
End User:
Procurement authority is migrating from direct operator ownership toward lessor-mediated specifications, consolidating buyer influence.
- Rail Operators:State-owned and privatized train operating companies with direct fleet ownership, historically the primary specification authority. European incumbents like SNCF and Trenitalia retain design control on owned rolling stock.
- Government Agencies:National transport ministries and regional authorities funding infrastructure-led procurement. Vietnam and Indonesia are initiating modernization programs with limited incumbent supplier relationships, opening specification windows.
- Private Companies:Corporate shuttle services and industrial site railways with customized fleet requirements.
- Tour Operators:Curated rail experience providers commissioning bespoke carriage interiors for heritage and luxury routes.
Rail operators retain the largest installed base. Government agencies are where procurement expansion concentrates as state-funded corridor development accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal procurement incentives are redirecting specification authority toward carbon-disclosing suppliers across European rolling stock programs. China's CRRC-led fleet modernization and India's Dedicated Freight Corridor expansions concentrate capital deployment in Asia. Brazil and the United States anchor Americas demand through commuter rail rehabilitation and private intercity ventures.
China
CRRC Corporation dominates fleet orders for high-speed and intercity services, prioritizing ergonomic density optimization at 300+ km/h operations. MIIT enforces GB standards for rail vehicle fire safety and crashworthiness that shape foam chemistry and frame metallurgy choices. Manufacturing clusters in Changchun and Qingdao host vertically integrated seat production serving both domestic deployment and export markets across Southeast Asia.
Germany
Deutsche Bahn mandates minimum recycled polyol percentages in upholstery tenders, compressing margins for virgin-material foam suppliers. ECHA enforcement of REACH Annex XVII restrictions on halogenated flame retardants forces reformulation of seat cushioning layers. Industrial concentration in North Rhine-Westphalia and Bavaria supports premium intercity seat fabrication with phosphorus-based fire-retardant chemistry.
India
The Dedicated Freight Corporation specifies heavy-duty crew seating configurations for harsh environmental exposure across corridor expansions. BIS certification requirements for rail vehicle materials extend product validation timelines for imported components. Manufacturing activity clusters in Chennai and Pune as domestic fabrication capacity scales to meet localization targets under Make-in-India procurement rules.
United States
FRA crashworthiness and fire-resistance standards directly determine foam chemistry and aluminum frame design for domestic service entry. Commuter rail authorities in the Northeast Corridor and California prioritize lightweight retrofit seating for aging fleet rehabilitation. Private intercity ventures in Florida and Texas are commissioning premium recliner configurations to compete with short-haul aviation.
Brazil
ANVISA and national transport ministry regulations govern material safety for urban rail systems in São Paulo and Rio de Janeiro. State-funded commuter modernization programs specify rapid-replacement upholstered seating for high-abuse environments. Industrial fabricators in São Paulo state are expanding capacity to serve rolling stock lessors entering Latin American lease markets.
Train Seat Market Vendor Landscape
On the supply side, the industry is consolidating around three strategic tiers: European heritage manufacturers with established operator relationships, Asian scale producers serving domestic fleet programs, and North American specialists capturing retrofit and leasing contract flows. Archetypes include vertically integrated chemical processors controlling foam formulation, modular platform architects enabling rapid configuration swaps, and regional fabricators with captive maintenance networks. Competitive positioning hardens through backward integration into aluminum extrusion capacity and specification capture via rolling stock lessor partnerships.
Within the European heritage tier, Compin-Fainsa and GRAMMER occupy positions anchored by regional manufacturing footprints and state-owned operator relationships. Freedman Seating exemplifies the North American retrofit specialist archetype, serving commuter authorities and private operators with lightweight configuration expertise. Shanghai Tanda represents Asian scale production serving CRRC-led domestic demand and selective export deployment.
| Leading Market Players |
|---|
| Compin-Fainsa |
| Freedman Seating |
| GRAMMER |
| Saira Seats |
| Shanghai Tanda |
| Magna International |
| Kiel |
| Transcal |
| Seats Incorporated |
| Others |
Supply Flow & Price Mechanics
India's Dedicated Freight Corridor logistics cost dynamics compress margins for polyurethane foam suppliers while amplifying price differentiation between EN 45545-2 certified and uncertified seating tiers across the supply chain.
Pricing Analysis
Certification level (EN 45545-2 HL3 versus HL2) creates the primary spread between premium and standard seating tiers. Three-tier pricing structure across premium intercity, standard regional, and economy commuter levels dominates procurement frameworks. Cost compression in economy tiers is intensifying because recycled polyol mandates from Deutsche Bahn and SNCF squeeze virgin-material foam producers. Regional operators exhibit highest price sensitivity, while luxury intercity services absorb reformulation premiums for phosphorus-based fire-retardant chemistry.
Supply Chain Analysis
Polyol feedstock production draws from concentrated Gulf Coast petrochemical clusters in the United States, Germany's industrial chemical corridor, and China's propylene oxide manufacturing bases. Aluminum extrusion for seat frames rests on European and East Asian mill capacity, with textile weaving concentrated in China's Zhejiang province and India's Tamil Nadu. Single-source vulnerability in high-strength alloy supply creates exposure for frame fabricators. Distribution runs through rolling stock lessors like Mitsui Rail Capital and Akiem who now dictate specification standards across leased fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The train seat market functions as a defensive-moat industry where regulatory certification requirements create switching costs that entrench incumbent positions against new supplier qualification.
For Market Incumbents: Entrench position by deepening backward integration into aluminum extrusion capacity in Changchun or Qingdao manufacturing clusters. Capture specification authority through exclusive partnerships with Mitsui Rail Capital and Akiem as lessor influence consolidates. Invest in EN 45545-2 HL3 certification assets before REACH compliance deadlines tighten further, neutralizing emerging foam chemistry specialists. For New Entrants and Emerging Players: Establish a beachhead in Vietnam and Indonesia corridor development programs where incumbent supplier relationships remain underdeveloped. Target government agency procurement as state-funded rail modernization accelerates across Southeast Asia. Pursue modular seat platform architectures that enable rapid configuration swaps between commuter and regional profiles as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming rail seating divisions lacking lessor partnerships. Long-term viability centers on suppliers with captive foam formulation capabilities and established ECHA compliance track records. Watch for inflection when India's BIS certification timelines compress as domestic fabrication scales under Make-in-India localization mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Captive supply of high-strength alloys insulates margins from European and East Asian mill concentration. |
| REACH-Compliant Foam Chemistry Certification | EN 45545-2 HL3 qualification opens specification windows with Deutsche Bahn and SNCF tenders. |
| Modular Platform Architecture Development | Standardized frames enable rapid swaps between commuter and regional configurations for fleet lessors. |
| Recycled Polyol Production Scale-Up | Vertical integration into sustainable chemistry aligns with EU Green Deal procurement incentives. |
| Rolling Stock Lessor Partnership | Exclusive supply agreements with Mitsui Rail Capital and Akiem capture specification authority migration. |
Methodological Framework
Initial hypotheses were tested against primary input from rolling stock procurement managers, foam chemistry R&D directors, fleet lessor specification engineers, and rail operator maintenance heads, then refined through secondary validation. Primary fieldwork combined structured interviews with secondary analysis of customs trade data, SEC filings from diversified seating suppliers, ECHA REACH regulatory filings, and CRRC fleet order disclosures. Bottom-up seat unit demand modeling triangulated against top-down rail vehicle production forecasts.
Demand-supply balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions included product type (standard, recliner, sleeper), material composition (upholstered, leather, recycled-content), application (passenger, freight, luxury, commuter), and end-user procurement authority (operator direct, lessor-mediated, government agency). CAGRs derived from fitted growth curves applied to fleet replacement cycles and corridor expansion capital deployment schedules. Vibration-dampening engineering intensity and fire-safety chemistry transition timelines served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in petrochemical feedstock pricing, aluminum alloy availability, or state rail capital budgets would shift the trajectory. Forecasts reflect documented assumptions about REACH enforcement timelines and high-speed rail fleet deployment schedules. Cross-checking against CRRC and Alstom order book disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
India Luxury Car Market
Passenger Vehicles
Global SUV Market
Passenger Vehicles
Compact Cars Market
Passenger Vehicles
Train Market
Passenger Vehicles
Latin America Passenger Car Market
Passenger Vehicles
North American Lightweight Car Market
Passenger Vehicles
Quadricycle and Tricycle Market
Passenger Vehicles
Minivans Market
Passenger Vehicles
Microcars Market
Passenger Vehicles
Electric Sports Car Market
Passenger Vehicles
South America Passenger Cars Market
Passenger Vehicles
Lightweight Cars Market
Passenger Vehicles
Indonesia Passenger Car Market
Passenger Vehicles
Large Suvs Market
Passenger Vehicles
Limousines Market
Passenger Vehicles
Automotive Passenger Vehicle Sensor Market