
 South Africa Radiotherapy Market | 2026-2036
South Africa Radiotherapy Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Radiotherapy Market Insights
Image-guided radiation therapy is reconfiguring treatment planning workflows across South African cancer centers. Siemens Healthineers leverages its installed base of linear accelerators to sustain service revenue in Gauteng and Western Cape provinces. Elekta anchors proton therapy development through its regional partnerships with academic medical centers. Varian Medical Systems competes on software integration, positioning its radiation therapy planning systems for hospital network consolidation.
South Africa radiotherapy encompasses ionizing radiation delivery systems that generate megavoltage X-rays or electron beams through linear accelerator waveguides, with isocentric precision measured in sub-millimeter tolerances for tumor targeting while sparing healthy tissue. External beam radiation dominates current installations, though brachytherapy grows fastest as gynecological and prostate programs expand at dedicated cancer treatment centers. Linear accelerators represent the mature revenue base, while image-guided radiation therapy captures margin pools through adaptive planning software upgrades.
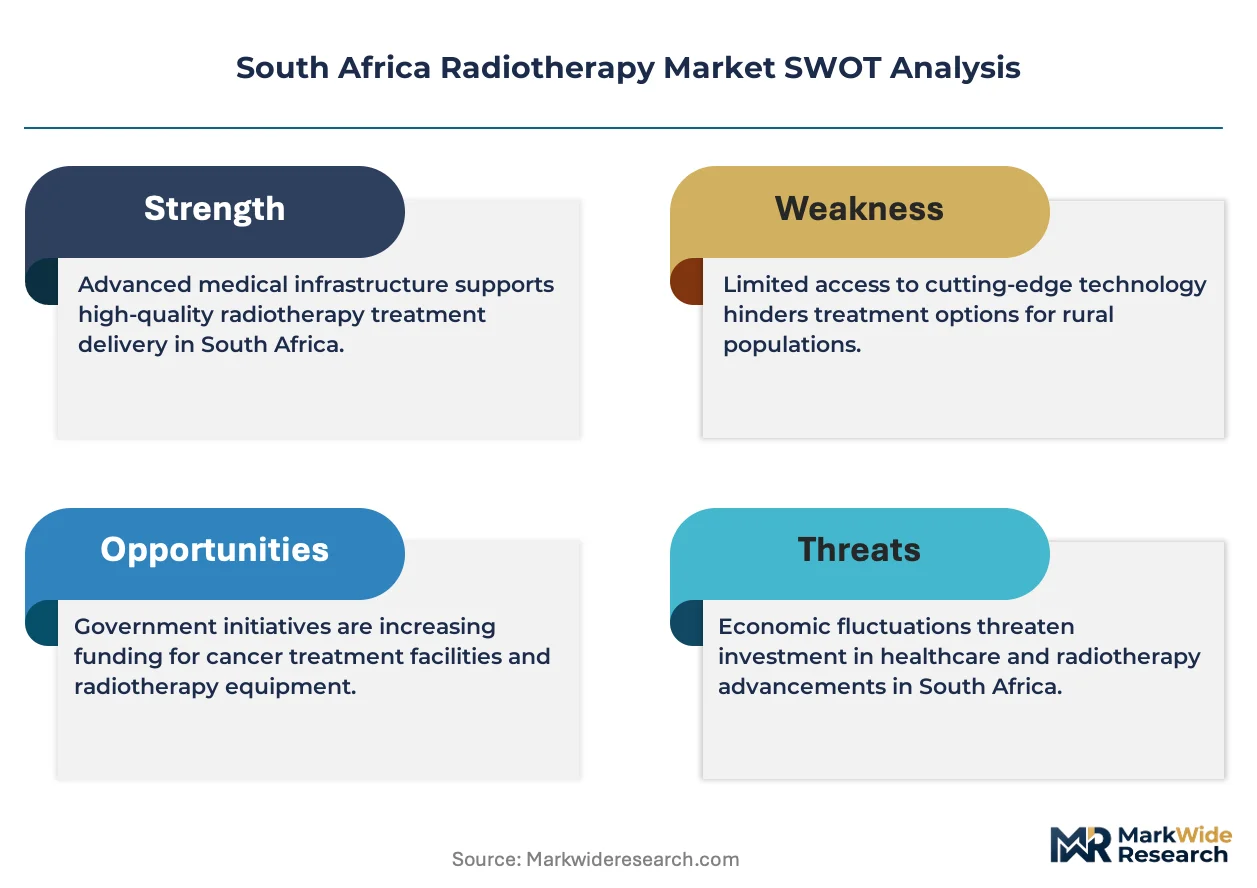
South Africa's National Department of Health and the South African Health Products Regulatory Authority shape equipment procurement through licensing requirements and cancer care pathway guidelines. The country's compliance with ISO 13485 for medical device quality management and IAEA safety standards for radiation protection influences vendor qualification and facility accreditation. Stakeholders must monitor public-sector tender cycles and private hospital group capital allocation priorities as these determine equipment refresh timelines and technology diffusion patterns.
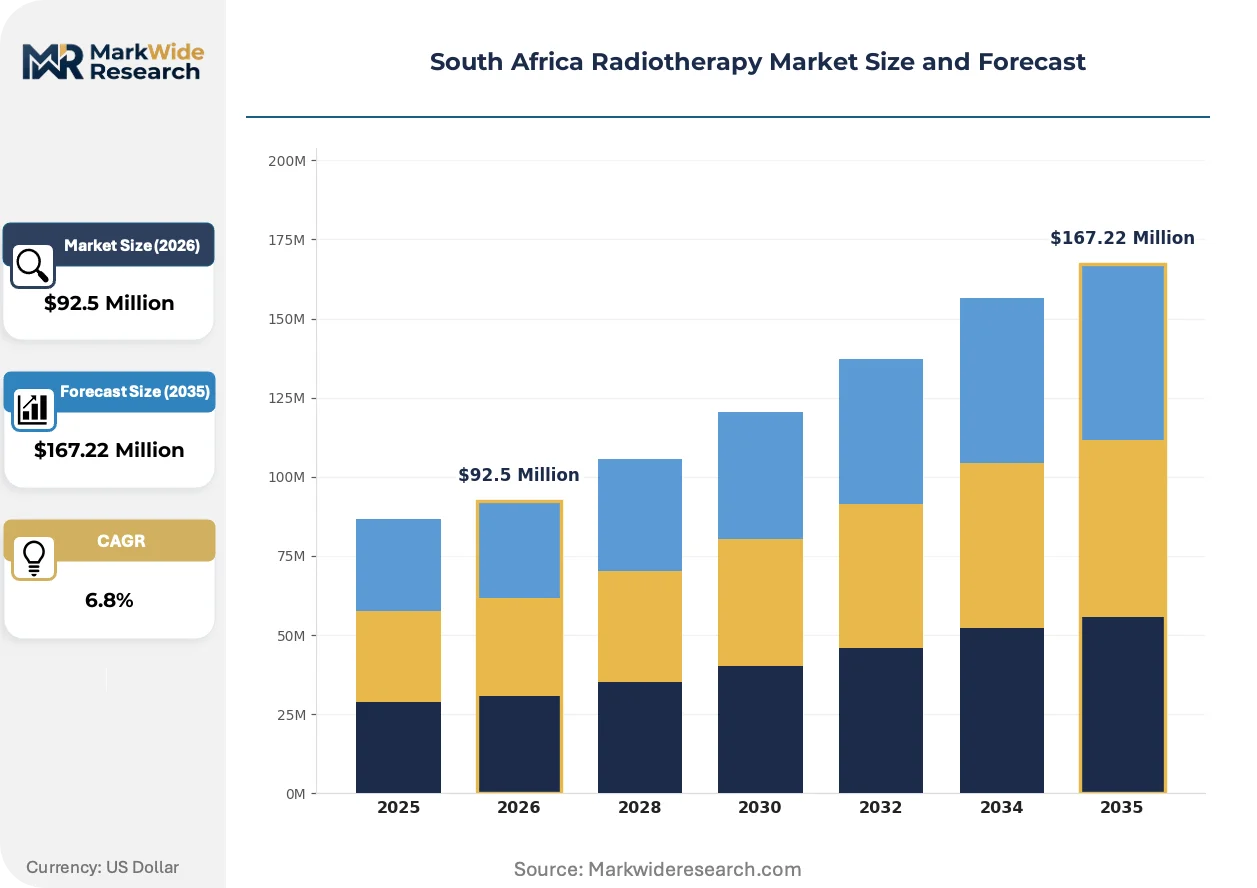
Market Dynamics
Public hospital oncology departments in South Africa are expanding external beam radiation programs under revised National Department of Health cancer care guidelines, creating concentrated demand pull toward linear accelerator installations and adaptive planning software upgrades.
Growth Catalysts
- Regulatory pathway expansion:The National Department of Health's revised cancer care guidelines mandate expanded radiotherapy access, directly increasing equipment procurement quotas across provincial health departments.
- Provincial demand concentration:Gauteng province hosts Johannesburg and Pretoria's largest radiotherapy centers, concentrating patient volumes and justifying capital investment in advanced linear accelerator deployments.
- Brachytherapy program expansion:Dedicated cancer treatment centers are scaling gynecological and prostate brachytherapy services, driving fastest-growing segment demand for afterloading systems and applicator kits.
Market Restraints
- Equipment import dependency:Linear accelerators and proton therapy systems rely entirely on foreign OEM supply chains, exposing procurement timelines to currency volatility and shipping bottlenecks.
- Specialized technical workforce scarcity:Medical physicists and radiation therapy technologists require IAEA-aligned training programs that South African universities struggle to scale at replacement rates.
- Capital intensity barriers:Private hospital groups face extended payback periods for image-guided radiation therapy upgrades, compressing refresh cycles below optimal equipment lifespans.
Strategic Opportunities
- Western Cape hub development:Cape Town's academic medical centers present underutilized capacity for proton therapy partnerships that could anchor regional referral networks.
- Service revenue unbundling:Linear accelerator vendors are separating hardware sales from software maintenance contracts, creating recurring revenue streams through adaptive planning module subscriptions.
- Public-private equipment sharing:Provincial health departments and private hospital groups are piloting joint-use linear accelerator arrangements to optimize machine utilization rates.
Industry Challenges
- Regulatory compliance timelines:South African Health Products Regulatory Authority licensing requirements for radiation-emitting medical devices create 12-18 month approval gaps between purchase orders and clinical deployment.
- Legacy system integration friction:Hospital networks consolidating radiation therapy planning systems face data migration complexity between Varian, Elekta, and Siemens Healthineers software architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Radiotherapy Market |
| Market Size in 2026 | $92.5 Million |
| Market Size in 2035 | $167.22 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: External Beam Radiation, Brachytherapy, Radiopharmaceuticals, Radiation Therapy Planning End User: Hospitals, Cancer Treatment Centers, Research Institutions, Outpatient Clinics Technology: Linear Accelerators, Proton Therapy, CyberKnife, Image-Guided Radiation Therapy Application: Oncology, Pain Management, Palliative Care, Thyroid Disorders |
| Companies Covered | Siemens Healthineers, Elekta, Accuray, GE Healthcare, Varian Medical Systems, IBA Worldwide, ViewRay, IsoRay, NTP Radioisotopes, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Radiotherapy Market Trends and Innovations
Image-guided radiation therapy is reconfiguring treatment planning workflows across South African cancer centers, compressing margins on hardware while expanding software and service revenue pools.
Adaptive radiation therapy is hybridizing real-time imaging feedback with automated dose recalculation, enabling tumor tracking during treatment delivery. Academic medical centers in Johannesburg and Pretoria are piloting these systems for lung and prostate cases. The technology is hybridizing hardware vendors' competitive positions, forcing linear accelerator manufacturers to deepen software capabilities to defend installed base relationships.
The National Department of Health's alignment with IAEA safety standards and ISO 13485 quality management frameworks is tightening equipment qualification requirements. Vendors must now demonstrate comprehensive radiation protection protocols and medical device quality systems before tender eligibility. Private hospital groups are responding by pre-qualifying suppliers through dedicated procurement panels that accelerate subsequent purchase cycles.
After-sales service contracts are unbundling from initial equipment sales, with hospital networks negotiating separate software maintenance and hardware service agreements. This shift is compressing upfront capital outlays while extending vendor relationships over 10-15 year equipment lifespans. Gauteng province's largest radiotherapy centers are leading this transition, using scale to negotiate performance-based service level agreements.
South Africa Radiotherapy Market Segmentation
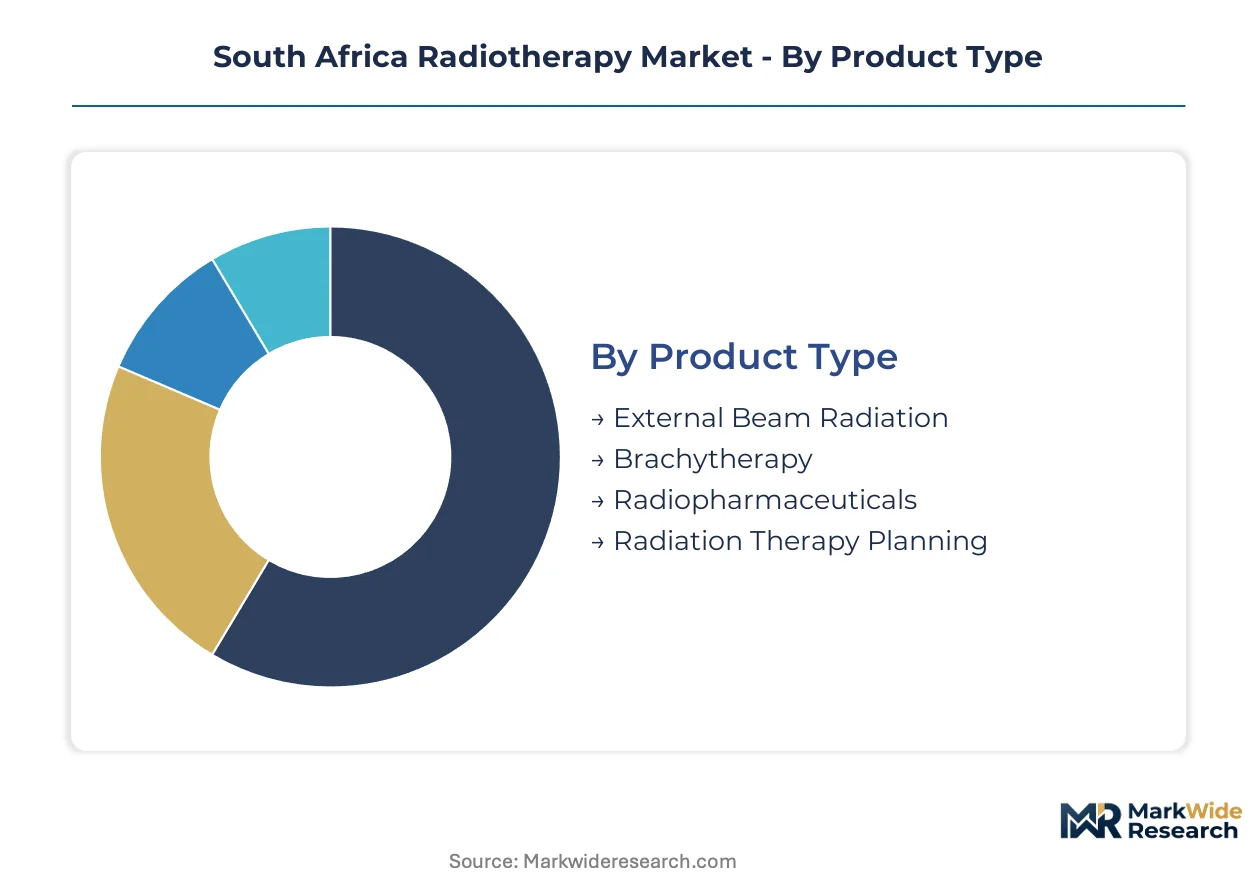
Radiotherapy segmentation in South Africa reveals how capital intensity, clinical workflow complexity, and provincial health infrastructure shape equipment procurement patterns. Understanding these dimensions clarifies why external beam systems dominate installed base while brachytherapy captures margin expansion.
Product Type:
Cost tier stratification separates high-capital external beam installations from lower-entry brachytherapy systems and consumable-driven radiopharmaceuticals.
- External Beam Radiation:Linear accelerator-based systems generating megavoltage X-rays through isocentric gantry delivery. Demand concentrates in Gauteng province where Johannesburg's Charlotte Maxeke and Steve Biko Academic hospitals anchor the country's largest treatment volumes, constrained by extended procurement timelines through the National Department of Health tender system.
- Brachytherapy:Internal radiation delivery via afterloading systems and radioactive source applicators. Dedicated cancer treatment centers in Pretoria and Cape Town are scaling gynecological and prostate programs fastest, driven by shorter treatment courses and lower infrastructure requirements compared to external beam alternatives.
- Radiopharmaceuticals:Diagnostic and therapeutic isotope compounds for nuclear medicine applications.
- Radiation Therapy Planning:Software systems for dose calculation, contouring, and treatment optimization.
External beam radiation commands the established base. The steepest expansion runs through brachytherapy.
End User:
Customer type segmentation reflects how public sector procurement quotas, private hospital group capital cycles, and academic research mandates create divergent equipment specifications.
- Hospitals:Public and private inpatient facilities with integrated oncology departments.
- Cancer Treatment Centers:Dedicated radiation therapy facilities with specialized staffing and patient throughput models. These centers in Johannesburg and Pretoria are consolidating multi-vendor linear accelerator fleets under single software platforms, pressured by radiation oncologist shortages and the need to maximize machine utilization rates.
- Research Institutions:Academic medical centers with clinical trial and technology evaluation mandates. University-affiliated hospitals in Cape Town and Johannesburg are piloting adaptive radiation therapy protocols and proton therapy feasibility studies, accessing National Research Foundation funding streams unavailable to purely clinical operators.
- Outpatient Clinics:Community-based facilities with limited radiation therapy capabilities.
Cancer treatment centers command the established base. The steepest expansion runs through research institutions.
Technology:
Maturity gradients separate decades-linear accelerator dominance from emerging proton and robotic delivery platforms still seeking reimbursement pathways.
- Linear Accelerators:Mature waveguide-based systems producing megavoltage photon and electron beams. Gauteng and Western Cape provinces host the densest installed bases, where Siemens Healthineers and Varian Medical Systems compete through service contract unbundling and adaptive planning software upgrades.
- Proton Therapy:Particle beam systems with Bragg peak dose deposition for pediatric and ocular tumors. Academic medical center partnerships in Cape Town represent the only viable deployment pathway given capital requirements exceeding private hospital group appetite.
- CyberKnife:Robotic radiosurgery platforms for intracranial and extracranial stereotactic delivery.
- Image-Guided Radiation Therapy:Real-time imaging integration for tumor tracking and adaptive replanning.
Linear accelerators command the established base. The steepest expansion runs through image-guided radiation therapy.
Application:
Volume concentration in curative oncology versus margin opportunities in palliative and non-oncology indications shapes service line prioritization.
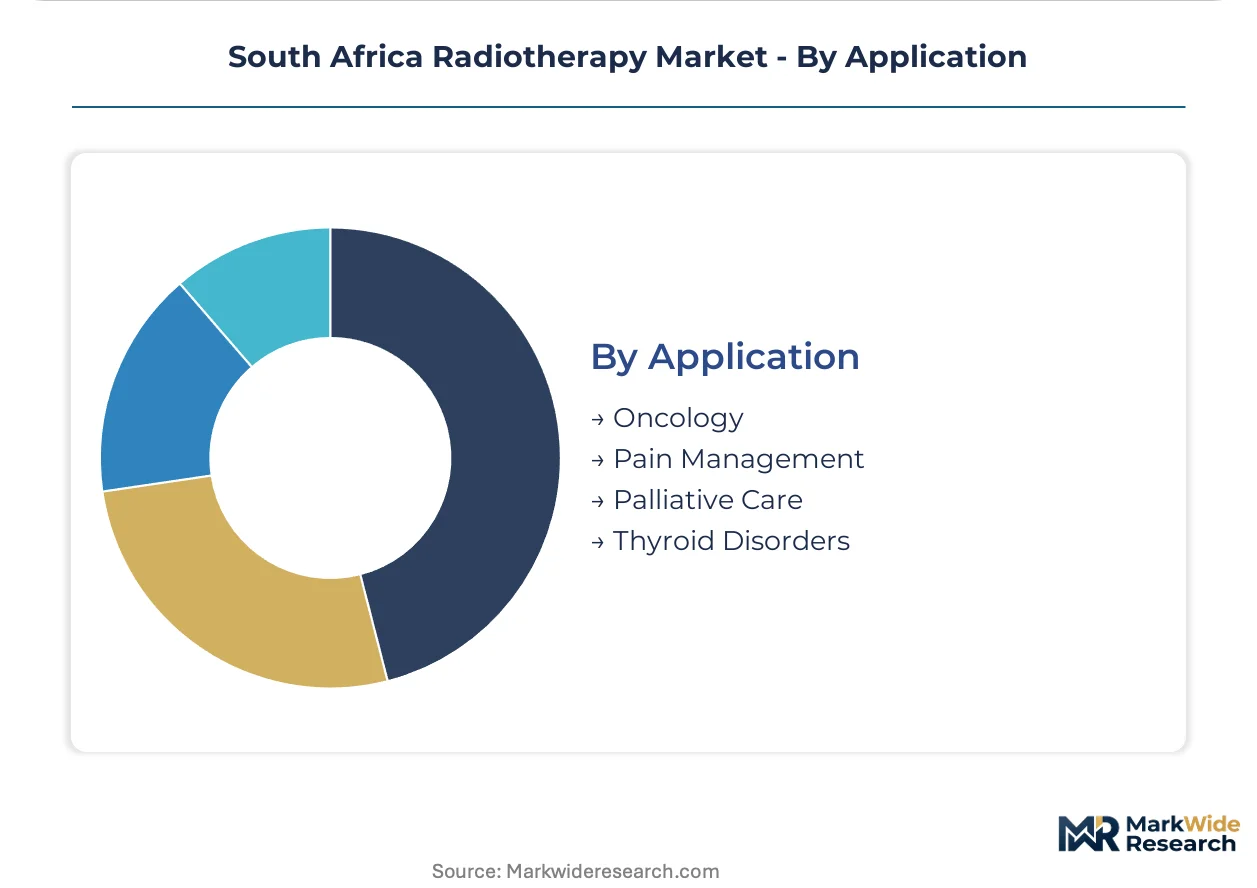
- Oncology:Curative and adjuvant radiation for solid tumors and hematologic malignancies. Breast, lung, and prostate cases dominate treatment schedules at Johannesburg and Pretoria centers, where patient volumes justify extended linear accelerator operating hours and weekend service coverage.
- Pain Management:Radiotherapy for bone metastases and neuropathic pain syndromes. Outpatient clinics in KwaZulu-Natal are expanding these services fastest, responding to aging population demographics and hospice partnership opportunities with lower technical complexity than curative protocols.
- Palliative Care:Symptom-directed radiation for advanced disease.
- Thyroid Disorders:Radioiodine therapy for hyperthyroidism and differentiated thyroid cancer.
Oncology commands the established base. The steepest expansion runs through pain management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and American linear accelerator manufacturers dominate equipment supply into South Africa's public health procurement channels, with Johannesburg and Pretoria receiving the highest shipment volumes for external beam radiation systems.
Gauteng Province
Johannesburg's Charlotte Maxeke Academic Hospital and Steve Biko Academic Hospital anchor the densest linear accelerator concentration in South Africa. The National Department of Health's revised cancer care guidelines mandate expanded radiotherapy access through these facilities. Pretoria's dedicated cancer treatment centers are consolidating multi-vendor fleets under single software platforms to maximize machine utilization rates.
Western Cape Province
Cape Town's academic medical centers are piloting proton therapy feasibility studies and adaptive radiation therapy protocols for lung and prostate cases. University-affiliated hospitals access National Research Foundation funding streams unavailable to purely clinical operators. The province's private hospital groups are negotiating performance-based service level agreements for image-guided radiation therapy upgrades.
KwaZulu-Natal Province
Outpatient clinics in Durban are expanding pain management radiotherapy services for bone metastases and neuropathic pain syndromes. These facilities respond to aging population demographics through hospice partnership arrangements with lower technical complexity than curative protocols. The province lacks dedicated cancer treatment centers, creating referral pressure toward Gauteng.
Eastern Cape Province
Public hospital oncology departments in Port Elizabeth and East London face extended procurement timelines through provincial tender systems. The South African Health Products Regulatory Authority's 12-18 month licensing requirements for radiation-emitting medical devices delay clinical deployment. Equipment sharing pilots between provincial health departments and private hospital groups are testing joint-use linear accelerator arrangements.
South Africa Radiotherapy Market Competitive Landscape
Channel-controlling players compete with product-specialist players across South Africa's radiotherapy procurement landscape. The market structure concentrates around multinational medical device manufacturers with established service infrastructure in Gauteng and Western Cape provinces. Three archetypes dominate: linear accelerator incumbents defending installed bases through software upgrades, proton therapy developers seeking academic medical center partnerships, and brachytherapy specialists targeting dedicated cancer treatment centers. Competitive moves center on unbundling hardware sales from software maintenance contracts and forming public-private equipment sharing arrangements.
Among Germany-based healthcare conglomerates, Siemens Healthineers leverages its regional installed base to sustain service revenue through adaptive planning module subscriptions. Swedish precision radiation therapy developer Elekta anchors proton therapy development through partnerships with Johannesburg and Cape Town academic medical centers. American oncology solutions provider Varian Medical Systems competes on software integration, positioning its radiation therapy planning systems for hospital network consolidation in Gauteng province.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Elekta |
| Accuray |
| GE Healthcare |
| Varian Medical Systems |
| IBA Worldwide |
| ViewRay |
| IsoRay |
| NTP Radioisotopes |
| Others |
Pricing and Supply Chain Analysis
Johannesburg's Charlotte Maxeke and Steve Biko Academic hospitals anchor Gauteng province's densest linear accelerator concentration, concentrating procurement volumes that compress hardware margins while amplifying service contract pricing power for adaptive planning software subscriptions.
Pricing Analysis
Current-generation image-guided radiation therapy systems command substantial premiums over prior-generation linear accelerators and next-generation proton therapy platforms still seeking reimbursement pathways. Three-tier pricing structure across premium IGRT configurations, standard external beam systems, and economy-tier refurbished units dominates equipment procurement. Price differentiation hinges on software integration depth and IAEA-aligned certification tier. Cost compression in economy-tier hardware is intensifying because extended public-sector tender cycles delay capital recovery timelines. Public hospital oncology departments exhibit highest price sensitivity, while private hospital groups in Gauteng demonstrate lowest sensitivity due to bundled service revenue streams.
Supply Chain Analysis
Contract manufacturing for linear accelerator waveguides and gantry assemblies concentrates with specialized German and American precision engineering firms holding exclusive capacity for megavoltage radiation delivery components. Geographic supply concentration centers on Germany, Sweden, and the United States for complete system integration. Raw material dependencies include high-purity copper for waveguide construction, rare-earth magnets for beam steering, and specialized tungsten alloys for collimation systems. Single-source vulnerability for proton therapy cyclotron components creates procurement bottlenecks extending clinical deployment timelines. Distribution runs through multinational OEM direct sales organizations serving South Africa's National Department of Health tender system and private hospital group procurement panels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adaptive planning software subscriptions and performance-based service level agreements expand faster than linear accelerator hardware sales, transforming capital equipment markets into recurring revenue service-attach opportunities.
For Market Incumbents: Build switching-cost moats through deep software integration into hospital network radiation therapy planning systems. Siemens Healthineers and Varian Medical Systems should accelerate adaptive planning module deployment across Gauteng's consolidated multi-vendor fleets. Consolidate service infrastructure in Western Cape province to capture proton therapy partnership maintenance contracts. Vertical integration into localized technical training programs counters medical physicist scarcity threatening equipment utilization rates. For New Entrants and Emerging Players: Mid-market cancer treatment centers in KwaZulu-Natal and Eastern Cape provinces represent the most penetrable entry point given underutilized capacity and referral pressure toward Gauteng. Brachytherapy afterloading systems for gynecological and prostate programs offer lower capital barriers than external beam alternatives. Partner with provincial health departments on equipment sharing pilots to circumvent extended tender cycle disadvantages against established OEM relationships. For Investors and Strategic Acquirers: Long-term, this sits as a service-attach play because hardware refresh cycles extend toward 15-year lifespans while software maintenance contracts generate decade-plus recurring revenue. Acquisition targets should emphasize vendors with unbundled service contract portfolios exceeding 60% of total revenue. Monitor National Department of Health cancer care guideline revisions as inflection indicators for procurement quota expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Service Contract Unbundling | Separates hardware sales from adaptive planning software subscriptions, extending vendor relationships across 10-15 year equipment lifespans. |
| Public-Private Equipment Sharing | Joint-use linear accelerator arrangements between provincial health departments and private hospital groups optimize machine utilization rates. |
| Proton Therapy Partnership Development | Academic medical center alliances in Cape Town anchor regional referral networks for pediatric and ocular tumor specialization. |
| IAEA-Aligned Training Program Investment | Medical physicist and radiation therapy technologist education partnerships address workforce scarcity constraining treatment capacity expansion. |
| Software Platform Consolidation | Multi-vendor fleet unification under single radiation therapy planning systems reduces radiation oncologist workflow friction. |
Research Methodology
Operator-level perspectives from radiation oncologists, medical physicists, hospital procurement managers, biomedical engineers, and National Department of Health oncology program directors anchored the qualitative base. Primary interviews combined with secondary validation from IAEA safety standard documentation, South African Health Products Regulatory Authority licensing records, hospital procurement databases, and GPO contract filings. Bottom-up equipment installation tracking and top-down cancer incidence epidemiology triangulated market sizing across the analysis window.
Scenario-bracketing framed the analytical approach, modeling conservative, baseline, and expansion pathways across product type, technology generation, end-user facility category, and provincial health infrastructure maturity dimensions. CAGRs derived from equipment refresh cycle analysis, tender pipeline assessment, and software upgrade adoption curves. Forecast inputs incorporated National Department of Health guideline implementation timelines and private hospital group capital allocation priority shifts.
Macroeconomic conditions sit as an overlay; deviation in Rand exchange rate volatility, import tariff regimes, or National Treasury health budget allocations would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory approval timelines and workforce training program scale. Quarterly review of public-sector tender award announcements and private hospital group capex disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
New-Born Screening Equipment Market
Medical Equipment
Surgical Generators Market
Medical Equipment
Cell Culture Incubator Market
Medical Equipment
Marijuana Drying and Curing Equipment Market
Medical Equipment
Urodynamics Equipment and Disposables Market
Medical Equipment
Tissue Processing Systems Market
Medical Equipment
Medical Oxygen Gas Cylinder Market
Medical Equipment
Global Latex Medical Gloves Market
Medical Equipment
Medical X-Ray Generators Market
Medical Equipment
Life Support Systems Market
Medical Equipment
Southern Europe and Middle East Medical Robotics Market
Medical Equipment
Operating Table Parts Market
Medical Equipment
Centrifuge Market
Medical Equipment
Global Single-Arm Medical Pendant Market
Medical Equipment
Medical Automation Market
Medical Equipment
Global Stereotactic Radiosurgery (Gamma Knife) Market