
 India Massage Equipment Market | 2026-2036
India Massage Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
India Massage Equipment Market Insights
Spa and salon procurement is rebalancing toward electric massage tables and portable equipment as commercial wellness centers expand beyond metro cores. Panasonic Life Solutions India Pvt Ltd anchors its position through deep channel control in tier-1 appliance retail. Nureca Limited (Dr. Physio) specializes in affordable massage guns and cushions for household buyers. Therabody, Inc. differentiates through recovery-focused technology leadership in percussive therapy devices.
India massage equipment encompasses electrically powered and manually operated devices designed for therapeutic muscle manipulation, typically incorporating motors generating percussive forces or vibration frequencies calibrated for tissue relief. These products serve commercial wellness establishments and residential consumers seeking physiotherapy support, stress reduction, and post-exercise recovery. Massage chairs command the largest revenue pool among product types due to high unit values and feature integration, while massage guns represent the fastest-expanding category driven by fitness culture penetration. Hydraulic technology retains dominance in professional-grade tables, though electric variants gain share in premium salon installations.
BIS mandates electrical safety certification for motorized massage devices, compelling importers and domestic assemblers to align with IS standards before market placement. The CDSCO framework governs therapeutic claims on equipment marketed with medical benefits, restricting unsubstantiated health assertions. India's PLI scheme for consumer electronics offers indirect cost advantages to manufacturers scaling local assembly of electric massage products. Stakeholders must monitor evolving BIS testing protocols and state-level wellness infrastructure investments to calibrate product portfolios and distribution depth.
Market Dynamics
Commercial wellness centers across Maharashtra and Gujarat are accelerating procurement of electric massage tables, compressing replacement cycles from seven years to four years as spa chains compete on service consistency.
Growth Catalysts
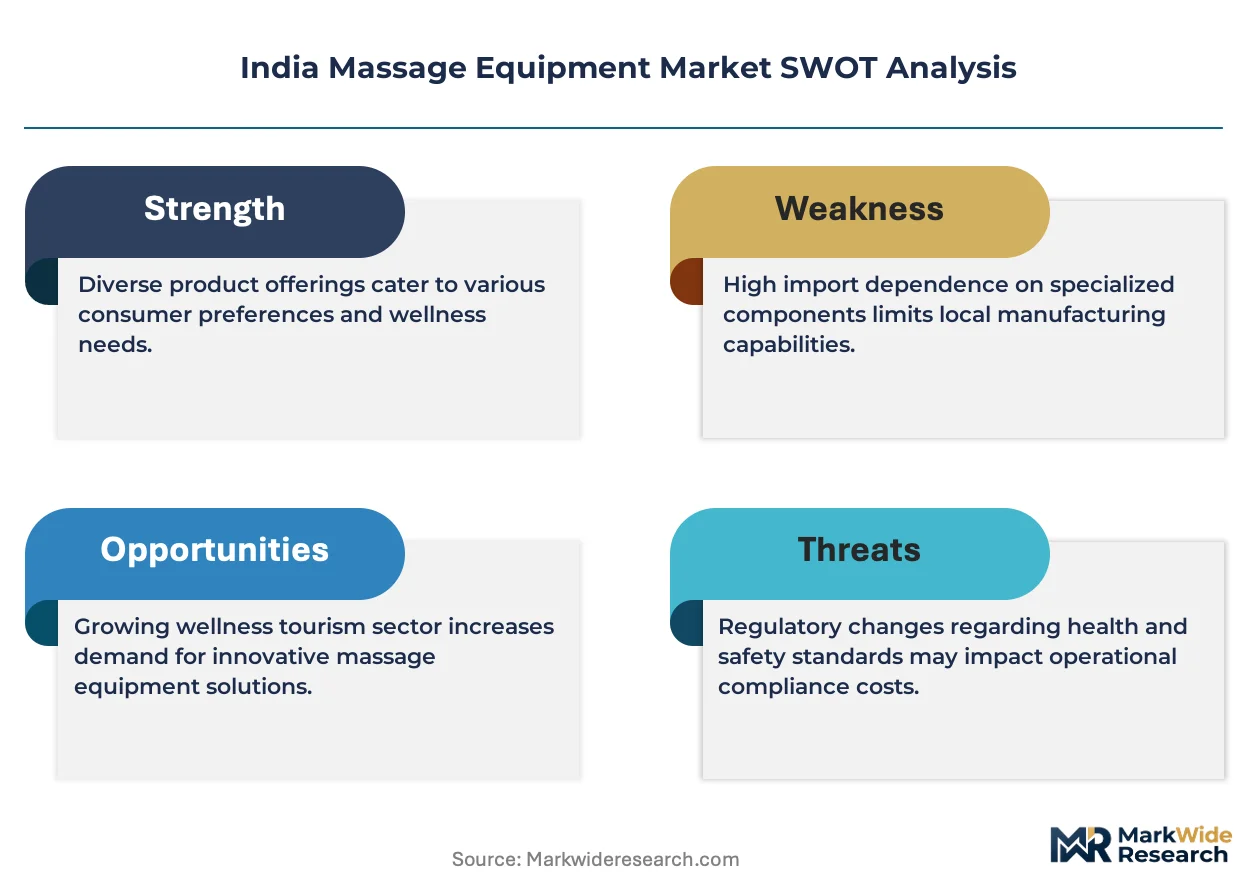
- BIS electrical safety mandates:Standardized IS certification protocols are elevating product quality floors across motorized device categories, filtering out substandard imports and rewarding domestic assemblers with compliant supply chains.
- Home wellness penetration:Urban households in Mumbai and Delhi are integrating massage chairs into daily recovery routines, creating pull-through demand for complementary portable devices.
- PLI scheme incentives:Local assembly scale-up under India's consumer electronics production-linked incentive framework is reducing landed cost structures for electric massage equipment manufacturers.
Market Restraints
- Import dependency for precision motors:Domestic massage chair assembly relies on Japanese and German motor suppliers, exposing margins to yen-euro volatility and elongated lead times.
- BIS testing bottlenecks:Certification queue lengths at Bureau of Indian Standards laboratories extend product launch timelines by four to six months for new electric entrants.
- Manual equipment substitution:Price-sensitive tier-2 salon operators continue favoring hydraulic tables over electric variants, capping premium product penetration in non-metro clusters.
Strategic Opportunities
- Tier-3 city wellness infrastructure:Spa and salon expansion into Indore, Surat, and Nagpur presents first-mover positioning for portable massage equipment distributors.
- CDSCO therapeutic claim pathways:Equipment vendors securing medical device classification unlock institutional procurement channels through hospital physiotherapy departments.
- Fitness center integration:Post-workout recovery stations at premium gym chains represent an emerging application vector for percussive therapy devices.
Industry Challenges
- Skilled technician scarcity:Electric massage chair repair networks remain thin outside Mumbai, Delhi, and Bangalore, constraining after-sales service reach.
- Multi-regulator compliance complexity:Simultaneous BIS electrical safety and CDSCO therapeutic claim filings create documentation duplication for hybrid-positioned products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Massage Equipment Market |
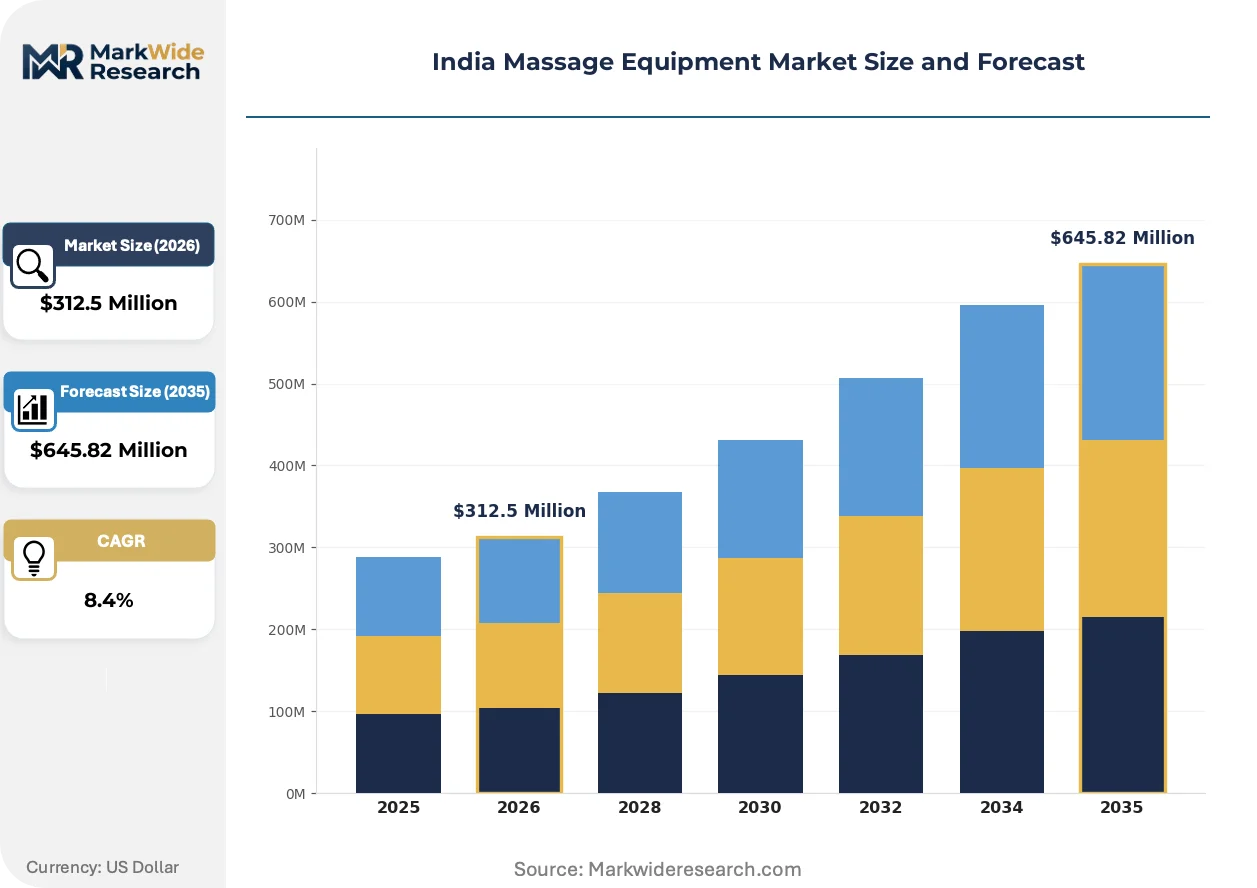
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Massage Chairs, Massage Tables, Massage Cushions, Massage Guns End User: Households, Salons, Spas, Gyms Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales Technology: Hydraulic, Electric, Portable, Manual |
| Companies Covered | Nureca Limited (Dr. Physio), Panasonic Life Solutions India Pvt Ltd, Paramount Surgimed Limited (OSIM India), Nirvana Electronics, Therabody, Inc., iRest Systems Private Limited, Omron Healthcare India Private Limited, AGARO Lifestyle, JSB Health And Fitness Private Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Massage Equipment Market Trends and Innovations
Intelligent pressure-mapping systems and connected recovery protocols are redefining value propositions across both commercial and residential segments, compressing differentiation cycles for incumbent manufacturers.
AI-driven body scanning technology is expanding into mid-tier massage chair configurations, enabling real-time adjustment of roller pressure and heat zones based on user biometrics. Tier-1 appliance retailers in Delhi and Mumbai are stocking these models as traffic drivers. This capability diffusion is expanding into price brackets previously occupied by static-program chairs, forcing feature-table recalibration across product lines.
BIS has tightened electromagnetic compatibility testing protocols for motorized wellness devices, mandating revised IS standards compliance for all new market placements. Domestic assemblers with captive testing facilities are absorbing certification costs more efficiently than import-reliant competitors. Premium salon chains now specify BIS-certified electric tables exclusively, transferring compliance burden upstream to equipment vendors.
Post-purchase service unbundling is fragmenting traditional warranty bundles, with commercial buyers negotiating separate maintenance contracts from equipment procurement. Spa operators in Gujarat are piloting usage-based service subscriptions rather than fixed-term coverage. This behavioral shift is most visible in Maharashtra's organized wellness chains, where finance teams treat service spend as opex rather than capitalized warranty reserves.
India Massage Equipment Market Segmentation
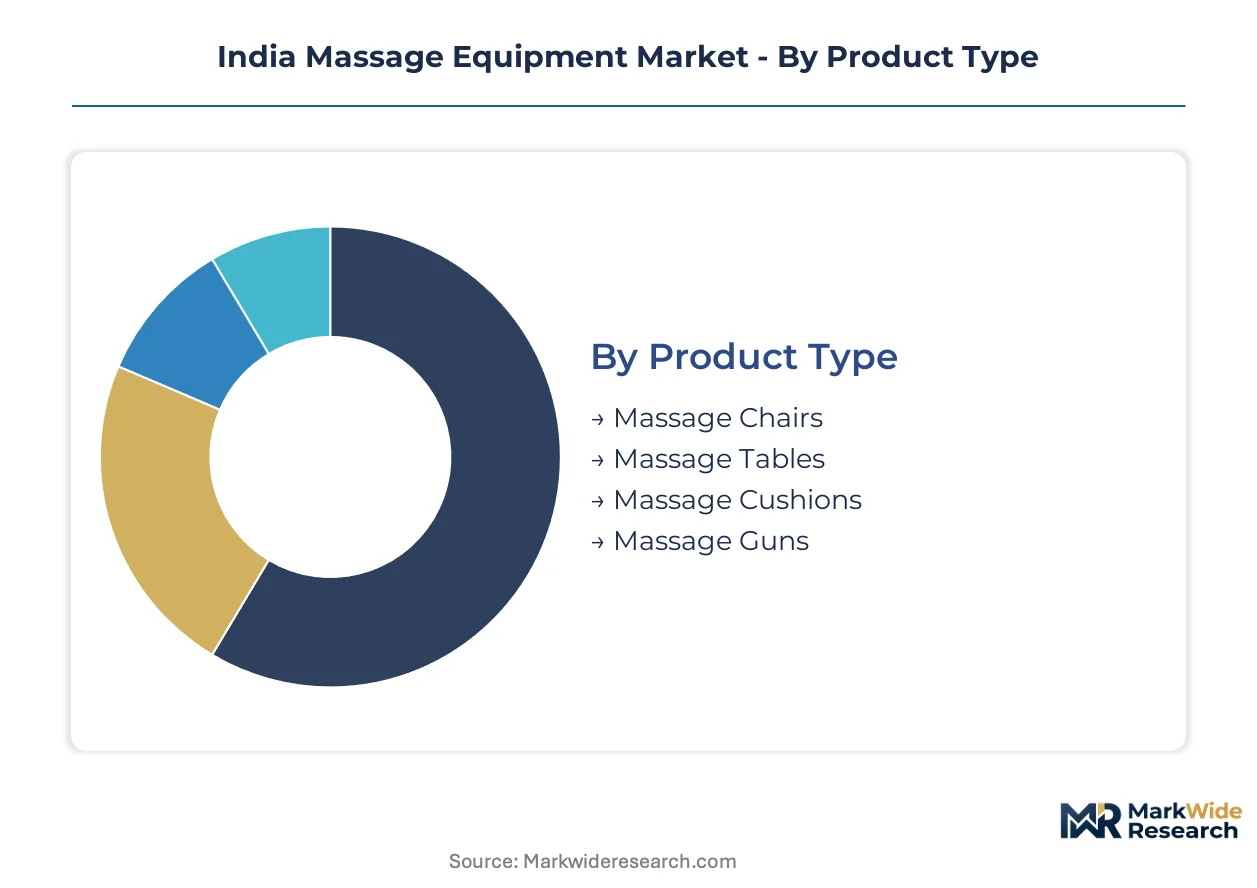
Segmentation in the India massage equipment market reveals divergent procurement patterns between residential buyers prioritizing convenience and commercial operators optimizing service throughput. Understanding these splits enables vendors to calibrate feature sets, pricing tiers, and channel investments against distinct performance requirements.
Product Type:
Motorization intensity and unit economics separate these categories, with premium seating commanding capital outlays that reshape household furniture budgets.
- Massage Chairs:Full-body recliners integrate quad-roller mechanisms, zero-gravity positioning, and heat therapy modules. Mumbai and Delhi households drive procurement as primary wellness furniture, with BIS electrical certification filtering substandard imports from tier-1 retail floors.
- Massage Tables:Professional-grade platforms span fixed-base and portable configurations, with electric variants gaining share in premium salon installations. Spa chains in Maharashtra compress replacement cycles to four years as competitive pressure intensifies on service consistency.
- Massage Cushions:Seat-back attachments deliver localized vibration therapy through DC motor arrays. Price-sensitive tier-2 households favor these for entry-level muscle relief without dedicated floor space commitment.
- Massage Guns:Percussive therapy devices generate rapid amplitude forces for post-exercise recovery. Fitness culture penetration across Gujarat gym chains positions this category for steepest expansion trajectory.
Massage chairs lead on scale; massage guns lead on momentum.
End User:
Procurement authority and usage intensity create distinct specification demands across residential and commercial contexts.
- Households:Individual buyers prioritize space efficiency and silent operation for daily recovery routines. Urban Maharashtra and Delhi NCR households anchor residential demand, with massage chairs functioning as status-comfort hybrid purchases.
- Salons:Beauty-focused operators require multi-position tables with face cradle adjustability for extended client sessions. Gujarat's organized salon chains specify BIS-certified electric equipment exclusively, transferring compliance burden to vendors.
- Spas:Wellness centers demand whisper-quiet operation and rapid position transition for treatment throughput. Commercial buyers in tier-3 expansion markets like Indore and Surat negotiate usage-based service subscriptions rather than capitalized warranty reserves.
- Gyms:Fitness centers integrate recovery stations into premium membership tiers. Post-workout percussive therapy deployment at Mumbai premium chains creates pull-through demand for portable devices among member households.
Commercial wellness establishments concentrate procurement volume; gym integration opens the fastest adoption pathway.
Distribution Channel:
Channel selection correlates with buyer sophistication and equipment complexity, with high-consideration purchases demanding tactile evaluation.
- Online Retail:E-commerce platforms capture massage gun and cushion sales through fitness influencer attribution. Price transparency and review aggregation attract digitally native households across tier-2 cities.
- Supermarkets:Mass retail chains stock entry-level portable devices alongside general merchandise. Impulse accessibility drives cushion sales, though massage chairs remain absent due to footprint constraints.
- Specialty Stores:Dedicated wellness retailers provide trial infrastructure for chair purchases. Panasonic Life Solutions India Pvt Ltd anchors tier-1 appliance retail through deep channel control in Delhi and Mumbai.
- Direct Sales:Manufacturer representatives handle commercial bulk procurement for spa and salon chains. Relationship-based contracting dominates electric table sales to organized wellness operators in Maharashtra.
Specialty stores command chair transactions; online retail captures the steepest growth curve in portable categories.
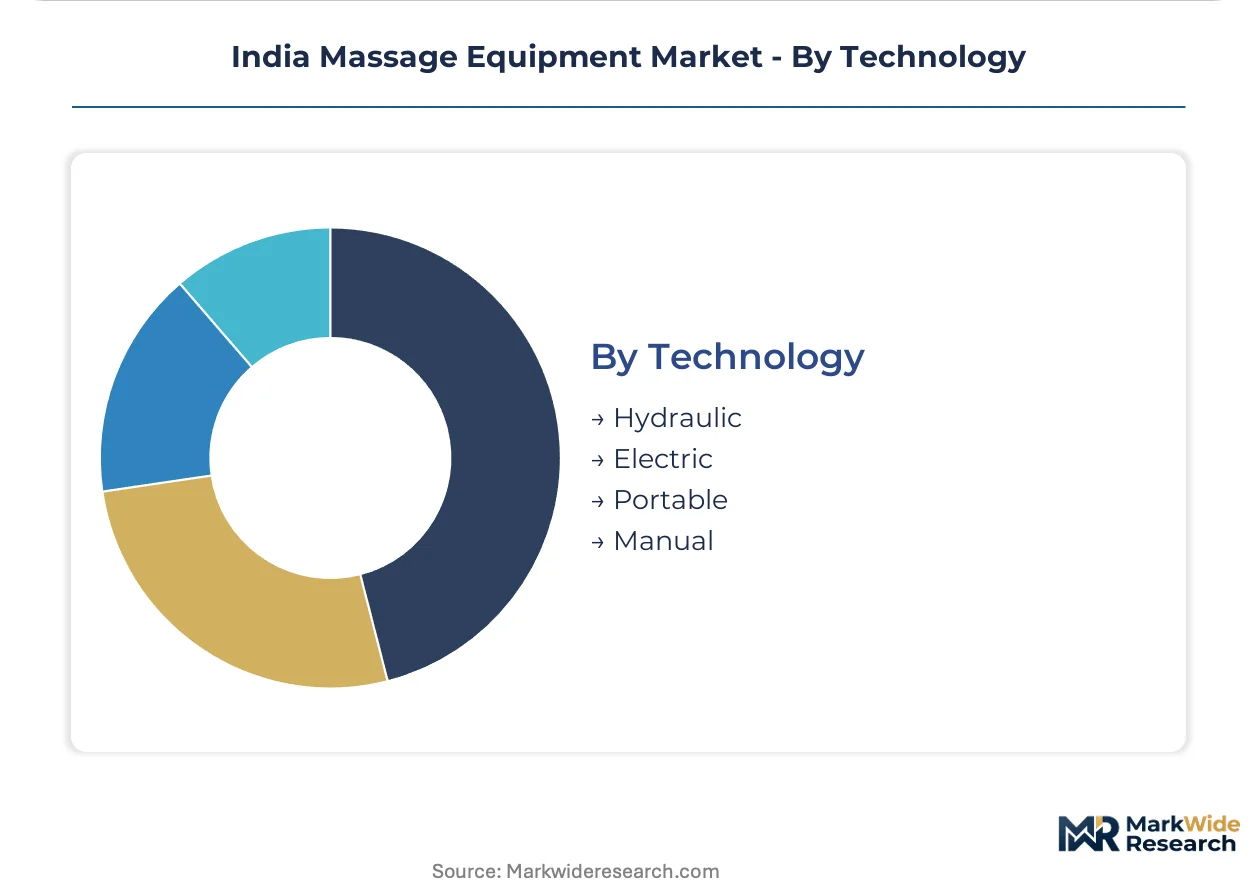
Technology:
Power source and mobility characteristics determine application fit and margin structure across the equipment spectrum.
- Hydraulic:Fluid-powered lift mechanisms dominate professional table installations through proven durability and maintenance simplicity. Tier-2 salon operators favor these over electric alternatives due to lower acquisition cost and technician independence.
- Electric:Motorized actuation enables programmable position memory and synchronized multi-zone therapy. BIS electromagnetic compatibility mandates filter non-compliant imports, rewarding domestic assemblers with captive testing facilities.
- Portable:Battery-powered or manual-lift designs prioritize transportability for mobile therapists and home users. Massage gun category expansion concentrates here, with compact form factors enabling gym bag integration.
- Manual:Non-powered tables and tools persist in price-sensitive segments through minimal failure modes and zero electrical certification requirements. Rural and semi-urban markets retain residual demand for these configurations.
Hydraulic systems retain installed base dominance; electric platforms gain share fastest in premium commercial retrofit cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing assembly capacity toward Indian states with streamlined BIS certification pathways and PLI scheme access, compressing cost-of-compliance gaps that previously favored import-heavy distribution models.
Maharashtra
Mumbai's organized spa chains are compressing electric massage table replacement cycles from seven years to four years as competitive pressure intensifies on service consistency. The state's PLI scheme implementation for consumer electronics offers indirect cost advantages to manufacturers scaling local assembly. Pune and Nashik industrial corridors are attracting component fabricators serving motorized wellness device assemblers.
Gujarat
Surat and Ahmedabad salon operators are accelerating procurement of BIS-certified electric equipment exclusively, transferring compliance burden upstream to vendors. The state's dense spa infrastructure supports concentrated demand for professional-grade massage tables. Gandhinagar-based testing facilities are reducing BIS certification queue lengths for domestic assemblers.
Delhi-NCR
Urban households across Delhi and Gurugram are integrating massage chairs into daily recovery routines, creating pull-through demand for complementary portable devices. CDSCO therapeutic claim pathways are unlocking institutional procurement channels through hospital physiotherapy departments in the capital region. Noida electronics manufacturing clusters are scaling assembly of motorized wellness products.
Karnataka
Bangalore's premium gym chains are deploying post-workout recovery stations, creating emerging application vectors for percussive therapy devices. The state's skilled technician scarcity outside metro cores constrains after-sales service reach for electric massage chair networks. Mysuru component suppliers are serving domestic massage equipment assemblers with reduced lead times.
Tamil Nadu
Chennai's organized wellness chains are piloting usage-based service subscriptions rather than fixed-term warranty coverage, treating service spend as operational expenditure. The state's manufacturing base supports hydraulic table production for price-sensitive tier-2 salon operators. Coimbatore motor suppliers are reducing import dependency for precision actuation components.
India Massage Equipment Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbent appliance manufacturers and specialized wellness device vendors recalibrate feature sets against distinct residential and commercial procurement patterns. The vendor base organizes around three strategic archetypes: diversified electronics conglomerates with deep channel control, affordable wellness specialists targeting household penetration, and recovery-technology innovators serving fitness-integrated applications. Competitive intensity concentrates on certification compliance speed and tier-3 city distribution depth.
Among diversified electronics conglomerates, Panasonic Life Solutions India Pvt Ltd anchors tier-1 appliance retail positioning through established channel relationships in Delhi and Mumbai. Nureca Limited (Dr. Physio) exemplifies the affordable wellness specialist archetype, occupying a position calibrated toward price-sensitive household buyers seeking entry-level muscle relief devices. Therabody, Inc. represents the recovery-technology innovation vector, sitting within the premium percussive therapy segment where fitness culture penetration drives category expansion. These three anchors illustrate the competitive spectrum spanning mass-market accessibility through technology-led premium positioning.
| Leading Market Players |
|---|
| Nureca Limited (Dr. Physio) |
| Panasonic Life Solutions India Pvt Ltd |
| Paramount Surgimed Limited (OSIM India) |
| Nirvana Electronics |
| Therabody, Inc. |
| iRest Systems Private Limited |
| Omron Healthcare India Private Limited |
| AGARO Lifestyle |
| JSB Health And Fitness Private Limited |
| Others |
Pricing and Supply Chain Analysis
Backward integration into precision motor sourcing anchors both supply security and pricing power for domestic massage equipment assemblers competing against import-reliant rivals exposed to yen-euro volatility. Panasonic Life Solutions India Pvt Ltd leverages captive testing facilities to absorb BIS certification costs more efficiently than competitors, translating compliance speed into margin expansion.
Pricing Analysis
Distributor margins in tier-1 appliance retail compress as Panasonic Life Solutions India Pvt Ltd exercises direct channel control in Delhi and Mumbai. Three-tier pricing structure across premium, standard, and economy levels separates AI-enabled massage chairs with body-scanning technology from static-program configurations and manual alternatives. Cost compression in the electric table segment intensifies because spa chains in Maharashtra negotiate usage-based service subscriptions rather than capitalized warranty bundles. Tier-2 salon operators in Gujarat exhibit highest price sensitivity, favoring hydraulic tables over electric variants, while premium gym chains in Bangalore demonstrate lowest sensitivity for percussive therapy recovery stations.
Supply Chain Analysis
Workforce availability in Noida and Pune electronics manufacturing clusters supports scaling of motorized wellness product assembly under India's PLI scheme for consumer electronics. Component sourcing draws from Japanese and German precision motor suppliers, Mysuru-based component fabricators, and Coimbatore motor suppliers reducing import dependency. Single-source vulnerability concentrates in high-torque actuator supply for premium massage chairs. Distribution runs through tier-1 appliance retailers for high-consideration chair purchases, direct sales teams for commercial bulk procurement, and e-commerce platforms for portable device categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in the India massage equipment market rests on PLI scheme cost-down benefits for domestic assemblers and premium-tier shift toward AI-enabled configurations with body-scanning technology.
For Market Incumbents: Lock in channel control through exclusive arrangements with tier-1 appliance retailers in Delhi and Mumbai, and accelerate BIS certification queue management via captive testing facilities to outpace import-reliant competitors facing four-to-six month launch delays. Defend against emerging affordable wellness specialists by embedding intelligent pressure-mapping systems into mid-tier product lines before feature diffusion erodes differentiation. For New Entrants and Emerging Players: Enter via the tier-3 wellness infrastructure expansion corridor in Indore, Surat, and Nagpur, where portable massage equipment distribution remains underdeveloped and first-mover positioning is available. Target gym chain recovery station procurement in premium fitness centers across Bangalore and Mumbai, deploying percussive therapy devices through influencer-attributed digital channels before establishing specialty retail presence. For Investors and Strategic Acquirers: Consolidation pressure builds where domestic assemblers with PLI scheme access and captive BIS testing capabilities face capital constraints for scaling component fabrication. Long-term viability favors vertically integrated specialists controlling precision motor supply and certification speed. Watch CDSCO therapeutic claim pathway approvals as inflection indicators unlocking institutional procurement through hospital physiotherapy departments.| Strategic Initiative | Industry Significance |
|---|---|
| PLI Scheme Manufacturing Scale-Up | Reduces landed cost structures for electric massage equipment assemblers in Noida and Pune corridors. |
| BIS Certification Investment | Accelerates product launch timelines and filters non-compliant import competitors from tier-1 retail. |
| CDSCO Therapeutic Claim Pathway | Unlocks institutional procurement channels through hospital physiotherapy departments in Delhi-NCR. |
| Channel Control Deepening | Secures exclusive tier-1 appliance retail positioning against affordable wellness specialist encroachment. |
| AI-Enabled Product Launch | Expands body-scanning technology into mid-tier configurations before feature-table recalibration completes. |
Research Methodology
Coverage spans Maharashtra, Gujarat, Delhi-NCR, Karnataka, and Tamil Nadu, with primary inputs from each state informing demand pattern calibration. Primary interviews with spa procurement directors, salon chain operators, gym facility managers, appliance retail buyers, and BIS certification consultants combined with secondary validation from BIS notification records, CDSCO device classification databases, PLI scheme implementation documents, and organized retail trade data. Bottom-up demand estimation across end-user segments triangulated with top-down market sizing from production cluster output analysis.
Rate-of-change decomposition separated volume expansion from value migration across the projection horizon. Segmentation dimensions modeled include product type, end-user category, distribution channel, and technology platform, with motorization intensity and certification tier as industry-specific stratifiers. CAGRs derived from segment-level growth trajectory analysis incorporating PLI scheme incentive flow-through, BIS compliance cost absorption curves, and tier-3 city wellness infrastructure investment pipelines.
The model holds under sustained PLI scheme implementation and stable BIS certification queue management; deviation in yen-euro exchange volatility or CDSCO therapeutic claim approval delays would shift competitive positioning toward import-reliant or non-medical-positioned competitors respectively. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Solar Powered Vaccine Refrigerator Market
Medical Equipment
Global Microtome Market
Medical Equipment
Floor-Standing Platelet Agitator Market
Medical Equipment
Medical Oxygen Systems Market
Medical Equipment
US Durable Medical Equipment Market
Medical Equipment
Defibrillator Analyzers Market
Medical Equipment
Global Intraoperative Radiation Therapy Market
Medical Equipment
Electron Beam Linear Accelerators Market
Medical Equipment
Patient Mechanical Lift Handling Equipment Market
Medical Equipment
Hybrid Operating Room Market
Medical Equipment
Medical Equipment Reimbursement Market
Medical Equipment
Global Stereotactic Radiosurgery (Gamma Knife) Market
Medical Equipment
Clinical Microscopes Market
Medical Equipment
Healthcare Simulators Market
Medical Equipment
Asia-Pacific Nuclear Medicine Equipment Market
Medical Equipment
Medical Whirlpool Market