
 X-Ray Generator Market | 2026-2036
X-Ray Generator Market Size, Share, and Industry Trends Forecast 2026-2036
X-Ray Generator Market Analytics
The gap between premium high-frequency generators and commodity fixed units is shifting from a price spread into a capability chasm. Siemens Healthineers leverages its integrated imaging platforms to dominate hospital procurement cycles. Spellman High Voltage Electronics Corporation anchors the independent supplier tier with specialized high-voltage architectures for OEM integration. GE Healthcare differentiates through service-network density that sustains installed-base loyalty across North American diagnostic centers.
An X-ray generator is an electrical device that converts input power into high-voltage potential—typically 20–150 kV for medical applications—to drive electron acceleration within an X-ray tube and produce controlled ionizing radiation for diagnostic or industrial imaging. The core assembly comprises a high-voltage transformer, rectifier bridge, filament circuit, and control module housed in oil-filled or solid-state insulated enclosures. Portable generators lead volume in field-deployed and point-of-care settings where mobility outweighs maximum output capacity, while high-frequency technology captures margin pools through superior dose efficiency and shorter exposure times that reduce patient radiation burden. Fixed installations in hospital radiography departments represent the mature revenue base, with replacement cycles tied to regulatory compliance timelines rather than performance obsolescence.
The US FDA governs device classification and 510(k) clearance pathways that determine market access timelines for new generator architectures, while the EU MDR imposes post-market surveillance and clinical evidence requirements that reshape R&D allocation for CE-marked products. ISO 13485 quality management certification functions as a de facto procurement filter across OECD healthcare systems, excluding non-compliant suppliers from tender participation. Stakeholders must weigh escalating regulatory documentation costs against the defensive value of early compliance positioning as emerging economies adopt harmonized standards.
Market Dynamics
High-frequency generator architectures are compressing exposure windows while Siemens Healthineers and Spellman High Voltage Electronics Corporation battle for control of hospital procurement cycles and OEM integration channels.
Growth Catalysts
- MDR post-market surveillance mandates:EU clinical evidence requirements accelerate replacement of legacy fixed-frequency systems in German radiology departments.
- Point-of-care mobility demand:Emergency medicine and field-deployed trauma units drive portable generator volume where maximum output capacity is traded for transportability.
- Silicon carbide power electronics:Wide-bandgap semiconductors enable compact high-voltage switching that reduces generator footprint and thermal load.
Market Restraints
- Copper and ferrite core volatility:Transformer winding materials face commodity price swings that compress margin on fixed-installation units.
- Single-source high-voltage cable dependency:Specialized dielectric suppliers concentrate in Japan and Germany, creating geographic chokepoints for OEMs.
- Ionization chamber calibration drift:Dose measurement accuracy degrades without frequent recalibration, elevating total cost of ownership.
Strategic Opportunities
- Veterinary imaging expansion:Companion animal diagnostic chains in Brazil and Mexico underpenetrate relative to human healthcare infrastructure.
- Industrial CT metrology convergence:Additive manufacturing quality control fuses radiographic inspection with dimensional analysis for aerospace components.
- US FDA 510(k) parallel review pathways:Streamlined clearance for predicate-equivalent high-frequency architectures compresses time-to-revenue for domestic manufacturers.
Industry Challenges
- High-voltage engineering talent scarcity:Specialized transformer design and oil-impregnated insulation expertise concentrates among aging workforce cohorts.
- ISO 13485 documentation burden:Quality management system certification timelines extend 18-24 months for new market entrants.
- Legacy analog control integration:Digital high-frequency generators must interface with decades-old radiography room infrastructure without full department retrofit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | X-Ray Generator Market |
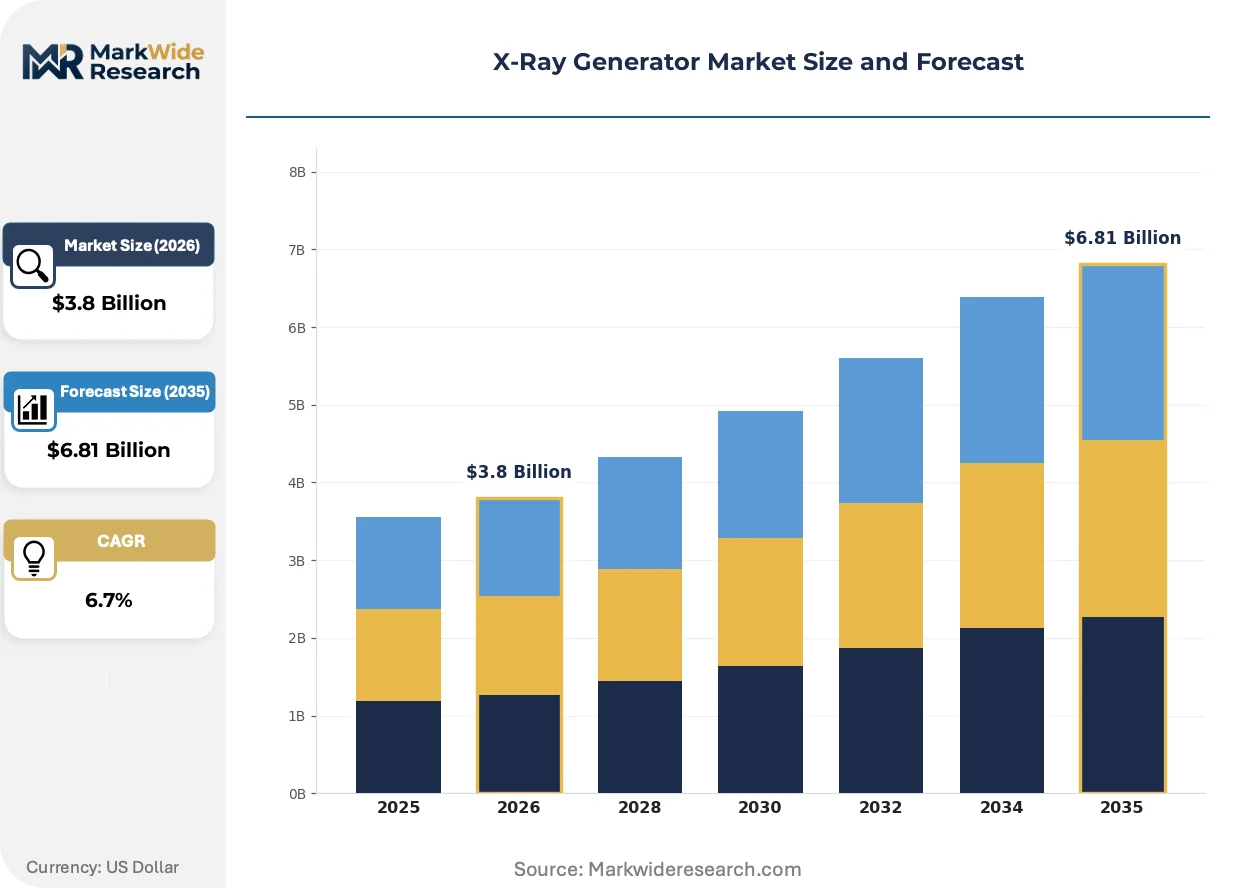
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Fixed, Mobile, Stationary Technology: High-Frequency, High-Voltage, Constant Potential, Solid State End User: Hospitals, Diagnostic Centers, Research Labs, Clinics Application: Orthopedics, Dental Imaging, Mammography, Radiography |
| Companies Covered | Spellman High Voltage Electronics Corporation, Siemens Healthineers, Communications & Power Industries LLC, GE Healthcare, COMET Group, DRGEM Corporation, Philips Healthcare, Teledyne ICM, Innomed Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
X-Ray Generator Market Evolving Landscape
Generator control intelligence is migrating from hardware-defined to software-configurable architectures, enabling real-time dose modulation and predictive maintenance capabilities that reshape service contract economics.
Artificial intelligence-based exposure parameter selection is automating technologist workflow in busy hospital radiography departments. Siemens Healthineers integrates deep learning models that predict optimal kV and mAs settings from patient body habitus data. This capability is automating the traditional trial-and-error exposure adjustment process that consumed valuable scanner time and elevated retake rates.
The EU MDR clinical evidence requirements are forcing manufacturers to fund prospective imaging studies that demonstrate diagnostic equivalence for cleared generator architectures. Small and mid-size OEMs face documentation burdens that favor integrated platform vendors with captive clinical research infrastructure. German notified bodies report 40% backlog increases for radiology device submissions as legacy certificates expire.
Hospital procurement committees are unbundling generator purchases from full imaging system contracts, creating direct sourcing channels for high-voltage subassemblies. Independent service organizations now compete for maintenance contracts previously captured by original equipment manufacturers. This disintermediation is most visible in North American diagnostic centers where capital equipment budgets face pressure from staffing cost inflation.
X-Ray Generator Market Segmentation
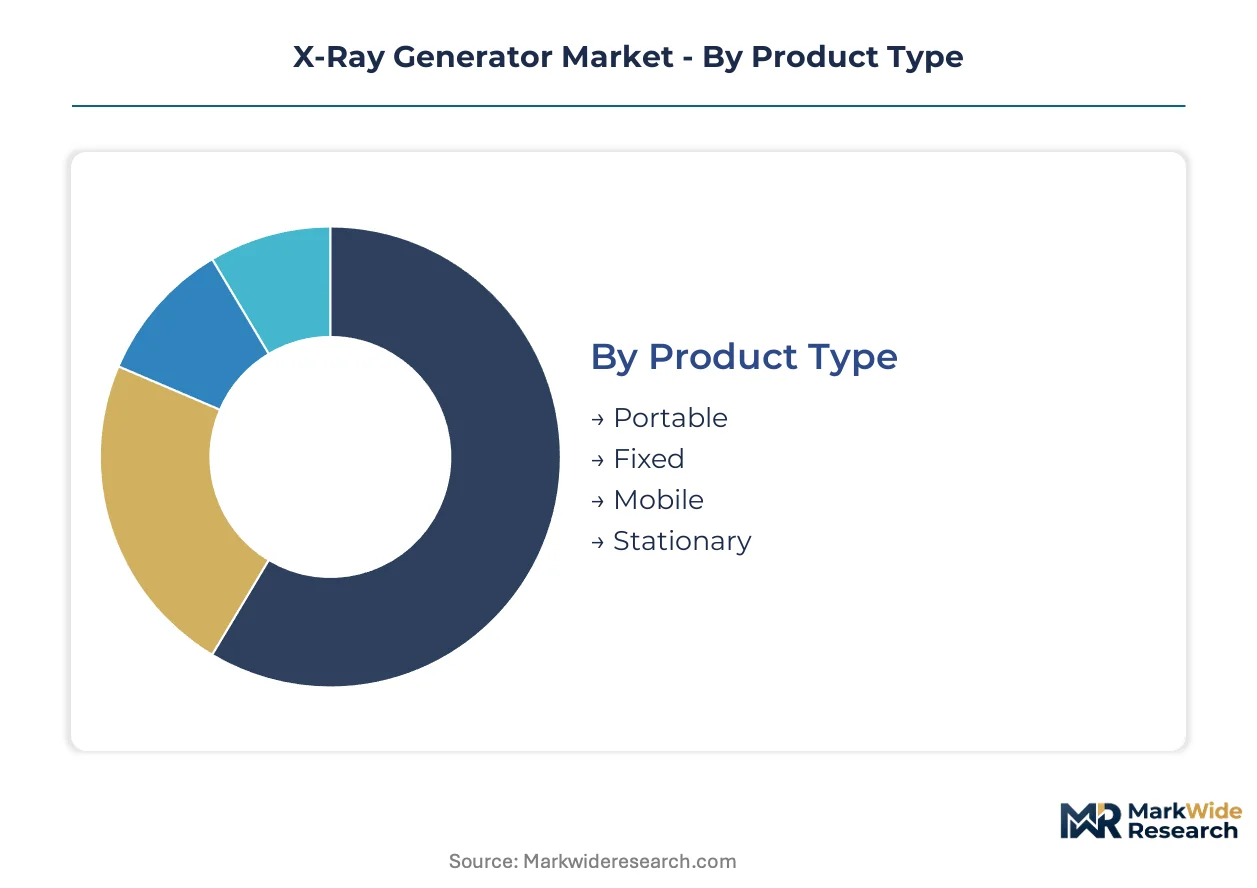
X-ray generator segmentation reveals how product architecture, power electronics, and clinical workflow requirements fragment procurement decisions across healthcare delivery tiers. Each dimension carries distinct margin profiles and regulatory compliance burdens that reshape vendor positioning.
Product Type:
Standalone generators dominate field-deployed settings while embedded units integrate into complete imaging platforms.
- Portable:Battery-powered or capacitor-discharge units deliver 5-20 kW output for emergency medicine and military trauma units. Demand concentrates in US rural health networks where transportability outweighs maximum tube loading capacity. Battery chemistry limitations constrain exposure repetition rates.
- Fixed:Hardwired installations in dedicated radiography rooms supply 50-150 kW continuous output for high-throughput hospital departments. German university hospitals anchor replacement demand as EU MDR compliance deadlines accelerate legacy system retirement.
- Mobile:Motorized wheeled generators bridge bedside imaging in intensive care units with limited department retrofit budgets. Japanese acute care facilities favor these units for space-constrained urban hospitals.
- Stationary:Permanent gantry-mounted generators serve computed tomography and angiography suites requiring precise mechanical alignment. Aerospace manufacturing quality control drives secondary demand for non-destructive testing configurations.
Fixed installations lead volumes today; portable configurations are gaining share fastest.
Technology:
Power conversion architecture determines dose efficiency, thermal management, and service interval economics across installation types.
- High-Frequency:Inverter-based designs operating above 20 kHz reduce transformer size and enable precise kV modulation. US FDA quality standard tightening favors these systems in hospital procurement cycles demanding superior dose reproducibility.
- High-Voltage:Conventional line-frequency transformers with oil-impregnated insulation remain prevalent in cost-sensitive emerging markets. Brazilian diagnostic chains continue specifying these units where capital constraints override efficiency premiums.
- Constant Potential:Three-phase full-wave rectification delivers minimal ripple for magnification radiography and micro-focus industrial inspection. German automotive suppliers specify these generators for casting defect detection in powertrain components.
- Solid State:Silicon carbide and gallium nitride switching elements eliminate oil cooling and enable sealed enclosures for harsh environments. Offshore pipeline inspection contractors in Norway adopt these for subsea deployment reliability.
High-frequency systems dominate revenue contribution; solid-state architectures show steepest expansion trajectory.
End User:
Procurement authority concentration varies sharply across customer types, from centralized hospital supply chains to fragmented independent practice purchasing.
- Hospitals:Integrated health systems negotiate enterprise contracts bundling generators with PACS and radiology information systems. US academic medical centers drive specification toward AI-enabled exposure automation.
- Diagnostic Centers:Specialized imaging chains prioritize throughput density and rapid patient turnaround. Indian metro markets see these operators demanding compact high-frequency units for leased facility footprints.
- Research Labs:Synchrotron facilities and materials science institutes require ultra-stable output for diffraction and spectroscopy applications. CERN and DESY specifications influence commercial high-voltage engineering standards.
- Clinics:Small outpatient practices favor refurbished fixed-frequency units or entry-level portable systems. Mexican government procurement programs target this segment for primary care network expansion.
Hospitals command the largest installed base; diagnostic centers are expanding most quickly.
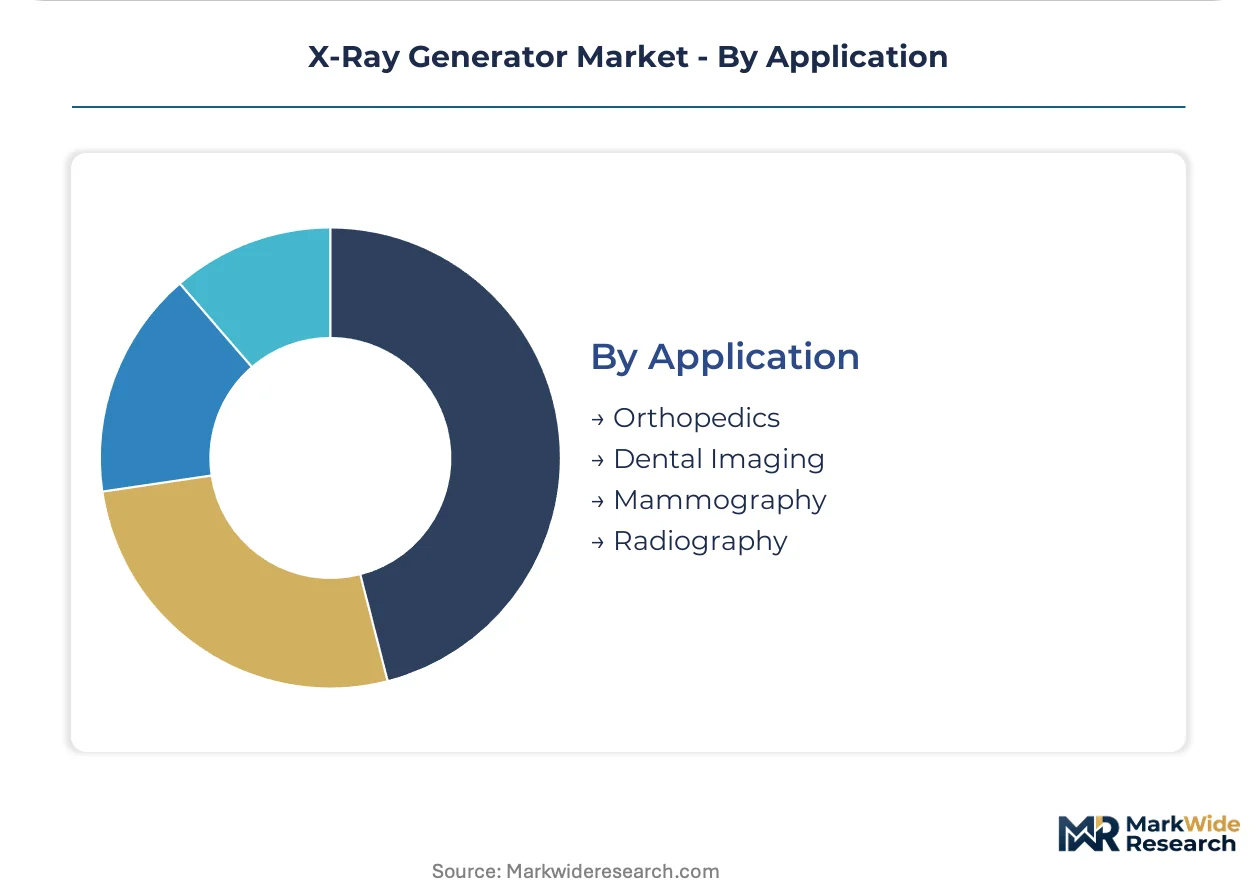
Application:
Clinical specialty requirements fragment tube loading profiles, filtration standards, and detector synchronization protocols.
- Orthopedics:High-output generators support weight-bearing extremity imaging and intraoperative fluoroscopy. US ambulatory surgery centers drive demand for compact C-arm integrated units.
- Dental Imaging:Low-dose panoramic and cephalometric systems operate at 60-90 kV with specialized collimation. South Korean manufacturing clusters supply these compact generators for global dental equipment OEMs.
- Mammography:Molybdenum or rhodium target tubes require precise kV stability for soft-tissue contrast optimization. EU breast screening program tenders mandate dose tracking compliance that favors high-frequency architectures.
- Radiography:General diagnostic chest and abdominal imaging represents the volume base with standardized 125-150 kV capability. Australian regional hospitals prioritize these workhorse installations for remote community coverage.
Radiography leads procedure volumes today; mammography applications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized high-voltage engineering talent concentrates in Germany's industrial belt, anchoring European radiology infrastructure renewal while Japanese precision electronics clusters and US hospital procurement networks shape demand trajectories across distinct regulatory environments.
United States
Academic medical centers in Boston and Houston drive specification toward AI-enabled exposure automation systems. FDA 510(k) clearance pathways determine market access timelines for new generator architectures entering hospital procurement cycles. Cleveland Clinic and Mayo Clinic networks anchor enterprise contract negotiations bundling generators with PACS integration.
Germany
Radiology infrastructure renewal accelerates in university hospitals across Bavaria and North Rhine-Westphalia as EU MDR compliance deadlines approach. Siemens Healthineers anchors domestic manufacturing capacity in Erlangen and Forchheim. German notified bodies report substantial backlog increases for radiology device submissions as legacy certificates expire.
Japan
Space-constrained urban hospitals in Tokyo and Osaka favor mobile generator configurations for bedside intensive care imaging. METI industrial standards influence global high-voltage engineering specifications through precision electronics clusters in Nagoya. Specialized dielectric suppliers concentrate in Kanagawa Prefecture, creating geographic chokepoints for high-voltage cable procurement.
China
Government procurement programs target primary care network expansion in Sichuan and Shandong provinces with entry-level fixed-frequency systems. NMPA device classification determines import substitution timelines for domestic generator manufacturers. Yangtze River Delta electronics clusters in Suzhou and Wuxi develop silicon carbide power electronics for next-generation compact architectures.
Brazil
Diagnostic chains in São Paulo and Rio de Janeiro continue specifying conventional line-frequency transformers where capital constraints override efficiency premiums. ANVISA regulatory harmonization with EU MDR standards shapes quality management system certification requirements. Companion animal veterinary imaging networks in Minas Gerais underpenetrate relative to human healthcare infrastructure.
X-Ray Generator Market Competitive Landscape
Top-tier vendors anchor integrated imaging platform supply, while independent high-voltage specialists and regional fabricators occupy differentiated tiers. The vendor base stratifies across three strategic archetypes: multinational health technology conglomerates with captive generator divisions, specialized high-voltage engineering houses focused on OEM integration, and emerging-market manufacturers serving cost-sensitive procurement segments. Dominant competitive moves include backward integration into power electronics semiconductor sourcing and strategic partnerships with artificial intelligence software vendors for exposure automation capabilities.
Within the integrated platform tier, Siemens Healthineers and GE Healthcare exemplify multinational health technology conglomerates that bundle generator procurement with enterprise imaging system contracts. Spellman High Voltage Electronics Corporation occupies a distinct position as an independent high-voltage engineering specialist serving OEM integration channels without competing at the system level. These three anchors represent the structural segmentation between platform-integrated and component-supplier competitive positions.
| Leading Market Players |
|---|
| Spellman High Voltage Electronics Corporation |
| Siemens Healthineers |
| Communications & Power Industries LLC |
| GE Healthcare |
| COMET Group |
| DRGEM Corporation |
| Philips Healthcare |
| Teledyne ICM |
| Innomed Medical |
| Others |
Value Network & Pricing Analysis
Family-owned German precision engineering houses anchor high-voltage transformer winding capacity, translating generational technical debt into pricing power over hospital procurement committees while constraining margin compression for commodity fixed-frequency units.
Pricing Analysis
The bundled-vs-unbundled service split separates premium high-frequency architectures from stripped fixed-installation hardware. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification grade and after-sales service bundling intensity. Cost compression in the economy tier intensifies because Brazilian diagnostic chains prioritize capital outlay minimization over dose efficiency. Independent service organizations exhibit highest price sensitivity; integrated health systems least.
Supply Chain Analysis
Domestic-content mandates in China's NMPA procurement programs are reshaping sourcing patterns for silicon carbide power electronics. Transformer winding materials draw from Germany, Japan, and China; specialized dielectric cable feeds from Kanagawa Prefecture and Bavaria. Single-source vulnerability concentrates in high-voltage cable suppliers. Distribution runs through OEM integration channels and independent high-voltage engineering houses serving radiography equipment manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where EU MDR compliance deadlines force hospital procurement toward premium high-frequency specifications with superior dose reproducibility.
For Market Incumbents: Lock in service-network density across North American diagnostic centers to defend against independent service organization disintermediation. Prioritize backward integration into silicon carbide semiconductor sourcing to secure wide-bandgap power electronics supply. ISO 13485 certification investment functions as the primary defensive moat excluding emerging-market entrants from OECD tender participation. For New Entrants and Emerging Players: Independent high-voltage engineering specialists offer the most penetrable channel for OEM integration without competing at the full imaging system level. Veterinary imaging networks in Brazil and Mexico present white-space expansion where human healthcare infrastructure saturation has not occurred. Target companion animal diagnostic chains with portable generator configurations emphasizing transportability over maximum output capacity. For Investors and Strategic Acquirers: Valuations sit cheapest among independent high-voltage component suppliers lacking captive imaging platform integration. Long-term viability hinges on software-configurable control architectures migrating from hardware-defined systems. Watch FDA 510(k) parallel review pathway utilization rates as inflection indicator for domestic manufacturer time-to-revenue compression.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Power Electronics Integration | Wide-bandgap semiconductors enable compact high-voltage switching that reduces generator thermal load and footprint. |
| AI-Enabled Exposure Automation Development | Deep learning models predicting optimal kV and mAs settings from patient body habitus data automate technologist workflow. |
| EU MDR Clinical Evidence Investment | Prospective imaging studies demonstrating diagnostic equivalence satisfy notified body backlog demands for radiology device submissions. |
| Independent Service Organization Partnership | Maintenance contract capture previously held by original equipment manufacturers expands recurring revenue streams. |
| Veterinary Imaging Platform Extension | Companion animal diagnostic chains in Latin American markets underpenetrate relative to human healthcare infrastructure maturity. |
Research Methodology
Multiple input streams — primary interviews with hospital purchasing committees, biomedical engineers, and GPO contracts managers; secondary validation through FDA 510(k) filings, EU MDR submission databases, and hospital procurement records; and trade data from German notified bodies — were reconciled through bottom-up and top-down triangulation across the analysis window.
Historical shipment patterns were cross-referenced against expert panel inputs to model volume and value outputs across product type, technology architecture, end-user concentration, and application specialty dimensions. CAGRs were derived from segmented growth trajectory analysis incorporating silicon carbide adoption curves and EU MDR compliance deadline impacts on replacement cycles.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to copper and ferrite core commodity volatility, high-voltage engineering talent scarcity, and emerging economy regulatory harmonization pace. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Medical Carts Market
Medical Equipment
Nuclear Medicine Equipment Market
Medical Equipment
Electric Bed Market
Medical Equipment
MRI Transport Market
Medical Equipment
Automated Dialysis Concentrated Production Systems Market
Medical Equipment
Surgical Generators Market
Medical Equipment
Next Generation Centrifuge Market
Medical Equipment
North America Durable Medical Equipment Market
Medical Equipment
Life Support Systems Market
Medical Equipment
Global Countertop Platelet Incubator Market
Medical Equipment
Brazil Massage Equipment Market
Medical Equipment
Medical CO2 Carboxytherapy Machine Market
Medical Equipment
Medical Equipment Leasing Market
Medical Equipment
Cell Washer Market
Medical Equipment
Global Examination Lights Market
Medical Equipment
Global Medical Gas Analyzer Market