
 Carboxy Therapy Market | 2026-2036
Carboxy Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Carboxy Therapy Market Outlook
Medical-grade device certification is redrawing competitive boundaries in the carboxy therapy market. Alma Lasers leverages its laser-aesthetic crossover expertise to sustain premium positioning across European and Middle Eastern clinics. Beijing Jontelaser Technologies anchors cost-efficient manufacturing for Asian markets, while DTA Medical specializes in precision gas flow regulators that differentiate its platform from commodity injectors.
Carboxy therapy involves the therapeutic administration of carbon dioxide gas beneath the skin or into target tissues to stimulate oxygenation, neovascularization, and metabolic activity; devices typically regulate flow rates between 20-80 mL/min with subcutaneous needles ranging 30-32 gauge for controlled micro-depot formation. The aesthetic treatment application dominates current revenue as cellulite reduction protocols command recurring patient visits, while wound healing represents the fastest-growing segment where chronic diabetic ulcer management drives hospital procurement of combination therapy systems. Device-based delivery holds mature margin pools due to capital equipment financing structures, though injectable consumables generate steadier recurring revenue streams across high-volume clinic networks.
FDA premarket notification requirements shape device commercialization timelines for US manufacturers, while the EU MDR and CE marking obligations impose clinical evidence standards that filter smaller European competitors from premium tiers. Brazil's ANVISA registration pathway for gas delivery systems creates a distinct regulatory gateway for Latin American market access. Stakeholders must monitor evolving equivalence determinations between pure CO2 sources and blended gas formulations as regulators reassess safety thresholds.
Market Dynamics
FDA premarket validation timelines for subcutaneous gas delivery devices are compressing commercialization windows for new equipment entrants while physician-operated clinics in Brazil and the United States drive procurement concentration toward certified platforms.
Growth Catalysts
- EU MDR clinical evidence standards:Stricter CE marking obligations for gas flow regulators are filtering commodity injectors from premium tiers, elevating manufacturers with validated precision engineering.
- Chronic diabetic ulcer protocols:Hospital procurement of combination therapy systems for wound healing is accelerating device adoption beyond aesthetic applications.
- Brazilian aesthetic procedure density:Physician-operated clinics in São Paulo and Rio de Janeiro sustain among the highest global treatment volumes, generating recurring consumable demand for carboxy therapy platforms.
Market Restraints
- Medical-grade CO2 supply concentration:Industrial gas suppliers in Germany and the United States control pharmaceutical-grade carbon dioxide sourcing, creating input cost volatility for device manufacturers.
- FDA 510(k) pathway friction:Subcutaneous gas delivery classification as Class II medical devices extends premarket notification timelines, delaying revenue recognition for new entrants.
- Topical cellulite treatment substitution:Radiofrequency and acoustic wave platforms compete for the same patient visit budgets in dermatology clinics.
Strategic Opportunities
- Home-use device regulatory pathway:ANVISA in Brazil and FDA in the United States are evaluating over-the-counter classifications for low-flow carboxy therapy systems, opening direct-to-consumer channels.
- Combination laser-carboxy platforms:Convergence with fractional laser technology enables bundled procedure pricing in Middle Eastern aesthetic chains.
- Chronic wound care expansion:Hospital outpatient departments in India and China represent underpenetrated procurement channels for metabolic stimulation therapies.
Industry Challenges
- Micro-needling certification gaps:Subcutaneous gas administration requires specialized training beyond standard aesthetic injector credentials, constraining clinic staffing scalability.
- Equipment financing complexity:Capital expenditure requirements for precision flow regulators strain independent dermatology practice cash flows.
- Legacy device interoperability:Integration of new gas delivery systems with existing electronic medical records and practice management software creates implementation friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carboxy Therapy Market |
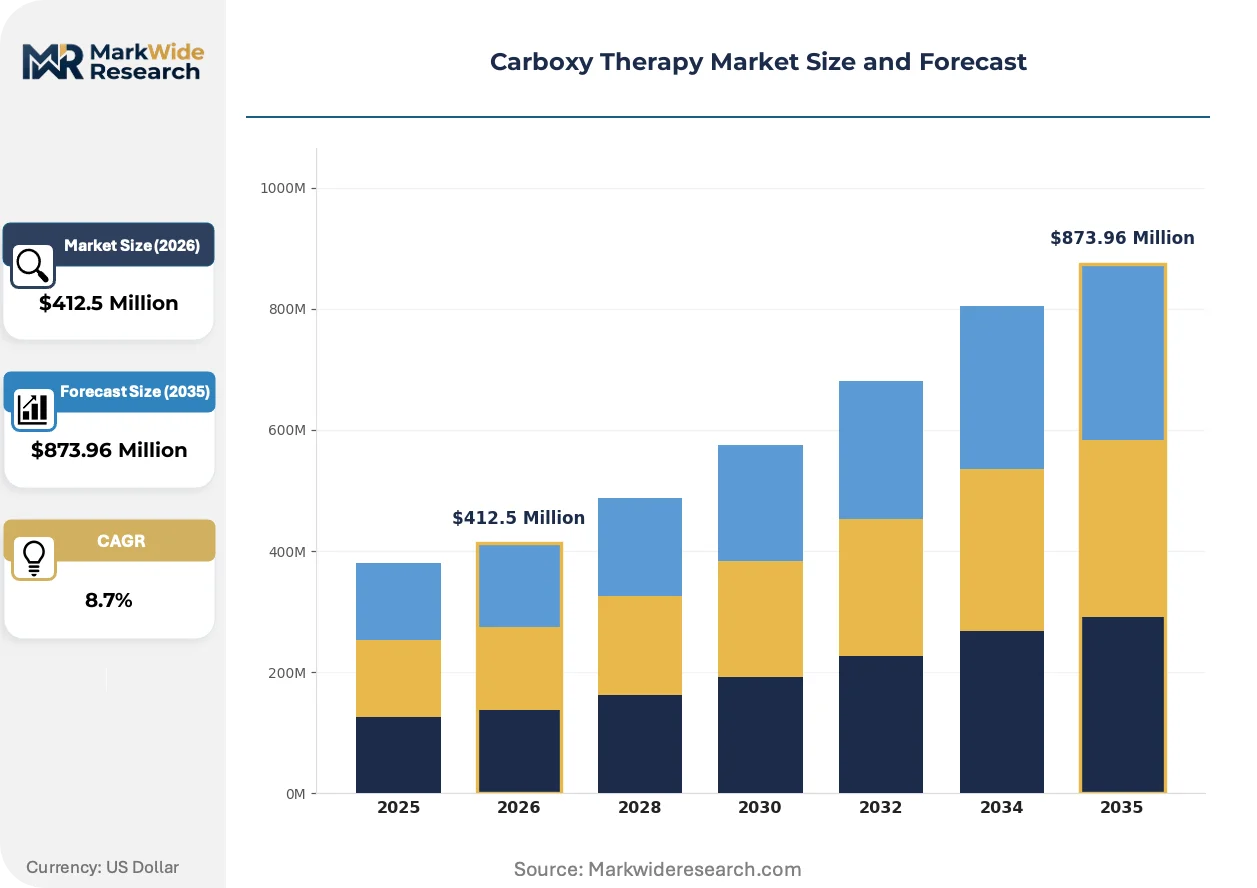
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Device, Combination Therapy, Accessories End User: Clinics, Spas, Hospitals, Home Care Application: Aesthetic Treatment, Pain Management, Cellulite Reduction, Wound Healing Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Topical |
| Companies Covered | DTA Medical, Alvi Prague, Cosmopro, Beijing Jontelaser Technologies, Alma Lasers, Kastner-Praxisbedarf, MBE Medical Divisions, Carbossiterapia Italiana, Mezopharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carboxy Therapy Market Strategic Shifts
Digital flow control architectures and blended gas formulations are redrawing device differentiation boundaries while regulatory equivalence determinations reshape competitive access across major markets.
Micro-processor regulated injectors with real-time pressure feedback are decomposing the traditional mechanical valve market. Dermatology chains in the United States and Brazil are standardizing on these platforms within eighteen-month equipment refresh cycles. The technology is decomposing margin pools for legacy spring-loaded flow regulators while enabling procedure outcome documentation for reimbursement appeals.
The EU MDR recast of medical device classification rules is elevating clinical evidence requirements for gas delivery systems previously grandfathered under the MDD. Manufacturers must now submit post-market surveillance data for CE marking renewals, compressing product lifecycle economics. German and French notified bodies are prioritizing review queues for combination therapy platforms, disadvantaging pure-play carboxy device specialists.
Patients are requesting outcome-guaranteed treatment packages rather than per-session pricing. Aesthetic clinic networks in Dubai and São Paulo are responding with subscription models bundling carboxy therapy with lymphatic drainage and compression garments. This behavioral shift is most visible in Brazil, where physician-operated chains compete for recurring revenue streams against med-spa aggregators.
Carboxy Therapy Market Segmentation
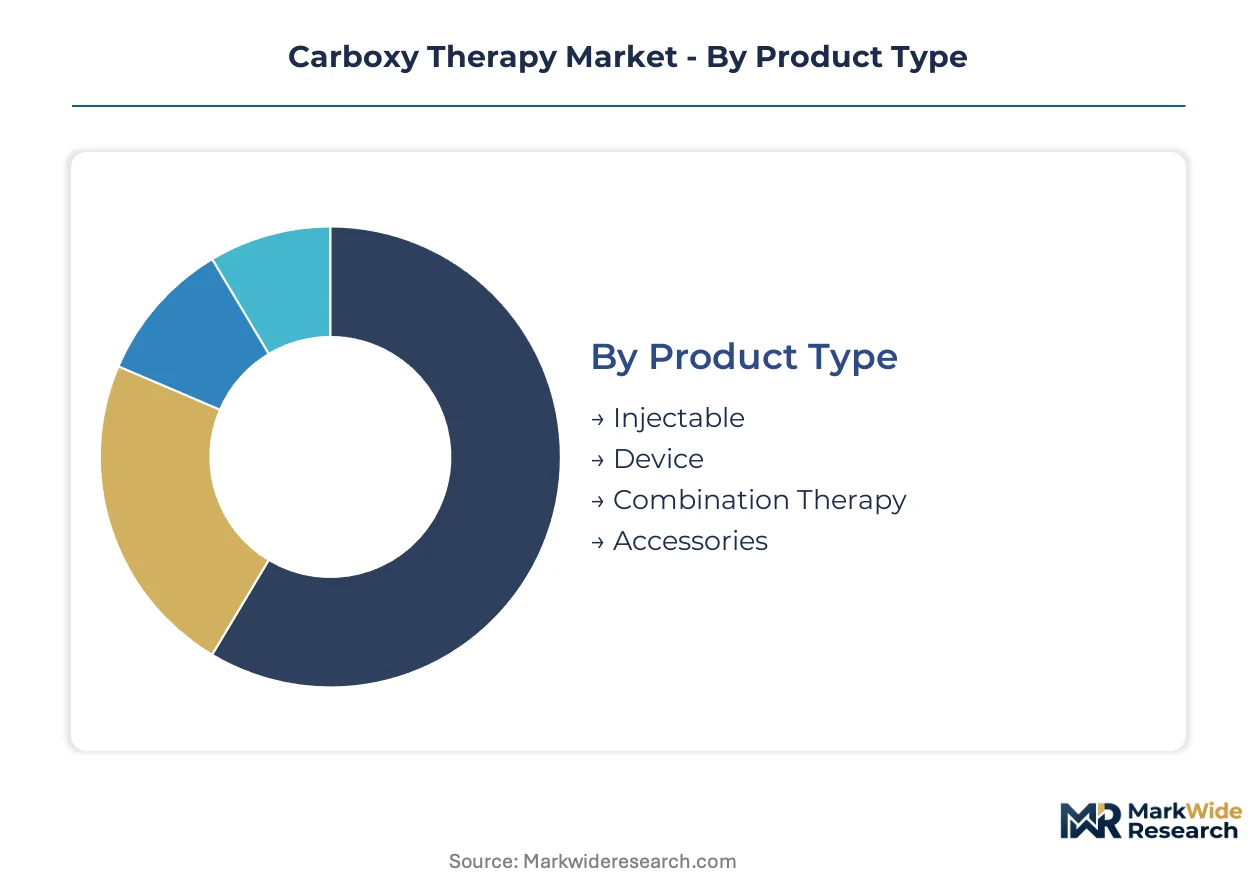
Segmentation in the carboxy therapy market reveals distinct margin profiles and regulatory exposure across delivery formats. Product architecture and end-user concentration determine which segments face displacement from competing modalities.
Product Type:
Injectable consumables face the strongest substitution pressure from radiofrequency and acoustic wave platforms, while capital equipment segments defend position through certification barriers.
- Injectable:Pharmaceutical-grade carbon dioxide ampules and pre-filled syringes enable precise micro-depot formation at 30-32 gauge needle specifications. Demand concentrates in Brazilian physician-operated clinics where recurring consumable purchases generate steady revenue streams against per-session pricing competition from energy-based devices.
- Device:Precision flow regulators with micro-processor architectures deliver 20-80 mL/min rates with real-time pressure feedback. Hospital procurement in the United States and Germany favors these platforms for chronic wound protocols, though FDA 510(k) timelines compress commercialization windows for new entrants.
- Combination Therapy:Integrated laser-carboxy platforms bundle fractional resurfacing with gas delivery for Middle Eastern aesthetic chains.
- Accessories:Disposable tubing sets and filter cartridges attach to capital equipment bases.
Injectable consumables anchor the volume base while combination therapy platforms gain share at the steepest rate.
End User:
Cost tier stratification separates premium-certified clinics from budget spa aggregators, with reimbursement access defining procurement authority.
- Clinics:Physician-operated dermatology and aesthetic medicine practices in São Paulo and Rio de Janeiro sustain the highest global treatment densities. These facilities prioritize ANVISA-certified platforms with validated training protocols for subcutaneous gas administration.
- Hospitals:Outpatient wound care departments in the United States and Germany procure combination therapy systems for diabetic ulcer management. EU MDR clinical evidence requirements filter commodity injectors from hospital tenders, elevating manufacturers with post-market surveillance data.
- Spas:Non-physician med-spa aggregators compete on price-per-session with lower-flow devices.
- Home Care:Direct-to-consumer channels await FDA and ANVISA over-the-counter classification rulings for low-flow systems.
Clinics anchor the volume base while hospitals expand share through chronic care reimbursement pathways.
Application:
Volume concentration in aesthetic procedures contrasts with expansion velocity in metabolic stimulation therapies.
- Aesthetic Treatment:Cellulite reduction and stretch mark protocols command recurring patient visits with subscription bundling in Dubai and São Paulo. Dermatology chains refresh equipment on eighteen-month cycles, decomposing margin pools for legacy mechanical valve systems.
- Wound Healing:Chronic diabetic ulcer management drives hospital procurement beyond cosmetic applications. German and French notified bodies prioritize review queues for metabolic stimulation platforms, accelerating CE marking for combination therapy devices.
- Cellulite Reduction:Dedicated protocols within aesthetic treatment use higher flow rates for adipose tissue targeting.
- Pain Management:Intramuscular delivery for musculoskeletal conditions remains underdeveloped relative to aesthetic applications.
Aesthetic treatment anchors the volume base while wound healing climbs the fastest through hospital procurement expansion.
Delivery Mode:
Regulatory classification intensity varies by tissue penetration depth, with subcutaneous routes facing the tightest premarket validation.
- Subcutaneous:Micro-depot formation beneath the dermis stimulates neovascularization for cellulite and skin rejuvenation protocols. FDA Class II medical device classification extends premarket notification timelines, delaying revenue recognition for new gas delivery entrants relative to topical alternatives.
- Intravenous:Systemic CO2 administration for metabolic modulation requires specialized training beyond standard aesthetic injector credentials.
- Intramuscular:Deeper tissue targeting for pain management applications carries higher safety threshold requirements.
- Topical:Transdermal gas diffusion systems face lower regulatory barriers but reduced efficacy claims.
Subcutaneous delivery anchors the volume base while intravenous protocols expand through specialized metabolic clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in medical-grade carbon dioxide equipment tilt toward net-importing markets in Latin America and the Middle East, while Germany and the United States sustain trade surpluses in precision flow regulators. Brazil absorbs the largest share of cross-border device shipments as physician-operated clinics expand service menus.
Brazil
Physician-operated aesthetic clinics in São Paulo and Rio de Janeiro drive the highest treatment volumes globally for cellulite and stretch mark protocols. ANVISA registration pathways for gas delivery systems create a distinct regulatory gateway that filters uncertified equipment from premium procurement channels. São Paulo's Jardins district concentrates flagship clinic networks that refresh devices on compressed eighteen-month cycles.
United States
Dermatology chains across Florida and California are standardizing on micro-processor regulated injectors with real-time pressure feedback for outcome documentation. FDA 510(k) premarket notification requirements for Class II subcutaneous gas delivery devices extend commercialization timelines for new equipment entrants. Los Angeles and Miami metropolitan areas anchor the densest clinic networks pursuing subscription-based patient retention models.
Germany
Hospital outpatient departments in Berlin and Munich procure combination therapy systems for chronic diabetic ulcer management under metabolic stimulation protocols. EU MDR clinical evidence standards for CE marking renewal filter commodity injectors from hospital tenders, elevating manufacturers with validated post-market surveillance data. The Rhine-Ruhr industrial corridor hosts pharmaceutical-grade carbon dioxide suppliers that control input costs for downstream device manufacturers.
United Arab Emirates
Aesthetic clinic networks in Dubai bundle carboxy therapy with lymphatic drainage and compression garments under outcome-guaranteed subscription pricing. MOHAP device registration requirements align with EU MDR evidence standards, compressing access for manufacturers without established European certification. Dubai Healthcare City clusters premium-tier providers competing for medical tourism flows from Saudi Arabia and Egypt.
South Korea
MFDS regulatory frameworks for subcutaneous gas delivery devices emphasize clinical validation for neovascularization claims, extending review timelines relative to topical alternatives. Seoul Capital Area dermatology chains are piloting combination laser-carboxy platforms that enable bundled procedure pricing against standalone energy-based competitors. Gangnam district aesthetic aggregators drive consumable volume through high-frequency patient visit protocols.
Carboxy Therapy Market Competitive Environment
Listed leaders compete with private specialists across certification tiers, with publicly traded laser-aesthetic crossover firms defending premium positioning through regulatory validation depth while family-owned European device fabricators occupy mid-market niches. The vendor base stratifies across three archetypes: precision engineering specialists with validated gas flow regulators, diversified energy-based platform vendors leveraging aesthetic crossover expertise, and cost-efficient Asian manufacturers anchoring volume-tier procurement. Consolidation pressure concentrates in the combination therapy segment where laser-carboxy convergence rewards integrated platform development, while standalone injector specialists face margin compression from radiofrequency substitution.
Among precision engineering specialists, DTA Medical exemplifies the validated-flow-regulator archetype through its focus on gas administration precision. Beijing Jontelaser Technologies occupies the cost-efficient manufacturing position for Asian market access. Alma Lasers represents the laser-aesthetic crossover model, leveraging diversified energy-based platform expertise to sustain premium-tier positioning across Middle Eastern and European clinic networks.
| Leading Market Players |
|---|
| DTA Medical |
| Alvi Prague |
| Cosmopro |
| Beijing Jontelaser Technologies |
| Alma Lasers |
| Kastner-Praxisbedarf |
| MBE Medical Divisions |
| Carbossiterapia Italiana |
| Mezopharma |
| Others |
Value Chain & Pricing Dynamics
Take-or-pay contracts for pharmaceutical-grade carbon dioxide lock in supply access for Brazilian and German device manufacturers while anchoring price visibility against industrial gas supplier concentration. These arrangements tether procurement costs to named industrial corridors in the Rhine-Ruhr region and Gulf Coast petrochemical clusters.
Pricing Analysis
Physician-operated clinics anchor three-tier pricing structure across premium, standard, and economy levels based on ANVISA certification grade and bundled training protocols. Price differentiation separates FDA 510(k)-validated platforms from CE-marked commodity injectors, with premium tiers commanding financing-inclusive packages. Cost compression in the consumables segment intensifies as radiofrequency platforms compete for per-session patient budgets. Independent dermatology practices in São Paulo exhibit highest price sensitivity, while hospital outpatient departments in Germany demonstrate lowest sensitivity due to reimbursement-protected procurement authority.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for micro-processor components sourced from South Korean foundries. Manufacturing concentration in Germany, the United States, and China feeds from pharmaceutical-grade CO2 refineries, precision flow regulator machining facilities, and disposable needle fabrication plants. Single-source vulnerability concentrates in German industrial gas suppliers controlling medical-grade carbon dioxide purification. Distribution runs through ANVISA-certified import channels for Brazilian clinic networks and FDA-registered device distributors for United States hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The carboxy therapy market is recovering from regulatory compression cyclicality as EU MDR recast timelines stabilize and hospital procurement for diabetic ulcer protocols accelerates.
For Market Incumbents: Consolidate certification depth against radiofrequency substitution threats by accelerating post-market surveillance data collection for CE marking renewals. Backward integration into pharmaceutical-grade CO2 supply partnerships with Rhine-Ruhr suppliers defends margin position against input cost volatility. Priority capacity addition in São Paulo clinic networks captures recurring consumable demand from eighteen-month equipment refresh cycles. For New Entrants and Emerging Players: ANVISA fast-track registration for low-flow home-use devices opens direct-to-consumer channels ahead of FDA over-the-counter classification rulings. Target hospital outpatient departments in India and China for chronic wound care expansion where metabolic stimulation therapy procurement remains underpenetrated. Go-to-market angle should emphasize combination laser-carboxy platform bundling for Middle Eastern aesthetic chains seeking procedure differentiation. For Investors and Strategic Acquirers: Precision engineering specialists with validated gas flow regulators offer acquisition exposure to EU MDR clinical evidence tiering. Long-term viability hinges on chronic care reimbursement pathway expansion beyond cosmetic applications. Watch for FDA equivalence determinations between pure CO2 and blended gas formulations as inflection indicator for device platform obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Fast-Track Registration | Accelerates Brazilian market access for home-use device categories ahead of FDA timelines. |
| Combination Therapy Platform Development | Enables bundled procedure pricing for Dubai aesthetic chains competing for medical tourism flows. |
| Post-Market Surveillance Investment | Satisfies EU MDR clinical evidence requirements for CE marking renewal in German hospital tenders. |
| Pharmaceutical-Grade CO2 Supply Partnership | Secures input cost stability against Rhine-Ruhr industrial gas supplier concentration. |
| Hospital System Partnership | Unlocks chronic diabetic ulcer procurement channels in United States outpatient wound care departments. |
Study Parameters
Initial hypotheses were tested against primary input from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and dermatology clinic operators and refined through secondary validation against FDA 510(k) filings, ANVISA registration databases, EU MDR notified body decisions, and hospital procurement contract disclosures. Bottom-up demand modeling across clinic, hospital, spa, and home care end users triangulated with top-down market sizing from device shipment tracking and consumable volume estimates.
Variance decomposition across product type, end user, application, and delivery mode segments structured the analytical framework over the projection horizon. CAGRs were derived from procedure volume elasticity models and equipment replacement cycle analysis. Industry-specific forecast inputs included eighteen-month refresh cycle timing for United States dermatology chains and ANVISA registration approval velocity for Brazilian market entrants.
Decision-makers should treat outputs as directional under stable regulatory equivalence assumptions for pure versus blended CO2 formulations; material deviation would warrant model refresh. Specific risk factors include FDA reclassification of subcutaneous gas delivery devices and industrial gas supplier consolidation in Germany. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
North America Non-Invasive Aesthetic Treatment Market
Aesthetic Medicine
Spain Facial Aesthetics Market
Aesthetic Medicine
Global Stretch Marks Treatment Market
Aesthetic Medicine
Global Aesthetic Fillers Market
Aesthetic Medicine
Professional Beauty Services Market
Aesthetic Medicine
Middle East and Africa Aesthetic Dermatology Market
Aesthetic Medicine
Body Contouring Market
Aesthetic Medicine
Middle East and Africa Dermal Fillers Market
Aesthetic Medicine
Aesthetic Medicine Market
Aesthetic Medicine
Italy Aesthetic Market
Aesthetic Medicine
Global Aesthetic Dermatology Market
Aesthetic Medicine
Platysmaplasty Treatment Market
Aesthetic Medicine
Radio Frequency Beauty Equipment Market
Aesthetic Medicine
Asia-Pacific Aesthetic Dermatology Market
Aesthetic Medicine
Asia-Pacific Facial Aesthetics Market
Aesthetic Medicine
Aesthetic Surgery Procedures Market