
 Asia-Pacific Medical Carts Market | 2026-2036
Asia-Pacific Medical Carts Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Medical Carts Market Analytics
Preventive maintenance subscriptions and software-defined fleet management is rebalancing vendor revenue models away from one-time hardware sales. Advantech Co Ltd leverages its industrial computing heritage to dominate embedded PC modules for cart integration. Capsa Healthcare sustains competitive position through specialized medication cart configurations for acute care workflows. Ergotron, Inc. anchors its regional presence with adjustable mounting systems that address ergonomic compliance in extended nursing shifts.
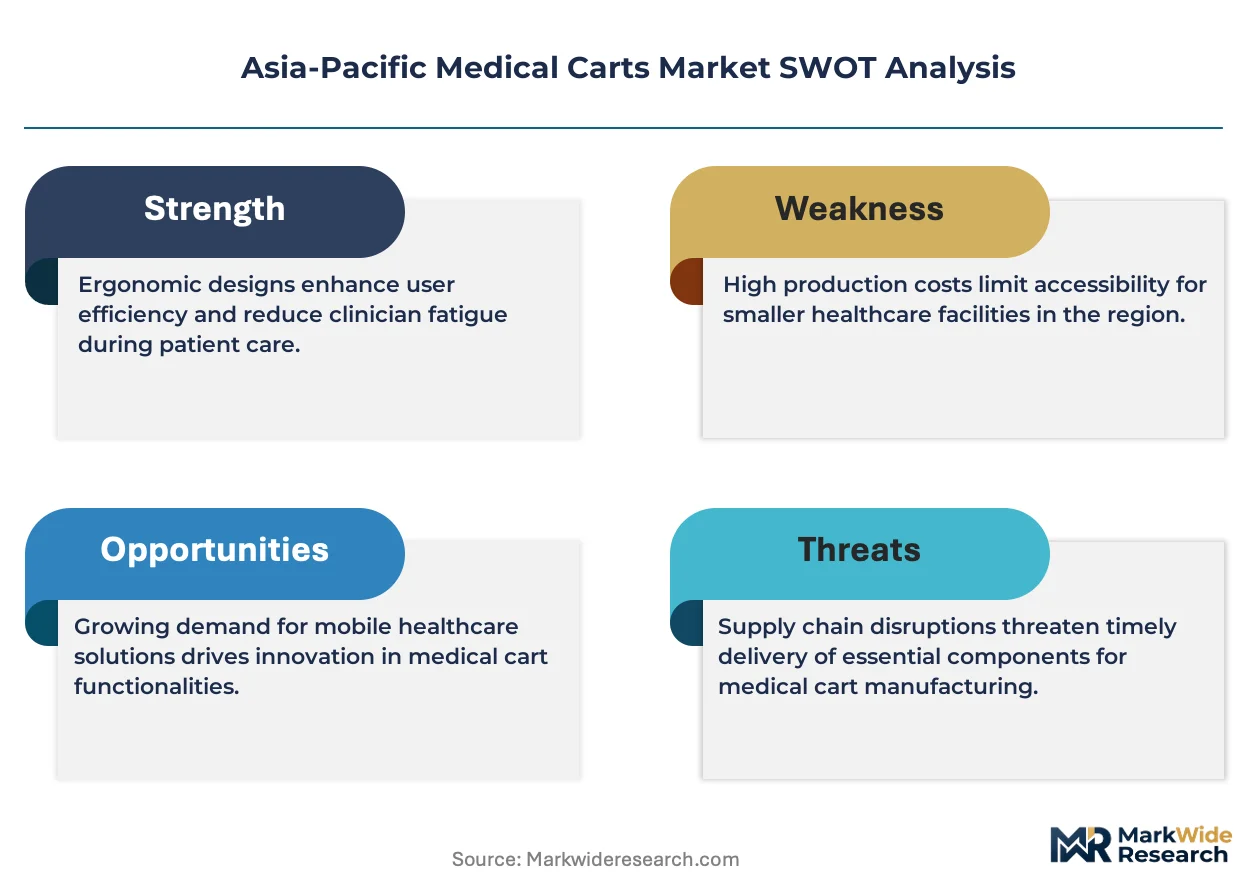
Asia-Pacific medical carts are mobile workstation platforms integrating computing hardware, power systems, and clinical supply storage for bedside care delivery. Units typically incorporate hot-swappable battery systems, antimicrobial surface coatings, and height-adjustable frames to support continuous clinical workflows across shift changes. Medication carts command the largest revenue pool due to narcotics security requirements and barcode medication administration integration. Electric delivery mode units represent the fastest-expanding category as hospital infrastructure upgrades support powered mobility across expanded campus footprints. Stainless steel construction retains preference in infection-control-intensive settings despite aluminum's weight advantages for manual transport.
Japan's PMDA medical device quality management standards and Australia's TGA therapeutic goods framework collectively shape product certification requirements for regional market access. China's NMPA implements increasingly stringent electrical safety and electromagnetic compatibility testing that foreign manufacturers must satisfy for import approval. India's CDSCO and BIS standards create dual compliance pathways that domestic producers navigate more efficiently than offshore competitors. Stakeholders must monitor how each country's national pharmaceutical regulator evolves software validation requirements as carts incorporate more connected diagnostic peripherals.
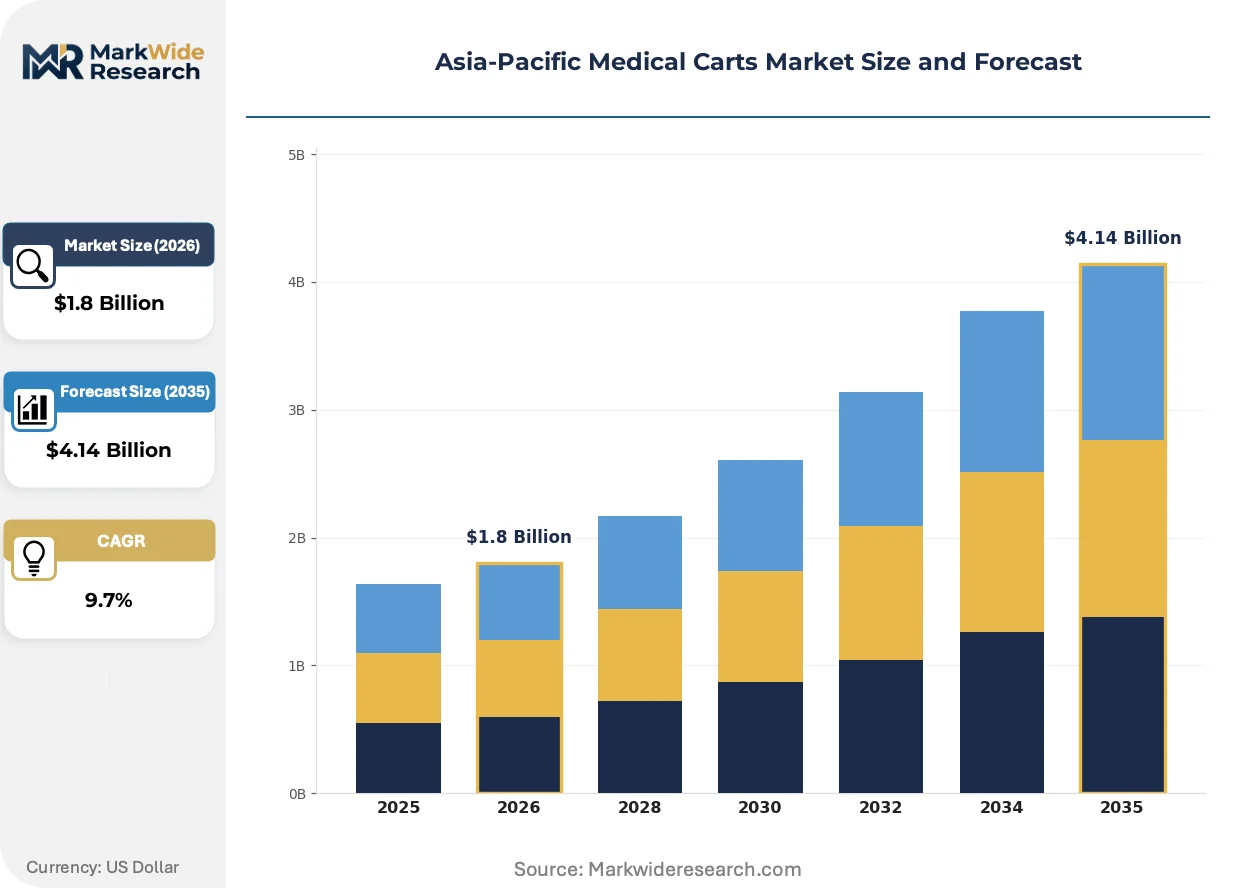
Market Dynamics
Hospital digitization programs across China, Japan, and Australia are consolidating bedside computing infrastructure around integrated mobile platforms. The shift from stationary workstations to powered, network-connected carts is compressing replacement cycles and elevating software compatibility requirements above hardware durability in procurement scoring.
Growth Catalysts
- India's PLI scheme:Production-linked incentives for medical device manufacturing are accelerating localized assembly of cart frames, battery modules, and castor systems. Domestic producers gain cost advantages against import-dependent competitors.
- Barcode medication administration mandates:Hospital accreditation standards across Australia and South Korea require integrated medication verification at point-of-care. Carts with locked narcotics compartments and wireless scanner mounts satisfy these protocols.
- Hot-swappable lithium battery systems:Elimination of plug-in charging downtime supports continuous 24-hour clinical workflows. Facilities prioritize units with standardized battery interfaces compatible across fleet vendors.
Market Restraints
- Aluminum alloy price volatility:Input cost swings for lightweight frame materials compress margin predictability for mid-tier manufacturers. Stainless steel alternatives add 15-20% transport burden for manual-push units.
- Embedded PC module supply concentration:Taiwan-based industrial computing suppliers control 70% of regional motherboard and fanless PC supply for cart integration. Geopolitical friction elevates delivery risk for China-assembled finished goods.
- NMPA electrical safety testing complexity:China's electromagnetic compatibility certification requires 6-12 month validation timelines for foreign-designed power systems. Domestic competitors navigate SAMR approval pathways more efficiently.
Strategic Opportunities
- Vietnam and Indonesia hospital construction:Greenfield medical facilities in Southeast Asian tier-two cities lack legacy infrastructure constraints. Deployments accept fully electric, software-defined cart fleets without retrofit compatibility burdens.
- Telemedicine cart configurations:Integration of high-definition cameras, bidirectional audio, and diagnostic peripheral mounts supports remote specialist consultations. Rural health networks in India and the Philippines represent unserved demand pools.
- Japan METI carbon-neutral procurement guidelines:Public hospital purchasing now weights lifecycle emissions in vendor selection. Carts with recyclable aluminum construction and energy-efficient DC power systems gain scoring advantages.
Industry Challenges
- Biomedical engineering technician shortages:Fleet maintenance for software-integrated carts requires IT-hardware hybrid skill sets. Australian and Singaporean health systems compete for limited qualified personnel against broader medical device sectors.
- Legacy nurse call system integration:Proprietary communication protocols in aging hospital infrastructure demand costly middleware development. Cart vendors absorb customization engineering or forfeit accounts to incumbent suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Medical Carts Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medication Carts, Procedure Carts, Utility Carts, Anesthesia Carts Delivery Mode: Manual, Electric, Hybrid, Gas-Operated End User: Hospitals, Clinics, Long-Term Care Facilities, Emergency Departments Material: Stainless Steel, Plastic, Aluminum, Wood |
| Companies Covered | Advantech Co Ltd, Capsa Healthcare, ITD GmbH, AFC Industries Inc, JACO Inc., Ergotron, Inc., Harloff Manufacturing Co., Medline Industries, Inc., Enovate Medical, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Medical Carts Market Evolving Landscape
Software-defined functionality is displacing fixed-purpose hardware configurations across Asia-Pacific medical cart deployments. Vendors now compete on firmware update cadence and API ecosystem breadth rather than frame durability alone.
Hot-swappable battery architecture is modularizing power system design across emergency, anesthesia, and medication cart categories. Japanese and Australian hospitals are standardizing on 24V lithium-iron-phosphate platforms that interoperate across three or more OEM fleets. This interoperability is compressing vendor lock-in and elevating third-party battery suppliers to strategic supply chain positions.
China's NMPA has tightened electromagnetic compatibility testing protocols for wireless-enabled medical devices, effective across all imported cart systems. The regulation forces foreign manufacturers to establish in-country testing partnerships or absorb 4-6 month certification delays. Premium cart vendors with Shanghai-based validation laboratories are capturing accelerated approval timelines that translate to first-mover positioning in tier-one city tenders.
Subscription-based fleet management contracts are displacing traditional capital purchase models in Australian and South Korean health networks. Procurement teams prioritize vendors offering predictive maintenance analytics and guaranteed uptime service level agreements. This shift concentrates account control with suppliers capable of regional spare parts warehousing and 4-hour response commitments across metropolitan hospital clusters.
Asia-Pacific Medical Carts Market Segmentation
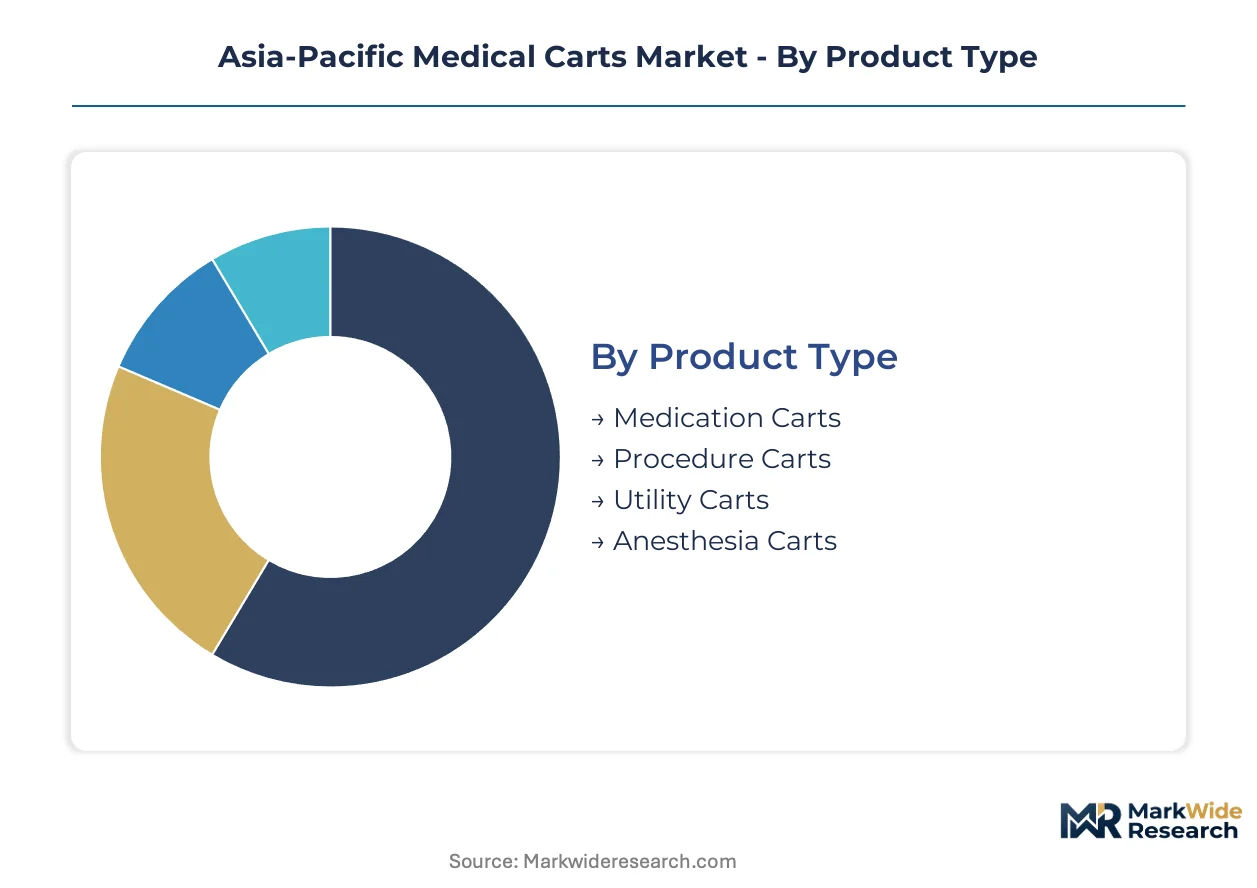
Medical cart procurement across Asia-Pacific stratifies sharply by clinical risk profile and infrastructure maturity. Certification pathways from Japan's PMDA, China's NMPA, and Australia's TGA create divergent compliance burdens that reshape segment economics and vendor selection criteria.
Product Type:
Medication carts face the heaviest regulatory scrutiny under narcotics control mandates, while anesthesia carts trigger electromagnetic compatibility testing under China's GB standards. Procedure and utility carts navigate lighter approval pathways.
- Medication Carts:Locked narcotics compartments with biometric access and barcode scanner integration dominate hospital specifications. Australia's TGA medication safety standards and South Korea's MFDS barcode administration mandates concentrate demand in tertiary facilities across Sydney, Seoul, and Shanghai.
- Procedure Carts:Modular drawer systems accommodate sterile supply organization for surgical preparation. China's tier-one hospitals in Beijing and Guangzhou prioritize units with integrated waste segregation compartments to meet MEE environmental compliance.
- Anesthesia Carts:Specialized configurations for perioperative medication management with volatile agent storage.
- Utility Carts:General-purpose transport for linens, records, and non-clinical supplies with minimal certification overhead.
Leading the category by volume: Medication Carts. Growing fastest: Anesthesia Carts.
Delivery Mode:
Power system selection tracks directly against hospital infrastructure investment cycles and nursing workforce availability. Electric units command premium positioning where 24-hour continuous operation is mandatory.
- Electric:Lithium-iron-phosphate battery platforms with standardized 24V interfaces enable hot-swap workflows. Japan's METI carbon-neutral procurement guidelines favor energy-efficient DC motor systems in public hospital tenders.
- Manual:Castor-based units dominate cost-constrained procurement in India's tier-two cities and Indonesia's expanding provincial hospital networks.
- Hybrid:Dual-mode systems switch between powered and manual operation for flexible deployment.
- Gas-Operated:Pneumatic lift mechanisms for heavy-load supply transport in warehouse and pharmacy settings.
Electric configurations claim the steepest expansion trajectory as China's NMPA streamlines powered medical device approvals for domestic assembly.
End User:
Facility type determines software integration depth and fleet management contract structures. Hospitals absorb subscription-based predictive maintenance; smaller settings favor capital purchase simplicity.
- Hospitals:Enterprise-grade deployments with nurse call system integration and EMR connectivity. Australia's tertiary networks in Melbourne and Brisbane standardize on API-compatible platforms for centralized fleet monitoring.
- Emergency Departments:Rapid-deployment configurations with crash cart functionality and defibrillator mounting. India's AIIMS facilities and Japan's university hospitals drive specification intensity for resuscitation-ready mobility.
- Clinics:Compact footprints for limited-space outpatient workflows with basic computing mount options.
- Long-Term Care Facilities:Height-adjustable frames and antimicrobial surfaces for extended resident contact environments.
Hospitals anchor absolute demand volume. Emergency Departments are climbing the fastest as trauma network expansion accelerates across Southeast Asia.
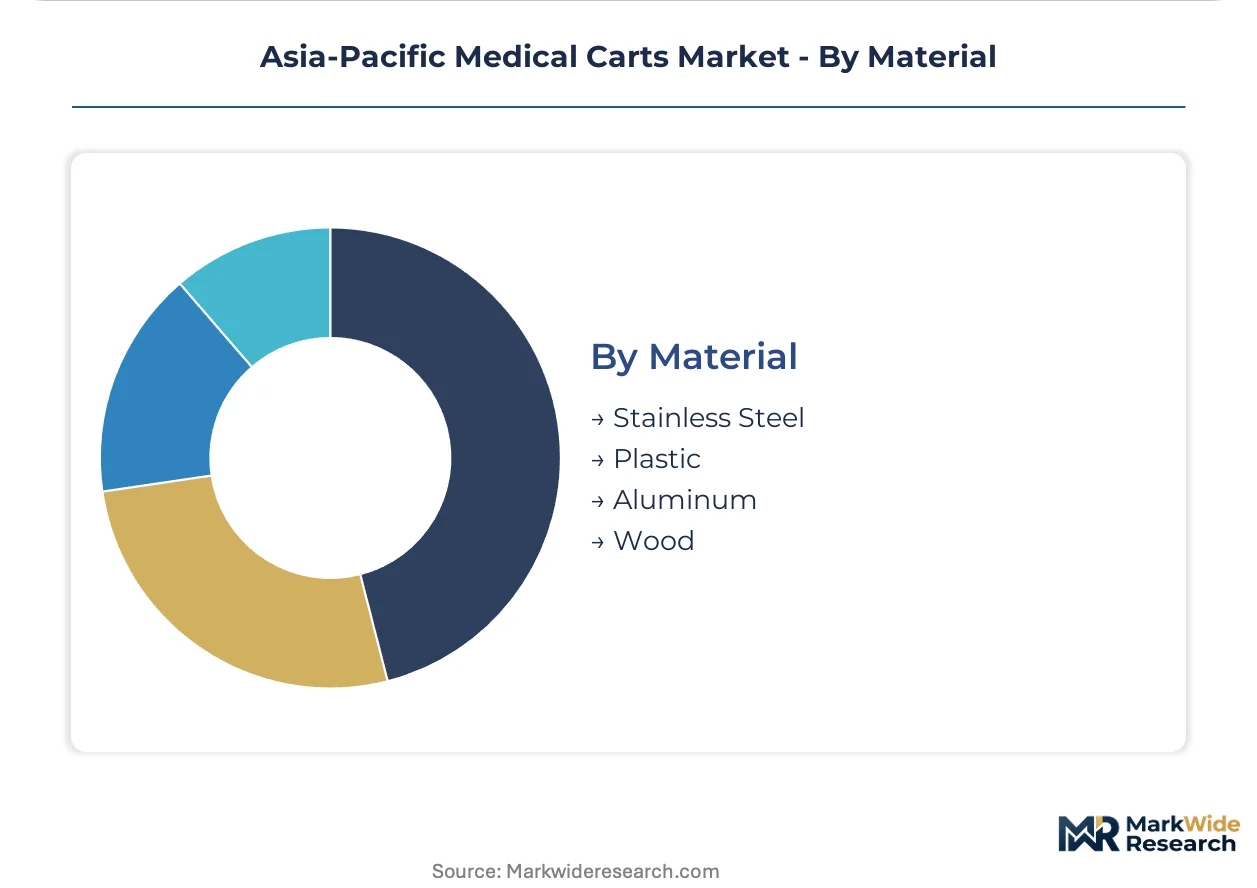
Material:
Frame composition trades infection control performance against transport ergonomics and lifecycle emissions scoring under Japan's green procurement frameworks.
- Stainless Steel:304-grade construction retains dominance in operating theaters and isolation units where sterilization protocols are non-negotiable. Australia's TGA infection control guidelines reinforce specification persistence despite weight penalties.
- Aluminum:Extruded alloy frames reduce manual-push burden by 15-20% versus steel alternatives. China's NMPA electrical safety testing applies additional grounding verification for conductive metal chassis in powered configurations.
- Plastic:Polymer construction for lightweight supply transport and corrosion-resistant pharmacy applications.
- Wood:Limited aesthetic deployments in administrative and hospitality-oriented healthcare settings.
Stainless Steel maintains volume leadership. Aluminum is gaining share fastest as recyclable construction aligns with METI carbon-neutral weighting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in China's industrial hubs while consumption spreads across mature hospital networks in Japan, Australia, and South Korea. India's PLI scheme is shifting component assembly toward domestic facilities. Southeast Asian greenfield hospitals absorb electric fleet deployments without legacy retrofit burdens.
China
Shanghai and Beijing tier-one hospitals drive demand for NMPA-certified powered carts with integrated computing platforms. The NMPA electromagnetic compatibility testing protocol extends foreign manufacturer approval timelines to 6-12 months. Domestic assemblers in Jiangsu and Zhejiang provinces capture accelerated SAMR pathways for hospital tenders.
Japan
Tokyo and Osaka metropolitan health networks prioritize METI carbon-neutral procurement scoring for recyclable aluminum construction. The PMDA medical device quality management standards enforce stringent software validation for connected diagnostic peripherals. Kanto region public hospitals weight lifecycle emissions above upfront capital costs in vendor selection.
India
AIIMS facilities and tier-two city hospital expansions fuel medication cart procurement with barcode administration integration. The CDSCO and BIS dual compliance framework advantages domestic producers over import-dependent competitors. Gujarat and Maharashtra manufacturing clusters leverage PLI incentives for localized battery module and frame assembly.
Australia
Melbourne and Brisbane tertiary networks standardize on API-compatible platforms for centralized fleet monitoring. The TGA therapeutic goods framework shapes medication safety specifications for locked narcotics compartments. Victoria and New South Wales health systems compete for limited biomedical engineering technicians against broader medical device sectors.
South Korea
Seoul metropolitan hospitals enforce MFDS barcode medication administration mandates at point-of-care. The national health insurance system's digitization program compresses replacement cycles for network-connected cart fleets. Gyeonggi province medical centers prioritize hot-swappable battery interoperability across multi-vendor deployments.
Asia-Pacific Medical Carts Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the Asia-Pacific medical carts market. Integrated hardware manufacturers with captive battery and frame production face margin pressure from specialized cart assemblers sourcing modular subsystems. Three archetypes dominate: industrial computing heritage players extending into medical platforms, dedicated healthcare furniture specialists, and diversified medical supply conglomerates with distribution scale. Competitive moves concentrate on predictive maintenance subscription models and regional spare parts warehousing commitments.
Among Taiwan-based industrial computing suppliers, Advantech Co Ltd anchors the embedded PC module tier for cart integration. US-origin specialists Ergotron, Inc. and Capsa Healthcare occupy positions within the ergonomic mounting and acute care configuration segments respectively. These named entities exemplify how geographic origin and corporate structure shape archetype positioning rather than determining specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Advantech Co Ltd |
| Capsa Healthcare |
| ITD GmbH |
| AFC Industries Inc |
| JACO Inc. |
| Ergotron, Inc. |
| Harloff Manufacturing Co. |
| Medline Industries, Inc. |
| Enovate Medical |
| Others |
Value Network & Pricing Analysis
Captive in-house production of lithium-iron-phosphate battery modules anchors supply positioning for leading cart assemblers while simultaneously insulating pricing power against Taiwan-based embedded PC module volatility. Manufacturers with Jiangsu and Zhejiang frame fabrication facilities command procurement leverage over import-dependent competitors navigating NMPA certification delays.
Pricing Analysis
Margin tightening in mid-tier manual cart configurations reflects India's PLI scheme accelerating domestic assembly cost advantages against offshore producers. Three-tier pricing structure across premium electric fleets, standard hybrid units, and economy manual push models stratifies by NMPA certification tier and hot-swappable battery interoperability. Cost-down pressure on aluminum-frame units intensifies because alloy price volatility compresses margin predictability for non-integrated manufacturers. Tier-two city hospitals in Indonesia and Vietnam exhibit highest price sensitivity; Australian tertiary networks prioritize uptime service level agreements over capital expenditure minimization.
Supply Chain Analysis
Freight cost escalation for lithium battery cell imports from South Korea and Japan elevates landed cost differentials against China-sourced alternatives. Component concentration centers on Taiwan for embedded PC modules, Jiangsu province for extruded aluminum frames, and South Korea for lithium-iron-phosphate cells. Single-source vulnerability in Taiwan-based industrial computing supply creates delivery risk exposure for cart OEMs assembling finished goods in mainland China. Distribution runs through hospital GPO contracts in Australia and direct tender participation in China's tier-one city procurement systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific medical carts sector sits at a software-defined functionality transition, with firmware-update-capable platforms displacing fixed-configuration hardware legacy systems across hospital digitization programs.
For Market Incumbents: Deepen backward integration into hot-swappable battery module production to neutralize Taiwan PC supply concentration risk and capture METI carbon-neutral procurement scoring advantages. Fortify regional spare parts warehousing commitments across Melbourne, Sydney, and Seoul metropolitan clusters to defend subscription-based fleet management contract renewals against asset-light competitors.
For New Entrants and Emerging Players: Begin with telemedicine cart configurations for rural health networks in India's tier-three districts and Philippine provincial hospital systems, where specialist consultation demand outpaces infrastructure deployment. Penetrate through software companion development partnerships with existing EMR platform vendors rather than direct hospital capital sales cycles.
For Investors and Strategic Acquirers: Exit pathways concentrate in industrial computing heritage players seeking medical platform diversification and dedicated healthcare furniture specialists with captive aluminum extrusion capabilities. Long-term viability hinges on predictive maintenance analytics infrastructure deployment scale. Monitor NMPA software validation requirement evolution as the inflection signal for connected diagnostic peripheral integration intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Fleet Management Platform | Predictive maintenance analytics enable subscription revenue displacement of capital purchase models across Australian health networks. |
| Hot-Swappable Battery Interoperability Standard | 24V lithium-iron-phosphate platform standardization compresses vendor lock-in and elevates third-party battery supplier strategic positioning. |
| NMPA In-Country Testing Partnership | Shanghai-based validation laboratories accelerate electromagnetic compatibility certification timelines for foreign-designed power systems. |
| Telemedicine Configuration Development | High-definition camera and diagnostic peripheral integration captures unserved demand in India's rural health networks. |
| METI Carbon-Neutral Procurement Alignment | Recyclable aluminum construction and energy-efficient DC power systems gain scoring advantages in Kanto region public hospital tenders. |
Research Methodology
Multi-period observation of hospital procurement database entries, GPO contract award records, and NMPA certification timelines anchored the trend analysis, supplemented by interviews with biomedical engineering directors, hospital purchasing committee members, GPO contracts managers, and cart fleet maintenance technicians. Secondary validation drew from CDSCO device registration filings, TGA therapeutic goods determinations, METI green procurement guideline releases, and customs trade data for aluminum alloy and lithium battery imports. Bottom-up unit shipment modeling triangulated against top-down health infrastructure investment forecasts.
Segment-weighting across product type, delivery mode, end-user facility category, and material composition informed volume distribution assumptions throughout the projection horizon. CAGRs derived from logistic curve penetration modeling for electric fleet adoption and replacement cycle compression analysis for software-integrated platforms. Forecast inputs incorporated NMPA approval timeline distributions and PLI scheme capacity addition announcements.
Underlying measurement precision varies by segment; medication carts with narcotics security specifications carry tighter precision than general utility cart categories given regulatory filing transparency. Forecasts reflect documented assumptions regarding hospital digitization program continuation and battery chemistry cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Medical Vacuum System Market
Medical Equipment
North America Nuclear Medicine Equipment Market
Medical Equipment
US Durable Medical Equipment Market
Medical Equipment
Histology Embedding System Market
Medical Equipment
Global Platelet Agitator Market
Medical Equipment
Autopsy Saw Market
Medical Equipment
Global Ultra Low Temperature Freezers Market
Medical Equipment
Urodynamic Equipment Market
Medical Equipment
US ECG Equipment Market
Medical Equipment
Medical Ultrasonic Cleaners Market
Medical Equipment
Single-Coated Medical Tape Market
Medical Equipment
Refurbished Medical Equipment Market
Medical Equipment
Global Medical Refrigerators Market
Medical Equipment
Global Surgical Lights Market
Medical Equipment
Medical Oxygen Systems Market
Medical Equipment
Refurbished MRI Systems Market