
 Stereotactic Biopsy Tables Market | 2026-2036
Stereotactic Biopsy Tables Market Size, Share, and Industry Trends Forecast 2026-2036
Stereotactic Biopsy Tables Market Analytics
Market Context
A shortage of trained breast imaging technologists is redrawing deployment timelines for stereotactic biopsy suites across developed health systems. Hologic leverages its installed base of mammography platforms to bundle table placements through integrated room solutions. Siemens Healthineers anchors its position through R&D intensity in robotic patient positioning subsystems. Metaltronica competes on manufacturing scale from its European production footprint, while Accuray Incorporated specializes in radiation oncology crossover applications that demand sub-millimeter table stability.
Technical Definition and Structural Segments
Stereotactic biopsy tables are precision-positioning platforms engineered to immobilize patients during image-guided tissue sampling, typically achieving spatial accuracy within one millimeter through motorized coordinate adjustment. These systems integrate with mammography, CT, or MRI guidance to enable minimally invasive core needle extraction of suspect lesions. Motorized tables command the dominant share of product type revenue due to their workflow efficiency in high-volume screening programs. Digital imaging technology leads technology segmentation as facilities phase out analog detector compatibility. Hospitals represent the most mature end-user channel, while imaging centers represent the fastest-growing installation destination as decentralized breast care networks expand.
Regulatory Frame and Outlook
FDA 510(k) premarket notification requirements govern table safety and electromagnetic compatibility in the United States, while the EU MDR and CE marking framework impose post-market surveillance obligations across European markets. Japan's PMDA maintains distinct mechanical safety standards that delay foreign product entry without localized testing partnerships. Health Canada and TGA Australia align with IEC 60601-1 third edition for electrical safety, creating partial harmonization pathways. Stakeholders must monitor evolving cybersecurity guidance from FDA and post-market clinical follow-up mandates from notified bodies as software-integrated tables proliferate.
Market Dynamics
Precision table manufacturers face mounting pressure from the EU MDR's post-market surveillance mandates, which are extending certification timelines and forcing portfolio rationalization across European supply chains.
Growth Catalysts
- Screening Program Maturation:Germany's national breast cancer screening program drives replacement demand for analog-compatible tables with digital imaging integration.
- FDA 510(k) Streamlining:Predicate device pathways for Class II medical devices accelerate clearance timelines for motorized positioning platforms in the United States.
- Decentralized Care Networks:Imaging centers in Japan expand installation capacity as hospital-based breast units reach saturation.
Market Restraints
- Input Cost Volatility:Precision linear actuator supply concentrates in German and Japanese component suppliers, exposing manufacturers to extended lead times.
- Regulatory Friction:Japan's PMDA mechanical safety standards require localized testing partnerships that delay foreign product entry by 12-18 months.
- Technical Limitation:Sub-millimeter stability requirements for radiation oncology crossover applications restrict viable vendor pools to specialized producers.
Strategic Opportunities
- Underpenetrated Geographies:India's expanding private diagnostic chains present first-mover positioning for digital table platforms ahead of CDSCO harmonization.
- Technology Convergence:Integration of robotic patient positioning subsystems with AI-guided lesion targeting creates premium pricing tiers.
- Channel Innovation:Direct equipment financing through manufacturer captive leasing arms bypasses traditional hospital capital budget cycles.
Industry Challenges
- Specialized Workforce Scarcity:Trained breast imaging technologist shortages in the United States and Germany delay suite deployment timelines.
- Legacy System Integration:PACS connectivity requirements for older mammography platforms complicate digital table retrofit installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stereotactic Biopsy Tables Market |
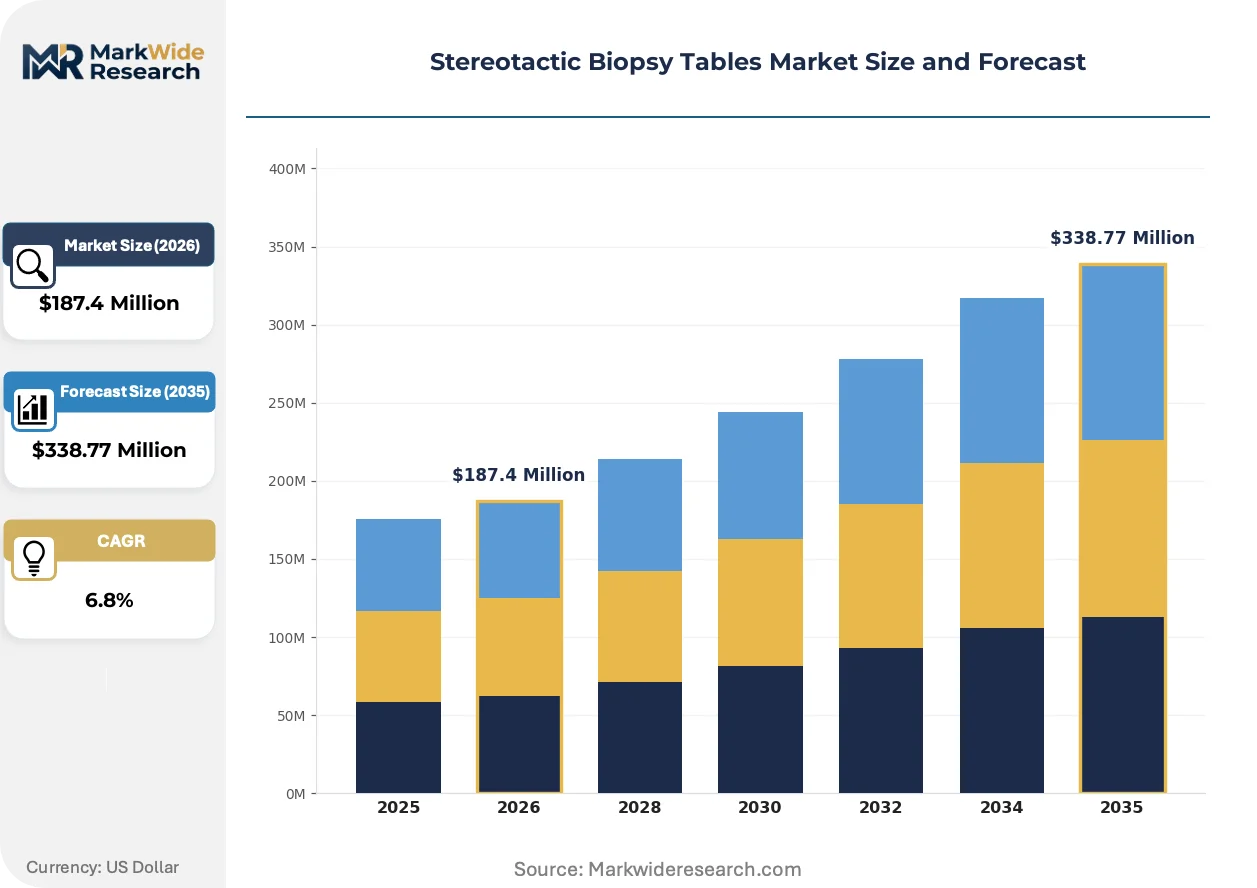
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Tables, Motorized Tables, Adjustable Tables, Portable Tables End User: Hospitals, Imaging Centers, Research Laboratories, Outpatient Clinics Technology: Digital Imaging, Analog Imaging, Computed Tomography, Magnetic Resonance Imaging Installation: Permanent Installation, Modular Installation, Temporary Setup, Integrated Systems |
| Companies Covered | Hologic, Siemens Healthineers, Planmeca, MPI Medical, Devicor Medical Products, Aurora Imaging Technology, Metaltronica, Accuray Incorporated, Biodex Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stereotactic Biopsy Tables Market Evolving Landscape
Software-integrated positioning platforms are redrawing competitive boundaries as real-time imaging feedback loops replace manual coordinate verification, compressing procedure times and redefining workflow benchmarks.
Robotic patient positioning subsystems are fragmenting the traditional motorized table category. High-volume screening centers in the United States adopt these platforms to reduce technologist physical strain and standardize compression protocols. The technology is fragmenting vendor competitive sets by creating distinct performance tiers between precision robotics and conventional motorized tables.
The EU MDR's post-market clinical follow-up mandates are elevating documentation burdens for table manufacturers selling into European markets. Notified bodies now require systematic vigilance reporting on electromagnetic compatibility and mechanical safety incidents. Small and mid-cap manufacturers without dedicated regulatory affairs teams are retreating from CE-marked product lines.
Equipment procurement through integrated room solutions is displacing standalone table purchases in hospital-based breast imaging centers. Bundled mammography-table-workstation contracts concentrate buying power with platform-agnostic vendors. This pattern is most visible in Germany, where hospital procurement consortia negotiate multi-site deployment agreements.
Stereotactic Biopsy Tables Market Segmentation
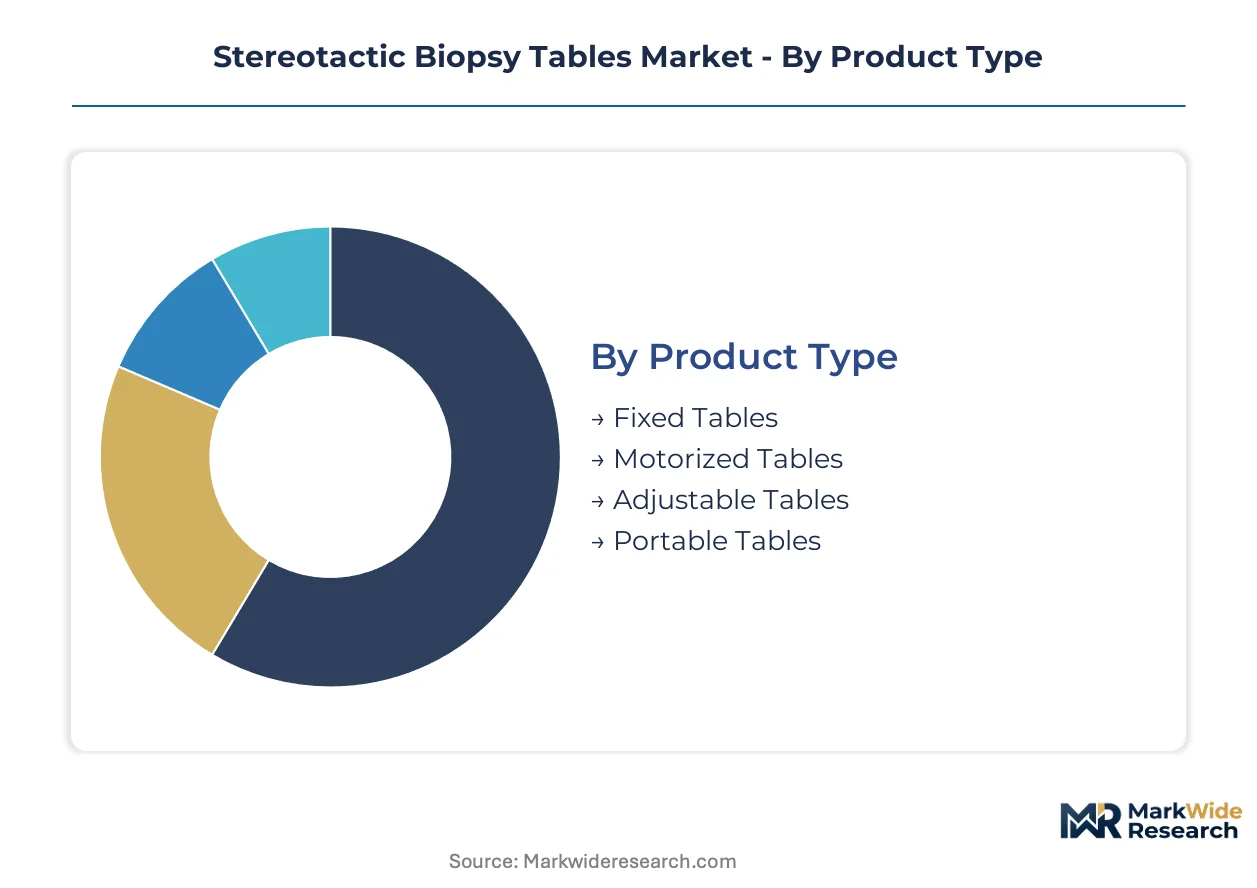
Stereotactic biopsy table procurement patterns diverge sharply between high-volume screening networks and specialized academic settings, creating distinct performance tiers across product configurations. Understanding these segment boundaries clarifies where manufacturers must align R&D investment with reimbursement pathways and facility infrastructure constraints.
Product Type:
Motorized tables dominate export-led demand from German and Japanese component suppliers, while fixed tables concentrate in domestic replacement cycles across mature screening programs in the United States and Germany.
- Motorized Tables:Electromechanical coordinate adjustment systems achieve sub-millimeter spatial accuracy through precision linear actuators. Demand concentrates in high-volume hospital-based breast imaging centers in the United States and Germany, driven by workflow efficiency requirements under screening program maturation.
- Fixed Tables:Static positioning platforms with manual coordinate verification rely on mechanical stability rather than powered adjustment. Installation clusters in cost-sensitive imaging centers across India and Brazil, constrained by capital budget limitations and lower procedural volumes.
- Adjustable Tables:Hybrid platforms offering limited motorized axis control with manual override capabilities.
- Portable Tables:Lightweight, collapsible units designed for temporary deployment in mobile screening units and field diagnostic programs.
Motorized tables command the established base. The steepest expansion runs through portable configurations.
End User:
Customer procurement authority separates capital-intensive hospital systems from decentralized imaging networks, with research laboratories occupying a distinct funding channel through grant-based acquisition.
- Hospitals:Integrated breast imaging suites with dedicated mammography-table-workstation configurations. Procurement in Germany flows through hospital consortia negotiating multi-site bundled agreements, while Japanese hospital-based units approach saturation.
- Imaging Centers:Decentralized diagnostic facilities outside hospital ownership expanding across Japan and the United States. Growth accelerates as trained technologist shortages delay hospital suite deployment timelines.
- Research Laboratories:Academic medical centers and pharmaceutical trial sites requiring sub-millimeter stability for longitudinal studies.
- Outpatient Clinics:Primary care-integrated breast diagnostic units with lower procedural throughput and compressed equipment budgets.
Hospitals retain the dominant installed base. Imaging centers are climbing the fastest.
Technology:
Detector technology maturity creates a cost-performance gradient, with digital platforms capturing replacement demand and legacy analog installations persisting in budget-constrained settings.
- Digital Imaging:Flat-panel detector integration enabling real-time coordinate verification and PACS connectivity. Facilities in Germany phase out analog-compatible tables under national screening program digital mandates.
- Computed Tomography:Cross-sectional guidance capability for lesions occult to mammographic visualization. Adoption concentrates in tertiary referral centers in Japan and the United States managing complex diagnostic cases.
- Analog Imaging:Screen-film detector compatibility with legacy mammography platforms.
- Magnetic Resonance Imaging:MR-conditional table construction for MRI-guided biopsy procedures in specialized academic centers.
Digital imaging anchors the current installed base. Computed tomography guidance is gaining share fastest.
Installation:
Physical deployment configuration determines supply chain complexity, with permanent installations requiring structural site preparation and modular systems enabling faster revenue recognition for manufacturers.
- Permanent Installation:Fixed-room construction with dedicated electrical and data infrastructure. German hospital procurement consortia favor these configurations for screening program standardization.
- Integrated Systems:Pre-engineered mammography-table-workstation bundles from single-vendor platforms. Hologic leverages its installed base to displace standalone table purchases in the United States through room-level contracts.
- Modular Installation:Component-based assembly allowing phased capital deployment and future upgrade paths.
- Temporary Setup:Rapid-deployment configurations for mobile screening programs and emergency diagnostic capacity.
Permanent installation holds the established base. Modular configurations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways anchor the United States as the procedural volume leader, while Japan's PMDA mechanical safety standards and Germany's EU MDR compliance frameworks shape equipment procurement patterns across developed health systems.
United States
Hospital-based breast imaging centers drive replacement demand for digital-compatible motorized tables as screening program maturation accelerates equipment upgrade cycles. FDA Class II device regulations govern electromagnetic compatibility and software-integrated positioning platform clearances. The Greater Boston and Pacific Northwest clusters concentrate academic medical center procurement for research-grade sub-millimeter stability configurations.
Germany
National breast cancer screening program standardization mandates digital imaging integration, forcing analog-compatible table phase-outs across hospital consortia. EU MDR post-market surveillance obligations extend certification timelines and elevate documentation burdens for manufacturers serving European markets. The Bavaria and North Rhine-Westphalia industrial corridors host precision linear actuator suppliers that feed regional table assembly operations.
Japan
Imaging centers expand installation capacity as hospital-based breast units approach saturation, creating decentralized diagnostic network growth. PMDA mechanical safety standards require localized testing partnerships that delay foreign product entry by 12-18 months without domestic collaboration. The Kanto/Tokyo metropolitan cluster concentrates tertiary referral centers managing complex diagnostic cases requiring computed tomography guidance capabilities.
India
Private diagnostic chains present first-mover positioning opportunities for digital table platforms ahead of CDSCO harmonization with international standards. The country's national pharmaceutical and medical device regulator maintains evolving documentation requirements for imported Class II equipment. Maharashtra and Karnataka urban corridors concentrate capital deployment for imaging center expansion outside public hospital infrastructure constraints.
United Kingdom
NHS screening program procurement consolidation favors integrated room solutions over standalone table purchases, bundling mammography-table-workstation contracts. MHRA alignment with EU MDR transitional provisions maintains post-market surveillance continuity following regulatory separation. The London/Southeast corridor concentrates private imaging center networks addressing backlog-driven diagnostic demand outside NHS capacity constraints.
Stereotactic Biopsy Tables Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with bundled platform providers commanding hospital procurement consortia and component-scale manufacturers serving cost-sensitive imaging center segments. The vendor base separates into three archetypes: mammography-platform integrators leveraging installed bases for room-level contracts, precision actuator specialists supplying sub-systems to downstream assemblers, and radiation oncology crossover players demanding sub-millimeter table stability. Competitive moves concentrate on portfolio rationalization under EU MDR documentation burdens and captive financing arms bypassing traditional hospital capital budget cycles.
Within the integrated platform tier, Hologic and Siemens Healthineers occupy positions shaped by mammography-system bundling power, while Metaltronica exemplifies European manufacturing-scale competition from its production footprint base. Accuray Incorporated represents the radiation oncology crossover specialization requiring precision stability standards that restrict viable vendor pools.
| Leading Market Players |
|---|
| Hologic |
| Siemens Healthineers |
| Planmeca |
| MPI Medical |
| Devicor Medical Products |
| Aurora Imaging Technology |
| Metaltronica |
| Accuray Incorporated |
| Biodex Medical Systems |
| Others |
Value Network & Pricing Analysis
Precision linear actuator substitution for legacy hydraulic positioning systems is redrawing manufacturing geography toward German and Japanese component clusters while compressing price premiums for motorized table configurations. This input shift simultaneously elevates supplier concentration risk and forces buyers into longer contract commitments to secure electromechanical subsystems.
Pricing Analysis
Long-term offtake agreements dominate procurement between table manufacturers and precision actuator suppliers, insulating high-volume producers from spot-market volatility while squeezing smaller assemblers into project-based spot purchasing. Pricing stratifies across premium, standard, and economy tiers based on sub-millimeter stability certification and bundled after-sales service contracts. Cost compression in the economy tier is intensifying because Indian and Brazilian imaging centers prioritize capital outlay minimization over precision specifications. Hospital procurement consortia in Germany exhibit the lowest price sensitivity, accepting bundled room-solution premiums in exchange for standardization guarantees.
Supply Chain Analysis
Strategic stockpiling of precision linear actuators has become standard practice among tier-one table manufacturers, buffering against 12-18 month lead times from German and Japanese suppliers. Component sourcing draws from Bavaria and North Rhine-Westphalia in Germany, alongside Tokyo and Osaka industrial corridors in Japan. Single-source vulnerability concentrates in high-torque electromechanical drives and specialized medical-grade aluminum alloys. Distribution runs through manufacturer-direct sales teams for hospital consortia, with third-party medical equipment distributors serving decentralized imaging centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation is accelerating as robotic positioning subsystems create performance tiers that incumbent motorized-table vendors cannot easily bridge. Decentralized diagnostic network expansion across Japan and the United States is spawning niche demand for portable and modular configurations.
For Market Incumbents: Fortify installed-base lock-in through captive equipment financing arms that bypass traditional hospital capital budget cycles. Deepen backward integration into precision actuator supply by acquiring German or Japanese component specialists. The EU MDR's documentation burdens threaten smaller competitors; incumbents should accelerate portfolio rationalization to absorb regulatory costs that fragment the vendor base.
For New Entrants and Emerging Players: FDA 510(k) predicate device pathways offer the fastest regulatory clearance for motorized positioning platforms entering the United States market. White-space concentration sits in India's private diagnostic chains ahead of CDSCO harmonization, and in portable configurations for mobile screening programs. A leasing-first go-to-market model bypasses capital-constrained buyers in cost-sensitive geographies.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with established CE marking and FDA clearance portfolios facing EU MDR compliance exhaustion. Long-term viability centers on software-integrated positioning platforms with AI-guided targeting capabilities. The signal to watch is imaging center installation growth rates outpacing hospital deployments, indicating channel shift toward decentralized care networks.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance secures European market access before smaller competitors retreat. |
| Hospital System Partnership | Bundled room solutions concentrate procurement power with platform-agnostic vendors. |
| Software Companion Development | Real-time imaging feedback loops compress procedure times and redefine workflow benchmarks. |
| Reimbursement Strategy | Alignment with national screening program digital mandates accelerates replacement cycles. |
| Backward Integration | In-house precision actuator production insulates against German and Japanese supply concentration. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with breast imaging technologists, hospital procurement committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up installation data triangulated against top-down screening program expenditure estimates across the analysis window.
Across the projection horizon, the analytical framework modeled volume and value outputs through segmentation across product type, end user, technology, and installation configuration dimensions. CAGRs were derived from fitted trend extrapolation anchored to procedural volume growth and equipment replacement cycle data. Industry-specific inputs included trained technologist shortage rates and national screening program digital mandate timelines.
The analysis sits within stated boundaries; outcomes outside sustained reimbursement support for digital imaging integration or accelerated EU MDR enforcement would require recalibration. Forecasts reflect assumptions about screening program maturation trajectories and component supply lead time stability. Revision becomes warranted when PMDA mechanical safety standard harmonization crosses thresholds that reshape foreign market entry economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Benchtop Platelet Agitator Market
Medical Equipment
Medical Physics Market
Medical Equipment
Automated Dialysis Concentrated Production Systems Market
Medical Equipment
Global Surgical Table Market
Medical Equipment
Global Medical Device Reprocessing Market
Medical Equipment
Auditory Brainstem Response Analyzers Market
Medical Equipment
North America Radiotherapy Market
Medical Equipment
North America Medical Carts Market
Medical Equipment
Global Intraoperative Radiation Therapy Market
Medical Equipment
Global Medical Equipment Cooling Market
Medical Equipment
Global Single-Arm Medical Pendant Market
Medical Equipment
Medication Pouch Inspection Systems Market
Medical Equipment
Electrophysiology Equipment and Recording Systems Market
Medical Equipment
Cell Washer Market
Medical Equipment
Global Surgical Lights Market
Medical Equipment
North America Nuclear Medicine Equipment Market