
 Cryogenic Freezers Market | 2026-2036
Cryogenic Freezers Market Size, Share, and Industry Trends Forecast 2026-2036
Cryogenic Freezers Market Intelligence
Hospital procurement of cryogenic freezers is collapsing as biobanks and pharmaceutical companies expand storage infrastructure. Thermo Fisher Scientific Inc. leverages its laboratory equipment distribution network to sustain recurring revenue from service contracts. Haier Biomedical anchors its position through manufacturing scale in Asia, while ARCTIKO Ltd. specializes in ultra-low temperature systems for niche clinical applications.
Cryogenic freezers maintain biological specimens below minus 150 degrees Celsius using liquid nitrogen or mechanical cascade refrigeration to arrest cellular degradation for extended preservation. The product mix tilts toward liquid nitrogen freezers where margin pools remain deepest due to operational simplicity and reduced maintenance cycles. Mechanical freezers compete on energy efficiency in regions with elevated electricity costs, while vaccine storage applications within the end-user base command premium pricing from validated cold-chain compliance.
FDA 21 CFR Part 11, EU MDR, and the EPA Significant New Alternatives Policy shape equipment validation, refrigerant selection, and documentation standards across installations. The F-Gas Regulation accelerates transition toward closed-loop systems with lower global warming potential refrigerants. Stakeholders must monitor evolving refrigerant phase-down schedules and regional energy efficiency mandates to align capital deployment with compliance timelines.
Market Dynamics
Precision medicine pipelines are forcing biobanks to scale cryogenic storage infrastructure, while EU F-Gas Regulation and FDA cold-chain mandates reshape equipment specifications and refrigerant choices across procurement cycles.
Growth Catalysts
- EU MDR compliance mandates:Biobanks in Germany and France must upgrade to validated cold-chain equipment, accelerating replacement demand for compliant freezer systems.
- Liquid nitrogen operational simplicity:Reduced maintenance cycles and lower technician training requirements pull pharmaceutical manufacturers toward vapor-phase storage architectures.
- Japan's regenerative medicine commercialization:PMDA-approved cell therapies require ultra-low temperature preservation, expanding biobank storage capacity in Osaka and Tokyo clusters.
Market Restraints
- Liquid nitrogen supply concentration:Regional production bottlenecks in industrial gas infrastructure create dependency risks for vapor-phase freezer operators.
- Mechanical cascade energy intensity:Elevated electricity costs in California and Germany compress operating margins for facilities running compressor-based systems.
- F-Gas refrigerant phase-down:EU regulatory timelines force premature equipment retirement before mechanical freezer depreciation cycles complete.
Strategic Opportunities
- India biobank infrastructure gaps:CDSCO's expanding clinical trial framework creates demand for validated cryogenic storage in Hyderabad and Bengaluru research corridors.
- Closed-loop refrigerant systems:Convergence of IoT monitoring and automated leak detection enables predictive maintenance contracts with premium pricing.
- US IRA clean energy incentives:Tax credits for energy-efficient laboratory equipment subsidize mechanical freezer upgrades in Boston and San Diego pharma clusters.
Industry Challenges
- Cryogenic technician certification scarcity:Liquid nitrogen handling protocols require specialized training programs that lag behind installation growth in emerging markets.
- Legacy equipment integration friction:Biobanks running 15-year mechanical freezers face data migration complexity when connecting to modern LIMS platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryogenic Freezers Market |
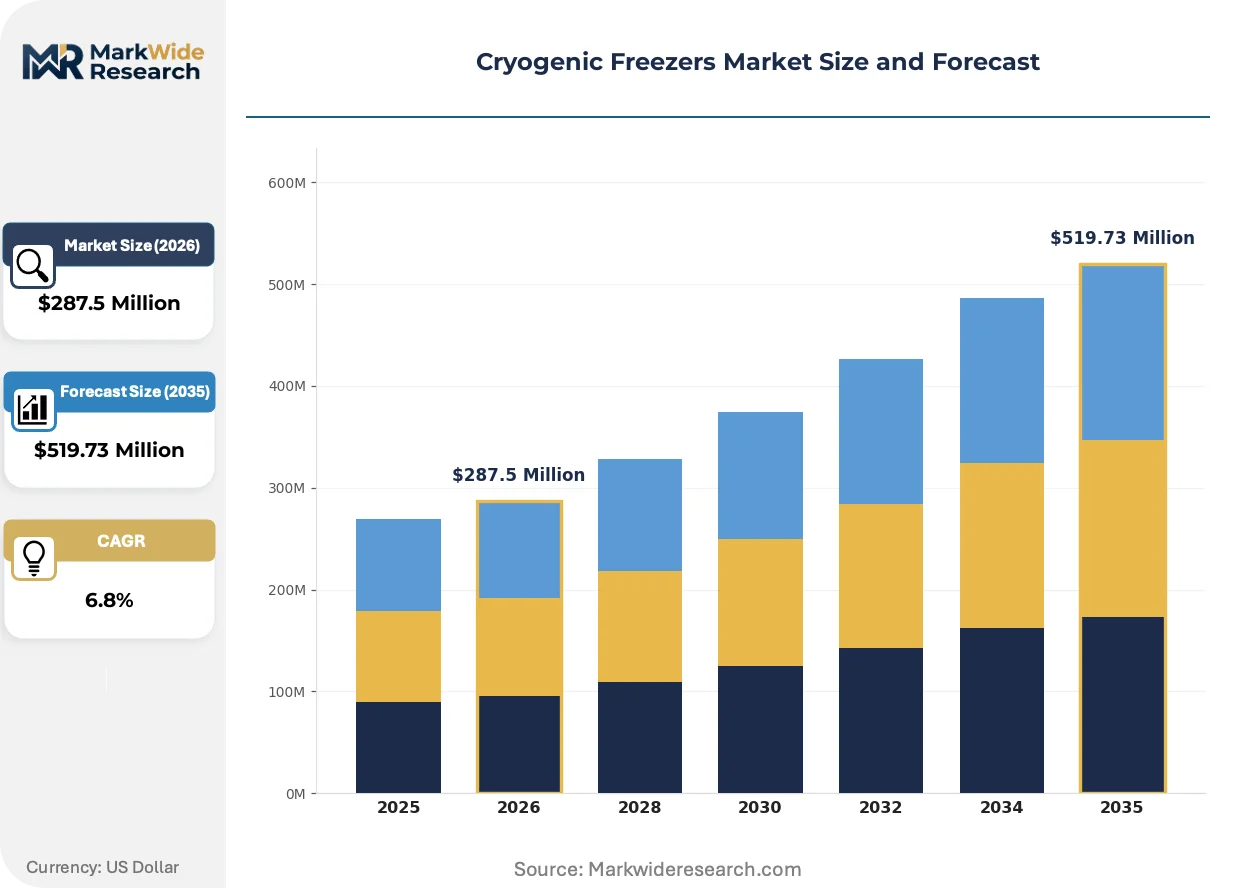
| Market Size in 2026 | $287.5 Million |
| Market Size in 2035 | $519.73 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Nitrogen Freezers, Mechanical Freezers, Glass Door Freezers, Chest Freezers End User: Research Laboratories, Hospitals, Biobanks, Pharmaceutical Companies Application: Cell Preservation, Vaccine Storage, Sample Preservation, Tissue Storage Technology: Conventional Cooling, Turbo Brayton Cycle, Closed-loop System, Open-loop System |
| Companies Covered | PHC Holdings Corporation, ARCTIKO Ltd., Thermo Fisher Scientific Inc., Air Products and Chemicals, Inc., MVE Biological Solutions by Cryoport, Inc., Haier Biomedical, Azenta, Inc., Linde PLC, Chart Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryogenic Freezers Market Strategic Shifts & Innovations
Equipment architectures are splitting between liquid nitrogen simplicity and mechanical efficiency, while regulatory pressure on refrigerants and documentation standards accelerates technology turnover across installed bases.
Mechanical cascade refrigeration is bifurcating the installed base between energy-conscious European facilities and nitrogen-dependent biobanks prioritizing temperature uniformity. German pharmaceutical manufacturers are retrofitting compressor systems with lower-GWP refrigerants ahead of F-Gas deadlines. This technology split is compressing vendor R&D budgets across two incompatible thermal architectures.
EPA Significant New Alternatives Policy is restricting hydrofluorocarbon refrigerants in new equipment, forcing manufacturers to certify alternative cooling chemistries. The industrial consequence is extended product validation timelines and higher compliance costs. US biobanks in Research Triangle Park and San Francisco Bay Area are front-loading procurement to secure grandfathered refrigerant systems.
Service contract unbundling is fragmenting the traditional equipment-plus-maintenance bundle into discrete monitoring, calibration, and emergency response offerings. Biobanks with internal engineering capabilities are opting for à la carte coverage, compressing OEM recurring revenue per installation. This pattern is most visible in Boston's concentrated academic medical center cluster.
Cryogenic Freezers Market Segmentation
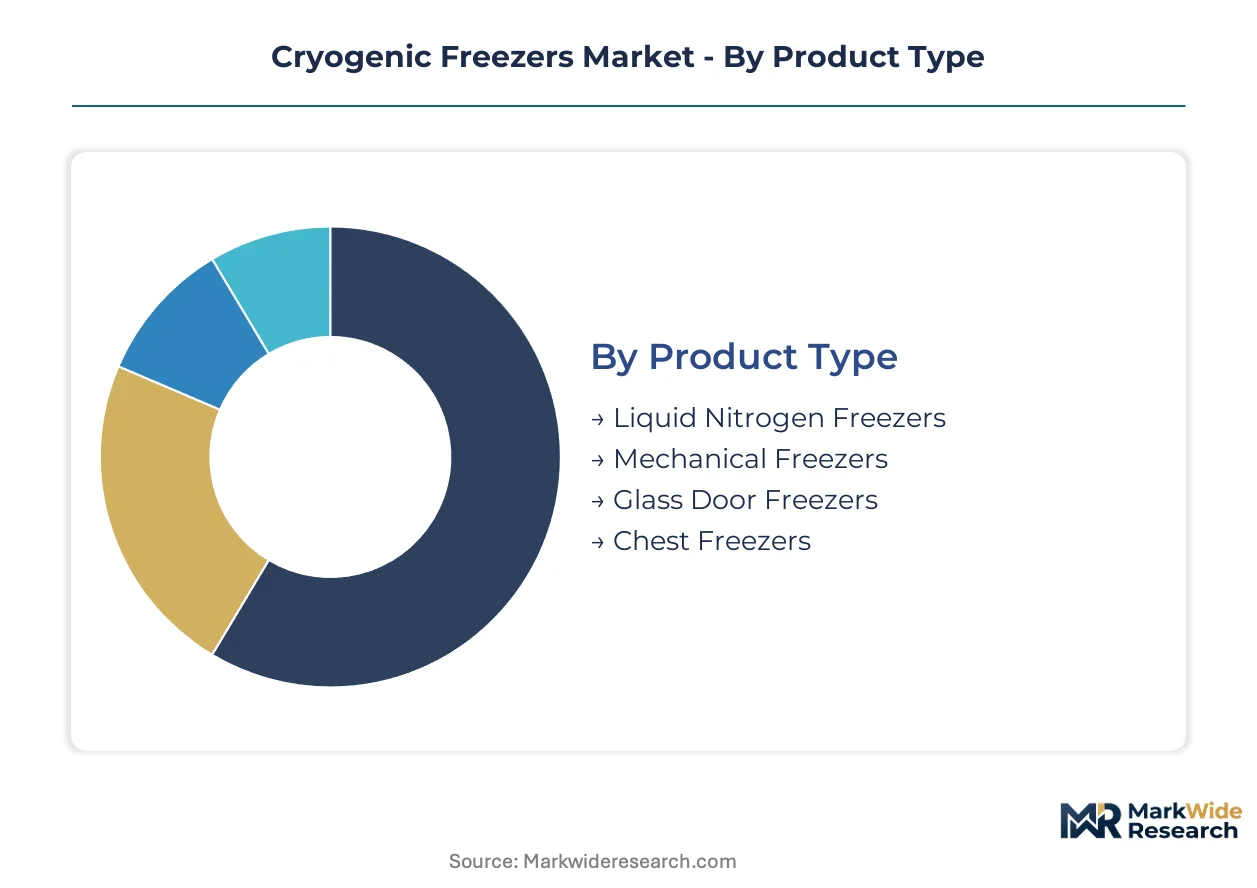
Cryogenic freezer procurement splits along thermal architecture lines, with regulatory pressure on refrigerants and documentation standards forcing distinct capital deployment strategies across product categories. End-user concentration in pharmaceutical manufacturing clusters and biobank expansion programs reshapes segment prioritization.
Product Type:
FDA 21 CFR Part 11 and EU F-Gas Regulation create divergent compliance burdens across thermal architectures, with refrigerant phase-down timelines accelerating equipment replacement cycles in European installations.
- Liquid Nitrogen Freezers:Vapor-phase storage systems maintain temperatures below minus 150 degrees Celsius using liquid nitrogen immersion or jacketed chambers without compressor maintenance. Pharmaceutical manufacturers in Germany and Japan favor these architectures for operational simplicity and reduced technician certification requirements under PMDA and EU MDR documentation mandates.
- Mechanical Freezers:Cascade refrigeration systems using two-stage compressors achieve ultra-low temperatures through synthetic refrigerant circulation, with energy efficiency becoming critical in California and German facilities facing elevated electricity tariffs. EPA Significant New Alternatives Policy restrictions on hydrofluorocarbon refrigerants force premature equipment retirement ahead of depreciation cycles.
- Glass Door Freezers:Visibility-optimized units serve research laboratories requiring frequent sample access without full chamber exposure, common in Boston and San Diego academic medical centers.
- Chest Freezers:Top-opening configurations minimize cold air loss during access events, preferred by biobanks with high-throughput sample retrieval protocols.
Established volume favors mechanical freezers in electricity-subsidized regions; emerging adoption favors liquid nitrogen architectures in facilities prioritizing temperature uniformity and reduced maintenance overhead.
End User:
Customer type determines capital intensity and service contract structure, with biobank procurement scaling toward enterprise-grade installations while hospital purchasing fragments across departmental budgets.
- Research Laboratories:Academic and government facilities in Research Triangle Park and Oxford prioritize grant-funded equipment with extended warranty terms and LIMS integration capabilities.
- Hospitals:Clinical pathology departments face procurement compression as capital shifts toward biobank infrastructure, with remaining purchases concentrated in transplant centers and fertility clinics requiring validated cold-chain compliance.
- Biobanks:National population-scale repositories and commercial specimen archives drive the steepest expansion trajectory, with Germany's DKMS and Japan's RIKEN BioResource Center expanding vapor-phase capacity to support precision medicine pipelines.
- Pharmaceutical Companies:Cell therapy manufacturers in Basel and Cambridge, Massachusetts require GMP-validated storage with continuous monitoring and automated alarm systems under FDA and Swissmedic guidance.
Procurement concentration clusters in biobanks and pharmaceutical companies; hospital purchasing is fragmenting across smaller departmental budgets.
Application:
Use case specificity determines temperature setpoint precision and monitoring redundancy, with cell preservation demanding the narrowest thermal bands and vaccine storage commanding premium pricing from cold-chain validation requirements.
- Cell Preservation:CAR-T and stem cell therapies require minus 150 degrees Celsius or below with temperature excursion alarms, driving specification intensity in Osaka and Philadelphia manufacturing clusters.
- Vaccine Storage:mRNA and viral vector formulations need minus 70 to minus 80 degrees Celsius stability, with WHO prequalification standards shaping equipment selection in emerging market distribution hubs.
- Sample Preservation:Blood, plasma, and serum repositories in national biobanks tolerate wider temperature bands with higher sample density priorities.
- Tissue Storage:Transplant programs and fertility clinics require rapid access protocols with backup liquid nitrogen dewars for emergency transfer scenarios.
Specification intensity peaks in cell preservation; volume scale concentrates in sample preservation applications.
Technology:
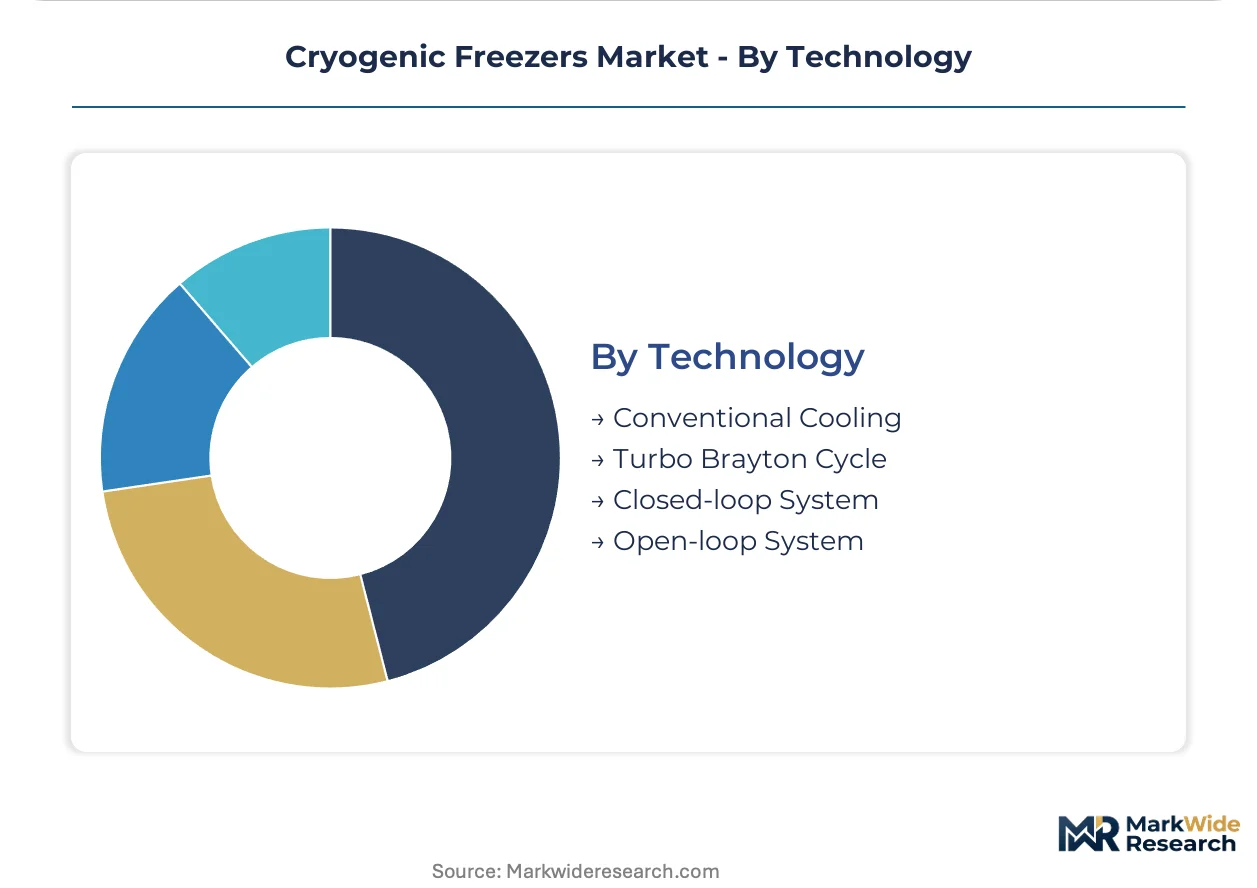
Cooling methodology selection locks facilities into distinct refrigerant supply chains and technician certification requirements, with closed-loop architectures gaining preference under tightening environmental regulations.
- Conventional Cooling:Single-stage compressor systems serve minus 40 to minus 80 degrees Celsius applications with lowest capital cost, common in secondary sample storage tiers.
- Turbo Brayton Cycle:Gas-bearing turbine systems eliminate lubricants and achieve minus 150 degrees Celsius without liquid nitrogen, emerging in German facilities ahead of F-Gas refrigerant phase-down deadlines.
- Closed-loop System:Sealed refrigerant circuits with automated leak detection and IoT monitoring enable predictive maintenance contracts, preferred by CDSCO-regulated biobanks in Hyderabad and Bengaluru.
- Open-loop System:Liquid nitrogen venting architectures maintain temperature through continuous nitrogen consumption, with supply security concerns limiting adoption outside established industrial gas corridors.
Installed base remains concentrated in conventional cooling; capital deployment is shifting fastest toward closed-loop and turbo Brayton alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision-engineered cryogenic systems to biobank operators across the United States and Japan, establishing a dominant trade corridor in validated cold-chain equipment.
United States
Cell therapy manufacturers in Cambridge and San Diego drive specification intensity for GMP-validated storage systems. The FDA's 21 CFR Part 11 documentation mandates accelerate replacement cycles for legacy mechanical freezers. Boston's academic medical center cluster concentrates procurement of liquid nitrogen vapor-phase architectures under NIH grant funding.
Germany
DKMS and Fraunhofer Institute biobanks expand vapor-phase nitrogen capacity to support precision medicine pipelines. The EU F-Gas Regulation forces premature retirement of hydrofluorocarbon-based mechanical systems ahead of depreciation schedules. Baden-Württemberg pharmaceutical manufacturers retrofit compressor systems with lower-GWP refrigerants from Honeywell and Chemours.
Japan
PMDA-approved regenerative therapies require minus 150 degrees Celsius preservation protocols, expanding demand in Osaka and Tokyo manufacturing clusters. METI's carbon neutrality roadmap subsidizes energy-efficient mechanical freezer upgrades at RIKEN BioResource Center. The Kanto region concentrates domestic production of ultra-low temperature monitoring systems.
India
CDSCO's expanding clinical trial framework creates infrastructure gaps in cryogenic storage across Hyderabad and Bengaluru research corridors. The PLI scheme for medical devices attracts foreign OEMs to establish local assembly operations. Telangana's biotech policy offers capital subsidies for biobank equipment procurement exceeding specified investment thresholds.
United Kingdom
UK Biobank's sample archive expansion drives enterprise-grade vapor-phase nitrogen procurement in Cambridge and Oxford. The MHRA's post-Brexit alignment with EU MDR cold-chain standards maintains equipment validation complexity. London's cell and gene therapy cluster concentrates demand for automated sample retrieval systems with LIMS integration.
Cryogenic Freezers Market Key Industry Players
Listed leaders compete with private specialists across thermal architecture expertise, with public companies leveraging capital markets for refrigerant transition R&D while family-owned fabricators defend niche positions in liquid nitrogen system integration. The vendor base splits between diversified laboratory conglomerates and focused cryogenic equipment builders. Three archetypes dominate: scale-driven platform players, regional manufacturing specialists, and precision-application engineers. Competitive moves center on M&A for refrigerant technology access and strategic partnerships with industrial gas distributors.
Within the precision-application tier, ARCTIKO Ltd. and MVE Biological Solutions by Cryoport, Inc. exemplify engineering-intensive positioning for clinical and biobank end-users. Thermo Fisher Scientific Inc. anchors the diversified platform archetype, leveraging cross-selling density across laboratory workflows. PHC Holdings Corporation represents the Asia-Pacific manufacturing scale model, competing on cost structure in emerging market procurement cycles. These three companies illustrate the strategic segmentation between thermal architecture specialization and broad laboratory equipment portfolios.
| Leading Market Players |
|---|
| PHC Holdings Corporation |
| ARCTIKO Ltd. |
| Thermo Fisher Scientific Inc. |
| Air Products and Chemicals, Inc. |
| MVE Biological Solutions by Cryoport, Inc. |
| Haier Biomedical |
| Azenta, Inc. |
| Linde PLC |
| Chart Industries |
| Others |
Cost & Logistics Intelligence
Twelve-to-sixteen-week lead times for turbo Brayton compressor assemblies concentrate pricing power with German and Japanese component fabricators, while liquid nitrogen supply contracts indexed to industrial gas spot markets expose biobank operators to cost volatility that compresses mechanical freezer margins.
Pricing Analysis
Current-generation closed-loop refrigerant systems command 40-60% premiums over prior-generation hydrofluorocarbon cascade units, while next-generation solid-state cooling prototypes remain pre-commercial. Three-tier pricing structure across GMP-validated, research-grade, and secondary storage tiers separates pharmaceutical manufacturers from academic laboratories on certification intensity. Cost compression in mechanical freezer segments is intensifying because EPA refrigerant restrictions force premature R&D amortization across shortened product lifecycles. Hospital pathology departments exhibit highest price sensitivity due to capital budget fragmentation, whereas cell therapy manufacturers demonstrate lowest sensitivity given cold-chain compliance mandates.
Supply Chain Analysis
Basel-Strasbourg industrial gas corridor transit underwrites liquid nitrogen supply security for European biobanks, with single-source dependency on Linde and Air Products creating vulnerability to regional production outages. Compressor manufacturing concentrates in Germany, Japan, and the United States; rare-earth magnets for high-efficiency motors draw from Chinese processing facilities. Steel alloy cryogenic chambers and IoT sensor modules constitute critical component dependencies. Distribution runs through OEM direct sales for enterprise installations and laboratory equipment distributors for mid-scale research facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cryogenic freezer procurement is shifting toward platform-integrated monitoring ecosystems, with LIMS interoperability emerging as the decisive switching cost for biobank retention.
For Market Incumbents: Compound service revenue density by unbundling predictive maintenance contracts from equipment sales, addressing the threat of à la carte procurement from Boston academic medical centers with internal engineering capabilities. Prioritize backward integration into refrigerant recovery and reclamation services to capture margin pools from F-Gas compliance mandates. For New Entrants and Emerging Players: Lead with IoT-native architectures targeting India's CDSCO-regulated biobank infrastructure gaps in Hyderabad and Bengaluru, where validated cold-chain equipment demand outpaces established vendor service capacity. Position around closed-loop system integration with automated leak detection as the go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because EU MDR and FDA documentation mandates create durable competitive moats around validated equipment suppliers. Target precision-application engineers with proprietary thermal architecture expertise rather than diversified laboratory conglomerates. Watch F-Gas refrigerant phase-down acceleration as the signal for mechanical freezer replacement cycle inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Refrigerant System Certification | EU F-Gas Regulation compliance secures market access ahead of hydrofluorocarbon phase-down deadlines. |
| LIMS Platform Integration Partnership | Biobank software interoperability reduces customer churn and extends equipment replacement cycles. |
| Industrial Gas Supply Agreement | Long-term liquid nitrogen contracts with Air Products insulate vapor-phase operators from spot price volatility. |
| Predictive Maintenance Service Launch | IoT-enabled monitoring contracts with CDSCO-regulated Indian biobanks capture recurring revenue streams. |
| Turbo Brayton Cycle R&D Investment | METI-subsidized Japanese development programs accelerate next-generation cooling technology commercialization. |
Research Approach
The analysis maps liquid nitrogen freezer, mechanical cascade, and emerging solid-state cooling sub-sectors, each validated through biobank operations directors, pharmaceutical cold-chain managers, and laboratory equipment procurement officers. Primary interviews with GPO contracts managers and biomedical engineers cross-reference against FDA 510(k) filings, EU MDR technical documentation, and industrial gas supply databases. Bottom-up installation counts triangulate with top-down pharmaceutical capital expenditure disclosures.
Consistency checks against biobank expansion announcements and refrigerant phase-down regulatory timelines validate volume and value outputs across the projection horizon. Segmentation dimensions span thermal architecture, end-user type, application temperature requirements, and regional regulatory cluster. CAGRs derive from equipment replacement cycle analysis and precision medicine pipeline growth trajectories, with inputs from CDSCO clinical trial registration trends and PMDA regenerative therapy approval patterns.
Underlying assumptions cover stable industrial gas supply infrastructure and gradual F-Gas implementation timelines, with deviation risk concentrated in liquid nitrogen production bottlenecks and accelerated refrigerant restrictions. Practitioners should keep alternative scenarios live as EU MDR enforcement intensity and IRA clean energy subsidy allocations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Europe Medical Carts Market
Medical Equipment
Irradiation Apparatus Market
Medical Equipment
Patient Lifting Equipment Market
Medical Equipment
Global Medical Lasers Market
Medical Equipment
Single-Coated Medical Tape Market
Medical Equipment
Global Blood Purification Equipment Market
Medical Equipment
Bone Densitometer Systems Market
Medical Equipment
Operating Table Parts Market
Medical Equipment
Terminal Sterilization Market
Medical Equipment
Portable Steam Autoclave Market
Medical Equipment
Refurbished Medical Equipment Market
Medical Equipment
Refurbished MRI Systems Market
Medical Equipment
North America Medical Carts Market
Medical Equipment
Global Operating Table Mattresses Market
Medical Equipment
Global Single-Arm Medical Pendant Market
Medical Equipment
Urodynamic Equipment Market