
 Global Platelet Incubator Market | 2026-2036
Global Platelet Incubator Market Size, Share, and Industry Trends Forecast 2026-2036
Global Platelet Incubator Market Foresight
The capital-intensity divergence between automated digital monitoring platforms and basic temperature-controlled cabinets is unwinding competitive stability in the platelet incubator landscape. Helmer Scientific leverages its integrated manufacturing footprint to sustain premium positioning across North American hospital networks. Terumo Corporation anchors its presence through deep relationships with Japanese and Asia-Pacific blood banking systems. Boekel Scientific competes on specialized benchtop configurations for mid-tier diagnostic centers.
A platelet incubator is a precision thermal management device that maintains platelet concentrates at controlled temperatures between 20°C and 24°C with continuous gentle agitation to preserve viability and prevent aggregation. Benchtop incubators occupy the largest installed base due to their compatibility with existing blood bank workflows and moderate throughput requirements, while digital monitoring technology captures expanding margin pools as facilities prioritize remote alarm integration and audit-ready data logging. Floor-standing units serve high-volume centralized transfusion centers where batch processing efficiency determines operational economics.
The FDA enforces 21 CFR Part 606 standards for platelet storage conditions, while the EU Medical Device Regulation imposes conformity assessment burdens on incubator manufacturers seeking CE-marked distribution. ISO 13485 quality management requirements shape supplier qualification protocols across both jurisdictions. Stakeholders must weigh regulatory compliance investments against the operational flexibility demanded by regenerative medicine and stem cell laboratory expansion.
Market Dynamics
The FDA's updated platelet bacterial detection guidance is forcing blood banks to upgrade temperature-controlled environments, compressing replacement cycles and reshaping vendor qualification protocols across hospital networks and centralized transfusion services.
Growth Catalysts
- 21 CFR Part 606 enforcement:The FDA's stringent platelet storage standards mandate continuous thermal monitoring, compelling facilities to replace aging equipment with validated systems.
- Stem cell laboratory expansion:Regenerative medicine protocols require identical 20-24°C agitation conditions, extending incubator demand beyond traditional blood banking.
- Benchtop workflow compatibility:Mid-sized diagnostic centers prioritize space-efficient configurations that integrate with existing laboratory information management systems.
Market Restraints
- Refrigeration compressor supply concentration:Precision thermal components originate from a narrow supplier base in Germany and Japan, exposing manufacturers to input bottlenecks.
- ISO 13485 certification timelines:Quality management system audits impose 12-18 month delays on new market entrants seeking CE-marked distribution.
- Passive thermal storage alternatives:Phase-change material transport containers reduce real-time monitoring requirements for short-duration platelet movement.
Strategic Opportunities
- India's blood banking modernization:CDSCO harmonization with international storage standards creates first-mover advantage for validated 21 CFR Part 606-compliant systems.
- Remote alarm integration:Cloud-connected temperature logging addresses audit-ready documentation requirements for Joint Commission-accredited hospitals.
- Extended shelf-life protocols:Pathogen reduction technologies enable 7-day platelet storage, doubling incubator utilization efficiency per unit.
Industry Challenges
- Biomedical equipment technician scarcity:Specialized calibration expertise for agitation mechanism maintenance concentrates in metropolitan hospital clusters.
- Legacy LIMS integration complexity:Proprietary data formats from incumbent monitoring platforms resist standardized API connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Platelet Incubator Market |
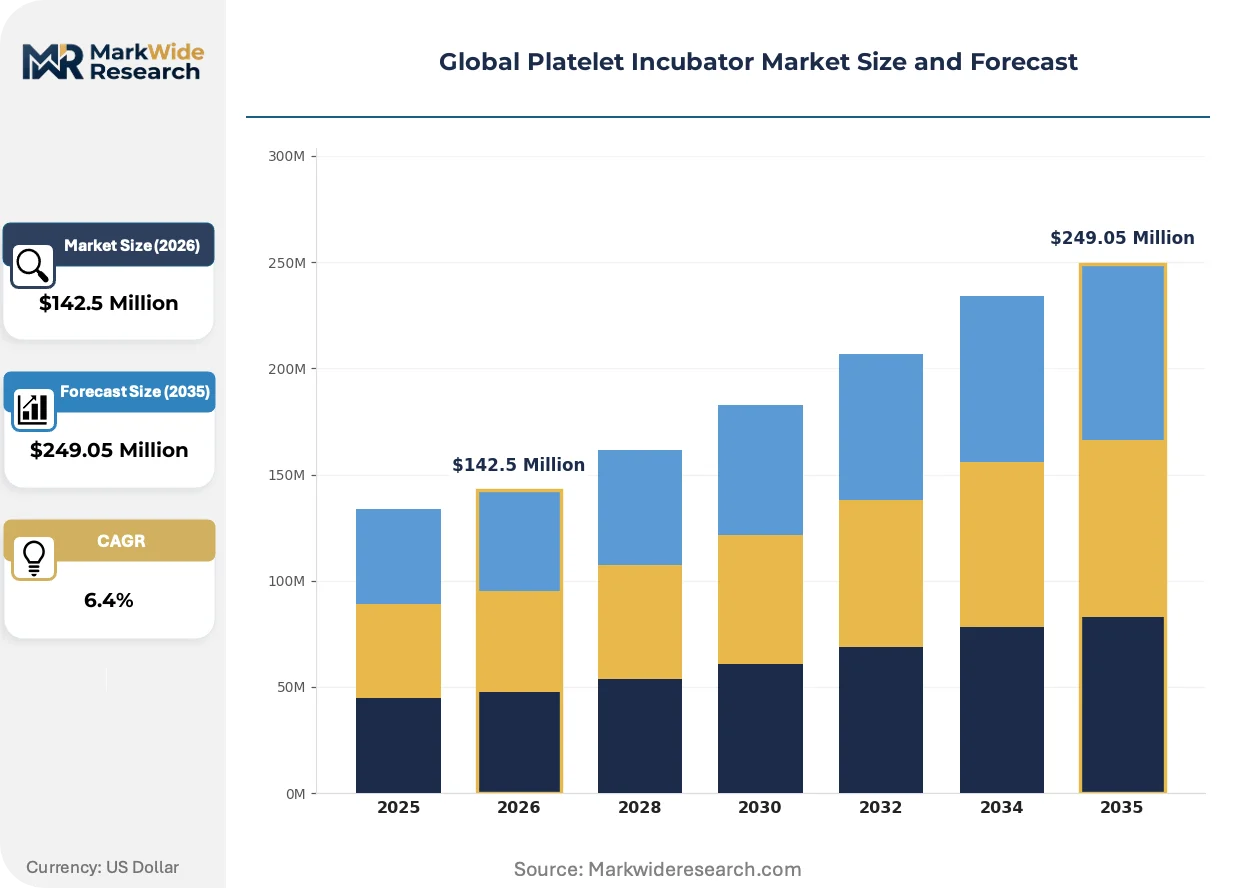
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $249.05 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop Incubators, Benchtop Incubators, Floor-standing Incubators, Portable Incubators Technology: Temperature Control, Humidity Control, CO2 Regulation, Ultra-clean Air Filtration, Digital Monitoring Application: Blood Banks, Research Laboratories, Regenerative Medicine, Biopharmaceutical Production End User: Hospitals, Diagnostic Centers, Clinical Research Organizations, Stem Cell Laboratories |
| Companies Covered | Helmer Scientific, Terumo Corporation, Boekel Scientific, BIOBASE, Meditech Technologies India Private Limited, SARSTEDT AG & Co.KG, Lmb Technologie GmbH, LABCOLD, Biolab Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Platelet Incubator Market Shifts & Advancements
Digital telemetry is penetrating platelet storage infrastructure, converting standalone thermal cabinets into networked nodes within hospital asset management ecosystems. This connectivity shift redefines competitive differentiation around data interoperability rather than mechanical reliability alone.
Continuous temperature logging with automated alert escalation is decomposing the market for manual chart recorders and periodic spot-check protocols. Large academic medical centers in the United States are deploying these systems fleet-wide. The technology is decomposing traditional service contract structures by enabling predictive maintenance algorithms that reduce unplanned downtime.
The EU Medical Device Regulation's post-market surveillance requirements impose annual safety update reporting on incubator manufacturers, elevating documentation burdens for CE-marked products. Blood establishments in Germany and France now demand supplier evidence of systematic vigilance data collection. High-volume transfusion centers are consolidating procurement around vendors with established notified body relationships.
Hospital supply chain departments are unbundling after-sales service from capital equipment purchases, negotiating standalone preventive maintenance agreements with third-party biomedical service firms. This purchasing pattern disrupts traditional manufacturer-captive service revenue streams. The trend is most pronounced in United States health systems pursuing operational expenditure optimization.
Global Platelet Incubator Market Segmentation
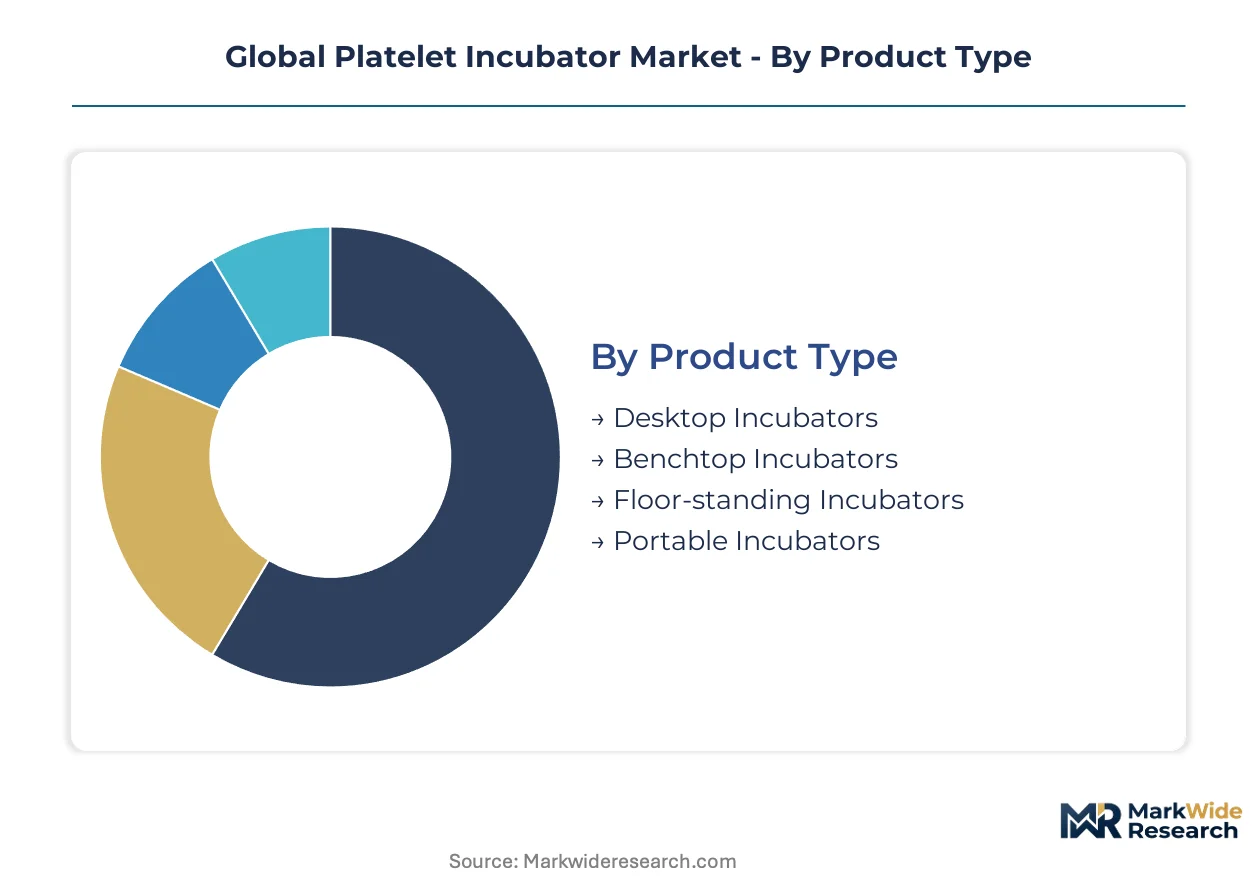
Segmentation in platelet incubators reveals how substitution pressures from passive thermal containers and alternative storage modalities reshape competitive boundaries across product configurations and end-use environments. Understanding these fault lines exposes where vendors must defend installed base against displacement and where new demand formation creates expansion opportunity.
Product Type:
Benchtop configurations face the most acute substitution threat from phase-change material transport containers for short-duration platelet movement, forcing vendors to emphasize LIMS integration and audit documentation as defensive differentiators.
- Desktop Incubators:Compact units designed for low-throughput settings with minimal agitation capacity and basic temperature control. Demand concentrates in small diagnostic centers in India and Southeast Asia where CDSCO-aligned procurement budgets constrain capital expenditure; these facilities prioritize footprint reduction over remote monitoring capability.
- Benchtop Incubators:Mid-capacity systems with continuous gentle agitation and validated 20-24°C thermal stability. United States hospital networks and centralized transfusion services in Germany specify these for workflow compatibility with existing blood bank infrastructure; FDA 21 CFR Part 606 compliance documentation drives vendor selection criteria.
- Floor-standing Incubators:High-volume batch processing units serving regional blood centers with 100+ platelet concentrate capacity. Japanese Red Cross facilities and French blood establishments (EFS) deploy these for operational economics at scale.
- Portable Incubators:Battery-powered mobile units for emergency transfusion and military field deployment. Defense medical services in the United States and mobile blood collection teams in Australia specify ruggedized variants.
Benchtop incubators retain volume leadership; portable incubators hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium digital ecosystems from basic thermal management, with reimbursement pressure in European hospital systems accelerating migration toward connected platforms that reduce manual documentation labor.
- Temperature Control:Precision thermal regulation systems maintaining 20-24°C setpoints with ±0.5°C stability using compressor-based or thermoelectric cooling. Blood banks in France and Germany require redundant sensor arrays for EFS and PEI compliance.
- Humidity Control:Active moisture management preventing platelet concentrate desiccation during extended storage. High-humidity climates in Singapore and Gulf Cooperation Council countries drive specification for these systems in hospital pharmacies.
- CO2 Regulation:Gas-permeable storage environments with controlled atmosphere for specialized platelet additive solutions. Academic medical centers in the United States and Swiss university hospitals deploy these for research-grade storage protocols.
- Ultra-clean Air Filtration:HEPA or ULPA filtration systems maintaining ISO 5 or better air quality for open-system platelet processing. Stem cell laboratories in South Korea and Japan specify these for concurrent regenerative medicine applications.
- Digital Monitoring:Cloud-connected telemetry with automated alarm escalation, predictive maintenance algorithms, and audit-ready data logging. United States health systems pursuing Joint Commission accreditation and German hospitals implementing EU MDR post-market surveillance requirements prioritize these platforms.
Digital monitoring is gaining share fastest; basic temperature control retains the largest installed base.
Application:
Customer type concentration varies sharply by application maturity, with regenerative medicine presenting the most fragmented procurement landscape and blood banking the most consolidated vendor relationships.
- Blood Banks:Established transfusion services with validated cold chain protocols and regulatory inspection histories. National blood services in Japan, France, and the United States operate under FDA, PMDA, or ANSM oversight with stringent equipment qualification requirements.
- Research Laboratories:Academic and institutional settings with variable throughput and protocol customization needs. Max Planck Institutes in Germany and NIH-funded centers in the United States specify flexible configurations.
- Regenerative Medicine:Cell therapy manufacturing and stem cell expansion requiring identical 20-24°C agitation conditions. CDMOs in South Korea and clinical trial sites in Switzerland are expanding capacity.
- Biopharmaceutical Production:GMP-compliant manufacturing environments for platelet-derived therapeutic products. Contract manufacturers in Ireland and Singapore serving EU and Asia-Pacific markets drive demand.
Blood banks retain volume leadership; regenerative medicine holds the steepest expansion curve.
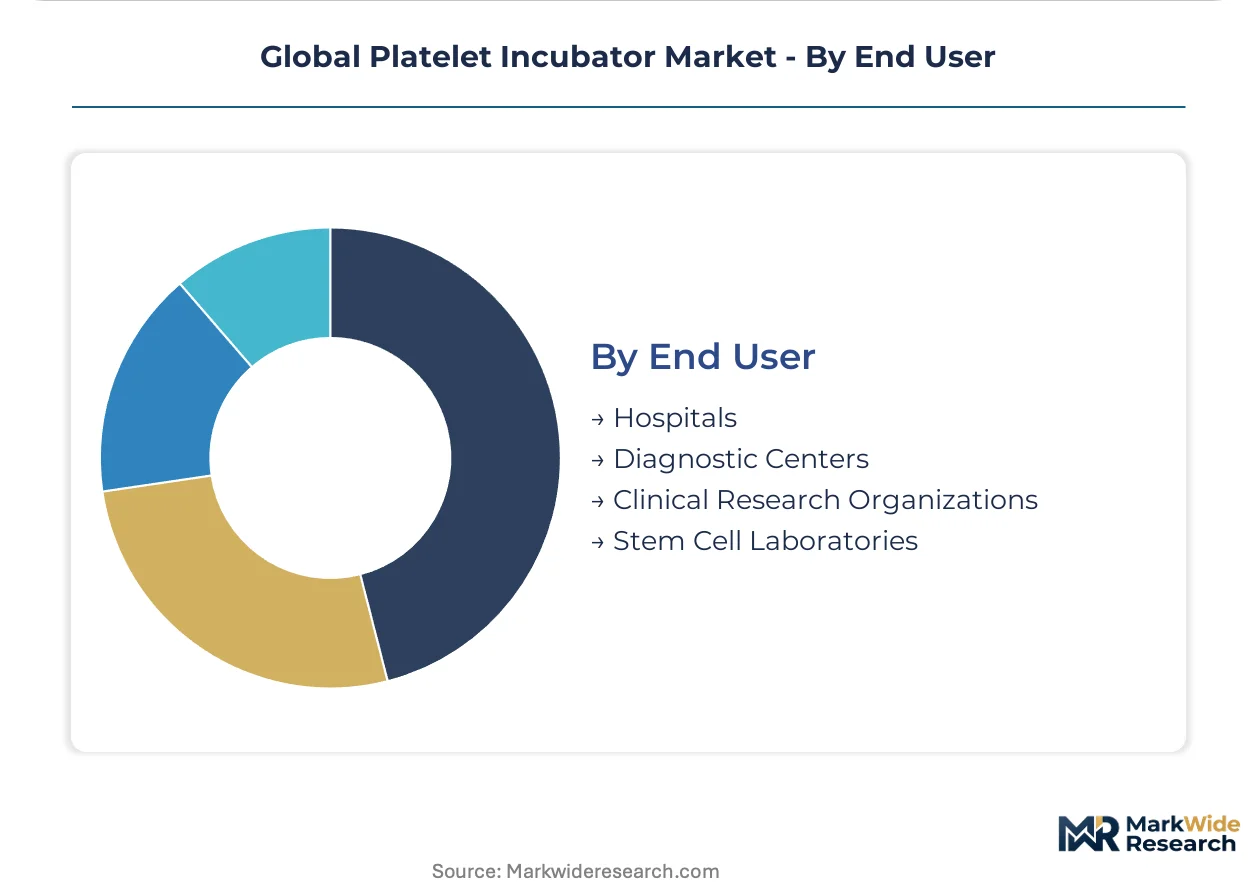
End User:
Procurement authority concentration determines pricing leverage, with hospital supply chain departments unbundling service contracts and diagnostic center networks negotiating fleet-wide agreements.
- Hospitals:Integrated delivery networks with centralized transfusion services and standardized equipment platforms. Kaiser Permanente and Mayo Clinic systems in the United States consolidate procurement across multi-site footprints.
- Diagnostic Centers:Mid-tier laboratories with moderate throughput and space constraints. Quest Diagnostics and LabCorp reference laboratories in the United States specify benchtop configurations.
- Clinical Research Organizations:Trial sites requiring protocol-specific storage documentation and temperature excursion reporting. IQVIA and PPD sites across the United States and Western Europe deploy validated systems.
- Stem Cell Laboratories:Specialized facilities processing hematopoietic progenitor cells and mesenchymal stem cells. Cord blood banks in South Korea and cellular therapy centers in Germany expand capacity.
Hospitals retain volume leadership; stem cell laboratories hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. United States hospital networks absorb premium digital monitoring systems, while Indian blood banks prioritize capital efficiency over telemetry integration.
United States
Hospital consolidation and centralized transfusion services compress replacement cycles for validated equipment. FDA 21 CFR Part 606 enforcement mandates continuous thermal monitoring, disqualifying aging inventory. Mayo Clinic and Kaiser Permanente systems in Minnesota and California consolidate multi-site procurement around connected platforms.
Germany
National blood service modernization and EU MDR post-market surveillance requirements elevate documentation burdens. Paul-Ehrlich-Institut compliance protocols shape vendor qualification. EFS-affiliated facilities in Frankfurt and Berlin cluster procurement around established notified body relationships.
Japan
Japanese Red Cross high-volume processing centers demand floor-standing batch configurations. PMDA quality management requirements align with international storage standards. Tokyo and Osaka metropolitan clusters anchor regional equipment deployment for operational economics at scale.
India
CDSCO harmonization with international storage standards accelerates blood banking modernization. Government hospital procurement budgets constrain capital expenditure in tier-2 cities. Maharashtra and Karnataka state health systems expand validated cold chain capacity for platelet pooling protocols.
France
ANSM oversight of blood establishments enforces stringent equipment qualification requirements. EFS national network consolidation drives standardization across regional processing centers. Paris and Lyon academic medical centers specify redundant sensor arrays for research-grade storage protocols.
Global Platelet Incubator Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the platelet incubator landscape. The upper tier commands premium positioning through captive manufacturing footprints and established regulatory dossiers. Mid-cap specialists compete on workflow-specific configurations for diagnostic centers and research laboratories. Dominant competitive moves include geographic expansion into harmonizing regulatory environments and portfolio diversification toward regenerative medicine applications.
Among integrated North American manufacturers, Helmer Scientific and Boekel Scientific occupy positions spanning hospital network and mid-tier diagnostic center segments respectively. Terumo Corporation anchors the Asia-Pacific vector through deep relationships with national blood banking systems. These three exemplify how regulatory dossier depth and manufacturing integration separate sustainable positioning from transactional equipment supply.
| Leading Market Players |
|---|
| Helmer Scientific |
| Terumo Corporation |
| Boekel Scientific |
| BIOBASE |
| Meditech Technologies India Private Limited |
| SARSTEDT AG & Co.KG |
| Lmb Technologie GmbH |
| LABCOLD |
| Biolab Scientific |
| Others |
Supply & Pricing Matrix
ISO 13485 certification timelines gate both vendor qualification and price differentiation simultaneously, extending 12-18 month delays for CE-marked distribution while compressing margins for uncertified competitors seeking hospital network procurement.
Pricing Analysis
After-sales service contracts drive lifetime value more than equipment margins, with preventive maintenance agreements and calibration subscriptions extending revenue streams five to seven years post-installation. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated digital monitoring platforms from basic thermal cabinets and unvalidated imports. Cost compression in the economy tier intensifies as Indian and Southeast Asian blood banks prioritize capital efficiency over telemetry integration. Diagnostic center networks exhibit highest price sensitivity; academic medical centers absorb premium positioning for Joint Commission compliance.
Supply Chain Analysis
Extended lead times for precision refrigeration compressors from German and Japanese suppliers constrain manufacturer inventory flexibility and extend order-to-delivery cycles. Component sourcing draws from compressor specialists in Germany, sensor arrays from Japan, and electronic controls from Taiwan. Single-source vulnerability concentrates in thermoelectric cooling modules, where qualified suppliers number fewer than five globally. Distribution runs through hospital supply chain departments unbundling service from capital purchases, with third-party biomedical service firms capturing standalone maintenance agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory dossier depth creates switching costs that entrench incumbent positions against displacement.
For Market Incumbents: Fortify installed base retention by deepening captive manufacturing of agitation mechanisms and thermal sensors, reducing exposure to German and Japanese component bottlenecks. Expand ISO 13485 certification coverage to emerging regenerative medicine CDMOs before specialized entrants capture stem cell laboratory procurement. Priority lever: predictive maintenance algorithms that reduce unplanned downtime and resist third-party service unbundling. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for benchtop configurations with pre-validated 21 CFR Part 606 documentation offer the most penetrable entry vector. Target India's CDSCO-harmonizing blood banking modernization, where government hospital procurement budgets constrain capital expenditure and favor validated economy-tier systems. Go-to-market angle: fleet-wide agreements with diagnostic center networks seeking LIMS-compatible workflow integration. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across digital monitoring sub-segments as cloud-connected telemetry platforms achieve scale economies. Five-to-ten year viability favors vendors with established notified body relationships and captive manufacturing footprints. Acquisition target archetype: mid-cap specialists with regenerative medicine application expertise and shallow CE-marked distribution. Signal to watch: hospital system consolidation velocity compressing replacement cycles for validated equipment.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EU MDR post-market surveillance requirements elevate documentation burdens for notified body relationships. |
| Hospital System Partnership | Kaiser Permanente and Mayo Clinic consolidation creates fleet-wide procurement leverage for connected platforms. |
| Software Companion Development | Cloud-connected temperature logging addresses Joint Commission audit-ready documentation requirements. |
| Backward Integration into Sensors | Captive supply of thermal arrays reduces German and Japanese component dependency and lead-time exposure. |
| Regenerative Medicine Application Expansion | Stem cell laboratory protocols in South Korea and Switzerland extend incubator demand beyond blood banking. |
Research Methodology
Initial hypotheses were tested against primary input from blood bank operations directors, biomedical equipment technicians, hospital purchasing committee members, and GPO contracts managers, and refined through secondary validation against FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and ISO 13485 certification registries. Bottom-up equipment shipment estimates were triangulated with top-down healthcare capital expenditure patterns.
Variance-decomposition across product type, technology tier, application maturity, and end-user procurement authority shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate reconciliation against macro healthcare infrastructure investment trends. Industry-specific forecast inputs included blood bank consolidation velocity and regenerative medicine laboratory expansion trajectories.
Decision-makers should treat outputs as directional under assumptions of continued FDA 21 CFR Part 606 enforcement and stable compressor supply from German and Japanese sources; material deviation in regulatory stringency or component availability would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Mortuary Equipment Market
Medical Equipment
Europe Medical Automation Market
Medical Equipment
Global Medical Lighting Technologies Market
Medical Equipment
Medical Cart Battery Market
Medical Equipment
PMMA Healthcare Market
Medical Equipment
Global Microtome Market
Medical Equipment
Global Embryo Incubator Market
Medical Equipment
Brazil Massage Equipment Market
Medical Equipment
Global Capnography Equipment Market
Medical Equipment
Global Medical Lasers Market
Medical Equipment
Asia-Pacific Medical Carts Market
Medical Equipment
Global Vacuum Mixing Devices Market
Medical Equipment
X-Ray Generator Market
Medical Equipment
Urodynamic Equipment Market
Medical Equipment
Podiatry Equipment Market
Medical Equipment
Global Surgical Lights Market