
 Asia-Pacific Nuclear Medicine Equipment Market | 2026-2036
Asia-Pacific Nuclear Medicine Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Nuclear Medicine Equipment Market Analytics
Japan's dual carbon goals and hospital energy-efficiency mandates are consolidating procurement standards across the Asia-Pacific nuclear medicine equipment landscape. GE HealthCare leverages its installed base of cyclotron systems to sustain service revenue across Japanese and Australian facilities. Siemens Healthineers anchors its position through R&D intensity in digital PET detector technology, while Canon Medical Systems Corporation competes on manufacturing scale in Southeast Asian markets.
Asia-Pacific nuclear medicine equipment encompasses ionizing radiation-based diagnostic and therapeutic systems that detect gamma ray emissions from administered radiopharmaceuticals, with SPECT and PET systems utilizing scintillation crystals measuring 4–6 millimeters in thickness to achieve spatial resolution below 5 millimeters for lesion detection. These systems serve primarily to localize metabolic activity for cancer staging, myocardial perfusion assessment, and neurodegenerative disease diagnosis. PET systems command the dominant margin pool due to cyclotron dependency and radiotracer half-life logistics, while hybrid imaging technology leads growth as hospitals integrate anatomical CT with functional nuclear data. Diagnostic centers represent the fastest-expanding end-user channel, though hospitals retain the largest absolute procurement volume across the region.
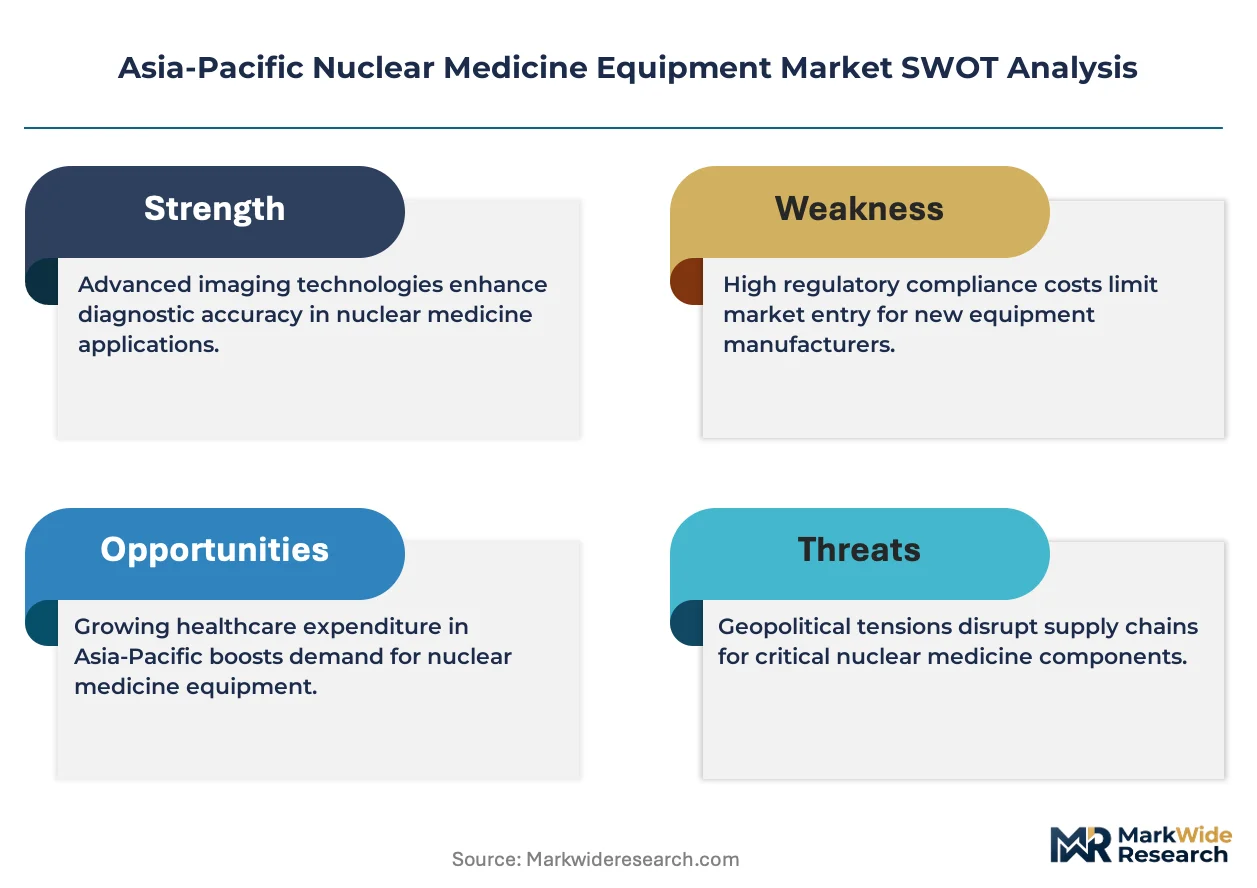
PMDA in Japan, China's NMPA, and Australia's TGA collectively shape product registration timelines, radiation safety certification, and clinical trial requirements for equipment deployment across the region. These regulators enforce divergent standards on detector calibration protocols and shielding specifications, creating compliance complexity for multinational suppliers. Stakeholders must monitor evolving radiopharmaceutical supply chain security policies and reimbursement adjustments for theranostic procedures to anticipate capital equipment deployment cycles.
Market Dynamics
Japan's PMDA streamlining of radiopharmaceutical approvals is compressing procurement cycles across the Asia-Pacific nuclear medicine equipment landscape, forcing suppliers to accelerate cyclotron deployment and service infrastructure buildout to match hospital network expansion timelines.
Growth Catalysts
- Dual carbon mandates:Japan's METI energy-efficiency standards for medical facilities are consolidating procurement specifications across hospital networks, creating standardized demand pools for low-power PET systems.
- Proton therapy center expansion:China's tier-one cities are scaling hybrid imaging capabilities at new proton facilities, requiring integrated PET-CT installations with specialized radiotracer logistics.
- Theranostic reimbursement pathways:Australia's TGA is expanding coverage for radioligand therapies, pulling diagnostic equipment procurement into oncology department capital budgets.
Market Restraints
- Molybdenum-99 supply concentration:Five aging reactors outside the Asia-Pacific region supply the majority of diagnostic isotopes, creating vulnerability to unplanned maintenance shutdowns.
- Detector material cost volatility:Lutetium-based scintillation crystals face price pressure from competing demand in solid-state lighting and radiation detection applications.
- Shielding specification divergence:China's GB standards, Japan's JIS requirements, and Australia's ARPANSA guidelines enforce incompatible lead-equivalent thicknesses for identical clinical applications.
Strategic Opportunities
- Southeast Asian diagnostic center buildout:Vietnam and Indonesia are licensing independent imaging facilities outside hospital systems, creating distributed demand for compact SPECT systems.
- Digital PET detector convergence:Silicon photomultiplier arrays combined with AI-based reconstruction algorithms are enabling lower-dose protocols that expand patient throughput.
- Radiopharmaceutical supply chain localization:South Korea's MFDS is incentivizing domestic cyclotron manufacturing through accelerated facility licensing.
Industry Challenges
- Qualified medical physicist scarcity:Calibration and quality assurance protocols for hybrid imaging systems require specialized training that outpaces regional education program output.
- Legacy SPECT integration friction:Hospital networks with installed analog detector systems face data format incompatibilities when upgrading to digital acquisition platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Nuclear Medicine Equipment Market |
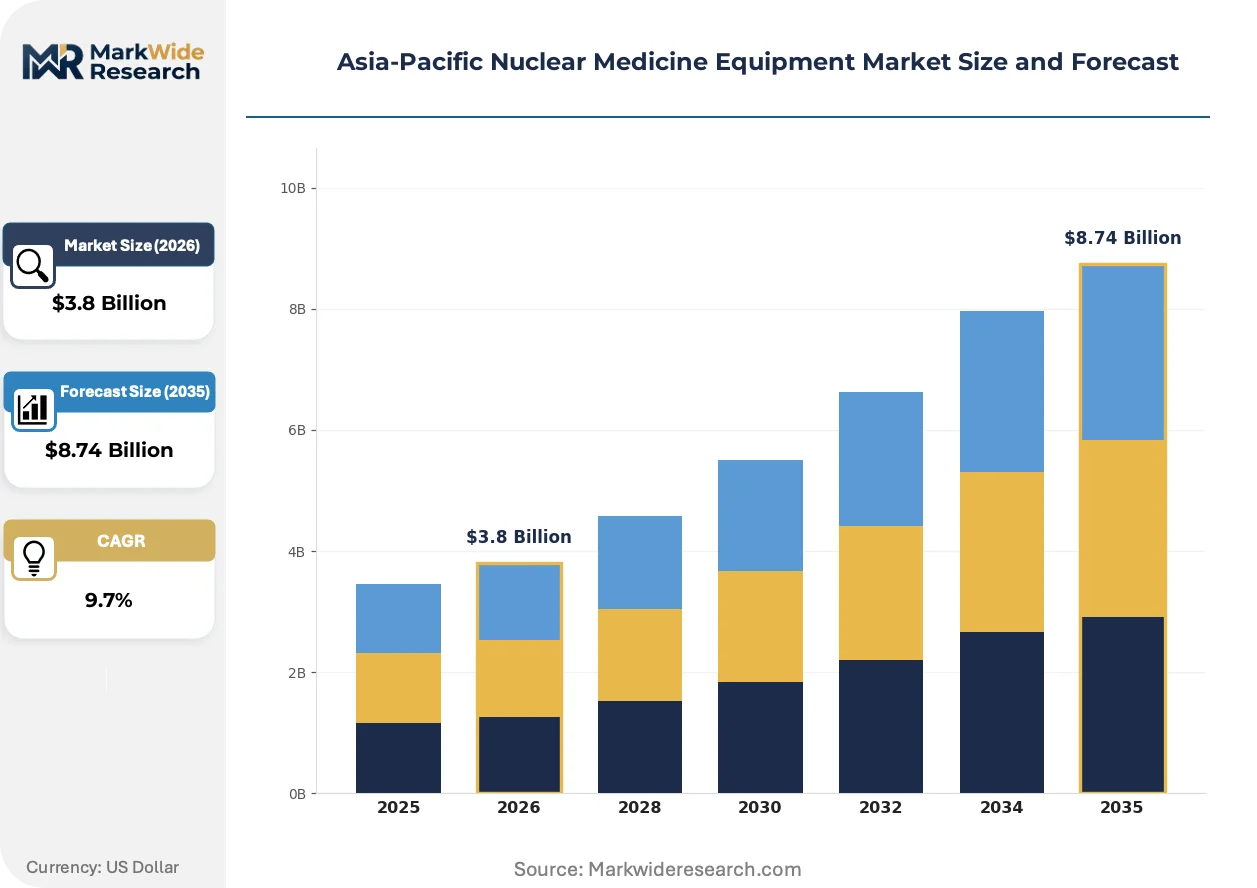
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gamma Cameras, SPECT Systems, PET Systems, Radioisotope Generators End User: Hospitals, Diagnostic Centers, Research Institutions, Outpatient Clinics Technology: Hybrid Imaging, Molecular Imaging, Digital Imaging, Conventional Imaging Application: Oncology, Cardiology, Neurology, Pediatrics |
| Companies Covered | GE HealthCare, Siemens Healthineers, Koninklijke Philips N.V., Canon Medical Systems Corporation, Neusoft Medical Systems Co., Ltd., Mediso Ltd., Shenzhen Anke High-tech Co., Ltd., China Isotope & Radiation Corp., Jubilant Pharmova Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Nuclear Medicine Equipment Market Evolving Landscape
Digital detector architectures are actively reshaping competitive positioning in the Asia-Pacific nuclear medicine equipment market, compressing the performance gap between premium and mid-tier system categories while enabling new service-based revenue models.
Silicon photomultiplier-based PET detectors are overtaking traditional photomultiplier tube arrays in new installations across Japanese university hospitals and Australian private imaging networks. These solid-state sensors eliminate magnetic field sensitivity, enabling simultaneous PET-MRI operation without interference shielding. The technology is overtaking analog signal chains by reducing detector volume requirements by half, allowing equipment manufacturers to shrink system footprints for Southeast Asian facilities with space-constrained installation sites.
PMDA's 2023 guidance on software-as-a-medical-device classification is redefining regulatory boundaries for AI-enabled reconstruction algorithms in Japan. The policy requires standalone validation of deep-learning denoising tools, extending approval timelines for integrated PET-CT systems. Japanese OEMs are responding by modularizing software components to permit independent update cycles without full system recertification.
Diagnostic centers in China's tier-one cities are consolidating procurement decisions under centralized purchasing alliances that negotiate multi-year service bundles alongside equipment acquisition. These alliances are displacing traditional distributor networks by demanding direct manufacturer relationships with transparent parts pricing and guaranteed uptime penalties. The shift is most visible in Shanghai and Beijing, where municipal health authorities have mandated standardized equipment specifications across public-private joint venture imaging facilities.
Asia-Pacific Nuclear Medicine Equipment Market Segmentation
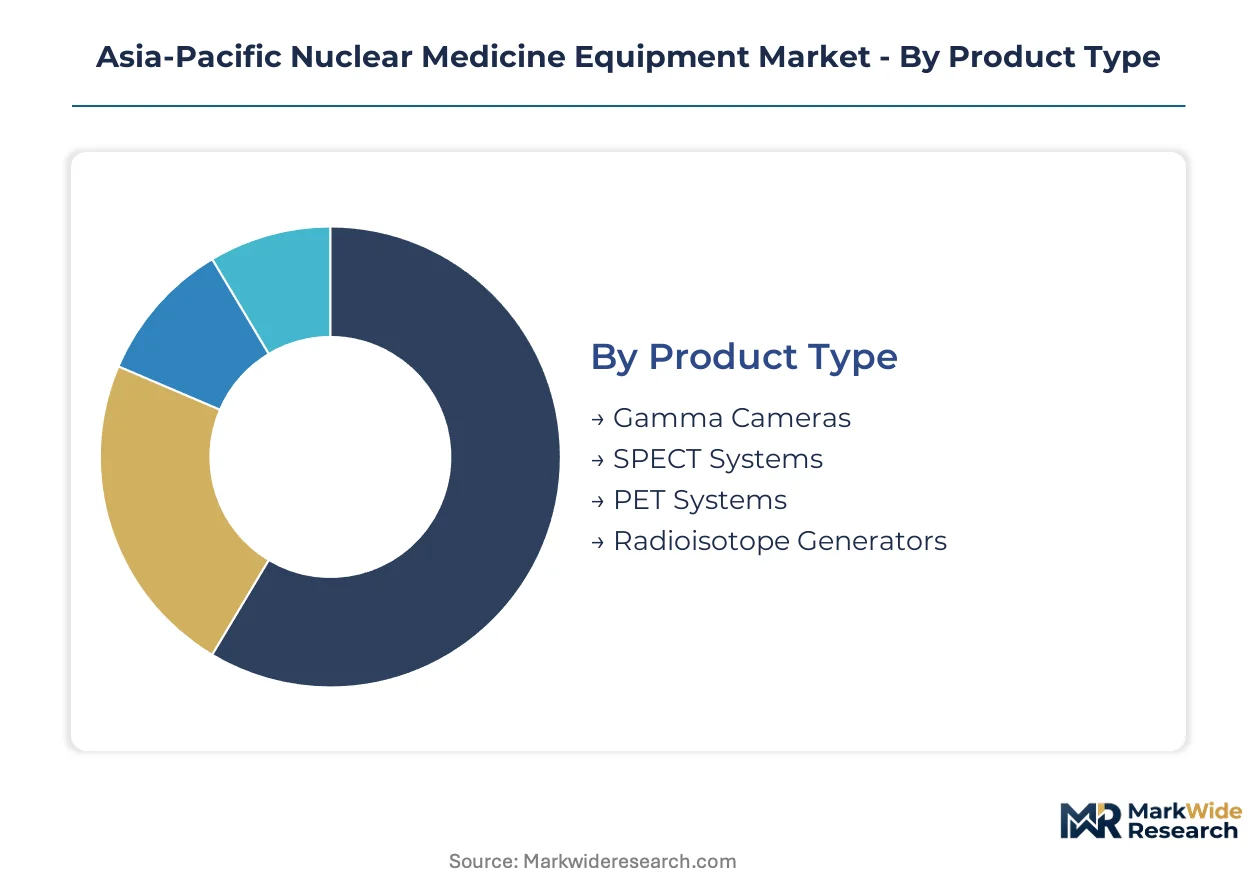
Segmentation in the Asia-Pacific nuclear medicine equipment market reveals how regulatory pathways, procurement budgets, and clinical workflows fragment demand across distinct equipment categories. Understanding these divisions clarifies where capital deployment concentrates and which technology tiers attract investment priority.
Product Type:
PMDA clearance timelines vary substantially across these equipment classes, with cyclotron-dependent systems facing extended radiopharmaceutical co-approval requirements that compress procurement velocity for PET platforms.
- Gamma Cameras:Single-head and dual-head Anger camera configurations utilizing sodium iodide crystals for planar scintigraphy. Demand concentrates in India's tier-two hospital expansion programs where cost constraints favor refurbished analog systems over digital upgrades.
- SPECT Systems:Rotating gamma camera arrays with multi-detector geometries enabling tomographic reconstruction. China's county-level hospital networks are standardizing on dual-detector SPECT-CT configurations to meet NMPA diagnostic imaging mandates for cardiac perfusion studies.
- PET Systems:Ring-detector geometries with lutetium oxyorthosilicate scintillation arrays requiring cyclotron proximity for fluorine-18 logistics.
- Radioisotope Generators:Molybdenum-99/technetium-99m elution systems for decentralized isotope production.
PET Systems sit at the top of the volume ranking, with Radioisotope Generators climbing the fastest as South Korea and Australia pursue supply chain localization.
End User:
Procurement authority and reimbursement pathways diverge sharply across these customer types, with hospital networks leveraging capital scale against diagnostic centers' volume-based equipment utilization models.
- Hospitals:Integrated health systems with dedicated nuclear medicine departments and in-house radiopharmacy capabilities. Japan's METI energy-efficiency mandates are consolidating procurement specifications across university hospital networks, favoring low-power PET system standardization.
- Diagnostic Centers:Independent imaging facilities operating on fee-for-service models with high throughput requirements. Vietnam's licensing reforms for standalone imaging facilities are accelerating compact SPECT deployment outside hospital ownership structures.
- Research Institutions:Academic medical centers with clinical trial infrastructure and exploratory radiotracer development programs.
- Outpatient Clinics:Limited-service settings focusing on myocardial perfusion imaging and thyroid uptake studies.
Hospitals retain the dominant procurement volume position, though Diagnostic Centers are expanding most quickly as Southeast Asian licensing frameworks liberalize.
Technology:
Margin structures and service revenue potential stratify across these technology tiers, with hybrid configurations commanding premium pricing and digital platforms enabling recurring software subscription models.
- Hybrid Imaging:Anatomical-functional fusion systems combining PET or SPECT with CT or MRI for co-registered datasets. China's proton therapy center buildout in Shanghai and Beijing is pulling integrated PET-CT installations into oncology capital budgets with specialized radiotracer logistics requirements.
- Molecular Imaging:Radiotracer-specific detection platforms optimized for receptor-targeted and metabolic pathway visualization.
- Digital Imaging:Silicon photomultiplier-based detector arrays with AI-enabled reconstruction algorithms. Australian private imaging networks are prioritizing digital PET detector upgrades to eliminate magnetic field sensitivity and enable simultaneous PET-MRI operation.
- Conventional Imaging:Analog photomultiplier tube architectures with established service infrastructure and lower capital thresholds.
Hybrid Imaging leads absolute revenue contribution, while Digital Imaging gains share fastest as Japanese university hospitals accelerate detector replacement cycles.
Application:
Reimbursement density and procedure volume intensity vary across clinical specialties, with oncology commanding capital priority due to theranostic integration and radioligand therapy expansion.
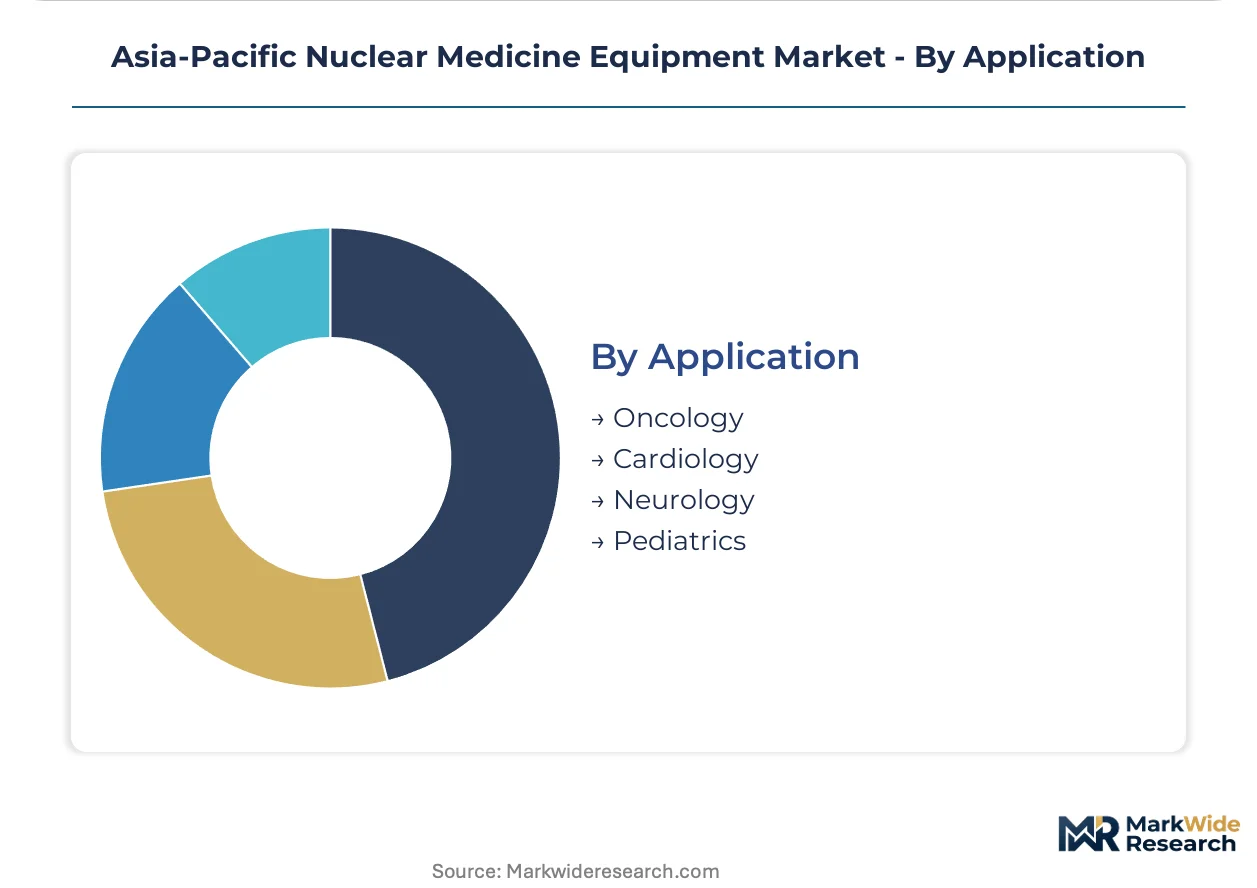
- Oncology:Cancer staging, treatment response monitoring, and radioligand therapy planning utilizing FDG and prostate-specific membrane antigen tracers. Australia's TGA reimbursement expansion for lutetium-177 therapies is pulling diagnostic equipment procurement into oncology department capital allocations.
- Cardiology:Myocardial perfusion imaging and viability assessment using technetium-99m and thallium-201 agents.
- Neurology:Amyloid and tau imaging for neurodegenerative disease diagnosis with specialized radiotracer requirements.
- Pediatrics:Low-dose protocols and size-optimized detector configurations for pediatric oncology and cardiology applications.
Oncology dominates absolute equipment deployment, with Cardiology maintaining steady replacement demand across mature hospital networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan pioneered commercial cyclotron manufacturing and hybrid imaging integration in the 1980s, establishing technical standards that shaped procurement specifications across Asia-Pacific. This historical foundation continues to influence regulatory frameworks and equipment deployment patterns throughout the region.
Japan
University hospital networks in Tokyo and Osaka are accelerating digital PET detector replacement cycles to meet METI energy-efficiency mandates for medical facilities. PMDA's streamlined radiopharmaceutical approval pathways are compressing procurement timelines for cyclotron-dependent systems. The Kanto region anchors the highest concentration of PET-MRI installations, with Nagoya's Chubu medical corridor emerging as a secondary hub for theranostic procedure development.
China
Proton therapy centers in Shanghai and Beijing are scaling hybrid imaging capabilities, pulling integrated PET-CT installations into oncology capital budgets with specialized radiotracer logistics requirements. NMPA diagnostic imaging mandates for county-level hospital networks are standardizing dual-detector SPECT-CT configurations for cardiac perfusion studies. The Yangtze River Delta concentrates the fastest equipment deployment, with Shenzhen-based manufacturers supplying compact systems to tier-two city expansions.
Australia
Private imaging networks in Sydney and Melbourne are prioritizing silicon photomultiplier-based PET detector upgrades to eliminate magnetic field sensitivity and enable simultaneous PET-MRI operation. TGA reimbursement expansion for lutetium-177 radioligand therapies is pulling diagnostic equipment procurement into oncology department capital allocations. The southeastern corridor maintains the region's densest concentration of independent diagnostic centers operating outside hospital ownership structures.
South Korea
Domestic cyclotron manufacturing is receiving MFDS incentives through accelerated facility licensing, reducing dependency on imported isotope supply chains. Seoul's university-affiliated medical centers are deploying digital imaging platforms with AI-enabled reconstruction algorithms to expand patient throughput. The capital region hosts the majority of research institutions engaged in exploratory radiotracer development programs.
Vietnam
Standalone imaging facilities in Ho Chi Minh City and Hanoi are licensing operations outside hospital systems, creating distributed demand for compact SPECT systems with space-constrained footprints. Regulatory reforms for independent diagnostic center establishment are accelerating equipment procurement from Chinese and Japanese suppliers. The southern economic zone concentrates the fastest buildout of fee-for-service imaging capacity.
Asia-Pacific Nuclear Medicine Equipment Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the Asia-Pacific nuclear medicine equipment landscape, creating a tiered structure where integrated health technology conglomerates anchor premium positioning while regional specialists capture mid-market volume. The vendor base stratifies across three archetypes: cyclotron-integrated system suppliers leveraging radiopharmaceutical logistics dependencies, digital detector technology specialists monetizing software-enabled service models, and manufacturing-scale competitors optimizing production costs for Southeast Asian price sensitivity. Dominant competitive moves include strategic partnerships with radiopharmaceutical distributors and geographic expansion through localized assembly operations.
Within the integrated health technology tier, GE HealthCare and Siemens Healthineers occupy positions sustained by cyclotron system installed bases and service infrastructure density across Japanese and Australian facilities. Canon Medical Systems Corporation exemplifies the manufacturing-scale archetype competing on production volume for Southeast Asian market penetration. Among Asia-based specialists, Neusoft Medical Systems Co., Ltd. and Shenzhen Anke High-tech Co., Ltd. represent regional players capitalizing on domestic procurement preferences and standardized NMPA certification pathways.
| Leading Market Players |
|---|
| GE HealthCare |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| Canon Medical Systems Corporation |
| Neusoft Medical Systems Co., Ltd. |
| Mediso Ltd. |
| Shenzhen Anke High-tech Co., Ltd. |
| China Isotope & Radiation Corp. |
| Jubilant Pharmova Limited |
| Others |
Value Network & Pricing Analysis
China's tier-one city hospital procurement alliances concentrate equipment purchasing decisions under standardized specifications, anchoring a three-tier pricing structure across premium, standard, and economy levels that compresses margins for mid-tier suppliers while rewarding cyclotron-integrated system vendors with recurring service revenue streams.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates equipment transactions, with differentiation driven by detector resolution grade and NMPA certification tier. Price erosion runs through the economy tier as Shenzhen-based manufacturers scale compact SPECT production for county-level hospital networks. Diagnostic centers in Vietnam and Indonesia exhibit highest price sensitivity due to capital constraints, while Japan's university hospital networks prioritize energy-efficiency ratings over upfront cost.
Supply Chain Analysis
Single-source vulnerability sits with Belgium, Netherlands, and South Africa reactor facilities supplying Molybdenum-99 feedstock for technetium-99m generators. Lutetium oxyorthosilicate crystals and silicon photomultiplier arrays draw from Japanese and German specialty material suppliers. Tariff exposure on detector electronics creates procurement timing risk for Chinese OEMs. Distribution runs through radiopharmaceutical logistics partnerships that tether equipment sales to cyclotron service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific nuclear medicine equipment market functions as a geographic-arbitrage play where South Korea's MFDS accelerated licensing timelines for domestic cyclotron manufacturing create cost advantages against Japan's lengthier PMDA radiopharmaceutical co-approval requirements.
For Market Incumbents: Extend cyclotron service infrastructure density across Australian and Southeast Asian facilities to lock in recurring revenue against emerging Chinese OEMs with lower capital thresholds. Deepen detector calibration protocol standardization under METI energy-efficiency mandates to raise switching costs for Japanese hospital networks. Prioritize backward integration into lutetium-based scintillation crystal supply to offset material cost volatility. For New Entrants and Emerging Players: Vietnam's standalone diagnostic center licensing reforms represent the most penetrable buyer archetype, with space-constrained compact SPECT systems commanding premium positioning against refurbished analog alternatives. Indonesia's tier-two city hospital expansion programs offer secondary white-space entry through NMPA-aligned certification pathways. Pursue direct manufacturer relationships with municipal health procurement alliances to bypass traditional distributor networks. For Investors and Strategic Acquirers: Health technology conglomerates with radiopharmaceutical distribution assets are the most active acquirer in this space, consolidating cyclotron-dependent system suppliers to capture theranostic procedure growth. Long-term viability hinges on digital detector platform transitions and AI-enabled reconstruction algorithm validation. Monitor PMDA software-as-a-medical-device classification enforcement as an inflection indicator for modular software component monetization potential.| Strategic Initiative | Industry Significance |
|---|---|
| Cyclotron Supply Chain Localization | South Korea's MFDS incentives reduce isotope import dependency and compress procurement timelines for domestic facilities. |
| Digital Detector Platform Migration | Silicon photomultiplier arrays enable PET-MRI integration and shrink system footprints for Southeast Asian space constraints. |
| Radiopharmaceutical Logistics Partnership | Integrated service contracts with fluorine-18 distribution networks lock in equipment placement and recurring revenue streams. |
| Software-as-Medical-Device Modularization | PMDA's 2023 guidance permits independent AI reconstruction algorithm updates without full system recertification cycles. |
| Diagnostic Center Licensing Expansion | Vietnam's regulatory reforms for independent imaging facilities create distributed demand outside hospital ownership structures. |
Research Methodology
Coverage spans Japan, China, Australia, South Korea, and Vietnam, with primary inputs from each market combining interviews with hospital procurement committee members, biomedical engineers, cyclotron facility operators, and GPO contracts managers alongside secondary validation from NMPA filings, PMDA approval databases, TGA reimbursement schedules, and hospital equipment procurement records. Bottom-up equipment shipment tallies triangulate against top-down radiopharmaceutical production capacity estimates.
Granularity-level modeling disaggregates volume and value outputs across product type, end user, technology tier, and application dimensions, with hybrid imaging configurations and digital detector platforms receiving discrete treatment. CAGRs derive from equipment replacement cycle analysis, radiopharmaceutical supply expansion trajectories, and reimbursement pathway evolution across the projection horizon. Inputs include METI energy-efficiency mandate compliance timelines and MFDS cyclotron licensing velocity.
Underlying measurement precision varies by segment; PET systems and hybrid imaging configurations carry tighter precision than conventional gamma cameras due to cyclotron dependency transparency. Forecasts reflect assumptions on radiopharmaceutical supply chain stability, regulatory approval pathway durations, and hospital capital budget allocation priorities. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
PCR Plate Sealer Market
Medical Equipment
Global Platelet Agitator Market
Medical Equipment
Operating Light Market
Medical Equipment
Medical Equipment Rental Market
Medical Equipment
Global Kidney Dialysis Equipment and Supplies Market
Medical Equipment
Hybrid Operating Room Market
Medical Equipment
Global Ultra Low Temperature Freezers Market
Medical Equipment
Tanning Units Market
Medical Equipment
Europe Nuclear Medicine Equipment Market
Medical Equipment
Chile Radiotherapy Market
Medical Equipment
Global Indirect Calorimeter Market
Medical Equipment
X-Ray Machine Manufacturing Market
Medical Equipment
Global Medical Power Supply Market
Medical Equipment
Dialysis Equipment Market
Medical Equipment
Apheresis Equipment Market
Medical Equipment
Global Laminar Airflow Cabinets Market