
 Birthing Beds Market | 2026-2036
Birthing Beds Market Size, Share, and Industry Trends Forecast 2026-2036
Birthing Beds Market Insights
ISO 13485 certification is rotating as the primary gating mechanism for supplier qualification in maternal-care equipment, forcing smaller fabricators to either invest in quality-management systems or exit tender pools. Stryker Corporation leverages its integrated manufacturing footprint across North America and Europe to sustain bid competitiveness on large hospital contracts. Hill-Rom Holdings, Inc. anchors premium positioning through dedicated labor-and-delivery engineering teams, while Linet Group SE specializes in configurable modular platforms that accommodate regional ergonomic preferences.
Birthing beds are height-adjustable medical platforms engineered for obstetric procedures, typically supporting Trendelenburg and lithotomy positioning via electric or hydraulic actuation with load ratings exceeding 250 kg; their primary purpose centers on enabling safe patient transfer, epidural access, and emergency resuscitation during labor. Electric beds with automated controls command the widest installed base in tertiary hospitals where nurse-staffing costs make one-touch positioning economically justified. Convertible beds represent the fastest-growing product category as facilities seek dual-use assets that transition from antenatal examination to active delivery without room transfers.
FDA 510(k) clearance and EU MDR Class I classification govern market access, with the latter's strengthened post-market surveillance requirements extending compliance costs for steel-frame and foam-upholstery suppliers. Japan's PMDA enforces localized electrical-safety testing that adds six to nine months to product registration timelines for foreign manufacturers. Stakeholders must monitor how WHO maternal-health initiatives and national safe-birth campaigns redirect procurement budgets toward beds with integrated fetal-monitoring mounts and emergency resuscitation capabilities.
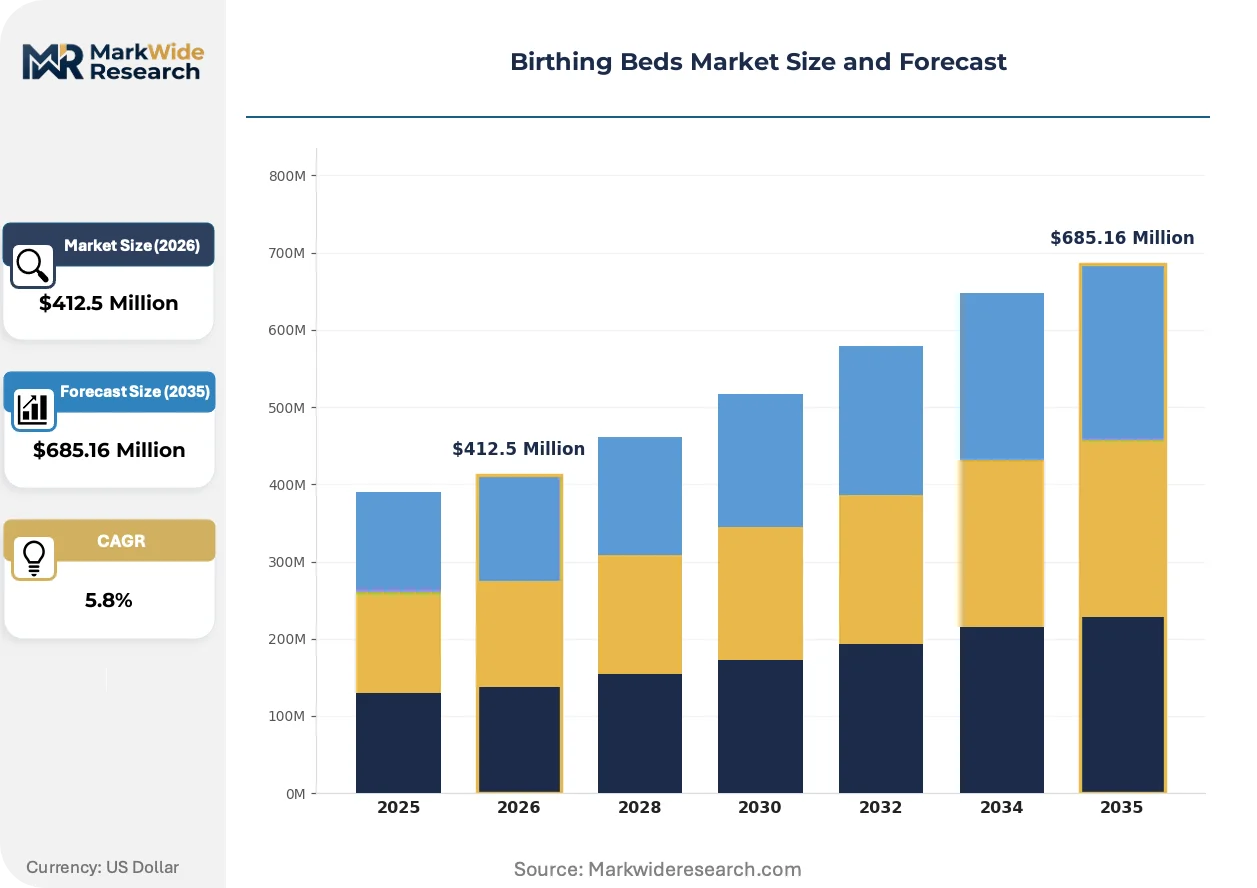
Market Dynamics
Hospital systems in Germany, the United States, and Japan are consolidating labor-delivery unit upgrades into single procurement cycles, forcing birthing bed suppliers to bundle automated positioning systems with extended service agreements to win multi-year contracts.
Growth Catalysts
- EU MDR post-market surveillance mandates:Tertiary hospitals across France and Italy are replacing legacy hydraulic beds with electric models to satisfy Class I device tracking requirements, accelerating replacement cycles.
- Integrated fetal-monitoring mounts:WHO maternal-health initiatives in Brazil and Nigeria are redirecting procurement budgets toward beds with emergency resuscitation capabilities and built-in monitoring hardware.
- Nurse-staffing cost pressures:Hospital systems in California and Texas prioritize one-touch positioning controls to reduce manual handling injuries and overtime expenditure.
Market Restraints
- Stainless steel and medical-grade foam input volatility:European steel tariffs and petrochemical price swings compress margins for frame and upholstery fabricators operating on fixed-price tenders.
- PMDA electrical-safety testing timelines:Foreign manufacturers face six-to-nine-month registration delays in Japan, freezing market entry for mid-tier suppliers lacking local certification partners.
- Manual birthing stools and floor-based delivery methods:Natural birth advocates in Netherlands and Scandinavian maternity centers resist capital-intensive bed purchases, capping addressable volume.
Strategic Opportunities
- India's expanding private maternity hospital chains:Apollo and Fortis networks in Mumbai and Bangalore are standardizing on convertible examination-delivery platforms, creating demand for mid-range modular configurations.
- US IRA hospital infrastructure grants:Federally funded rural critical access hospitals in Mississippi and Kentucky are accessing capital for labor unit modernization, opening price-sensitive segments.
- Telemedicine-enabled remote positioning:Convergence of IoT actuators and cloud-based monitoring allows manufacturers to offer predictive maintenance subscriptions alongside hardware sales.
Industry Challenges
- ISO 13485 quality-management system implementation:Smaller fabricators in Eastern Europe and Southeast Asia lack documentation infrastructure to satisfy supplier qualification gates, excluding them from hospital tender pools.
- Legacy hydraulic bed fleet integration:Facilities with mixed actuator technologies face technician training fragmentation and incompatible spare parts inventories, complicating service contract standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Birthing Beds Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Beds, Electric Beds, Convertible Beds, Specialty Beds End User: Hospitals, Maternity Centers, Clinics, Home Care Technology: Basic Mechanism, Hydraulic, Pneumatic, Automated Controls Material: Steel, Aluminum, Wood, Foam, Others |
| Companies Covered | Hill-Rom Holdings, Inc., Stryker Corporation, Getinge AB, Invacare Corporation, Medline Industries, Inc., Linet Group SE, Arjo AB, Paramount Bed Co., Ltd., Stiegelmeyer Krankenhausmöbel GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Birthing Beds Market Trends and Innovations
Sensor-embedded birthing platforms are compressing the boundary between capital equipment and digital health infrastructure, enabling real-time maternal positioning analytics that feed into hospital quality dashboards and insurance reimbursement documentation.
Capacitive load-cell arrays embedded in bed frames are miniaturizing to the point of invisibility beneath standard upholstery, allowing continuous weight and position tracking without protruding hardware. Tertiary hospitals in Massachusetts and Bavaria are piloting these systems for fall-risk alerts and epidural positioning verification. The technology is miniaturizing cost structures for integrated monitoring, collapsing the premium gap between basic electric beds and telemetry-equipped platforms.
Japan's PMDA revised electrical-safety standards for medical actuators in 2023, requiring additional insulation testing and documentation for imported motor systems. Domestic manufacturers with captive JIS-certified component supply chains are absorbing compliance costs more efficiently than foreign competitors, tilting procurement decisions toward local brands in Tokyo and Osaka metropolitan tenders. European suppliers are responding by establishing Tokyo-based regulatory liaison offices to compress resubmission cycles.
Hospital procurement committees are unbundling after-sales service from capital purchase contracts, negotiating three-year hardware warranties separately from preventive maintenance agreements. This behavior is most pronounced in Texas and Florida health systems where capital budgets and operational expenditures sit under different administrative controls. Distributors are responding with modular service tiers—basic parts coverage, full labor-inclusive plans, and on-demand technician dispatch—allowing facilities to match service spend to actual utilization intensity.
Birthing Beds Market Segmentation
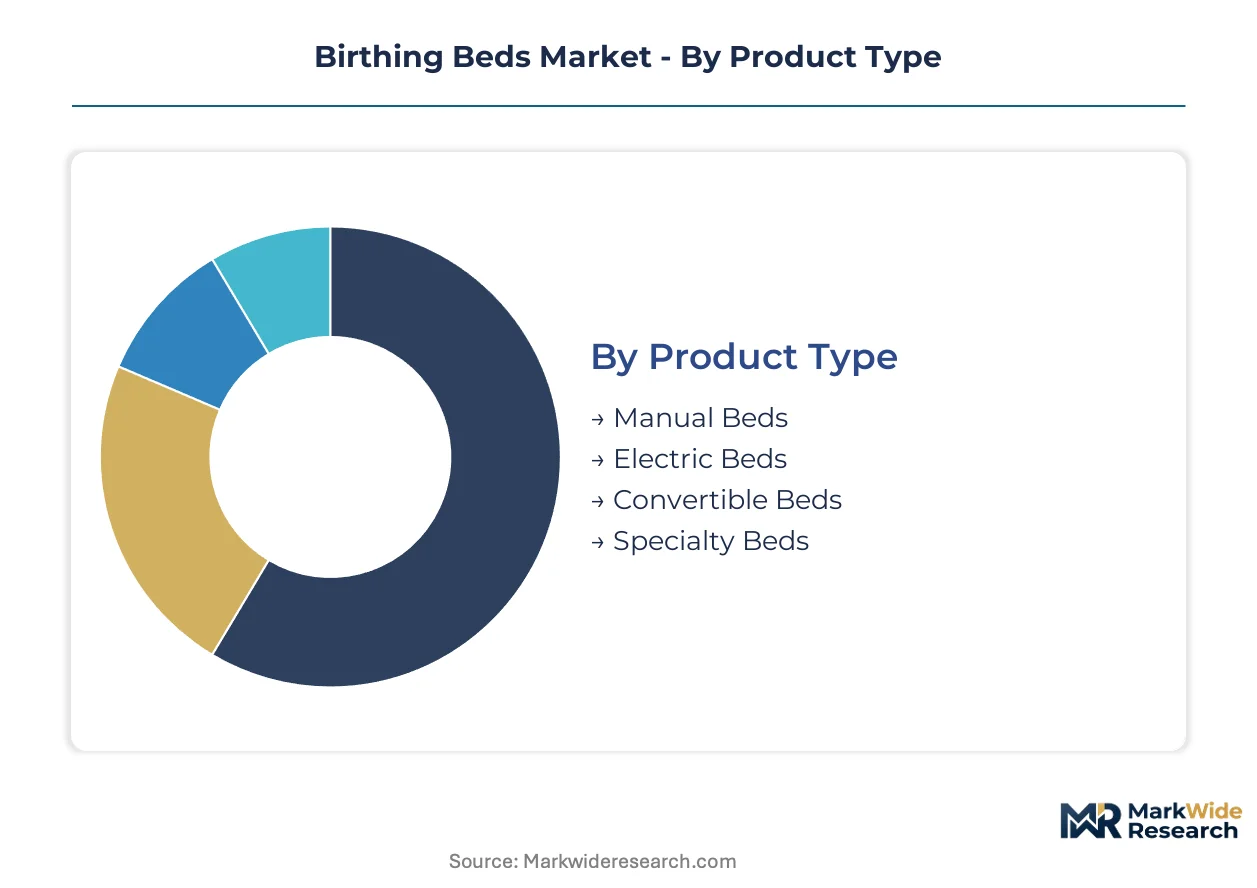
Segmentation in birthing beds separates procurement patterns across facility tiers and technology readiness. Electric and convertible platforms dominate tertiary hospital tenders, while manual configurations persist in price-sensitive maternity centers and emerging markets.
Product Type:
Manual beds concentrate in domestic procurement cycles across India and Southeast Asia, whereas electric and convertible platforms drive export-led revenue from German and Japanese manufacturers.
- Manual Beds:Hand-cranked height and backrest adjustment with mechanical locking casters. Demand clusters in rural Indian maternity centers and Nigerian district hospitals where capital budgets exclude powered actuation and technician maintenance capacity is limited.
- Electric Beds:Motorized Trendelenburg, lithotomy, and height positioning via handset or foot controls. Tertiary hospitals in Texas, Bavaria, and Tokyo standardize on these for labor-delivery units, justified by nurse injury reduction and one-touch emergency positioning.
- Convertible Beds:Modular platforms transitioning from antenatal examination to active delivery without patient transfer. Apollo and Fortis networks in Mumbai and Bangalore are standardizing these dual-use assets.
- Specialty Beds:Bariatric-rated frames exceeding 300 kg capacity and water-birth compatible designs with integrated immersion tubs.
Electric beds hold the largest share; momentum sits with convertible beds.
End User:
Procurement authority fragments across capital budget owners, with hospitals consolidating multi-year tenders while maternity centers and clinics purchase through distributor spot-buy channels.
- Hospitals:Acute-care systems with dedicated labor-delivery units and emergency resuscitation protocols. Kaiser Permanente in California and Charité in Berlin bundle automated birthing beds with fetal monitoring infrastructure.
- Maternity Centers:Standalone obstetric facilities emphasizing low-intervention birth. Dutch birth centers and Scandinavian maternity houses prioritize manual and hydraulic configurations over capital-intensive electric platforms.
- Clinics:Outpatient antenatal and postnatal service providers. Urban Indian polyclinics in Bangalore and Hyderabad deploy basic examination beds with detachable stirrups.
- Home Care:Rental and purchase channels for planned home births. UK midwife-led home birth services and Australian private midwifery practices source lightweight aluminum frames.
Hospitals command the dominant procurement volume; maternity centers are expanding most quickly in India's private sector.
Technology:
Actuator technology stratifies by maintenance infrastructure availability, with automated controls requiring dedicated biomedical engineering support concentrated in tertiary urban centers.
- Basic Mechanism:Mechanical linkages and hand-operated cranks without powered components. Nigerian and Kenyan district hospitals specify these for reliability in settings with intermittent electrical supply.
- Hydraulic:Fluid-pressure height and position adjustment with manual release valves. Legacy fleet concentration in Italian and Spanish public hospitals now facing EU MDR replacement pressure.
- Pneumatic:Compressed-air actuation for backrest and leg section articulation. Limited installed base in Japanese rural clinics leveraging existing compressor infrastructure.
- Automated Controls:Programmable position memory, integrated scale systems, and IoT-enabled predictive maintenance. Massachusetts General and Munich's Klinikum rechts der Isar pilot sensor-embedded platforms for maternal positioning analytics.
Automated controls are gaining share fastest; hydraulic systems retain residual presence in Southern European replacement cycles.
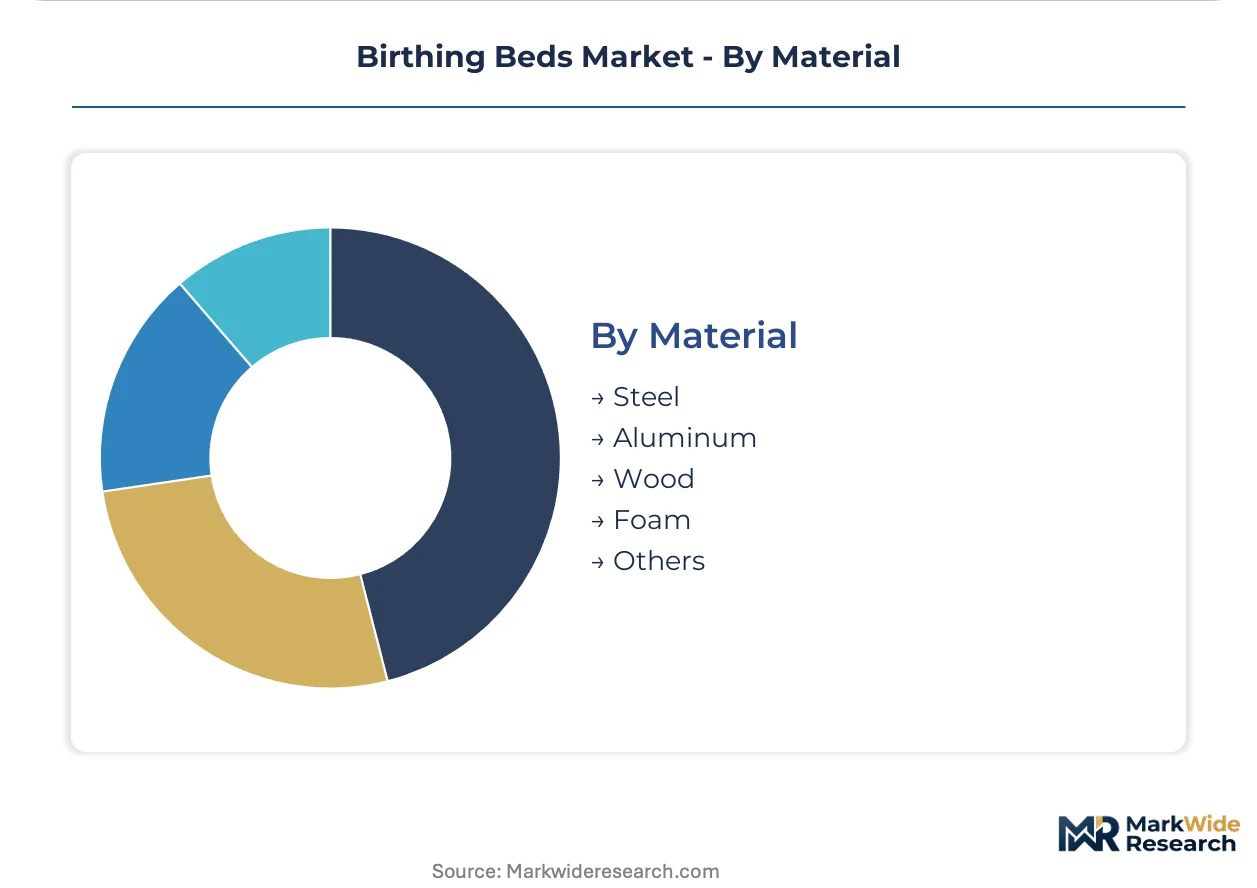
Material:
Frame and upholstery material selection tracks infection control protocols and regional supply chain proximity, with stainless steel dominating institutional procurement and aluminum penetrating home care channels.
- Steel:Powder-coated or stainless tubular frames supporting load ratings above 250 kg. German and US hospital systems specify medical-grade stainless for steam sterilization compatibility.
- Aluminum:Lightweight extruded frames for portable and home care applications. Australian and UK home birth services prioritize these for transportability.
- Wood:Aesthetic finishes for low-intervention birth centers. Dutch and Danish maternity houses specify beech and birch laminates.
- Foam:Medical-grade polyurethane upholstery with antimicrobial coatings and pressure-relief contouring.
- Others:Composite polymers and fiberglass-reinforced plastics for water-birth tub integration.
Steel frames anchor institutional procurement; aluminum is climbing the fastest in home care and rental segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in Germany, the United States, and Japan concentrate the largest tender volumes for electric birthing beds with automated positioning systems. These three markets anchor replacement demand as regulatory standards tighten and labor-delivery units modernize.
United States
Kaiser Permanente and HCA Healthcare systems in California and Texas drive consolidated procurement of electric birthing beds with one-touch positioning controls. FDA 510(k) clearance requirements govern market access, with post-market surveillance obligations extending compliance documentation. Massachusetts General Hospital pilots sensor-embedded platforms for maternal positioning analytics.
Germany
Charité Berlin and university hospitals across Bavaria bundle automated birthing beds with fetal monitoring infrastructure in multi-year tenders. EU MDR Class I classification and strengthened post-market surveillance accelerate replacement of legacy hydraulic fleets. Munich's Klinikum rechts der Isar integrates predictive maintenance subscriptions with hardware procurement.
Japan
Metropolitan hospitals in Tokyo and Osaka tilt procurement toward domestic manufacturers with captive JIS-certified component supply chains. PMDA electrical-safety testing adds six to nine months to foreign manufacturer registration timelines. European suppliers establish Tokyo-based regulatory liaison offices to compress resubmission cycles.
India
Apollo and Fortis private maternity hospital chains in Mumbai and Bangalore standardize on convertible examination-delivery platforms. The country's national pharmaceutical regulator oversees medical device registration with localized quality-management requirements. Urban polyclinics in Hyderabad deploy basic examination beds with detachable stirrups for antenatal services.
Brazil
WHO maternal-health initiatives redirect public procurement budgets toward birthing beds with integrated fetal-monitoring mounts and emergency resuscitation capabilities. ANVISA medical device regulations require in-country testing for electrical safety. São Paulo's hospital network concentrates demand for mid-range electric configurations.
Birthing Beds Market Competitive Landscape
Player mix skews toward diversified medical equipment conglomerates with integrated manufacturing footprints across multiple continents. The supplier base concentrates around three strategic archetypes: premium-tier engineering specialists with dedicated labor-delivery teams, scale-driven manufacturers leveraging North American and European production networks, and modular platform fabricators accommodating regional ergonomic preferences. Dominant competitive moves include geographic expansion through regulatory liaison offices and portfolio diversification into predictive maintenance subscriptions.
Among diversified medical technology conglomerates, Stryker Corporation and Hill-Rom Holdings, Inc. occupy positions exemplifying scale-driven manufacturing and premium-tier engineering specialization respectively. Linet Group SE represents the modular platform archetype with configurable designs. Getinge AB and Arjo AB sit within the European engineering-intensive tier, while Paramount Bed Co., Ltd. anchors domestic Japanese supply chains.
| Leading Market Players |
|---|
| Hill-Rom Holdings, Inc. |
| Stryker Corporation |
| Getinge AB |
| Invacare Corporation |
| Medline Industries, Inc. |
| Linet Group SE |
| Arjo AB |
| Paramount Bed Co., Ltd. |
| Stiegelmeyer Krankenhausmöbel GmbH & Co. KG |
| Others |
Pricing and Supply Chain Analysis
Steel-to-aluminum frame substitution in home care segments simultaneously shifts procurement geography toward Southeast Asian extrusion hubs and compresses per-unit manufacturing economics for rental channel suppliers.
Pricing Analysis
Cost-plus contracts with stainless steel indexation dominate German and US hospital tenders, insulating fabricators from European tariff volatility while compressing margins for fixed-price agreements in emerging markets. Price differentiation centers on ISO 13485 certification tier and bundled predictive maintenance subscriptions. Pricing pressure intensifies in manual bed segments as Indian domestic manufacturers absorb petrochemical foam cost swings. Rural critical access hospitals in Mississippi and Kentucky exhibit highest price sensitivity; tertiary systems in Bavaria and Tokyo prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
Inventory buffers for medical-grade actuators stretch lead times for European and Japanese manufacturers sourcing from Chinese motor suppliers. Frame fabrication concentrates in Germany, China, and Poland; upholstery foam production centers on Belgium and South Korea. Supply chains draw from stainless steel mills, polyurethane chemical feedstocks, and precision actuator assemblies. Single-source vulnerability in JIS-certified electrical components for Japanese market entry poses structural risk. Distribution runs through regional medical equipment distributors with GPO contract access in the United States and direct hospital sales teams in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a replacement cycle recovery as EU MDR post-market surveillance mandates accelerate hydraulic fleet obsolescence across Southern European hospital systems.
For Market Incumbents: Compound installed base advantages by embedding IoT-enabled predictive maintenance subscriptions into multi-year service agreements, locking out mid-tier competitors lacking cloud infrastructure. Deepen backward integration into medical-grade foam formulations to offset petrochemical price volatility threatening fixed-price tender competitiveness. Prioritize ISO 13485 certification investment as the primary gating mechanism for supplier qualification pools. For New Entrants and Emerging Players: Differentiate on modular platform configurability targeting India's Apollo and Fortis private maternity chains, where standardized convertible examination-delivery platforms are displacing basic manual beds. White-space opportunity concentrates in US rural critical access hospitals accessing IRA infrastructure grants for labor unit modernization. Pursue regulatory liaison office establishment in Tokyo to compress PMDA electrical-safety testing timelines. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors engineering-intensive specialists with captive JIS-certified supply chains over pure-play distributors. Long-term viability over the next decade hinges on digital health convergence capabilities and predictive maintenance revenue streams. Target acquisition archetype: mid-tier modular platform fabricators with established hospital GPO relationships. Watch FDA 510(k) clearance velocity and EU MDR technical documentation completeness as inflection signals for competitive positioning durability.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Subscription Launch | Stryker and Linet Group SE bundle cloud-based actuator monitoring with hardware procurement to capture recurring revenue from Kaiser Permanente and Charité Berlin. |
| Regulatory Liaison Office Establishment | European suppliers open Tokyo-based compliance teams to compress PMDA resubmission cycles and tilt Osaka metropolitan tenders toward imported electric platforms. |
| Convertible Platform Standardization | Apollo and Fortis networks in Mumbai and Bangalore drive demand for dual-use assets transitioning from antenatal examination to active delivery without patient transfer. |
| ISO 13485 Quality System Investment | Smaller Eastern European fabricators invest in documentation infrastructure to satisfy supplier qualification gates and re-enter hospital tender pools. |
| Sensor-Embedded Platform Pilot | Massachusetts General and Klinikum rechts der Isar trial capacitive load-cell arrays for maternal positioning analytics feeding hospital quality dashboards. |
Research Methodology
The analysis maps electric, convertible, manual, and specialty birthing bed sub-sectors, each validated through hospital procurement managers, biomedical engineering directors, GPO contracts specialists, and regulatory affairs leads at device manufacturers. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and trade flow data for medical equipment. Bottom-up unit economics triangulated against top-down market sizing across the projection horizon.
Consistency checks validated volume and value outputs against external benchmarks including customs records for medical device trade flows and capital expenditure disclosures from major hospital systems. The analytical framework modeled product type, end-user facility tier, actuator technology, and frame material segmentation throughout the forecast period. CAGRs derived from replacement cycle analysis, regulatory mandate timelines, and nurse-staffing cost elasticity assumptions. Forecast inputs incorporated EU MDR compliance cost trajectories and PMDA registration timeline distributions.
The analysis sits within stated boundaries; outcomes outside sustained hospital capital expenditure commitment or accelerated regulatory enforcement would require recalibration. Forecasts reflect documented assumptions regarding replacement cycle timing and procurement budget availability. Supply chain disruption, steel tariff escalation, or natural birth advocacy resurgence in Northern Europe could revise trajectory. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Proctologic Table Market
Medical Equipment
Biomedical Refrigerators and Freezers Market
Medical Equipment
Hospital-at-Home Equipment Rental Market
Medical Equipment
Histology Embedding System Market
Medical Equipment
Portable Steam Autoclave Market
Medical Equipment
Tissue Processing Systems Market
Medical Equipment
Spinal Surgery Tables Market
Medical Equipment
Podiatry Equipment Market
Medical Equipment
Electrophysiology Equipment and Recording Systems Market
Medical Equipment
Stereotactic Biopsy Tables Market
Medical Equipment
Ultrasound Equipment Market
Medical Equipment
Autopsy Saw Market
Medical Equipment
Healthcare Simulators Market
Medical Equipment
Medical Gas Equipment Market
Medical Equipment
Hemodialysis Equipment Market
Medical Equipment
Global Emergency Medical Equipment Market