
 Medical Procedure Tray Market | 2026-2036
Medical Procedure Tray Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Procedure Tray Market Outlook
Hospital procurement consolidation is decoupling volume concentration from geographic dispersion as integrated delivery networks negotiate enterprise-wide tray contracts. Cardinal Health leverages its distribution infrastructure to sustain national account relationships across IDNs. Medline Industries anchors its competitive position through private-label manufacturing scale. Mölnlycke Health Care differentiates via proprietary barrier material technology in surgical tray configurations.
A medical procedure tray constitutes a pre-assembled, terminally sterilized collection of instruments, drapes, and consumables arranged for a specific clinical intervention, typically packaged in rigid plastic or composite materials with breathable microbial barriers. The assembly undergoes ethylene oxide or gamma irradiation sterilization with documented sterility assurance levels to eliminate intraoperative contamination risk. Surgical trays dominate current revenue flows due to high procedure volumes, while ambulatory surgical centers represent the fastest-growing end-user channel as outpatient migration accelerates. Plastic materials lead unit economics through disposability and cost efficiency, though composite substrates capture premium positioning in cardiac and orthopedic custom configurations.
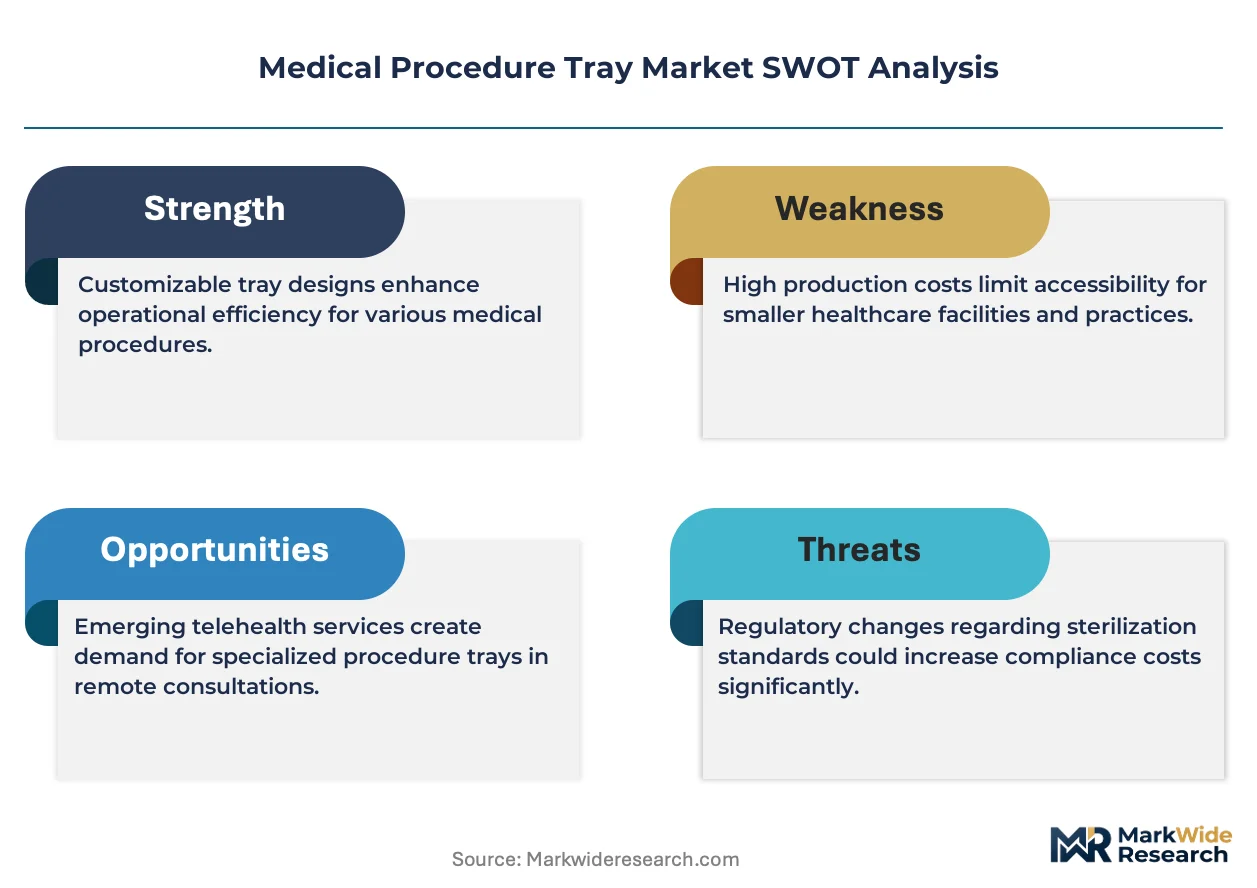
FDA 510(k) clearance pathways and EU MDR technical documentation requirements govern tray sterilization validation and biocompatibility testing protocols, directly influencing product development timelines and market access costs. BIS certification in India and CDSCO import licensing add compliance layers for manufacturers targeting Asian hospital procurement tenders. Stakeholders must monitor evolving EPA sterilization emission standards and state-level reusable device reprocessing regulations as sustainability pressures intersect with infection control mandates.
Market Dynamics
Hospital procurement centralization is compressing vendor relationships into enterprise-wide contracts that privilege standardized tray formats over custom configurations, forcing manufacturers to retool assembly lines for volume scalability rather than SKU proliferation.
Growth Catalysts
- Ambulatory surgical center expansion:Outpatient procedure migration accelerates tray consumption as ASCs prioritize rapid turnover kits over reusable instrument reprocessing. Germany's hospital procurement centralization amplifies standardized tray demand.
- EU MDR traceability mandates:Device identification requirements are elevating pre-configured tray adoption over loose instrument sets that complicate documentation workflows.
- Ethylene oxide sterilization infrastructure:Terminal sterilization capacity expansion enables broader tray format penetration into cardiovascular and orthopedic procedure categories.
Market Restraints
- Polypropylene resin cost volatility:Feedstock price swings compress margin structures for disposable tray manufacturers locked into annual hospital contracts.
- Gamma irradiation facility concentration:Sterilization service providers cluster in industrial corridors near nuclear research centers, creating geographic supply risk for tray distributors.
- Reusable instrument reprocessing substitution:Central sterile departments in cost-constrained hospitals retain metal instrument sets for high-volume procedures, limiting single-use tray penetration.
Strategic Opportunities
- India CDSCO tender pathways:Import licensing requirements favor established tray manufacturers with local sterilization partnerships over fragmented domestic assemblers.
- RFID-enabled tray tracking:Convergence of wireless identification with barrier packaging creates premium positioning for procedure kits in liability-sensitive surgical segments.
- Composite substrate cardiac configurations:Custom tray formats for structural heart interventions capture pricing premiums unavailable in commoditized general surgery kits.
Industry Challenges
- FDA 510(k) sterilization validation timelines:Biocompatibility testing protocols extend product development cycles, delaying market access for reformulated barrier materials.
- Legacy hospital inventory system integration:Tray consumption tracking requires middleware development to connect manufacturer RFID tags with provider ERP platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Procedure Tray Market |
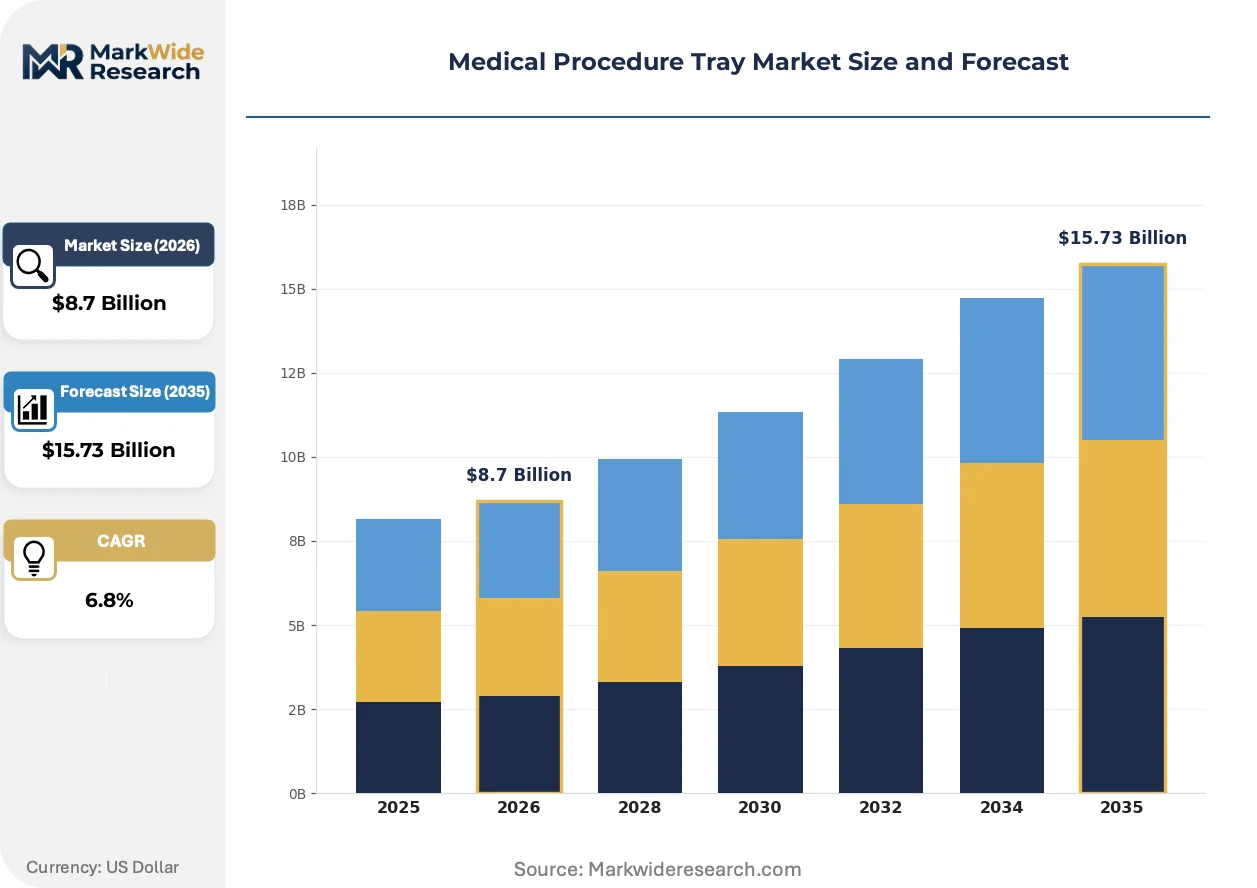
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Trays, Dental Trays, Wound Care Trays, Emergency Trays End User: Hospitals, Clinics, Long-term Care Facilities, Ambulatory Surgical Centers Material: Plastic, Metal, Glass, Composite Customization Level: Standardized, Semi-Custom, Fully Customized, Disposable |
| Companies Covered | Cardinal Health, Medline Industries, Mölnlycke Health Care, Owens & Minor, Becton, Dickinson and Company, Teleflex, B. Braun, 3M Company, Merit Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Procedure Tray Market Strategic Shifts
Barrier material science and sterilization modality diversification are compressing product development cycles while regulatory documentation requirements expand technical complexity for market entrants.
Antimicrobial composite substrates are integrating silver-ion or copper-alloy layers directly into tray base materials rather than applying topical coatings that degrade during ethylene oxide cycles. Cardiac surgery units in German university hospitals are piloting these configurations for valve replacement procedures. This material evolution is integrating infection control liability reduction into tray procurement specifications, displacing commodity plastic formats in premium surgical segments.
EU MDR technical documentation requirements are mandating sterilization process validation across multiple production batches before CE marking approval. Tray manufacturers must now submit biocompatibility testing protocols for every substrate-adhesive combination rather than leveraging predicate device exemptions. Cardiac and orthopedic custom configurations face the steepest compliance burden due to patient contact duration classifications.
Integrated delivery networks are consolidating vendor contracts into single-source agreements covering procedure trays, surgical instruments, and consumables. Ambulatory surgical centers lose negotiating leverage as health system procurement offices centralize purchasing authority. This concentration is most visible in Germany, where hospital federation tenders specify enterprise-wide tray formats that individual facilities cannot override.
Medical Procedure Tray Market Segmentation
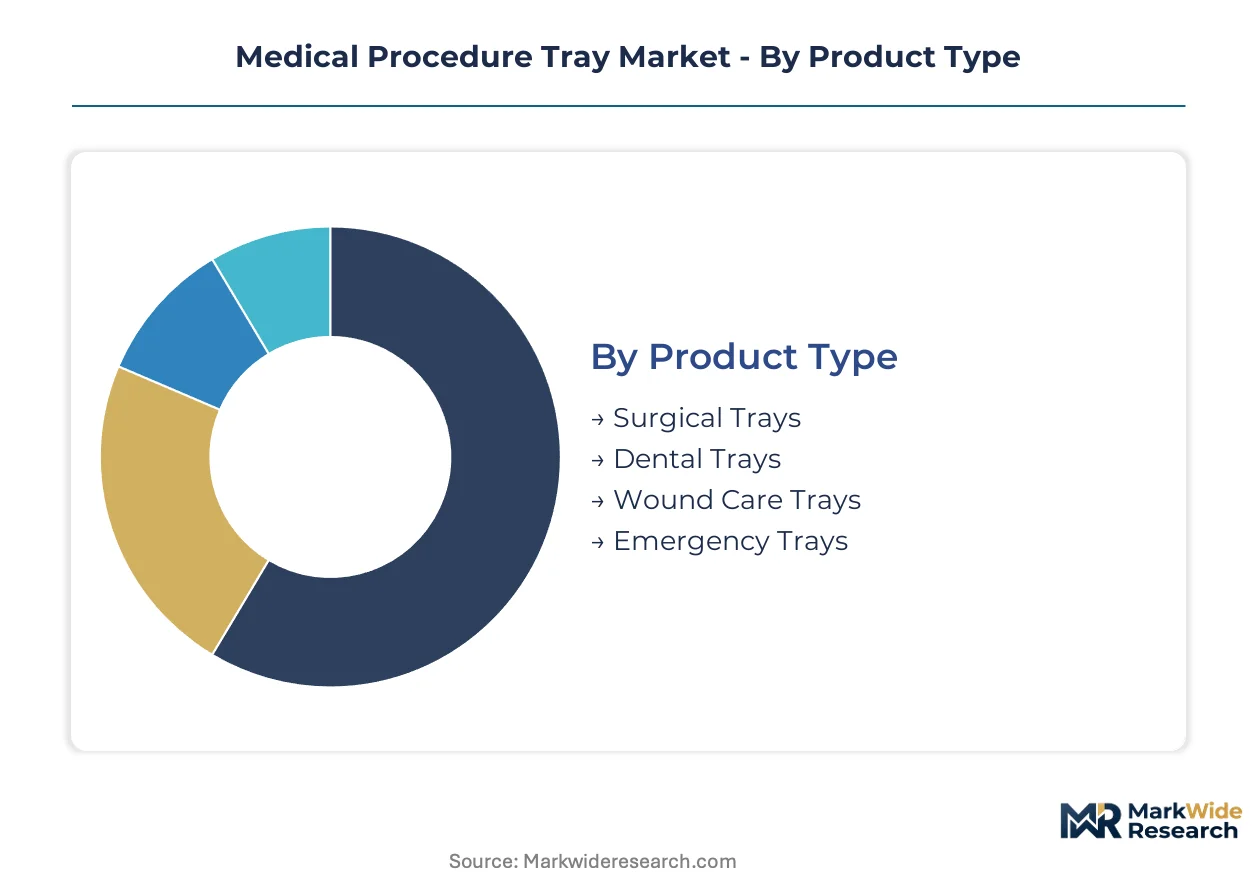
Tray configuration choices directly determine sterilization validation costs, procurement contract structures, and assembly line economics for manufacturers serving hospital systems and ambulatory networks.
Product Type:
Procedure complexity and reimbursement rates separate high-value surgical configurations from commodity formats in manufacturer portfolios.
- Surgical Trays:Pre-assembled instrument collections for operating room interventions, incorporating drapes, scalpels, and hemostats in rigid barrier packaging. Demand concentrates in German university hospitals where procurement centralization mandates standardized formats for cardiac and orthopedic procedures, compressing SKU variety in favor of volume-scalable production.
- Dental Trays:Compact configurations for extraction, implant, and endodontic procedures, typically utilizing lighter-gauge plastics than surgical equivalents. ASCs in outpatient dental surgery chains drive consumption as they replace reusable instrument reprocessing with single-use alternatives to accelerate chair turnover.
- Wound Care Trays:Sterile dressing and debridement kits for chronic ulcer management and post-operative site maintenance.
- Emergency Trays:Rapid-deployment configurations for trauma bays and field medicine, prioritizing packaging integrity over component sophistication.
Volume sits with Surgical Trays; growth tilts toward Dental Trays.
End User:
Capital intensity and reprocessing infrastructure availability shape whether facilities adopt disposable trays or retain reusable metal instrument sets.
- Hospitals:Integrated delivery networks with centralized sterile processing departments negotiate enterprise-wide tray contracts privileging standardized formats. German hospital federation tenders exemplify this concentration, specifying uniform configurations that individual facilities cannot override.
- Ambulatory Surgical Centers:Outpatient migration accelerates consumption of rapid-turnover kits as these facilities lack capital for instrument reprocessing infrastructure. EU MDR traceability mandates amplify preference for pre-configured trays over loose instrument sets that complicate documentation workflows.
- Clinics:Primary care and specialty outpatient settings with limited procedure volumes favor compact, procedure-specific configurations.
- Long-term Care Facilities:Wound care and minor procedure applications dominate tray consumption in skilled nursing environments.
Procurement scale favors Hospitals; expansion velocity favors Ambulatory Surgical Centers.
Material:
Cost structure and barrier performance requirements determine substrate selection across procedure risk tiers.
- Plastic:Polypropylene and PETG substrates dominate unit economics through disposability and manufacturing scalability, though resin price volatility compresses margins for manufacturers locked into annual hospital contracts.
- Composite:Multi-layer configurations integrating antimicrobial silver-ion or copper-alloy layers capture premium positioning in cardiac and orthopedic custom applications where infection liability reduction justifies higher procurement expenditure.
- Metal:Stainless steel trays persist in reusable instrument sets retained by cost-constrained central sterile departments.
- Glass:Limited application in specialty pharmaceutical and laboratory procedure configurations requiring chemical inertness.
Unit volume concentrates in Plastic; value capture concentrates in Composite.
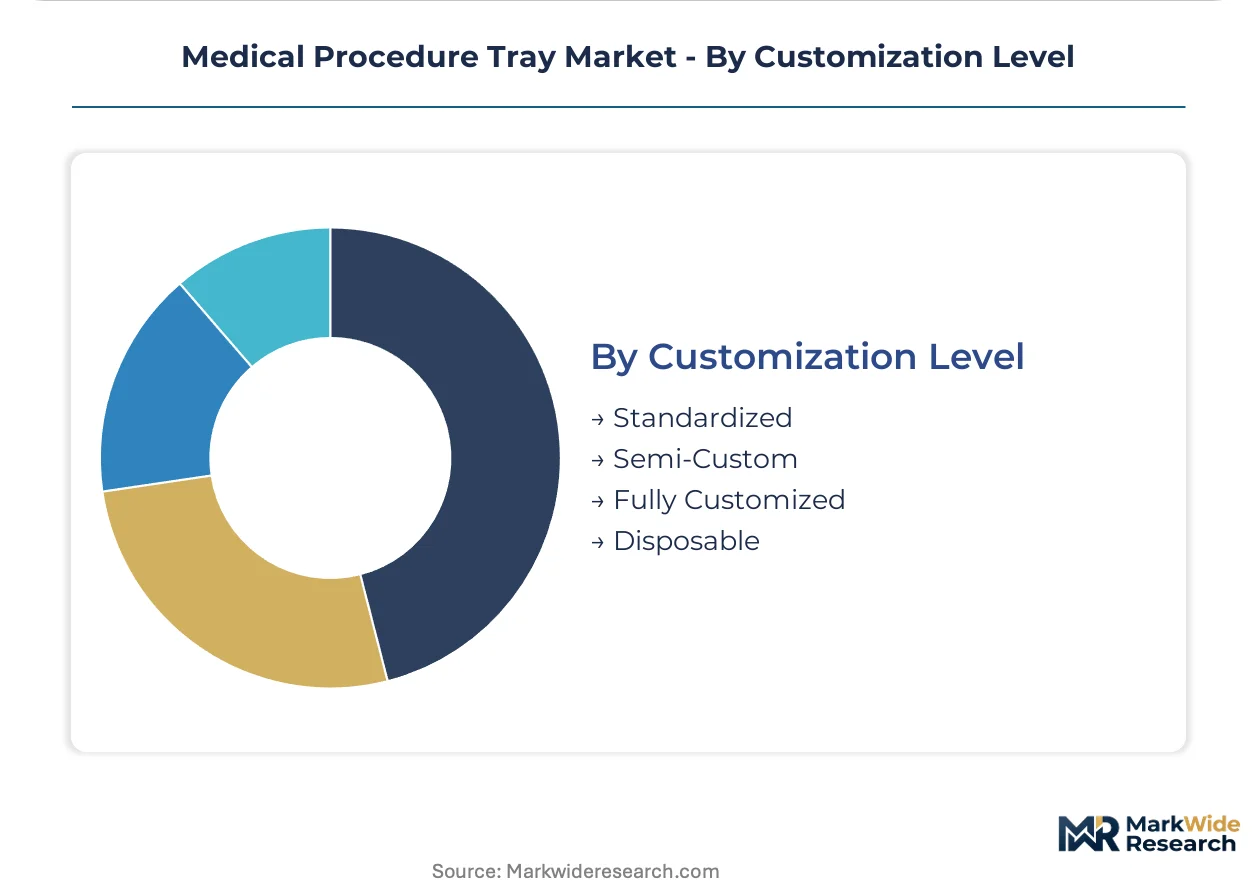
Customization Level:
Regulatory documentation burden and production flexibility separate configurable formats from fixed configurations.
- Standardized:Fixed-format trays with predetermined component arrays enable volume manufacturing and simplified FDA 510(k) clearance pathways through predicate device referencing.
- Fully Customized:Procedure-specific configurations for structural heart and complex orthopedic interventions require individual sterilization validation cycles and extended biocompatibility testing protocols, elevating development timelines and pricing premiums.
- Semi-Custom:Modular base trays with swappable component modules for hospital-specific preferences.
- Disposable:Single-use orientation across all material substrates, distinct from reusable metal alternatives.
Manufacturing efficiency favors Standardized; margin expansion favors Fully Customized.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polypropylene resin production clusters in Texas and Louisiana anchor North American tray manufacturing capacity, while ethylene oxide sterilization infrastructure concentrates near nuclear research centers in industrial corridors across multiple continents.
United States
Ambulatory surgical center expansion and hospital procurement consolidation drive standardized tray consumption. FDA 510(k) clearance pathways govern sterilization validation timelines for barrier material innovations. The Gulf Coast petrochemical corridor supplies polypropylene feedstock to tray manufacturers serving integrated delivery networks.
Germany
Hospital federation tenders mandate enterprise-wide standardized formats that individual facilities cannot override, compressing SKU variety. EU MDR traceability requirements elevate pre-configured tray adoption over loose instrument sets. Bavarian university hospitals pilot antimicrobial composite substrates for cardiac valve replacement procedures.
China
Domestic sterilization capacity expansion enables broader tray penetration into cardiovascular and orthopedic categories. NMPA technical documentation requirements align with international biocompatibility testing protocols. Yangtze River Delta manufacturing clusters supply plastic substrates for both domestic hospital procurement and export markets.
India
CDSCO import licensing requirements favor established manufacturers with local sterilization partnerships over fragmented domestic assemblers. Government hospital procurement tenders specify pre-configured kits to reduce surgical site infection liability. Maharashtra's medical device manufacturing zones attract tray assembly operations serving South Asian markets.
Japan
MetI standards harmonization with ISO sterilization protocols facilitates tray importation for aging hospital infrastructure. PMDA quality management system requirements extend validation documentation burdens for foreign manufacturers. Kanto region central sterile departments balance reusable metal instrument retention against single-use tray adoption for cost containment.
Medical Procedure Tray Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue composite material differentiation and RFID-enabled tracking capabilities. The vendor base stratifies across three tiers: multinational distributors with sterilization infrastructure, regional manufacturers with private-label scale, and specialty providers with antimicrobial barrier technology. Three archetypes dominate: distribution-integrated suppliers, manufacturing-scale private-label producers, and technology-differentiated barrier specialists. Competitive moves concentrate on enterprise contract consolidation and sterilization capacity expansion near target hospital markets.
Among distribution-integrated suppliers, Cardinal Health and Owens & Minor exemplify the archetype of logistics infrastructure leveraged for national account retention. Medline Industries occupies a position representing manufacturing-scale private-label production. Mölnlycke Health Care anchors the technology-differentiated tier with proprietary barrier material positioning. Becton, Dickinson and Company and B. Braun sit within the diversified medical device conglomerate category, where tray offerings complement broader surgical consumables portfolios.
| Leading Market Players |
|---|
| Cardinal Health |
| Medline Industries |
| Mölnlycke Health Care |
| Owens & Minor |
| Becton, Dickinson and Company |
| Teleflex |
| B. Braun |
| 3M Company |
| Merit Medical Systems |
| Others |
Value Chain & Pricing Dynamics
Polypropylene resin futures on the Gulf Coast petrochemical corridor cascade through tray manufacturing into three-tier pricing stratification across premium antimicrobial composites, standard polypropylene disposables, and economy-grade bulk configurations for high-volume hospital contracts.
Pricing Analysis
Warranty and validation documentation bundling separates premium-tier composite trays from unbundled standard offerings where sterilization certification costs shift to buyers. Pricing stratifies across premium, standard, and economy tiers based on barrier material technology and FDA 510(k) clearance status. Cost compression in economy-grade plastic trays is intensifying because resin price volatility outpaces annual contract escalation clauses. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraints, while German university hospitals show lowest sensitivity given infection liability reduction priorities.
Supply Chain Analysis
Single-source vulnerability sits with ethylene oxide sterilization capacity concentrated near nuclear research centers in Belgium, the United States, and Russia. Raw material flows draw from Saudi Arabian and Qatari polypropylene feedstock, German barrier film production, and Chinese molded component manufacturing. Tariff exposure on medical-grade plastics from Asia threatens margin structures for North American assemblers. Distribution runs through integrated delivery network procurement offices and group purchasing organization contracts rather than direct hospital sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR traceability mandates have erected a cost-of-compliance barrier that favors incumbent manufacturers with established sterilization validation infrastructure over fragmented domestic assemblers lacking technical documentation capabilities.
For Market Incumbents: Extend sterilization capacity into Maharashtra and Bavaria to anchor regional hospital federation contracts before emerging entrants secure local partnerships. Consolidate enterprise-wide agreements with integrated delivery networks to lock out private-label competitors. Vertical integration into antimicrobial composite substrate production protects margin position against resin cost volatility.
For New Entrants and Emerging Players: Launch via CDSCO import licensing partnerships with established Indian sterilization facilities to bypass capital-intensive infrastructure requirements. Target wound care trays in long-term care facilities as the most penetrable segment given lower regulatory documentation burdens. Pursue RFID-enabled tracking differentiation to capture premium positioning in liability-sensitive cardiac surgery units.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale composite substrate specialists with proprietary barrier technology in Germany and the United States. Long-term viability hinges on sterilization infrastructure ownership rather than contract sterilization dependence. Monitor EPA ethylene oxide emission standard revisions as the critical inflection signal for capacity relocation strategies.
| Strategic Initiative | Industry Significance |
|---|---|
| Sterilization Capacity Expansion | Terminal sterilization infrastructure near target hospital markets reduces logistics risk and contract fulfillment timelines. |
| Antimicrobial Composite Development | Silver-ion substrate integration captures cardiac surgery premium pricing unavailable in commodity plastic formats. |
| EU MDR Technical Documentation Investment | Biocompatibility testing protocols for substrate-adhesive combinations accelerate CE marking approval pathways. |
| RFID-Enabled Tray Tracking Integration | Wireless identification convergence with barrier packaging creates liability reduction value for surgical segments. |
| Hospital System Partnership Consolidation | Enterprise-wide contracts with integrated delivery networks compress vendor relationships and lock out competitors. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with hospital purchasing committee members, GPO contracts managers, biomedical engineers, and sterile processing department directors. FDA 510(k) clearance databases, EU MDR technical documentation repositories, CDSCO import licensing records, and hospital procurement tender databases provided validation benchmarks. Bottom-up tray consumption modeling triangulated against top-down manufacturer revenue estimates.
Data-stream reconciliation across shipment volumes, sterilization capacity utilization, and hospital procurement contract values informed the analytical framework throughout the projection horizon. Segmentation dimensions modeled include tray configuration type, end-user facility category, material substrate, and customization level alongside regional regulatory cluster variations. CAGRs derived from procedure volume growth trajectories, outpatient migration rates, and sterilization infrastructure expansion pipelines.
The model assumes a particular technology adoption path; alternative pathways for antimicrobial composite substrates would alter the outlook if silver-ion integration costs fall below polypropylene parity. Forecasts reflect assumptions about EU MDR enforcement consistency, ethylene oxide sterilization capacity expansion, and hospital procurement centralization momentum. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Swab and Viral Transport Medium Market
Medical Supplies
Ultrasound Gels Market
Medical Supplies
Ear and Nasal Packing Market
Medical Supplies
Drainage Bottles Market
Medical Supplies
Italy Hospital Supplies Market
Medical Supplies
Medical Tapes and Bandages Market
Medical Supplies
North America Medical Clothing Market
Medical Supplies
Elbow Splints Market
Medical Supplies
Slip Tip Syringe Market
Medical Supplies
Europe Intravenous Solutions Market
Medical Supplies
Trauma Products Market
Medical Supplies
Bile Collection Bags Market
Medical Supplies
Asia Pacific Medical Rubber and Balloon Product Market
Medical Supplies
Western Europe Sterile Gloves Market
Medical Supplies
Sequencing Consumables Market
Medical Supplies
Global IV Bags Market