
 Cardiovascular Enterprise Viewer Market | 2026-2036
Cardiovascular Enterprise Viewer Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiovascular Enterprise Viewer Market Outlook
Multi-source procurement of imaging software is repositioning how hospital systems evaluate cardiovascular enterprise viewers. Philips Healthcare leverages deep integration with diagnostic hardware to sustain platform stickiness across IDN contracts. Siemens Healthineers anchors its competitive stance through in-house AI development for echocardiography analysis. GE Healthcare competes on workflow breadth, extending its enterprise imaging footprint into cardiovascular service lines.
A cardiovascular enterprise viewer is a software platform that aggregates, displays, and distributes cardiac imaging data from modalities including echocardiography, catheterization labs, and nuclear cardiology, typically supporting DICOM and HL7 FHIR interoperability standards for clinical decision-making. The product type dimension reveals ECG Systems and Imaging Devices commanding established installed bases, while Workflow Solutions captures expanding margin pools as hospitals prioritize operational efficiency over hardware replacement. Cloud-based Solutions within the technology dimension is gaining fastest, though On-premise Systems retains dominance in markets with stringent data residency requirements.
FDA 510(k) clearance pathways shape product development timelines for cardiovascular imaging software, while HIPAA mandates govern patient data exchange architectures across US deployments. The ONC Cures Act Final Rule drives interoperability requirements that force legacy system upgrades. Stakeholders must monitor evolving AI diagnostic validation standards and reimbursement pathways for algorithm-assisted cardiology reads.
Market Dynamics
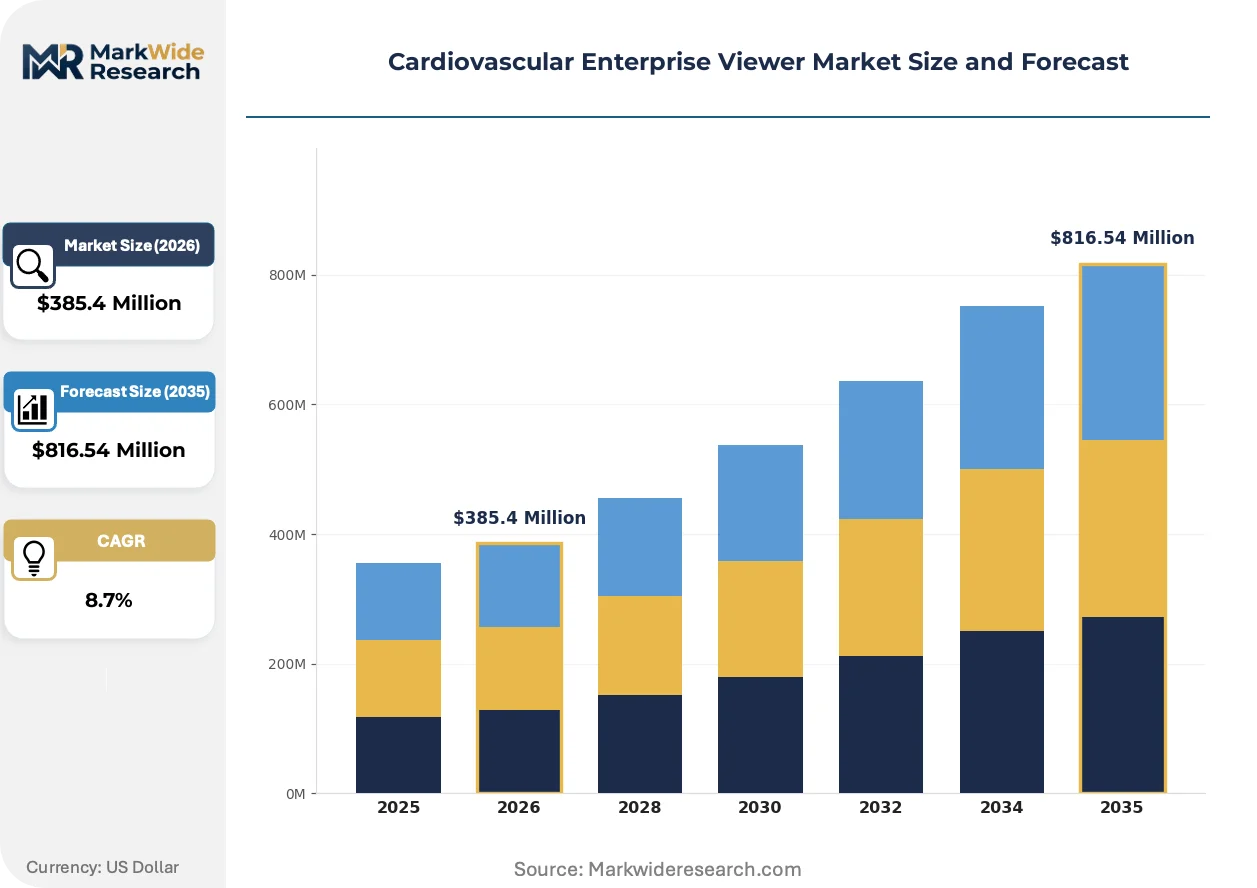
Hospital networks are consolidating cardiovascular imaging infrastructure around cloud-native platforms that displace fragmented PACS silos, driven by ONC Cures Act interoperability mandates and the operational imperative to unify cath lab, echo, and nuclear cardiology workflows.
Growth Catalysts
- ONC Cures Act Final Rule:Federal interoperability mandates force legacy system upgrades, accelerating replacement cycles for disconnected cardiovascular imaging archives across US integrated delivery networks.
- Catheterization lab digitization:Structural heart programs require real-time hemodynamic data integration with imaging archives, pulling enterprise viewer deployment into hybrid OR construction projects.
- Cloud migration in cardiology:Amazon Web Services and Microsoft Azure health data lakes are capturing cardiovascular imaging workloads previously locked in on-premise datacenters.
Market Restraints
- Data residency compliance:German Bundesdatenschutzgesetz and French CNIL guidance impose localization requirements that fragment cloud deployment architectures and inflate infrastructure costs.
- DICOM standard fragmentation:Vendor-specific private tags in echocardiography datasets impede seamless image portability between competing enterprise platforms.
- Specialized integration labor:Shortage of HL7 FHIR implementation engineers with cardiovascular workflow expertise constrains deployment velocity for mid-sized hospital systems.
Strategic Opportunities
- AI-assisted echocardiography reads:FDA breakthrough device designation pathways for left ventricular ejection fraction algorithms create reimbursement positioning for integrated diagnostic platforms.
- Rural hospital telecardiology:Underserved markets in Montana, Wyoming, and North Dakota present white space for cloud-based enterprise viewers with teleradiology service bundling.
- Cardiovascular service line unification:Health system consolidation is creating demand for single-platform imaging across acquired community hospitals and ambulatory surgery centers.
Industry Challenges
- Legacy PACS migration complexity:Decades of DICOM study archives require costly normalization and metadata reconstruction before cloud ingestion.
- AI validation timelines:FDA 510(k) clearance for algorithm-assisted measurements extends product development cycles and delays revenue recognition.
- Cross-modality workflow standardization:Echocardiography, cardiac CT, and invasive angiography operate on divergent measurement conventions that resist unified reporting templates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiovascular Enterprise Viewer Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ECG Systems, Imaging Devices, Monitoring Systems, Workflow Solutions End User: Hospitals, Diagnostic Labs, Outpatient Clinics, Research Institutions Technology: Cloud-based Solutions, On-premise Systems, Mobile Applications, AI-Driven Analytics Application: Cardiology Care, Patient Monitoring, Remote Diagnostics, Data Management |
| Companies Covered | Fujifilm Healthcare, Agfa HealthCare, Philips Healthcare, Samsung Medison, Sectra, Siemens Healthineers, Canon Medical Systems Corporation, Medtronic, GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiovascular Enterprise Viewer Market Strategic Shifts
Cardiovascular enterprise imaging is pivoting from departmental PACS replacement toward AI-augmented diagnostic platforms that embed decision support directly into clinical workflows. Three forces are compressing traditional vendor positioning.
Edge computing architectures for catheterization labs are decentralizing image processing from centralized datacenters to procedure room endpoints. Siemens Healthineers and Philips Healthcare are deploying GPU-enabled acquisition workstations that execute real-time AI inference on angiographic sequences. This topology reduces latency for quantitative coronary analysis and diminishes dependency on hospital network bandwidth.
The EU AI Act risk classification framework is reclassifying cardiovascular diagnostic algorithms as high-risk AI systems requiring conformity assessment and post-market surveillance. European manufacturers must now maintain quality management systems exceeding ISO 13485 baseline requirements. Cardiac CT calcium scoring and automated wall motion analysis tools face extended validation documentation obligations before CE marking.
Subscription-based enterprise imaging contracts are displacing perpetual license models as health system CFOs prioritize operational expenditure predictability. Philips and GE Healthcare are restructuring pricing around study volume tiers with minimum commitment clauses. This transition is most visible in US nonprofit health systems where capital budget constraints intersect with Epic EHR integration requirements.
Cardiovascular Enterprise Viewer Market Segmentation
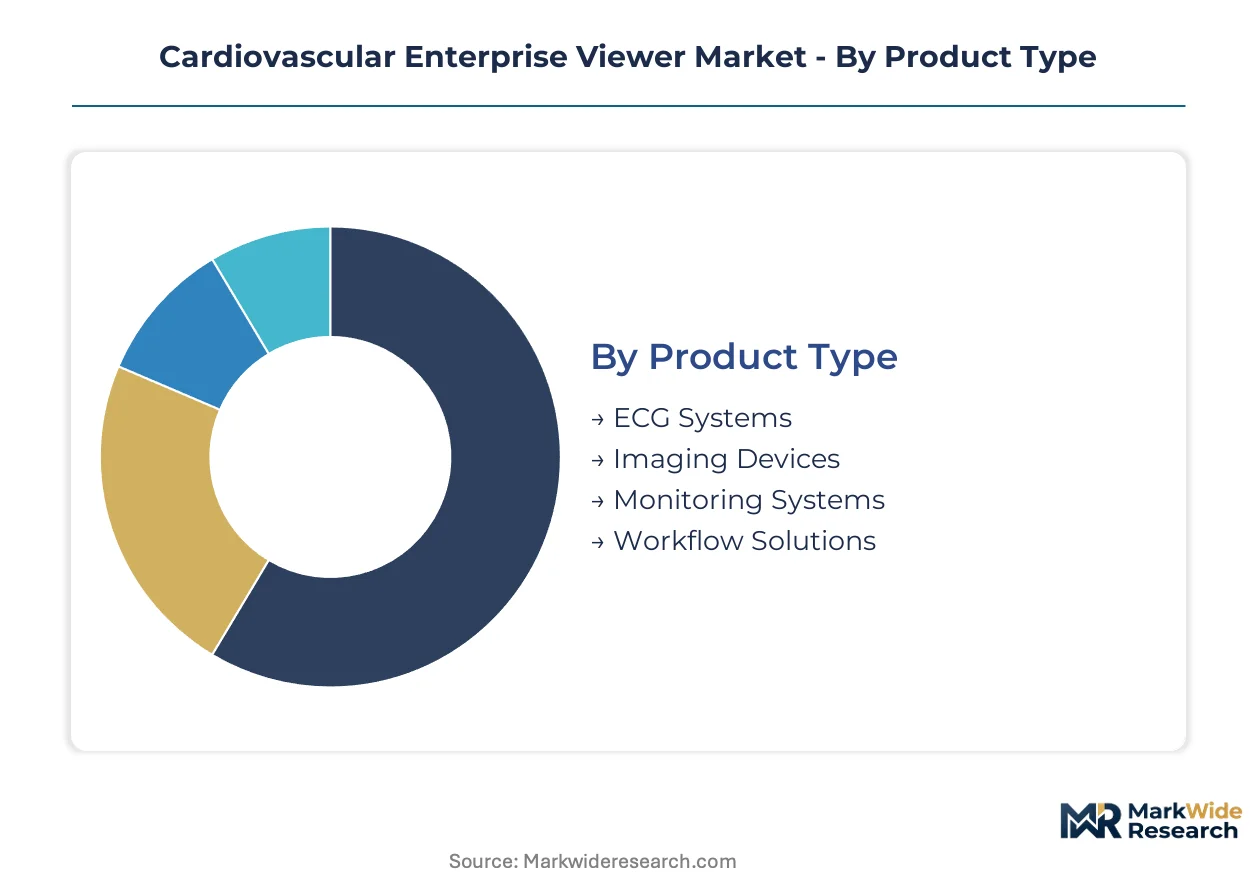
Cardiovascular enterprise viewers serve heterogeneous deployment contexts, from catheterization labs requiring sub-second image retrieval to rural clinics demanding lightweight remote access. Segmentation reveals how vendor roadmaps diverge across hardware-centric versus software-centric procurement patterns.
Product Type:
The customization-to-standardization spectrum stretches from configurable imaging hardware to plug-and-play workflow modules that integrate with existing infrastructure.
- ECG Systems:Electrocardiography acquisition devices with integrated viewing software dominate ambulatory and emergency department deployments. Demand concentrates in United States hospital networks modernizing telemetry infrastructure under value-based care contracts. Hardware refresh cycles accelerate as 12-lead ECG machines reach end-of-life.
- Imaging Devices:Dedicated workstations for echocardiography and angiography display represent the largest installed base segment. Cath lab construction projects in Germany and France pull multimodality viewers into hybrid operating room specifications.
- Monitoring Systems:Continuous cardiac monitoring with enterprise archive connectivity serves step-down units and critical care floors.
- Workflow Solutions:Software-only platforms unifying reporting, scheduling, and image distribution across cardiology service lines.
Leading the category by volume: Imaging Devices. Growing fastest: Workflow Solutions.
End User:
Procurement sophistication varies sharply across this category, from centralized IDN technology committees to single-physician practice IT decisions.
- Hospitals:Integrated delivery networks command the largest contract values, standardizing enterprise viewers across acquired facilities. United States health systems prioritize Epic EHR interoperability in vendor selection criteria.
- Diagnostic Labs:Independent cardiology testing centers require DICOM routing and HL7 FHIR connectivity to referring physicians. Volume concentration in India and Brazil drives demand for cost-optimized cloud deployments.
- Outpatient Clinics:Community cardiology practices seek lightweight viewers with teleradiology handoff capabilities.
- Research Institutions:Academic medical centers demand advanced quantification tools and multi-site data federation for clinical trials.
Hospitals dominate procurement value. Outpatient Clinics are expanding most quickly as care shifts to lower-acuity settings.
Technology:
Architecture choices here determine total cost of ownership trajectories and regulatory compliance burdens across deployment geographies.
- Cloud-based Solutions:Subscription models with AWS or Azure health data lake backends capture new hospital system contracts. German Bundesdatenschutzgesetz and French CNIL localization mandates fragment pure-cloud architectures in Europe.
- On-premise Systems:Hospital-controlled datacenter deployments retain preference where data residency requirements or network latency constraints dominate. Legacy PACS migration complexity sustains installed base stickiness.
- Mobile Applications:Tablet and smartphone viewers for point-of-care consultation and emergency department triage.
- AI-Driven Analytics:Embedded algorithms for automated ejection fraction calculation and coronary calcium scoring.
On-premise Systems retain the largest installed base. AI-Driven Analytics shows the steepest expansion trajectory as FDA breakthrough pathways mature.
Application:
Use case specificity determines integration depth requirements and user interface customization needs across this dimension.
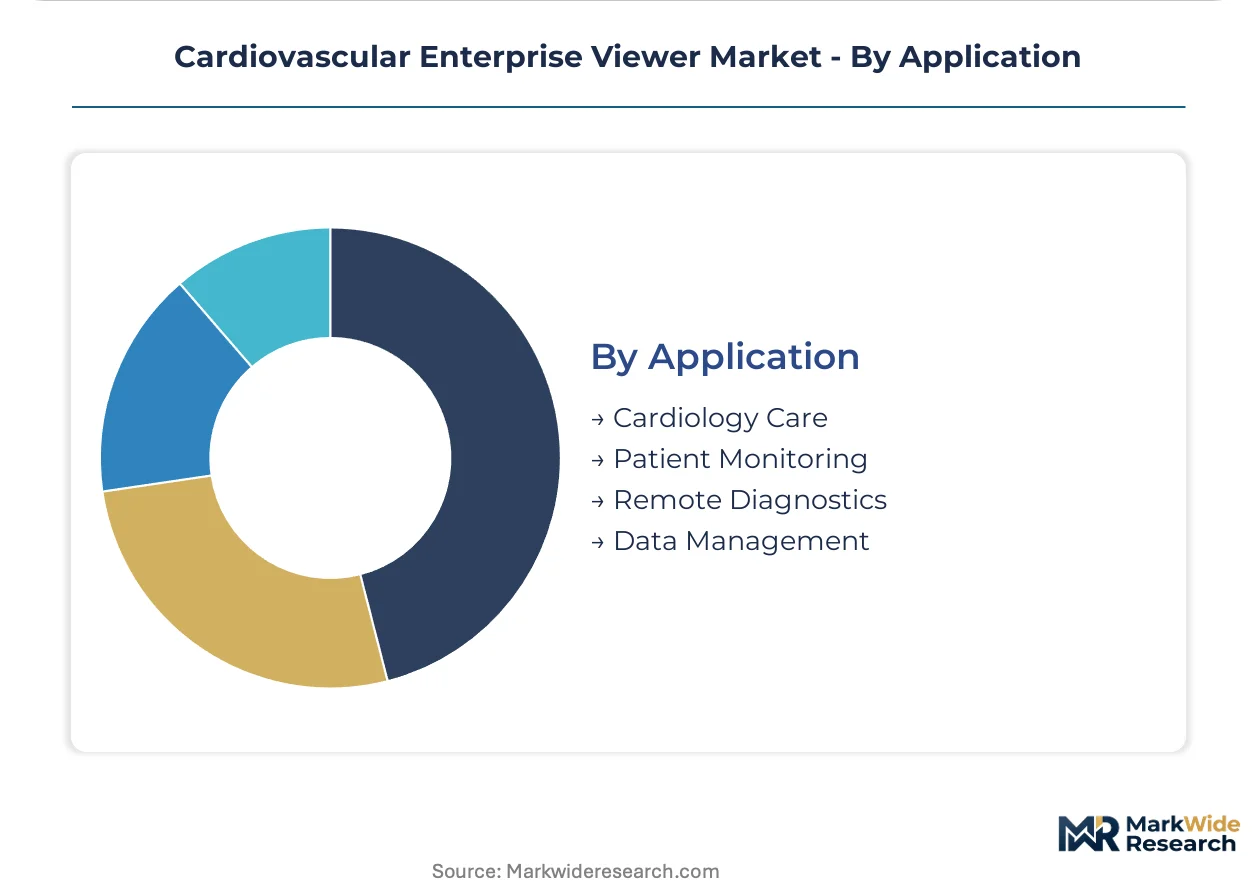
- Cardiology Care:Comprehensive imaging workflows spanning diagnosis through intervention planning. Structural heart programs in United States academic centers drive demand for multimodality fusion viewers.
- Patient Monitoring:Real-time telemetry integration with enterprise archives for trend analysis and alarm management.
- Remote Diagnostics:Telecardiology platforms enabling specialist interpretation of studies acquired at distant sites.
- Data Management:Archive normalization, lifecycle management, and cross-enterprise image exchange infrastructure.
Cardiology Care commands the deepest functionality requirements. Remote Diagnostics is gaining share fastest as rural hospital closures concentrate interpretation expertise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's health data infrastructure anchors North American cardiovascular imaging software development, while German industrial automation clusters and Japanese precision electronics centers shape hardware-integrated viewer manufacturing across three continents.
United States
Integrated delivery networks in Texas and Florida are consolidating cath lab infrastructure around cloud-native platforms. The ONC Cures Act Final Rule mandates HL7 FHIR interoperability, forcing legacy PACS upgrades across nonprofit health systems. The Boston-Cambridge corridor houses Epic Systems and specialist AI firms advancing echocardiography algorithm validation.
Germany
Structural heart programs in Munich and Heidelberg drive multimodality viewer procurement for hybrid operating rooms. The Bundesdatenschutzgesetz imposes strict data localization requirements that fragment pure-cloud architectures and sustain on-premise system preference. Bavaria's medical device cluster anchors Siemens Healthineers' cardiovascular imaging development.
Japan
Aging demographics in Osaka and Nagoya accelerate telecardiology deployment for rural island communities. The PMDA's streamlined SaMD approval pathway reduces time-to-market for AI-assisted diagnostic algorithms. Tokyo's academic medical centers lead clinical validation studies for automated coronary calcium scoring tools.
India
Diagnostic lab chains in Maharashtra and Karnataka demand cost-optimized cloud viewers with DICOM routing to referring physicians. The CDSCO's medical device rules increasingly align with IMDRF standards, streamlining import registration for multinational vendors. Hyderabad's health IT cluster supports teleradiology service bundling for enterprise viewer platforms.
United Kingdom
NHS England's imaging networks consolidate cardiovascular archives across London and Manchester trusts. The MHRA's post-Brexit regulatory framework maintains CE marking recognition while building UKCA capacity for domestic manufacturers. Cambridge's life sciences cluster advances AI validation methodologies for echocardiography analysis.
Cardiovascular Enterprise Viewer Market Competitive Environment
Strategic partnerships dominate the current landscape as vendors seek to bridge hardware-software gaps and secure IDN contracts. The vendor base clusters around three tiers: diversified imaging conglomerates with captive device ecosystems, pure-play software vendors competing on interoperability depth, and emerging AI specialists seeking FDA breakthrough designations. Two competitive moves define current positioning: cloud infrastructure alliances with hyperscalers and vertical integration into cath lab hemodynamic data capture.
Within the diversified imaging tier, Philips Healthcare, Siemens Healthineers, and GE Healthcare exemplify distinct strategic postures. Philips leverages deep diagnostic hardware integration to sustain platform stickiness across multi-hospital contracts. Siemens anchors its position through in-house AI development for echocardiography quantification. GE competes on workflow breadth, extending enterprise imaging footprints into cardiovascular service lines through modular software procurement.
| Leading Market Players |
|---|
| Fujifilm Healthcare |
| Agfa HealthCare |
| Philips Healthcare |
| Samsung Medison |
| Sectra |
| Siemens Healthineers |
| Canon Medical Systems Corporation |
| Medtronic |
| GE Healthcare |
| Others |
Value Chain & Pricing Dynamics
Integrated delivery networks in the United States concentrate procurement authority for cardiovascular enterprise viewers, driving subscription-based SaaS contracts that bundle perpetual software licenses with cloud infrastructure and AI module access. This buyer consolidation shifts pricing power toward vendors with established Epic EHR interoperability and FDA-cleared diagnostic algorithms.
Pricing Analysis
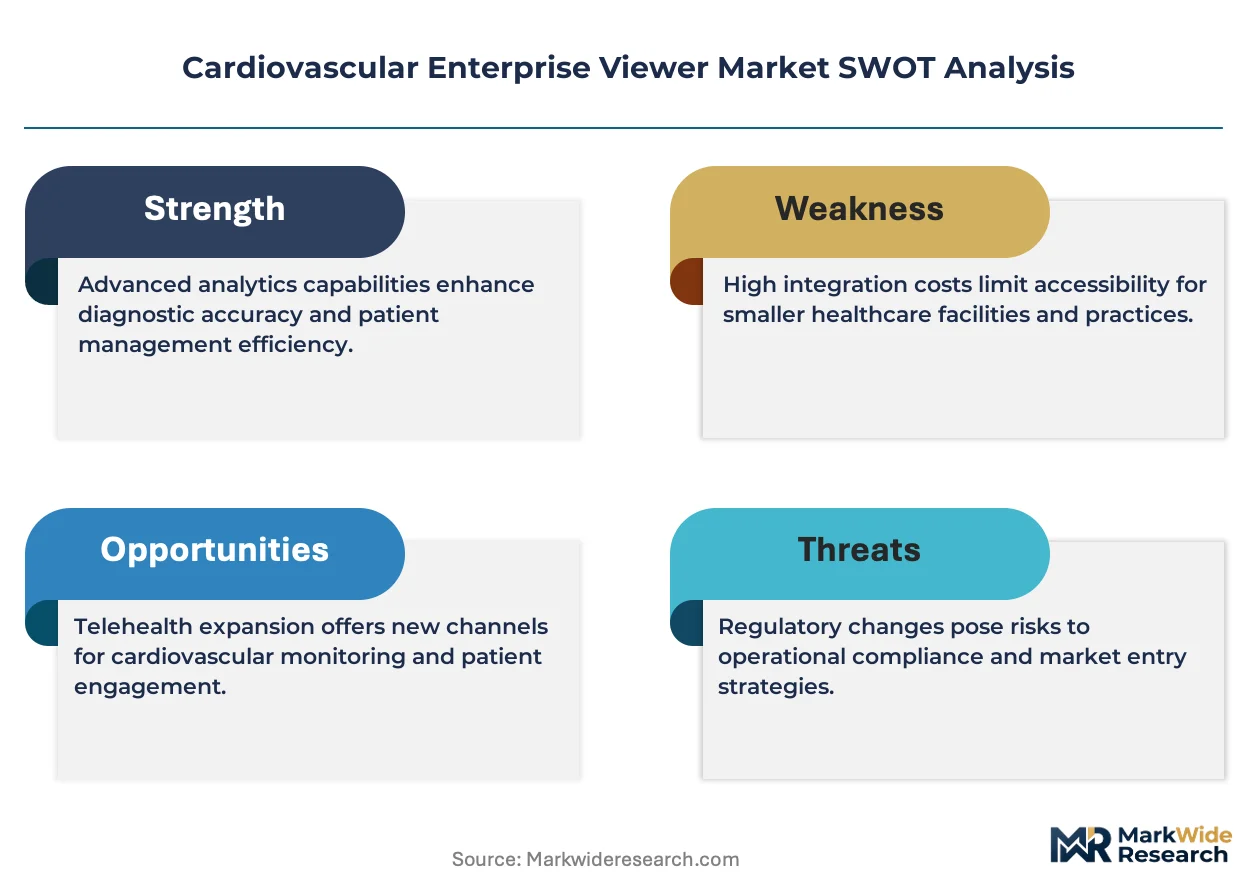
Extended warranty and implementation service bundling distinguishes premium-tier contracts from stripped-down SaaS offerings. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth—FDA 510(k) cleared AI modules command substantial premiums over basic viewing licenses. Pricing pressure stems from hyperscaler cloud cost transparency as AWS and Azure pricing benchmarks force legacy on-premise vendors toward competitive subscription rates. Mid-sized hospital systems exhibit highest price sensitivity, deferring AI module purchases until reimbursement pathways solidify.
Supply Chain Analysis
Freight costs for GPU-enabled cath lab workstations and specialized DICOM storage arrays inflate landed costs for European and Asia-Pacific deployments. Component manufacturing concentrates in Germany, Japan, and the United States, with NVIDIA GPU supply and medical-grade display panels representing critical dependencies. Single-source vulnerability in AI accelerator chips creates procurement risk for real-time echocardiography analysis platforms. Distribution runs through regional medical device distributors with specialized cardiovascular imaging expertise, bypassing general IT channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cardiovascular enterprise viewer market operates as a cost-of-compliance story where FDA 510(k) clearance timelines and ONC Cures Act interoperability certification create substantial barrier-to-entry moats favoring established players with regulatory affairs infrastructure.
For Market Incumbents: Anchor platform stickiness through deep Epic EHR integration and captive AI algorithm development. Siemens Healthineers' echocardiography quantification roadmap exemplifies defensive positioning against pure-play software entrants. Prioritize backward integration into hemodynamic data capture systems for cath lab workflow control. For New Entrants and Emerging Players: The price-point gap between Philips-GE premium contracts and regional PACS vendors creates white-space opportunity in rural telecardiology and Indian diagnostic lab chains. Cloud-native workflow solutions with teleradiology service bundling penetrate most easily where capital budget constraints intersect with specialist shortages. For Investors and Strategic Acquirers: The window for entry favors AI specialists with FDA breakthrough device designations and proven clinical validation partnerships. Long-term viability hinges on reimbursement pathway establishment for algorithm-assisted cardiology reads. Monitor CMS coverage determinations for automated ejection fraction analysis as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Hyperscaler Cloud Partnership | AWS HealthLake and Azure Health Data Services integration accelerates hospital system contract velocity. |
| AI Algorithm FDA Submission | 510(k) clearance for left ventricular ejection fraction tools unlocks reimbursement and enterprise platform bundling. |
| Epic EHR Integration Certification | MyChart and Haiku mobile compatibility satisfies IDN interoperability mandates under ONC Cures Act rules. |
| Cath Lab Hardware-Software Bundle | Philips and Siemens leverage diagnostic device installed bases to displace third-party enterprise viewers. |
| Telecardiology Service Launch | Rural hospital network partnerships in Montana and North Dakota address specialist access gaps with cloud platforms. |
Study Parameters
SEC 10-K filings, FDA 510(k) clearance databases, and hospital GPO contract repositories formed the secondary backbone, cross-referenced with primary interviews involving cath lab directors, health system CIOs, biomedical engineers, and HL7 FHIR implementation specialists. Bottom-up and top-down triangulation validated vendor-reported installed bases against health system procurement records and cloud infrastructure deployment disclosures.
Bottom-up modeling aggregated individual hospital system contract values by technology tier and deployment scale, while top-down analysis calibrated aggregate market sizing against medical device trade association estimates across the projection horizon. Segmentation dimensions included product type, end-user category, deployment architecture, and geographic regulatory cluster. CAGRs derived from historical replacement cycle analysis and interoperability mandate implementation timelines, with AI module attach rates and cloud migration velocity as industry-specific forecast inputs.
Inputs from FDA clearance databases and hospital procurement systems were available through the study window; gaps in private vendor pricing disclosure introduce uncertainty bands around subscription revenue estimates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Carotid Stenosis Market
Cardiovascular
Eisenmenger Syndrome Treatment Market
Cardiovascular
Aortic Coarctation Market
Cardiovascular
Tachycardia Market
Cardiovascular
Vasculitis Market
Cardiovascular
Cardiac Biomarkers Market
Cardiovascular
Hypercholesterolemia Drugs Market
Cardiovascular
Heart Health Products Market
Cardiovascular
Middle East and Africa Acute Coronary Syndrome Market
Cardiovascular
Carotid Artery Disease Market
Cardiovascular
Acute Coronary Syndrome (ACS) Market
Cardiovascular
Global Hypotension Treatment Market
Cardiovascular
Chronic Heart Failure Market
Cardiovascular
Global Cardiac Rehabilitation Market
Cardiovascular
Unstable Angina Therapeutics Market
Cardiovascular
Restrictive Cardiomyopathy Treatment Market