
 Mortuary Refrigerator Market | 2026-2036
Mortuary Refrigerator Market Size, Share, and Industry Trends Forecast 2026-2036
Mortuary Refrigerator Market Outlook
China's manufacturing expansion is rewriting supply dynamics for mortuary refrigeration equipment. Fiocchetti leverages Italian engineering heritage to dominate premium European installations. CEABIS sustains a strong position in Mediterranean markets through specialized funeral home distribution. Bally Refrigerated Boxes anchors North American demand with heavy-gauge stainless steel construction.
Mortuary refrigerators are temperature-controlled cabinets designed to preserve deceased human remains at 2°C to 4°C using vapor compression or thermoelectric cooling systems, primarily serving funeral homes, hospitals, and medical examiners requiring hygienic temporary storage. Vapor compression technology leads installed base due to reliability in high-humidity environments, while thermoelectric systems are gaining traction in portable and wall-mounted installations where noise reduction matters. Multi-body units command the largest revenue share among product types as regional hospital networks consolidate procurement, though single-body configurations retain stable demand from independent funeral operators.
FDA guidelines on medical device sanitation and EPA energy conservation standards shape product development cycles and certification costs for manufacturers selling into the United States. CE marking under EU MDR and F-Gas Regulation compliance in Europe add parallel testing burdens that favor established players with dedicated regulatory affairs teams. Stakeholders must monitor evolving cold-chain traceability requirements and decide whether to absorb compliance costs or exit jurisdictions with tightening environmental rules.
Market Dynamics
Hospital network consolidation across the United States is compressing procurement timelines and favoring multi-body refrigeration units over single-body configurations, reshaping manufacturer capacity planning and service infrastructure requirements.
Growth Catalysts
- EPA Energy Conservation Standards:Tightening compressor efficiency mandates in the United States are accelerating replacement cycles for aging mortuary refrigeration equipment in hospital and medical examiner facilities.
- Funeral Home Case Volume Expansion:Rising death rates in aging Western populations are forcing independent funeral operators to expand cold storage capacity beyond legacy single-body configurations.
- Thermoelectric Cooling Advancement:Solid-state refrigeration technology is penetrating portable and wall-mounted installations where noise reduction and vibration elimination are prioritized over energy efficiency.
Market Restraints
- Stainless Steel Input Volatility:Heavy-gauge 304 and 316 stainless steel price fluctuations directly compress manufacturing margins for premium cabinet construction.
- Supply Concentration in Chinese Manufacturing:Component sourcing for compressors and control systems clusters in East Asian production hubs, exposing lead time risks to North American and European assemblers.
- F-Gas Regulatory Friction:EU phasedown of hydrofluorocarbon refrigerants under the F-Gas Regulation is forcing costly retooling of vapor compression systems for European market access.
Strategic Opportunities
- Indian Healthcare Infrastructure:Government hospital expansion under the Ayushman Bharat scheme is creating first-time demand for mortuary refrigeration in tier-2 and tier-3 cities.
- Cold-Chain Traceability Mandates:Emerging requirements for temperature logging and digital documentation in medical examiner offices favor connected refrigeration platforms with integrated monitoring.
- Rental and Leasing Channels:Funeral home operators are migrating from capital purchase to operational expenditure models, opening recurring revenue streams for equipment-as-a-service providers.
Industry Challenges
- Refrigeration Technician Scarcity:Specialized knowledge of medical-grade cooling systems and FDA sanitation protocols is concentrating among aging technician cohorts in developed markets.
- CE-MDR Certification Timelines:Extended conformity assessment periods under the EU Medical Device Regulation are delaying product launches and freezing R&D roadmaps for European-bound portfolios.
- Legacy Control System Integration:Hospital IT departments face friction connecting new refrigeration units to existing building management systems and electronic health record platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mortuary Refrigerator Market |
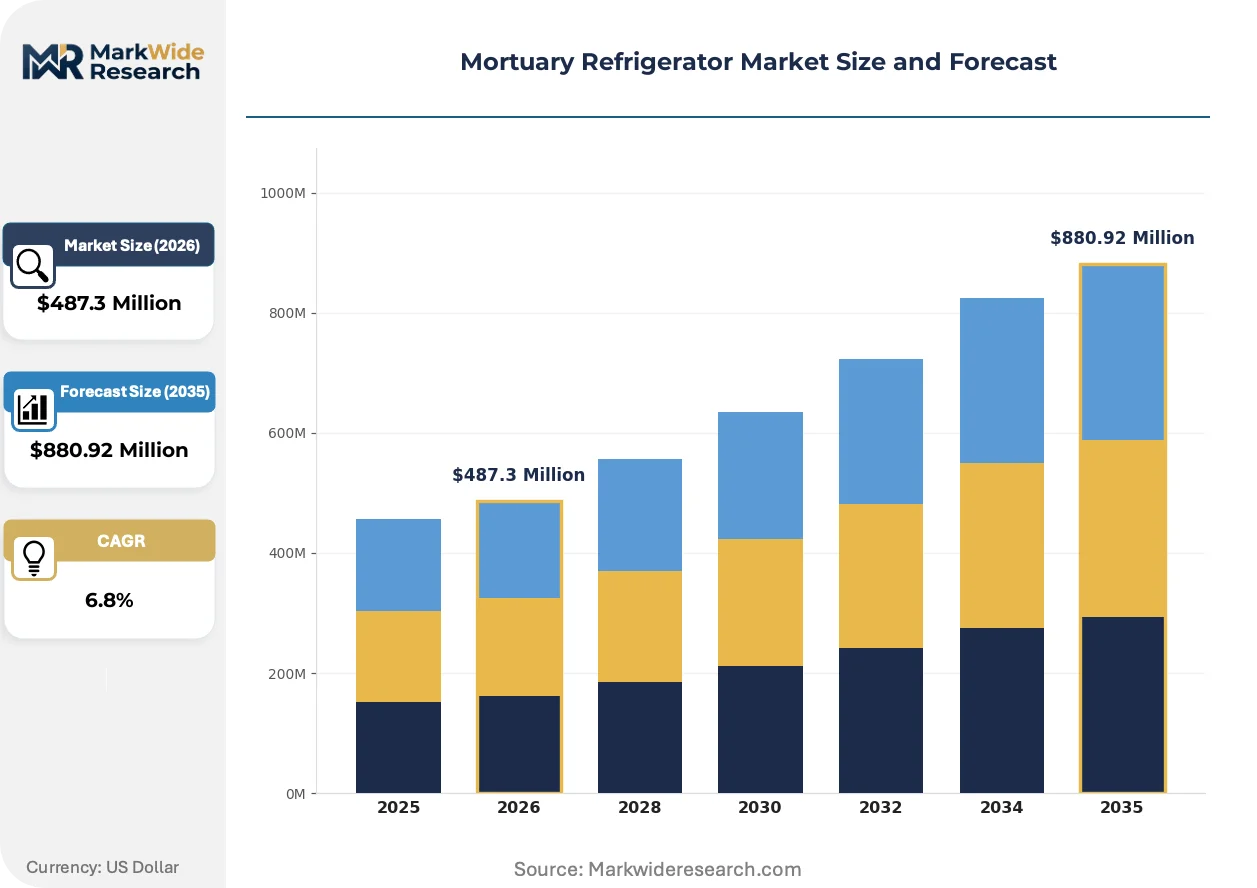
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Body, Double Body, Multi-Body, Cold Storage Unit Technology: Vapor Compression, Thermoelectric, Air-Cooled, Water-Cooled End User: Funeral Homes, Hospitals, Research Facilities, Medical Examiners Installation: Free-standing, Wall-mounted, Custom-built, Portable |
| Companies Covered | Fiocchetti, CEABIS, Bally Refrigerated Boxes, Hygeco, EIHF Isofroid, Mortech Manufacturing, Barber Medical, Paragon Care Ltd., LEEC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mortuary Refrigerator Market Strategic Shifts
Digital monitoring capabilities and refrigerant chemistry changes are converging to redefine equipment specifications and service expectations across funeral home, hospital, and medical examiner installations.
Remote temperature monitoring systems using IoT sensors and cloud-based dashboards are virtualizing the traditional manual logging protocols that medical examiners and hospital morgues have relied upon for decades. Large hospital networks in the United States are mandating these connected platforms to satisfy Joint Commission audit requirements and reduce liability exposure. The technology is virtualizing aftermarket service relationships by enabling predictive maintenance alerts and remote diagnostics that compress technician dispatch frequency.
The EU F-Gas Regulation phasedown schedule is forcing refrigerant transitions from high-global-warming-potential hydrofluorocarbons to natural alternatives including propane and carbon dioxide in vapor compression architectures. Equipment manufacturers serving European markets must redesign compressor systems and pressure vessels to accommodate flammable or high-pressure refrigerants. Multi-body unit portfolios face the steepest redesign burden due to larger refrigerant charge volumes and complex piping networks.
Consolidated procurement departments at regional hospital systems are unbundling after-sales service contracts from equipment purchase agreements and sourcing maintenance through third-party clinical engineering firms. Independent service organizations are displacing manufacturer-direct service teams in North American metropolitan markets. This pattern is most visible in the United States, where health system mergers have concentrated buying power and standardized vendor qualification processes across multi-state footprints.
Mortuary Refrigerator Market Segmentation
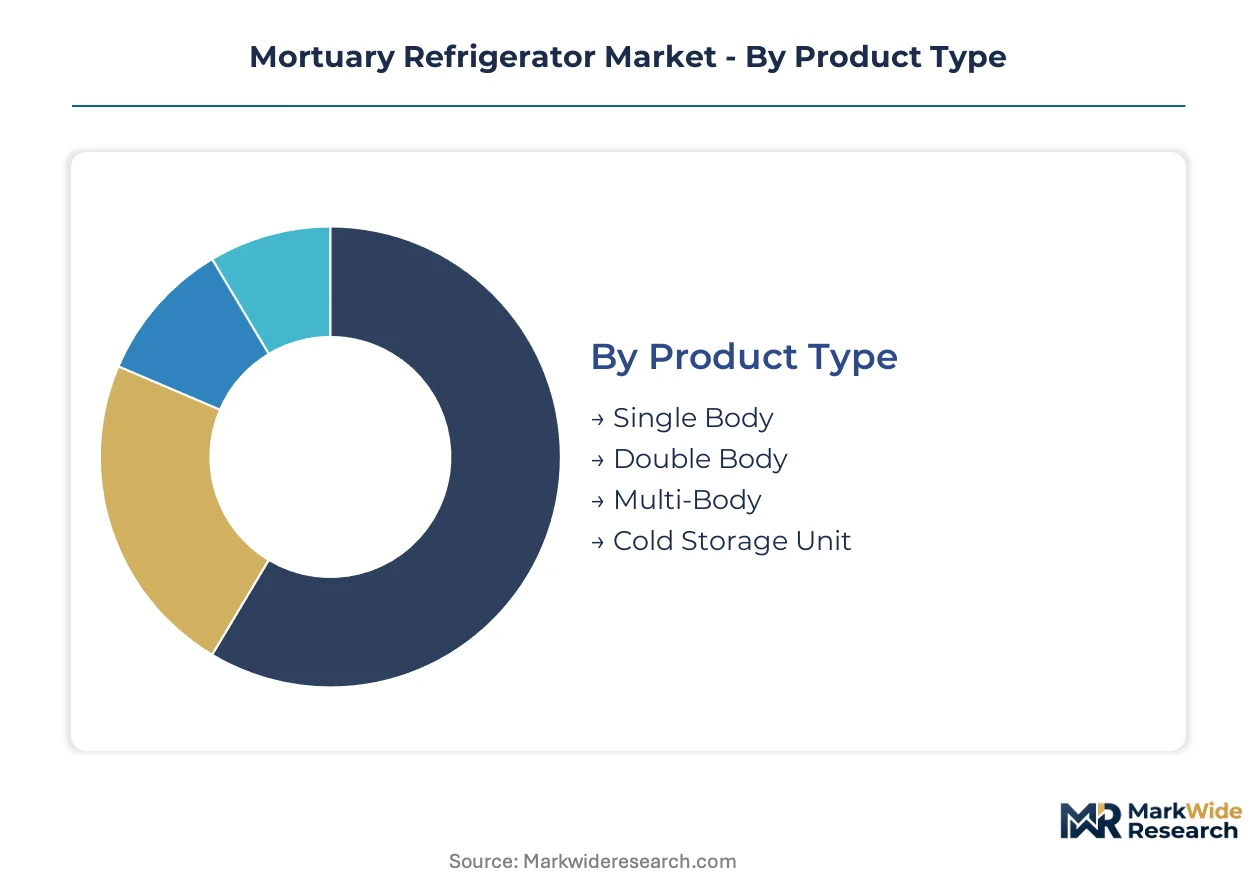
Mortuary refrigeration procurement patterns diverge sharply by facility scale and regulatory exposure. Hospital networks prioritize multi-body configurations with connected monitoring, while independent funeral operators favor modular single-body units that preserve floor plan flexibility.
Product Type:
Cost tier differentiation separates capital-intensive hospital installations from budget-constrained independent operators.
- Multi-Body:Three-to-six chamber cabinets dominate consolidated hospital procurement in the United States, where bulk purchasing agreements favor standardized footprints over customization. Regional health system mergers are compressing vendor qualification lists and mandating unified service contracts across state boundaries.
- Single Body:Individual chamber units serve independent funeral homes requiring incremental capacity expansion without infrastructure overhaul. Legacy single-body installations in Western Europe face replacement pressure from EU F-Gas Regulation compliance deadlines.
- Double Body:Twin-chamber configurations balance space constraints against throughput needs in mid-sized medical examiner offices.
- Cold Storage Unit:Walk-in chamber systems address mass casualty surge capacity requirements in metropolitan medical examiner facilities.
Multi-body units hold installed capacity. Single-body configurations are rotating up the share rankings as independent funeral home case volumes expand.
Technology:
Application environment dictates cooling architecture selection between reliability-critical hospital settings and noise-sensitive funeral installations.
- Vapor Compression:Mechanical refrigeration using hermetic compressors maintains temperature stability across high-humidity morgue environments. FDA sanitation protocols and EPA energy conservation standards in the United States are accelerating replacement of pre-2010 compressor systems in hospital networks.
- Thermoelectric:Solid-state Peltier cooling eliminates compressor vibration and acoustic signature, penetrating wall-mounted and portable installations in funeral homes where family viewing proximity demands silence. Thermoelectric efficiency limitations restrict penetration in high-ambient-temperature climates.
- Air-Cooled:Fin-and-tube condenser configurations dominate free-standing installations where water infrastructure is unavailable or restricted.
- Water-Cooled:Shell-and-tube or plate heat exchanger systems serve high-density multi-body installations with available chilled water loops.
Vapor compression anchors the installed base. Thermoelectric architectures are climbing the fastest as solid-state reliability improves.
End User:
Customer type determines specification stringency, with medical examiner offices imposing the most rigorous documentation and chain-of-custody requirements.
- Hospitals:Clinical morgue operations demand continuous temperature logging, redundant cooling circuits, and integration with building management systems. Joint Commission accreditation requirements in the United States are mandating connected monitoring platforms with automated alert escalation.
- Funeral Homes:Family-owned operators prioritize aesthetic integration with viewing room décor and quiet operation over technical sophistication. Funeral home consolidation into corporate chains is standardizing procurement specifications across multi-location portfolios.
- Medical Examiners:Forensic pathology facilities require evidentiary-grade temperature documentation with tamper-proof logging for legal defensibility.
- Research Facilities:University anatomy departments and biobank operations utilize mortuary-grade refrigeration for cadaver preservation in medical education contexts.
Hospitals command specification leadership. Funeral homes are gaining procurement volume as death rate demographics shift.
Installation:
Volume and mobility requirements separate permanent infrastructure investments from flexible deployment strategies.
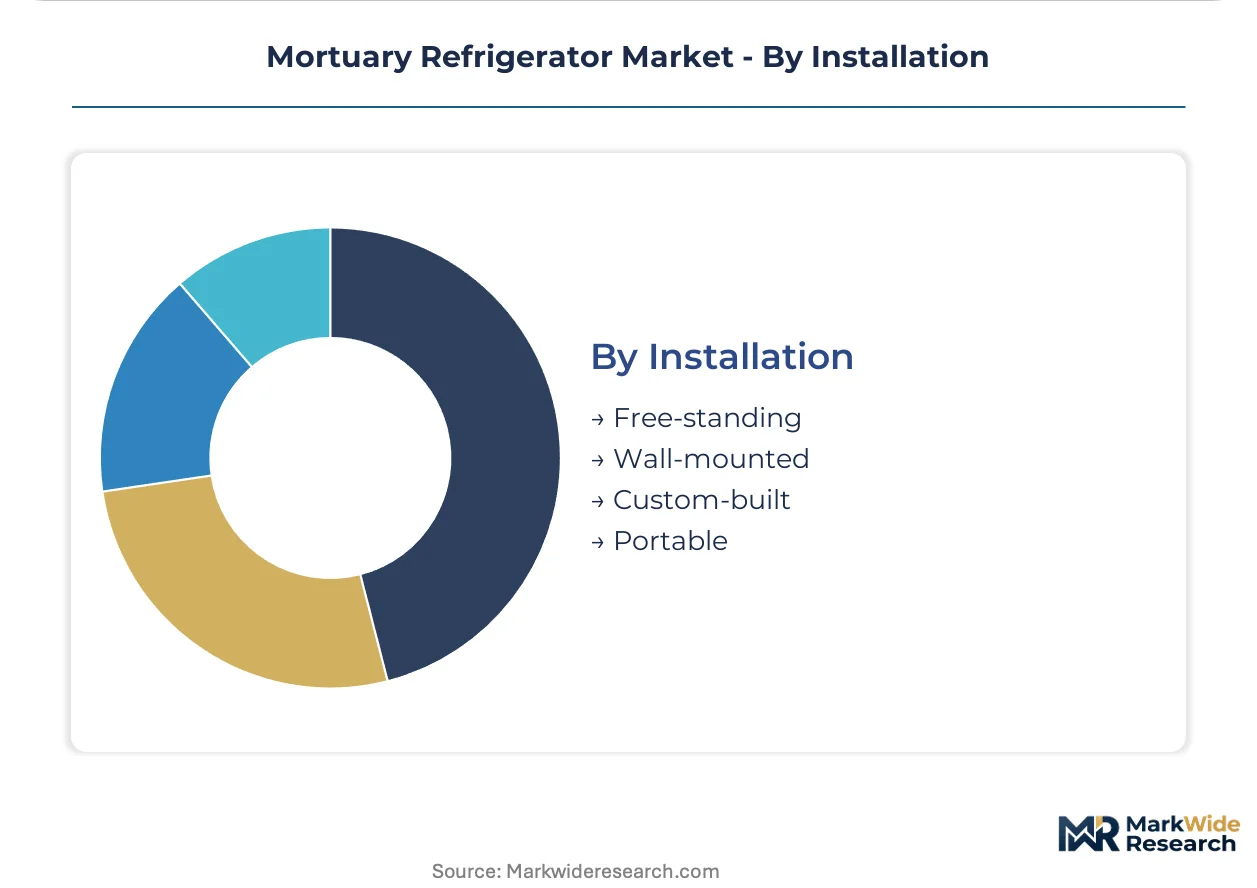
- Free-standing:Self-supported cabinet configurations accommodate existing floor plans without structural modification, dominating retrofit installations in aging hospital facilities.
- Wall-mounted:Suspended units preserve floor space in constrained funeral home preparation rooms, with thermoelectric cooling enabling slim profiles impossible with compressor-based systems.
- Custom-built:Architect-integrated installations serve new hospital construction and morgue renovation projects with precise dimensional and finish specifications.
- Portable:Mobile cart-based units address temporary surge capacity, disaster response deployment, and rental channel expansion in the United States funeral services market.
Free-standing units hold installed capacity. Portable configurations are rotating up the share rankings as rental channels mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturing clusters supply compressor assemblies and control systems to assemblers across North America and Europe, creating lead time vulnerabilities that procurement departments now hedge through dual-sourcing strategies. Regional demand patterns diverge sharply between aging Western populations requiring replacement cycles and emerging Asian markets building first-time cold storage infrastructure.
United States
Hospital network consolidation across state boundaries compresses vendor qualification lists and mandates unified service contracts for multi-body installations. EPA energy conservation standards tighten compressor efficiency specifications, accelerating replacement of pre-2010 systems in clinical morgues. Metropolitan medical examiner facilities in Chicago and Los Angeles anchor demand for walk-in cold storage units addressing mass casualty surge capacity.
Germany
EU F-Gas Regulation phasedown schedules force refrigerant transitions from hydrofluorocarbons to natural alternatives in vapor compression architectures. CE marking under EU MDR extends conformity assessment timelines, freezing R&D roadmaps for European-bound portfolios. The industrial corridor between Stuttgart and Munich concentrates precision fabrication capabilities serving premium cabinet specifications.
China
Government hospital expansion under provincial healthcare infrastructure programs creates first-time demand for mortuary refrigeration in tier-2 and tier-3 cities. NMPA medical device registration requirements shape product development cycles for domestic manufacturers. The Yangtze River Delta manufacturing cluster dominates compressor component sourcing, exposing North American assemblers to shipping lead time volatility.
India
Ayushman Bharat scheme hospital expansion generates initial procurement of mortuary refrigeration equipment in previously underserved urban centers. CDSCO medical device regulations establish quality benchmarks that favor established players with dedicated regulatory affairs teams. Maharashtra and Karnataka state hospital networks drive bulk procurement volumes for multi-body configurations.
United Kingdom
NHS trust consolidation standardizes procurement specifications across regional pathology networks, favoring connected monitoring platforms with automated alert escalation. MHRA post-Brexit regulatory autonomy creates parallel certification requirements distinct from EU MDR pathways. The Greater London medical examiner system anchors specification leadership for evidentiary-grade temperature documentation.
Mortuary Refrigerator Market Competitive Environment
Italian engineering specialists and North American heavy-fabrication houses split the market along premium-standard tier boundaries. The vendor base concentrates around three strategic archetypes: European precision manufacturers leveraging heritage positioning, Asian-scale fabricators optimizing component costs, and regional service-integrated distributors capturing aftermarket revenue. Competitive dynamics center on M&A activity consolidating funeral home operator supply chains and capacity expansion into Indian healthcare infrastructure.
Among European heritage manufacturers, Fiocchetti and CEABIS exemplify the premium-tier positioning built on specialized funeral home distribution networks. Bally Refrigerated Boxes anchors North American demand through heavy-gauge stainless steel construction capabilities. These three names occupy positions reflecting geographic specialization rather than scale dominance, with each representing distinct supply chain configurations serving their respective regional regulatory environments.
| Leading Market Players |
|---|
| Fiocchetti |
| CEABIS |
| Bally Refrigerated Boxes |
| Hygeco |
| EIHF Isofroid |
| Mortech Manufacturing |
| Barber Medical |
| Paragon Care Ltd. |
| LEEC |
| Others |
Value Chain & Pricing Dynamics
Chinese compressor manufacturing clusters in the Yangtze River Delta concentrate upstream supply for vapor compression systems, anchoring margin pools in North American and European assembly operations that command premium pricing through FDA and CE-MDR certification tiers.
Pricing Analysis
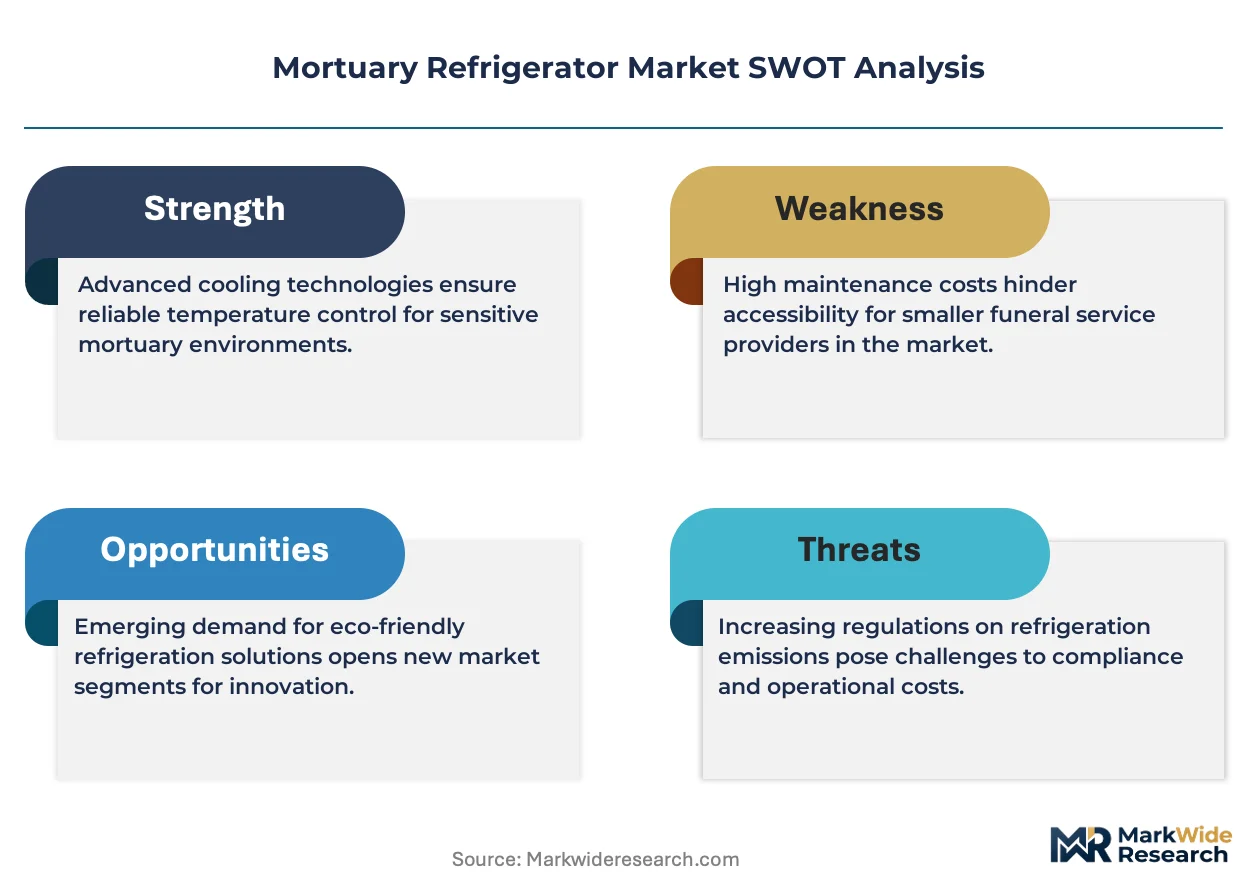
EPA energy conservation standards and EU F-Gas Regulation compliance dictate the pricing tier structure across premium, standard, and economy levels. Price differentiation rests on certification grade and after-sales service bundling, with FDA-validated systems commanding substantial premiums over non-medical-grade alternatives. Cost compression in the standard tier is intensifying due to Chinese component imports, while independent funeral operators remain the most price-sensitive segment and consolidated hospital networks the least.
Supply Chain Analysis
Extended payment terms from Chinese component suppliers have become standard practice, compressing working capital cycles for North American and European assemblers. Manufacturing draws from China, Italy, and the United States, with heavy-gauge 304 and 316 stainless steel, hermetic compressors, and IoT control modules as critical inputs. Single-source vulnerability concentrates in compressor assemblies from East Asian hubs. Distribution runs through funeral home equipment distributors, hospital GPO contracts, and direct regional service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across independent funeral operators and tier-2 hospital networks creates niche entry points, as procurement decentralization outpaces consolidation in underserved geographies.
For Market Incumbents: Build regulatory compliance moats through CE-MDR and FDA dual-certification investments to defend against emerging Asian-scale fabricators. Deepen backward integration into stainless steel fabrication to offset commodity volatility, while expanding service infrastructure across multi-state hospital networks to capture unbundled maintenance contracts. For New Entrants and Emerging Players: Establish a beachhead in India's Ayushman Bharat hospital expansion, where first-time demand for mortuary refrigeration outpaces established vendor presence. Target tier-3 city procurement through CDSCO-registered product lines and localized service partnerships, leveraging rental-channel economics to bypass capital-purchase barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed funeral services consolidators seeking vertical integration into equipment supply. Five-to-ten-year viability hinges on cold-chain traceability mandate adoption; monitor Joint Commission connected-monitoring requirements as the inflection signal for platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| CE-MDR Dual Certification Investment | Unlocks premium European hospital procurement and defends margin position against Asian competitors. |
| IoT Platform Integration | Meets Joint Commission audit requirements and enables predictive maintenance revenue streams. |
| Natural Refrigerant System Redesign | Ensures EU market access under F-Gas Regulation phasedown schedules. |
| Indian Distribution Partnership | Captures Ayushman Bharat infrastructure expansion in tier-2 and tier-3 cities. |
| Equipment-as-a-Service Launch | Converts funeral home capital expenditure to recurring revenue and reduces customer churn. |
Study Parameters
The analysis maps vapor compression and thermoelectric technology segments, each validated through hospital biomedical engineers, funeral home operators, medical examiner office administrators, and refrigeration service technicians. Primary interviews combined with secondary validation from FDA 510(k) filings, EPA energy conservation standard dockets, EU MDR technical documentation databases, and hospital GPO contract records. Bottom-up unit demand modeling triangulated against top-down healthcare infrastructure spending forecasts.
Assumptions held fixed include regulatory compliance timelines and stainless steel input cost trajectories, while technology adoption rates and hospital consolidation velocity were varied across sensitivity scenarios. Segmentation dimensions modeled encompass product type, cooling technology, end-user facility, installation configuration, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles and first-time demand penetration curves, with compressor efficiency standards and death rate demographics as key forecast inputs.
Stress conditions across refrigerant chemistry transitions, Chinese shipping lead times, and hospital merger approval timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and supply chain resilience. Macroeconomic contraction, accelerated F-Gas phasedown schedules, or breakthrough solid-state cooling technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Medical Device and Equipment Tags Market
Medical Equipment
Forensic Equipment and Supplies Market
Medical Equipment
Global Optometry Equipment Market
Medical Equipment
Home Medical Equipment Market
Medical Equipment
Single-Coated Medical Tape Market
Medical Equipment
Defibrillator Analyzers Market
Medical Equipment
US Biomedical Refrigerators and Freezers Market
Medical Equipment
Bone Densitometer Systems Market
Medical Equipment
Tanning Units Market
Medical Equipment
Global Renal Dialysis Equipment Market
Medical Equipment
Fluoroscopy Equipment Market
Medical Equipment
Medical Fluid Bags Market
Medical Equipment
Medical Ultrasonic Cleaners Market
Medical Equipment
PMMA Healthcare Market
Medical Equipment
Autoclaves Market
Medical Equipment
Refurbished Medical Equipment Market