
 Thermo Elastic Acrylic Market | 2026-2036
Thermo Elastic Acrylic Market Size, Share, and Industry Trends Forecast 2026-2036
Thermo Elastic Acrylic Market Analytics
Aftermarket service revenue for thermo elastic acrylic fabrication and refurbishment is reshaping margin distribution across the value chain. Mitsubishi Chemicals leverages captive monomer supply to sustain cost advantages in sheet-grade production. Evonik Industries anchors European demand through specialized molding compounds for medical equipment. AGC Inc. competes on optical-clarity specifications in consumer-facing applications across East Asia.
Thermo elastic acrylic denotes a class of thermoplastic polymers combining polymethyl methacrylate backbone structures with elastomeric modifiers, typically processed via extrusion or injection molding at temperatures between 160°C and 240°C to achieve reversible flexibility for impact-resistant glazing and conformable surface coatings. Flexible Sheets command the largest current volume pool due to established architectural and transportation glazing demand, while Coatings represent the fastest-growing segment as manufacturers seek solvent-free application methods for automotive interiors. Molding Compounds retain concentrated margin pools in healthcare device housings where ISO 10993 biocompatibility certification creates qualification barriers.
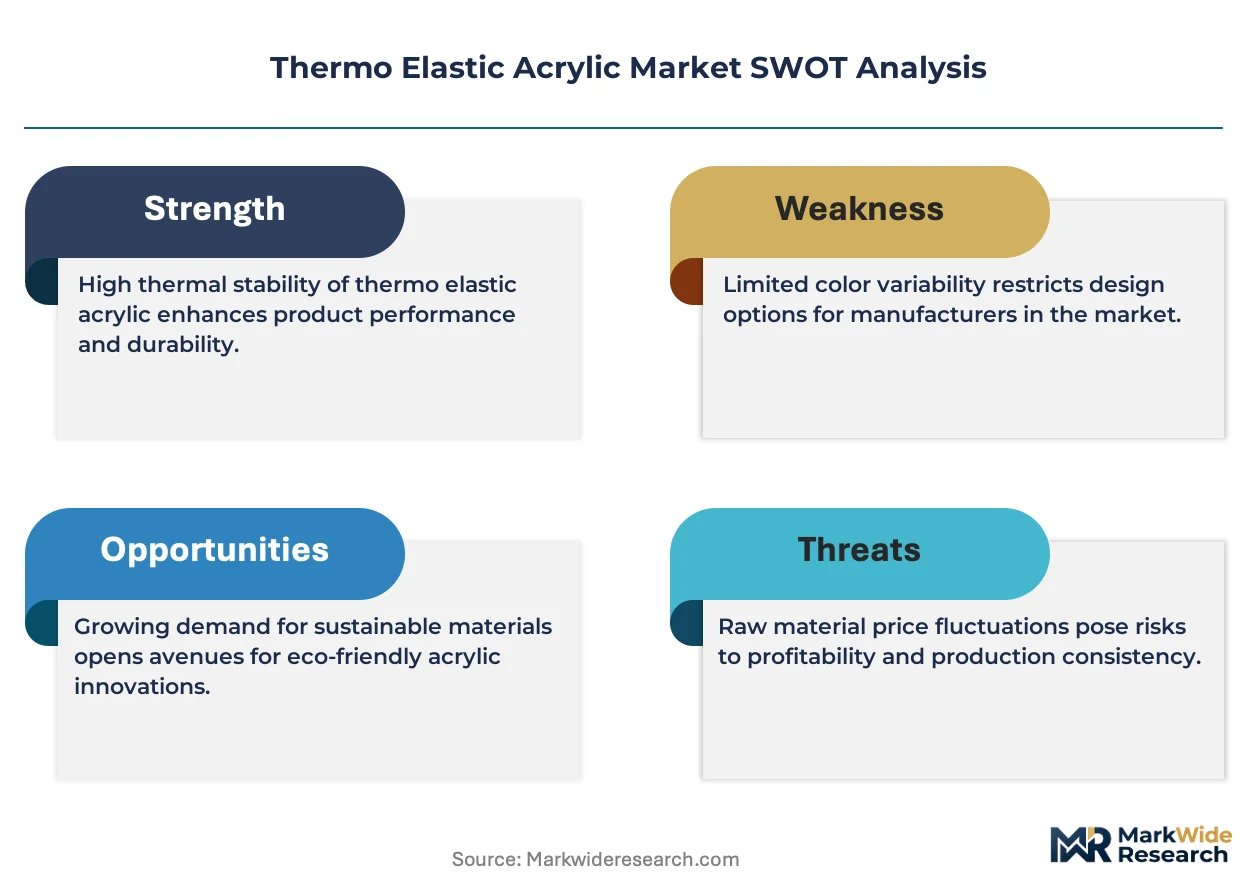
REACH registration requirements in Europe, GB standard compliance protocols administered by SAMR in China, and FDA material master file submissions for US medical device applications collectively elevate testing and documentation costs for multi-territory suppliers. The EU F-Gas Regulation indirectly shapes acrylic demand by restricting fluorinated polymer alternatives in certain sealing and barrier applications. Stakeholders must monitor evolving polymer substance restrictions under ECHA SVHC candidate list reviews to anticipate reformulation cycles and qualification timelines.
Market Dynamics
Automotive OEMs are consolidating interior material specifications around lighter thermoplastic alternatives, compressing qualification timelines and forcing reformulation cycles across the acrylic supply base.
Growth Catalysts
- Automotive lightweighting mandates:Cabin weight reduction targets in Germany and Japan are accelerating sheet-grade absorption for dashboard substrates and pillar trim.
- REACH SVHC transparency requirements:European substance disclosure rules are favoring acrylic formulations with established monomer supply chains over fluorinated polymer alternatives.
- Extrusion process refinements:Temperature control automation is widening the processing window for high-clarity optical grades in consumer electronics housings.
Market Restraints
- Methyl methacrylate feedstock volatility:Acetone cyanohydrin route dependence exposes margin compression during propylene supply disruptions.
- East Asian production concentration:Shanghai and Guangzhou corridor dominance creates single-region exposure for global sheet supply.
- Impact resistance ceiling:Elastomeric modifier loading limits restrict penetration into safety-critical automotive glazing above specified thickness thresholds.
Strategic Opportunities
- India automotive component localization:PLI scheme incentives for domestic manufacturing are opening qualification pathways for molding compound suppliers.
- Solvent-free coating protocols:Powder and UV-cure application methods are capturing automotive interior refurbishment demand previously served by solvent-based systems.
- Medical device biocompatibility certification:ISO 10993 master file accumulation creates defendable positions in diagnostic equipment housings.
Industry Challenges
- Multi-territory registration timelines:Parallel FDA, EMA, and NMPA material master file submissions extend product launch cycles by 18-24 months.
- Legacy extrusion asset retrofit costs:Temperature uniformity upgrades for elastomeric-modified formulations strain mid-cap processor balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermo Elastic Acrylic Market |
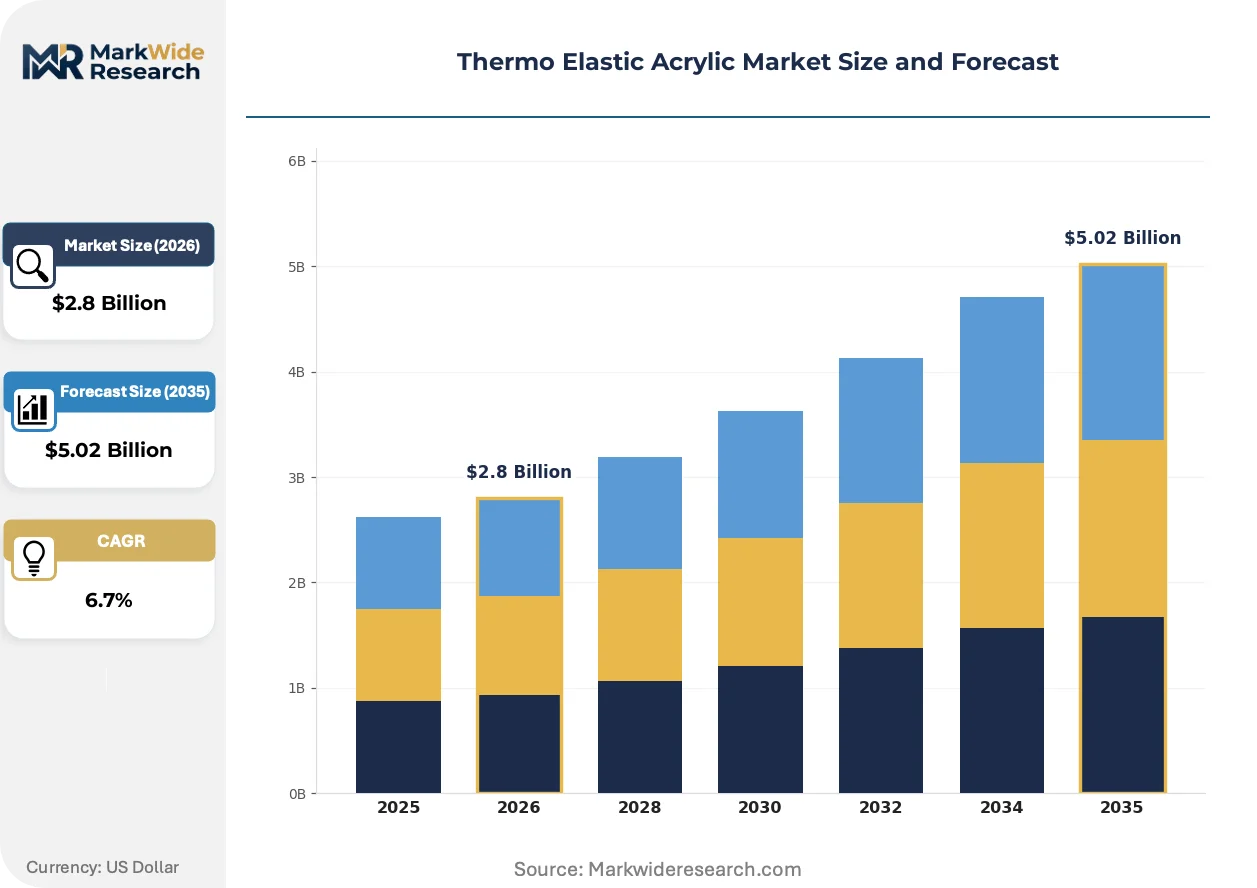
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Sheets, Coatings, Adhesives, Molding Compounds End User: Aerospace, Automotive Parts, Healthcare Devices, Consumer Products Application: Packaging, Automotive Interiors, Medical Equipment, Furniture Form: Solid, Liquid, Paste, Granules |
| Companies Covered | Mitsubishi Chemicals, Altuglas International, Evonik Industries, GARY Acrylic Xishun, Asia Poly Industrial Sdn Bdh, Ray Chung Acrylic Enterprise Co Ltd, Jumei Acrylic, Ningbo Shen Chuen Chemical Co, Ltd, AGC Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermo Elastic Acrylic Market Evolving Landscape
Process instrumentation and regulatory disclosure requirements are converging to reshape how acrylic formulations are qualified, traced, and priced across end-use verticals.
Real-time rheology monitoring is digitizing extrusion line control for thermo elastic acrylic sheet production. Tier-1 automotive suppliers in Germany are deploying inline viscosity sensors to reduce off-spec material generation. The technology is digitizing quality assurance workflows, compressing batch release timelines from days to hours.
The EU F-Gas Regulation is restricting fluorinated polymer alternatives in barrier and sealing applications, indirectly expanding acrylic formulation addressable markets. Industrial consequence includes accelerated qualification of acrylic-based sealing compounds for HVAC and refrigeration components. Medical equipment manufacturers in Switzerland and Germany are responding with expanded ISO 10993 testing programs to capture displaced fluoropolymer demand.
Specification consolidation among automotive OEMs is compressing approved vendor lists and elongating contract durations. Tier-2 processors are losing direct OEM access as procurement authority concentrates at Tier-1 systems integrators. The pattern is most visible in Japanese and South Korean supply chains, where platform sharing across brands amplifies buyer concentration effects.
Thermo Elastic Acrylic Market Segmentation
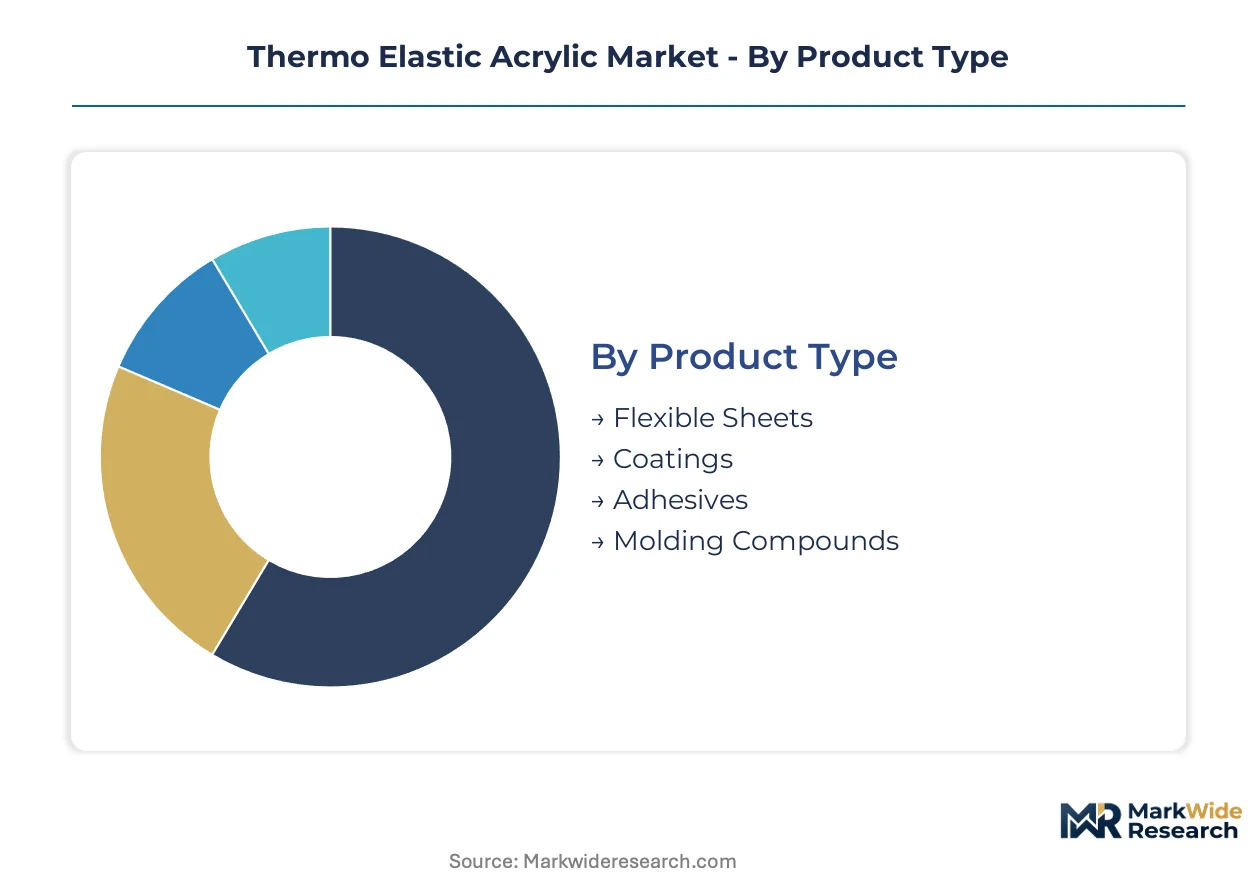
Product architecture in thermo elastic acrylic markets splits across four distinct form factors and application modalities. Each configuration carries specific processing constraints and margin profiles that shape supplier positioning across automotive, medical, and consumer verticals.
Product Type:
Application requirements dictate which material format commands procurement budgets across glazing, coating, and structural end-uses.
- Flexible Sheets:Extruded polymethyl methacrylate-elastomer laminates deliver impact-resistant glazing for transportation and architectural installations. Demand concentrates in German and Japanese automotive dashboard substrates where cabin weight reduction mandates accelerate sheet-grade absorption.
- Coatings:Solvent-free and UV-cure acrylic formulations enable conformable surface finishes without volatile organic compound exposure. Powder application methods are capturing automotive interior refurbishment demand previously served by solvent-based systems across East Asian manufacturing corridors.
- Adhesives:Pressure-sensitive and structural bonding grades bond dissimilar substrates in assembly operations.
- Molding Compounds:Injection-grade pellets with elastomeric modifiers target healthcare device housings requiring ISO 10993 biocompatibility certification.
Flexible Sheets command the established base. The steepest expansion runs through Coatings.
End User:
Customer sophistication and regulatory burden vary sharply across aerospace certification, automotive scale, medical compliance, and consumer price sensitivity.
- Automotive Parts:Tier-1 systems integrators consolidate specifications around lighter thermoplastic alternatives for interior trim, pillar covers, and dashboard substrates. OEM procurement authority concentrates at integrator level, compressing direct supplier access.
- Healthcare Devices:Diagnostic equipment and surgical instrument housings demand ISO 10993 master file accumulation and FDA material submissions. Swiss and German manufacturers are expanding testing programs to capture fluoropolymer displacement under EU F-Gas Regulation.
- Aerospace:Cabin interior panels and window surrounds require flame-retardant grades meeting FAA and EASA certification protocols.
- Consumer Products:Electronics housings and display covers prioritize optical clarity and scratch resistance at volume price points.
Automotive Parts absorbs the largest volume commitment. Healthcare Devices offers the most defensible margin structure.
Application:
Functional performance requirements determine formulation chemistry and processing method selection across barrier, structural, and aesthetic roles.
- Automotive Interiors:Dashboard substrates, door panels, and pillar trim specifications consolidate around thermoplastic alternatives as German and Japanese OEMs pursue cabin weight reduction targets. REACH SVHC transparency requirements favor established acrylic monomer supply chains over fluorinated alternatives.
- Medical Equipment:Diagnostic housings and surgical device enclosures require biocompatibility certification and sterilization resistance. Parallel FDA, EMA, and NMPA material master file submissions extend product launch cycles by 18-24 months for multi-territory suppliers.
- Packaging:Blister packs and sterile barrier systems leverage clarity and seal integrity for pharmaceutical distribution.
- Furniture:Surface laminates and edge banding exploit thermoformability for curved component fabrication.
Automotive Interiors represents the volume anchor. Medical Equipment shows the most rapid qualification expansion.
Form:
Physical state at point of use shapes logistics, equipment investment, and processing flexibility across the value chain.
- Solid:Extruded sheet and rod stock serve fabrication shops and OEM direct-forming operations. Temperature control automation is widening the processing window for high-clarity optical grades in consumer electronics housings.
- Liquid:Casting resins and coating dispersions enable in-situ polymerization for custom shapes and surface finishes.
- Paste:High-viscosity compounds support gap-filling adhesive and sealant applications in assembly operations.
- Granules:Injection molding feedstock pellets with controlled particle size distribution feed automated processing lines.
Solid forms dominate current shipment volumes. Liquid formulations are climbing fastest on coating substitution trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. German and Japanese automotive OEMs absorb sheet-grade volumes for cabin lightweighting, while East Asian manufacturing corridors concentrate coating demand for electronics and refurbishment applications.
China
GB standard compliance protocols administered by SAMR are tightening cross-border material specifications for thermo elastic acrylic imports. Shanghai and Guangzhou industrial zones dominate sheet extrusion capacity, serving domestic automotive Tier-1 suppliers and export-oriented electronics fabricators. Dual carbon goals are accelerating solvent-free coating substitution in Pearl River Delta manufacturing clusters.
Germany
REACH SVHC transparency requirements favor established acrylic monomer supply chains over fluorinated polymer alternatives in automotive sealing applications. KBA vehicle certification protocols integrate material substance disclosure into type-approval workflows. Bavarian chemical processing corridors around Ludwigshafen anchor European sheet-grade production for dashboard substrate supply to domestic OEMs.
United States
FDA material master file submissions for medical device applications elevate documentation burdens for molding compound suppliers targeting diagnostic equipment housings. EPA volatile organic compound regulations are compressing solvent-based coating demand in automotive refurbishment channels. Midwest extrusion processors serving Tier-1 integrators are retrofitting temperature control automation for elastomeric-modified formulations.
Japan
METI industrial standards for automotive interior materials are consolidating approved vendor lists around lighter thermoplastic alternatives. Platform sharing across domestic OEM brands amplifies buyer concentration effects in procurement workflows. Kanto and Kansai manufacturing belts concentrate optical-grade sheet production for consumer electronics display cover applications.
India
PLI scheme incentives for domestic automotive component manufacturing are opening qualification pathways for molding compound suppliers. BIS polymer standards are harmonizing with ISO frameworks to streamline import substitution in medical device housings. Gujarat and Maharashtra industrial corridors are attracting extrusion capacity investments targeting dashboard substrate localization for passenger vehicle OEMs.
Thermo Elastic Acrylic Market Competitive Landscape
Capability concentration sits with specialized compounders holding ISO 10993 master files; scale advantage sits with integrated petrochemical groups commanding captive monomer supply. The vendor base stratifies across three tiers: global diversified chemical conglomerates, regional sheet extrusion specialists, and niche medical-grade compounders. Strategic moves center on backward integration into methyl methacrylate feedstock and geographic expansion into Indian automotive supply chains.
Among Asia-Pacific fabricators, Mitsubishi Chemicals and AGC Inc. occupy positions anchored in East Asian manufacturing corridors, while Evonik Industries exemplifies the European specialist archetype with concentrated medical-grade molding compound capabilities. These three entities represent distinct competitive vectors: integrated petrochemical scale, optical-clarity specification leadership, and biocompatibility certification depth respectively.
| Leading Market Players |
|---|
| Mitsubishi Chemicals |
| Altuglas International |
| Evonik Industries |
| GARY Acrylic Xishun |
| Asia Poly Industrial Sdn Bdh |
| Ray Chung Acrylic Enterprise Co Ltd |
| Jumei Acrylic |
| Ningbo Shen Chuen Chemical Co, Ltd |
| AGC Inc. |
| Others |
Value Network & Pricing Analysis
Undercapacity in European sheet-grade production is tightening supplier discipline and amplifying pricing leverage for qualified compounders serving automotive OEM qualification programs.
Pricing Analysis
Long-term offtake contracts dominate procurement between Tier-1 automotive integrators and sheet extruders, insulating volume commitments from methyl methacrylate spot volatility. Price differentiation rests on ISO 10993 certification tier and captive monomer integration depth. Cost compression in standard-grade sheet runs through acetone cyanohydrin route exposure during propylene supply disruptions. Aftermarket fabricators exhibit highest price sensitivity; medical device OEMs demonstrate lowest sensitivity due to master file switching costs.
Supply Chain Analysis
Methyl methacrylate feedstock draws from integrated petrochemical complexes in Japan, Germany, and Saudi Arabia, with merchant market dependence elevating margin volatility for non-integrated processors. Acetone, hydrogen cyanide, and sulfuric acid constitute critical input exposures. Single-source vulnerability concentrates in Shanghai and Guangzhou corridor extrusion capacity. Distribution runs through Tier-1 systems integrators consolidating procurement authority away from direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermo elastic acrylic penetration sits at early-cycle expansion as automotive lightweighting mandates accelerate thermoplastic substitution in cabin architectures.
For Market Incumbents: Insulate qualification positions by deepening captive methyl methacrylate supply and accelerating ISO 10993 master file accumulation ahead of EU F-Gas Regulation displacement cycles. Prioritize temperature control automation retrofits to defend optical-grade sheet margins against emerging East Asian competitors.
For New Entrants and Emerging Players: Build out India automotive component supply chains under PLI scheme incentives, targeting dashboard substrate localization gaps left by incumbent capacity constraints. Establish solvent-free coating protocols to capture automotive interior refurbishment demand migrating from solvent-based systems.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among medical-grade compounders with FDA material master file libraries and multi-territory registration capabilities. Five-to-ten-year viability favors targets with backward integration into monomer supply or established biocompatibility certification depth. Monitor REACH SVHC candidate list expansions as inflection signals for fluoropolymer displacement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methyl Methacrylate | Captive monomer supply insulates margin compression during propylene disruption cycles. |
| ISO 10993 Master File Accumulation | Biocompatibility certification creates defendable positions in diagnostic equipment housing procurement. |
| Temperature Control Automation Deployment | Inline rheology monitoring compresses batch release timelines from days to hours for optical grades. |
| Solvent-Free Coating Protocol Expansion | Powder and UV-cure methods capture automotive refurbishment demand from solvent-based systems. |
| India Manufacturing Footprint Establishment | PLI scheme incentives open qualification pathways for dashboard substrate localization. |
Research Methodology
Operator-level perspectives from plant managers at extrusion facilities, procurement leads at Tier-1 automotive suppliers, distribution channel partners, and technical R&D directors anchored the qualitative base. These primary insights combined with secondary validation from customs trade data, SEC 10-K filings of listed chemical conglomerates, SAMR GB standard compliance bulletins, and ECHA SVHC candidate list reviews. Bottom-up segment sizing and top-down macroeconomic triangulation cross-checked volume estimates across the analysis window.
Scenario-bracketing around automotive lightweighting mandate intensity and REACH regulatory expansion pace shaped the analytical framework across product type, end-use industry, application function, and regional production hub dimensions. CAGRs derived from elasticity-adjusted demand curves incorporating extrusion capacity utilization rates, methyl methacrylate feedstock cost trajectories, and qualification timeline compression effects.
Stress conditions across propylene supply disruption severity, automotive OEM platform consolidation pace, and multi-territory registration timeline elongation were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against IHS Markit vehicle production databases and Cefic polymer trade statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Polyolefin Elastomer Market
Elastomeric Membrane
Specialty Elastomer Market
Elastomeric Membrane
North America Performance Elastomer Market
Elastomeric Membrane
Elastomeric Membrane Market
Elastomeric Membrane
Olefinic Thermoplastic Elastomers Market
Elastomeric Membrane
Ethylene Propylene Elastomers Market
Elastomeric Membrane
Middle-East and Africa Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Silicone Elastomers Market
Elastomeric Membrane
Water Soluble Elastomers Market
Elastomeric Membrane
Elastomeric Foam Insulation Market
Elastomeric Membrane
Elastomer Coated Fabric Market
Elastomeric Membrane
Bio-Based Elastomers Market
Elastomeric Membrane
Polyurethane Elastomers Market
Elastomeric Membrane
Middle-East and Africa Fluoroelastomers Market
Elastomeric Membrane
Cold Cast Elastomers Market
Elastomeric Membrane
Ultra-Soft Thermoplastic Elastomer Market