
 Polystyrene (PS) and Expanded Polystyrene (EPS) Market | 2026-2036
Polystyrene (PS) and Expanded Polystyrene (EPS) Market Size, Share, and Industry Trends Forecast 2026-2036
Polystyrene (PS) and Expanded Polystyrene (EPS) Market Analysis
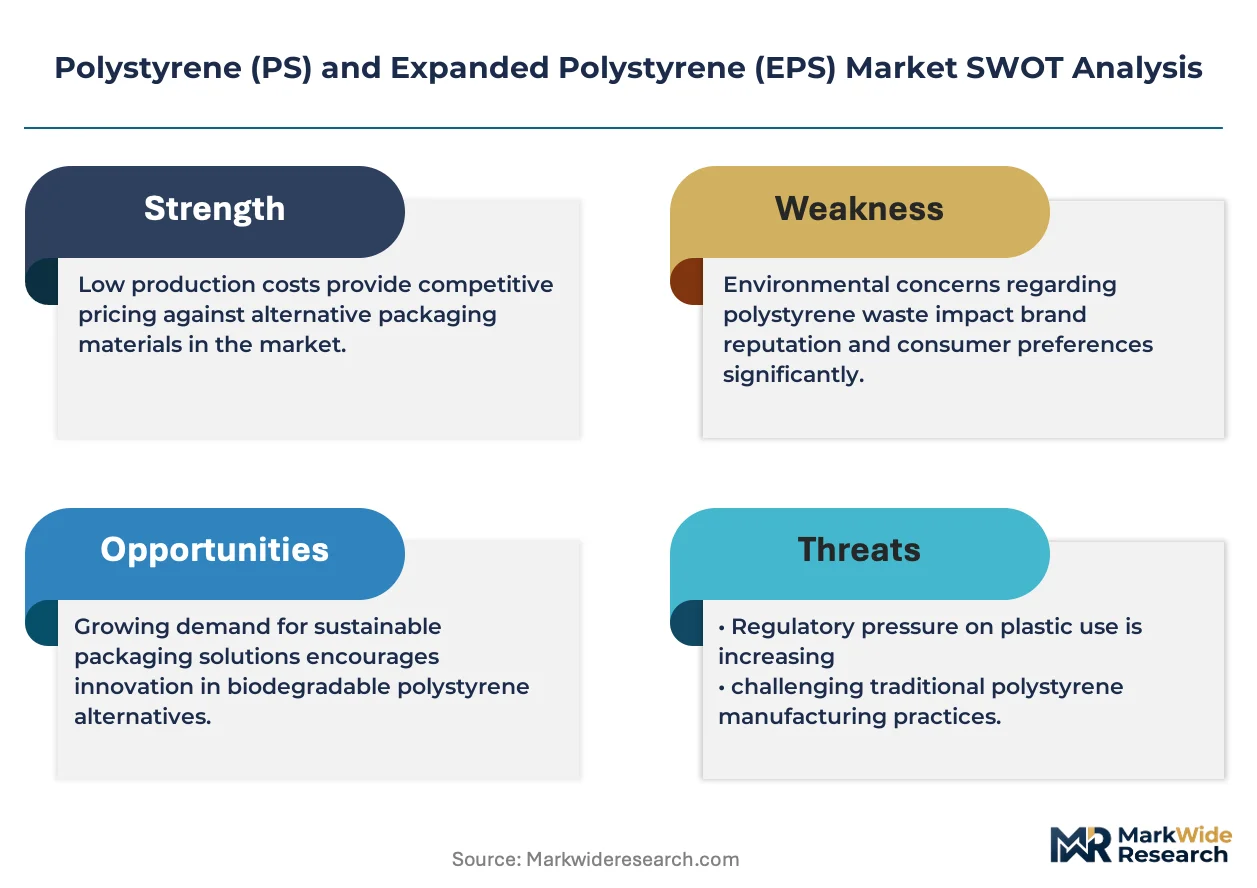
Project finance tied to green building certification is tilting competitive access toward capitalized producers. BASF SE leverages its integrated styrene monomer position to sustain margin stability across foam and solid grades. Alpek SAB de CV anchors its Americas footprint through backward integration into petrochemical feedstock. NOVA Chemicals differentiates via high-purity resin streams directed at food-contact packaging applications.
Polystyrene and expanded polystyrene comprise styrenic polymers ranging from rigid crystal PS with tensile strength near 50 MPa to cellular EPS with densities from 15 to 30 kg/m³ produced through suspension polymerization and bead expansion with pentane blowing agents, serving primarily as protective packaging, thermal insulation, and disposable foodservice articles. Foam EPS leads volume due to entrenched construction insulation demand, while solid PS in food-contact sheet occupies higher-margin niches governed by FDA and EFSA migration limits. High-impact PS competes in appliance housings where toughness specifications exceed general-purpose grades.
The EPA oversees VOC emissions from EPS manufacturing under Clean Air Act provisions, while REACH restricts residual styrene monomer in articles placed on the European market. ECHA's persistent organic pollutant screenings are reshaping flame-retardant additive choices in construction-grade EPS. Stakeholders must monitor regulatory tightening on microplastic release from EPS fragmentation and corresponding substitution pressure from bio-based alternatives.
Market Dynamics
The EU F-Gas Regulation and tightening building energy codes across multiple jurisdictions are redirecting specification toward higher-thermal-performance insulation materials, compressing demand for conventional EPS grades while elevating certified products.
Growth Catalysts
- Urban infrastructure build-out:India's cold-chain logistics investment and commercial construction pipeline are accelerating consumption of both solid PS and foam EPS grades for temperature-controlled storage.
- REACH flame-retardant screenings:ECHA's persistent organic pollutant evaluations are reshaping additive choices in construction-grade EPS, creating pull for reformulated compliant grades.
- Bead expansion technology:Advanced pentane recovery systems in EPS manufacturing are reducing VOC emissions while improving blowing agent efficiency.
Market Restraints
- Styrene monomer volatility:Benzene-ethylene feedstock cost swings compress margins for non-integrated processors lacking captive aromatics supply.
- Microplastic release scrutiny:Fragmentation concerns from EPS packaging are triggering substitution pressure from molded fiber and bio-based alternatives in foodservice applications.
- REACH residual monomer limits:Migration caps on styrene in articles placed on the European market add testing burden and disqualify non-compliant imports.
Strategic Opportunities
- India cold-chain penetration:Underdeveloped refrigerated transport infrastructure offers white space for EPS box liners and insulated panel systems in pharmaceutical and agricultural distribution.
- Green building certification finance:LEED and BREEAM-linked project lending is tilting competitive access toward producers with verified environmental product declarations.
- Digital inventory platforms:Direct-to-fabricator EPS distribution is bypassing traditional merchant channels in European construction supply.
Industry Challenges
- Pentane handling certification:EPA Clean Air Act compliance for VOC emissions requires specialized engineering controls and operator training that smaller molders struggle to fund.
- Food-contact migration testing:FDA and EFSA compliance timelines for solid PS sheet delay new grade launches by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polystyrene (PS) and Expanded Polystyrene (EPS) Market |
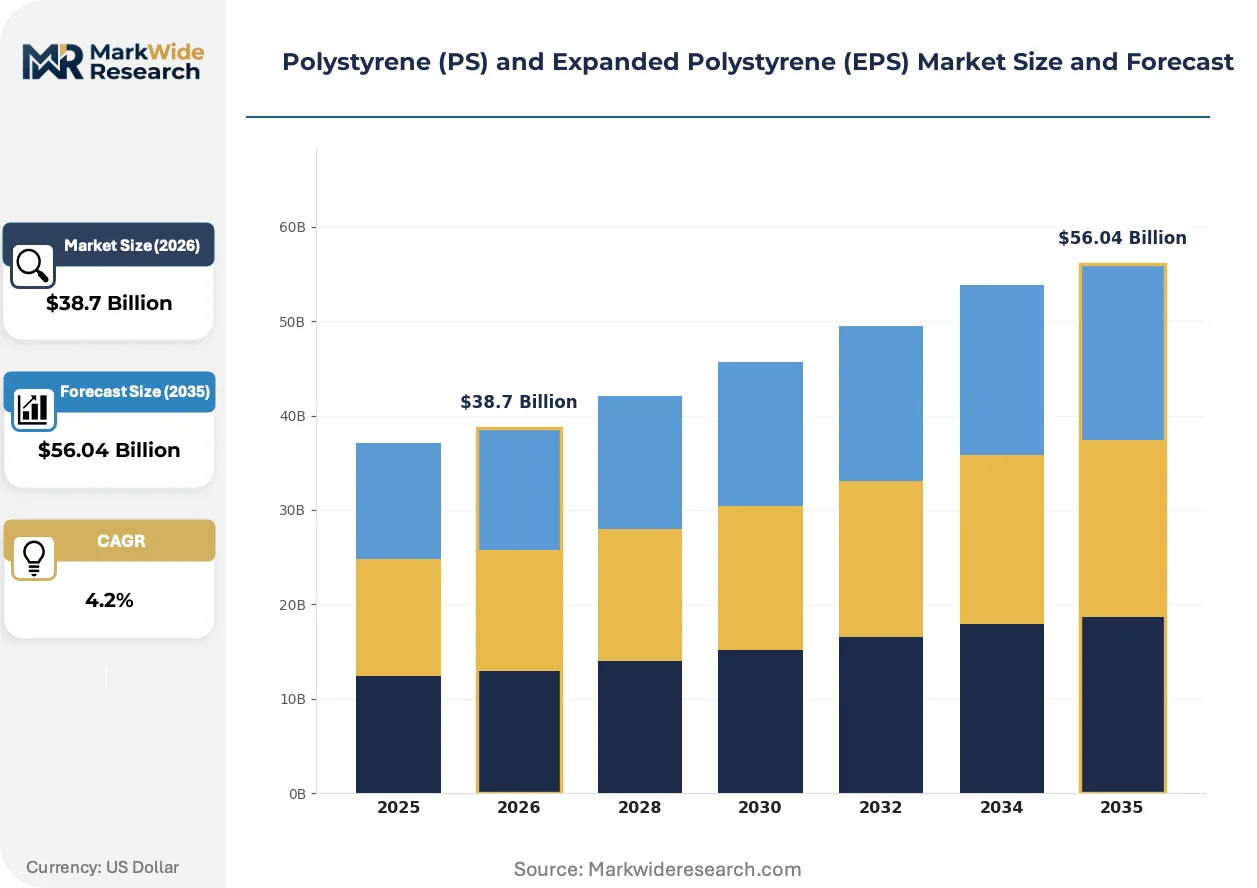
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $56.04 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid PS, Foam EPS, High-Impact PS, General Purpose PS End Use Industry: Packaging, Construction, Automotive, Consumer Goods Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors Form: Sheets, Blocks, Granules, Beads |
| Companies Covered | BASF SE, Alpek SAB de CV, NOVA Chemicals, SABIC, Synthos, Trinseo, Flint Hills Resources, ACH Foam Technologies, Sunpor Kunststoff, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polystyrene (PS) and Expanded Polystyrene (EPS) Market Emerging Trajectories
Manufacturing intelligence and regulatory chemistry are converging to transform how polystyrene grades are formulated, tracked, and specified across construction and packaging end-uses.
Closed-loop pentane recovery and real-time density monitoring is digitizing quality control in EPS bead expansion operations. Tier-one insulation fabricators in Germany and South Korea are deploying these systems to compress batch-to-batch variation and reduce virgin blowing agent consumption by half. The data streams are enabling predictive maintenance that cuts unplanned downtime.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon blowing agents is forcing reformulation of extruded polystyrene boards toward CO₂ and hydrocarbon alternatives. XPS producers in Poland and Italy are retooling extrusion lines to handle higher-pressure hydrocarbon systems. Construction specifiers in Nordic markets are already prioritizing these lower-global-warming-potential grades in public tender documents.
Certification-driven procurement is consolidating buyer preference around environmental product declarations and health product declarations. Large general contractors in California and British Columbia are embedding these requirements into subcontractor prequalification. The documentation burden is filtering out uncertified EPS molders from specification-grade commercial insulation projects.
Polystyrene (PS) and Expanded Polystyrene (EPS) Market Segmentation
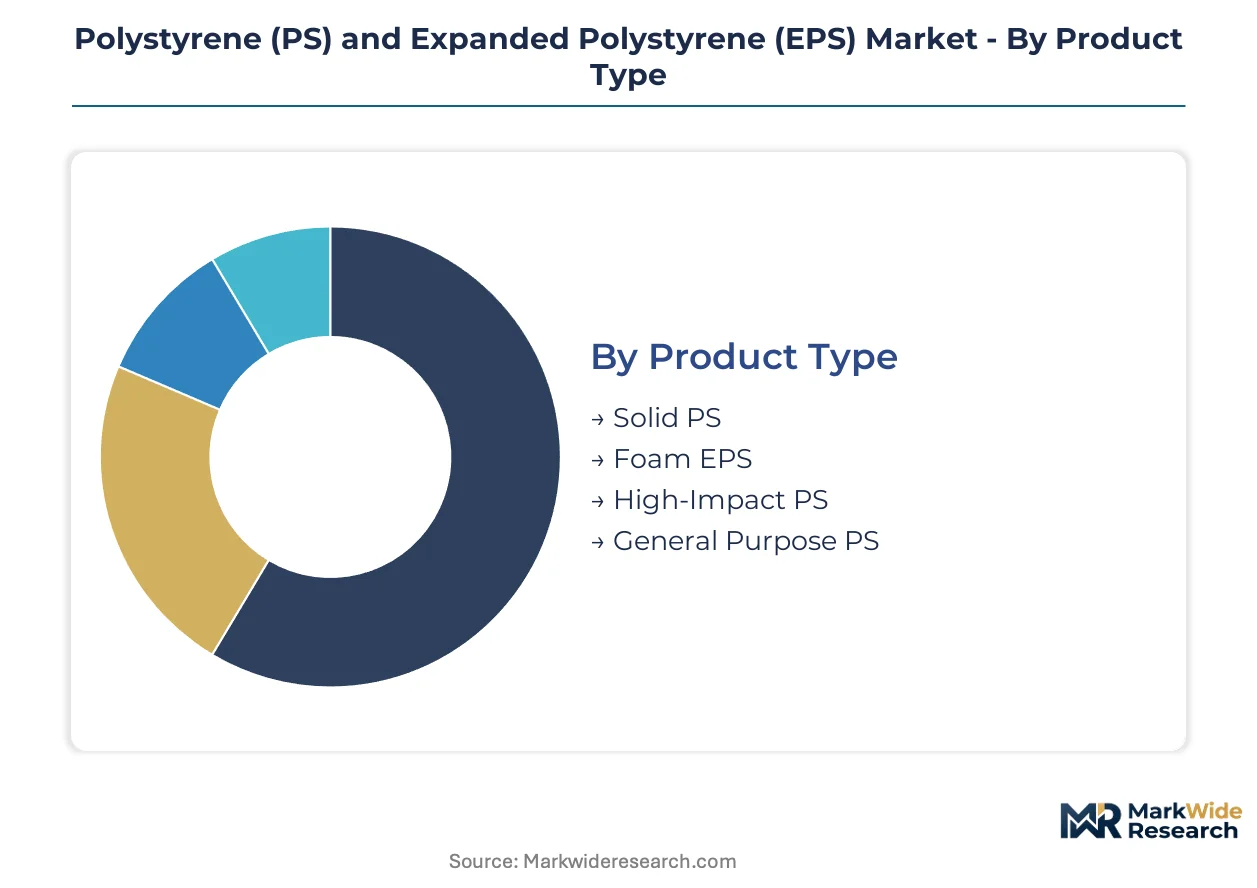
Segmentation in the polystyrene market reveals divergent margin profiles and regulatory exposure across product grades. Understanding these divisions enables producers to allocate capital toward insulated panel systems with green building certification premiums while managing commodity foam exposure.
Product Type:
After-sales service intensity varies sharply across product types, with foam EPS requiring technical field support for density calibration and construction-grade compliance documentation, while solid PS demands minimal post-sale engagement beyond standard quality claims.
- Foam EPS:Cellular structure with densities from 15 to 30 kg/m³ produced through bead expansion with pentane blowing agents. Demand concentrates in India's cold-chain logistics build-out, where pharmaceutical distribution networks require temperature-controlled box liners with validated thermal performance.
- Solid PS:Rigid crystal polymer with tensile strength near 50 MPa, governed by FDA and EFSA migration limits for food-contact applications. Specification in European foodservice packaging is tightening around residual monomer thresholds under REACH.
- High-Impact PS:Rubber-modified grade delivering enhanced toughness for appliance housings and durable goods.
- General Purpose PS:Unmodified crystal resin serving commodity injection molding and disposable applications.
Foam EPS holds the largest share; momentum sits with solid PS as food-contact compliance barriers elevate pricing power for certified grades.
End Use Industry:
Margin profiles stratify across end-use applications, with construction insulation commanding project-linked premiums and packaging facing relentless cost compression from molded fiber substitutes.
- Construction:Thermal insulation boards and insulated concrete form systems. EU F-Gas Regulation and tightening building energy codes in Germany and Poland are redirecting specification toward higher-thermal-performance certified products with environmental product declarations.
- Packaging:Protective cushioning and foodservice articles. Fragmentation concerns in California and British Columbia are triggering substitution pressure from bio-based alternatives in single-use applications.
- Automotive:Lightweight interior components and energy-absorbing structures.
- Consumer Goods:Appliance housings, electronics enclosures, and household durables.
Construction absorbs the highest volume; packaging is expanding most quickly in India's underpenetrated cold-chain infrastructure.
Distribution Channel:
Channel economics reflect customer scale and technical service requirements, with direct sales capturing specification-grade construction projects and merchant channels serving fragmented packaging molders.
- Direct Sales:Producer-to-fabricator relationships for large insulation contracts. Tier-one EPS producers in Germany and South Korea are deploying digital inventory platforms to bypass traditional merchant channels.
- Distributors:Regional stock-and-serve networks for small-batch packaging processors.
- Wholesalers:Volume aggregation for commodity-grade general purpose PS.
- Online Retail:Emerging channel for standardized bead and sheet products.
Direct sales dominate value capture; digital platforms are gaining share fastest among mid-size construction fabricators.
Form:
Physical form determines processing equipment requirements and logistics economics, with beads requiring specialized expansion infrastructure and sheets demanding precision extrusion capabilities.
- Beads:Expandable polystyrene precursor for molded foam applications. Advanced pentane recovery systems in South Korean manufacturing are reducing VOC emissions while improving blowing agent efficiency.
- Sheets:Extruded solid PS for thermoformed packaging. FDA compliance timelines for food-contact grades delay new product launches by 12-18 months.
- Blocks:Pre-expanded foam for carving and fabrication.
- Granules:Compounding feedstock for modified grades.
Beads constitute the highest volume form; sheets command the steepest premium expansion trajectory in certified food-contact applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction contractors and cold-chain logistics operators concentrate procurement in economies with active building energy code revisions and underdeveloped refrigerated distribution networks. India's pharmaceutical distribution infrastructure and Germany's insulation specification standards exemplify divergent buyer archetypes driving regional demand patterns.
India
Pharmaceutical cold-chain expansion and urban commercial construction accelerate consumption of both solid PS and foam EPS grades. The Bureau of Indian Standards enforces insulation performance benchmarks for temperature-controlled storage facilities. Maharashtra's Mumbai-Pune industrial corridor hosts expanding EPS molding capacity serving agricultural export packaging.
Germany
Building renovation subsidies and district heating network upgrades sustain specification-grade insulation demand. The EU F-Gas Regulation phases down hydrofluorocarbon blowing agents in extruded polystyrene applications. The Rhine-Ruhr chemical cluster maintains integrated styrene monomer production feeding foam board fabricators.
United States
LEED-certified commercial construction and appliance manufacturing anchor solid PS and high-impact grade consumption. The EPA oversees VOC emissions from EPS bead expansion under Clean Air Act provisions. The Gulf Coast petrochemical corridor supplies captive styrene feedstock to integrated resin producers.
China
Energy efficiency retrofits for existing building stock and expanding consumer electronics production drive insulation and packaging grade demand. The Ministry of Ecology and Environment enforces dual carbon goals affecting petrochemical feedstock sourcing. The Yangtze River Delta concentration houses expandable polystyrene bead production serving domestic construction markets.
Saudi Arabia
Giga-project construction and desalination facility insulation create demand for high-density foam boards. The Saudi Standards, Metrology and Quality Organization implements building thermal performance codes aligned with Gulf Cooperation Council harmonization. The Jubail industrial city cluster hosts aromatics integration supporting captive polystyrene resin output.
Polystyrene (PS) and Expanded Polystyrene (EPS) Market Vendor Landscape
Channel-controlling players compete with product-specialist players across differentiated specification tiers. Three to five integrated petrochemical groups anchor global resin supply through captive styrene monomer positions. Mid-scale regional molders occupy construction and packaging fabrication segments. Dominant competitive moves include backward integration into aromatics feedstock and certification-driven prequalification for green building project finance.
Among European-headquartered chemical conglomerates, BASF SE and Synthos occupy positions reflecting integrated feedstock control and regional manufacturing density. NOVA Chemicals represents North American-based producers with resin stream specialization. These three exemplify archetypes spanning integrated petrochemicals, regional scale players, and application-focused grade developers.
| Leading Market Players |
|---|
| BASF SE |
| Alpek SAB de CV |
| NOVA Chemicals |
| SABIC |
| Synthos |
| Trinseo |
| Flint Hills Resources |
| ACH Foam Technologies |
| Sunpor Kunststoff |
| Others |
Supply Flow & Price Mechanics
Overcapacity signals from China's Yangtze River Delta expandable polystyrene bead plants are compressing regional spot pricing and forcing integrated producers toward long-term offtake structures that lock in buyer commitments through indexed styrene monomer clauses.
Pricing Analysis
Cost-plus contracts indexed to ICIS benzene-ethylene spot assessments dominate resin procurement between integrated producers and large insulation fabricators. Price differentiation separates REACH-certified food-contact grades from commodity construction foam, with certification premiums widening as EFSA migration testing timelines extend. Pricing pressure stems from molded fiber substitution in California foodservice applications. Small-batch packaging molders exhibit highest price sensitivity; pharmaceutical cold-chain buyers accept certified-grade premiums.
Supply Chain Analysis
Upstream benzene-ethylene aromatics production concentrates in Saudi Arabia's Jubail cluster, Germany's Rhine-Ruhr chemical corridor, and the US Gulf Coast petrochemical belt. Polystyrene resin manufacturing draws from captive styrene monomer, imported high-purity grades, and recycled feedstock streams. Single-source vulnerability runs through pentane blowing agent supply concentrated with Middle Eastern LPG fractionators. Distribution runs through direct producer-to-fabricator relationships for construction insulation, bypassing merchant channels in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Green building certification mandates are accelerating specification-grade EPS demand, creating a high-growth disruption as LEED and BREEAM-linked project finance redirects procurement toward environmental product declaration holders.
For Market Incumbents: Build certification moats through third-party verified environmental product declarations and health product declarations embedded in prequalification systems. Anchor margin stability by securing captive aromatics supply through backward integration into benzene-ethylene feedstock. Defend against bio-based packaging substitutes by accelerating compliant flame-retardant reformulations ahead of ECHA persistent organic pollutant screenings.
For New Entrants and Emerging Players: India's underpenetrated pharmaceutical cold-chain infrastructure offers white space for insulated box liner systems with validated thermal performance documentation. Target Maharashtra's Mumbai-Pune industrial corridor for regional molding capacity serving agricultural export packaging. Pursue direct-to-fabricator digital distribution platforms to bypass entrenched merchant channels in European construction supply.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across certified food-contact solid PS grades due to extended FDA and EFSA compliance timelines. Long-term viability favors producers with integrated styrene monomer positions and green building certification access. Acquisition targets include regional EPS molders with environmental product declaration capabilities and underutilized bead expansion assets. Monitor ECHA microplastic release regulatory developments as inflection signal for substitution risk acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aromatics Feedstock | Captive benzene-ethylene supply insulates margin stability against feedstock volatility from Middle Eastern LPG markets. |
| Green Certification Program | Third-party environmental product declarations unlock LEED-linked project finance in California and British Columbia commercial construction. |
| Long-term Supply Agreement | Indexed cost-plus contracts with pharmaceutical cold-chain operators secure volume commitments through India's logistics infrastructure build-out. |
| Capacity Expansion | Bead expansion lines in Maharashtra's industrial corridor capture agricultural export packaging demand from underpenetrated regional markets. |
| Joint Venture | Technology partnerships with South Korean pentane recovery system developers reduce VOC emissions compliance costs for EU F-Gas Regulation alignment. |
Methodological Framework
A spread of perspectives from plant managers at integrated petrochemical facilities, procurement leads at downstream insulation fabricators, distribution channel partners, and technical R&D directors converged on the working assumptions. Primary field engagement combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and building energy code regulatory databases. Bottom-up grade-level volume estimates and top-down macroeconomic triangulation anchored the analytical framework.
Demand-supply balance modeling across the projection horizon incorporated grade tier, end-use industry, packaging format, and regional production hub segmentation. CAGRs derived from historical volume trajectories, capacity utilization rates, and substitution elasticity parameters. Pentane blowing agent efficiency improvements and REACH flame-retardant reformulation timelines served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Middle Eastern aromatics-integrated producers or accelerated bio-based packaging substitution would shift outcomes. Cross-checking against ICIS benzene-ethylene price benchmarks and EU construction permit databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
North America Super Absorbent Polymers (SAP) Market
Polymers & Resins
United Kingdom Engineering Plastics Market
Polymers & Resins
Global Protein a Resin Market
Polymers & Resins
Global Polymer Chameleons Market
Polymers & Resins
Vinyl Acetate Ethylene Copolymer Powder Market
Polymers & Resins
EVA Resins and Films Market
Polymers & Resins
China Engineering Plastics Market
Polymers & Resins
Semi-Rigid Spray Polyurethane Foam Market
Polymers & Resins
Polymer Gel Market
Polymers & Resins
South America Polyvinyl Chloride (PVC) Market
Polymers & Resins
Styrene Acrylonitrile (SAN) Resins Market
Polymers & Resins
Polyalkylene Glycols (Pags) Market
Polymers & Resins
Polyethylene Wax Market
Polymers & Resins
China Geopolymer Market
Polymers & Resins
Vinyl Acetate Homopolymer Emulsion Market
Polymers & Resins
Antimicrobial Plastics Market