
 Perfluoroelastomer (FFKM) Market | 2026-2036
Perfluoroelastomer (FFKM) Market Size, Share, and Industry Trends Forecast 2026-2036
Perfluoroelastomer (FFKM) Market Analysis
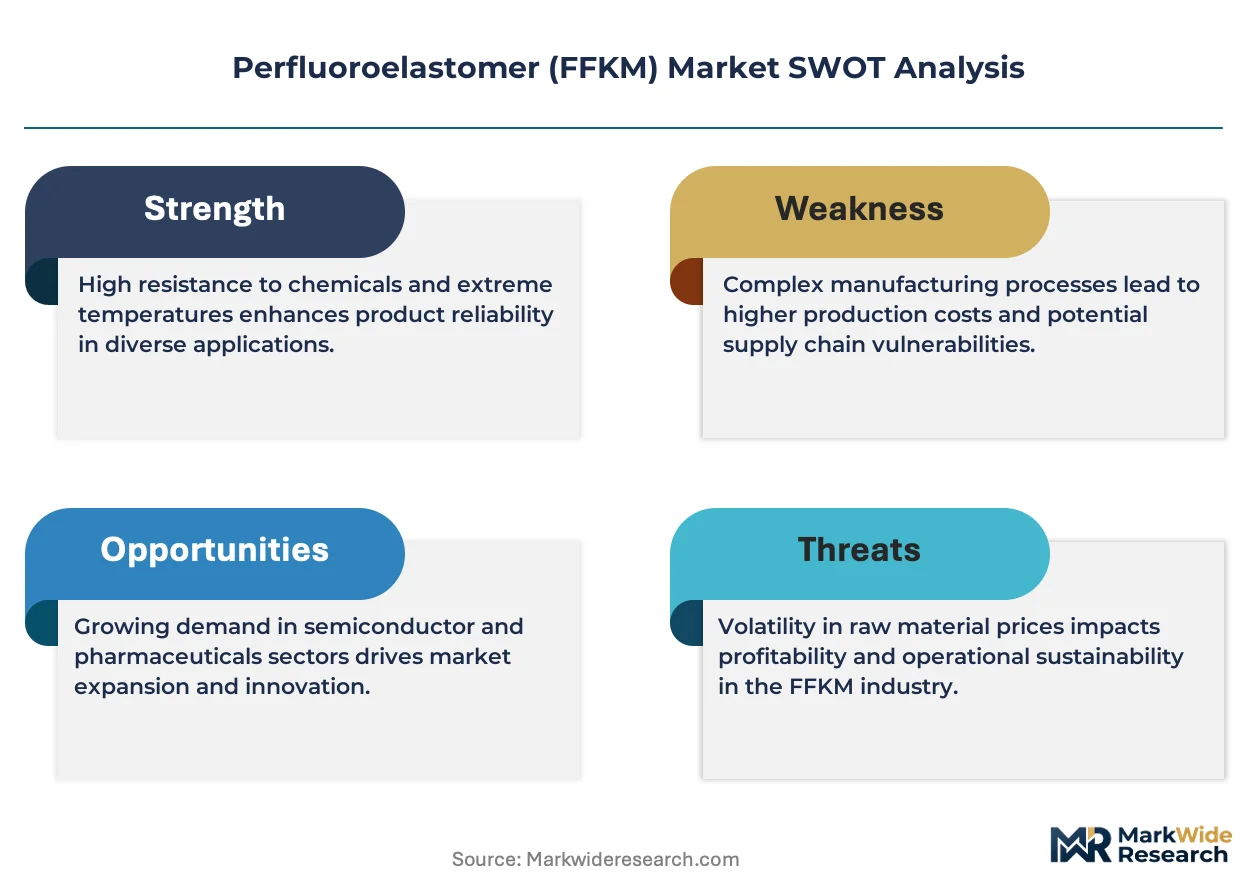
Semiconductor-grade purity specifications is unwinding legacy fluoroelastomer demand as chipmakers demand sub-ppb contamination control. DuPont sustains technology leadership through proprietary cure chemistry platforms optimized for plasma etch environments. Greene Tweed specializes in custom-compounded FFKM formulations for aerospace propulsion systems requiring sustained thermal oxidative stability. Precision Polymer Engineering dominates European aftermarket service channels with rapid-turn seal fabrication capabilities.
Perfluoroelastomer denotes a fully fluorinated polymeric material where all hydrogen atoms on the carbon backbone are replaced by fluorine, yielding continuous service temperatures exceeding 300°C and universal chemical inertness against aggressive acids, bases, and organic solvents. Virgin FFKM commands premium positioning in semiconductor wafer processing where metallic ion extraction must remain below detection limits. Filled FFKM competes aggressively in chemical processing valve sealing where carbon or mineral fillers enhance compressive set resistance without compromising fluid compatibility. Specialty FFKM variants incorporating perfluorinated ether monomers are displacing standard grades in extended-reach oilfield applications demanding low-temperature flexibility concurrent with sour gas resistance.
EPA hazardous air pollutant standards under NESHAP constrain elastomer selection in chemical process equipment, directly elevating FFKM specification rates for compliance-critical sealing points. REACH authorization requirements for perfluorinated substances are forcing compounders to document full material lifecycle profiles, advantaging established producers with existing registration dossiers. Semiconductor OEMs must monitor evolving EU F-Gas Regulation amendments that could restrict certain fluoropolymer precursor chemistries, potentially reshaping raw material sourcing strategies for seal fabricators serving this high-growth application segment.
Market Dynamics
Semiconductor fabrication complexity is accelerating FFKM specification rates as sub-3nm node transitions demand sealing materials with metallic ion extraction below single-digit ppb thresholds. Equipment OEMs now mandate full material lifecycle documentation ahead of procurement decisions.
Growth Catalysts
- EPA NESHAP hazardous air pollutant standards:Chemical processors in Texas and Louisiana are replacing legacy elastomers with FFKM seals at emissions-critical valve points to maintain operating permits.
- Extended-reach oilfield drilling:Sour gas resistance requirements at temperatures below -20°C are pulling perfluorinated ether-modified FFKM grades into North Sea and Permian Basin completions.
- German precision manufacturing clusters:Pharmaceutical isolator and reactor sealing applications in Ludwigshafen and Leverkusen are standardizing on semiconductor-grade FFKM for batch consistency.
Market Restraints
- Fluoropolymer precursor concentration:Tetrafluoroethylene monomer supply is concentrated among three Japanese and Chinese chemical conglomerates, creating feedstock vulnerability.
- REACH authorization timelines:ECHA's perfluorinated substance evaluation dossiers are extending compounder registration cycles to 18-24 months, freezing formulation innovation.
- High-performance thermoplastic substitution:PEEK and PFA injection-molded seals are capturing static sealing positions below 200°C where FFKM compression set advantages diminish.
Strategic Opportunities
- Indian semiconductor manufacturing incentives:PLI scheme subsidies for Gujarat and Karnataka fab construction are creating first-mover FFKM specification opportunities before supply chains mature.
- Green hydrogen electrolyzer scaling:Proton exchange membrane stack sealing at 80-90°C with concentrated KOH exposure represents an unpenetrated FFKM application vector.
- EU F-Gas Regulation amendment preparation:Seal fabricators documenting low-GWP precursor alternatives are positioning for preferred supplier status during 2027-2030 phase-down windows.
Industry Challenges
- Plasma etch chemistry certification delays:OEM validation protocols for new FFKM formulations in fluorocarbon and chlorine-based plasma environments extend 14-18 months, compressing product launch windows.
- Compound-to-fabrication coordination:Virgin resin batch variability requires real-time rheological adjustment at seal machining centers, straining quality systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Perfluoroelastomer (FFKM) Market |
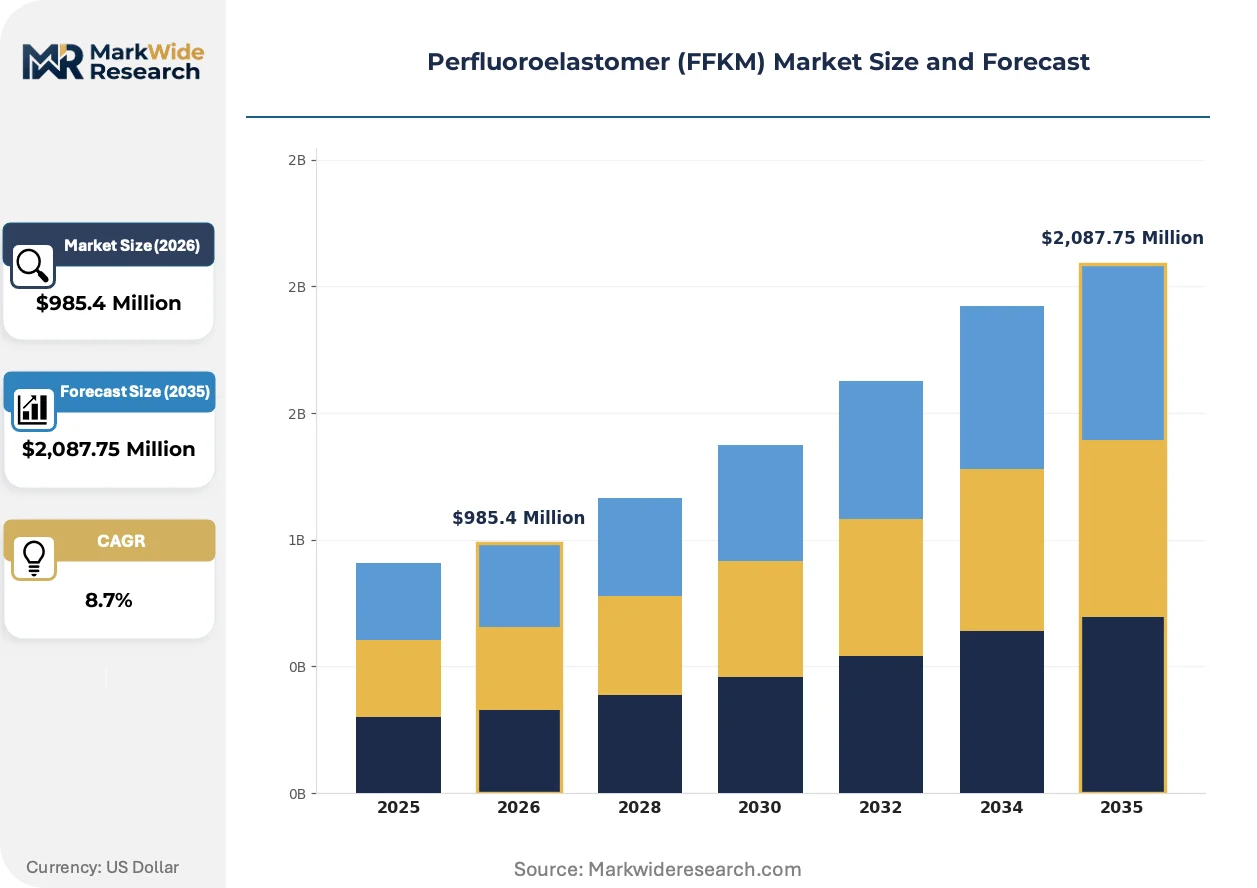
| Market Size in 2026 | $985.4 Million |
| Market Size in 2035 | $2,087.75 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Virgin FFKM, Filled FFKM, Coated FFKM, Specialty FFKM Application: Aerospace, Chemical Processing, Semiconductor, Pharmaceutical End User: Manufacturers, Research Institutions, OEMs, Service Providers Technology: Material Science, Polymer Engineering, Chemical Synthesis, Quality Assurance |
| Companies Covered | Daikin, Trelleborg, DuPont, Precision Polymer Engineering, Greene Tweed, 3M, Asahi Glass, Parker Hannifin, Solvay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Perfluoroelastomer (FFKM) Market Emerging Trajectories
Material science convergence with digital manufacturing is compressing FFKM development cycles while regulatory chemistry restrictions are forcing molecular architecture reinvention ahead of traditional R&D timelines.
Perfluorinated ether backbone modifications are supplanting standard tetrafluoroethylene-propylene copolymer structures in oilfield and aerospace applications. Equipment manufacturers in Norway's North Sea operations and California's Mojave test facilities are qualifying these grades for sustained thermal oxidative stability beyond 325°C. This molecular redesign is supplanting legacy FFKM in extended-temperature envelopes where standard grades experience catastrophic chain scission.
REACH authorization requirements for perfluorinated substances are forcing compounders to submit full material lifecycle profiles to ECHA by 2026. German and Belgian chemical processors are now demanding third-party verified extraction data for metallic ions and volatile oligomers before contract execution. Semiconductor seal fabricators serving Dresden and Leuven clusters are responding by captive-sourcing virgin resin batches with full pedigree documentation.
Consolidated procurement through equipment OEMs is displacing distributor-led specification in semiconductor capital equipment. Applied Materials and Lam Research are now mandating approved vendor lists with pre-qualified FFKM compounders, freezing out regional seal shops. This channel compression is most visible in Taiwan's Hsinchu Science Park and South Korea's Yongin cluster, where foundry maintenance teams lose material substitution autonomy.
Perfluoroelastomer (FFKM) Market Segmentation
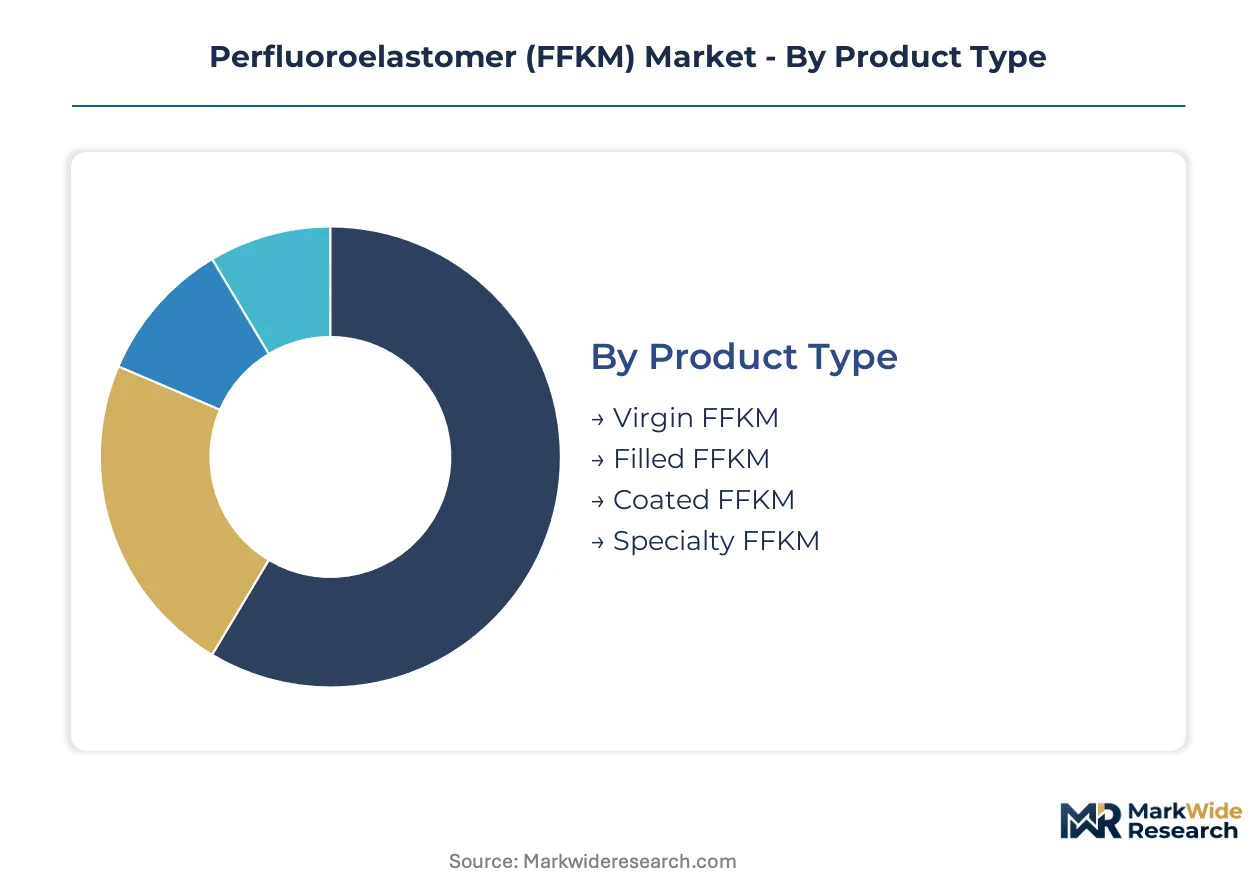
FFKM segmentation reveals distinct substitution vulnerabilities across product tiers, with thermoplastic alternatives encroaching on lower-specification grades while ultra-high-purity segments defend irreplaceable positions. Understanding these pressure gradients guides compounder R&D allocation and seal fabricator portfolio prioritization.
Product Type:
Substitution pressure intensifies downward through the product hierarchy, with filled grades facing PEEK displacement in static sealing while virgin and specialty formulations maintain defensive moats through contamination control mandates.
- Virgin FFKM:Fully fluorinated polymer with zero fillers or additives, achieving metallic ion extraction below single-digit ppb thresholds. Semiconductor wafer processing in Dresden and Leuven clusters demands this grade for sub-3nm node equipment where any contamination risks catastrophic yield loss. EPA NESHAP compliance timelines in Texas chemical processing are accelerating specification rates at emissions-critical valve points.
- Specialty FFKM:Perfluorinated ether-modified backbones engineered for simultaneous low-temperature flexibility and sour gas resistance. North Sea extended-reach drilling operations and California aerospace test facilities qualify these grades for thermal oxidative stability beyond 325°C where standard copolymers undergo chain scission.
- Filled FFKM:Carbon or mineral filler incorporation enhances compressive set resistance for chemical processing valve sealing.
- Coated FFKM:Surface-modified variants for specialized friction reduction in dynamic sealing applications.
Virgin FFKM anchors the volume base while specialty FFKM gains share at the steepest rate.
Application:
Margin structures diverge sharply across application verticals, with semiconductor and pharmaceutical commanding 40-60% premiums over chemical processing due to certification burdens and batch consistency requirements.
- Semiconductor:Wafer processing equipment sealing at sub-ppb contamination thresholds. Applied Materials and Lam Research mandate approved vendor lists with pre-qualified compounders, channeling procurement through consolidated OEM specifications in Hsinchu and Yongin clusters.
- Chemical Processing:Aggressive acid, base, and solvent exposure in reactor and valve sealing. REACH authorization dossiers for perfluorinated substances extend compounder registration cycles to 18-24 months, freezing formulation innovation for European processors.
- Aerospace:Propulsion system sealing requiring sustained thermal oxidative stability.
- Pharmaceutical:Isolator and reactor sealing for batch consistency in precision manufacturing.
Chemical processing provides the installed base volume while semiconductor applications deliver the steepest margin expansion trajectory.
End User:
Procurement autonomy is concentrating upward through the customer hierarchy, with OEMs capturing specification authority previously held by distributor networks and maintenance teams.
- OEMs:Original equipment manufacturers in semiconductor capital equipment now control material selection through pre-qualified supplier lists. This channel compression eliminates substitution autonomy for foundry maintenance teams in Taiwan and South Korea.
- Manufacturers:Precision chemical and pharmaceutical producers in Ludwigshafen and Leverkusen standardize on semiconductor-grade FFKM for batch consistency.
- Service Providers:Aftermarket seal fabrication and replacement services.
- Research Institutions:Experimental formulation development and qualification testing.
Manufacturers anchor current demand volumes while OEMs capture specification authority at the fastest clip.
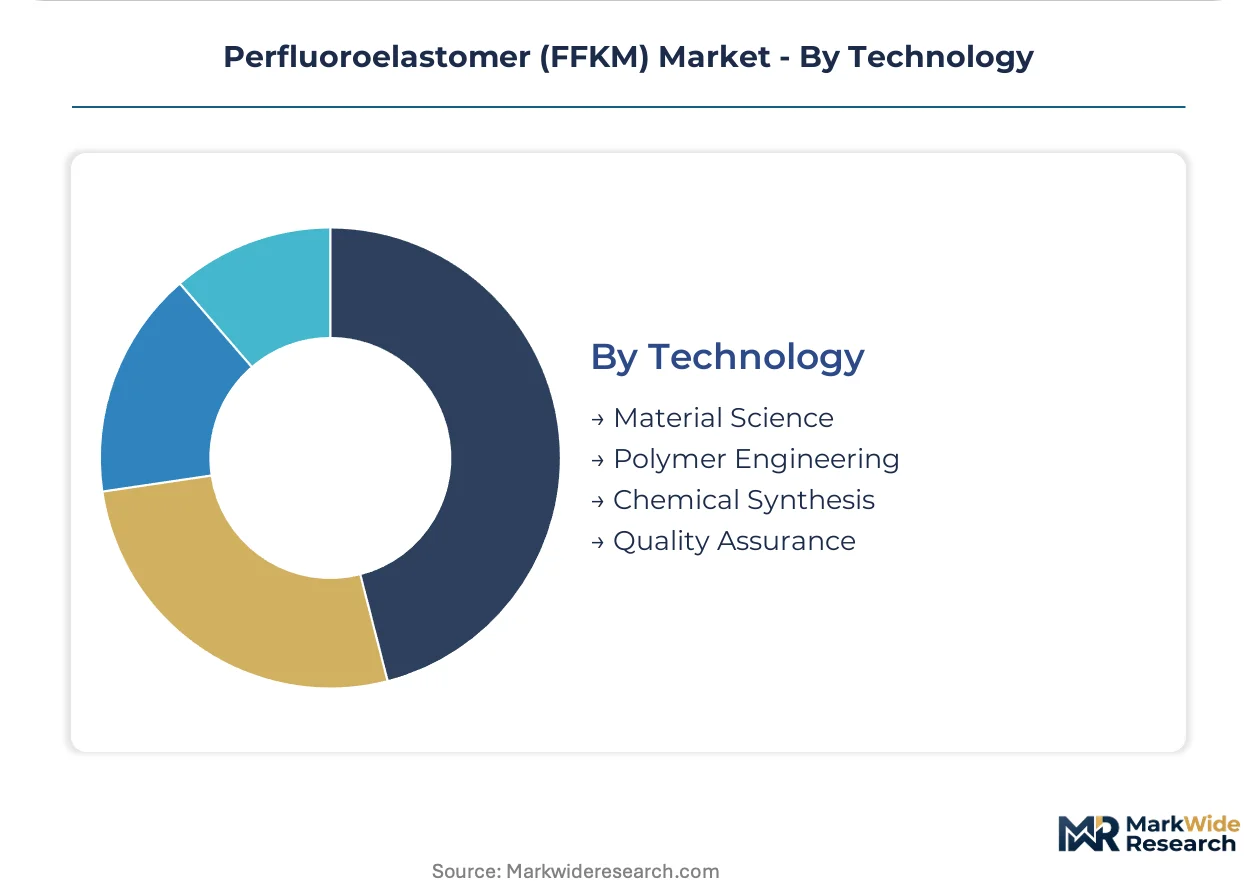
Technology:
Supply-side capability scarcity clusters around integrated polymer engineering and quality assurance functions, fragmenting competitive positioning between compounders with captive synthesis and fabricators dependent on merchant resin.
- Polymer Engineering:Molecular architecture design for perfluorinated ether backbone modifications and cure chemistry optimization. DuPont maintains leadership through proprietary platforms tuned for plasma etch environments.
- Quality Assurance:Metallic ion and volatile oligomer extraction verification with third-party documentation. German and Belgian processors now demand full pedigree data before contract execution.
- Material Science:Fundamental fluoropolymer structure-property relationships.
- Chemical Synthesis:Tetrafluoroethylene monomer polymerization and compounding operations.
Quality assurance anchors customer retention while polymer engineering drives the steepest capability differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in fluoropolymer feedstocks are reshaping regional FFKM manufacturing footprints. Countries with captive tetrafluoroethylene production command supply security advantages, while import-dependent fabricators face feedstock cost volatility.
United States
EPA NESHAP hazardous air pollutant standards are compelling Texas and Louisiana chemical processors to replace legacy elastomers at emissions-critical valve points. The EPA's enforcement timelines are compressing procurement cycles for compliant sealing solutions. Houston's petrochemical corridor is standardizing on virgin FFKM grades to maintain operating permits under intensifying regulatory scrutiny.
Germany
ECHA's REACH authorization requirements for perfluorinated substances are extending compounder registration cycles to 18-24 months. The EU F-Gas Regulation amendments are forcing seal fabricators to document low-GWP precursor alternatives. Ludwigshafen and Leverkusen pharmaceutical manufacturing clusters now demand semiconductor-grade FFKM for batch consistency in isolator and reactor sealing applications.
China
Domestic tetrafluoroethylene monomer supply concentration among state-backed chemical conglomerates is insulating Chinese fabricators from import dependency. The country's dual carbon goals are tightening emissions standards for chemical process equipment. Yangtze River Delta semiconductor fabrication facilities are accelerating FFKM specification rates for sub-3nm node transitions requiring metallic ion extraction below single-digit ppb thresholds.
Japan
METI industrial policy is prioritizing domestic supply chain resilience for critical semiconductor materials. Japanese chemical conglomerates control substantial fluoropolymer precursor production capacity, creating feedstock security for domestic compounders. Kyushu and Tohoku semiconductor manufacturing clusters are consolidating procurement through equipment OEM approved vendor lists, channeling demand toward pre-qualified FFKM suppliers.
South Korea
MFDS pharmaceutical manufacturing standards are elevating sealing material purity requirements for domestic drug production facilities. The Yongin semiconductor cluster is experiencing channel compression as Applied Materials and Lam Research mandate pre-qualified compounder relationships. Korean foundry maintenance teams are losing material substitution autonomy as OEM specification authority concentrates procurement decisions.
Perfluoroelastomer (FFKM) Market Vendor Landscape
Listed leaders compete with private specialists across technology and geographic dimensions. The vendor base organizes into three tiers: integrated chemical conglomerates with captive monomer supply, independent compounders with proprietary cure chemistry platforms, and regional seal fabricators dependent on merchant resin. Strategic moves concentrate on backward integration into fluoropolymer precursor production and quality certification investments for semiconductor-grade purity documentation.
Within the integrated chemical tier, Daikin and Solvay exemplify archetypes combining monomer production with downstream compounding capabilities. DuPont occupies a position representing proprietary cure chemistry specialization for plasma etch environments. Precision Polymer Engineering and Greene Tweed sit within the independent fabricator segment, with the former anchoring European aftermarket service channels and the latter exemplifying custom-compounded formulations for aerospace thermal oxidative stability requirements.
| Leading Market Players |
|---|
| Daikin |
| Trelleborg |
| DuPont |
| Precision Polymer Engineering |
| Greene Tweed |
| 3M |
| Asahi Glass |
| Parker Hannifin |
| Solvay |
| Others |
Supply Flow & Price Mechanics
PEEK and PFA thermoplastic substitution in static sealing below 200°C simultaneously redraws supply geography toward injection-molding hubs and compresses pricing economics for filled FFKM grades. This displacement dynamic concentrates procurement power among equipment OEMs while fragmenting residual demand across specialty compounders.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on semiconductor-grade certification and volume scale, with virgin resin batches commanding substantial premiums over filled formulations. Cost compression in economy tiers is intensifying because PEEK seals capture static applications without metallic ion constraints. Chemical processors in Texas and Louisiana exhibit highest price sensitivity due to NESHAP compliance deadlines, while semiconductor OEMs in Hsinchu and Yongin prioritize contamination thresholds over unit economics.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for European fabricators dependent on Japanese and Chinese tetrafluoroethylene monomer. Supply concentrates in Japan, China, and Germany, with raw material dependencies on fluoropolymer precursors, cure chemistry additives, and precision machining equipment. Single-source vulnerability in tetrafluoroethylene monomer creates structural exposure to feedstock disruption. Distribution runs through consolidated equipment OEM approved vendor lists, displacing regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as OEM procurement consolidation creates underserved aftermarket niches. Precision chemical manufacturers in Ludwigshafen and Leverkusen demand batch-consistent sealing solutions outside pre-qualified supplier lists.
For Market Incumbents: Shield semiconductor-grade positioning through captive virgin resin sourcing and full pedigree documentation. Backward integration into fluoropolymer precursor production secures feedstock against Japanese and Chinese supply concentration. Invest in plasma etch chemistry certification to extend OEM validation moats. For New Entrants and Emerging Players: Aftermarket rapid-turn fabrication services represent the most penetrable white-space where Precision Polymer Engineering's European dominance leaves regional gaps. Target pharmaceutical isolator sealing in German manufacturing clusters with third-party verified extraction data as entry credential. Pursue service-based differentiation over compounder scale. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors independent fabricators with proprietary cure chemistry platforms. Long-term viability hinges on regulatory dossier completeness under REACH authorization timelines. Monitor ECHA perfluorinated substance evaluation progress as inflection indicator for compounder valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Production | Captive tetrafluoroethylene supply insulates Japanese and Chinese fabricators from import dependency. |
| Semiconductor-Grade Certification Investment | Full material lifecycle documentation satisfies Applied Materials and Lam Research vendor mandates. |
| Perfluorinated Ether Backbone R&D | Molecular architecture modifications extend thermal oxidative stability beyond 325°C for aerospace applications. |
| European Aftermarket Service Expansion | Rapid-turn seal fabrication capabilities capture pharmaceutical maintenance demand in Ludwigshafen clusters. |
| Low-GWP Precursor Alternative Documentation | EU F-Gas Regulation amendment preparation positions fabricators for preferred supplier status. |
Methodological Framework
Desk research of fluoropolymer trade data, ECHA registration dossiers, and semiconductor equipment OEM procurement disclosures preceded structured interviews with FFKM compounder technical directors, seal fabricator plant managers, chemical processor procurement leads, and aerospace propulsion system engineers. Secondary validation drew from SEC filings of listed chemical conglomerates, customs import records, and EPA NESHAP compliance documentation. Bottom-up volume estimates triangulated against top-down industry value assessments.
Variance decomposition across product grade, application vertical, end-user procurement channel, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Modeled inputs included semiconductor node transition timelines, REACH authorization cycle durations, and oilfield sour gas resistance specification rates.
Forecasts assume regulatory continuity in EPA NESHAP enforcement and EU F-Gas Regulation amendment schedules; material policy shifts would require re-modeling. Forecasts reflect assumptions on tetrafluoroethylene monomer supply stability and plasma etch chemistry certification timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Butyl Elastomers Market
Elastomeric Membrane
EPDM Waterproofing Membrane Market
Elastomeric Membrane
Global Acrylic Elastomers Market
Elastomeric Membrane
Elastomer Coated Fabric Market
Elastomeric Membrane
Rubber Membrane Market
Elastomeric Membrane
UV Stabilized Thermoplastic Elastomer Market
Elastomeric Membrane
Polydimethylsiloxane (PDMS) Market
Elastomeric Membrane
Global Fluoroelastomers Market
Elastomeric Membrane
South America Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Polyolefin Elastomer Market
Elastomeric Membrane
Industrial PU Elastomer Market
Elastomeric Membrane
Hot Cast Elastomers Market
Elastomeric Membrane
Elastic Laminates Market
Elastomeric Membrane
North America Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Thermo Elastic Acrylic Market
Elastomeric Membrane
Polyisoprene Elastomers Market