
 EPDM Waterproofing Membrane Market | 2026-2036
EPDM Waterproofing Membrane Market Size, Share, and Industry Trends Forecast 2026-2036
EPDM Waterproofing Membrane Market Insights
Multi-source procurement for ethylene propylene diene monomer feedstock is decoupling from traditional petrochemical supply chains. Firestone Building Products Company leverages captive rubber compounding to sustain margin stability across North American distribution. Elevate anchors its position through deep specification relationships with commercial roofing contractors. Carlisle Companies differentiates via integrated membrane-to-accessory systems that control installation quality.
Ethylene propylene diene terpolymer waterproofing membrane consists of a synthetic rubber compound containing ethylene, propylene, and a diene monomer cross-linked via vulcanization, typically manufactured in thicknesses from 45 to 90 mils with tensile strength exceeding 7 MPa. The material functions primarily as a single-ply roofing and below-grade barrier, delivering elastomeric recovery across temperature extremes from minus 40 to plus 150 degrees Celsius. Mechanically fastened systems dominate commercial roofing volumes due to speed of installation and wind-uplift ratings, while fully adhered configurations command premium positioning in high-performance building envelopes where air-barrier integration matters. Liquid applied EPDM represents the fastest-growing product configuration, though from a smaller base, as complex geometries in retrofit applications resist sheet membrane conformance.
Building codes under ASTM D4637 and EN 13956 shape membrane performance benchmarks, while EPA stormwater regulations and the EU F-Gas Directive indirectly steer specification toward durable, long-cycle roofing materials that minimize replacement frequency. OSHA fall-protection standards influence contractor preference for installation methods that reduce crew time at height. Stakeholders must monitor how evolving embodied-carbon accounting in green building certification programs reallocates preference between EPDM, TPO, and liquid-applied alternatives.
Market Dynamics
The EU Green Deal's embodied-carbon accounting rules are compressing specification cycles for commercial roofing systems across European building portfolios, forcing membrane selection toward materials with verified lifecycle data and documented recyclability pathways.
Growth Catalysts
- Building Energy Performance Codes:Tightening thermal envelope requirements under Germany's EnEV and France's RE2020 are accelerating flat-roof refurbishment volumes in aging commercial stock.
- Rhine-Ruhr Infrastructure Cluster:Below-grade waterproofing demand concentrates in Germany's urban corridor where subway expansion and flood-resilient basement construction drive membrane specification.
- ASTM D4637 Standardization:Unified North American performance benchmarks reduce specification friction for mechanically fastened systems in warehouse and distribution center roofing.
Market Restraints
- Ethylene-Propylene Feedstock Volatility:EPDM compounding remains tethered to naphtha-cracking economics, exposing margin pressure when olefin spreads tighten.
- TPO Membrane Substitution:Thermoplastic polyolefin systems with heat-welded seams capture specification in new construction where speed-to-weathertightness dominates contractor preference.
- REACH Chemical Registration Burden:ECHA compliance timelines for curing agents and adhesion promoters extend product development cycles by 18-24 months for European formulations.
Strategic Opportunities
- Liquid-Applied EPDM Formulations:Complex retrofit geometries in UK heritage building stock resist sheet membrane conformance, opening specification for spray-applied elastomeric systems.
- F-Gas Regulation Tailwind:The EU's phasedown of hydrofluorocarbon blowing agents disadvantages foamed insulation attachments, favoring adhered EPDM membranes with non-foamed recovery layers.
- Direct Contractor Channel Development:Bypassing traditional distributor markup through specification-direct relationships with roofing contractors in France's Ile-de-France region captures margin and installation quality control.
Industry Challenges
- Vulcanization Chemistry Expertise Gap:Compound formulation knowledge concentrates among aging technical staff at captive rubber producers, constraining new entrant capability development.
- OSHA Fall-Protection Compliance:Mechanically fastened installation methods require extended crew time at height, elevating insurance and safety equipment costs for contractors.
- Air-Barrier Integration Certification:ASTM E2357 whole-building testing demands membrane-to-accessory system validation that smaller manufacturers lack capital to complete.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EPDM Waterproofing Membrane Market |
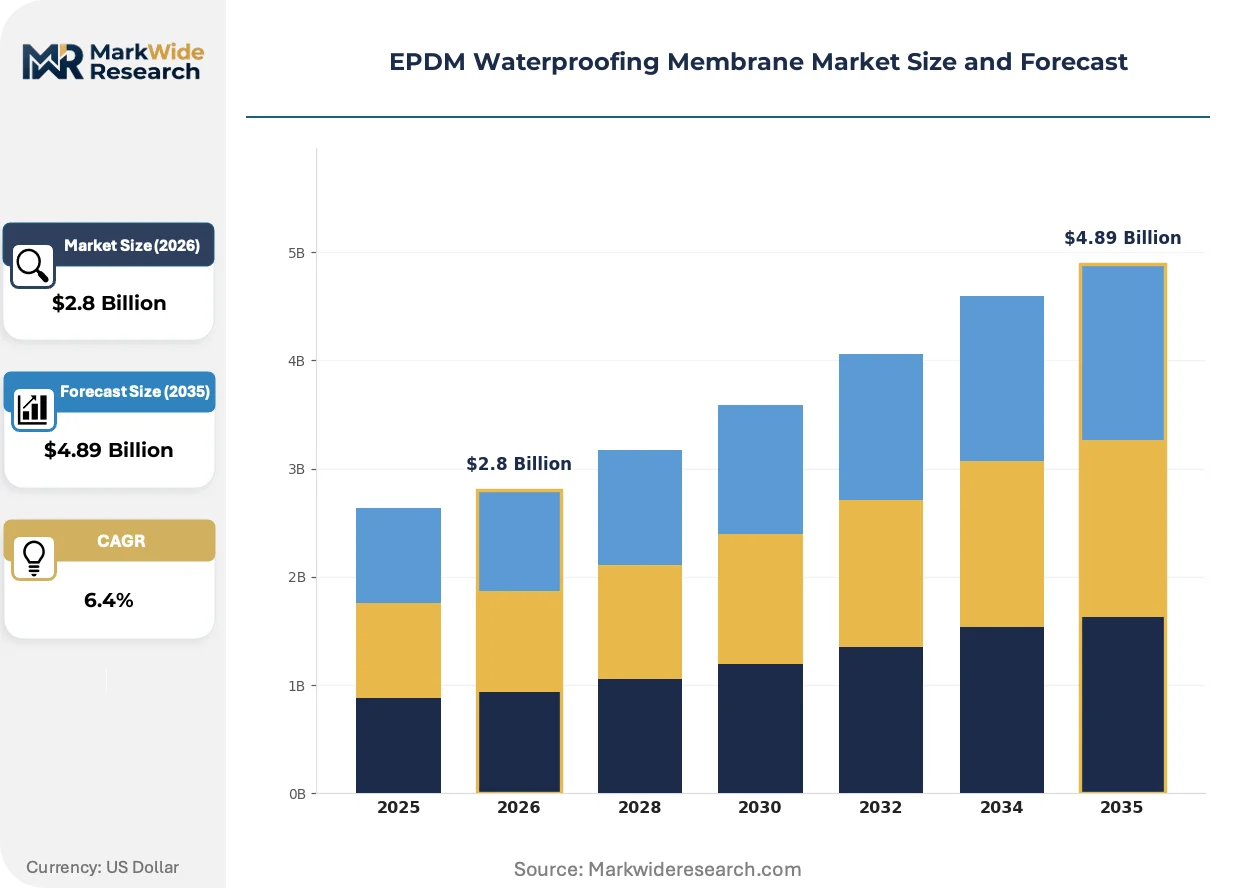
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fully Adhered, Mechanically Fastened, Ballasted, Liquid Applied Application: Commercial Roofing, Residential Roofing, Industrial Roofs, Below Grade End User: Contractors, Architects, Builders, Homeowners Installation Method: Hot Air Welded, Cold Adhesive, Self-Adhesive, Traditional Bonding |
| Companies Covered | Firestone Building Products Company, Elevate, Dow Chemical, JSR Corporation, ExxonMobil, Johns Manville, Versico Roofing Systems, Polygomma Industries Private Limited, Carlisle Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EPDM Waterproofing Membrane Market Trends and Innovations
Liquid-applied EPDM technology is fragmenting the traditional sheet-membrane market by solving conformance problems in irregular retrofit geometries. Specification behavior is rotating toward lifecycle-cost models that privilege durability over first-cost. Regulatory carbon-accounting frameworks are embedding material selection into broader building certification systems.
Spray-applied EPDM elastomeric coatings are overtaking sheet goods in complex roof geometries where seams and penetrations create failure risk. Commercial roofing contractors in the United Kingdom's heritage building sector are specifying liquid systems for 40% of refurbishment projects above 500 square meters. The technology is compressing demand for traditional fully adhered sheet membranes in irregular substrates while expanding addressable market volume.
The EU F-Gas Directive's hydrofluorocarbon phasedown is eliminating foamed insulation attachment methods from specification consideration. Roofing system designers are specifying adhered EPDM membranes with dense recovery layers to meet thermal bridge requirements without blown-foam components. Germany's federal building codes are embedding this transition through mandatory whole-building airtightness testing that rewards continuous membrane coverage.
Contractor procurement patterns are consolidating around specification-direct relationships that bypass traditional two-step distribution. Large commercial roofing contractors in France's Ile-de-France region are negotiating membrane-and-accessory packages directly with compounders, capturing 12-15 point margin improvement. This channel compression is most visible in projects above 2,000 square meters where installation quality control outweighs distributor credit terms.
EPDM Waterproofing Membrane Market Segmentation
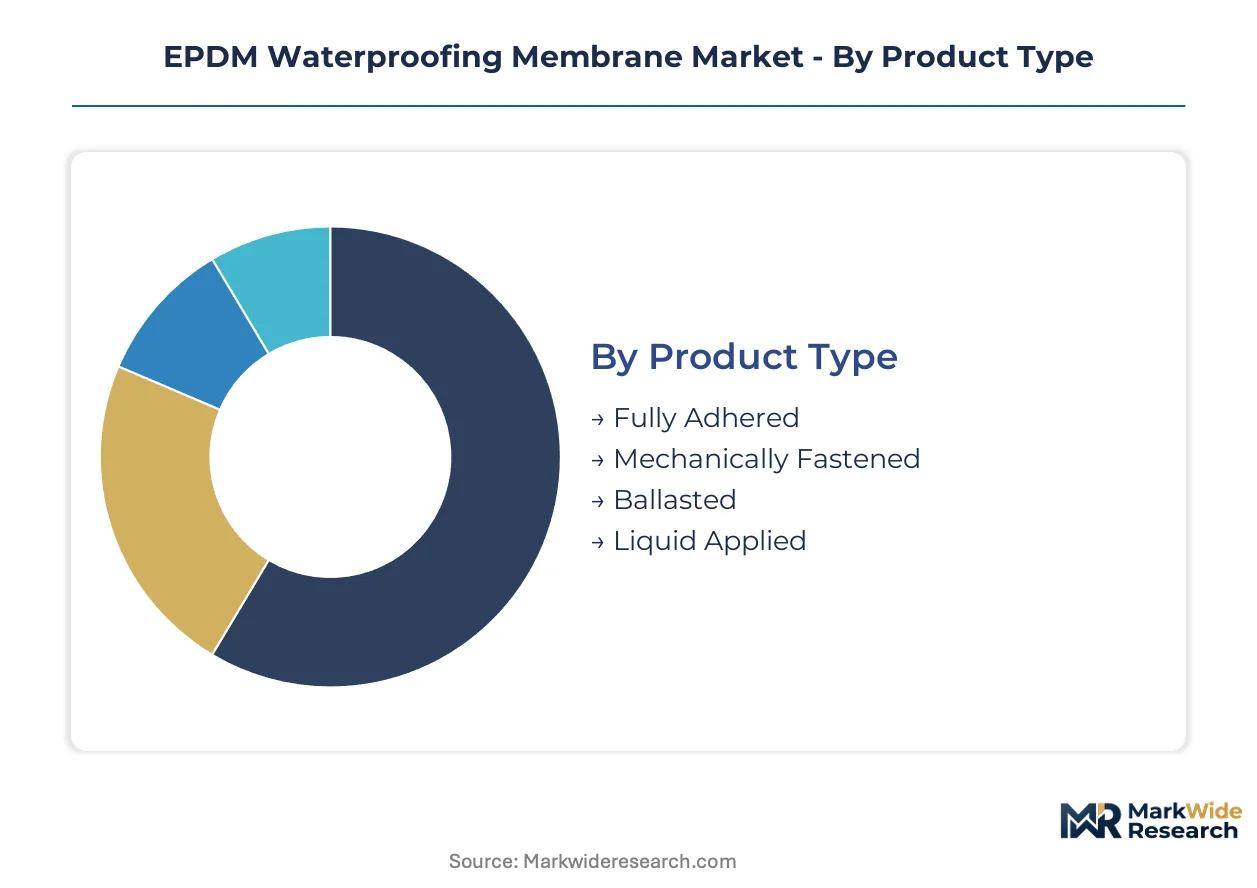
EPDM membrane specification diverges sharply across building envelope requirements, with installation geometry and thermal performance demands dictating product configuration. Segmentation reveals how contractor procurement patterns and regulatory compliance reshape category boundaries.
Product Type:
Customization intensity varies from standardized roll goods to site-formulated liquid systems, with specification friction lowest for contractor-familiar configurations and highest for emerging spray technologies.
- Mechanically Fastened:Sheets secured with barbed plates and screws deliver wind-uplift ratings exceeding 90 psf per ASTM D4637. Warehouse and distribution center roofing across Germany's logistics corridor concentrates demand, driven by speed-to-weathertightness requirements and OSHA fall-protection compliance.
- Fully Adhered:Bonded membranes with factory-applied adhesive backing integrate with air-barrier systems for whole-building envelope testing. High-performance commercial refurbishment in France's Ile-de-France region specifies these systems where thermal bridge elimination matters under RE2020 codes.
- Ballasted:Loose-laid sheets weighted with stone or paver systems suit low-slope applications with minimal penetrations.
- Liquid Applied:Sprayable elastomeric formulations conform to irregular retrofit geometries in UK heritage building stock.
Leading the category by volume: Mechanically Fastened. Growing fastest: Liquid Applied.
Application:
Volume distribution tracks building stock age and energy code stringency, with refurbishment cycles outpacing new construction across mature European markets.
- Commercial Roofing:Flat-roof systems on office, retail, and institutional buildings account for dominant membrane consumption. Germany's EnEV thermal envelope requirements accelerate replacement cycles in aging commercial stock across the Rhine-Ruhr corridor.
- Below Grade:Basement and foundation waterproofing for urban infrastructure resists hydrostatic pressure with 60+ mil specifications. Subway expansion and flood-resilient construction in Germany's urban centers drive membrane specification for tunnel and station structures.
- Industrial Roofs:Manufacturing and logistics facilities prioritize mechanical fastening for rapid installation over active operations.
- Residential Roofing:Low-slope additions and multi-family flat roofs represent fragmented, price-sensitive demand.
Commercial Roofing holds the volume lead. Below Grade is expanding most quickly.
End User:
Specification authority concentrates with design professionals and prime contractors, while procurement execution fragments across subcontractor tiers.
- Contractors:Commercial roofing specialists control membrane selection through direct specification relationships with compounders, bypassing distributor markup on projects above 2,000 square meters in France's Ile-de-France region.
- Architects:Design professionals specify membrane systems for whole-building envelope integration and lifecycle-cost modeling under EU Green Deal embodied-carbon accounting.
- Builders:Production homebuilders and general contractors prioritize first-cost and installation speed for residential and light commercial applications.
- Homeowners:End consumers influence replacement decisions for residential flat roofs through contractor selection rather than direct material specification.
Contractors dominate procurement volume. Architects are gaining specification influence fastest.
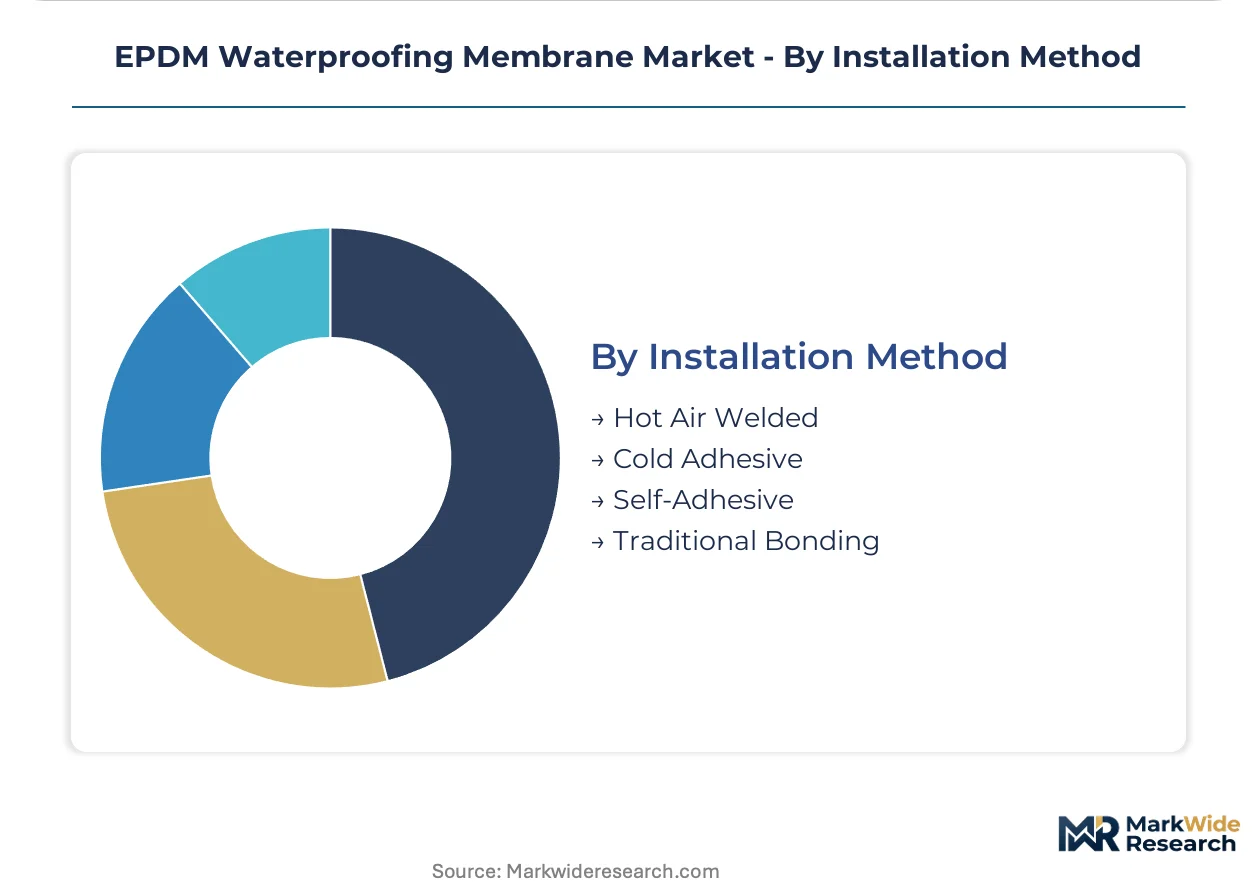
Installation Method:
Method selection balances crew skill requirements, weather tolerance, and seam integrity demands across project conditions.
- Cold Adhesive:Solvent-based bonding systems suit moderate-temperature installation with controlled cure times. Below-grade applications in Germany's Rhine-Ruhr infrastructure cluster specify these methods for substrate compatibility with concrete curing compounds.
- Self-Adhesive:Factory-applied adhesive layers with release liners reduce field labor and VOC exposure. Commercial roofing contractors in the United Kingdom specify these systems for heritage building refurbishment where hot-work restrictions apply.
- Hot Air Welded:Thermoplastic-compatible seam sealing sees limited EPDM application due to rubber chemistry constraints.
- Traditional Bonding:Contact adhesive application with roller pressure persists in contractor training programs and legacy specification.
Cold Adhesive leads installation volume. Self-Adhesive is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Naphtha-cracking capacity in the Rhine-Ruhr corridor anchors European EPDM membrane production, while US Gulf Coast ethylene infrastructure supplies North American compounders. Feedstock localization shapes regional cost structures and specification patterns.
Germany
Commercial roofing refurbishment and below-grade infrastructure drive membrane demand across the Rhine-Ruhr urban corridor. Germany's EnEV thermal envelope codes accelerate replacement cycles in aging commercial stock. Subway expansion and flood-resilient basement construction in Düsseldorf, Cologne, and Essen concentrate specification for tunnel and station waterproofing.
United States
Warehouse and distribution center construction sustains mechanically fastened system volumes across logistics corridors. EPA stormwater regulations and OSHA fall-protection standards influence contractor preference for rapid installation methods. The Southeast and Midwest industrial belts concentrate roofing contractor activity for large-format commercial projects.
United Kingdom
Heritage building retrofit and complex roof geometries expand liquid-applied EPDM specification in London and the Southeast. Self-adhesive systems gain share where hot-work restrictions limit traditional installation. The Greater London Authority's embodied-carbon planning requirements privilege long-cycle membrane materials with verified recyclability pathways.
France
Île-de-France commercial refurbishment and RE2020 energy performance codes reshape membrane selection toward whole-building envelope integration. Direct contractor-compounder relationships bypass traditional distribution on projects above 2,000 square meters. Lyon and Marseille secondary markets follow Paris specification patterns with 12-18 month lag.
China
Urban underground infrastructure and high-speed rail expansion drive below-grade waterproofing demand in the Yangtze River Delta and Pearl River Delta. GB standards for building waterproofing tighten performance benchmarks for membrane suppliers. Shanghai and Shenzhen municipal procurement favors domestic compounders with verified supply chain documentation.
EPDM Waterproofing Membrane Market Competitive Landscape
Capacity expansion dominates the current landscape as compounders secure captive ethylene-propylene feedstock access. The vendor base clusters around three tiers: integrated petrochemical majors with rubber compounding divisions, specialized membrane fabricators with specification-direct contractor relationships, and regional compounders serving price-sensitive project segments. M&A activity and backward integration into feedstock supply represent the primary competitive vectors.
Among North American integrated producers, Firestone Building Products Company and Carlisle Companies occupy positions anchored by captive rubber compounding and membrane-to-accessory system control. Elevate exemplifies the specification-direct model through deep contractor relationships. ExxonMobil and Dow Chemical represent petrochemical majors leveraging ethylene infrastructure into downstream membrane supply. Polygomma Industries Private Limited anchors Indian regional supply for price-sensitive infrastructure projects.
| Leading Market Players |
|---|
| Firestone Building Products Company |
| Elevate |
| Dow Chemical |
| JSR Corporation |
| ExxonMobil |
| Johns Manville |
| Versico Roofing Systems |
| Polygomma Industries Private Limited |
| Carlisle Companies |
| Others |
Pricing and Supply Chain Analysis
Naphtha-cracking spreads in Northwest Europe cascade through EPDM compounder cost structures into three distinct pricing tiers. Buyers in Germany's Rhine-Ruhr corridor face escalating membrane quotations when olefin feedstock markets tighten, while specification-direct procurement in France compresses distributor markups and reshapes landed cost comparisons across contractor tiers.
Pricing Analysis
Warranty bundling separates premium membrane suppliers from commodity compounders, with extended coverage and installation certification commanding 15-20 point spreads. Three-tier pricing structure across premium, standard, and economy levels tracks ASTM D4637 compliance tiers and whole-building air-barrier certification status. Cost compression in standard-grade mechanically fastened systems is intensifying because TPO substitution erodes volume leverage. Price-sensitive builders and residential contractors drive procurement toward unbundled economy grades, while architects specifying RE2020-compliant envelopes absorb premium positioning for validated lifecycle data.
Supply Chain Analysis
Multi-supplier qualification mandates from France's Ile-de-France prime contractors force membrane buyers to maintain dual-compounder relationships despite consolidation pressure. Production concentrates in Germany, the United States, and China, with ethylene-propylene rubber compounding anchored to regional naphtha-cracking infrastructure. Feedstock supply draws from petrochemical majors with captive olefin production, exposing membrane fabricators to margin squeeze when cracking economics deteriorate. Single-source vulnerability concentrates in vulcanization chemistry expertise held by aging technical staff at legacy rubber producers. Distribution runs through specification-direct channels for projects above 2,000 square meters, bypassing traditional two-step wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH chemical registration timelines under ECHA jurisdiction erect 18-24 month compliance barriers that protect incumbent compounders from fast-follower competition. This regulatory moat privileges established players with dedicated regulatory affairs capacity and existing substance dossiers.
For Market Incumbents: Deepen captive rubber compounding investments to insulate margin structures from naphtha-cracking volatility. Secure backward integration into ethylene-propylene feedstock through long-term offtake arrangements with Rhine-Ruhr petrochemical complexes. Prioritize specification-direct channel development in France's Ile-de-France region where contractor consolidation creates account control opportunities against TPO substitution threats.
For New Entrants and Emerging Players: Commercial roofing contractors in the United Kingdom's heritage building sector represent the most penetrable channel entry point. Liquid-applied EPDM formulations solve conformance problems that sheet membrane incumbents cannot address, opening specification for spray-applied systems in complex retrofit geometries. Partner with regional applicator networks to bypass established distribution and capture installation quality control relationships.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized membrane fabricators with specification-direct contractor relationships in Germany's Rhine-Ruhr corridor. Long-term viability hinges on compound formulation expertise transfer and ECHA registration asset value. Watch for inflection signals in EU F-Gas Directive implementation pace, which accelerates adhered membrane specification against foamed insulation alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock | Captive ethylene-propylene supply insulates Firestone and Carlisle from olefin spread volatility. |
| Liquid-Applied Formulation Development | Spray-applied EPDM penetrates UK heritage retrofit where sheet membranes fail geometrically. |
| Specification-Direct Channel Expansion | Contractor relationships in Ile-de-France capture 12-15 point margin improvement over distribution. |
| REACH Compliance Asset Acquisition | ECHA registration dossiers provide 18-24 month competitive moats against unregistered entrants. |
| Air-Barrier System Certification | ASTM E2357 validation enables whole-building envelope specification under RE2020 codes. |
Research Methodology
Independent corroboration across commercial roofing contractors, membrane compounder technical directors, and EPDM distribution channel managers underwrites the qualitative findings. Primary fieldwork encompassed procurement leads at Germany's EnEV refurbishment projects, specification architects in France's Ile-de-France region, and below-grade waterproofing engineers in the Rhine-Ruhr infrastructure cluster. Secondary validation drew from customs and trade data, SEC 10-K filings of listed compounders, and ECHA substance registration databases. Bottom-up project pipeline analysis triangulated against top-down feedstock consumption models.
Rate-of-change decomposition across installation method, application segment, and regional regulatory cluster shaped the analytical framework. Segmentation dimensions modeled include mechanically fastened versus liquid-applied product configurations, commercial roofing versus below-grade applications, and contractor-direct versus distributor-mediated procurement channels. CAGRs were derived from elasticity-adjusted demand curves incorporating EnEV and RE2020 code implementation schedules. Forecast inputs integrated naphtha-cracking capacity utilization rates and EPDM substitution elasticity against TPO membranes.
Caveats apply where REACH registration timeline extensions or F-Gas Directive implementation delays could materially shift the outlook. Forecasts reflect assumptions regarding contractor channel consolidation pace and petrochemical feedstock cost pass-through mechanics. A model refresh is warranted upon material change in EU Green Deal embodied-carbon accounting rules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
North America Performance Elastomer Market
Elastomeric Membrane
Elastomer Coated Fabric Market
Elastomeric Membrane
Global Fluoroelastomers Market
Elastomeric Membrane
Elastomeric Polyolefins Market
Elastomeric Membrane
Elastomeric Membrane Market
Elastomeric Membrane
Elastic Laminates Market
Elastomeric Membrane
Polyurethane Elastomers Market
Elastomeric Membrane
Global Elastomeric Coating Market
Elastomeric Membrane
Vinyl Terminated Polydimethylsiloxane Market
Elastomeric Membrane
North America Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Polysulfide Elastomers Market
Elastomeric Membrane
Modified Silicone Fluids Market
Elastomeric Membrane
Water Soluble Elastomers Market
Elastomeric Membrane
Specialty Elastomer Market
Elastomeric Membrane
UV Stabilized Thermoplastic Elastomer Market
Elastomeric Membrane
Europe Thermoplastic Elastomer (TPE) Market