
 Global Acrylic Elastomers Market | 2026-2036
Global Acrylic Elastomers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Acrylic Elastomers Market Foresight
Specialty chemical distribution is fragmenting as regional distributors lose ground to direct procurement relationships between compounders and resin producers. Zeon Corporation leverages its captive acrylic acid supply to anchor premium polyacrylate grades across Japanese automotive supply chains. BASF SE competes through backward integration into emulsion polymerization, while Arkema S.A. differentiates via specialty copolymer architectures for high-temperature sealant applications.
Acrylic elastomers are synthetic rubber materials synthesized from acrylic acid esters, typically containing ethyl acrylate or butyl acrylate repeat units with chlorine-containing crosslinking sites, delivering continuous service temperatures from minus 15 degrees Celsius to 175 degrees Celsius with exceptional resistance to ozone, weathering, and transmission fluids. Polyacrylate formulations dominate volume flows into automotive underhood sealing, where thermal aging resistance commands premium positioning over styrene-acrylic alternatives. Emulsion forms capture the majority of adhesives and paints demand, while bulk and powder grades serve molded automotive components where compression set requirements are most stringent.
EPA fuel permeation standards and EU REACH chemical registration protocols are tightening specifications for elastomeric seals in fuel delivery systems, forcing reformulation toward lower-swell acrylic grades. Japan's METI maintains JIS K 6250 testing protocols that govern automotive elastomer qualification, creating a technical barrier for non-domestic suppliers. Stakeholders must monitor how dual carbon goals in China and South Korea reshape acrylic acid feedstock economics and, consequently, elastomer cost structures.
Market Dynamics
Automotive thermal management specifications are compressing formulation cycles as OEMs simultaneously chase electrification heat loads and ICE efficiency gains. The tension between legacy fuel system sealing and battery pack gasketing forces compounders to dual-track R&D pipelines.
Growth Catalysts
- EPA fuel permeation standards:Mandates for sub-15 gram per square meter per day permeation rates in fuel delivery systems force adoption of low-swell polyacrylate grades across North American vehicle platforms.
- Battery thermal interface materials:Electric vehicle manufacturers specify acrylic elastomer compression pads for cell-to-cell isolation, opening volume demand from Tesla, BYD, and Hyundai Motor Group assembly lines.
- East Asian feedstock clustering:Acrylic acid plant co-location with elastomer polymerization in South Korea's Ulsan and China's Ningbo chemical zones compresses monomer logistics costs.
Market Restraints
- Acrylic acid price volatility:Propylene feedstock exposure ties elastomer raw material costs to crude oil futures, squeezing compounder margins during energy price spikes.
- Fluorocarbon substitution in extreme heat:Viton and similar FKM grades retain advantage above 175 degrees Celsius, capping acrylic elastomer penetration in turbocharger sealing.
- Japan's JIS K 6250 qualification barriers:Domestic testing protocols extend automotive approval timelines for non-Japanese suppliers by 18-24 months.
Strategic Opportunities
- India's PLI scheme for auto components:Production-linked incentives for advanced automotive parts manufacturing attract elastomer compounders to Tamil Nadu and Gujarat industrial corridors.
- Copolymer architectures for hydrogen fuel cells:Peroxide-curable ACM grades with enhanced chemical resistance address sealing requirements in high-pressure hydrogen recirculation systems.
- Direct procurement platforms:Digital B2B marketplaces connecting resin producers with Tier-2 molders disintermediate traditional specialty chemical distributors in Southeast Asia.
Industry Challenges
- Peroxide cure system expertise gap:Shortage of polymer chemists familiar with non-sulfur crosslinking chemistry delays commercialization of next-generation heat-resistant grades.
- REACH SVHC documentation burdens:EU chemical substance registration requirements consume 12-18 months of compliance bandwidth for new formulation introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Acrylic Elastomers Market |
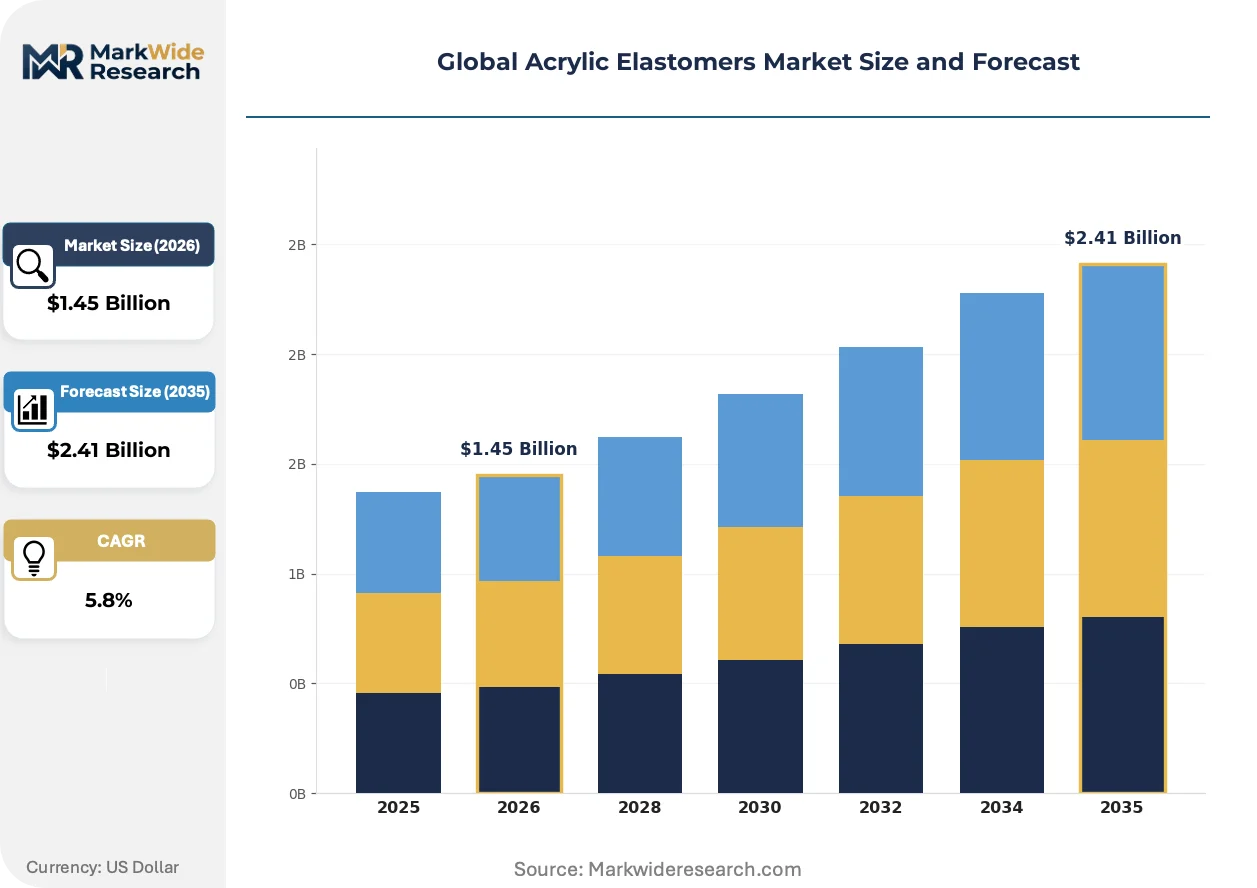
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $2.41 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylonitrile-Butadiene, Styrene-Acrylic, Polyacrylate, Methyl Methacrylate, Copolymer Application: Adhesives, Paints & Coatings, Textile Finishing, Automotive Components, Sealants End User Industry: Construction, Consumer Goods, Electronics Manufacturing, Packaging, Footwear Form: Latex, Powder, Solution, Emulsion, Bulk |
| Companies Covered | BASF SE, Zeon Corporation, Kuraray Co., Ltd., NOK Corporation, Dow Inc., Arkema S.A., Mitsubishi Chemical Corporation, DuPont de Nemours, Inc., Trelleborg AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Acrylic Elastomers Market Shifts & Advancements
Material science advances and regulatory chemistry restrictions are rewriting formulation priorities. Manufacturers now balance thermal performance against halogen-free mandates and circular economy feedstock requirements.
Peroxide-curable polyacrylate elastomers are migrating from niche aerospace applications toward mainstream automotive underhood sealing. BMW and Mercedes-Benz powertrain engineers specify these grades for charge air cooler hoses where sulfur-cure systems fail. The shift enables continuous service to 180 degrees Celsius while eliminating metal oxide residues that clog modern fuel injection systems.
EU REACH restrictions on short-chain chlorinated paraffins are forcing reformulation of chlorine-containing ACM grades used in transmission seals. Compounders in Germany and Belgium accelerate bio-based acrylic acid pilot programs to preempt broader SVHC listings. The regulatory pressure concentrates most acutely on molders serving Stellantis and Volkswagen Group transmission supply chains.
Compounders now consolidate purchase orders through vertically integrated resin producers rather than regional distributors. Korean automotive parts manufacturers lead this behavior shift, negotiating direct tonnage contracts with LG Chem and Kumho Petrochemical. The channel restructuring collapses distributor margins in Seoul and Busan trading hubs while rewarding producers with captive acrylic acid supply.
Global Acrylic Elastomers Market Segmentation
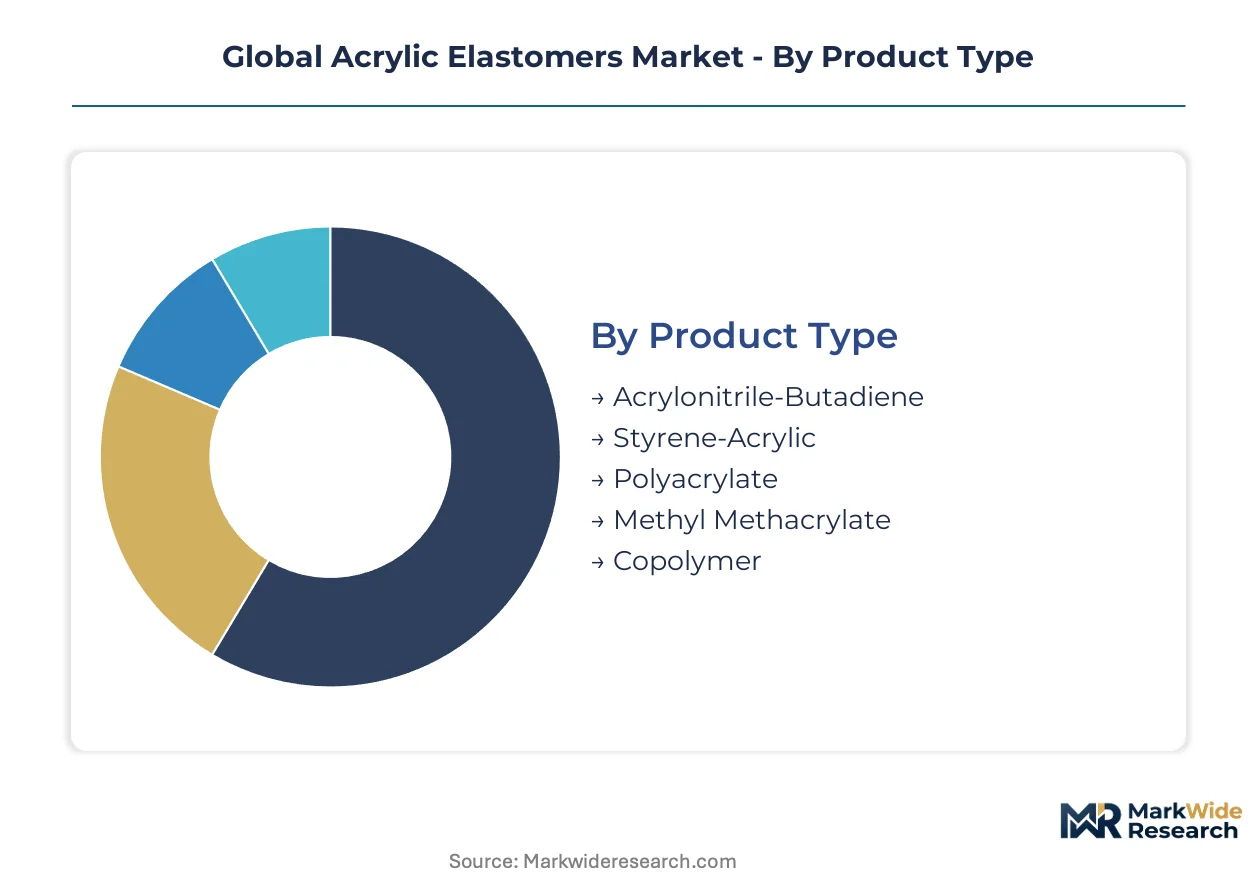
Segmentation in acrylic elastomers reveals how molecular architecture and physical form dictate channel economics. Manufacturers optimize polymerization routes and cure systems around specific performance thresholds demanded by automotive thermal management and construction weatherproofing.
Product Type:
Cost tier differentiation separates commodity volume grades from specialty heat-resistant formulations commanding formulation premiums.
- Polyacrylate:Ethyl acrylate and butyl acrylate repeat units with chlorine-containing crosslinking sites deliver continuous service from minus 15 degrees Celsius to 175 degrees Celsius. Automotive underhood sealing in Germany and Japan concentrates demand where EPA fuel permeation standards and JIS K 6250 protocols enforce thermal aging resistance over styrene-acrylic alternatives.
- Copolymer:Peroxide-curable ACM architectures enable service to 180 degrees Celsius while eliminating metal oxide residues. BMW and Mercedes-Benz powertrain engineers specify these grades for charge air cooler hoses where sulfur-cure systems fail, opening volume from European premium OEM assembly lines.
- Acrylonitrile-Butadiene:Nitrile rubber hybrids balance oil resistance against acrylic weathering performance.
- Styrene-Acrylic:Lower-cost emulsion grades serve construction adhesives and paint modifiers where thermal ceilings are modest.
- Methyl Methacrylate:Rigid backbone variants target optical clarity and UV stability in specialty coatings.
Polyacrylate holds installed capacity. Copolymer is rotating up the share rankings.
Application:
Application focus determines whether emulsion polymerization or bulk polymerization routes achieve margin targets.
- Automotive Components:Compression set requirements in molded seals and gaskets demand bulk and powder grades with stringent post-cure protocols. Tesla, BYD, and Hyundai Motor Group assembly lines specify acrylic elastomer compression pads for battery cell-to-cell isolation, creating dual demand from ICE thermal management and EV battery pack gasketing.
- Sealants:Low-swell polyacrylate grades address EPA sub-15 gram per square meter per day fuel permeation mandates across North American vehicle platforms. EU REACH restrictions on short-chain chlorinated paraffins force reformulation of chlorine-containing ACM grades in transmission seals serving Stellantis and Volkswagen Group supply chains.
- Adhesives:Emulsion forms dominate construction and packaging bonding where ambient cure speeds matter.
- Paints & Coatings:Latex and solution grades provide weatherability in exterior architectural finishes.
- Textile Finishing:Soft hand modifiers and durable press treatments in apparel manufacturing.
Automotive Components commands formulation R&D bandwidth. Sealants is gaining share fastest.
End User Industry:
Customer type concentration shapes technical service intensity and contract structuring across direct procurement relationships.
- Construction:Weatherproofing membranes and structural adhesives drive emulsion volume in coastal China and South Korea chemical manufacturing clusters. Acrylic acid plant co-location with elastomer polymerization in Ulsan and Ningbo compresses monomer logistics costs for compounders serving regional infrastructure buildout.
- Electronics Manufacturing:Thermal interface materials and gasketing for consumer devices require clean-room compatible powder grades. South Korean electronics parts manufacturers negotiate direct tonnage contracts with LG Chem and Kumho Petrochemical, bypassing regional distributors in Seoul and Busan trading hubs.
- Packaging:Pressure-sensitive adhesives and flexible film laminations.
- Consumer Goods:Appliance gaskets and durable goods cushioning.
- Footwear:Midsole foams and weather-resistant upper coatings.
Construction holds established volume positions. Electronics Manufacturing is climbing the fastest.
Form:
Supply concentration around acrylic acid feedstock integration determines which physical forms achieve cost competitiveness.
- Emulsion:Aqueous dispersions capture majority share in adhesives and paints where water-borne application systems dominate. Zeon Corporation leverages captive acrylic acid supply to anchor premium polyacrylate emulsion grades across Japanese automotive supply chains.
- Bulk:Unvulcanized rubber compounds serve molded automotive components where compression set requirements are most stringent. BASF SE competes through backward integration into emulsion polymerization while maintaining bulk grade capacity for Tier-2 molders.
- Latex:High-solids dispersions for dipped goods and foam applications.
- Powder:Free-flowing grades for dry-blend compounding and extrusion.
- Solution:Solvent-based systems for specialty coatings and impregnation.
Emulsion maintains capacity leadership. Bulk is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's METI anchors the dominant geography through JIS K 6250 testing protocols that govern automotive elastomer qualification, creating technical barriers for non-domestic suppliers while simultaneously certifying the thermal performance standards that shape global formulation priorities.
United States
EPA fuel permeation standards mandate sub-15 gram per square meter per day rates in fuel delivery systems, forcing adoption of low-swell polyacrylate grades across North American vehicle platforms. The Inflation Reduction Act channels investment toward domestic battery manufacturing, expanding demand for acrylic elastomer compression pads in EV thermal management. Detroit-area automotive supply chains concentrate compounding capacity for underhood sealing applications.
Germany
BMW and Mercedes-Benz powertrain engineers specify peroxide-curable ACM grades for charge air cooler hoses where sulfur-cure systems fail. EU REACH restrictions on short-chain chlorinated paraffins force reformulation of chlorine-containing grades in transmission seals serving Stellantis and Volkswagen Group supply chains. The Rhine-Ruhr chemical corridor hosts backward-integrated emulsion polymerization capacity serving premium OEM assembly lines.
China
Dual carbon goals reshape acrylic acid feedstock economics and elastomer cost structures across the Yangtze River Delta. Ningbo chemical zones compress monomer logistics costs through acrylic acid plant co-location with elastomer polymerization. BYD assembly lines specify acrylic elastomer compression pads for battery cell-to-cell isolation, creating parallel demand from ICE thermal management and EV battery pack gasketing.
South Korea
Hyundai Motor Group assembly lines drive volume demand for battery thermal interface materials. The Ulsan chemical cluster anchors captive acrylic acid supply for premium polyacrylate grades. Korean automotive parts manufacturers negotiate direct tonnage contracts with LG Chem and Kumho Petrochemical, bypassing regional distributors in Seoul and Busan trading hubs.
India
The PLI scheme for auto components attracts elastomer compounders to Tamil Nadu and Gujarat industrial corridors. BIS standards govern automotive elastomer qualification alongside evolving EPA-aligned fuel permeation benchmarks. Construction weatherproofing applications in coastal infrastructure buildout drive emulsion volume through regional chemical manufacturing partnerships.
Global Acrylic Elastomers Market Competitive Landscape
Petrochemical conglomerates and specialty polymer architects split the market into distinct capability tiers. The vendor base concentrates around backward-integrated producers with captive acrylic acid supply and formulation specialists commanding premium positioning through cure system expertise. Three archetypes dominate: integrated petrochemical groups with monomer-to-polymer control, Japanese precision compounders with JIS-certified qualification pathways, and European specialty copolymer designers targeting high-temperature sealant applications. Competitive moves center on direct procurement platform development and peroxide cure system commercialization.
Among Japanese fabricators, Zeon Corporation and NOK Corporation occupy positions anchored by METI-compliant testing infrastructure and automotive supply chain integration. BASF SE exemplifies the European integrated archetype through emulsion polymerization scale. Arkema S.A. represents specialty copolymer architecture differentiation for elevated thermal service requirements.
| Leading Market Players |
|---|
| BASF SE |
| Zeon Corporation |
| Kuraray Co., Ltd. |
| NOK Corporation |
| Dow Inc. |
| Arkema S.A. |
| Mitsubishi Chemical Corporation |
| DuPont de Nemours, Inc. |
| Trelleborg AB |
| Others |
Supply & Pricing Matrix
Overcapacity signals from China's Ningbo chemical zones are compressing spot acrylic acid margins and forcing integrated producers toward long-term offtake contracts with automotive compounders, reshaping how pricing power distributes between feedstock owners and formulation specialists.
Pricing Analysis
Geographic price spreads between South Korean Ulsan hub quotes and European Rhine-Ruhr delivered prices reflect captive acrylic acid advantages versus propylene import exposure. Three-tier pricing structure across peroxide-curable premium grades, standard sulfur-cure polyacrylates, and emulsion commodity tiers separates JIS K 6250-certified supply from uncertified alternatives. Cost compression in standard grades is intensifying because Chinese producers are absorbing logistics discounts to defend export volume. Tier-2 molders serving domestic automotive supply chains exhibit highest price sensitivity, while German premium OEM procurement teams prioritize thermal performance over unit cost.
Supply Chain Analysis
Upstream propylene feedstock exposure ties elastomer raw material costs to crude oil futures, with South Korea, Japan, and coastal China anchoring acrylic acid polymerization capacity. The supply chain draws from propylene derivatives, chlorine-containing crosslinking agents, and peroxide cure system chemicals. Single-source vulnerability concentrates in Japanese JIS-certified qualification pathways, which extend automotive approval timelines for non-domestic suppliers. Distribution runs through direct procurement relationships between resin producers and compounders, bypassing traditional specialty chemical distributors in Seoul and Busan trading hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping acrylic elastomer procurement as digital B2B marketplaces connect resin producers directly with Tier-2 molders, collapsing distributor margins and rewarding backward-integrated producers with captive feedstock supply.
For Market Incumbents: Insulate margin position by deepening JIS K 6250 certification infrastructure against emerging South Korean compounders, while locking long-term offtake agreements with Hyundai Motor Group and BYD assembly lines before battery thermal interface material specifications crystallize. Prioritize peroxide cure system R&D to capture BMW and Mercedes-Benz charge air cooler hose demand above 175 degrees Celsius service thresholds. For New Entrants and Emerging Players: Pursue India's PLI scheme for auto components as the most penetrable geography, targeting Tamil Nadu and Gujarat industrial corridors where BIS standards are still aligning with EPA fuel permeation benchmarks. Lead with emulsion-grade construction adhesives for coastal infrastructure buildout before attempting automotive qualification pathways. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Japanese precision compounders with METI-compliant testing infrastructure and multi-year automotive supply agreements. Long-term viability hinges on peroxide-curable ACM architecture expertise and hydrogen fuel cell sealing qualifications. Watch for acrylic acid feedstock economics shifts under China's dual carbon goals as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Acid | Zeon Corporation and Korean petrochemical groups compress monomer logistics costs through captive supply. |
| Peroxide Cure System Commercialization | BMW and Mercedes-Benz specifications above 175 degrees Celsius open premium tier positioning. |
| Direct Procurement Platform Development | Digital B2B marketplaces disintermediate regional distributors in Southeast Asian trading hubs. |
| JIS K 6250 Certification Investment | METI-compliant testing infrastructure extends qualification timelines for non-domestic competitors. |
| Hydrogen Fuel Cell Sealing Development | Peroxide-curable ACM grades address high-pressure hydrogen recirculation system requirements. |
Research Methodology
A spread of perspectives from acrylic elastomer plant managers, automotive Tier 1 procurement leads, technical R&D directors at compounders, and specialty chemical distribution channel partners converged on the working assumptions. Primary fieldwork combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from petrochemical conglomerates, and vehicle production databases. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic drivers.
Demand-supply balance dynamics across the analysis window shaped the analytical framework, with segmentation across product type tiers, end-use industry concentration, physical form factors, and regional production hub clustering. CAGRs were derived from elasticity-adjusted volume projections and value chain margin compression modeling. Feedstock integration economics and regulatory chemistry restrictions served as primary forecast sensitivity inputs.
Sensitivities concentrate around propylene price volatility, REACH SVHC listing expansions, and JIS K 6250 protocol revisions. Forecasts reflect documented assumptions on automotive thermal management specification evolution and battery pack gasketing adoption curves. Cross-checking against IHS Markit vehicle production data and customs import records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
UV Stabilized Thermoplastic Elastomer Market
Elastomeric Membrane
Ultra-Soft Thermoplastic Elastomer Market
Elastomeric Membrane
Elastomeric Membrane Market
Elastomeric Membrane
South America Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Elastomeric Polyolefins Market
Elastomeric Membrane
Stretchable Conductive Material Market
Elastomeric Membrane
Cold Cast Elastomers Market
Elastomeric Membrane
Thermoplastic Polyester Elastomer Market
Elastomeric Membrane
Asia-Pacific Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Polydimethylsiloxane (PDMS) Market
Elastomeric Membrane
Specialty Elastomer Market
Elastomeric Membrane
Elastomer Coated Fabric Market
Elastomeric Membrane
Polyolefin Elastomer Market
Elastomeric Membrane
Elastomeric Foam Insulation Market
Elastomeric Membrane
Middle-East and Africa Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Perfluoroelastomer (FFKM) Market