
 United States Active Pharmaceutical Ingredients (API) Market | 2026-2036
United States Active Pharmaceutical Ingredients (API) Market Size, Share, and Industry Trends Forecast 2026-2036
United States Active Pharmaceutical Ingredients (API) Market Analytics
Contract manufacturing revenue is fragmenting across captive facilities, third-party CDMOs, and hybrid partnership models. Pfizer Inc. sustains one of the largest vertically integrated API networks in North America, producing critical inputs for its branded oncology portfolio. Lonza Group specializes in microbial fermentation and mammalian cell culture capacity, anchoring high-complexity biotech API supply for US innovators. Catalent, Inc. controls fill-finish and oral dose integration points, extending its influence from intermediate synthesis through final drug product.
Active pharmaceutical ingredients are pharmacologically active substances—synthesized through chemical routes or produced via recombinant DNA, fermentation, or extraction processes—that deliver therapeutic effects in finished dosage forms, typically manufactured to purity specifications exceeding 99% and characterized by defined impurity profiles per USP-NF monographs. Synthetic API retains the dominant revenue position due to mature chemistry infrastructure and broad generic applicability, though biotech API captures expanding margin pools as monoclonal antibodies and cell therapies multiply. Specialty API, encompassing complex peptides and antibody-drug conjugates, posts the fastest demand acceleration driven by precision oncology investments from pharmaceutical companies and research organizations.
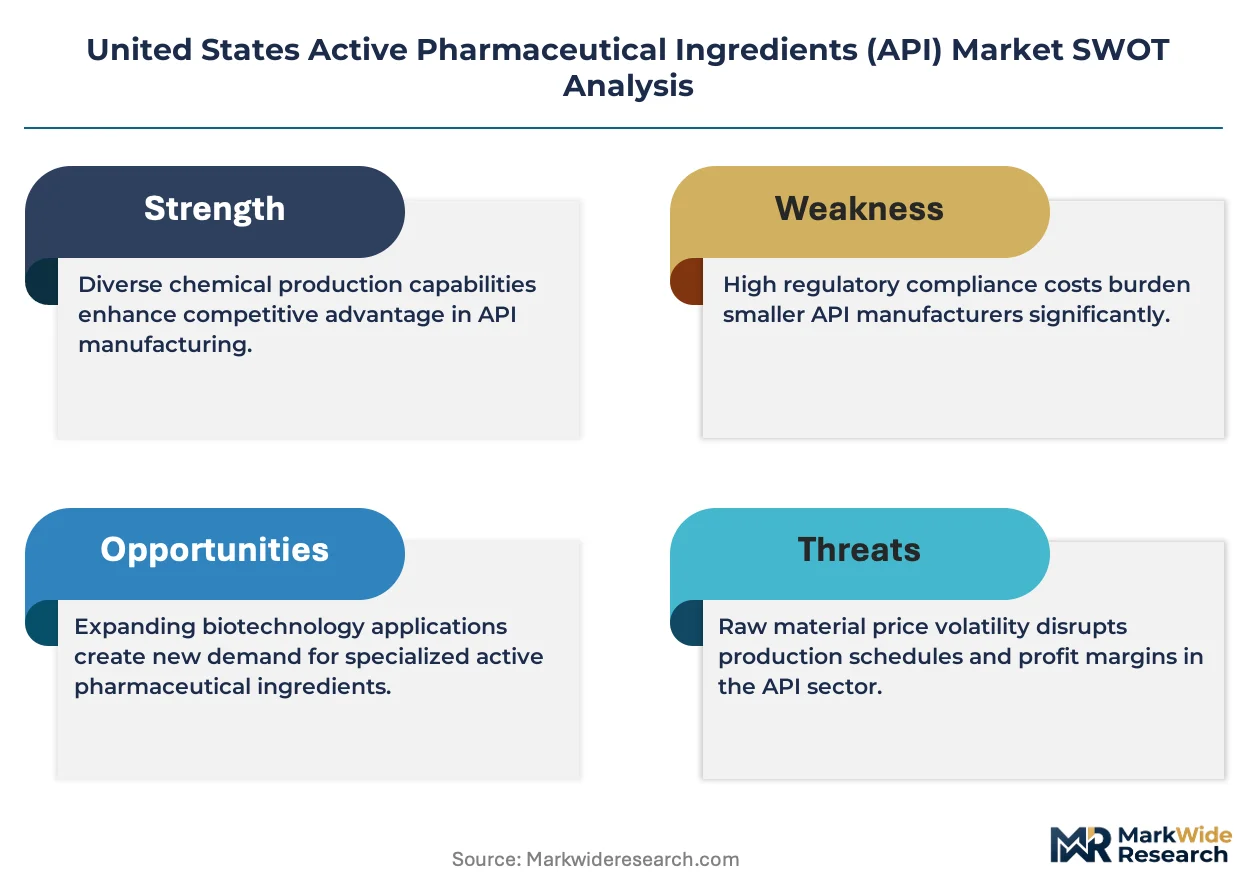
FDA current good manufacturing practice (cGMP) inspections and USP-NF compendial standards govern API purity, stability, and documentation requirements, while the Drug Supply Chain Security Act (DSCSA) mandates track-and-trace protocols that reshape logistics and qualification burdens for domestic manufacturers. The Environmental Protection Agency (EPA) regulates solvent discharge and active pharmaceutical ingredient environmental release thresholds, particularly for synthetic chemistry sites concentrated in Puerto Rico and the Eastern Seaboard. Stakeholders must monitor how FDA advanced manufacturing programs and emerging continuous processing guidance alter capital deployment timelines and facility qualification protocols.
Market Dynamics
FDA quality-by-design mandates and continuous manufacturing guidance are compressing batch cycle times while elevating capital intensity for domestic API producers. The regulatory push toward real-time release testing is forcing facility redesigns across the Northeast pharmaceutical corridor.
Growth Catalysts
- Biologics pipeline expansion:Oncology drug manufacturers are deepening API procurement for monoclonal antibodies and cell therapies, pulling capacity investments toward mammalian cell culture infrastructure.
- DSCSA track-and-trace mandates:The Drug Supply Chain Security Act is qualifying domestic manufacturers for serialized supply chains, privileging US-based intermediate producers over import-reliant competitors.
- Precision oncology investments:Antibody-drug conjugates and complex peptides are commanding dedicated synthesis capacity as research organizations advance targeted therapeutic platforms.
Market Restraints
- Solvent discharge thresholds:EPA regulations on active pharmaceutical ingredient environmental release are constraining synthetic chemistry expansion in Puerto Rico and the Eastern Seaboard.
- Specialized fermentation capacity scarcity:Microbial and mammalian cell culture facilities remain concentrated among a limited supplier base, creating qualification bottlenecks for novel biotech APIs.
- High-purity specification costs:USP-NF monograph compliance exceeding 99% purity with defined impurity profiles is elevating analytical and purification expenditures for generic API producers.
Strategic Opportunities
- Continuous processing adoption:FDA advanced manufacturing programs are incentivizing flow chemistry investments that compress production footprints and accelerate scale-up timelines.
- Hybrid partnership models:Captive facilities are unbundling non-core synthesis steps to third-party CDMOs, creating service revenue pools for specialized fermentation and high-potency handling.
- Specialty API white space:Complex peptides and ADC payloads remain undersupplied relative to clinical pipeline growth, rewarding early movers with dedicated containment infrastructure.
Industry Challenges
- cGMP inspection readiness:FDA facility qualification protocols demand sustained documentation rigor that strains quality assurance staffing across mid-scale manufacturers.
- Legacy batch system integration:Continuous manufacturing retrofits face control architecture conflicts with existing distributed control systems, extending commissioning timelines.
- Process analytical technology deployment:Real-time monitoring implementation requires spectroscopic expertise and data science capabilities that outpace current workforce supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Active Pharmaceutical Ingredients (API) Market |
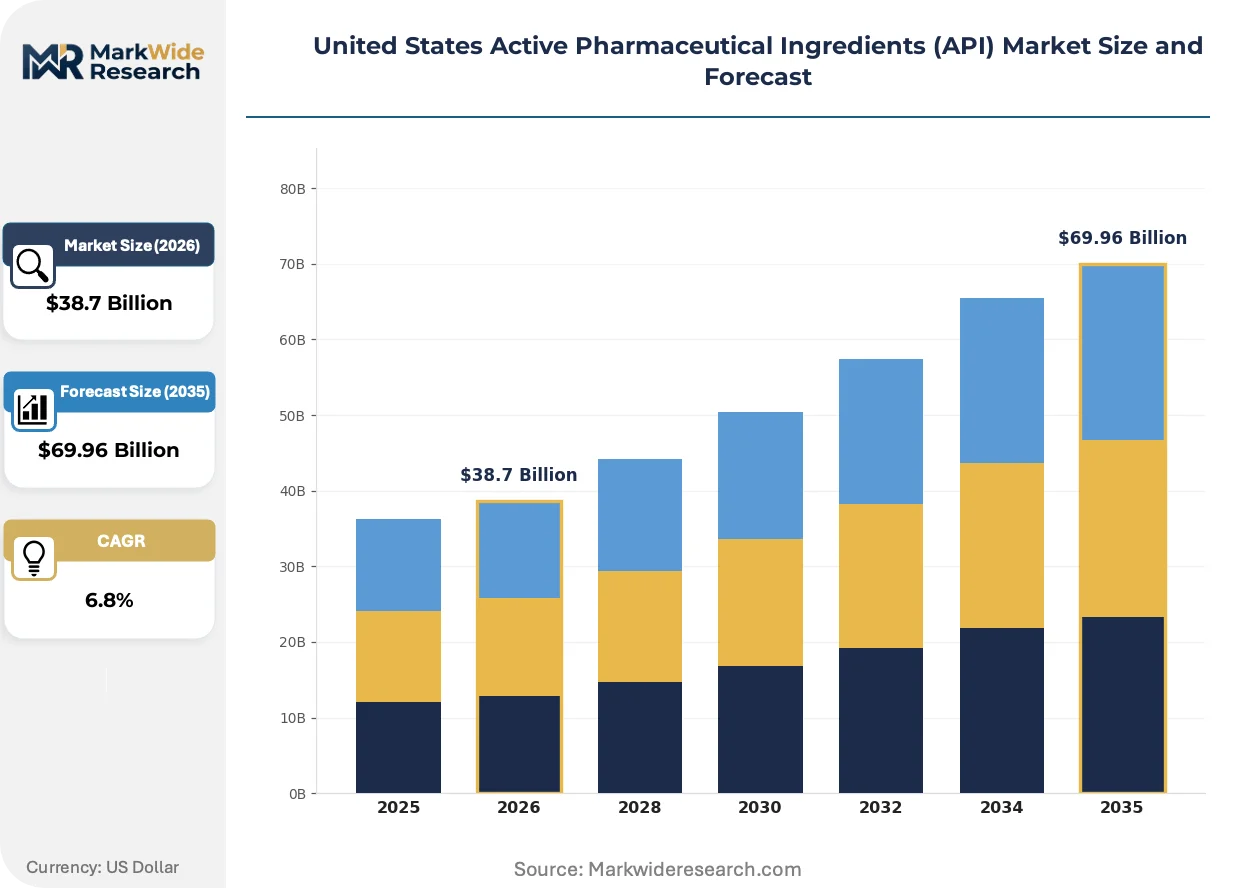
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic API, Biotech API, Generic API, Specialty API End User: Pharmaceutical Companies, Contract Manufacturers, Research Organizations, Hospital Pharmacies Form: Solid, Liquid, Semi-Solid, Gas Application: Oncology, Cardiovascular, Neurology, Anti-Infectives |
| Companies Covered | AbbVie Inc., Eli Lilly and Company, Pfizer Inc., Catalent, Inc., Viatris Inc., Teva Pharmaceutical Industries Ltd, Bristol-Myers Squibb Company, Lonza Group, Merck & Co., Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Active Pharmaceutical Ingredients (API) Market Evolving Landscape
Continuous manufacturing architectures are collapsing traditional batch economics while FDA guidance accelerates their qualification. These shifts compress capital deployment timelines and reshape competitive differentiation around process control sophistication rather than scale alone.
Single-use bioreactor systems are collapsing stainless-steel infrastructure requirements for mammalian cell culture. Biotech API manufacturers are adopting disposable fermentation platforms to reduce cross-contamination risk and accelerate product changeover. This technology is collapsing the minimum efficient scale for commercial biologics production, enabling distributed manufacturing networks closer to demand clusters.
FDA's emerging guidance on advanced manufacturing and continuous processing is elevating real-time release testing as a regulatory expectation. Drug sponsors must demonstrate process analytical technology integration to justify reduced end-product testing. Oncology API producers with integrated spectroscopic monitoring are securing priority review pathways and abbreviated inspection cycles.
Buyer consolidation among large pharmaceutical sponsors is compressing supplier qualification timelines while elevating technical service expectations. CDMO selection now weights integrated fill-finish capability and regulatory submission support more heavily than unit cost. This pattern concentrates procurement volume among vertically integrated API-to-dosage-form providers in the Massachusetts and New Jersey corridor.
United States Active Pharmaceutical Ingredients (API) Market Segmentation
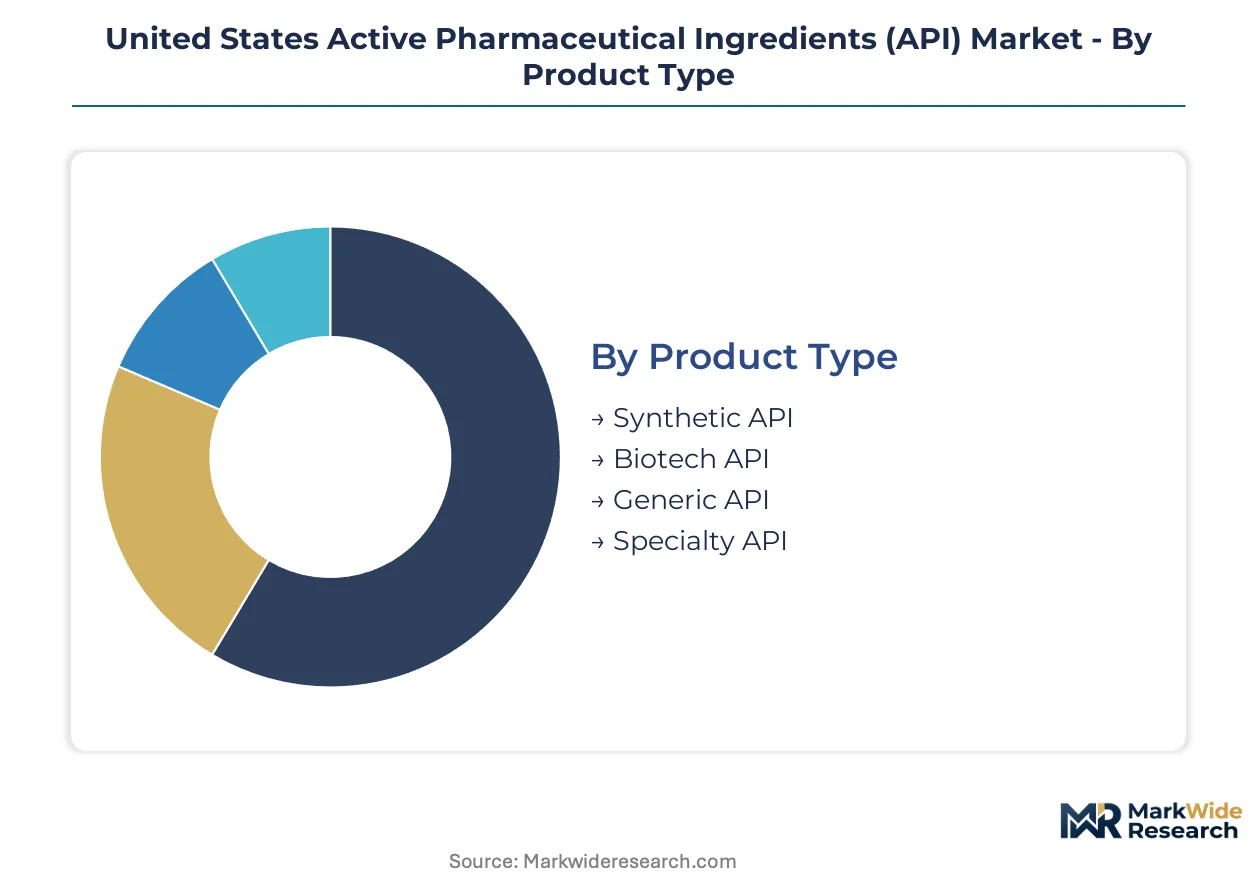
API procurement patterns diverge sharply across product chemistry, end-user sophistication, and therapeutic application. Segmentation reveals where FDA compliance burdens concentrate and where biotech capacity investments yield the steepest returns.
Product Type:
Synthetic chemistry cycles compress to weeks while mammalian cell culture runs extend across months, creating divergent capital intensity profiles.
- Synthetic API:Chemically synthesized small molecules manufactured through batch or continuous processes, typically achieving purity thresholds above 99% via crystallization and chromatographic purification. Demand concentrates among generic drug manufacturers in Puerto Rico and the Eastern Seaboard, though EPA solvent discharge thresholds constrain greenfield expansion.
- Biotech API:Recombinant proteins and monoclonal antibodies produced via microbial fermentation or mammalian cell culture, requiring single-use bioreactor infrastructure and extended batch timelines. Massachusetts and New Jersey corridor innovators are pulling capacity investments toward dedicated containment facilities for high-potency biologics.
- Generic API:Off-patent small molecules subject to intense USP-NF monograph compliance and ANDA submission requirements. Price compression from Indian and Chinese import competition is elevating domestic manufacturers' analytical expenditure burdens.
- Specialty API:Complex peptides, antibody-drug conjugate payloads, and high-potency compounds demanding dedicated containment infrastructure. Contract manufacturers with integrated fill-finish capability are capturing premium procurement volumes from precision oncology sponsors.
Synthetic API anchors the volume base while specialty API gains share at the steepest rate.
End User:
Procurement sophistication stratifies sharply between vertically integrated sponsors and outsourced development partners.
- Pharmaceutical Companies:Branded drug sponsors with captive API production networks or preferred CDMO partnerships, prioritizing integrated regulatory submission support and serialized supply chain compliance under DSCSA mandates.
- Contract Manufacturers:CDMOs and CMOs unbundling synthesis steps across fermentation, purification, and fill-finish, with Lonza and Catalent commanding qualification priority from biotech innovators.
- Research Organizations:Academic medical centers and translational research institutes sourcing preclinical and Phase I material, driving demand for flexible batch scales and rapid specification adjustment.
- Hospital Pharmacies:Institutional buyers procuring compounded preparations and 503B outsourcing facility supply, concentrated in Northeast corridor health systems with integrated specialty pharmacy operations.
Pharmaceutical companies anchor procurement volume while contract manufacturers expand their intermediation role fastest.
Form:
Physical state determines stability requirements, packaging configuration, and distribution logistics intensity.
- Solid:Powders, crystals, and granules dominating oral dosage form feedstock, with tableting and encapsulation integration points concentrated among New Jersey-based dose manufacturers.
- Liquid:Solutions and suspensions for parenteral administration, requiring aseptic processing capability and cold chain logistics that elevate handling costs for biotech API.
- Semi-Solid:Creams, ointments, and gels for topical and transdermal delivery, commanding specialized homogenization equipment and viscosity-controlled filling infrastructure.
- Gas:Inhalation anesthetics and respiratory therapeutics, subject to compressed gas cylinder serialization and stringent purity verification under USP monograph standards.
Solid forms anchor manufacturing throughput while liquid biotech formulations climb fastest.
Application:
Therapeutic category dictates potency requirements, regulatory pathway complexity, and manufacturing containment specifications.
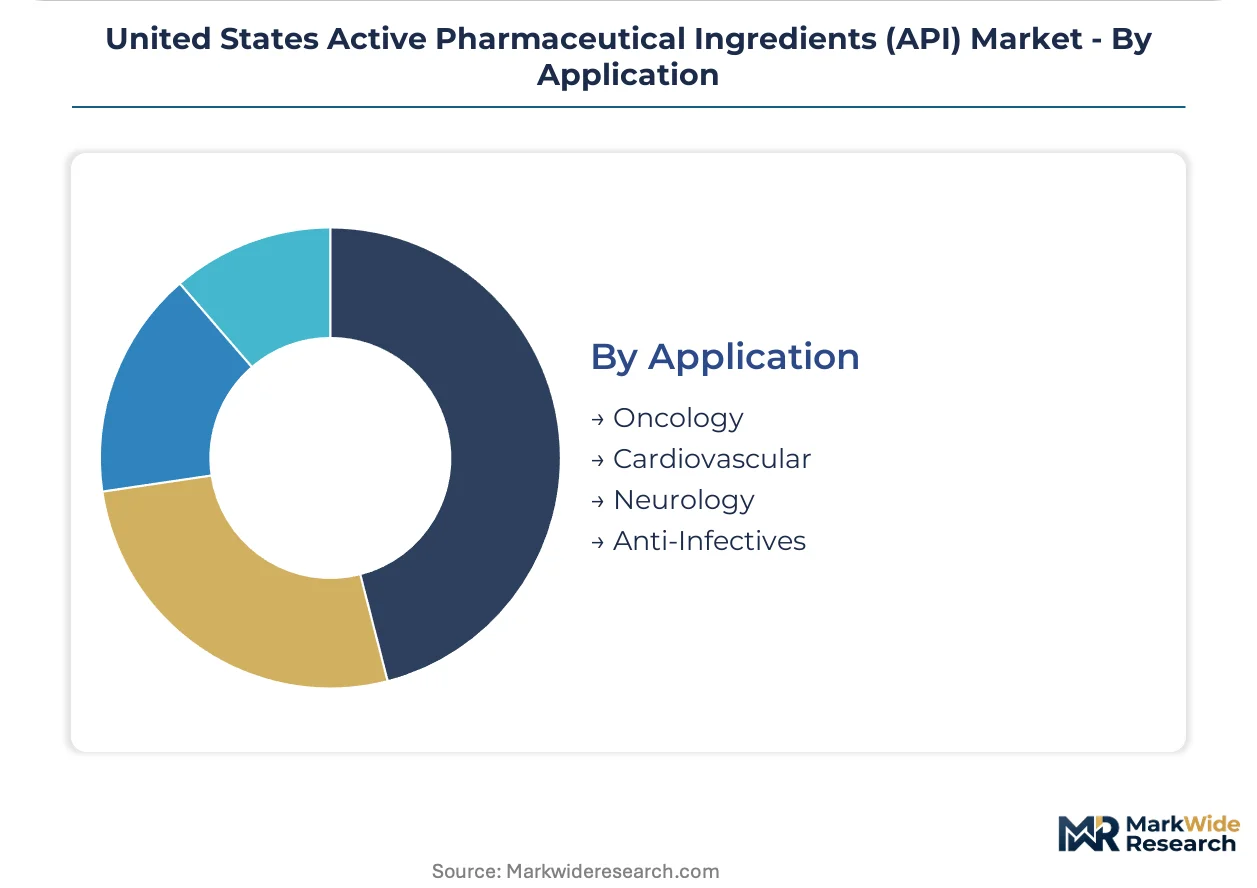
- Oncology:Cytotoxic small molecules, monoclonal antibodies, and antibody-drug conjugates requiring high-containment manufacturing infrastructure. FDA priority review pathways and breakthrough therapy designations are accelerating API qualification timelines for precision oncology sponsors.
- Cardiovascular:Statins, anticoagulants, and antihypertensives with mature generic competition, where USP-NF compliance and supply security dominate procurement criteria over innovation premiums.
- Neurology:CNS-active compounds with blood-brain barrier penetration challenges, including complex peptides and controlled substances subject to DEA scheduling and quota constraints.
- Anti-Infectives:Antibiotics and antivirals facing resistance-driven pipeline renewal, with federal BARDA contracts and pandemic preparedness stockpiling reshaping domestic production economics.
Cardiovascular applications anchor volume consumption while oncology commands the steepest capacity investment trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Northeast pharmaceutical corridor consumes API differently than other US regions—prioritizing high-complexity biotech inputs for precision oncology over commodity generic volumes. This demand-mix differential concentrates capital investment in mammalian cell culture infrastructure around Boston and New Jersey while the Southeast and Puerto Rico anchor synthetic chemistry scale.
Northeast Corridor
Oncology innovators and academic medical centers pull specialized biotech API toward Massachusetts and New Jersey. FDA breakthrough therapy designations accelerate qualification timelines for local manufacturers. Greater Boston's Kendall Square cluster anchors mammalian cell culture expansion as venture-backed biotechs deepen clinical pipelines.
Puerto Rico
Generic drug manufacturers concentrate synthetic API production for oral solid dosage forms. EPA solvent discharge thresholds constrain greenfield expansion despite existing infrastructure depth. San Juan's pharmaceutical zone hosts legacy batch chemistry facilities serving cardiovascular and anti-infective applications.
Midwest
Contract manufacturers and agricultural feedstock processors diversify into fermentation-derived APIs. USDA bio-based manufacturing incentives support microbial production platform development. Illinois and Ohio industrial corridors attract mid-scale CDMOs seeking lower-cost containment infrastructure.
Southeast
Research Triangle Park and Atlanta metro areas concentrate Phase I clinical material supply. State-level biotech tax credits pull early-stage API procurement away from traditional Northeast concentration. North Carolina's RTP cluster anchors flexible-batch fermentation capacity for preclinical sponsors.
California
Cell therapy innovators and precision medicine platforms demand novel bioconjugation and ADC payload synthesis. CAR-T manufacturing requirements reshape local procurement toward patient-specific API logistics. South San Francisco's biotech density supports dedicated high-potency containment investments.
United States Active Pharmaceutical Ingredients (API) Market Competitive Landscape
Capability concentration sits with specialized CDMOs commanding mammalian cell culture and high-potency containment expertise; scale advantage sits with vertically integrated pharmaceutical sponsors with captive fermentation networks. The vendor base stratifies across three tiers: global CDMOs with integrated regulatory submission support, mid-scale regional manufacturers serving generic ANDA filers, and niche specialists in complex peptide and ADC payload synthesis. Dominant competitive moves include hybrid partnership unbundling—where sponsors outsource non-core synthesis steps—and continuous processing technology licensing to compress batch cycle economics.
Among the vertically integrated pharmaceutical sponsors, Pfizer Inc. and Eli Lilly and Company occupy positions exemplifying captive API-to-dosage-form control. Within the contract manufacturing tier, Lonza Group and Catalent, Inc. anchor specialized service provision for biotech innovators lacking in-house fermentation infrastructure. AbbVie Inc. represents the hybrid model—maintaining selective captive capacity while partnering for non-core synthesis steps.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Eli Lilly and Company |
| Pfizer Inc. |
| Catalent, Inc. |
| Viatris Inc. |
| Teva Pharmaceutical Industries Ltd |
| Bristol-Myers Squibb Company |
| Lonza Group |
| Merck & Co., Inc |
| Others |
Value Network & Pricing Analysis
Puerto Rico's synthetic chemistry infrastructure anchors cost-competitive generic API production for oral solid dosage forms, while Massachusetts and New Jersey biotech clusters command premium pricing for high-containment mammalian cell culture capacity. This geographic bifurcation concentrates pricing power among specialized CDMOs with integrated regulatory submission support and serialized supply chain compliance under DSCSA mandates.
Pricing Analysis
Long-term offtake contracts dominate procurement between branded pharmaceutical sponsors and captive or preferred CDMO partners, insulating volume commitments from spot market volatility. Specialty API commands premium-mid-economy pricing differentiation based on containment infrastructure investment and FDA priority review pathway access. Cost compression in generic synthetic API is intensifying because Indian and Chinese import competition elevates domestic analytical expenditure burdens. Generic drug manufacturers exhibit the highest price sensitivity, while precision oncology sponsors prioritize technical service integration over unit cost.
Supply Chain Analysis
Upstream fermentation feedstocks and specialized cell culture media draw from chemical suppliers concentrated in Germany, Switzerland, and the United States. Key inputs include recombinant protein expression systems, chromatography resins, and single-use bioreactor components. Single-source vulnerability in high-purity solvent supply from China creates qualification bottlenecks for domestic synthetic chemistry expansion. Distribution runs through serialized logistics networks mandated by DSCSA track-and-trace protocols, privileging Northeast corridor manufacturers with integrated fill-finish capability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States API market is recovering from cyclical trough conditions as biologics pipeline expansion and reshoring incentives restore capacity utilization. FDA advanced manufacturing programs and continuous processing guidance accelerate this recovery by compressing batch cycle economics and elevating technical barriers to import competition.
For Market Incumbents: Insulate fermentation capacity utilization through hybrid partnership structures that unbundle non-core synthesis steps to specialized CDMOs. Prioritize backward integration into single-use bioreactor component supply and chromatography resin sourcing to reduce exposure to Chinese import dependencies. Secure FDA priority review pathway access through integrated process analytical technology deployment.
For New Entrants and Emerging Players: Mid-scale contract manufacturing for preclinical and Phase I biotech API represents the most penetrable entry point, particularly in Research Triangle Park and Atlanta metro areas where state-level tax credits pull early-stage procurement from traditional Northeast concentration. Target flexible-batch fermentation capacity for research organizations requiring rapid specification adjustment. Pursue go-to-market positioning through regulatory submission support bundling rather than unit cost competition.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized CDMOs with dedicated high-potency containment infrastructure and integrated fill-finish capability. Long-term viability across the analysis window rests on mammalian cell culture expertise and ADC payload synthesis capacity rather than commodity generic scale. Monitor FDA breakthrough therapy designation velocity as the signal to watch for inflection in specialty API demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Adoption | Flow chemistry investments compress production footprints and accelerate FDA qualification timelines for domestic sponsors. |
| Hybrid Partnership Structuring | Captive facilities unbundling non-core synthesis steps create service revenue pools for specialized fermentation CDMOs. |
| High-Potency Containment Investment | Dedicated ADC payload infrastructure captures premium procurement from precision oncology innovators in Massachusetts and New Jersey. |
| Single-Use Bioreactor Conversion | Disposable fermentation platforms reduce cross-contamination risk and enable distributed manufacturing closer to demand clusters. |
| DSCSA Serialization Compliance | Track-and-trace protocol integration qualifies domestic manufacturers for pharmaceutical sponsor supply chain security requirements. |
Research Methodology
The analysis maps synthetic chemistry, biotech fermentation, specialty peptide synthesis, and high-potency containment sub-sectors, each validated through primary interviews with drug development executives, regulatory affairs leads, CDMO procurement managers, and hospital pharmacy directors. Secondary sources include FDA cGMP inspection databases, USP-NF monograph standards, ClinicalTrials.gov pipeline tracking, and EPA environmental release filings. Bottom-up capacity modeling and top-down pharmaceutical R&D expenditure triangulation anchor volume and value estimates.
Assumptions held fixed include FDA quality-by-design mandate continuity, DSCSA serialization phase-in schedules, and current EPA solvent discharge thresholds; varied assumptions encompass biologics pipeline advancement rates and continuous manufacturing adoption velocity. Segmentation dimensions modeled span product chemistry, end-user sophistication, therapeutic application, and regional regulatory cluster. CAGRs derive from capacity utilization trends and sponsor procurement pattern analysis, with inputs from ANDA filing volumes and breakthrough therapy designation trajectories.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting biotech venture funding or pharmaceutical M&A activity would shift the trajectory. Forecasts reflect assumptions about regulatory guidance stability and import policy continuity. Cross-checking against FDA drug approval databases and CDMO revenue disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Oral Doxycycline Hyclate Market
Pharmaceutical Ingredients
Pharmaceutical Lactose Market
Pharmaceutical Ingredients
Piperacillin Sodium API Market
Pharmaceutical Ingredients
Global Sugar-Based Excipients Market
Pharmaceutical Ingredients
Mitotic Inhibitors Market
Pharmaceutical Ingredients
Pharmaceutical Indicator Strips Market
Pharmaceutical Ingredients
Global Pharmaceutical Excipients Market
Pharmaceutical Ingredients
Oral Transmucosal Drugs Market
Pharmaceutical Ingredients
Medicinal Chemistry for Drug Discovery Market
Pharmaceutical Ingredients
United Kingdom Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Global Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Casein and Casein Derivatives Market
Pharmaceutical Ingredients
Small Molecule Drug Discovery Market
Pharmaceutical Ingredients
Pharmaceutical Grade Amino Acid Market
Pharmaceutical Ingredients
Pharmaceutical Desiccants Market
Pharmaceutical Ingredients
Global Chlorpheniramine Maleate Market