
 Solution Styrene Butadiene Rubber (S-SBR) Market | 2026-2036
Solution Styrene Butadiene Rubber (S-SBR) Market Size, Share, and Industry Trends Forecast 2026-2036
Solution Styrene Butadiene Rubber (S-SBR) Market Intelligence
South Korean petrochemical complexes is expanding S-SBR output to serve tire makers across East Asia. LANXESS leverages its backward integration into butadiene feedstock to sustain margin stability in European supply chains. JSR Corporation anchors its competitive position through specialized high-styrene grades tailored for premium tire treads. ARLANXEO dominates the Americas through its integrated Texas-Louisiana production corridor.
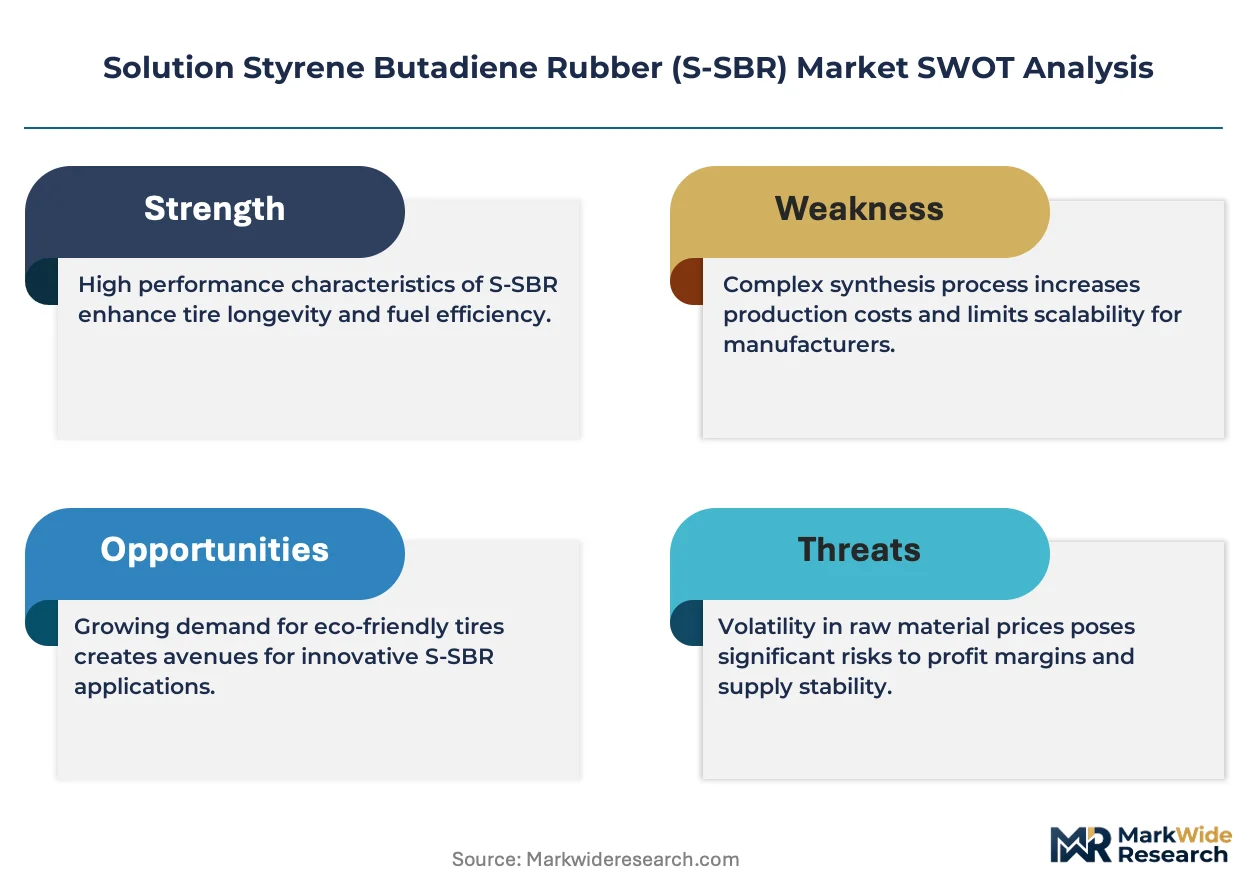
Solution Styrene Butadiene Rubber is a random copolymer synthesized via anionic solution polymerization, typically containing 15–40% styrene by weight with a narrow molecular weight distribution and high vinyl content that enables precise control over glass transition temperature and dynamic mechanical properties. Its primary commercial purpose is manufacturing tire tread compounds that reduce rolling resistance while maintaining wet grip performance. High-styrene S-SBR commands the strongest margin pool due to its specialized use in ultra-high-performance and winter tire formulations, while medium-styrene grades occupy the largest volume position across standard passenger vehicle applications. The solution polymerization process leads manufacturing process adoption because it yields the structural uniformity required for advanced silica-reinforced compounds.
The EPA regulates tire fuel-efficiency labeling through its SmartWay program, while the EU F-Gas Regulation and REACH framework constrain feedstock chemistry and emissions profiles in European S-SBR production. China's MIIT enforces GB standards for tire rolling resistance that directly specify solution-polymerized rubber content thresholds for domestic vehicle certification. Tire makers and chemical suppliers must monitor how evolving silica-coupling agent technologies and regional carbon-border adjustments will reshape feedstock sourcing decisions and compound formulation investments.
Market Dynamics
Automotive tire manufacturers face mounting pressure to source solution-polymerized rubber with verified low rolling resistance as fuel-efficiency mandates tighten across the EU, China, and the United States. The structural pull from silica-reinforced compound requirements is compressing procurement timelines and forcing compounders to qualify new S-SBR grades faster than historical norms.
Growth Catalysts
- EU Green Deal emission targets:The framework mandates fleet-wide CO2 reductions that tire makers address through high-vinyl S-SBR tread formulations. Domestic vehicle certification in EU member states now requires documented rolling resistance performance.
- China EV production surge:Battery electric vehicle manufacturers specify solution-polymerized rubber for original equipment tires to maximize range efficiency. Domestic tire plants in Shandong and Jiangsu provinces are expanding S-SBR blending capacity.
- Silica coupling agent advances:New organosilane chemistry enables higher silica loadings in S-SBR compounds without sacrificing abrasion resistance. Tire tread compounders are reformulating standard grades to capture these performance gains.
Market Restraints
- Butadiene feedstock volatility:Naphtha-cracking economics and steam cracker operating rates in South Korea and Singapore create raw material cost instability. S-SBR producers lack pricing power to pass through sharp butadiene spikes.
- Emulsion SBR substitution in commodity segments:Cold-polymerized emulsion grades satisfy basic tire carcass requirements at lower unit cost. Budget tire manufacturers in Southeast Asia default to E-SBR for non-tread applications.
- REACH registration burdens:The ECHA framework imposes costly substance evaluation and authorization procedures on novel S-SBR modifiers and process oils. European compounders face extended qualification timelines for new grade introductions.
Strategic Opportunities
- India tire export manufacturing:The PLI scheme incentivizes domestic production of fuel-efficient tires for Middle Eastern and African markets. S-SBR suppliers can anchor volume contracts with greenfield tire plants in Gujarat and Tamil Nadu.
- Winter tire premiumization:High-styrene S-SBR grades with tailored glass transition temperatures enable superior ice grip performance. Nordic and Alpine market tire makers are expanding specialized compound portfolios.
- Carbon border adjustment mechanism:The EU CBAM creates preference for S-SBR produced with verified low-carbon butadiene feedstock. European tire manufacturers will prioritize suppliers with documented Scope 3 emissions data.
Industry Challenges
- Anionic polymerization process expertise scarcity:Solution SBR production requires specialized knowledge of organolithium initiator handling and living polymerization control. The talent pool for plant operations and technical service is thinning across mature economies.
- Silica-SBR compatibility certification:Tire makers demand extensive compound testing protocols to validate wet grip and wear performance. Each new S-SBR grade requires 18-24 months of track and laboratory validation before commercial approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solution Styrene Butadiene Rubber (S-SBR) Market |
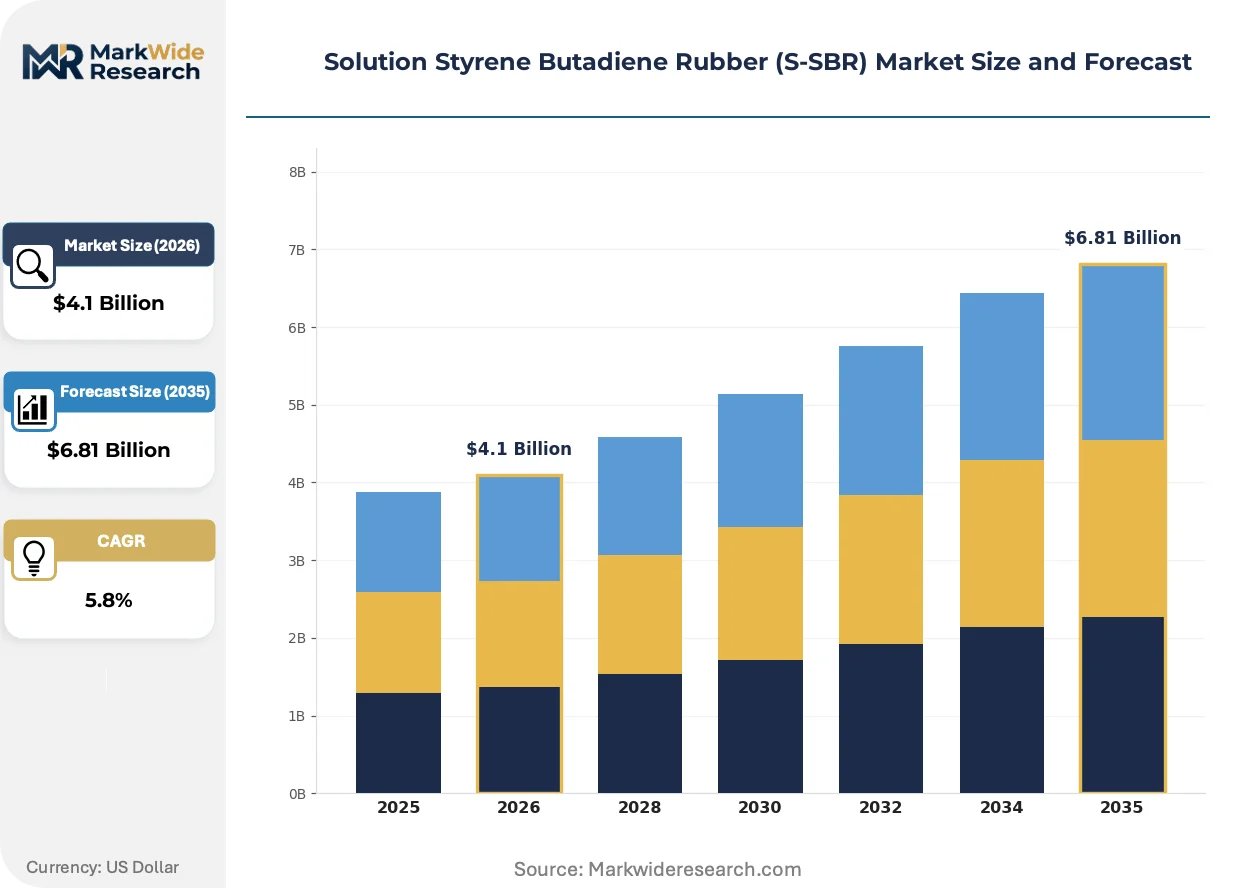
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medium Styrene, High Styrene, Low Styrene, Others Application: Tires, Adhesives, Coatings, Sealants End User: Automotive, Construction, Consumer Goods, Footwear Manufacturing Process: Emulsion Polymerization, Bulk Polymerization, Solution Polymerization, Other Methods |
| Companies Covered | SIBUR, LANXESS, ARLANXEO, Taiwan Synthetic Rubber Corporation, ENEOS Corporation, JSR Corporation, Asahi Kasei Corporation, Trinseo, Dynasol Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solution Styrene Butadiene Rubber (S-SBR) Market Strategic Shifts & Innovations
Silica-reinforced compound technology is consolidating its position as the dominant performance platform, compressing the viable design space for carbon-black-only formulations. This shift is reshaping how S-SBR producers structure their grade portfolios and technical service capabilities.
Advanced functionalized S-SBR grades with terminal silanol modification are consolidating their role in next-generation tire treads. Tier 1 tire manufacturers in Germany and Japan are adopting these materials for original equipment fitments on electric vehicles. The technology is consolidating margin concentration among producers capable of precise molecular architecture control, squeezing commodity-grade suppliers.
The EPA SmartWay program and EU tire labeling regulation are tightening enforcement of rolling resistance disclosure and verification requirements. Tire manufacturers must now submit standardized test data to national type-approval authorities before market entry. The regulatory pressure is concentrating procurement decisions on S-SBR grades with independently certified performance credentials, particularly for premium passenger segments.
Fleet operators and large automotive OEMs are consolidating S-SBR purchasing through multi-year compound supply agreements with embedded performance guarantees. Long-term contracts with volume commitments and technical collaboration clauses are displacing spot-market transactions for strategic tire programs. This pattern is most visible in China, where domestic EV manufacturers are locking in dedicated S-SBR supply for platform-specific tire development.
Solution Styrene Butadiene Rubber (S-SBR) Market Segmentation
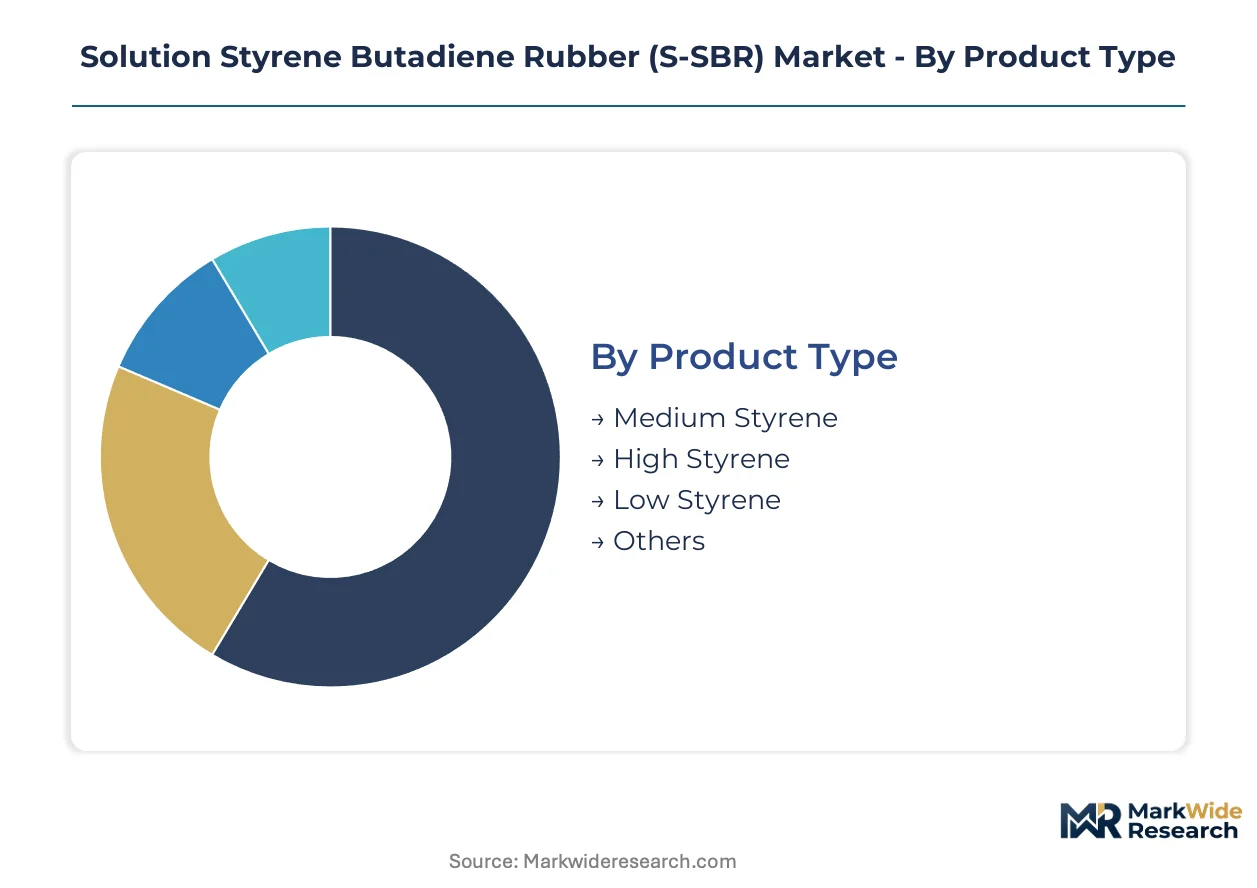
Segmentation in the S-SBR market reveals how styrene content tiers, application requirements, and manufacturing methods create distinct competitive arenas. Tire manufacturers drive volume procurement while specialized grades command premium positioning. Understanding these splits enables suppliers to align technical capabilities with margin architecture.
Product Type:
Volume concentration clusters in mid-range styrene grades, while premium pools form at the high-styrene extreme where formulation complexity erects barriers.
- Medium Styrene:Grades containing 20–30% styrene by weight deliver the balanced viscoelastic profile required for standard passenger tire treads. Chinese tire plants in Shandong province pull the largest procurement volumes as domestic EV manufacturers specify these grades for range-optimized original equipment fitments.
- High Styrene:Formulations exceeding 30% styrene content enable precise glass transition temperature tuning for winter and ultra-high-performance tire segments. Nordic tire compounders in Finland and Sweden concentrate demand here, driven by ice-grip certification requirements under EU tire labeling regulations.
- Low Styrene:Grades below 20% styrene serve industrial rubber applications requiring enhanced elasticity.
- Others:Specialty modified grades include functionalized variants with terminal silanol groups for silica coupling.
Mature deployment sits with Medium Styrene across mass-market passenger tires. Newer deployment is concentrated in High Styrene as winter tire portfolios expand.
Application:
Application segmentation tracks how rolling resistance mandates concentrate demand in tire compounds while adjacent sectors absorb residual capacity.
- Tires:Tread compounds represent the dominant consumption channel, with silica-reinforced S-SBR formulations specified for fuel-efficiency compliance under EPA SmartWay and EU CO2 fleet targets. German and Japanese OEMs lock in multi-year supply agreements for EV platform tires.
- Adhesives:Pressure-sensitive and structural adhesive applications leverage S-SBR's tack and cohesive strength. Construction sector demand in South Korea and Japan absorbs consistent volumes for flooring and panel bonding systems.
- Coatings:Protective and decorative coatings utilize S-SBR latex emulsions for flexibility and weather resistance.
- Sealants:Automotive and building sealant compounds exploit the polymer's aging stability and adhesion properties.
Procurement scale concentrates in Tires. Technical service intensity clusters in Adhesives.
End User:
End-user segmentation separates automotive volume buyers from fragmented industrial accounts with diverging specification protocols.
- Automotive:Tire manufacturers and automotive OEMs dominate procurement, with S-SBR specified for original equipment and replacement tire programs. China's MIIT enforces GB standards that directly mandate solution-polymerized rubber content for domestic vehicle certification.
- Construction:Waterproofing membranes, flooring adhesives, and sealant applications generate steady offtake. India's infrastructure expansion under the PLI scheme is pulling incremental volume for commercial building applications.
- Consumer Goods:Sporting equipment, household products, and packaging applications absorb smaller specialty volumes.
- Footwear:Soling compounds and athletic shoe components utilize S-SBR for abrasion resistance and flexibility.
Contract structure standardization sits with Automotive. Spot-market flexibility concentrates in Construction.
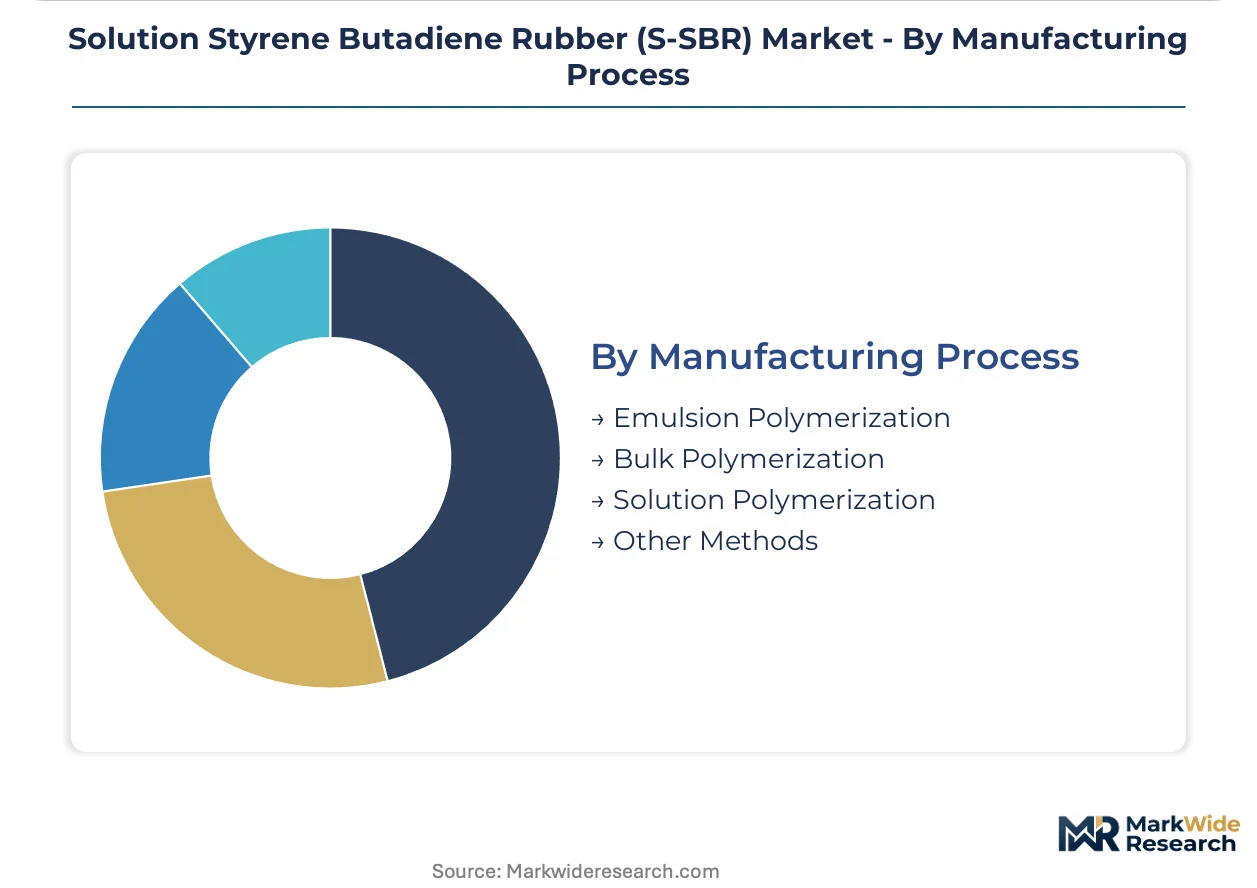
Manufacturing Process:
Process segmentation distinguishes the solution method's structural precision from legacy alternatives constrained by performance ceilings.
- Solution Polymerization:Anionic living polymerization with organolithium initiators yields narrow molecular weight distribution and controlled vinyl content. This process dominates tire-grade production because it enables the microstructural uniformity required for advanced silica coupling and rolling resistance optimization.
- Emulsion Polymerization:Cold and hot emulsion methods produce broader molecular weight distributions suitable for commodity tire carcass and industrial rubber applications. Southeast Asian budget tire makers default to E-SBR for non-tread components.
- Bulk Polymerization:Mass polymerization without solvent offers cost advantages for specific adhesive and sealant grades.
- Other Methods:Gas-phase and hybrid processes occupy niche positions for experimental or specialty formulations.
Performance certification concentration sits with Solution Polymerization. Cost-driven substitution clusters in Emulsion Polymerization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Butadiene feedstock availability in South Korea and Singapore anchors S-SBR supply chains across East Asia. Regional demand patterns diverge sharply between mature automotive markets tightening emission standards and emerging manufacturing hubs scaling tire export capacity.
China
Domestic EV manufacturers specify solution-polymerized rubber for original equipment tires to maximize range efficiency. MIIT enforces GB standards that mandate S-SBR content thresholds for vehicle certification. Tire plants in Shandong and Jiangsu provinces are expanding blending capacity to serve BYD and NIO platform programs.
Germany
EU Green Deal fleet CO2 targets compel Continental and Michelin to source high-vinyl S-SBR grades for rolling resistance compliance. ECHA REACH registration burdens extend qualification timelines for new compound modifiers. Industrial clusters in North Rhine-Westphalia concentrate technical service capabilities for silica-coupling agent integration.
United States
EPA SmartWay program enforcement tightens fuel-efficiency labeling requirements for commercial truck tires. Domestic tire makers qualify S-SBR grades through 18-24 month track validation protocols. Petrochemical corridors along the Texas-Louisiana Gulf Coast sustain integrated butadiene-to-polymer production.
South Korea
Naphtha-cracking economics at Yeosu and Ulsan complexes determine regional butadiene cost volatility. MFDS chemical safety frameworks govern process oil selection in tire compounds. Hyundai and Kia EV platforms pull specialized S-SBR volumes through dedicated supply agreements with domestic petrochemical groups.
India
PLI scheme incentives attract greenfield tire investments targeting Middle Eastern and African export markets. BIS tire quality standards are converging with EU rolling resistance benchmarks. Manufacturing clusters in Gujarat and Tamil Nadu are commissioning S-SBR blending lines for fuel-efficient passenger tire production.
Solution Styrene Butadiene Rubber (S-SBR) Market Key Industry Players
Global majors compete with regional champions across feedstock integration and technical service capabilities. Market structure tilts toward consolidated supply at the high-performance tier while commodity grades face fragmentation from emulsion SBR substitution. Three archetypes dominate: petrochemical conglomerates with captive butadiene, specialized elastomer houses with functionalization expertise, and tire-captive compounders with backward polymer integration. Capacity expansion and strategic partnerships represent the dominant competitive moves as producers secure silica-coupling agent supply chains.
Within the petrochemical-major tier, SIBUR anchors Russian feedstock-to-polymer supply chains while ARLANXEO exemplifies integrated Americas production. JSR Corporation occupies a specialist position in high-styrene functionalized grades for premium tire treads. These three represent distinct strategic postures: resource-backed scale, regional corridor dominance, and molecular-architecture precision.
| Leading Market Players |
|---|
| SIBUR |
| LANXESS |
| ARLANXEO |
| Taiwan Synthetic Rubber Corporation |
| ENEOS Corporation |
| JSR Corporation |
| Asahi Kasei Corporation |
| Trinseo |
| Dynasol Group |
| Others |
Cost & Logistics Intelligence
Tire manufacturer procurement consolidation around silica-reinforced compound specifications is compressing supplier margins and forcing S-SBR producers to absorb feedstock volatility rather than pass through costs. This demand-side pressure concentrates pricing power among integrated petrochemical groups with captive butadiene supply, while compounders without backward integration face margin erosion.
Pricing Analysis
Technical service bundling separates premium S-SBR contracts from commodity spot transactions, with silica-coupling agent formulation support and 18-24 month track validation protocols included in multi-year supply agreements. Three-tier pricing structure across premium, standard, and economy levels reflects styrene content grade and glass transition temperature precision. Cost compression in medium-styrene grades is intensifying because emulsion SBR substitution in tire carcass applications caps price ceilings. Budget tire manufacturers in Southeast Asia exhibit highest price sensitivity, while German and Japanese OEMs prioritize performance certification over unit cost.
Supply Chain Analysis
China's MIIT domestic-content thresholds for tire rolling resistance certification are reshaping sourcing patterns toward regional S-SBR blending capacity in Shandong and Jiangsu provinces. Manufacturing concentration clusters in South Korea, Singapore, and Germany, with naphtha-cracking economics at Yeosu and Ulsan complexes feeding East Asian tire plants. Butadiene feedstock dependency draws from steam cracker operating rates and naphtha pricing. Single-source vulnerability sits with organolithium initiator supply for anionic polymerization. Distribution runs through integrated petrochemical corridors with direct pipeline delivery to tire compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Anionic polymerization expertise scarcity constrains new capacity additions, propping pricing for qualified producers as tire makers face 18-24 month qualification timelines for grade substitutions.
For Market Incumbents: Anchor market position through captive butadiene integration and silica-coupling agent technology partnerships. Defend against emulsion SBR substitution in commodity segments by locking multi-year volume commitments with Chinese EV tire programs. Prioritize high-styrene grade capacity expansion in Nordic markets where winter tire premiumization sustains margin pools. For New Entrants and Emerging Players: India's PLI scheme in tire manufacturing opens a window for greenfield S-SBR supply agreements with Gujarat and Tamil Nadu export plants. Target fuel-efficient passenger tire blending capacity serving Middle Eastern and African markets. Penetrate through carbon-border-adjustment-compliant supply offerings with documented Scope 3 emissions data for EU-bound tire exports. For Investors and Strategic Acquirers: The window for entry favors functionalization specialists with terminal silanol modification capabilities and established silica-compound technical service relationships. Long-term viability hinges on molecular architecture precision rather than commodity scale. Watch silica-coupling agent technology inflection as signal for grade obsolescence risk among non-functionalized producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Butadiene | Captive feedstock supply from South Korean naphtha crackers insulates margin stability. |
| Silica Coupling Agent Partnership | Organosilane chemistry collaboration with tire compounders accelerates grade qualification timelines. |
| High-Styrene Grade Capacity Expansion | Winter tire demand in Nordic markets commands premium positioning over commodity grades. |
| Carbon Border Adjustment Compliance Program | Documented low-carbon butadiene sourcing secures EU tire manufacturer procurement preference. |
| Technical Service Center Localization | Shandong province facility placement supports Chinese EV platform tire development cycles. |
Research Approach
SEC 10-K filings, ECHA REACH registration databases, and MIIT GB standard documentation formed the secondary backbone for supply chain mapping and regulatory constraint identification. Primary interviews with tire compound procurement directors, anionic polymerization plant managers, and silica-coupling agent R&D leads combined with customs trade data and petrochemical capacity disclosures. Bottom-up grade volume estimates triangulated against top-down tire production forecasts across the analysis window.
Bottom-up modeling aggregated individual S-SBR grade consumption by styrene content tier, tire application segment, and regional production hub. Top-down validation cross-checked against OEM platform tire specifications and EV adoption trajectories. CAGRs derived from elasticity-adjusted demand curves incorporating fuel-efficiency mandate compliance deadlines. Silica-reinforcement technology penetration and organosilane chemistry advancement served as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery range extension would alter tire rolling resistance optimization priorities and S-SBR grade mix. Forecasts reflect assumptions around anionic polymerization capacity expansion rates and REACH authorization timelines for novel process oils. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Rubber Accelerators Market
Rubber
Rubber Splicing Tape Market
Rubber
EMEA and Asia Pacific Electrical Insulating Rubber Gloves Market
Rubber
Sterile Rubber Stopper Market
Rubber
Gum Rosin Market
Rubber
Global Rubber Market
Rubber
Global Rubber Processing Chemicals Market
Rubber
Fluorosilicone (FVMQ) Rubber Market
Rubber
Rubber Rollers Market
Rubber
US Nitrile Gloves Market
Rubber
Global Medical Rubber Stopper Market
Rubber
Global Tire Material Market
Rubber
Metallurgical Rubber Roller Market
Rubber
Global Chloroprene Rubber Market
Rubber
Rubber Foam Materials Market
Rubber
Rubber Molding Market