
 Styrenic Block Copolymer (SBC) Market | 2026-2036
Styrenic Block Copolymer (SBC) Market Size, Share, and Industry Trends Forecast 2026-2036
Styrenic Block Copolymer (SBC) Market Intelligence
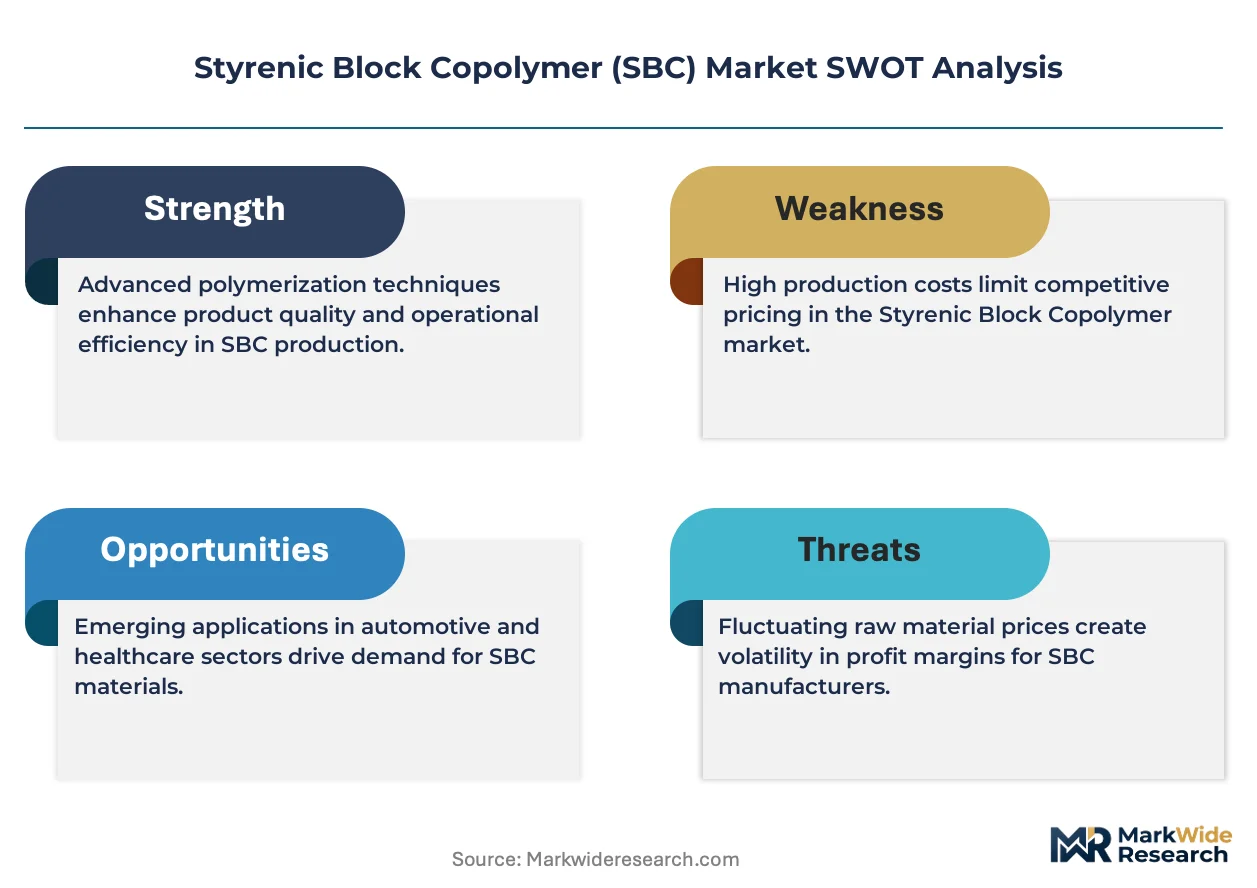
Aftermarket service revenue in technical support and formulation consulting is tilting margin pools away from commodity resin sales. Kraton Corporation leverages its hydrogenation expertise to sustain premium positioning in medical-grade SEBS. Asahi Kasei Corporation anchors its competitive stance through backward integration into styrene monomer supply.
Styrenic block copolymers are thermoplastic elastomers synthesized via anionic polymerization of styrene and diene monomers into triblock or multiblock architectures, with hydrogenated variants delivering enhanced UV and oxidative stability for outdoor and medical applications. SEBS dominates value contribution due to its saturated midblock structure, while SBS retains volume leadership in footwear and asphalt modification where cost sensitivity prevails. Adhesives and sealants command expanding share as pressure-sensitive formulations replace solvent-based systems in packaging and hygiene tapes.
EPA oversees volatile organic compound limits in adhesive formulations containing SBCs, while REACH mandates registration and hazard communication for styrene-based polymers imported into Europe. FDA regulates SBCs intended for food contact and medical device applications through biocompatibility and extraction testing protocols. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as SBCs gain substitution interest in fluoropolymer-free barrier films and coatings.
Market Dynamics
Medical device manufacturers are redirecting procurement toward hydrogenated SEBS grades as REACH and RoHS frameworks tighten chemical compliance thresholds, compressing formulation flexibility for conventional SBS alternatives in European healthcare applications.
Growth Catalysts
- Automotive lightweighting mandates:China's MIIT dual carbon goals accelerate hydrogenated SBC adoption for interior soft-touch components, displacing heavier PVC and TPU systems in electric vehicle cabins.
- REACH Article 33 disclosure requirements:European medical tubing suppliers pivot to SEBS formulations with documented SVHC-free status to maintain hospital procurement eligibility.
- Pressure-sensitive adhesive conversion:Solvent-based acrylic systems in hygiene tape applications face EPA VOC limits, pulling SBC hot-melt formulations into diaper and adult incontinence product supply chains.
Market Restraints
- Butadiene feedstock volatility:SBS producers absorb margin compression when naphtha-cracker co-product availability fluctuates with ethylene demand cycles.
- Hydrogenation capacity concentration:SEBS supply tightens around a narrow base of producers with dedicated hydrogenation assets, creating allocation risk during turnaround seasons.
- Fluoropolymer substitution ceiling:SBC barrier films hit performance limits against FEP and PFA in high-temperature medical sterilization pouches, capping penetration in Class II device packaging.
Strategic Opportunities
- India's PLI scheme for medical textiles:Domestic SEBS compounding investments align with CDSCO-registered tubing demand from Bengaluru and Hyderabad device manufacturing clusters.
- Thermoplastic polyurethane convergence:Co-extruded SBC-TPU alloys enable overmolding solutions for wearable diagnostic housings requiring both elasticity and chemical resistance.
- Direct-to-compounder digital channels:Specialty distributors bypass traditional resin merchant networks to deliver color-concentrate and additive-masterbatch integrated SBC pellets for mid-volume medical molders.
Industry Challenges
- Biocompatibility certification timelines:ISO 10993-5 cytotoxicity testing and USP Class VI validation extend qualification cycles for new SEBS medical grades, freezing formulation changes for 18-24 months.
- Anionic polymerization expertise scarcity:Operating living polymerization reactors with precise stoichiometry control requires specialized chemical engineering talent concentrated at legacy SBC production sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Styrenic Block Copolymer (SBC) Market |
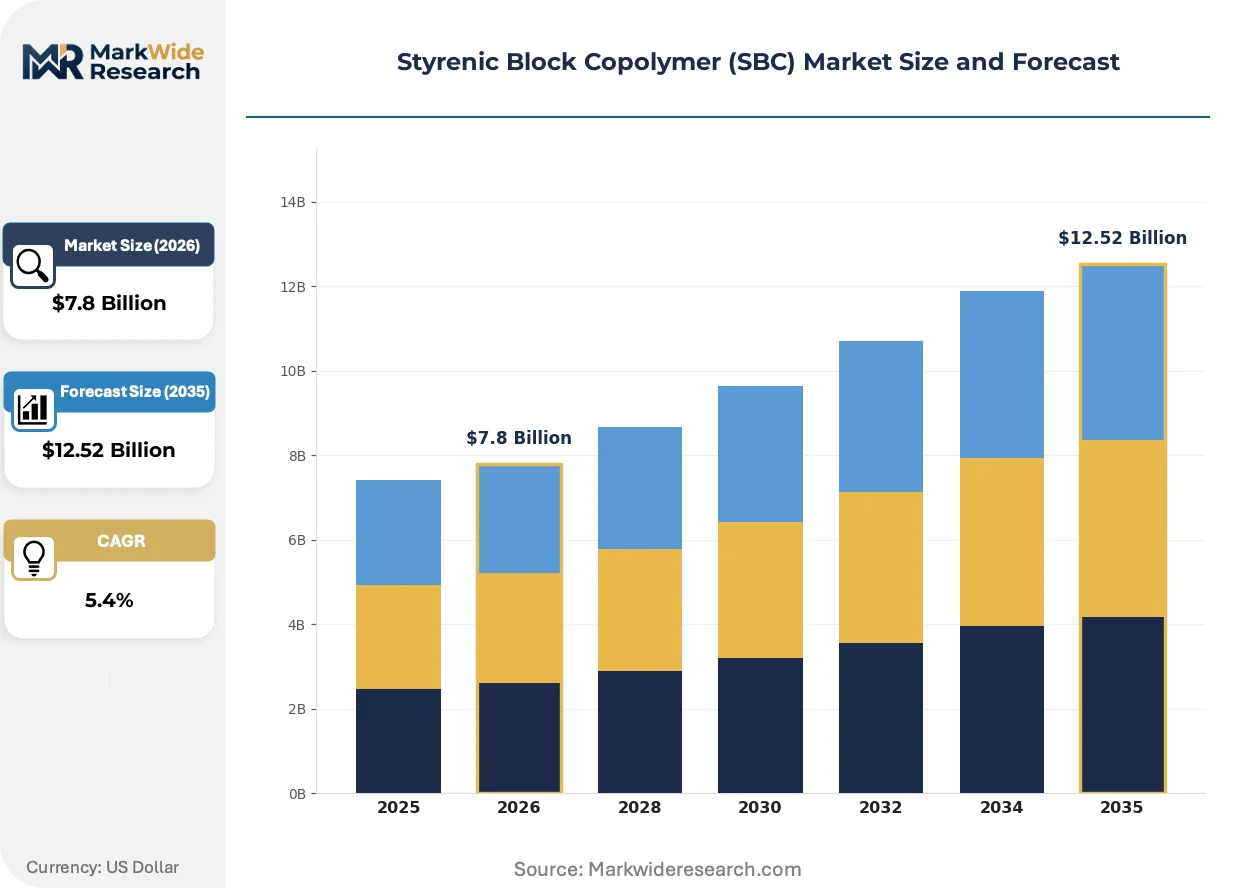
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SEBS, SBS, SIS, SIBS Application: Adhesives, Sealants, Coatings, Rubber Articles End User: Automotive, Construction, Consumer Goods, Electronics Form: Granules, Pellets, Blocks, Sheets |
| Companies Covered | Sinopec, Asahi Kasei Corporation, Kraton Corporation, LCY Group, ZEON Corporation, Dynasol Group, TSRC, INEOS, LG Chem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Styrenic Block Copolymer (SBC) Market Strategic Shifts & Innovations
Reactive extrusion advances and regulatory chemistry restrictions are compressing traditional formulation development cycles while opening substitution pathways for incumbent materials in barrier and elastomer applications.
Metallocene-catalyzed SBC variants with narrower polydispersity are collapsing the performance gap between commodity TPEs and engineering thermoplastics in overmolded automotive interior applications. Tier-one suppliers in Stuttgart and Detroit accelerate validation of these grades for instrument panel skins and door seals. The technology is collapsing historical compromises between surface aesthetics and compression set resistance that forced dual-material designs.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are redirecting investment toward SBC-based barrier films in food packaging and pharmaceutical cold-chain applications. Multilayer coextrusion lines in the Netherlands and northern Italy retrofit to run SEBS tie-layers and sealing plies previously reserved for PVDC and EVOH structures. Medical device exporters to Europe now specify fluoropolymer-free pouch constructions to preempt MDR technical documentation challenges.
Hospital procurement consortiums in the US consolidate vendor lists for single-use tubing and bag sets, compressing switching costs and forcing compounders to carry redundant FDA master file registrations. Group purchasing organizations in the Midwest and Texas now require disclosed polymer formulations with full monomer migration data, displacing black-box proprietary compounds from smaller regional suppliers. This concentration is most visible in peristaltic pump tubing for bioprocessing, where SEBS grades compete directly with platinum-cured silicone on total cost-per-meter metrics.
Styrenic Block Copolymer (SBC) Market Segmentation
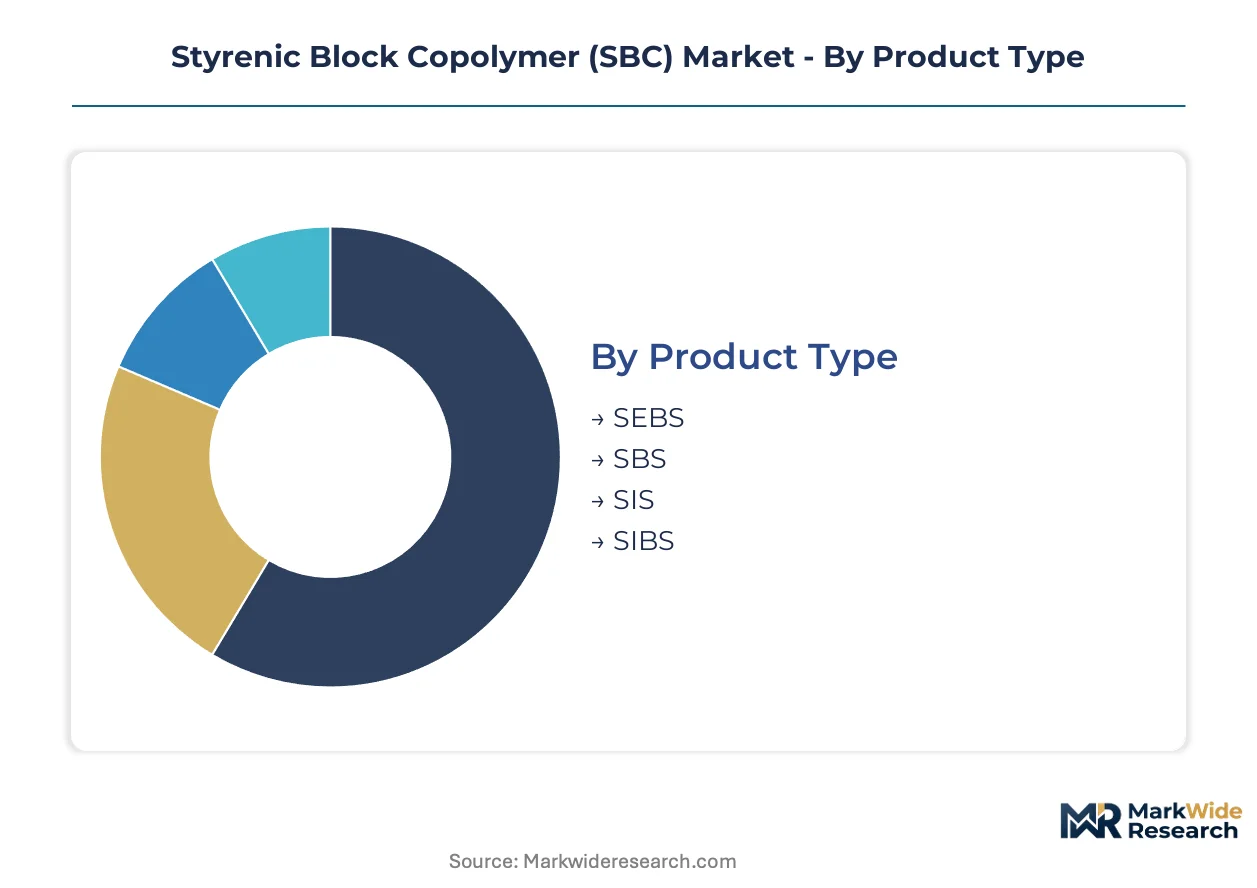
SBC market segmentation reveals divergent margin structures across hydrogenation grades and processing formats. Product type stratification separates premium medical-grade SEBS from commodity asphalt-modification SBS, while form factor choices determine compounding economics and downstream handling costs.
Product Type:
Cost tier separation defines competitive positioning across hydrogenation levels and performance specifications.
- SEBS:Hydrogenated midblock architecture delivers saturated olefin chains with superior UV resistance and oxidative stability. Medical tubing manufacturers in Germany and the US specify SEBS for peristaltic pump applications requiring USP Class VI compliance and documented SVHC-free status under REACH Article 33.
- SBS:Unsaturated diene midblock retains volume leadership in cost-sensitive footwear soling and asphalt modification where elasticity requirements tolerate moderate weathering exposure. Chinese road construction stimulus sustains SBS consumption in polymer-modified bitumen for highway surfacing.
- SIS:Isoprene-based midblock configuration optimizes tack and peel adhesion in pressure-sensitive tape formulations facing EPA VOC reduction mandates.
- SIBS:Mixed isoprene-butadiene architecture targets niche medical stent coatings and controlled-release pharmaceutical applications requiring specific permeability profiles.
SEBS holds installed capacity. SIS is rotating up the share rankings.
Application:
Application diversity spans bonding systems, protective layers, and molded elastomer articles with distinct formulation protocols.
- Adhesives:Hot-melt formulations displace solvent-based acrylics in hygiene product assembly. SBC adhesives serve diaper construction and adult incontinence product manufacturing under tightening EPA volatile organic compound thresholds.
- Sealants:Construction-grade SBS sealants flex through thermal cycling in window perimeter joints and expansion joint applications. Building code energy efficiency requirements in California and New York drive specification of low-modulus sealants maintaining adhesion across substrate movement.
- Coatings:SEBS-based barrier layers replace fluoropolymer films in pharmaceutical cold-chain packaging responding to EU F-Gas Regulation restrictions on fluorinated greenhouse gases.
- Rubber Articles:Injection-molded grips, gaskets, and overmolded soft-touch components utilize SBC elasticity without vulcanization overhead.
Adhesives command expanding formulation attention. Coatings are climbing the fastest on fluoropolymer substitution interest.
End User:
Customer type concentration varies across durable goods manufacturing, infrastructure deployment, and regulated healthcare supply chains.
- Automotive:Interior soft-touch components in electric vehicle cabins displace PVC and TPU systems under China's MIIT dual carbon lightweighting mandates. Hydrogenated SEBS serves instrument panel skins, door seals, and steering wheel grips requiring low fogging and compression set resistance.
- Construction:Roofing membranes, waterproofing sheets, and expansion joint sealants consume SBS for elasticity retention across temperature extremes. Infrastructure stimulus programs in India and Southeast Asia sustain modified asphalt demand.
- Consumer Goods:Footwear manufacturers specify SBS for injection-molded soling with cost structures competing against EVA and polyurethane alternatives. Athletic and casual shoe production clusters in Vietnam and Indonesia drive regional SBS consumption.
- Electronics:Wire insulation, cable jacketing, and connector seals utilize SEBS for halogen-free flame retardancy compliance in EU and Asian markets.
Automotive holds installed capacity. Electronics is rotating up the share rankings.
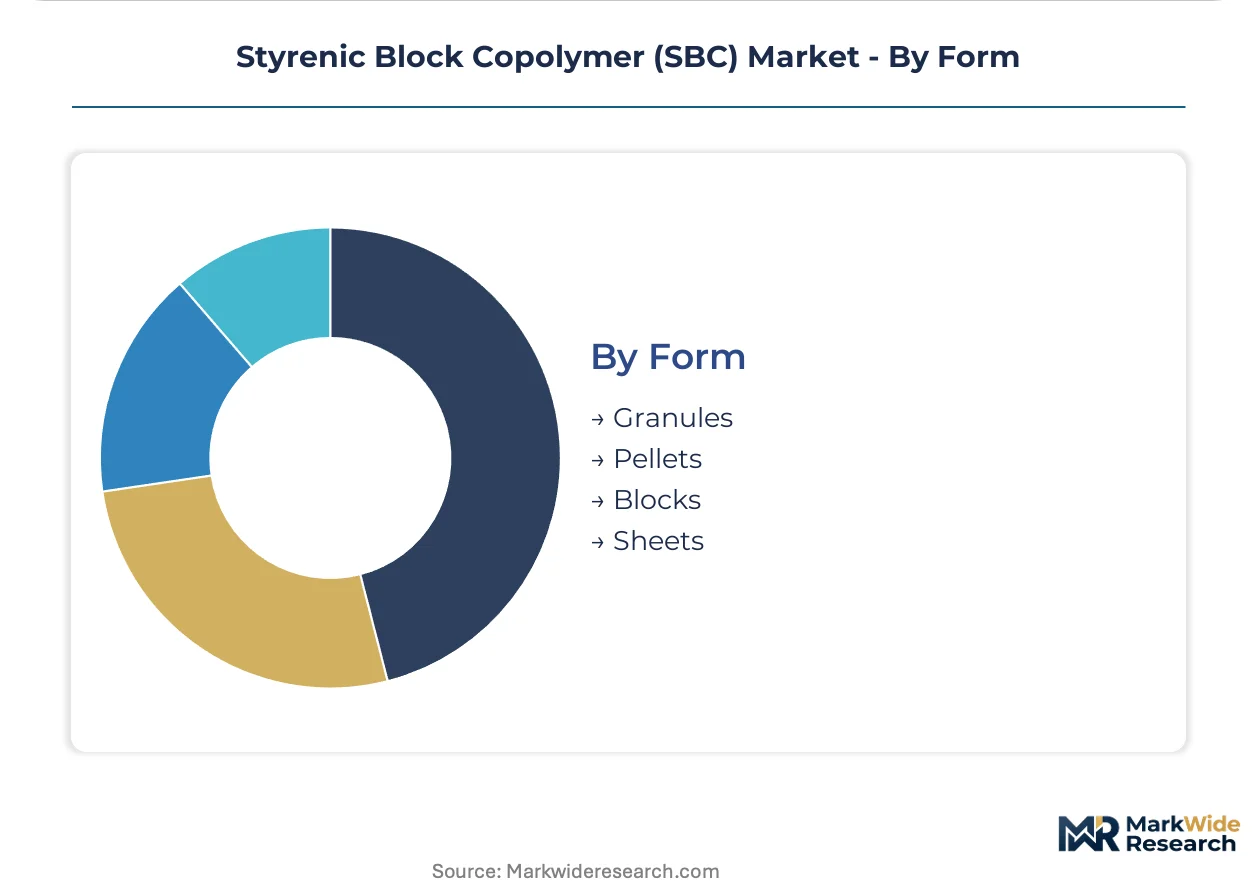
Form:
Physical presentation determines handling economics, compounding flexibility, and integration with downstream processing equipment.
- Granules:Free-flowing particulate format enables high-throughput extrusion and injection molding with consistent feed characteristics. Medical compounders prefer granules for cleanroom handling and precise dosing in twin-screw compounding lines.
- Pellets:Uniform cylindrical shape optimizes pneumatic conveying and bulk storage in automated resin handling systems. Tier-one automotive suppliers specify pelletized SBC for just-in-time delivery to interior component molding cells.
- Blocks:Solid billets support slabstock cutting and skiving operations for sheet goods manufacturing in roofing and geomembrane applications.
- Sheets:Pre-formed calendered rolls bypass pellet melting for direct thermoforming and die-cutting in gasket and diaphragm production.
Pellets hold installed capacity. Granules are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China and India exhibit the highest price elasticity, driving volume through cost-optimized SBS grades for asphalt and footwear, while German and US medical device manufacturers absorb premium SEBS pricing with limited substitution elasticity.
China
Domestic hydrogenated SEBS capacity expansion targets automotive soft-touch components and medical tubing for electric vehicle cabins and hospital supply chains. MIIT dual carbon goals accelerate PVC displacement in interior applications. Production clusters in Ningbo and Shanghai scale dedicated hydrogenation assets to serve BYD and NIO supplier networks.
Germany
REACH Article 33 SVHC disclosure requirements compress formulation flexibility for conventional SBS in European healthcare applications. ECHA regulatory updates drive medical tubing suppliers toward documented SEBS grades. Industrial concentration in Ludwigshafen and Leverkusen anchors compounding operations for peristaltic pump tubing exports.
United States
EPA VOC limits on solvent-based adhesive systems pull SBC hot-melt formulations into hygiene product manufacturing. FDA biocompatibility protocols extend qualification cycles for new medical grades. Group purchasing organizations in Texas and the Midwest consolidate vendor lists for single-use tubing, compressing switching costs for compounders.
India
PLI scheme incentives for medical textiles align with CDSCO-registered tubing demand from domestic device manufacturing. Infrastructure stimulus sustains SBS consumption in polymer-modified bitumen for highway surfacing. Bengaluru and Hyderabad clusters attract SEBS compounding investments for export-oriented medical molding operations.
Japan
METI chemical management frameworks tighten hazard communication for styrene-based polymer imports. PMDA medical device regulations reinforce biocompatibility certification requirements for SEBS grades. Osaka-based suppliers focus on halogen-free wire insulation and connector seals for regional electronics OEMs.
Styrenic Block Copolymer (SBC) Market Key Industry Players
Integrated petrochemical conglomerates and specialty hydrogenation specialists split the market into distinct capability tiers. Consolidation around hydrogenation assets creates supply allocation risk during turnaround seasons. Two strategic archetypes dominate: backward-integrated monomer producers capturing feedstock margin, and technology-focused compounders commanding premium positioning through formulation expertise. Capacity expansion and strategic partnerships represent the dominant competitive moves across both tiers.
Among Asia-Pacific-based producers, Sinopec and LCY Group exemplify scale-driven positioning through integrated petrochemical operations, while Kraton Corporation occupies a specialist tier focused on hydrogenation technology and medical-grade certification. Asahi Kasei Corporation anchors the Japanese contingent with styrene monomer integration. These three entities represent the spectrum from commodity volume leadership to premium formulation expertise.
| Leading Market Players |
|---|
| Sinopec |
| Asahi Kasei Corporation |
| Kraton Corporation |
| LCY Group |
| ZEON Corporation |
| Dynasol Group |
| TSRC |
| INEOS |
| LG Chem |
| Others |
Cost & Logistics Intelligence
Ningbo's hydrogenated SEBS production clusters anchor global supply elasticity, with dedicated hydrogenation asset availability translating directly into premium pricing power for medical-grade formulations serving hospital procurement networks.
Pricing Analysis
Aftermarket service revenue from formulation consulting and technical support drives lifetime value beyond commodity resin transactions. Three-tier pricing structure across premium, standard, and economy levels separates USP Class VI-certified medical grades from asphalt-modification SBS. Pricing pressure stems from butadiene feedstock volatility when naphtha-cracker co-product availability fluctuates with ethylene demand cycles. Footwear and construction buyers exhibit highest price sensitivity, while German and US medical device manufacturers absorb premium SEBS pricing with limited substitution elasticity.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Korean petrochemical conglomerates lubricate raw material procurement for downstream compounders. China, South Korea, and Germany concentrate hydrogenation capacity and styrene monomer production. SBC manufacturing draws from butadiene, styrene, and hydrogen feedstocks. Single-source vulnerability around dedicated hydrogenation assets creates allocation risk during turnaround seasons. Distribution runs through specialty distributors and direct-to-compounder digital channels bypassing traditional resin merchant networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense as thermoplastic polyurethane alloys and bio-based elastomers encroach on soft-touch automotive and wearable diagnostic applications.
For Market Incumbents: Pre-empt TPU convergence threats by accelerating SBC-TPU co-extrusion alloy development for wearable diagnostic housings. Deepen backward integration into styrene monomer supply to capture feedstock margin and buffer against butadiene volatility. Anchor capacity additions in Ningbo and Shanghai to serve BYD and NIO electric vehicle supplier networks.
For New Entrants and Emerging Players: India's medical textile clusters present white-space opportunity for CDSCO-registered SEBS tubing serving Bengaluru and Hyderabad device manufacturing. Target fluoropolymer-free barrier film formulations for EU F-Gas Regulation compliance as pharmaceutical cold-chain packaging pivots from PVDC and EVOH structures. Deploy direct-to-compounder digital channels with color-concentrate and additive-masterbatch integrated pellets.
For Investors and Strategic Acquirers: Long-term, this sits as a specialty hydrogenation play because medical-grade certification moats and REACH SVHC-free documentation requirements freeze formulation changes for 18-24 months. Target compounders with redundant FDA master file registrations and documented biocompatibility certifications. Watch hospital procurement consortium vendor list consolidation in the US Midwest and Texas as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Dedicated hydrogenation assets in Ningbo and Shanghai serve BYD and NIO electric vehicle networks. |
| Backward Integration | Captive styrene monomer supply anchors margin control against feedstock volatility cycles. |
| Long-term Supply Agreement | Hospital procurement consortium contracts in Texas and the Midwest lock in SEBS tubing volumes. |
| Joint Venture | Co-extrusion technology partnerships enable SBC-TPU alloys for wearable diagnostic housings. |
| Green Manufacturing Transition | Fluoropolymer-free barrier films align with EU F-Gas Regulation cold-chain packaging requirements. |
Research Approach
Operator-level perspectives from hydrogenation plant managers, medical device procurement leads at German tubing suppliers, automotive interior engineers at Stuttgart Tier 1s, and specialty distributor technical sales directors anchored the qualitative base. Primary interviews combined with secondary validation from SEC 10-K filings of listed petrochemical producers, ECHA REACH registration databases, FDA 510(k) and master file records, and customs trade data for styrene and butadiene flows. Bottom-up capacity modeling and top-down demand triangulation cross-validated volume estimates.
Scenario-bracketing framed analytical approach across the projection horizon, with segmentation modeling across hydrogenation grade tier, end-use industry, packaging format, and regional production hub. CAGRs derived from installed capacity expansion timelines, electric vehicle production ramp assumptions, and hospital procurement growth trajectories. Forecast inputs incorporated MIIT dual carbon policy enforcement intensity and ECHA SVHC list update frequency.
Practitioners should monitor butadiene-naphtha price spreads, hydrogenation asset turnaround schedules, and REACH Annex XIV authorization additions for early signals. Forecasts reflect documented assumptions about regulatory enforcement continuity and electric vehicle penetration curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
North America Plastic Compounding Market
Polymers & Resins
Polyurethanes (PU) Market
Polymers & Resins
Polymeric Sand Market
Polymers & Resins
Resin Intermediate Market
Polymers & Resins
Tie Layer Resin Market
Polymers & Resins
BMI Resins Market
Polymers & Resins
Acrylic Monomers Market
Polymers & Resins
Global Furan Resins Market
Polymers & Resins
Bio-Based Polypropylene in Medical Devices Market
Polymers & Resins
US Polymethyl Methacrylate Market
Polymers & Resins
Brazil Engineering Plastics Market
Polymers & Resins
Global Polyphthalamide Market
Polymers & Resins
Polyvinyl Alcohol Resins Market
Polymers & Resins
Acrylonitrile Butadiene Styrene (ABS) Market
Polymers & Resins
Global Medium Molecular Weight Polyisobutylene Market
Polymers & Resins
Fluorinated Polyimide Market