
 Global Elastomeric Foam Market | 2026-2036
Global Elastomeric Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Global Elastomeric Foam Market Foresight
REACH compliance is decoupling European market access from low-cost Asian supply chains. Armacell International S.A. leverages its captive polymer compounding network to sustain margin control across nitrile butadiene rubber formulations. Huamei Energy-saving Technology Group Co., Ltd. anchors volume leadership through integrated extrusion and foaming lines serving domestic HVAC OEMs. Rogers Corporation differentiates via high-performance silicone foam grades qualified for aerospace thermal barriers.
Elastomeric foam denotes closed-cell synthetic rubber materials manufactured through continuous extrusion or batch molding of polymers such as nitrile butadiene rubber, ethylene propylene diene monomer, or chloroprene, with densities typically ranging from 40 to 200 kg/m³ and thermal conductivity values below 0.040 W/m·K, engineered primarily for thermal insulation, acoustic absorption, and vibration isolation in built environments and industrial equipment. Nitrile butadiene rubber dominates current volume owing to its oil resistance and cost position in HVAC and refrigeration applications, while silicone foam captures premium margin pools in aerospace and electronics end-user industry segments where temperature stability beyond 200°C is non-negotiable. Polyurethane competes aggressively on price in construction cushioning and protective packaging, though its flammability profile limits penetration in regulated commercial building markets.
The EPA's Significant New Alternatives Policy program and the EU F-Gas Regulation jointly restrict hydrofluorocarbon blowing agents, forcing reformulation investments across the value chain. China's GB standards for building energy efficiency and Japan's METI Top Runner program impose escalating thermal-performance thresholds that favor higher-density, lower-lambda elastomeric foam constructions. Stakeholders must monitor regulatory divergence between North American and European test protocols for long-term thermal resistance, as certification fragmentation threatens to segment supply chains and inflate compliance overhead for multinational material suppliers.
Market Dynamics
The EPA's Significant New Alternatives Policy and the EU F-Gas Regulation are jointly forcing wholesale reformulation of blowing-agent chemistries across the elastomeric foam value chain, compressing margins for non-integrated compounders while advantaging producers with captive polymer synthesis capabilities.
Growth Catalysts
- Building energy-efficiency mandates:China's GB standards and Japan's METI Top Runner program impose escalating thermal-performance thresholds that favor higher-density elastomeric foam constructions in commercial envelope retrofits.
- Data-center cooling infrastructure:Prefabricated insulation kits are capturing procurement share from field-fabricated systems across China's coastal manufacturing clusters serving hyperscale facility operators.
- Hydrofluorocarbon phase-down schedules:The EU F-Gas Regulation's stepped reduction quotas are accelerating qualified demand for low-global-warming-potential foam formulations in HVAC and refrigeration OEM supply chains.
Market Restraints
- Petrochemical feedstock volatility:Nitrile butadiene rubber and ethylene propylene diene monomer prices track naphtha and propylene spreads, exposing non-backward-integrated foam producers to margin compression without pass-through mechanisms.
- REACH compliance decoupling:European market access now requires substance registration and downstream-user notification that low-cost Asian supply chains struggle to satisfy, fragmenting competitive participation.
- Polyurethane substitution in construction:Open-cell polyurethane competes aggressively on installed cost in residential and light commercial thermal-barrier applications where fire-code restrictions are less stringent.
Strategic Opportunities
- Aerospace thermal-barrier qualification:Silicone foam grades certified to temperature stability beyond 200°C command premium positioning in aircraft engine nacelle and auxiliary power unit insulation.
- Integrated extrusion-foaming lines:Domestic Chinese producers are capturing volume leadership by serving HVAC OEMs with just-in-time kit delivery from manufacturing clusters in Jiangsu and Zhejiang provinces.
- Long-term thermal resistance certification:Divergence between North American ASTM C177 and European EN ISO 8497 test protocols creates first-mover advantage for suppliers achieving dual-protocol validation.
Industry Challenges
- Polymer compounding expertise scarcity:Formulation chemists capable of balancing cell-structure uniformity with fire-retardant loading are concentrated among legacy producers, constraining new entrant scale-up.
- Continuous extrusion line capex intensity:Automated slab-stock and tube production systems require eight-figure capital commitments with payback horizons extending across multiple regulatory cycles.
- Dual-protocol testing timeline compression:Multinational material suppliers face inflated compliance overhead as certification fragmentation threatens to segment supply chains by end-use geography.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Elastomeric Foam Market |
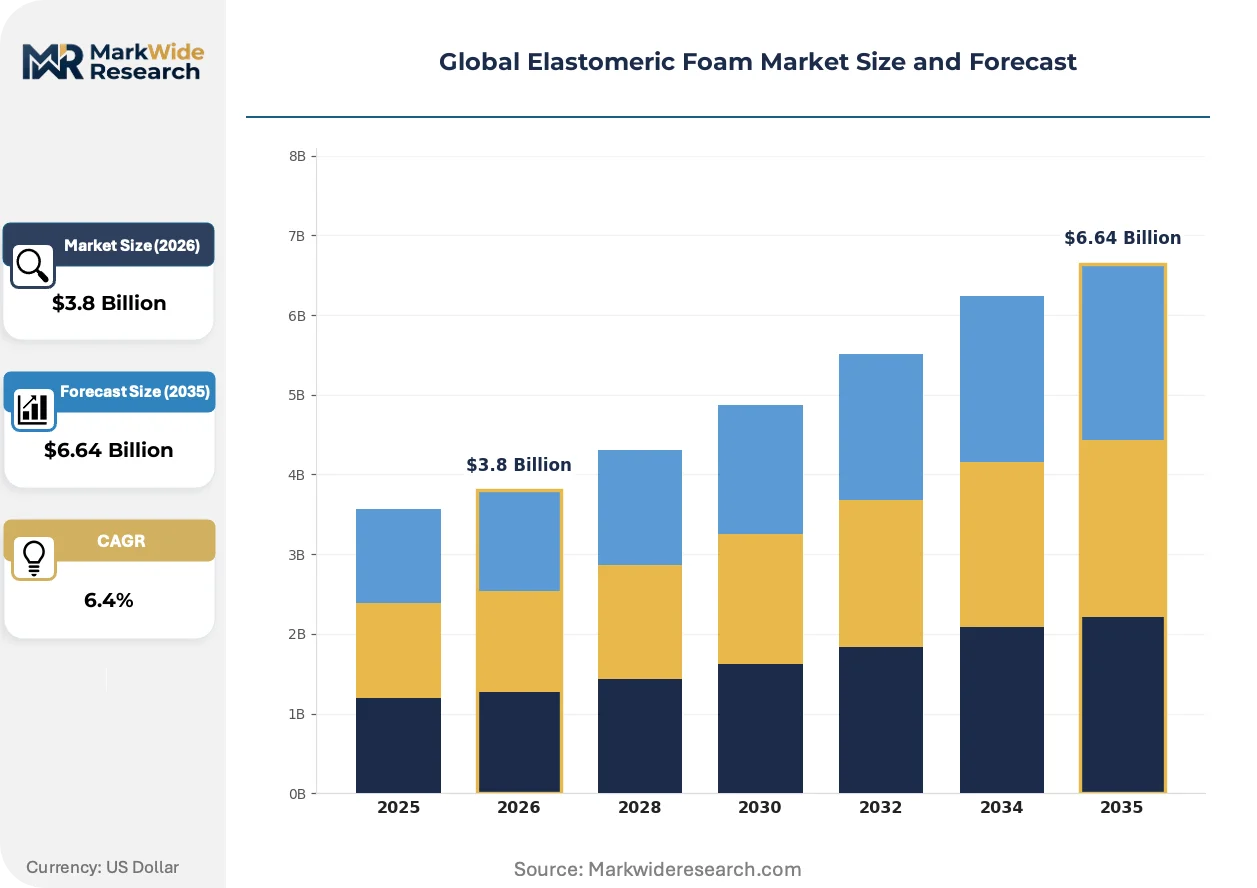
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
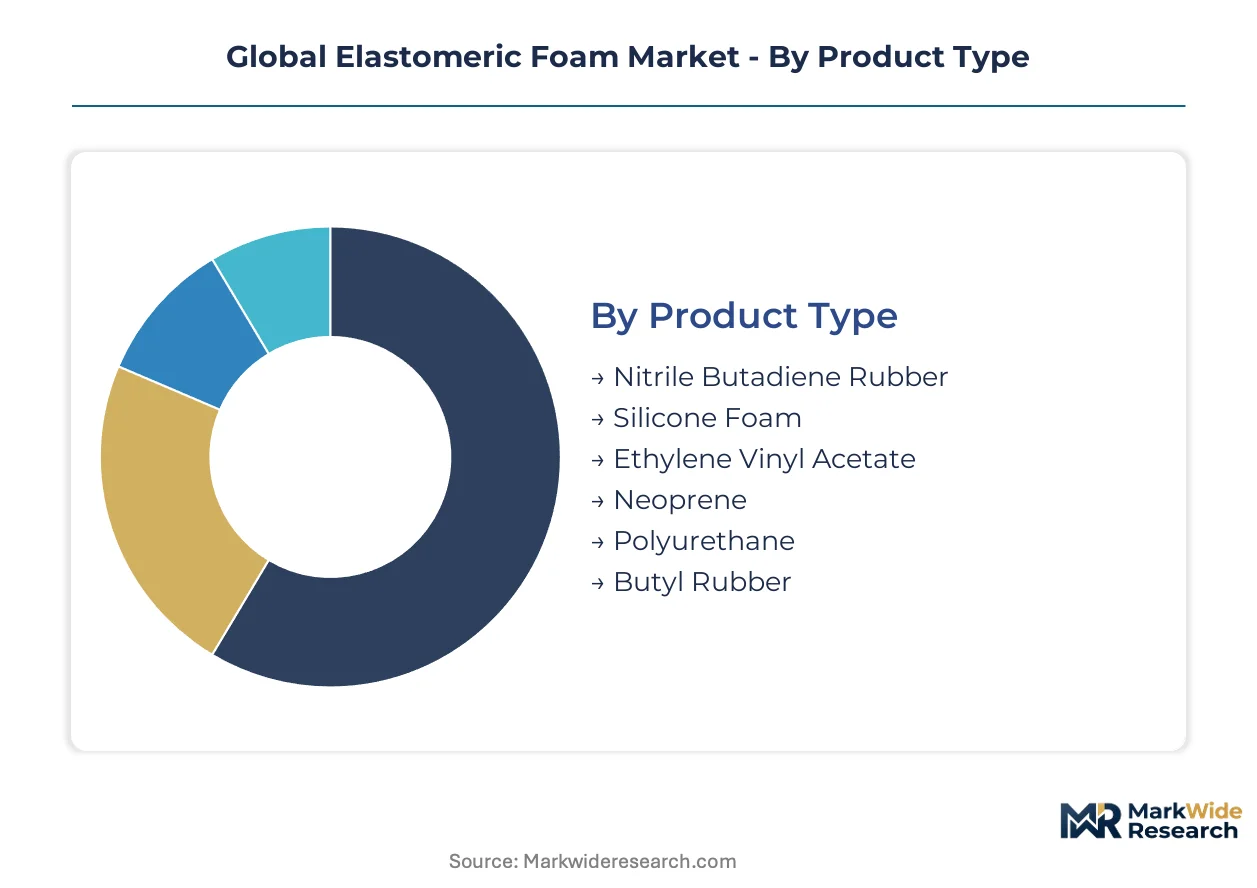
| Segmentation | Product Type: Nitrile Butadiene Rubber, Silicone Foam, Ethylene Vinyl Acetate, Neoprene, Polyurethane, Butyl Rubber Application: Thermal Insulation, Soundproofing, Vibration Dampening, Cushioning, Sealing, Protective Packaging End User Industry: Construction, Aerospace, Marine, Electronics, HVAC Systems, Appliance Manufacturing Form: Sheets, Rods, Tubes, Molded Blocks, Coiled Rolls, Granules |
| Companies Covered | Rogers Corporation, Zotefoams plc, Armacell International S.A., DuPont, BASF, L'Isolante K-FLEX S.p.A., Hira Industries LLC, Huamei Energy-saving Technology Group Co., Ltd., Saint-Gobain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Elastomeric Foam Market Shifts & Advancements
Reformulation chemistry and manufacturing-process control are the twin levers through which elastomeric foam producers are navigating regulatory discontinuity and end-use specification tightening across HVAC, aerospace, and industrial equipment markets.
Water-blown and hydrocarbon-blown foam technologies are rewriting competitive access rules for regulated building markets. HVAC OEMs in Germany and Japan are qualifying these formulations ahead of hydrofluorocarbon phase-down deadlines. The technology is compressing market share for legacy high-GWP product lines that lack reformulation capital.
REACH authorization and restriction procedures are redrawing supplier qualification criteria for European construction and refrigeration end-uses. Downstream users must now document substance safety across full supply chains, favoring compounders with in-house toxicology and regulatory-affairs capabilities. This restructuring most affects nitrile butadiene rubber foam imports from non-European Economic Area production sites.
Specification-driven procurement consolidation is concentrating buying power among tier-one HVAC and data-center engineering-procurement-construction contractors. Long-term framework agreements with technical-performance guarantees are displacing spot purchasing through distribution intermediaries. This behavioral shift is most visible in China's coastal provinces where domestic producers now bypass traditional wholesale channels to serve directly integrated project developers.
Global Elastomeric Foam Market Segmentation
Elastomeric foam markets fragment across polymer chemistry, physical form, and end-use performance requirements. Procurement specifications from HVAC OEMs and aerospace contractors drive divergent segmentation priorities across the value chain.
Product Type:
Volume leadership clusters in commodity rubber formulations, while premium margin capture depends on thermal stability beyond standard operating ranges.
- Nitrile Butadiene Rubber:Closed-cell synthetic rubber manufactured through continuous extrusion of acrylonitrile-butadiene copolymer, delivering oil resistance and lambda values below 0.040 W/m·K. Procurement concentrates among German and Japanese HVAC systems manufacturers qualifying formulations ahead of EU F-Gas Regulation phase-down deadlines. Reformulation investments toward water-blown blowing agents are compressing margin pools for non-integrated compounders lacking captive polymer synthesis.
- Silicone Foam:Platinum-cured or peroxide-cured polysiloxane elastomer with temperature stability exceeding 200°C and compression set resistance under 15 percent. Demand clusters in aerospace thermal barrier applications where FAA certification requirements for engine nacelle insulation command premium positioning. Rogers Corporation and specialized compounders dominate qualification pipelines for auxiliary power unit and thrust reverser applications.
- Ethylene Vinyl Acetate:Copolymer foam with tunable softness and UV stability, serving marine and recreational equipment cushioning where cost sensitivity dominates specification.
- Neoprene:Polychloroprene formulation balancing weather resistance with moderate oil resistance, deployed in gasket and sealing applications across industrial equipment.
- Polyurethane:Open-cell and closed-cell variants competing aggressively on installed cost in construction cushioning where fire-code restrictions permit penetration.
- Butyl Rubber:Isobutylene-isoprene copolymer valued for gas impermeability in vibration isolation mounts and specialized sealing applications.
Mature deployment sits with nitrile butadiene rubber across HVAC and refrigeration infrastructure. Newer deployment is concentrated in silicone foam grades qualifying for aerospace thermal management above 200°C.
Application:
End-use specification tightening across building energy codes and industrial equipment standards is reweighting application mix toward higher-density, lower-lambda constructions.
- Thermal Insulation:Closed-cell foam barriers engineered to EN ISO 8497 and ASTM C177 protocols for long-term thermal resistance certification. China's GB standards for building energy efficiency and Japan's METI Top Runner program are accelerating specification of higher-density elastomeric foam in commercial envelope retrofits. Dual-protocol validation creates first-mover advantage for multinational material suppliers.
- Soundproofing:Acoustic absorption layers targeting noise reduction coefficients above 0.80 in built environments and transportation equipment. Demand from data-center cooling infrastructure across China's Jiangsu and Zhejiang provinces is displacing field-fabricated systems with prefabricated insulation kits.
- Vibration Dampening:Elastomeric isolation mounts and pads decoupling mechanical equipment from structural substrates in HVAC and industrial machinery.
- Cushioning:Impact-absorbing layers in appliance manufacturing and consumer goods where polyurethane substitution pressures pricing.
- Sealing:Compression-set-resistant gaskets for fluid and gas containment in automotive and marine applications.
- Protective Packaging:Custom-molded and die-cut foam inserts for electronics and precision equipment transit protection.
Thermal insulation commands the steepest expansion trajectory as regulatory phase-down schedules force reformulation investments across HVAC OEM supply chains. Soundproofing applications are gaining share fastest in data-center engineering-procurement-construction contractor frameworks.
End User Industry:
Procurement consolidation among tier-one contractors is concentrating buying power and displacing spot purchasing through distribution intermediaries.
- Construction:Commercial building envelope and mechanical insulation subject to escalating thermal-performance thresholds under China's GB standards and EU Energy Performance of Buildings Directive. REACH compliance decoupling favors compounders with in-house toxicology capabilities.
- HVAC Systems:Original equipment manufacturer demand for closed-cell tube and sheet insulation in ductwork and refrigeration lines. German and Japanese manufacturers are expanding procurement of low-global-warming-potential foam formulations ahead of regulatory deadlines.
- Aerospace:Aircraft engine nacelle, auxiliary power unit, and thermal barrier applications requiring silicone foam qualification to temperature extremes. FAA and EASA certification timelines constrain supplier switching.
- Electronics:Thermal interface materials and protective packaging for semiconductor and battery systems.
- Appliance Manufacturing:Refrigeration cabinet and compressor insulation where cost engineering pressures material selection.
- Marine:Hull insulation and deck cushioning for commercial and recreational vessels.
Volume concentration rests with construction and HVAC systems serving building energy-efficiency mandates. Premium margin extraction concentrates in aerospace thermal barrier qualification.
Form:
Manufacturing-process control and just-in-time delivery capabilities are determining competitive access across form factor categories.
- Sheets:Continuous extrusion slab stock in standard and custom thicknesses for fabrication into gaskets, pads, and insulation barriers. Huamei Energy-saving Technology Group and domestic Chinese producers leverage integrated extrusion-foaming lines for direct supply to HVAC OEMs.
- Tubes:Closed-cell cylindrical insulation for pipe and ductwork applications. Automated tube production systems require capital commitments with payback horizons extending across multiple regulatory cycles.
- Rods:Solid and hollow profiles for sealing and cushioning applications in industrial equipment.
- Molded Blocks:Custom-geometry foam blocks for protective packaging and specialized industrial applications.
- Coiled Rolls:Continuous-length sheet material for field fabrication and distribution channel supply.
- Granules:Crumb and pellet forms for loose-fill insulation and compound blending operations.
Sheets and tubes dominate procurement volume through specification in HVAC and building insulation standards. Molded blocks and custom geometries command premium positioning in aerospace and electronics end-uses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's coastal manufacturing clusters concentrate procurement volume for data-center cooling infrastructure, while regulatory divergence between German and Japanese energy-efficiency mandates fragments certification requirements across major demand centers.
Germany
HVAC systems manufacturers in Bavaria and Baden-Württemberg are expanding procurement of closed-cell insulation materials. The EU F-Gas Regulation imposes stepped reduction quotas for hydrofluorocarbon blowing agents. Production gravity centers on industrial zones around Stuttgart and Munich where reformulation investments are compressing margin pools for non-integrated compounders.
Japan
METI energy-efficiency mandates are tightening thermal-performance requirements for building envelopes. The METI Top Runner program imposes escalating thresholds that favor higher-density elastomeric foam constructions. Manufacturing clusters in the Chubu region around Nagoya serve domestic HVAC OEMs with just-in-time kit delivery systems.
United States
The EPA's Significant New Alternatives Policy program restricts hydrofluorocarbon blowing agents and forces reformulation investments. Aerospace thermal barrier applications in California and Washington state command premium positioning for silicone foam grades. Rogers Corporation anchors qualification pipelines for aircraft engine nacelle insulation through FAA certification timelines.
China
GB standards for building energy efficiency accelerate specification of higher-density constructions in commercial envelope retrofits. Domestic producers in Jiangsu and Zhejiang provinces supply prefabricated insulation kits directly to hyperscale data-center operators. Huamei Energy-saving Technology Group leverages integrated extrusion and foaming lines to capture volume leadership.
India
Construction activity in Maharashtra and Gujarat drives demand for thermal insulation in commercial building envelopes. The Bureau of Indian Standards is developing domestic test protocols for long-term thermal resistance certification. Manufacturing capacity concentrates in industrial corridors around Mumbai and Ahmedabad where cost engineering pressures material selection.
Global Elastomeric Foam Market Competitive Landscape
German and Belgian producers anchor one tier; Chinese specialists hold volume leadership through integrated manufacturing. The vendor base organizes around three strategic archetypes: captive polymer compounders with backward integration into polymer synthesis, extrusion-foam integrators serving regional HVAC OEMs, and qualification-heavy silicone foam specialists. Competitive moves concentrate on dual-protocol certification investments and direct-to-contractor supply chain restructuring.
Within the captive-compounder tier, Armacell International S.A. represents European market access capabilities through REACH compliance infrastructure. Huamei Energy-saving Technology Group Co., Ltd. exemplifies scale-driven positioning through integrated extrusion-foaming lines in China's coastal provinces. Rogers Corporation occupies the premium-tier vector for aerospace thermal barrier qualification.
| Leading Market Players |
|---|
| Rogers Corporation |
| Zotefoams plc |
| Armacell International S.A. |
| DuPont |
| BASF |
| L'Isolante K-FLEX S.p.A. |
| Hira Industries LLC |
| Huamei Energy-saving Technology Group Co., Ltd. |
| Saint-Gobain |
| Others |
Supply & Pricing Matrix
EU F-Gas Regulation phase-down schedules gate qualified supply access and premium-tier pricing power, compressing margins for non-integrated compounders while rewarding producers with captive polymer synthesis and reformulation capital.
Pricing Analysis
Short lead-time premiums separate qualified suppliers from spot-market inventory discounters across HVAC OEM procurement cycles. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment, with dual-protocol ASTM C177 and EN ISO 8497 validation commanding top positioning. Pricing pressure stems from polyurethane substitution in residential construction where fire-code restrictions permit penetration. Tier-one engineering-procurement-construction contractors exhibit lowest price sensitivity due to technical-performance guarantees, while distribution-channel spot buyers face margin compression without pass-through mechanisms.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from China's Jiangsu and Zhejiang manufacturing clusters, displacing traditional wholesale intermediaries. Supply concentrates in Germany, China, and Japan, with polymer compounding expertise anchored in legacy European producers and integrated extrusion-foaming lines scaling across Chinese coastal provinces. Raw material dependencies rest on naphtha-derived nitrile butadiene rubber, propylene feedstocks for ethylene propylene diene monomer, and platinum catalysts for silicone foam curing. Single-source vulnerability concentrates in specialized formulation chemists capable of balancing cell-structure uniformity with fire-retardant loading. Distribution runs through just-in-time kit delivery systems serving domestic HVAC OEMs and direct-integrated project developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU F-Gas Regulation compliance costs erect a barrier-to-entry moat that consolidates margin pools among REACH-registered compounders with in-house toxicology capabilities.
For Market Incumbents: Acquire captive polymer synthesis assets to secure margin control across nitrile butadiene rubber formulations threatened by petrochemical feedstock volatility. Expand dual-protocol certification investments covering both ASTM C177 and EN ISO 8497 test standards to preempt supply chain fragmentation. Consolidate channel control through long-term framework agreements with technical-performance guarantees that displace spot purchasing. For New Entrants and Emerging Players: Regional HVAC OEMs in India's Maharashtra and Gujarat industrial corridors represent underserved buyer archetypes where cost engineering pressures material selection without stringent qualification timelines. Target data-center soundproofing applications across prefabricated insulation kit procurement as the most penetrable segment bypassing legacy distribution channels. Pursue direct-to-contractor supply positioning with just-in-time delivery capabilities from manufacturing clusters. For Investors and Strategic Acquirers: First dual-protocol validation announcements from mid-cap compounders is the leading indicator that certification fragmentation is segmenting supply chains by end-use geography. Long-term viability over the next decade rests on backward integration into polymer compounding and reformulation chemistry capabilities. Acquisition target archetypes include integrated extrusion-foam operators with regional HVAC OEM relationships and in-house toxicology infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Synthesis | Captive supply of nitrile butadiene rubber insulates margins from naphtha price volatility. |
| Dual-Protocol Certification Investment | ASTM C177 and EN ISO 8497 validation unlocks multinational HVAC OEM procurement frameworks. |
| Water-Blown Reformulation Scale-Up | Low-global-warming-potential formulations qualify ahead of EU F-Gas Regulation phase-down deadlines. |
| Direct-to-OEM Channel Restructuring | Just-in-time kit delivery bypasses distribution intermediaries in China's coastal manufacturing clusters. |
| Silicone Foam Aerospace Qualification | FAA certification for temperature stability beyond 200°C commands premium positioning in engine nacelle insulation. |
Research Methodology
Document review covered customs and trade data, SEC 10-K filings, and chemical industry association reports, complemented by interviews with plant managers at elastomeric foam producers, procurement leads at HVAC OEMs, distribution channel partners, and technical R&D directors specializing in polymer compounding. Bottom-up volume triangulation across polymer chemistry, physical form, and end-use segments was validated against top-down macroeconomic indicators and regulatory timeline assessments.
Segmented outputs across nitrile butadiene rubber, silicone foam, and ethylene propylene diene monomer chemistries, thermal insulation and soundproofing applications, and construction, HVAC systems, and aerospace end-user industries were generated over the projection horizon. CAGRs were derived from regression analysis against building energy-efficiency mandate adoption curves, data-center cooling infrastructure deployment rates, and hydrofluorocarbon phase-down schedule compliance timelines.
Revisions become necessary when regulatory test protocol divergence accelerates, petrochemical feedstock spreads destabilize compounder margins, or polyurethane substitution penetrates commercial building markets beyond fire-code restricted zones. Forecasts reflect assumptions regarding EU F-Gas Regulation enforcement consistency, China's GB standards implementation pace, and Japan's METI Top Runner program threshold escalation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Middle-East and Africa Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Cold Cast Elastomers Market
Elastomeric Membrane
Modified Silicone Fluids Market
Elastomeric Membrane
Polyurethane Elastomers Market
Elastomeric Membrane
Global Elastomeric Sealants Market
Elastomeric Membrane
Thermo Elastic Acrylic Market
Elastomeric Membrane
Ethylene Propylene Diene Monomer(EPDM) Market
Elastomeric Membrane
EPDM Waterproofing Membrane Market
Elastomeric Membrane
Specialty Elastomer Market
Elastomeric Membrane
Medical Grade Silicone Rubber Market
Elastomeric Membrane
Global Fluoroelastomers Market
Elastomeric Membrane
UV Stabilized Thermoplastic Elastomer Market
Elastomeric Membrane
North America Performance Elastomer Market
Elastomeric Membrane
Chlorinated Polyethylene Resins and Elastomers (CPE) Market
Elastomeric Membrane
Ethylene Propylene Elastomers Market
Elastomeric Membrane
Asia-Pacific Thermoplastic Elastomer (TPE) Market