
 Europe Automotive Thermoplastic Polymer Composites Market | 2026-2036
Europe Automotive Thermoplastic Polymer Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Thermoplastic Polymer Composites Market Foresight
Modular sub-assembly packaging is realigning how Tier-1 suppliers specify thermoplastic composite systems for platform-shared vehicle architectures. BASF SE leverages its integrated polyamide compounding network to anchor supply security for under-the-hood modules across German OEM programs. Solvay S.A. specializes in high-performance polymer matrices that sustain elevated thermal loads in powertrain applications. Covestro AG competes through differentiated polycarbonate blends optimized for exterior part aesthetics and impact resistance.
Europe automotive thermoplastic polymer composites comprise fiber-reinforced thermoplastic matrices—typically glass or carbon fiber in polypropylene, polyamide, or polycarbonate—processed by injection molding or thermoforming to achieve specific strength-to-weight ratios above 150 MPa/(g/cm³) while enabling end-of-life recyclability. Their primary purpose is substituting metal stampings and thermoset composites to reduce vehicle mass and simplify manufacturing cycle times. Polypropylene dominates volume demand due to its cost position and established recycling infrastructure, while polycarbonate and nylon concentrate in higher-margin electrical enclosure and thermal management applications where dielectric stability and heat resistance command premium positioning. Injection molding retains the largest installed base, though thermoforming is gaining share in exterior panel programs where larger surface areas and lower tooling amortization reshape supplier economics.
The EU Green Deal, REACH, and the F-Gas Regulation collectively mandate recyclability disclosure, restricted substance compliance, and lower-GWP process alternatives that filter material choices available to compounders and molders. ECHA substance evaluations and EMA carbon-footprint protocols for automotive supply chains are tightening qualification thresholds for imported resin systems. Stakeholders must monitor how the EU AI Act's quality-traceability requirements intersect with composite batch certification, as algorithmic process control becomes embedded in molding operations and regulatory audit trails extend deeper into material genealogy.
Market Dynamics
Platform-shared vehicle architectures are forcing Tier-1 suppliers to consolidate material specifications across multiple OEM programs, compressing qualification timelines and favoring compounders with integrated resin-to-part capabilities.
Growth Catalysts
- EU Green Deal material circularity mandates:Recyclable thermoplastic systems now carry preferential weighting in OEM sourcing scorecards, accelerating converter migration from thermoset alternatives.
- Glass-reinforced polypropylene cost position:Established recycling infrastructure and feedstock availability enable mass-market penetration in under-the-hood applications previously served by metal stampings.
- Stuttgart-Munich supplier cluster density:Proximity to German OEM technical centers compresses development cycles and reduces logistics friction for qualification programs.
Market Restraints
- Carbon fiber feedstock concentration:European precursor supply depends on a limited set of non-EU producers, exposing compounders to import tariff volatility and currency risk.
- High-performance polyamide technical ceiling:Continuous-use temperatures above 180°C remain problematic for powertrain thermal management modules, constraining substitution depth.
- REACH substance evaluation friction:ECHA screening of polymer additives creates registration bottlenecks that extend material approval timelines by 12-18 months.
Strategic Opportunities
- Eastern European manufacturing expansion:Slovakia and Czech Republic automotive corridors offer labor-cost advantages for thermoforming operations serving German OEM satellite plants.
- Battery enclosure thermal runaway containment:Flame-retardant polycarbonate blends address emerging EV safety standards with dielectric properties metal cannot match.
- EMA carbon-footprint protocol alignment:Early certification to automotive supply chain emissions tracking creates preferred-supplier status for EU-funded fleet electrification programs.
Industry Challenges
- Multi-material welding technician scarcity:Thermoplastic composite-to-metal joining requires specialized ultrasonic and vibration welding expertise that vocational training pipelines have not scaled.
- Batch certification algorithmic audit trails:EU AI Act quality-traceability mandates force molders to reconfigure MES systems for composite genealogy documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Thermoplastic Polymer Composites Market |
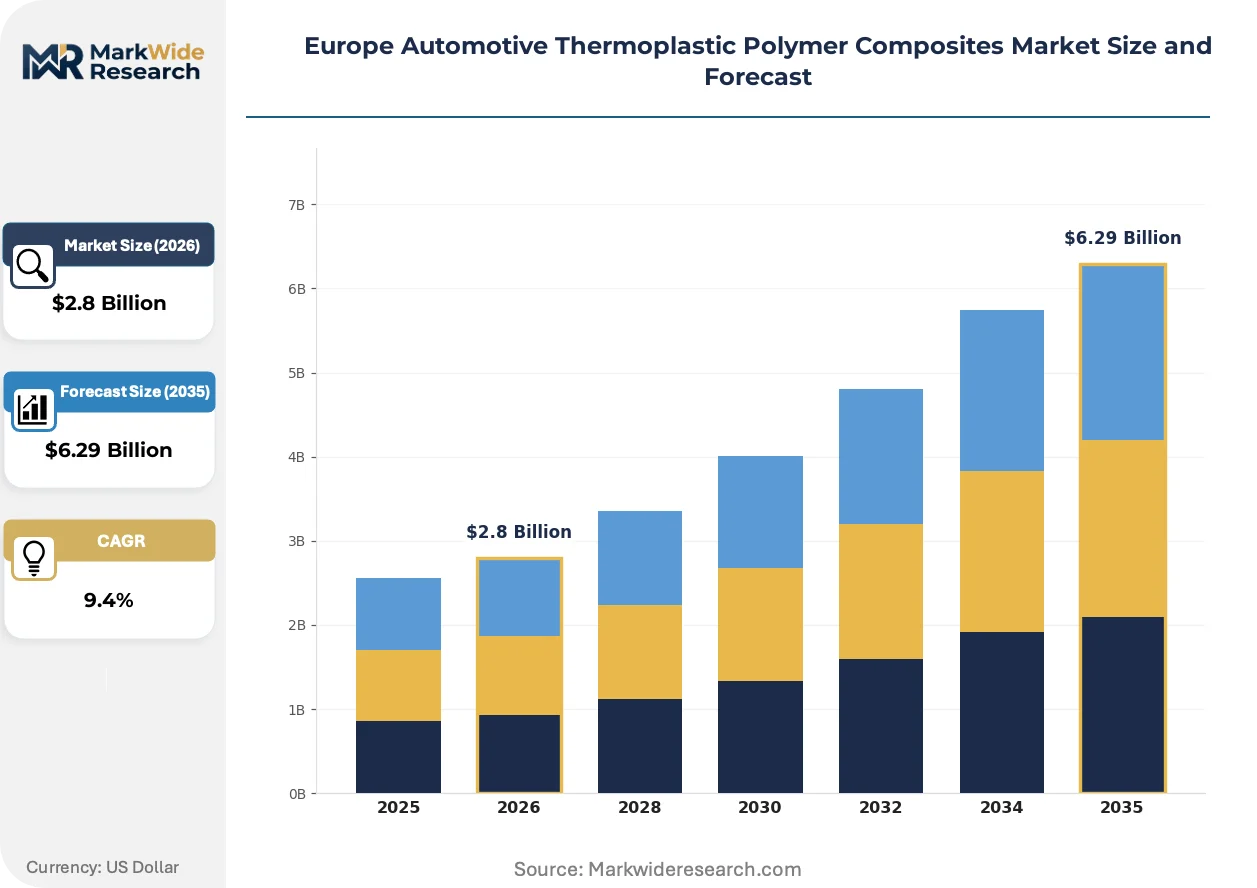
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ABS, Nylon, Polycarbonate, Polypropylene Application: Interior Components, Exterior Parts, Electrical Enclosures, Under-the-Hood End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Injection Molding, Thermoforming, Compression Molding, 3D Printing |
| Companies Covered | Arkema Group, Hexcel Corporation, BASF SE, Teijin Limited, Solvay S.A., DuPont de Nemours, SABIC, Covestro AG, Celanese Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Thermoplastic Polymer Composites Market Shifts & Advancements
Process automation and regulatory disclosure requirements are converging to reshape how thermoplastic composites move from compounder specification to OEM assembly line, with traceability and speed as competing priorities.
Continuous fiber-reinforced thermoplastic tapes are consolidating their position in structural automotive applications. BMW and Mercedes-Benz electric vehicle platforms specify these unidirectional tapes for floor pan and battery tray reinforcement. The technology is consolidating supplier tiers by eliminating separate fiber weaving and resin infusion steps, collapsing value chains that previously spanned three processing stages.
REACH authorization requirements for phthalate plasticizers are tightening formulation options across polyvinyl chloride and flexible polyamide compounds. Compounders must reformulate legacy recipes or seek alternative plasticizer chemistries. Electrical cable jacketing and interior soft-touch surfaces face the steepest compliance costs, with German OEMs already demanding pre-authorized additive packages in new RFQs.
Direct-to-OEM material specification is displacing traditional distributor-mediated procurement for engineered thermoplastic grades. Tier-1 suppliers now negotiate resin pricing and technical service directly with BASF, Covestro, and Solvay for platform-critical components. This pattern is most visible in German premium EV programs where thermal management module performance guarantees require compounder engineering involvement from concept phase.
Europe Automotive Thermoplastic Polymer Composites Market Segmentation
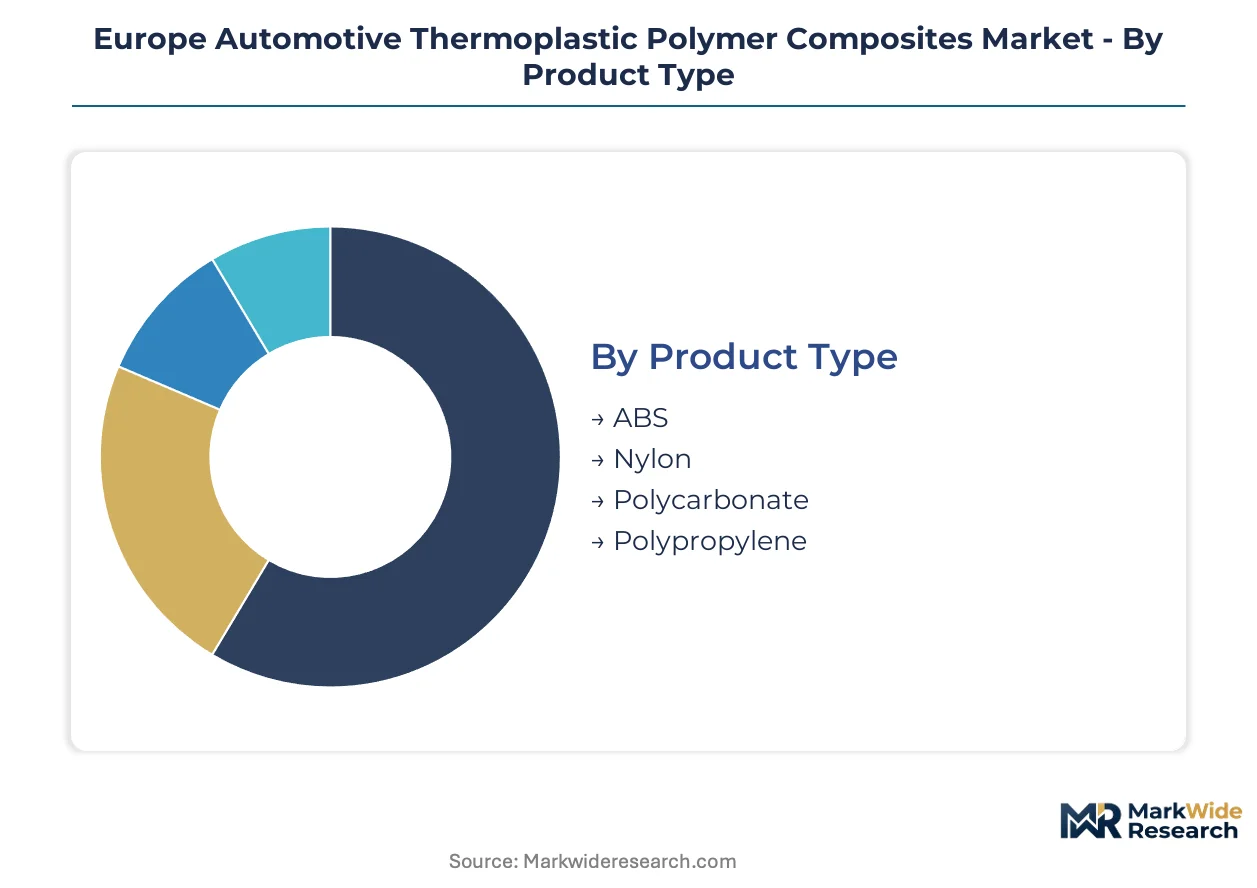
Segmentation in Europe's automotive thermoplastic composites market reveals how material specifications cascade from OEM platform decisions through converter capabilities to end-use performance requirements. Each dimension—product chemistry, application environment, procurement channel, and processing technology—creates distinct competitive arenas with different margin structures and qualification barriers.
Product Type:
Integration depth varies sharply across polymer chemistries, with some resins functioning as standalone structural materials and others requiring compounding with additives or fiber reinforcement to meet automotive specifications.
- Polypropylene:Glass-reinforced grades dominate under-the-hood mass production due to established recycling infrastructure and feedstock cost position. German OEMs specify this resin for bracketry and cooling module supports where metal substitution priorities outweigh thermal performance limits.
- Polycarbonate:Flame-retardant blends serve battery enclosure applications where dielectric isolation and thermal runaway containment meet emerging EV safety mandates. Covestro's optical-grade formulations also penetrate exterior glazing and lighting lens programs requiring impact resistance and aesthetic clarity.
- Nylon:Polyamide compounds concentrate in high-temperature powertrain zones where continuous-use thermal loads exceed polypropylene ceilings. REACH substance evaluations for certain additive packages create formulation bottlenecks extending qualification timelines.
- ABS:Acrylonitrile-butadiene-styrene systems occupy interior soft-touch and decorative trim applications where surface finish and colorability command specification priority over structural loading.
Volume placements concentrate in Polypropylene; the faster expansion belongs to Polycarbonate.
Application:
Application segmentation tracks how thermoplastic composites displace incumbent materials—metals, thermosets, and unreinforced plastics—across vehicle zones with divergent thermal, mechanical, and aesthetic requirements.
- Under-the-Hood:Thermal management modules, air intake manifolds, and cooling system housings exploit glass-reinforced polyamide and polypropylene to reduce mass while surviving engine-bay temperature cycling. Stuttgart-Munich supplier clusters capture the densest qualification activity for these programs.
- Electrical Enclosures:Battery housings, junction boxes, and high-voltage connector bodies demand flame-retardant polycarbonate and PBT blends with dielectric stability metal cannot replicate. EU battery safety regulations are accelerating specification shifts in this category.
- Exterior Parts:Fenders, tailgates, and body panels employ long-fiber-reinforced thermoplastics and thermoformed composite sheets where surface area and tooling amortization economics favor polymer over metal stamping.
- Interior Components:Dashboard carriers, door panels, and seating structures utilize glass-mat thermoplastic and injection-molded compounds to consolidate multi-part assemblies and reduce cabin weight.
Under-the-Hood commands the largest installed base; Electrical Enclosures are climbing the fastest as EV architectures proliferate.
End User:
End-user segmentation reflects procurement power concentration and technical specification authority across the automotive value chain, from OEM material science departments to aftermarket distributors.
- OEMs:Premium German manufacturers maintain direct material specification relationships with BASF, Solvay, and Covestro for platform-critical thermal management and battery enclosure programs, bypassing traditional distributor channels.
- Tier-1 Suppliers:Modular sub-assembly packagers consolidate multi-OEM demand to achieve resin volume commitments and compounding line utilization, compressing qualification timelines through platform-shared architectures.
- Vehicle Assemblers:Contract manufacturers and satellite production facilities in Eastern European corridors source pre-compounded pellets and semi-finished sheets from regional distribution hubs serving German OEM satellite plants.
- Aftermarket Providers:Collision repair and performance upgrade channels access thermoplastic composite components through specialized distributors with limited technical service capabilities compared to Tier-1 supply relationships.
Procurement volume aggregates at Tier-1 Suppliers; specification authority is concentrating most rapidly at OEMs.
Technology:
Processing technology segmentation captures how manufacturing method selection shapes part economics, performance characteristics, and supply chain configuration for composite converters.
- Injection Molding:The dominant installed base for glass-reinforced polypropylene and polyamide components, offering high-volume throughput and dimensional precision for under-the-hood and interior structural parts. Tooling lead times and capital intensity create barriers for new entrants.
- Thermoforming:Gaining share in exterior panel programs where continuous fiber-reinforced thermoplastic sheets enable larger surface areas and lower per-part tooling costs than injection molding for medium-volume vehicle platforms.
- Compression Molding:Serving structural applications with sheet molding compound and bulk molding compound formats, particularly where fiber length retention and fiber orientation control exceed injection molding capabilities.
- 3D Printing:Emerging for prototyping, tooling inserts, and low-volume customization where geometric complexity and lead time compression outweigh unit cost disadvantages versus conventional molding methods.
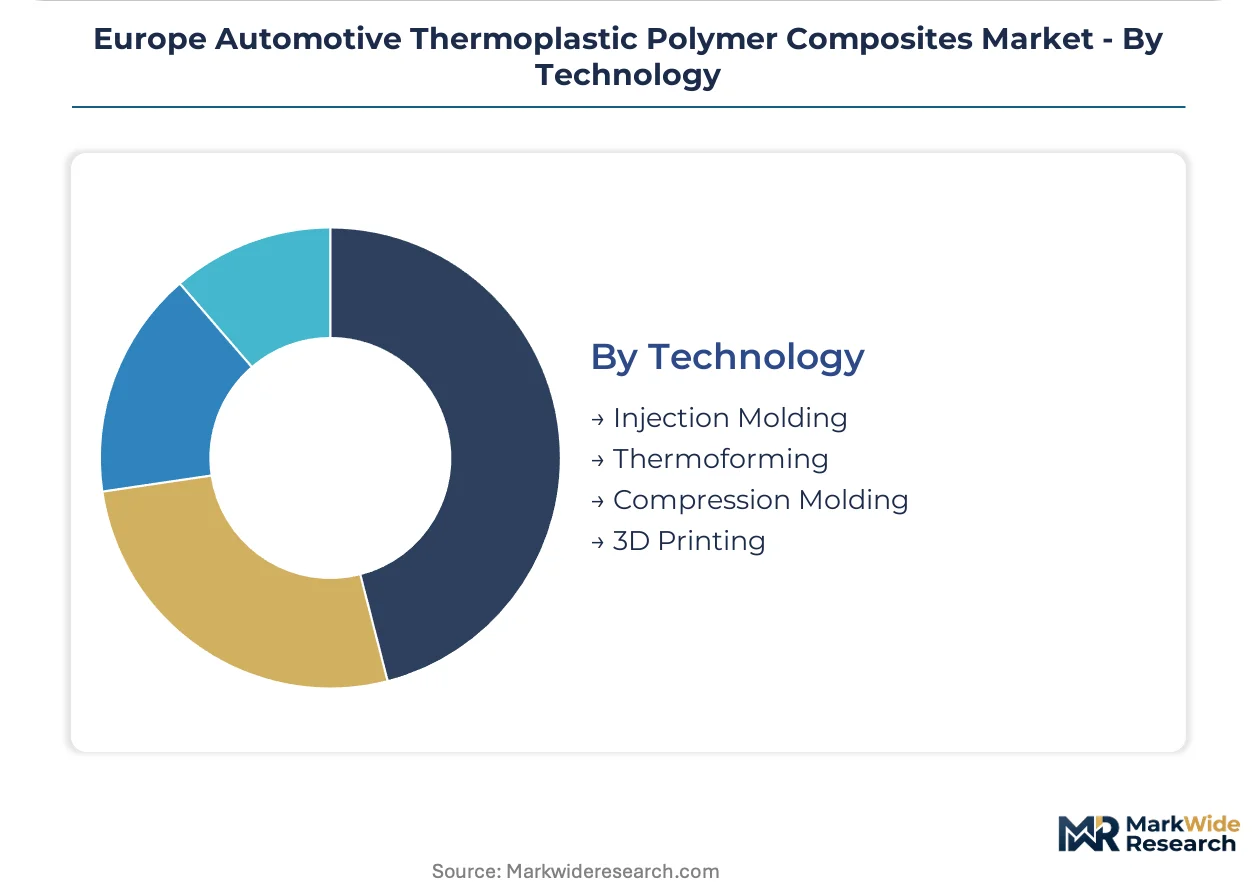
Injection Molding retains the broadest application footprint; Thermoforming is gaining share fastest in exterior programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Western Europe while Eastern European corridors absorb expanding thermoforming operations. German resin compounding and OEM technical centers anchor qualification programs. Slovak and Czech manufacturing satellites serve German OEM assembly plants with lower labor-cost structures.
Germany
Stuttgart and Munich supplier clusters host the densest concentration of composite qualification programs for German premium OEMs. The EU Green Deal's material circularity mandates accelerate converter migration from thermoset alternatives toward recyclable thermoplastic systems. Bavaria-based compounders maintain direct specification relationships with OEM material science departments for platform-critical thermal management modules.
France
Automotive polymer demand concentrates in Île-de-France and the Hauts-de-France corridor serving Renault and Stellantis technical centers. REACH authorization requirements for phthalate plasticizers force reformulation of legacy PVC and flexible polyamide compounds. Lyon-area converters specialize in flame-retardant polycarbonate blends for emerging EV battery safety standards.
Italy
Emilia-Romagna and Piedmont house Tier-1 suppliers consolidating multi-OEM material specifications for platform-shared vehicle architectures. ECHA substance evaluations create registration bottlenecks extending material approval timelines for polymer additives. Turin-based molders capture Fiat-Stellantis programs requiring glass-reinforced polypropylene for under-the-hood mass reduction.
Spain
Catalonia and the Basque Country support Volkswagen Group and Mercedes-Benz satellite production with regional distribution hubs for pre-compounded pellets. The F-Gas Regulation mandates lower-GWP process alternatives filtering material choices for compounders and molders. Barcelona-area thermoforming operations gain share in exterior panel programs serving medium-volume vehicle platforms.
Czech Republic
Automotive corridors in Moravia-Silesia and Central Bohemia absorb labor-cost-sensitive thermoforming operations from German Tier-1 suppliers. EMA carbon-footprint protocols for automotive supply chains tighten qualification thresholds for imported resin systems. Ostrava-based converters supply pre-compounded sheets to German OEM satellite plants with compressed logistics friction.
Europe Automotive Thermoplastic Polymer Composites Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across resin compounding, fiber reinforcement, and finished component manufacturing. Market structure tilts toward consolidation at the resin-compounding tier while fragmentation persists among regional molders and converters. Three archetypes dominate: integrated chemical conglomerates with captive polymer production, fiber-specialist compounders with aerospace-automotive crossover capabilities, and regional injection molders with OEM-direct qualification relationships. Capacity expansion and strategic partnerships represent the dominant competitive moves as compounders secure feedstock agreements and molders lock in platform-critical program awards.
Among integrated chemical conglomerates, BASF SE and Covestro AG anchor the European supply base with captive polyamide and polycarbonate production networks. Solvay S.A. occupies a specialist position in high-performance polymer matrices. These three represent the archetype of resin-to-part capability that Tier-1 suppliers increasingly specify for platform-shared architectures requiring compressed qualification timelines and technical service from concept phase.
| Leading Market Players |
|---|
| Arkema Group |
| Hexcel Corporation |
| BASF SE |
| Teijin Limited |
| Solvay S.A. |
| DuPont de Nemours |
| SABIC |
| Covestro AG |
| Celanese Corporation |
| Others |
Supply & Pricing Matrix
Captive resin compounding by BASF, Covestro, and Solvay anchors pricing power for European automotive thermoplastic polymer composites, locking in feedstock cost advantages that independent molders cannot replicate. This backward integration into polyamide and polycarbonate production shields integrated players from raw material volatility while compressing margins for converters dependent on merchant resin markets.
Pricing Analysis
Cost-down pressure on glass-reinforced polypropylene accelerates because German OEMs consolidate volume commitments across platform-shared architectures. Three-tier pricing structure across premium polycarbonate blends, standard polyamide compounds, and economy polypropylene grades differentiates by thermal performance ceiling and REACH compliance certification. Price erosion runs through merchant resin channels as Tier-1 suppliers negotiate direct compounder contracts. Vehicle assemblers in Eastern European corridors exhibit highest price sensitivity; premium German OEMs prioritize technical service over unit cost.
Supply Chain Analysis
REACH batch certification and EMA carbon-footprint protocols gate supply chain participation, filtering out non-compliant importers before qualification begins. Feedstock concentration centers on Germany, Belgium, and the Netherlands for polyamide and polycarbonate resin production. Carbon fiber precursor supply draws from limited non-EU sources, exposing compounders to tariff exposure. Distribution runs through Stuttgart-Munich supplier clusters for German OEM programs, with satellite hubs in Slovakia and Czech Republic serving assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
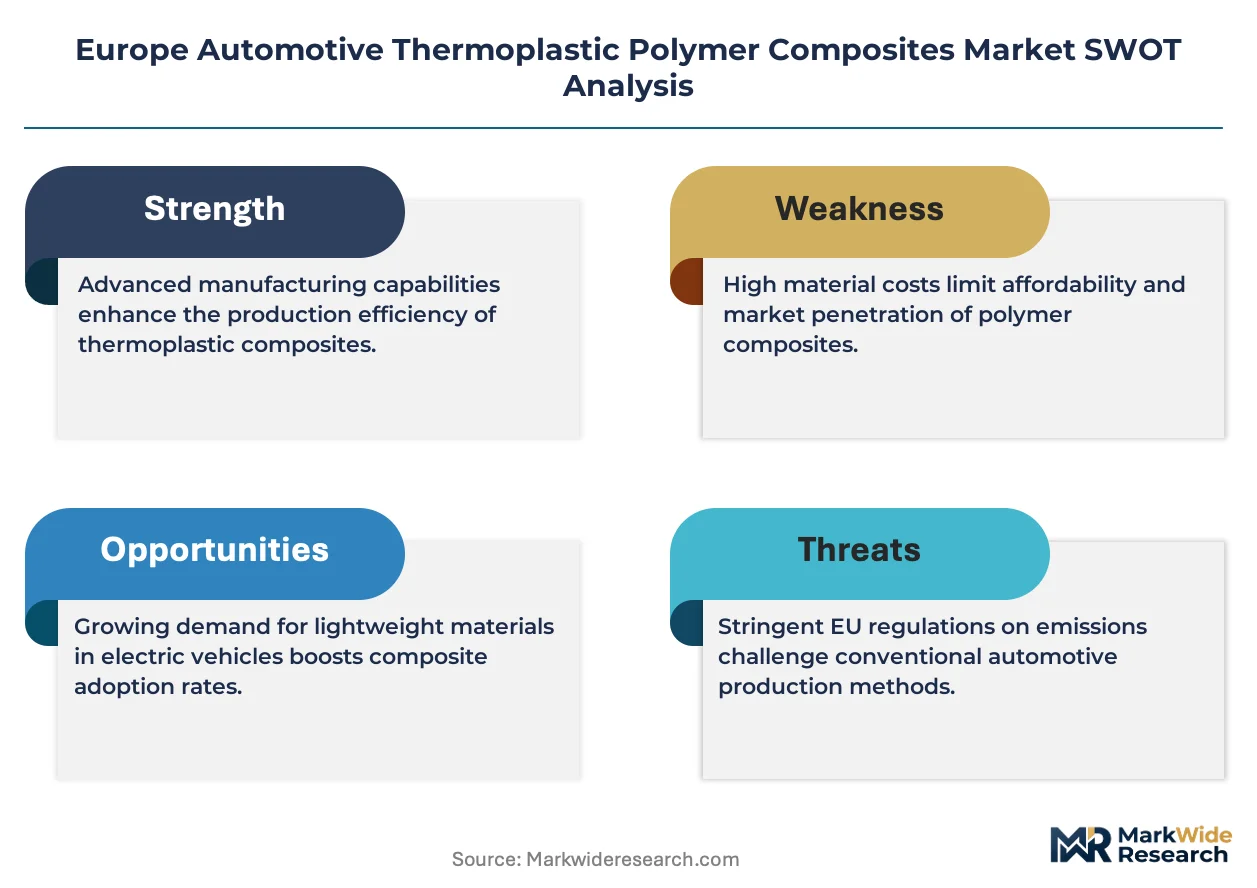
The Europe Automotive Thermoplastic Polymer Composites Market functions as a cost-of-compliance arena where REACH substance evaluations and EU Green Deal circularity mandates erect barrier-to-entry moats favoring compounders with pre-authorized additive packages and established recycling infrastructure.
For Market Incumbents: Anchor qualification relationships with German OEM material science departments through early-stage engineering involvement in platform-critical thermal management modules. Deepen backward integration into polyamide and polycarbonate resin production to defend margin position against merchant resin price volatility. Invest in EMA carbon-footprint protocol certification to secure preferred-supplier status for EU-funded fleet electrification programs. For New Entrants and Emerging Players: The premium-economy price-point gap in flame-retardant polycarbonate blends for battery enclosure applications creates entry space for specialty compounders with dielectric formulation expertise. Target electrical enclosure segments where EV safety mandates accelerate specification shifts away from incumbent metal solutions. Pursue joint development agreements with Lyon-area converters already specializing in polycarbonate thermal runaway containment systems. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated chemical conglomerates seeking resin-to-part capabilities for automotive platform consolidation. Long-term viability favors compounders with captive polymer production and direct OEM specification relationships over regional molders dependent on distributor-mediated procurement. Watch for inflection in EU AI Act audit trail mandates forcing MES system upgrades among mid-tier converters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyamide Resin Production | BASF's captive compounding network secures supply security for Stuttgart-Munich qualification programs. |
| EMA Carbon-Footprint Protocol Certification | Early alignment creates preferred-supplier positioning for EU Green Deal-funded electrification projects. |
| Direct-to-OEM Material Specification | Tier-1 suppliers bypass distributors to negotiate technical service with Covestro for premium EV platforms. |
| Eastern European Thermoforming Expansion | Slovak and Czech corridors absorb labor-cost-sensitive operations serving German OEM satellite plants. |
| Continuous Fiber-Reinforced Tape Qualification | BMW and Mercedes-Benz EV platforms specify unidirectional tapes for battery tray reinforcement applications. |
Research Methodology
Document review covered ECHA substance registration databases, EU Green Deal implementation guidelines, and automotive OEM technical specifications, complemented by interviews with resin compounding plant managers, Tier-1 supplier procurement leads, OEM platform engineers, and aftermarket distribution channel partners. Secondary validation drew from Cefic chemical industry reports, customs trade data for polymer feedstocks, and SEC filings of integrated chemical conglomerates. Bottom-up demand modeling across vehicle production platforms triangulated with top-down market sizing from resin consumption patterns.
Segmented outputs across the projection horizon reflect polymer chemistry, application environment, processing technology, and end-user procurement authority dimensions. CAGRs derived from regression analysis of historical resin pricing, vehicle platform content-per-vehicle trajectories, and regulatory compliance cost absorption rates. Model inputs incorporated EV battery enclosure thermal management requirements, REACH authorization timelines for plasticizer additives, and platform-shared architecture adoption curves among German premium OEMs.
Inputs from ECHA registration databases and OEM technical service agreements were available through the study window; gaps in real-time carbon-footprint audit data from Eastern European converters introduce uncertainty bands around supply chain emission intensity assumptions. Forecasts reflect documented assumptions regarding REACH enforcement consistency and EU Green Deal funding continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Dispersant Polymer Market
Polymers & Resins
Polystyrene Foam Market
Polymers & Resins
Global Chromatography Resin Market
Polymers & Resins
Global Bio Polyols Market
Polymers & Resins
Polyethylene Wax Market
Polymers & Resins
Global Polymerization Initiator Market
Polymers & Resins
Thermoplastic Polyimide Market
Polymers & Resins
Global Ethylene Vinyl Acetate Resins Market
Polymers & Resins
Water-Borne Resins Market
Polymers & Resins
Europe Polyolefin Foam Market
Polymers & Resins
Polystyrene Market
Polymers & Resins
United States Geopolymer Market
Polymers & Resins
PVDF Resin Market
Polymers & Resins
Polysulfide Market
Polymers & Resins
Antiviral Polymers for Packaging Market
Polymers & Resins
Global Corrosion Resistant Resin Market