
 Global Laparoscopy Devices Market | 2026-2036
Global Laparoscopy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Laparoscopy Devices Market Foresight
Aftermarket service revenue is narrowing as manufacturers bundle multi-year maintenance contracts with initial capital sales. Johnson & Johnson leverages its broad sterilization and reprocessing infrastructure to capture recurring revenue streams. Medtronic PLC anchors its position through proprietary vessel sealing platforms that lock in consumable pull-through. Karl Storz SE & Co. KG specializes in rigid optical systems for academic medical centers with high procedural volume.
Laparoscopy devices are minimally invasive surgical instruments—typically 5-10 mm in diameter—inserted through abdominal wall trocars to enable internal visualization and tissue manipulation without open incision, primarily to reduce patient recovery time and surgical site infection risk. Electrosurgical devices carry the deepest margin pools due to disposable electrode dependence and premium pricing on advanced bipolar systems. High-definition imaging and 3D visualization technologies are displacing standard-definition platforms in teaching hospitals where depth perception directly correlates with training outcomes and credentialing standards.
FDA 510(k) premarket notification governs device clearance in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements and unique device identification mandates that reshape product registration costs. Japan's PMDA and METI coordinate on software-as-medical-device classifications that increasingly capture AI-enhanced laparoscopic guidance systems. Stakeholders must monitor how divergent cybersecurity requirements across FDA, MDR, and PMDA jurisdictions fragment product architecture and compliance spending.
Market Dynamics
The laparoscopy devices market is restructuring around disposable-to-reusable instrument economics, where hospital procurement committees now weight total cost of ownership against per-procedure pricing in capital allocation decisions.
Growth Catalysts
- EU MDR compliance deadlines:Stricter clinical evidence requirements under the EU Medical Device Regulation are accelerating hospital replacement cycles for legacy instruments that cannot meet enhanced safety documentation standards.
- India's PLI scheme for medical devices:Production-linked incentives for domestic manufacturing are drawing component suppliers to Gujarat and Tamil Nadu, reducing import dependency for trocars and graspers.
- Single-port robotic platforms:Next-generation surgical systems enabling single-incision procedures are expanding addressable procedure volumes in gynecology and urology beyond traditional multi-port applications.
Market Restraints
- Stainless steel price volatility:Fluctuations in nickel and chromium input costs compress margin predictability for reusable instrument manufacturers operating on fixed hospital contract terms.
- German sterilization infrastructure concentration:Centralized reprocessing capacity in Baden-Württemberg and Bavaria creates geographic supply risk for reusable device-dependent hospital networks.
- Optical fiber technical limitations:Image degradation in flexible scopes beyond 10,000 sterilization cycles constrains true lifetime cost advantages against disposable alternatives.
Strategic Opportunities
- Brazil's ANVISA fast-track pathway:Expedited approval channels for devices with prior FDA or CE marking enable accelerated market entry into Latin America's largest private hospital sector.
- Augmented reality visualization convergence:Integration of heads-up displays with laparoscopic cameras creates premium pricing tiers for academic medical centers training surgical residents.
- Direct-to-hospital digital procurement:Manufacturer-owned e-commerce platforms bypass distributor markups in Australia's consolidated private hospital market dominated by Ramsay Health Care and Healthscope.
Industry Challenges
- Reprocessing technician certification gaps:Shortages of certified sterile processing staff in the United Kingdom delay instrument turnaround times and constrain surgical schedule density.
- Legacy camera system integration:Hospital IT departments struggle to interface new 4K visualization towers with existing picture archiving infrastructure without complete network overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Laparoscopy Devices Market |
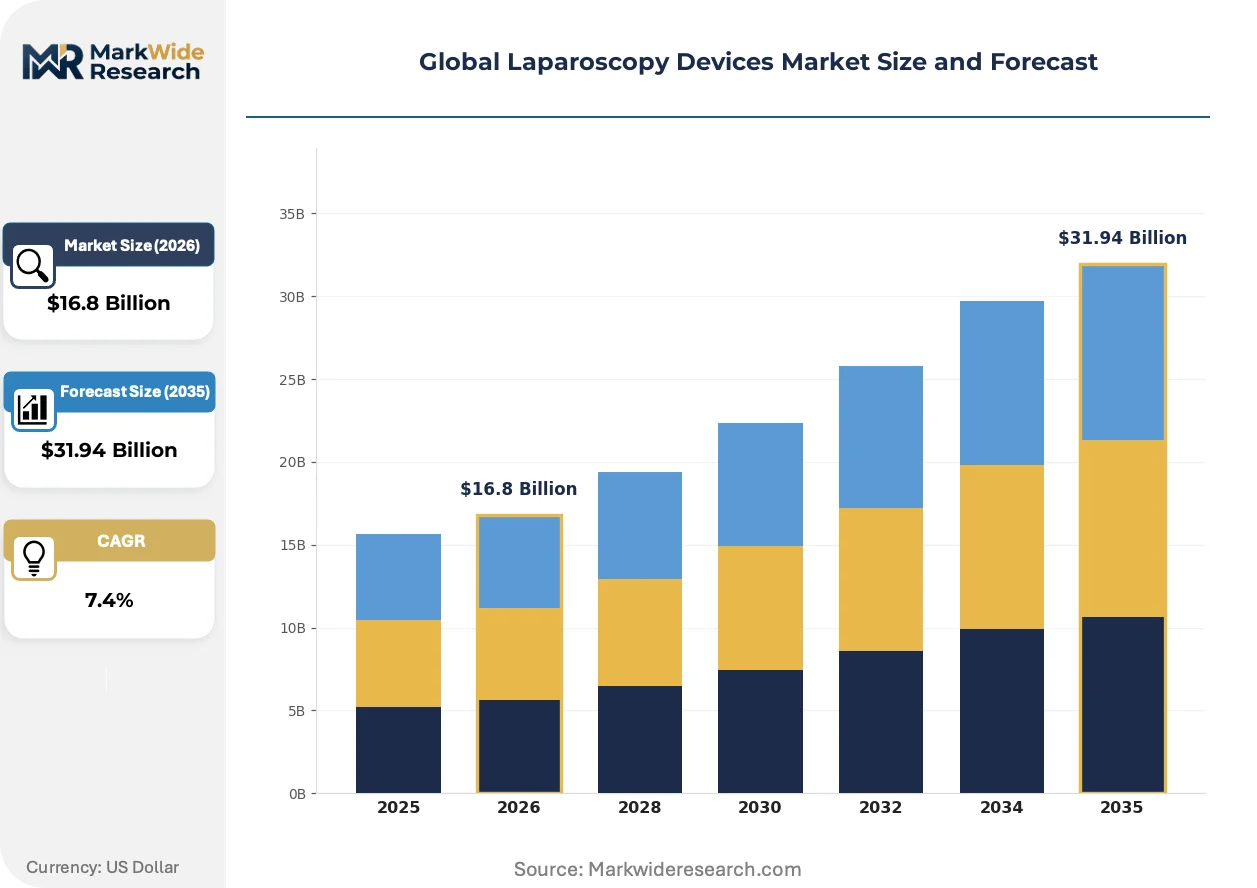
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $31.94 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laparoscopes, Electrosurgical Devices, Insufflators, Accessories Technology: Rigid Endoscopy, Flexible Endoscopy, High-Definition Imaging, 3D Visualization Application: Gynecological Procedures, Urological Procedures, General Surgery, Thoracic Surgery, Bariatric Surgery End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions |
| Companies Covered | Johnson & Johnson, Intuitive Surgical Inc., Medtronic PLC, Boston Scientific Corporation, B. Braun Melsungen AG, Olympus Corporation, Karl Storz SE & Co. KG, CONMED Corporation, Stryker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Laparoscopy Devices Market Shifts & Advancements
Technological trajectories in laparoscopy are converging on enhanced visualization fidelity and procedural autonomy, with hardware-software integration replacing standalone instrument sales as the primary value capture mechanism.
4K ultra-high-definition camera systems is migrating from early-adopter academic centers in the United States and Germany toward standard-of-care requirements in Japan's university hospitals. Surgical departments in Tokyo and Osaka now specify 4K resolution as mandatory for credentialing fellowship programs, compressing demand for standard-definition platforms into price-sensitive community hospital segments.
Japan's PMDA software-as-medical-device framework is reclassifying AI-enhanced image guidance systems as regulated products requiring standalone clinical validation. Manufacturers must now submit algorithm performance data separate from hardware clearances, extending registration timelines for computer-assisted suturing and anatomy recognition modules.
Hospital procurement committees in India's tier-1 cities are consolidating vendor relationships through multi-year managed service agreements that bundle instrument supply, maintenance, and training. Fortis Healthcare and Apollo Hospitals now negotiate enterprise-level contracts covering entire surgical device portfolios, displacing the traditional per-procedure purchasing model that dominated the 2010s.
Global Laparoscopy Devices Market Segmentation
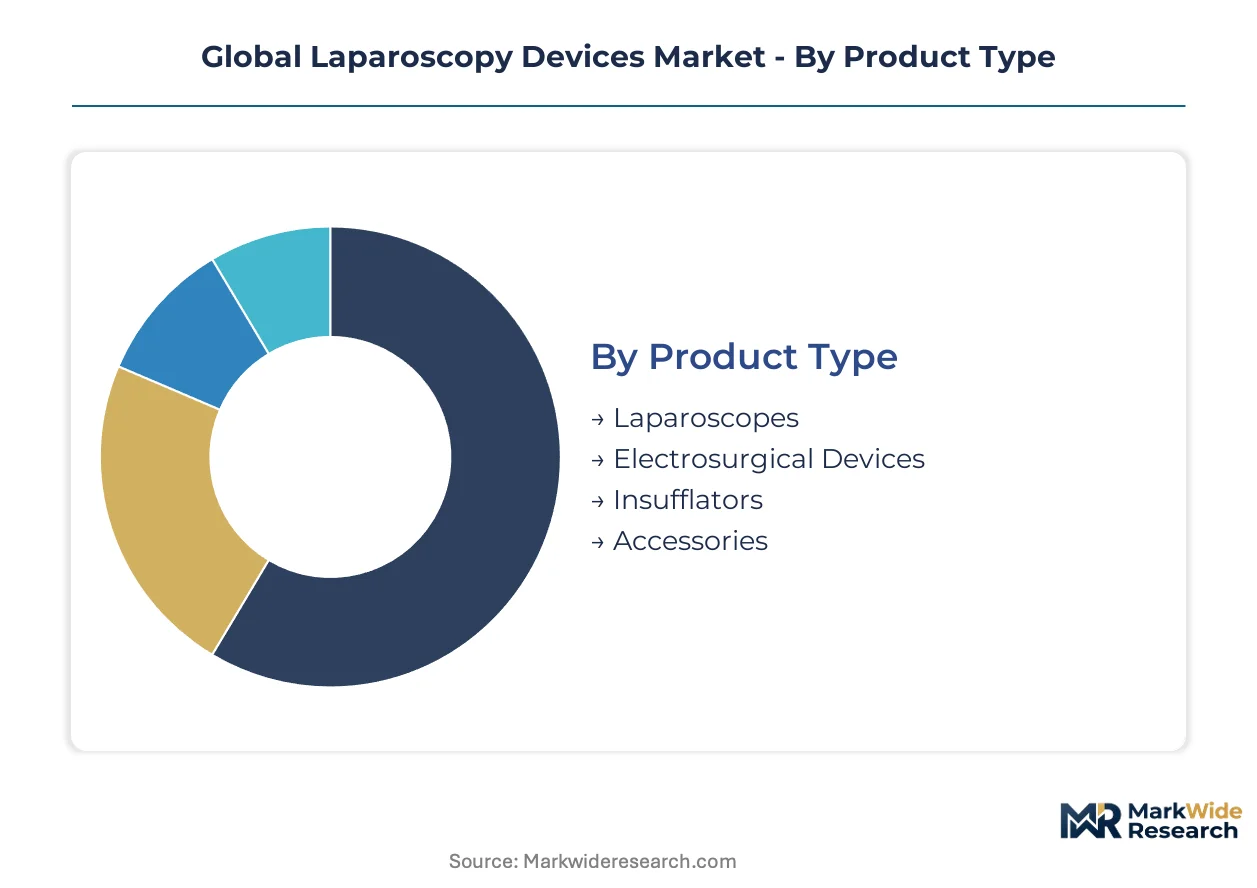
Segmentation in laparoscopy devices reveals how procurement priorities diverge across surgical settings and technology tiers. Hospital capital committees evaluate total cost of ownership differently than ambulatory centers focused on per-procedure economics. Understanding these fault lines enables targeted positioning against specific buyer value equations.
Product Type:
Cost tier differentiation separates premium integrated platforms from commoditized single-use components, with margin capture varying dramatically across the spectrum.
- Laparoscopes:Rigid optical systems with rod-lens or CMOS sensor architectures deliver visualization through 5-12 mm working channels. German university hospitals in Heidelberg and Munich now specify 4K resolution as standard for credentialing programs, displacing standard-definition inventory into secondary markets.
- Electrosurgical Devices:Bipolar vessel sealing systems and monopolar cautery instruments generate recurring consumable revenue through electrode dependence. India's Apollo Hospitals and Fortis Healthcare negotiate enterprise contracts bundling generator capital with multi-year electrode supply commitments.
- Insufflators:Carbon dioxide delivery systems maintain pneumoperitoneum pressure between 12-15 mmHg during procedures.
- Accessories:Trocars, graspers, and clip appliers complete instrument sets for specific surgical approaches.
Laparoscopes command the established base. The steepest expansion runs through electrosurgical devices.
Technology:
Application requirements in teaching versus community settings drive technology adoption velocity, with depth perception and image fidelity serving as the primary differentiators.
- Rigid Endoscopy:Straight-line optical systems dominate abdominal and pelvic procedures requiring stable instrument triangulation. Japanese academic centers in Tokyo and Osaka specify rigid 4K platforms for fellowship credentialing, compressing demand for lower-resolution alternatives into price-sensitive segments.
- 3D Visualization:Stereoscopic camera systems restore depth perception lost in conventional 2D laparoscopy, directly impacting suturing precision and training outcomes. Surgical residency programs in the United States and Germany now mandate 3D capability for minimally invasive curriculum accreditation.
- Flexible Endoscopy:Articulating scopes enable navigation around anatomical structures in bariatric and thoracic applications.
- High-Definition Imaging:1080p resolution platforms serve as the cost-optimized standard for high-volume community hospitals.
Rigid endoscopy anchors current installed base. The steepest expansion trajectory belongs to 3D visualization.
Application:
Procedure volume concentration and reimbursement levels determine capital allocation priority across surgical specialties.
- General Surgery:Cholecystectomy, appendectomy, and hernia repair constitute the highest-volume laparoscopic applications globally. Hospital networks in India's tier-1 cities—Mumbai, Delhi, Bangalore—have centralized general surgery capacity into dedicated minimally invasive units with standardized instrument platforms.
- Gynecological Procedures:Hysterectomy, myomectomy, and endometriosis excision drive specialized instrument demand including uterine manipulators and bipolar sealing devices. Private hospital chains in Brazil's São Paulo and Rio de Janeiro states have built dedicated gynecology surgical centers with single-port capability.
- Urological Procedures:Prostatectomy and nephrectomy applications require extended instrument reach and precision cautery control.
- Bariatric Surgery:Gastric bypass and sleeve procedures demand reinforced trocars and extended-length graspers for morbidly obese patient populations.
- Thoracic Surgery:Lung resection and mediastinal procedures utilize specialized angled scopes and vascular stapling systems.
General surgery commands the established base. The steepest expansion runs through gynecological procedures.
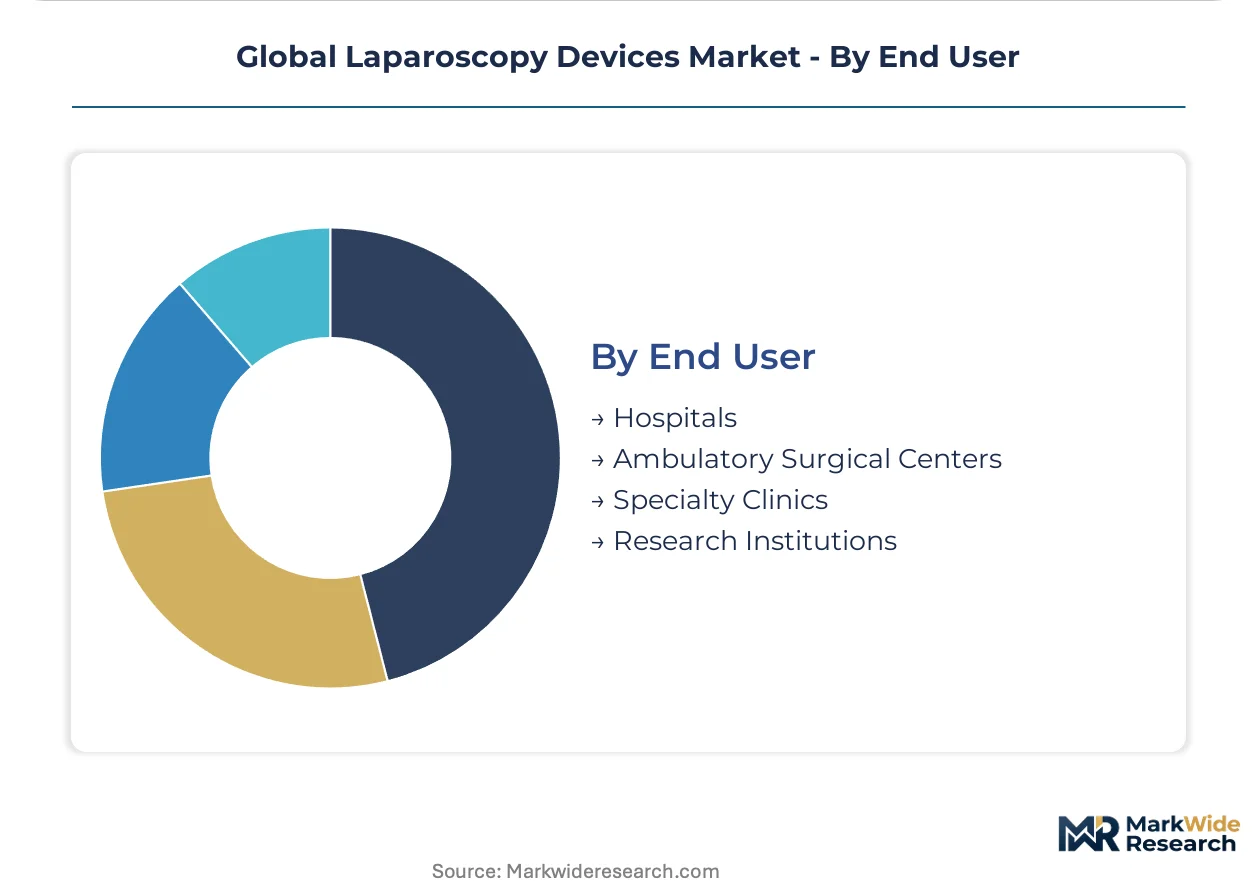
End User:
Customer type dictates procurement sophistication, contract structure, and service integration requirements across the care continuum.
- Hospitals:Integrated delivery networks with centralized sterile processing infrastructure favor reusable instrument economics and multi-year managed service agreements. Germany's Baden-Württemberg and Bavaria hospital clusters concentrate reprocessing capacity, creating geographic supply dependencies for reusable device-dependent networks.
- Ambulatory Surgical Centers:Freestanding facilities prioritize instrument turnaround speed and disposable alternatives to eliminate reprocessing bottlenecks. Australia's Ramsay Health Care and Healthscope facilities have adopted direct-to-hospital digital procurement platforms bypassing traditional distributor markups.
- Specialty Clinics:Focused gynecology and urology practices require procedure-specific instrument sets with lower capital thresholds.
- Research Institutions:Academic medical centers drive early adoption of 4K, 3D, and AI-enhanced visualization platforms for training and credentialing standard-setting.
Hospitals command the established base. The steepest expansion runs through ambulatory surgical centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's tier-1 hospital chains exhibit the highest price elasticity for standard-definition laparoscopes, while Japan's university hospitals show inelastic demand for 4K and 3D visualization platforms required for credentialing.
United States
Ambulatory surgical centers in Texas and Florida are consolidating procurement through direct-to-hospital digital platforms, bypassing traditional distributor networks. FDA 510(k) premarket notification pathways compress product development timelines for instrument manufacturers. Greater Boston's academic medical clusters drive early adoption of AI-enhanced image guidance systems for residency training programs.
Germany
Hospital networks in Baden-Württemberg and Bavaria are expanding minimally invasive surgical programs with centralized sterile processing infrastructure. EU Medical Device Regulation compliance deadlines accelerate replacement cycles for legacy instruments lacking enhanced safety documentation. Heidelberg and Munich university hospitals now specify 4K resolution as mandatory for credentialing programs, displacing older inventory.
Japan
Tokyo and Osaka surgical departments specify 4K resolution as mandatory for fellowship credentialing, compressing demand for standard-definition platforms. METI and PMDA coordinate on software-as-medical-device classifications capturing AI-enhanced laparoscopic guidance systems. Kanto region academic centers drive premium-tier visualization adoption with depth-perception requirements for training outcomes.
India
Private hospital chains in Mumbai, Delhi, and Bangalore build dedicated endoscopy centers with enterprise-level managed service agreements. CDSCO regulatory pathways and PLI scheme incentives for domestic manufacturing draw component suppliers to Gujarat and Tamil Nadu. Apollo Hospitals and Fortis Healthcare negotiate multi-year contracts bundling instrument supply, maintenance, and training across surgical portfolios.
Brazil
Private hospital chains in São Paulo and Rio de Janeiro states construct dedicated gynecology surgical centers with single-port capability. ANVISA fast-track approval channels for devices with prior FDA or CE marking accelerate market entry into Latin America's largest private hospital sector. Southeast regional networks prioritize disposable instrument economics to eliminate reprocessing bottlenecks in high-volume facilities.
Global Laparoscopy Devices Market Competitive Landscape
Capability concentration sits with integrated platform developers; scale advantage sits with diversified medical technology conglomerates. The market structures around three tiers: premium visualization specialists, electrosurgical platform anchors, and disposable instrument commoditizers. Strategic archetypes include hardware-software integrators capturing recurring revenue through consumable lock-in, and sterilization infrastructure operators bundling multi-year service contracts. Dominant competitive moves encompass proprietary vessel sealing ecosystems that anchor consumable pull-through, and backward integration into optical component manufacturing.
Among diversified medical technology conglomerates, Johnson & Johnson and Medtronic PLC occupy positions defined by sterilization infrastructure and proprietary energy platforms respectively. Karl Storz SE & Co. KG exemplifies the rigid optical systems specialist archetype serving high-procedure-volume academic centers. These three entities represent distinct competitive vectors: recurring revenue capture through service bundling, consumable-dependent platform economics, and premium visualization technology for credentialing-dependent institutions.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Intuitive Surgical Inc. |
| Medtronic PLC |
| Boston Scientific Corporation |
| B. Braun Melsungen AG |
| Olympus Corporation |
| Karl Storz SE & Co. KG |
| CONMED Corporation |
| Stryker Corporation |
| Others |
Supply & Pricing Matrix
Undercapacity in German sterilization infrastructure concentrates reprocessing capacity in Baden-Württemberg and Bavaria, driving hospital networks toward bundled service contracts that embed pricing power with manufacturers possessing captive sterilization assets. This utilization squeeze forces procurement committees to weight total cost of ownership against per-procedure pricing in capital allocation decisions.
Pricing Analysis
After-sales revenue through multi-year maintenance contracts and electrode consumables drives lifetime value capture for manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates 4K visualization platforms with AI guidance from standard-definition systems and commodity disposables. Cost compression in standard-definition laparoscopes is intensifying because Indian tier-1 hospital chains negotiate enterprise-level managed service agreements. Ambulatory surgical centers in Australia and Brazil exhibit highest price sensitivity due to disposable instrument economics, while Japanese university hospitals show lowest sensitivity given mandatory 4K credentialing requirements.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for component sourcing. Manufacturing concentration rests on Germany for rigid optical systems, China for CMOS sensors and electronic subassemblies, and India for trocars and graspers under PLI scheme incentives. Nickel and chromium price volatility for stainless steel instruments creates margin unpredictability for reusable device manufacturers. Distribution runs through hospital procurement committees in consolidated networks, direct-to-hospital digital platforms in Australia's private hospital sector, and traditional distributor channels in fragmented Latin American markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as procedure volume disperses from centralized academic centers toward ambulatory surgical centers and specialty clinics, creating niche positioning openings for focused equipment suppliers and service providers.
For Market Incumbents: Build consumable lock-in moats through proprietary vessel sealing ecosystems that anchor electrode pull-through revenue. Deepen backward integration into optical component manufacturing to secure CMOS sensor supply against Asian foundry concentration. Invest in sterilization infrastructure capacity additions in Germany's hospital clusters to capture multi-year service contract bundling opportunities. FDA 510(k) pathway expertise serves as a defensive certification investment against EU MDR compliance delays affecting competitors. For New Entrants and Emerging Players: Establish a beachhead in Brazil's ANVISA fast-track pathway by leveraging prior FDA or CE marking for accelerated market entry into São Paulo and Rio de Janeiro private hospital networks. Target India's tier-2 and tier-3 cities where domestic manufacturing under PLI schemes reduces import dependency and creates cost-competitive positioning against established multinationals. Direct-to-hospital digital procurement platforms offer a go-to-market angle in Australia's consolidated private hospital sector dominated by Ramsay Health Care and Healthscope. For Investors and Strategic Acquirers: Capital is best deployed toward sterilization infrastructure operators and AI-enhanced visualization software developers with standalone PMDA validation pathways. Long-term viability over the next decade hinges on regulatory navigation capabilities across FDA, EU MDR, and Japan's software-as-medical-device frameworks. The signal to watch is ANVISA approval velocity for devices with existing FDA clearance, indicating Latin American market access momentum.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Compliance Pathway | Accelerates hospital replacement cycles for legacy instruments lacking enhanced safety documentation in Heidelberg and Munich clusters. |
| Software-as-Medical-Device Validation | Japan's PMDA framework reclassifies AI guidance systems, extending registration timelines for computer-assisted suturing modules. |
| Hospital System Partnership | Apollo Hospitals and Fortis Healthcare negotiate enterprise contracts bundling instrument supply with maintenance across surgical portfolios. |
| Reimbursement Strategy | Japan's fellowship credentialing mandates for 4K visualization create institutional purchasing requirements with limited price elasticity. |
| Domestic Manufacturing Scale-Up | India's PLI scheme draws component suppliers to Gujarat and Tamil Nadu, reducing import dependency for trocars and graspers. |
Research Methodology
Desk research of FDA 510(k) filings, EU MDR technical documentation, and hospital procurement databases preceded structured interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and sterile processing department heads. Secondary validation drew from PMDA software classification guidance, CDSCO regulatory circulars, and ANVISA fast-track pathway records. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation anchored market sizing across the analysis window.
Assumptions held fixed include regulatory pathway timelines for FDA 510(k) and EU MDR compliance, while variables spanned stainless steel input cost trajectories and PLI scheme incentive continuity in India. Segmentation dimensions modeled encompass product type, technology tier, application specialty, and end-user setting with geographic regulatory cluster differentiation. CAGRs were derived from installed base replacement cycles and procedure volume expansion trajectories, incorporating AI-enhanced visualization adoption curves and single-port platform penetration rates in gynecology and urology.
Stress conditions across nickel and chromium price volatility, EU MDR documentation requirements, and Japanese software validation timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding hospital capital budget continuity and ambulatory surgical center accreditation expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Orthodontic Equipment Market
Medical Devices
Middle East and Africa Medical Device Reprocessing Market
Medical Devices
Artificial Ventilation and Anesthesia Masks Market
Medical Devices
Global Digital Therapeutic Devices Market
Medical Devices
Diabetes Devices Market
Medical Devices
Benign Prostatic Hyperplasia (BPH) Treatment Devices Market
Medical Devices
Enteral Stents Market
Medical Devices
Infant Oxygen Hoods Market
Medical Devices
Metered Dose Squeeze Dispenser Market
Medical Devices
Global Stereotaxic Instrument Market
Medical Devices
Breast Localization System Market
Medical Devices
Transcranial Doppler Ultrasounds System Market
Medical Devices
Asia-Pacific Bathroom and Toilet Assist Devices Market
Medical Devices
Pre-Filled Hemostasis Agents Market
Medical Devices
Intervertebral Implants Market
Medical Devices
Asia Pacific Hearing Aids Market