
 Robotic Catheterization Systems Market | 2026-2036
Robotic Catheterization Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Robotic Catheterization Systems Market Outlook
German precision engineering capacity is broadening the supplier base for electromechanical catheter platforms. Siemens Healthineers leverages its imaging heritage to integrate robotics with real-time fluoroscopy. Stereotaxis anchors the magnetic navigation segment with dedicated cardiac ablation systems. Robocath competes through compact, mobile robotic units designed for cath lab deployment.
Robotic catheterization systems are computer-assisted electromechanical platforms that translate operator hand motions into precise, filtered instrument movements inside the vascular network, typically achieving sub-millimeter positioning accuracy while reducing radiation exposure to clinical staff. These systems serve primarily to enhance procedural reproducibility in complex endovascular interventions where manual catheter manipulation faces anatomical constraints. Electromechanical systems currently occupy the largest installed base due to their proven torque response and haptic feedback architectures. Software control capabilities represent the fastest-expanding segment as artificial intelligence algorithms enable autonomous catheter navigation and predictive motion compensation. Remote systems are gaining traction in health systems pursuing hub-and-spoke models for specialist coverage across distributed hospital networks.
FDA premarket notification requirements and EU MDR technical documentation obligations impose substantial clinical validation burdens on manufacturers seeking commercial access. The EPA and OSHA frameworks governing cath lab radiation safety further influence system design priorities around shielding and operator distance protocols. Stakeholders must monitor evolving reimbursement determinations from CMS and parallel national health technology assessment bodies, as coverage decisions for robotic-assisted procedures will shape capital deployment cycles and regional adoption trajectories.
Market Dynamics
Precision requirements in electrophysiology procedures are compressing operator tolerance thresholds, forcing cath labs to reevaluate manual catheter platforms against robotic alternatives that filter physiological tremor and deliver sub-millimeter positioning repeatability.
Growth Catalysts
- FDA 510(k) clearance streamlining:Expedited review pathways for robotic surgical devices with predicate device claims are compressing time-to-market for second-generation electromechanical platforms. This accelerates capital refresh cycles in US cardiac centers.
- Electrophysiology procedure volume expansion:Atrial fibrillation ablation caseloads are climbing across tertiary cardiac centers, creating throughput pressure that robotic systems address through reduced fluoroscopy time and standardized catheter manipulation.
- German precision component supply:Bavarian electromechanical suppliers are scaling torque sensor and miniature motor production, broadening the vendor base for catheter platform manufacturers beyond single-source dependencies.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and samarium cobalt sourcing for magnetic navigation systems clusters with Chinese processors, exposing Stereotaxis-dependent installations to export control volatility.
- EU MDR technical documentation burden:Clinical evidence requirements for Class III robotic surgical devices are extending conformity assessment timelines by 18-24 months for manufacturers without legacy device predicates.
- Manual catheter cost anchoring:Disposable manual catheter ASPs below $200 create procurement inertia against robotic capital outlays exceeding $800,000 per installation, particularly in budget-constrained community hospitals.
Strategic Opportunities
- Hub-and-spoke telepresence deployment:Remote robotic catheterization enables specialist coverage across distributed Japanese prefectural hospitals where electrophysiologist density falls below metropolitan standards.
- AI navigation algorithm integration:Machine learning trajectory prediction converging with real-time impedance mapping is opening autonomous catheter steering applications in complex arrhythmia substrates.
- CMS transitional pass-through payments:New technology add-on payment designation for robotic-assisted cardiac procedures creates reimbursement visibility for US hospital capital committees evaluating platform acquisition.
Industry Challenges
- Cross-disciplinary training pipelines:Electrophysiologists must master robotic console operation alongside traditional manual skills, extending credentialing timelines and creating temporary productivity dips during transition periods.
- Legacy imaging system interoperability:Robotic platform integration with installed fluoroscopy and intracardiac echocardiography infrastructure requires custom interface development, complicating deployment in retrofit cath lab environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotic Catheterization Systems Market |
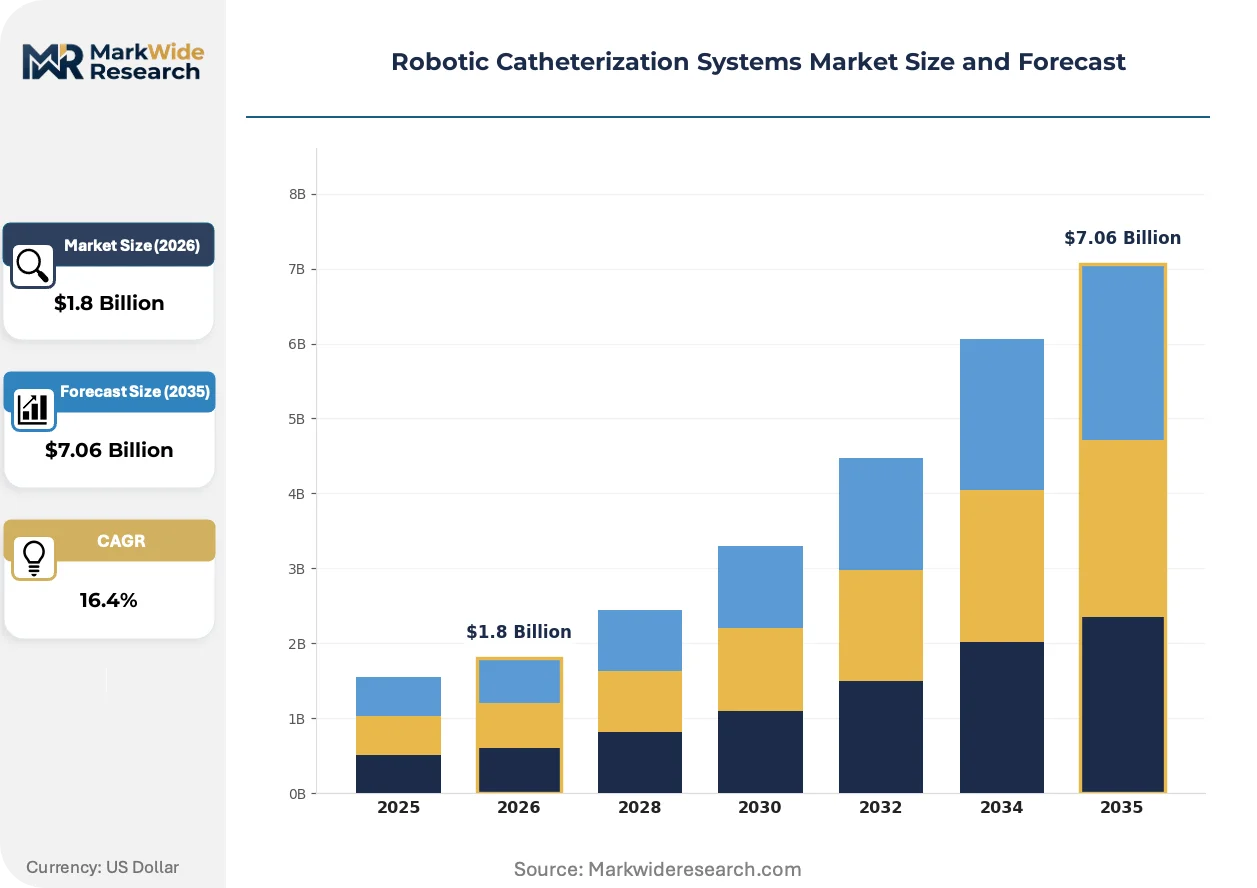
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steerable Systems, Remote Systems, Semi-Automated Systems, Manual Systems End User: Cardiac Centers, Surgical Hospitals, Research Institutions, Specialty Clinics Technology: Electromechanical Systems, Robotic Assistance, Imaging Integration, Software Control Application: Electrophysiology, Interventional Cardiology, Vascular Surgery, Neurovascular Procedures |
| Companies Covered | Siemens Healthineers, Stereotaxis, Robocath, Microbot Medical, Intuitive Surgical, Medtronic, Boston Scientific, Abbott Laboratories, Philips Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotic Catheterization Systems Market Strategic Shifts
Artificial intelligence architectures are penetrating catheter navigation workflows, compressing the boundary between operator intent and instrument response while regulatory frameworks scramble to keep pace with autonomous decision-making capabilities.
Haptic feedback systems are absorbing operator physiological noise through force-sensing sheath mechanisms and filtered motion scaling. Academic medical centers in the United States are deploying these platforms for complex ventricular tachycardia ablations where manual torque transmission fails. The technology is absorbing procedural variability that previously required case-by-case operator adaptation, standardizing outcomes across experience levels.
EU MDR post-market surveillance requirements are mandating systematic clinical follow-up for robotic catheter systems with implanted components. Manufacturers must establish European authorized representatives and maintain periodic safety update reports across all member states where devices are marketed. The regulation is forcing magnetic navigation specialists to expand EU clinical affairs headcount and restructure quality management systems around risk-classification documentation.
Academic medical centers are consolidating robotic catheter procurement through shared service agreements that pool utilization across multiple hospital sites. Purchasing committees now evaluate total cost-per-procedure rather than capital expenditure alone, favoring vendors with transparent disposable pricing and training commitment structures. This behavioral shift is most pronounced in German university hospital networks where joint procurement vehicles cover cath labs across three or more affiliated facilities.
Robotic Catheterization Systems Market Segmentation
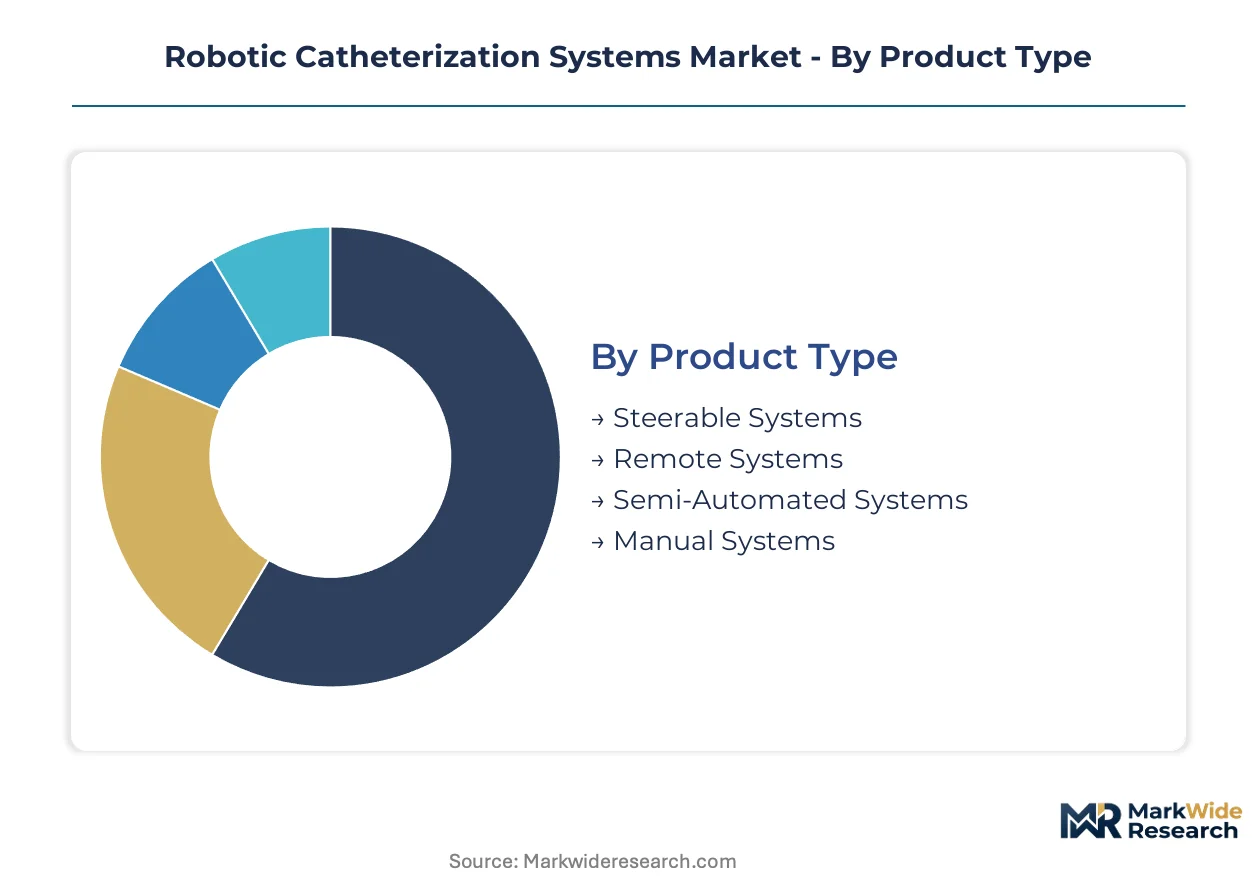
Procurement committees in cardiac centers evaluate robotic catheterization platforms through multiple lenses simultaneously. Product architecture determines capital outlay magnitude while end-user setting shapes utilization economics and training requirements. Technology maturity and application complexity further stratify vendor positioning across the installed base.
Product Type:
Capital allocation cycles in US cardiac centers favor platforms that balance precision gains against throughput economics and staff retraining burdens.
- Steerable Systems:Electromechanical catheter platforms with torque-responsive sheath mechanisms and filtered motion scaling achieve sub-millimeter positioning accuracy. Demand concentrates in German university hospital networks where joint procurement vehicles pool utilization across three or more affiliated facilities, driven by standardization mandates for complex ventricular tachycardia ablations.
- Remote Systems:Telepresence-enabled consoles allow electrophysiologist operation from shielded control rooms or distributed hospital sites. Japanese prefectural hospitals deploy these where specialist density falls below metropolitan standards, addressing hub-and-spoke coverage gaps through real-time procedural collaboration.
- Semi-Automated Systems:Hybrid platforms combining operator intent with algorithmic trajectory assistance reduce fluoroscopy exposure.
- Manual Systems:Traditional catheter manipulation without electromechanical intermediation persists in budget-constrained community settings.
Volume sits with Steerable Systems; growth tilts toward Remote Systems.
End User:
Reimbursement visibility and procedure complexity determine site-level adoption velocity across facility types.
- Cardiac Centers:Tertiary electrophysiology programs with high atrial fibrillation ablation caseloads drive platform utilization. These sites in the United States prioritize FDA 510(k)-cleared systems with CMS new technology add-on payment designation, compressing capital committee evaluation timelines.
- Surgical Hospitals:General acute care facilities with mixed service lines face procurement inertia against robotic capital outlays exceeding $800,000.
- Research Institutions:Academic medical centers absorb procedural variability through haptic feedback deployment for operator training and outcomes standardization.
- Specialty Clinics:Ambulatory settings with focused interventional services concentrate on compact, mobile robotic units.
Revenue concentrates in Cardiac Centers; Specialty Clinics are expanding most quickly.
Technology:
Intellectual property positioning around navigation algorithms and imaging fusion separates vendor tiers.
- Electromechanical Systems:Proven torque response architectures with haptic feedback occupy the largest installed base. Bavarian electromechanical suppliers scale torque sensor and miniature motor production, broadening vendor options beyond single-source dependencies.
- Robotic Assistance:Magnetic navigation platforms depend on neodymium and samarium cobalt sourcing concentrated with Chinese processors, exposing installations to export control volatility.
- Imaging Integration:Real-time fluoroscopy fusion with robotic catheter positioning requires custom interface development for legacy infrastructure.
- Software Control:Machine learning trajectory prediction converging with impedance mapping enables autonomous catheter steering.
Installed base dominance rests with Electromechanical Systems; Software Control shows steepest expansion trajectory.
Application:
Anatomical complexity and reimbursement coding specificity shape procedure-level economics.
- Electrophysiology:Atrial fibrillation and ventricular tachycardia ablations demand sub-millimeter positioning repeatability. Academic medical centers in the United States deploy these platforms where manual torque transmission fails, standardizing outcomes across operator experience levels.
- Interventional Cardiology:Percutaneous coronary intervention applications face competitive pressure from established manual techniques.
- Vascular Surgery:Peripheral and aortic endovascular procedures utilize robotic precision for anatomically constrained access routes.
- Neurovascular Procedures:Cerebral aneurysm and stroke interventions require navigation through tortuous vasculature.
Procedure volume anchors in Electrophysiology; Neurovascular Procedures gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neodymium and samarium cobalt processing clusters in China anchor magnetic navigation system supply chains, while Bavarian electromechanical component manufacturing underpins steerable platform production across Western Europe. These raw material and precision engineering localities shape regional deployment patterns for robotic catheterization infrastructure.
United States
FDA 510(k) clearance streamlining accelerates capital refresh cycles at tertiary cardiac centers in Cleveland and Boston. CMS new technology add-on payment designation for robotic-assisted cardiac procedures compresses hospital capital committee evaluation timelines. Academic medical centers in the United States deploy haptic feedback platforms for complex ventricular tachycardia ablations.
Germany
Bavarian electromechanical suppliers scale torque sensor and miniature motor production for catheter platform manufacturers. EU MDR technical documentation requirements extend conformity assessment timelines for Class III robotic surgical devices. Joint procurement vehicles across German university hospital networks pool utilization across cath labs in three or more affiliated facilities.
Japan
Prefectural hospitals deploy remote telepresence consoles where electrophysiologist density falls below metropolitan standards. METI frameworks govern medical device software validation for autonomous navigation algorithms. The Kanto region around Tokyo concentrates cardiac center infrastructure for hub-and-spoke specialist coverage models.
China
Neodymium and samarium cobalt sourcing for magnetic navigation systems clusters with domestic processors, exposing installations to export control volatility. NMPA medical device registration pathways impose clinical validation requirements for robotic surgical platforms. Yangtze River Delta medical device manufacturing clusters expand electromechanical component capacity.
United Kingdom
NHS England technology appraisal processes evaluate cost-per-procedure economics for robotic catheter platforms against manual alternatives. MHRA post-market surveillance requirements align with EU MDR transitional arrangements for legacy device predicates. London and Southeast England cardiac centers concentrate electrophysiology procedure volume for platform utilization.
Robotic Catheterization Systems Market Competitive Environment
Global majors compete with regional champions across imaging integration and electromechanical navigation dimensions, producing a tiered structure where diversified healthcare conglomerates anchor the premium segment alongside focused catheter robotics specialists. The vendor base separates into three strategic archetypes: imaging-heritage integrators leveraging fluoroscopy fusion capabilities, magnetic navigation pure-plays dependent on rare earth supply chains, and compact mobile unit specialists targeting cath lab retrofit deployments. Dominant competitive moves include strategic partnerships for legacy imaging system interoperability and capacity expansion in Bavarian precision component supply.
Within the imaging-heritage integrator tier, Siemens Healthineers and Philips Healthcare occupy positions that exemplify platform convergence with real-time fluoroscopy. Among focused catheter robotics specialists, Stereotaxis anchors the magnetic navigation segment while Robocath represents the compact mobile unit archetype designed for cath lab deployment. These three companies illustrate the competitive spectrum from diversified healthcare infrastructure to specialized electromechanical platforms.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Stereotaxis |
| Robocath |
| Microbot Medical |
| Intuitive Surgical |
| Medtronic |
| Boston Scientific |
| Abbott Laboratories |
| Philips Healthcare |
| Others |
Value Chain & Pricing Dynamics
Electromechanical platform tiers diverge sharply from magnetic navigation systems, with the former commanding premium positioning through bundled training and service commitments while the latter absorb volatility from rare earth magnet supply chains concentrated in Chinese processing facilities.
Pricing Analysis
Warranty and service bundling separates electromechanical platform vendors from magnetic navigation specialists, with Siemens Healthineers and Robocath including multi-year maintenance and operator certification in capital packages while Stereotaxis unbundles magnet replacement costs. Three-tier pricing structure across premium electromechanical, standard magnetic navigation, and economy manual catheter tiers reflects FDA 510(k) clearance status and EU MDR conformity documentation completeness. Pricing pressure stems from manual catheter ASPs below $200 anchoring procurement committees in budget-constrained community hospitals against robotic capital outlays exceeding $800,000. Surgical hospitals exhibit highest price sensitivity; tertiary cardiac centers with CMS new technology add-on payment designation show lowest.
Supply Chain Analysis
Warehouse and distribution layers for electromechanical components center on Bavarian regional distribution centers serving German university hospital networks, while magnetic navigation systems feed from Yangtze River Delta assembly clusters through Shanghai port logistics. Torque sensors and miniature motors draw from German and Japanese precision component suppliers; neodymium and samarium cobalt magnets rest on Chinese processors. Single-source vulnerability in rare earth magnet supply exposes Stereotaxis-dependent installations to export control volatility. Distribution runs through direct vendor-to-hospital contracts for capital platforms and GPO-aggregated purchasing for disposables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU MDR technical documentation requirements for Class III robotic surgical devices create an 18-24 month barrier-to-entry moat favoring manufacturers with legacy device predicates and established European authorized representative networks.
For Market Incumbents: Lock in cath lab retrofit opportunities through legacy imaging system interoperability partnerships, particularly fluoroscopy fusion interfaces that complicate deployment for new entrants. Acquire Bavarian electromechanical suppliers to secure torque sensor capacity and deny component access to emerging compact mobile unit competitors. Priority lever centers on EU clinical affairs headcount expansion ahead of MDR post-market surveillance mandates. For New Entrants and Emerging Players: Japanese prefectural hospitals represent the most penetrable buyer archetype, where electrophysiologist density gaps below metropolitan standards create demand for remote telepresence consoles. Target specialty clinics with compact, mobile robotic units designed for rapid cath lab deployment without infrastructure overhaul. Go-to-market angle emphasizes hub-and-spoke specialist coverage models with transparent disposable pricing and training commitment structures. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by imaging-heritage integrators seeking fluoroscopy fusion capabilities. Long-term viability favors vendors with software control architectures enabling autonomous catheter navigation, as machine learning trajectory prediction converges with real-time impedance mapping. Signal to watch is CMS reimbursement determination expansion beyond new technology add-on payment designation toward comprehensive procedure coverage codes.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Expedited review compresses time-to-market for second-generation electromechanical platforms at US cardiac centers. |
| EU MDR Conformity Assessment | Technical documentation obligations extend timelines for Class III devices without legacy predicates. |
| Hospital System Partnership | Joint procurement vehicles across German university networks pool utilization across three or more affiliated facilities. |
| Software Companion Development | AI navigation algorithms enable autonomous catheter steering in complex arrhythmia substrates. |
| Reimbursement Strategy | CMS new technology add-on payment designation creates visibility for US hospital capital committees. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with electrophysiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. FDA 510(k) databases, EU MDR notified body documentation, CMS reimbursement determinations, and Bavarian electromechanical supplier production records provided validation points. Bottom-up procedure volume modeling and top-down capital expenditure estimates were triangulated for convergence.
Data-stream reconciliation across electromechanical system installations, magnetic navigation console deployments, and manual catheter procedure volumes established baseline market sizing. Segmentation dimensions spanned product architecture, end-user facility type, navigation technology, and application complexity across the projection horizon. CAGRs were derived from fitted growth curves against historical capital refresh cycles and reimbursement policy trajectories. Forecast inputs incorporated electrophysiology procedure volume expansion rates and rare earth magnet supply stability assumptions.
Revisions become necessary when FDA clearance pathway modifications, EU MDR enforcement discretion changes, or export control actions on neodymium and samarium cobalt materialize. Forecasts reflect assumptions around reimbursement policy continuity and training pipeline capacity expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Prefilled Syringes Market
Medical Devices
Oxygen Generator Market
Medical Devices
Benign Prostatic Hyperplasia (BPH) Treatment Devices Market
Medical Devices
Digital Magnifiers Market
Medical Devices
Bare Metal Stents Market
Medical Devices
Global Anastomosis Devices Market
Medical Devices
ECG Patch and Holter Monitor Market
Medical Devices
North America and Europe Group 2 Powered Mobility Devices Market
Medical Devices
Sonohysterography Catheters Market
Medical Devices
Oxygen Conserving Devices Market
Medical Devices
General Surgery Devices Market
Medical Devices
Global Vaccine Delivery Devices Market
Medical Devices
Middle East and Africa Sleep Apnea Devices Market
Medical Devices
Vitrectomy Devices Market
Medical Devices
Electronic Skin Patch Market
Medical Devices
Interventional Cardiology Devices Market