
 South Korea Respiratory Devices Market | 2026-2036
South Korea Respiratory Devices Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Respiratory Devices Market Analytics
Multi-source procurement for ventilator components and sensor modules is expanding across South Korean hospital systems. ResMed Inc leverages its digital health ecosystem to sustain recurring revenue from cloud-connected CPAP platforms. Fisher & Paykel Healthcare Limited anchors the humidification subsystem segment through specialized breathing circuit technology. Nihon Kohden Corporation competes on patient monitoring integration with its ventilator and diagnostic platforms.
South Korea respiratory devices encompass mechanical ventilators, positive airway pressure systems, oxygen delivery apparatus, and aerosol therapy equipment engineered to maintain or restore pulmonary function, typically operating at pressure ranges from 4 to 20 cm H₂O for non-invasive applications and higher ranges for invasive ventilation. These devices serve acute care, chronic disease management, and sleep medicine by ensuring adequate gas exchange and reducing respiratory muscle workload. Automated technology segments are capturing margin pools through algorithm-driven pressure titration and remote compliance monitoring, while portable form factors are displacing stationary units in homecare channels. The COPD application category anchors hospital procurement cycles, though sleep apnea segments are expanding fastest as wearable diagnostics penetrate South Korea's aging population.
MFDS medical device licensing and Korea's national health insurance reimbursement schedules shape product entry timelines and pricing bands for both domestic manufacturers and importers. The Ministry of Environment enforces electromagnetic compatibility standards that filter out non-compliant wireless respiratory platforms. Stakeholders must monitor evolving digital therapeutics classification rules and reimbursement parity between connected and conventional devices.
Market Dynamics
MFDS digital health certification pathways are compressing product entry timelines and forcing technology shifts toward connected respiratory platforms across South Korean hospital systems.
Growth Catalysts
- Portable Oxygen Concentrators:Homecare settings in Seoul's metropolitan network are expanding adoption of lightweight, battery-powered units for COPD management.
- MFDS Connected Device Pathways:The Ministry of Food and Drug Safety's streamlined certification for cloud-integrated platforms accelerates market entry for remote monitoring systems.
- Aging-Related Disease Burden:Sleep apnea caseloads in Gyeonggi-do province are driving procurement volumes for positive airway pressure systems.
Market Restraints
- Sensor Module Supply Concentration:Multi-source procurement remains limited for critical ventilator components, creating vulnerability in hospital supply chains.
- Electromagnetic Compatibility Standards:The Ministry of Environment's wireless platform requirements filter out non-compliant devices, reducing import options.
- Reimbursement Parity Gaps:Korea's national health insurance maintains pricing bands that disadvantage connected devices against conventional equivalents.
Strategic Opportunities
- Busan-Ulsan Medical Corridor:Underpenetrated secondary hospital networks outside Seoul present expansion potential for regional distribution partnerships.
- Algorithm-Driven Pressure Titration:Automated technology segments are capturing margin pools through machine learning integration with diagnostic platforms.
- Digital Therapeutics Classification:Evolving MFDS rules on software-as-medical-device create first-mover advantage for compliance-ready platforms.
Industry Challenges
- Embedded Systems Engineering Talent:Shortage of firmware developers with medical device experience delays product development cycles for domestic manufacturers.
- Legacy Hospital IT Integration:Compatibility requirements with existing patient monitoring infrastructure complicate deployment of next-generation respiratory platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Respiratory Devices Market |
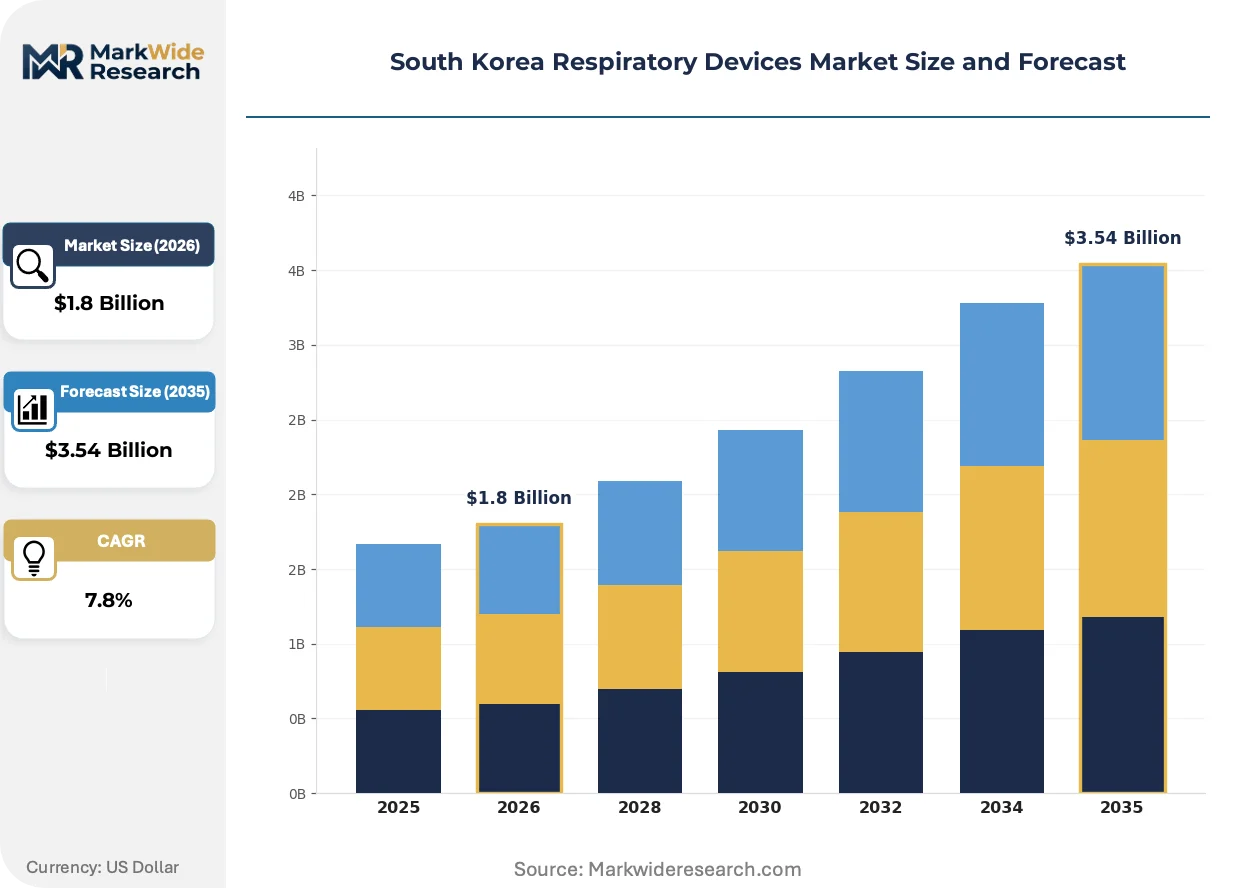
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.54 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalers, Nebulizers, CPAP Devices, Oxygen Concentrators Technology: Digital, Portable, Manual, Automated End User: Hospitals, Homecare, Clinics, Rehabilitation Centers Application: Asthma, COPD, Sleep Apnea, Acute Respiratory Failure |
| Companies Covered | Drägerwerk AG & Co. KGaA, M.I.One Co. Ltd, Teleflex Incorporated, HoneyNaps Co. Ltd, MEKICS Co. Ltd, Fisher & Paykel Healthcare Limited, iSenLAb Co. LTD, ResMed Inc, Nihon Kohden Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Respiratory Devices Market Evolving Landscape
Cloud-connected respiratory platforms are unifying diagnostic, therapeutic, and compliance monitoring functions into single ecosystems, reshaping how South Korean providers manage chronic pulmonary conditions.
Remote patient monitoring architecture is unifying pulse oximetry, airflow sensors, and pressure transducers into modular platforms that Seoul metropolitan hospitals are deploying across COPD and sleep medicine departments. The convergence reduces capital expenditure by consolidating multiple devices into integrated workstations. This unification is compressing vendor margins on standalone diagnostic equipment while expanding recurring revenue from subscription-based compliance services.
MFDS tightened its Software as a Medical Device classification framework in alignment with international harmonization initiatives, extending review timelines for AI-enabled respiratory diagnostics. The regulation forces manufacturers to submit clinical validation data for algorithm-driven pressure titration systems. Sleep apnea device categories face the steepest compliance burden, with several imported platforms delayed pending cybersecurity documentation.
Hospital procurement committees are consolidating vendor relationships through multi-year service agreements that bundle device leasing with preventive maintenance and remote technical support. The bundled model displaces traditional capital purchase cycles in Gyeonggi-do province's aging-focused care networks. Daegu-Gyeongbuk regional hospitals show the fastest transition, driven by budget constraints and preference for predictable operational expenditures over upfront equipment investment.
South Korea Respiratory Devices Market Segmentation
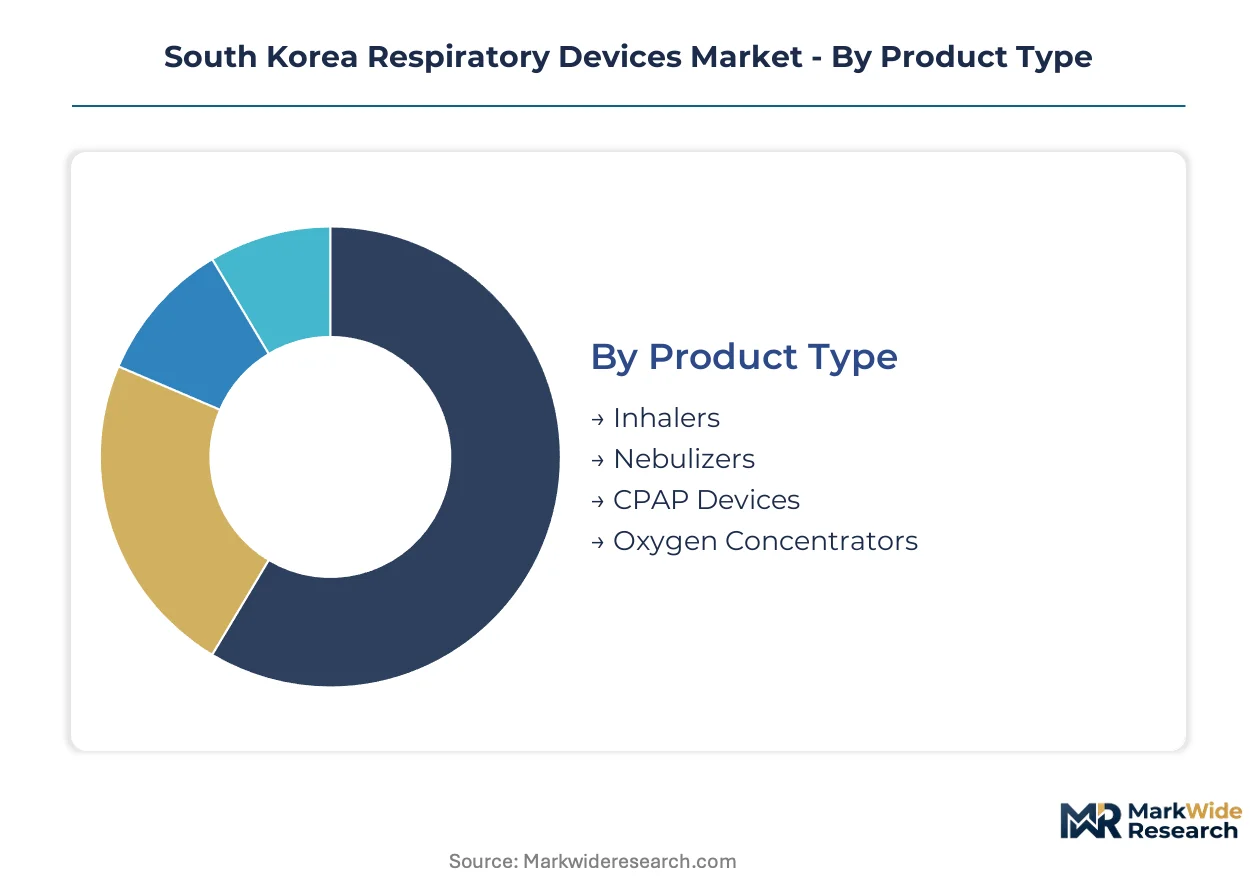
South Korea's respiratory device market fragments across four distinct dimensions that shape procurement priorities and margin capture. Hospital procurement committees evaluate products through technology readiness, care setting compatibility, and chronic disease application alignment.
Product Type:
Hospital procurement committees weight device selection against reimbursement tiers and patient throughput capacity.
- Inhalers:Metered-dose and dry-powder delivery systems dominate ambulatory COPD management across Seoul's metropolitan clinics. Gyeonggi-do province's aging population drives prescription volumes for combination bronchodilator formulations.
- CPAP Devices:Continuous positive airway pressure systems integrate pressure sensors, humidification modules, and cloud connectivity for sleep apnea therapy. Seoul metropolitan hospital networks prioritize MFDS-certified units with remote compliance monitoring to reduce clinic visit frequency.
- Nebulizers:Jet and mesh atomization systems deliver aerosolized medication for acute bronchospasm in emergency departments.
- Oxygen Concentrators:Stationary and portable units separate ambient nitrogen to deliver therapeutic oxygen flows for hypoxemic patients.
Volume sits with inhalers; growth tilts toward CPAP devices.
Technology:
Reimbursement parity gaps between connected and conventional platforms concentrate investment decisions on digital integration levels.
- Digital:Cloud-integrated respiratory platforms unify diagnostic data, therapy delivery, and remote monitoring through embedded cellular modules. MFDS streamlined certification pathways accelerate hospital adoption in Busan-Ulsan medical corridor facilities seeking operational efficiency.
- Automated:Algorithm-driven pressure titration systems adjust therapeutic parameters based on real-time physiological feedback. Daegu-Gyeongbuk regional hospitals deploy these for COPD exacerbation management to reduce manual intervention.
- Portable:Battery-powered concentrators and miniaturized CPAP units enable domiciliary care for mobile patients.
- Manual:Non-electric nebulizers and basic oxygen delivery systems serve cost-constrained procurement cycles.
Procurement volume clusters around digital platforms; automated segments gain share fastest.
End User:
Capital expenditure constraints and operational expenditure preferences reshape distribution channel strategies across care settings.
- Hospitals:Acute care facilities in Seoul's metropolitan network procure ventilators, high-flow nasal cannula systems, and intensive care monitoring platforms. Multi-year service agreements bundling device leasing with preventive maintenance displace traditional capital purchase cycles.
- Homecare:Domiciliary oxygen therapy and sleep apnea management drive demand for lightweight, patient-operated devices. Gyeonggi-do province's aging-focused care networks show fastest transition toward rental and subscription models.
- Clinics:Outpatient pulmonary practices require compact diagnostic and therapeutic equipment for ambulatory patient volumes.
- Rehabilitation Centers:Post-acute facilities focus on weaning protocols and respiratory muscle training devices.
Revenue concentrates in hospitals; expansion tilts toward homecare.
Application:
Disease prevalence patterns and clinical pathway standardization determine device specification requirements.
- COPD:Chronic obstructive pulmonary disease anchors hospital procurement cycles through oxygen therapy, non-invasive ventilation, and pulmonary rehabilitation equipment. Seoul metropolitan hospitals maintain dedicated COPD management units with integrated diagnostic-therapeutic workstations.
- Sleep Apnea:Obstructive sleep apnea diagnosis and therapy represent the steepest expansion trajectory as wearable diagnostics penetrate South Korea's aging population. Home sleep testing adoption in Gyeonggi-do province reduces polysomnography bottlenecks.
- Asthma:Allergic and exercise-induced bronchospasm management drives inhaler prescription volumes.
- Acute Respiratory Failure:Critical care ventilation and extracorporeal support address emergency pulmonary decompensation.
Installed base sits with COPD; sleep apnea climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul's metropolitan hospital network anchors domestic demand for respiratory devices, with Gyeonggi-do province's aging population amplifying procurement volumes for COPD and sleep apnea equipment.
Seoul Capital Area
Seoul's tertiary hospitals drive demand for ventilators and high-flow nasal cannula systems through dedicated COPD management units. MFDS digital health certification accelerates cloud-connected platform adoption. Bundled service agreements displace capital purchase cycles across the metropolitan network.
Busan-Ulsan
The Busan-Ulsan medical corridor presents underpenetrated secondary hospital networks for regional distribution partnerships. MFDS streamlined pathways for connected devices accelerate market entry for remote monitoring systems. Procurement committees here favor operational expenditure models over upfront equipment investment.
Daegu-Gyeongbuk
Daegu-Gyeongbuk regional hospitals show fastest transition toward multi-year service agreements for respiratory platforms. Budget constraints drive preference for predictable operational expenditures. Algorithm-driven pressure titration systems deploy for COPD exacerbation management to reduce manual intervention.
Daejeon-Sejong
Daejeon-Sejong's research institutions and government complexes concentrate regulatory expertise and clinical trial infrastructure. MFDS software-as-medical-device classification rules shape product development timelines. Domestic manufacturers cluster here to access embedded systems engineering talent for firmware development.
Gwangju-Honam
Gwangju-Honam's aging-focused care networks expand homecare settings for portable oxygen concentrators and miniaturized CPAP units. Rental and subscription models penetrate fastest in this region. Lightweight, battery-powered devices enable domiciliary care for mobile patients managing chronic pulmonary conditions.
South Korea Respiratory Devices Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors consolidate relationships through multi-year service agreements bundling device leasing with preventive maintenance. The vendor base fragments across multinational subsidiaries, domestic specialists, and regional distributors. Three archetypes occupy distinct positions: cloud-integrated platform providers, humidification subsystem specialists, and patient monitoring integrators. M&A activity and technology licensing agreements represent the dominant competitive moves reshaping market structure.
Among multinational platform providers, ResMed Inc and Fisher & Paykel Healthcare Limited occupy premium-tier positions exemplifying cloud-connected and humidification-specialized archetypes respectively. Nihon Kohden Corporation represents the patient monitoring integration archetype. Domestic specialists including MEKICS Co. Ltd and iSenLAb Co. LTD sit within the regional fabrication tier, while M.I.One Co. Ltd and HoneyNaps Co. Ltd exemplify emerging local players targeting specific application niches. Drägerwerk AG & Co. KGaA and Teleflex Incorporated anchor the European-origin equipment segment.
| Leading Market Players |
|---|
| Drägerwerk AG & Co. KGaA |
| M.I.One Co. Ltd |
| Teleflex Incorporated |
| HoneyNaps Co. Ltd |
| MEKICS Co. Ltd |
| Fisher & Paykel Healthcare Limited |
| iSenLAb Co. LTD |
| ResMed Inc |
| Nihon Kohden Corporation |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between MFDS-connected platforms and conventional respiratory devices manifests in both procurement pricing and component sourcing configurations across South Korean hospital systems. Premium-tier cloud-integrated systems command bundled service premiums while economy-tier manual devices face cost compression from concentrated sensor module supply.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium-tier digital respiratory platforms from unbundled economy-tier manual devices in South Korean hospital procurement. Three-tier pricing structure across premium, standard, and economy levels reflects MFDS certification grade and remote monitoring capability. Pricing pressure stems from national health insurance reimbursement parity gaps disadvantaging connected devices. Homecare segments in Gyeonggi-do province exhibit highest price sensitivity; Seoul metropolitan tertiary hospitals show lowest sensitivity due to operational expenditure preferences.
Supply Chain Analysis
Dual-sourcing qualification requirements for critical ventilator components remain limited in South Korean hospital supply chains despite vulnerability awareness campaigns. Manufacturing concentration centers on South Korea, Japan, and Germany for precision pressure sensors, flow transducers, and embedded control modules. Supply chain risk hinges on single-source vulnerability for specialized humidification subsystems and algorithm firmware. Distribution runs through regional medical device distributors with GPO contracts into hospital procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South Korea respiratory devices market is accelerating into a vertical-integration race as players pursue captive control over cloud-connected platform firmware and remote monitoring service stacks to defend margin pools.
For Market Incumbents: Deepen backward integration into embedded systems engineering talent pools within Daejeon-Sejong's research corridor to reduce firmware development cycle delays. Secure exclusive multi-year service agreements with Seoul metropolitan hospital networks before emerging domestic specialists capture Gyeonggi-do province's aging-focused care transitions. MFDS software-as-medical-device classification tightening represents the primary regulatory threat requiring compliance investment.
For New Entrants and Emerging Players: The mid-tier price-point gap between ResMed-cloud-integrated premium systems and basic manual nebulizers offers white-space entry for algorithm-driven pressure titration specialists. Busan-Ulsan medical corridor's underpenetrated secondary hospital networks present the most penetrable geography for regional distribution partnerships. Target operational expenditure procurement preferences with rental-subscription hybrid models for portable oxygen concentrators.
For Investors and Strategic Acquirers: Exit pathways concentrate in platform-specialist acquisition by multinational medical device conglomerates seeking MFDS-certified cloud connectivity capabilities. Long-term viability favors domestic manufacturers with embedded firmware development capacity and established GPO contract relationships. Watch MFDS digital therapeutics reimbursement parity decisions as the critical inflection signal for connected device margin sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Software-as-Medical-Device Certification | Accelerates market entry timelines for AI-enabled respiratory diagnostics platforms. |
| Hospital System Partnership | Secures multi-year bundled service agreements displacing capital purchase cycles. |
| Backward Integration into Firmware Development | Reduces dependency on Daejeon-Sejong's scarce embedded systems engineering talent. |
| Geographic Expansion to Busan-Ulsan Corridor | Captures underpenetrated secondary hospital networks outside Seoul metropolitan area. |
| Reimbursement Strategy Alignment | Positions connected devices for national health insurance pricing band adjustments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with hospital procurement managers, biomedical engineers, GPO contracts specialists, and MFDS regulatory affairs leads. Korean Medical Device Industry Association publications, MFDS medical device licensing databases, hospital procurement committee minutes, and national health insurance reimbursement schedules provided quantitative foundations. Bottom-up modeling of device shipments triangulated against top-down spending estimates from healthcare capital expenditure surveys.
Granularity-level modeling deployed product-type, technology-tier, end-user setting, and application-disease dimensions at the provincial level across the analysis window. CAGRs derived from logistic diffusion curves fitted to connected device adoption patterns and aging-population disease prevalence projections. Algorithm-driven pressure titration penetration rates and homecare rental-subscription transition velocities served as industry-specific forecast inputs.
Inputs from hospital procurement databases and GPO contract disclosures were available through the study window; gaps in real-time inventory positioning data introduce uncertainty bands around short-term shipment estimates. Forecasts reflect documented assumptions regarding MFDS certification timeline stability and national health insurance reimbursement parity evolution. Deviation in MFDS software-as-medical-device classification enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Clear Aligners Market
Medical Devices
3D-Printed Maxillofacial Implants Market
Medical Devices
Osmotic Pumps Market
Medical Devices
Netherlands Aesthetic Devices Market
Medical Devices
Interventional Oncology Devices Market
Medical Devices
Brazil Ultrasound Devices Market
Medical Devices
Australia and New Zealand Diabetes Devices Market
Medical Devices
US External Counterpulsation Devices Market
Medical Devices
Pulmonary Heart Valve Replacement Market
Medical Devices
Craniomaxillofacial Plate and Installation Tools Market
Medical Devices
Global Automated External Defibrillators Market
Medical Devices
Global Transradial Access Market
Medical Devices
Phototherapy Lamps Market
Medical Devices
Digital Body Thermometer Market
Medical Devices
Cholecystectomy Devices Market
Medical Devices
Digital X-Ray Devices Market