
 Hydrogel Contact Lenses Market | 2026-2036
Hydrogel Contact Lenses Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogel Contact Lenses Market Foresight
Buyer concentration in the optical retail channel is consolidating as independent practices merge into regional chains and online direct-to-consumer platforms capture repeat purchasers. Johnson & Johnson Vision Care leverages its Acuvue manufacturing scale to dominate daily wear supply contracts with major optical retailers. Alcon sustains extended wear leadership through proprietary silicone hydrogel formulations that command premium positioning in professional channels. CooperVision anchors toric and multifocal portfolios across Europe and Asia-Pacific through localized production facilities.
Hydrogel contact lenses are soft, water-absorbing polymer discs typically comprising HEMA or silicone hydrogel matrices with water content ranging from 38% to 75%, engineered to correct refractive errors while permitting oxygen transmission to the cornea. Daily wear silicone hydrogel leads volume due to disposable convenience and reduced infection risk, while extended wear retains margin concentration among presbyopic and astigmatic users requiring overnight permeability. Multifocal designs represent the fastest-growing structural segment as aging populations in developed markets seek alternatives to reading glasses.
FDA 510(k) clearance pathways and CE marking under the EU MDR govern material biocompatibility and oxygen transmissibility benchmarks, with Japan's PMDA enforcing additional Dk/t reporting standards for imported lenses. The EU F-Gas Regulation indirectly pressures silicone hydrogel precursor chemistry sourcing, prompting manufacturers to reformulate polymerization processes. Stakeholders must monitor regulatory divergence between FDA breakthrough device pathways and EU MDR clinical evidence requirements when allocating R&D budgets across geographic portfolios.
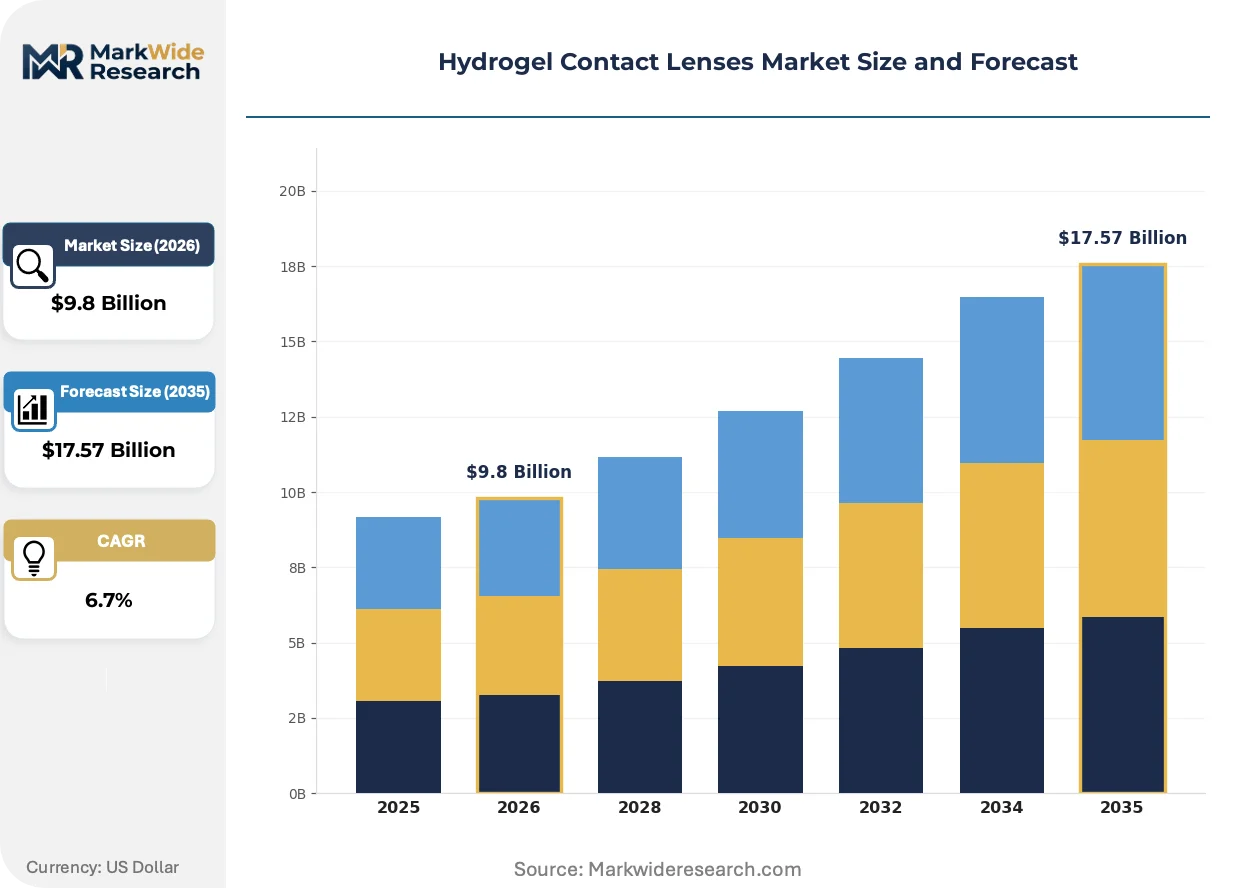
Market Dynamics
Silicone hydrogel oxygen permeability improvements are compressing replacement cycles and shifting professional fitting economics toward daily disposable protocols.
Growth Catalysts
- FDA 510(k) breakthrough device pathways:Accelerated clearance timelines for novel lens geometries are shortening product development cycles.
- Presbyopic populations in Japan and Germany:Aging demographics with high disposable income and established eye care professional relationships drive multifocal lens conversion.
- HEMA-to-silicone hydrogel material migration:Enhanced Dk/t values reduce hypoxic complications and expand overnight wear eligibility.
Market Restraints
- Silicone hydrogel precursor chemistry concentration:EU F-Gas Regulation constraints on fluorinated gas feedstocks limit polymerization input flexibility.
- Extended wear technical ceiling:Biofilm accumulation on 30-day surfaces caps safe wear duration regardless of oxygen transmissibility gains.
- Refractive surgery substitution:LASIK and SMILE procedures capture younger myopic candidates before contact lens dependency establishes.
Strategic Opportunities
- India's underpenetrated optical retail:Low eye care professional density and rising urban incomes create first-mover advantage for daily disposable education.
- Smart lens convergence with glucose monitoring:Integration of biosensor arrays opens continuous health monitoring applications beyond vision correction.
- Direct-to-consumer subscription channels:Automated replenishment models bypass traditional optical retail margin stacking.
Industry Challenges
- Specialized polymer chemist talent scarcity:Silicone hydrogel formulation expertise concentrates among legacy R&D teams with limited mobility.
- CE MDR clinical evidence requirements:Extended wear claims now demand prospective safety studies, extending certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogel Contact Lenses Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.57 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Daily Wear, Extended Wear, Multifocal, Toric Material: Silicone Hydrogel, Hydrogel, Polyhema, HEMA End User: Consumers, Eye Care Professionals, Retailers, Distributors Distribution Channel: Online, Retail Stores, Optical Chains, Hospitals |
| Companies Covered | Johnson & Johnson Vision Care, Alcon, Bausch + Lomb, CooperVision, Menicon Co., Ltd., Contamac, Hoya Corporation, SEED Co., Ltd., EssilorLuxottica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogel Contact Lenses Market Shifts & Advancements
Material science advances and regulatory recalibration are redefining competitive advantage around biocompatibility certification and oxygen delivery optimization rather than incremental comfort improvements.
Silicone hydrogel formulations with water content above 50% are expanding into presbyopic multifocal designs previously dominated by rigid gas-permeable alternatives. Optical chains in the United States and Japan report faster patient adaptation curves and reduced dropout rates. This material shift is expanding into premium pricing tiers that were historically reserved for specialty fitting services.
EU MDR clinical evidence requirements for extended wear classifications are compressing product lifecycle planning horizons. Manufacturers must now commission prospective safety studies for 30-day wear claims that previously relied on predicate device pathways. Extended wear silicone hydrogel portfolios face the steepest compliance cost escalation, with Germany and France representing the largest affected revenue pools.
Subscription-based replenishment models are displacing episodic optical retail purchasing among established wearers aged 25-40. Direct-to-consumer platforms capture repeat purchasers through automated delivery schedules calibrated to prescribed replacement frequencies. This behavioral shift concentrates in the United States where regulatory telehealth exemptions permit remote prescription renewal.
Hydrogel Contact Lenses Market Segmentation
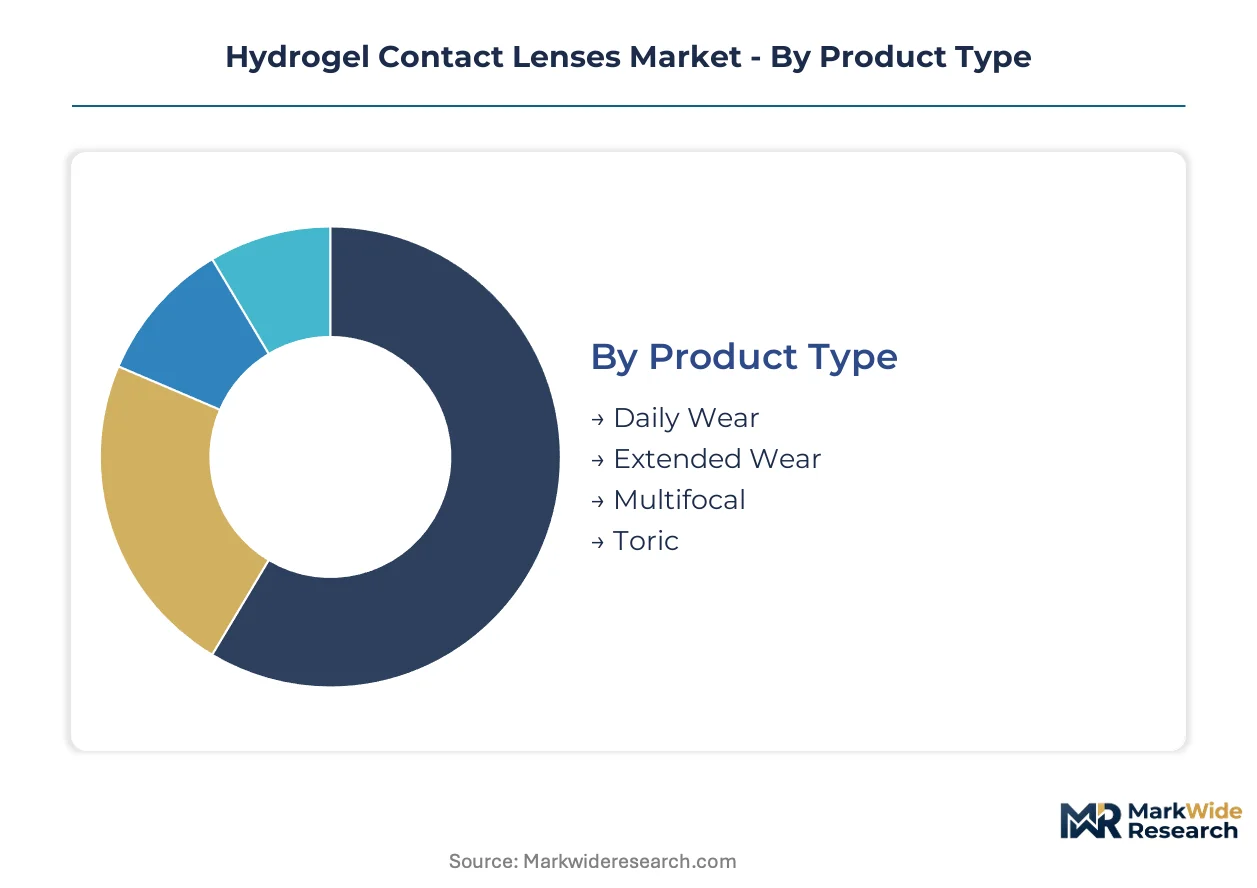
Segmentation in hydrogel contact lenses reveals how material chemistry, wear protocols, and channel economics split value capture across the supply chain. Manufacturers optimize R&D allocation by matching polymer innovation to specific refractive correction needs and purchasing behaviors.
Product Type:
Daily wear designs function as standalone disposable units, while extended and specialty formats embed into longer-term fitting relationships with eye care professionals.
- Daily Wear:Single-use silicone hydrogel lenses with water content between 58% and 75% dominate volume through convenience-driven purchasing. Demand concentrates in the United States and Japan where optical chain density supports high-frequency replenishment and younger demographics prioritize infection risk reduction over per-unit cost.
- Extended Wear:Continuous-wear formulations engineered for 7-30 day overnight oxygen transmission require specialized fitting protocols and professional monitoring. Presbyopic users in Germany and established wearers with consistent prescriptions drive adoption despite higher per-lens pricing and stricter FDA biocompatibility documentation.
- Multifocal:Progressive power designs address near and distance vision through simultaneous image formation.
- Toric:Cylindrical correction for astigmatism relies on stabilization zones and precise axis orientation.
Volume placements concentrate in Daily Wear; the faster expansion belongs to Multifocal.
Material:
Cost tier stratification separates premium oxygen-permeable formulations from legacy hydrogel standards in reimbursement and retail positioning.
- Silicone Hydrogel:Hybrid polymer matrices combining siloxane groups with hydrophilic components achieve Dk/t values exceeding 100, enabling overnight wear eligibility. Japan's PMDA enforces additional oxygen transmissibility reporting for imported silicone hydrogel products, elevating compliance costs for non-domestic manufacturers.
- Hydrogel:Conventional water-absorbing polymers with 38-55% moisture content retain economy positioning for price-sensitive daily wear segments. Demand persists in emerging optical retail markets where professional fitting infrastructure remains underdeveloped and consumers prioritize accessibility over extended wear performance.
- Polyhema:Poly(2-hydroxyethyl methacrylate) serves as the foundational hydrogel chemistry for entry-level correction.
- HEMA:Standard hydroxyethyl methacrylate formulations occupy the contracting mid-tier between silicone hydrogel and basic polyhema options.
Silicone Hydrogel captures the steepest expansion trajectory as presbyopic populations convert from rigid gas-permeable alternatives.
End User:
Customer type determines whether procurement flows through professional fitting relationships or direct replenishment channels.
- Consumers:Individual purchasers accessing lenses through subscription platforms or retail optical chains represent the terminal demand base. Repeat purchasing automation concentrates in the United States where telehealth exemptions permit remote prescription renewal and bypass traditional professional fitting economics.
- Eye Care Professionals:Optometrists and ophthalmologists control initial fitting decisions and material recommendations for complex prescriptions. Germany's dense network of independent practices and optical retail integration sustains professional channel influence over multifocal and toric selection.
- Retailers:Optical chains and independent practices intermediate inventory holding and patient education.
- Distributors:Wholesale logistics providers manage regional warehousing and regulatory compliance documentation.
Consumer direct purchasing is climbing the fastest; professional channel influence remains strongest in specialty correction segments.
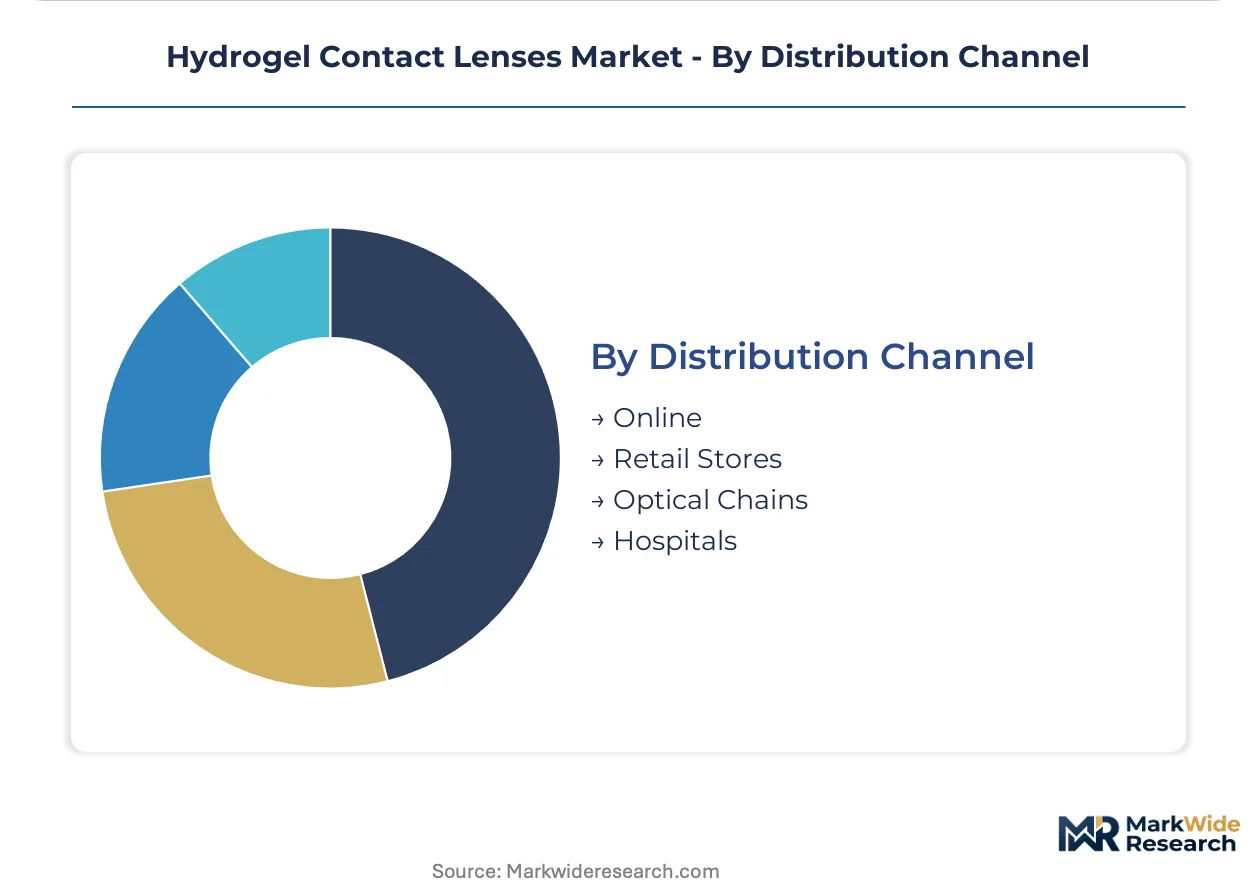
Distribution Channel:
Channel maturity varies by geography, with digital penetration highest in markets with established telehealth frameworks and optical retail consolidation.
- Online:Direct-to-consumer platforms and subscription services capture repeat purchasers through automated replenishment calibrated to prescribed replacement frequencies. United States regulatory exemptions for remote prescription renewal enable this channel's expansion where traditional optical retail margin stacking previously dominated.
- Retail Stores:Independent optical practices and regional chains maintain first-fit relationships and complex prescription handling. Japan's high eye care professional density preserves retail store relevance despite online encroachment in replenishment purchasing.
- Optical Chains:Consolidated regional and national chains leverage purchasing scale for supply contract negotiations.
- Hospitals:Institutional settings address post-surgical and therapeutic lens requirements.
Optical Chains retain volume concentration; Online channels are gaining share fastest among established wearers aged 25-40.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates where optical retail density and eye care professional penetration intersect with aging demographics and disposable income. United States, Japan, and Germany absorb the majority of premium silicone hydrogel volume through established fitting protocols and reimbursement frameworks.
United States
FDA 510(k) breakthrough device pathways accelerate novel lens geometry clearances, compressing development cycles for daily disposable formats. Telehealth exemptions for remote prescription renewal enable direct-to-consumer subscription channels to capture repeat purchasers aged 25-40. Optical chain consolidation in California and Texas concentrates procurement power among regional retail networks.
Japan
PMDA enforces additional Dk/t oxygen transmissibility reporting standards for imported silicone hydrogel products, elevating compliance costs for non-domestic manufacturers. Aging presbyopic populations in Tokyo and Osaka drive multifocal lens conversion from rigid gas-permeable alternatives. Domestic eye care professional density sustains retail store relevance despite online encroachment in replenishment purchasing.
Germany
EU MDR clinical evidence requirements for extended wear classifications now demand prospective safety studies, extending certification timelines for 30-day wear claims. Dense networks of independent practices in Bavaria and North Rhine-Westphalia preserve professional channel influence over complex prescription selection. F-Gas Regulation constraints on fluorinated gas feedstocks pressure polymerization input flexibility for domestic formulation facilities.
India
Rising urban incomes in Maharashtra and Karnataka create first-mover advantage for daily disposable education among underpenetrated optical retail markets. CDSCO medical device regulations govern import licensing for silicone hydrogel formulations, though professional fitting infrastructure remains underdeveloped outside major metros. Price-sensitive consumers prioritize accessibility over extended wear performance, sustaining hydrogel demand in entry-level segments.
United Kingdom
MHRA post-Brexit regulatory divergence from EU MDR creates parallel compliance pathways for manufacturers serving British and continental European markets. Optical retail consolidation in London and the Southeast concentrates volume through national chain procurement contracts. Subscription-based replenishment models penetrate faster among established wearers in urban corridors with established telehealth frameworks.
Hydrogel Contact Lenses Market Competitive Landscape
United States producers anchor one tier through manufacturing scale and optical retail supply contracts; Japanese and European specialists hold differentiated positions in material formulation and professional channel relationships. The vendor base stratifies across three archetypes: diversified healthcare conglomerates with vision care divisions, pure-play contact lens manufacturers with regional production footprints, and optical retail-integrated suppliers controlling distribution endpoints. Consolidation pressures intensify as daily disposable volume concentrates procurement power among merged optical chains. Competitive moves center on M&A to capture regional fitting relationships and capacity expansion to serve subscription replenishment logistics.
Within the diversified healthcare conglomerate tier, Johnson & Johnson Vision Care and Alcon exemplify scale-driven positioning through manufacturing breadth and professional channel penetration. CooperVision occupies a specialist position among pure-play manufacturers with localized production strategies across Europe and Asia-Pacific. These three entities represent the dominant competitive anchors, with Johnson & Johnson Vision Care and Alcon sitting within the premium-tier vector of daily disposable supply contracts, while CooperVision anchors toric and multifocal portfolio diversification through geographic production distribution.
| Leading Market Players |
|---|
| Johnson & Johnson Vision Care |
| Alcon |
| Bausch + Lomb |
| CooperVision |
| Menicon Co., Ltd. |
| Contamac |
| Hoya Corporation |
| SEED Co., Ltd. |
| EssilorLuxottica |
| Others |
Supply & Pricing Matrix
Silicone hydrogel polymerization chemistry transitions are simultaneously compressing per-unit manufacturing costs and concentrating formulation expertise among legacy R&D facilities in the United States, Ireland, and Singapore. This dual effect amplifies pricing power for incumbents controlling proprietary Dk/t optimization while squeezing margin flexibility for second-tier manufacturers dependent on licensed polymer platforms.
Pricing Analysis
Volume concentrates in daily disposable silicone hydrogel where per-lens economics favor high-frequency replenishment over per-unit margin extraction, while extended wear and multifocal formats retain premium positioning through specialized fitting protocols. Price differentiation hinges on oxygen transmissibility certification tiers and professional channel bundling with after-care services. Pricing pressure stems from optical chain consolidation in the United States and Germany, where procurement scale concentrates buyer leverage. Price sensitivity runs highest among first-time wearers in emerging markets prioritizing accessibility; established presbyopic users in Japan and Germany exhibit lowest sensitivity due to complex prescription requirements.
Supply Chain Analysis
Domestic-content mandates under Japan's PMDA and India's CDSCO are reshaping sourcing patterns by elevating compliance costs for imported silicone hydrogel precursors and incentivizing localized polymerization facilities. Raw material supply concentrates on fluorinated siloxane monomers from specialized chemical producers in the United States, Germany, and Japan, with finished lens manufacturing anchored in Ireland, Singapore, and Puerto Rico. Supply chain risk centers on EU F-Gas Regulation constraints limiting fluorinated gas feedstock flexibility for silicone hydrogel precursor synthesis. Distribution runs through optical chain central warehouses in the United States and Japan, with direct-to-consumer subscription platforms capturing replenishment volume among established wearers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
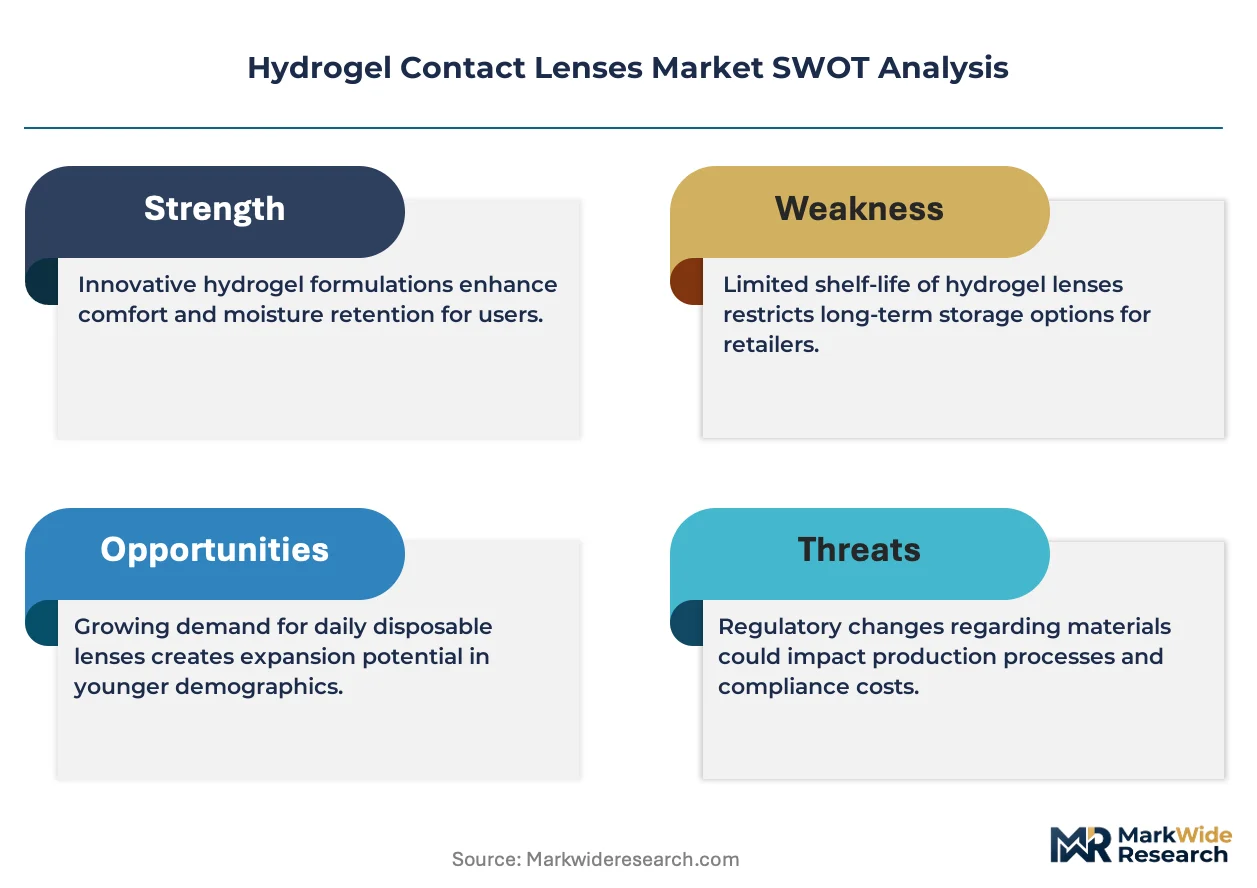
Silicone hydrogel oxygen permeability advances are displacing legacy HEMA formulations as the dominant material platform, compressing the window for incumbents to extract residual value from conventional hydrogel portfolios while opening white-space for specialists mastering next-generation Dk/t optimization.
For Market Incumbents: Deepen proprietary silicone hydrogel formulation capabilities through captive R&D investment in Singapore and Ireland facilities to defend against refractive surgery substitution among younger myopic candidates. Secure extended wear certification under EU MDR prospective study requirements before smaller competitors can accumulate clinical evidence. Prioritize supply contract lock-in with consolidating optical chains in California and Texas. For New Entrants and Emerging Players: Begin with daily disposable education campaigns in India's underpenetrated optical retail markets, where low eye care professional density and rising urban incomes create first-mover advantage before incumbent distribution infrastructure solidifies. Target Maharashtra and Karnataka metro corridors with localized pricing calibrated to hydrogel accessibility tiers. Leverage direct-to-consumer subscription mechanics to bypass traditional optical retail margin stacking. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified healthcare conglomerates seeking vision care division scale, with IPO viability contingent on demonstrating silicone hydrogel formulation differentiation beyond licensed polymer platforms. Target pure-play manufacturers with established PMDA import pathways and localized production footprints in Asia-Pacific. Watch FDA breakthrough device clearance velocity as inflection indicator for R&D productivity gaps between incumbents and emerging specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Silicone Hydrogel Formulation R&D Expansion | Proprietary Dk/t optimization above 100 unlocks overnight wear eligibility under FDA 510(k) pathways. |
| EU MDR Clinical Evidence Investment | Prospective safety studies for extended wear claims secure premium positioning in Germany and France. |
| Direct-to-Consumer Subscription Launch | Automated replenishment bypasses optical retail margin stacking in United States telehealth-exempt markets. |
| India Market Entry with Daily Disposable Focus | First-mover education in underpenetrated optical retail captures rising urban income demographics. |
| Optical Chain Supply Contract Consolidation | Procurement scale with merged United States regional chains locks out second-tier competitors. |
Research Methodology
FDA 510(k) clearance databases, PMDA Dk/t reporting filings, and EU MDR clinical evidence registries formed the secondary backbone, cross-referenced with SEC 10-K segment disclosures from vision care divisions and optical chain procurement contract announcements. Primary interviews with silicone hydrogel polymer chemists, optometrist practice owners, optical chain category buyers, and GPO contracts managers validated material substitution timelines and professional channel economics. Bottom-up patient population modeling by refractive error prevalence and top-down manufacturer shipment triangulation anchored volume estimates.
Bottom-up analysis modeled daily wear, extended wear, multifocal, and toric segments across silicone hydrogel and conventional hydrogel material tiers, with replacement frequency assumptions calibrated to professional fitting protocol variations by geography. Top-down verification checked manufacturer capacity disclosures and optical retail inventory turns against patient population penetration rates. CAGRs derived from segment-level growth rate blending weighted by revenue concentration in the United States, Japan, and Germany. Forecast inputs incorporated EU F-Gas Regulation implementation timelines and telehealth exemption policy stability in key states.
Underlying measurement precision varies by segment; daily disposable volume estimates carry tighter precision than extended wear due to higher optical retail data availability, while multifocal growth projections embed greater uncertainty around presbyopic conversion rates from rigid gas-permeable alternatives. Forecasts reflect assumptions regarding regulatory pathway stability, material science advancement continuity, and optical retail consolidation velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Japan Respiratory Devices Market
Medical Devices
Portable Dialysis Machines Market
Medical Devices
Jet Nebulizers Market
Medical Devices
Batteries for Skin Patches Market
Medical Devices
Scoliosis Traction Chairs Market
Medical Devices
Global Holter ECG Market
Medical Devices
Asia-Pacific Vaginal Slings Market
Medical Devices
Spinal Thoracolumbar Implants Market
Medical Devices
Global Nasal Cannula Market
Medical Devices
Transient Elastography Device Market
Medical Devices
Global Microkeratome Market
Medical Devices
Global Automated Dispensing Machines Market
Medical Devices
China Ophthalmic Devices Market
Medical Devices
Bionic Devices Market
Medical Devices
US Peripheral Vascular Devices and Accessories Market
Medical Devices
Europe Breast Implant Market