
 Endoprosthesis Market | 2026-2036
Endoprosthesis Market Size, Share, and Industry Trends Forecast 2026-2036
Endoprosthesis Market Intelligence
The orthopedic surgeon end-user channel is broadening as hospital systems expand same-day joint replacement programs. Zimmer Biomet Holdings, Inc. leverages its comprehensive hip and knee portfolio to dominate large integrated delivery networks. Stryker Corporation anchors its position through robotics-assisted surgical platforms that tighten surgeon loyalty. Smith & Nephew plc differentiates in advanced wound management adjacent to implant procedures.
An endoprosthesis is a permanent artificial substitute implanted to replace a damaged biological joint, organ, or tissue structure, typically fabricated from titanium alloy, cobalt chromium, or ultra-high molecular weight polyethylene and engineered to restore biomechanical function through osseointegration or endothelialization. Hip prosthesis and knee prosthesis categories command the largest revenue pools due to high procedure frequency and established reimbursement codes, while cardiovascular stents compete on thinner margins despite faster volume growth in emerging markets. Ceramic-on-ceramic bearing surfaces in hip applications command premium positioning as wear debris concerns reshape material selection across patient cohorts.
FDA premarket notification and EU MDR conformity assessment govern commercial entry in the two largest regulated markets, with clinical evidence requirements lengthening development timelines for novel bearing surfaces. Japan's PMDA and China's NMPA impose additional localization standards that favor regional manufacturing partnerships over direct export. Stakeholders must monitor regulatory divergence between FDA breakthrough device pathways and EU MDR recertification deadlines to preserve market access without duplicative clinical investments.
Market Dynamics
Robotics-assisted surgical platforms are compressing the traditional learning curve for complex joint replacement procedures, concentrating demand among surgeons who master these systems while forcing implant manufacturers to bundle hardware with consumable revenue streams.
Growth Catalysts
- Ambulatory surgical center expansion:Same-day discharge protocols in the United States now accommodate select total knee and hip replacements, pulling procedures from inpatient settings and expanding addressable volume for specialized implant portfolios.
- Ceramic-on-ceramic bearing surfaces:Wear debris reduction in younger, active patient cohorts is reshaping material selection criteria across orthopedic procurement committees.
- EU MDR recertification deadlines:Stricter clinical evidence requirements for legacy devices are accelerating market exits by smaller manufacturers, consolidating shelf space for established suppliers with robust quality management systems.
Market Restraints
- Cobalt chromium supply concentration:Foundry capacity for medical-grade alloys clusters in Germany and the United States, exposing manufacturers to energy cost volatility and single-source dependencies.
- FDA premarket approval timelines:Novel bearing surface innovations face extended clinical trial requirements that stretch development cycles and compress patent-protected commercialization windows.
- Non-surgical joint preservation therapies:Biologic injections and osteotomy techniques are capturing younger osteoarthritis patients before they reach arthroplasty eligibility.
Strategic Opportunities
- Japan's aging demographic:The world's oldest population presents underpenetrated demand for revision hip and knee procedures as early implant generations reach end-of-life.
- 3D-printed patient-specific instrumentation:Convergence of additive manufacturing with preoperative planning software is enabling customized cutting guides that reduce operative time and implant misfit rates.
- India's PLI scheme for medical devices:Production-linked incentives are attracting contract manufacturing investments that can serve domestic demand and regional export markets with localized cost structures.
Industry Challenges
- Robotics-trained surgeon scarcity:Health systems struggle to recoup capital investments in surgical platforms when fellowship-trained specialists concentrate in metropolitan academic centers.
- EU MDR technical documentation:Legacy implant families require retrospective clinical data compilation that strains regulatory affairs teams and delays portfolio rationalization decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endoprosthesis Market |
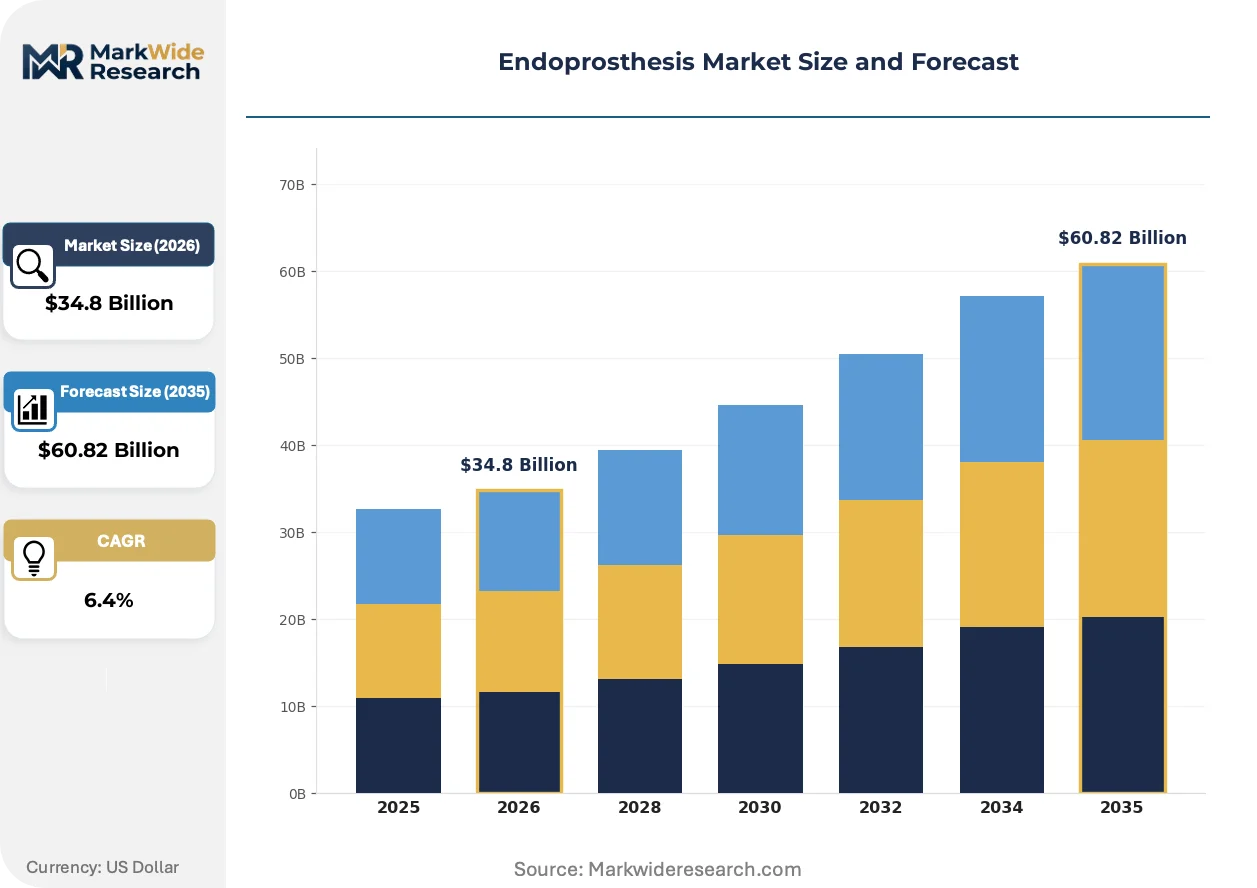
| Market Size in 2026 | $34.8 Billion |
| Market Size in 2035 | $60.82 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hip Prosthesis, Knee Prosthesis, Dental Implants, Spinal Implants, Cardiovascular Stents Material: Titanium Alloy, Stainless Steel, Ceramic, Polyethylene, Cobalt Chromium Application: Osteoarthritis Treatment, Spinal Degeneration, Dental Restoration, Cardiovascular Disease, Bone Fracture Repair End User: Orthopedic Surgeons, Dental Clinics, Cardiology Units, Rehabilitation Centers, Trauma Centers |
| Companies Covered | Smith & Nephew plc, Medacta International S.A., Zimmer Biomet Holdings, Inc., Exactech, Inc., MicroPort Scientific Corporation, Stryker Corporation, Boston Scientific Corporation, W.L. Gore & Associates, Inc., DePuy Synthes, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endoprosthesis Market Strategic Shifts & Innovations
Digital preoperative planning ecosystems are threading through every stage of joint replacement care, from templating software to postoperative remote monitoring, compressing variation in surgical outcomes and reshaping how implant manufacturers demonstrate value.
Sensor-embedded smart implants are unifying real-time biomechanical feedback with longitudinal patient monitoring. Orthopedic surgeons in integrated delivery networks are piloting these devices for early detection of implant loosening or abnormal gait patterns. The technology is unifying hardware revenue with recurring data service contracts, blurring traditional boundaries between device and digital health business models.
EU MDR Article 120 transition provisions are forcing systematic portfolio pruning across European markets. Manufacturers must prioritize high-volume hip and knee systems for renewed conformity assessments while withdrawing niche sizes and legacy designs. Knee revision components with limited clinical data are experiencing the sharpest compliance-driven attrition, redirecting R&D investment toward modular platform architectures that accommodate iterative updates.
Hospital procurement committees are consolidating vendor relationships through single-source frameworks that bundle implants with robotics access and staff training. Orthopedic service lines in the United States are negotiating multi-year agreements that lock in volume commitments and technical support tiers. This concentration is most visible in the southeastern United States, where health system mergers have created super-regional purchasing entities with sufficient scale to dictate customized instrument tray configurations and consignment inventory terms.
Endoprosthesis Market Segmentation
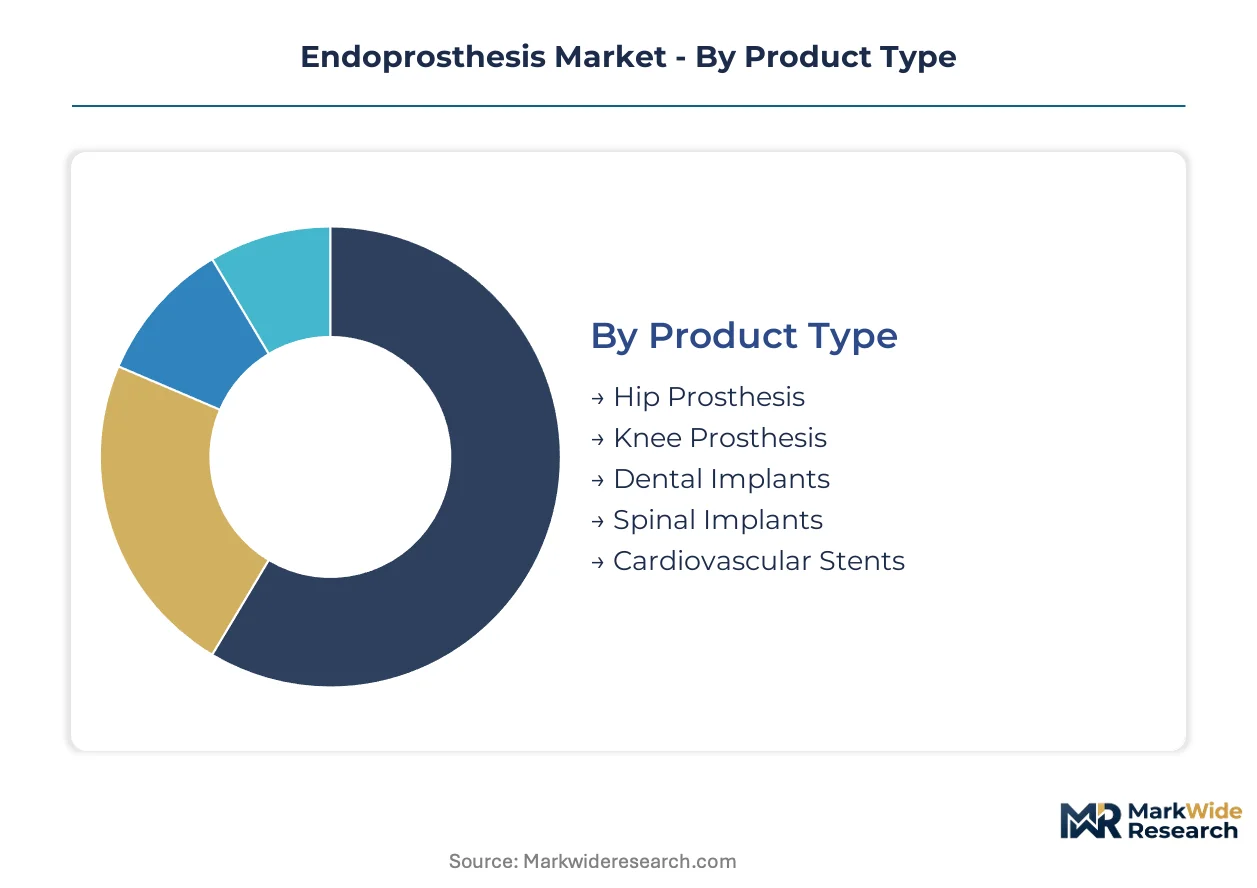
Endoprosthesis procurement patterns diverge sharply across product categories, with revision-cycle timing and bearing-surface durability driving replacement decisions. Material selection and end-user channel access determine margin capture and inventory turnover velocity for manufacturers competing across regulated markets.
Product Type:
Replacement-cycle intensity varies by anatomical site, with weight-bearing joints requiring earlier revision than dental or cardiovascular applications.
- Hip Prosthesis:Ceramic-on-ceramic and metal-on-polyethylene configurations dominate primary arthroplasty. United States hospital systems concentrate demand for modular stem designs that accommodate femoral canal variation.
- Knee Prosthesis:Fixed-bearing and rotating-platform constructs address tibiofemoral kinematics. Ambulatory surgical centers in the southeastern United States are accelerating same-day discharge protocols for unicompartmental systems.
- Dental Implants:Titanium screw-type fixtures integrate with alveolar bone through osseointegration protocols. Dental clinics in Germany favor immediate-loading designs that compress treatment timelines.
- Spinal Implants:Interbody cages and pedicle screw systems stabilize degenerative disc segments. Trauma centers prioritize titanium mesh constructs for corpectomy reconstruction.
- Cardiovascular Stents:Drug-eluting and bare-metal platforms restore vessel patency. Cardiology units in Japan leverage PMDA-approved bioresorbable scaffolds for younger patient cohorts.
Volume placements concentrate in hip and knee prosthesis; the faster expansion belongs to ambulatory-compatible knee systems.
Material:
Cost tiers separate medical-grade alloys from polymer and ceramic alternatives, with foundry capacity constraints influencing regional availability.
- Titanium Alloy:Biocompatible Ti-6Al-4V ELI dominates dental implant and spinal screw fabrication. Germany's foundry concentration shapes European supply security for aerospace-medical dual-use grades.
- Ceramic:Alumina and zirconia-toughened alumina reduce wear debris in active patient populations. Younger hip replacement candidates in the United States drive procurement committee preference for ceramic-on-ceramic bearings.
- Stainless Steel:316L grade serves provisional trauma fixation and cost-sensitive provisional implants. Rehabilitation centers in India utilize stainless constructs for temporary external fixation.
- Polyethylene:Cross-linked ultra-high molecular weight polyethylene articulates against metal or ceramic femoral heads. Vitamin E-stabilized variants extend oxidative stability in knee tibial inserts.
- Cobalt Chromium:CoCrMo casting and forging yield high-strength femoral heads and acetabular shells. Energy cost volatility at German foundries pressures margin structures for legacy implant families.
Premium positioning clusters around ceramic and titanium; polyethylene captures the highest unit volumes.
Application:
Patient age and activity level segment addressable populations, with biologic preservation therapies delaying surgical eligibility in younger cohorts.
- Osteoarthritis Treatment:Degenerative joint disease in weight-bearing anatomies drives hip and knee replacement volume. United States Medicare reimbursement stability sustains procedure frequency for primary arthroplasty.
- Cardiovascular Disease:Coronary and peripheral artery stenosis interventions deploy metallic and bioresorbable scaffolds. Cardiology units in Germany integrate intravascular imaging for stent sizing precision.
- Spinal Degeneration:Disc herniation and spondylolisthesis indications fuse motion segments. Trauma centers in Japan apply hybrid constructs combining interbody fusion with posterior instrumentation.
- Dental Restoration:Edentulism and partial arch reconstruction utilize endosseous and subperiosteal designs. Dental clinics in urban India are scaling immediate-implant protocols for aesthetic zone rehabilitation.
- Bone Fracture Repair:Comminuted and open fractures require internal fixation with plates, nails, and screws. Rehabilitation centers prioritize titanium elastic nailing for pediatric long-bone injuries.
Procedure volume concentrates in osteoarthritis treatment; cardiovascular disease applications are climbing the fastest.
End User:
Channel access and technical training requirements fragment purchasing authority across surgical specialties and care settings.
- Orthopedic Surgeons:Fellowship-trained arthroplasty specialists command robotics platform access and implant selection authority. Integrated delivery networks in the United States negotiate volume commitments through single-source frameworks.
- Cardiology Units:Interventional cardiologists deploy stents through catheterization laboratories. Germany's hospital procurement committees bundle drug-eluting platforms with imaging system service contracts.
- Dental Clinics:Oral surgeons and prosthodontists coordinate implant placement with restorative workflows. Private practice networks in Japan emphasize digital impression integration for abutment customization.
- Trauma Centers:Acute care surgeons manage polytrauma and open fracture stabilization. Level I centers in the United States stock comprehensive plating systems for pelvic and acetabular reconstruction.
- Rehabilitation Centers:Post-acute facilities coordinate prosthetic fitting and gait training. Germany's rehabilitation hospital networks manage revision hip and knee recovery pathways.
Procurement authority concentrates among orthopedic surgeons; dental clinics are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German foundries supply medical-grade alloys to implant fabricators worldwide, while the United States consumes the highest absolute volume of hip and knee procedures. Japan's aging population drives revision surgery demand as early implant generations require replacement.
United States
Medicare reimbursement stability sustains primary arthroplasty volumes across hospital systems and ambulatory surgical centers. FDA premarket approval pathways govern commercial entry for novel bearing surfaces and robotics platforms. The southeastern United States concentrates super-regional purchasing entities that negotiate multi-year implant supply agreements.
Germany
EU MDR recertification deadlines accelerate market exits by smaller manufacturers lacking robust quality management systems. Foundry capacity for cobalt chromium and titanium alloys clusters in industrial regions, exposing supply chains to energy cost volatility. Procurement committees in university hospitals bundle drug-eluting stents with imaging system service contracts.
Japan
The world's oldest population generates underpenetrated demand for revision hip and knee procedures as early implant generations reach end-of-life. PMDA localization standards favor regional manufacturing partnerships over direct export for cardiovascular and orthopedic applications. Kanto region hospitals pilot sensor-embedded smart implants for longitudinal patient monitoring.
China
NMPA imposes additional localization standards that favor domestic manufacturing partnerships for implantable devices. Production-linked incentives under medical device industrial policy attract contract manufacturing investments serving domestic and regional export markets. Yangtze River Delta medical technology clusters scale additive manufacturing capabilities for patient-specific instrumentation.
India
PLI scheme incentives for medical devices attract contract manufacturing investments with localized cost structures for domestic and export markets. CDSCO regulatory pathways govern commercial entry for imported and domestically fabricated implants. Maharashtra and Gujarat industrial corridors concentrate dental implant fabrication and trauma fixation device assembly.
Endoprosthesis Market Key Industry Players
Top-tier vendors anchor integrated delivery network contracts, while mid-tier specialists compete on robotics compatibility and bearing surface innovation. The vendor base stratifies across comprehensive portfolio holders, robotics platform integrators, and regional manufacturing specialists. Two dominant competitive moves are consolidating: M&A to capture robotics ecosystems and backward integration into medical-grade alloy foundries to secure supply.
Among diversified orthopedic holding companies, Zimmer Biomet Holdings, Inc. and Stryker Corporation exemplify the comprehensive portfolio archetype. Smith & Nephew plc occupies a position within the advanced wound management and sports medicine specialization tier. These three entities represent contrasting strategic postures—hardware bundling, robotics platform anchoring, and adjacent therapy integration—without any single approach dominating procurement committee selection criteria.
| Leading Market Players |
|---|
| Smith & Nephew plc |
| Medacta International S.A. |
| Zimmer Biomet Holdings, Inc. |
| Exactech, Inc. |
| MicroPort Scientific Corporation |
| Stryker Corporation |
| Boston Scientific Corporation |
| W.L. Gore & Associates, Inc. |
| DePuy Synthes, Inc. |
| Others |
Cost & Logistics Intelligence
Super-regional purchasing entities in the southeastern United States negotiate multi-year implant supply agreements that lock in volume commitments and technical support tiers, compressing margin structures for manufacturers while rewarding scale-based pricing concessions.
Pricing Analysis
Margin tightening in standard-tier hip and knee systems reflects procurement committee consolidation through single-source frameworks that bundle implants with robotics access. Three-tier pricing structure across premium, standard, and economy levels separates ceramic-on-ceramic bearings from metal-on-polyethylene configurations from stainless trauma fixation. Ambulatory surgical centers exhibit highest price sensitivity as same-day discharge protocols compress reimbursement yields, while academic medical centers absorb premium positioning for bearing surface innovation.
Supply Chain Analysis
Dual-sourcing requirements for medical-grade alloys mandate qualification of foundry partners across multiple jurisdictions, with orthopedic implant fabricators maintaining approved supplier lists in Germany and the United States. Cobalt chromium casting and titanium alloy forging draw from concentrated European and North American foundry capacity. Single-source vulnerability persists for ceramic powder suppliers serving bearing surface manufacturers. Distribution runs through consignment inventory models at integrated delivery networks, with instrument tray configurations customized to hospital system specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
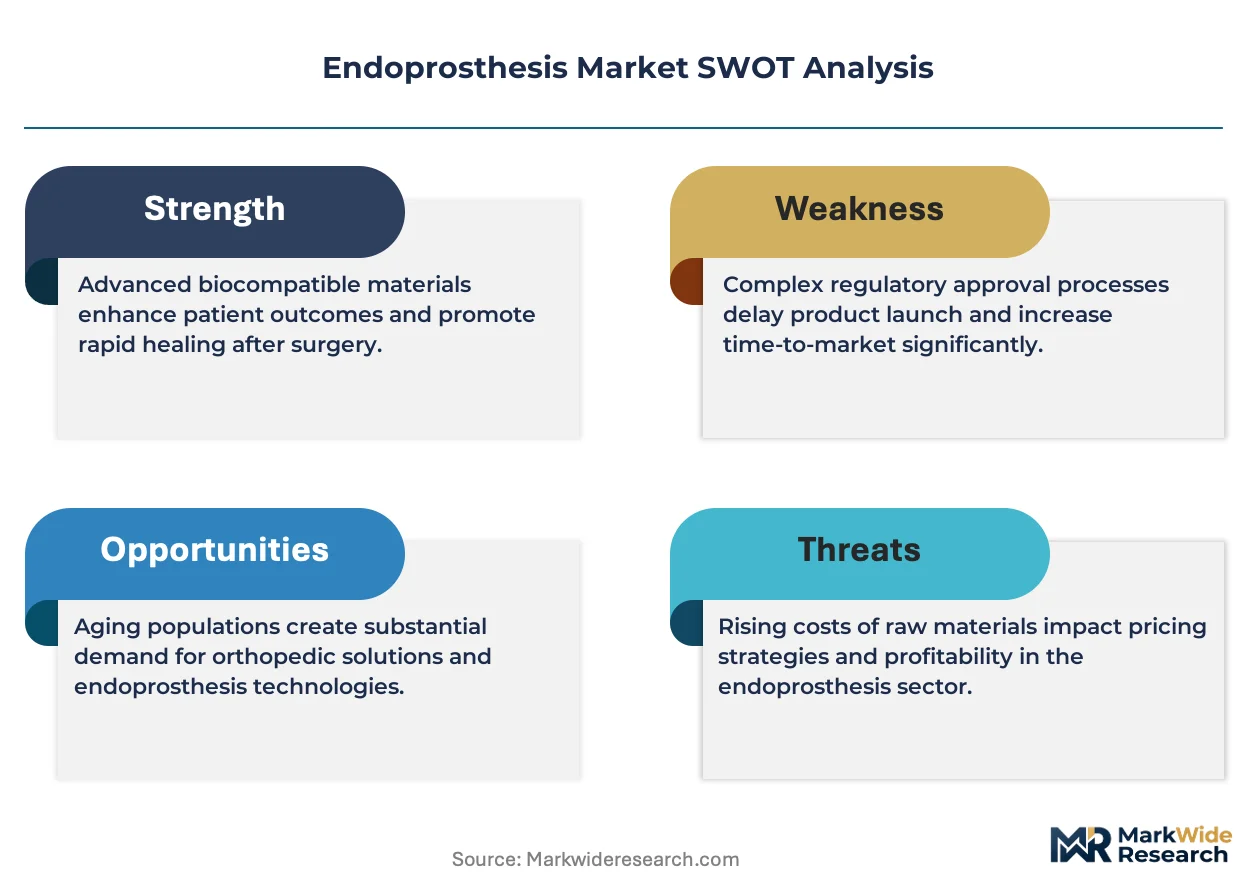
The endoprosthesis market is consolidating as EU MDR recertification deadlines force smaller manufacturers lacking robust quality management systems to exit, concentrating shelf space for established suppliers.
For Market Incumbents: Anticipate accelerated portfolio pruning as legacy implant families require retrospective clinical data compilation that strains regulatory affairs teams. Prioritize modular platform architectures that accommodate iterative updates without triggering full conformity reassessments. Secure backward integration into medical-grade alloy foundries to mitigate energy cost volatility exposure at German suppliers. For New Entrants and Emerging Players: Begin with sensor-embedded smart implant development for integrated delivery networks piloting real-time biomechanical feedback systems. Target Japan's revision hip and knee segment where early implant generations reach end-of-life and PMDA localization standards favor regional manufacturing partnerships. Deploy direct hospital system contracting to bypass GPO concentration. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier robotics platform specialists in Germany facing EU MDR technical documentation strains. Long-term viability hinges on capturing recurring data service contracts that blur hardware and digital health revenue boundaries. Monitor FDA breakthrough device pathway approvals as inflection indicators for novel bearing surface commercialization windows.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Recertification Acceleration | Legacy device exits consolidate shelf space for quality-system-compliant suppliers in German markets. |
| Robotics Platform Integration | Surgeon loyalty tightens around systems bundling hardware with consumable implant revenue streams. |
| Smart Implant Data Service Development | Real-time biomechanical feedback unifies hardware revenue with longitudinal monitoring contracts. |
| Foundry Backward Integration | Captive supply of cobalt chromium and titanium alloys insulates margin structures from energy volatility. |
| Japan Localization Partnership | PMDA manufacturing requirements favor regional joint ventures over direct export for revision procedures. |
Research Approach
Multi-period observation of hip and knee replacement procedure volumes, ambulatory surgical center expansion rates, and EU MDR conformity assessment timelines anchored the trend analysis, supplemented by interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs directors at implant manufacturers. Secondary validation drew from FDA premarket notification databases, EUDAMED device registrations, CMS Medicare procedure data, hospital procurement contract disclosures, and trade customs records for medical-grade alloy shipments. Bottom-up implant unit projections and top-down market value estimates underwent iterative reconciliation.
Segment-weighting across product type, material composition, application indication, and end-user channel shaped the analytical framework across the analysis window. Hip and knee prosthesis categories received distinct volume modeling reflecting replacement-cycle intensity variation. CAGRs derived from procedure volume trajectories, reimbursement code stability assessments, and ambulatory migration penetration curves. Forecast inputs incorporated ceramic-on-ceramic bearing adoption slopes and robotics-trained surgeon concentration metrics.
Underlying measurement precision varies by segment; hip and knee prosthesis carry tighter precision than dental implant and cardiovascular stent categories due to established procedure coding and reimbursement transparency. Forecasts reflect assumptions regarding EU MDR transition timeline adherence, FDA premarket approval pathway efficiency, and ambulatory surgical center eligibility expansion for total joint replacement. Deviation in cobalt chromium foundry capacity constraints or robotics platform capital expenditure cycles would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pedicle Screw Systems Market
Medical Devices
Hybrid Grafts Market
Medical Devices
Global Biopsy Punch Market
Medical Devices
Global Microelectronic Medical Implants Market
Medical Devices
Microcurrent Facial Market
Medical Devices
Tubal Obstruction Devices Market
Medical Devices
Transcatheter Pacing System Market
Medical Devices
Medical Oxygen Sensors Market
Medical Devices
Smart Bassinet Market
Medical Devices
Global Digital Pathology Systems Market
Medical Devices
Penile Prosthesis Market
Medical Devices
Wearable Breast Pumps Market
Medical Devices
Baby Warmer Devices Market
Medical Devices
Saudi Arabia Respiratory Devices Market
Medical Devices
Ventilator Accessories Market
Medical Devices
Smart Vision Aids Market