
 Medical Fiber Optics Market | 2026-2036
Medical Fiber Optics Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Fiber Optics Market Intelligence
Germany is tilting toward expanded cleanroom fiber production for minimally invasive surgical suites. Schott AG leverages its specialty glass expertise to anchor European supply of rigid endoscopic fibers. Coherent, Inc. sustains R&D intensity in high-power laser delivery systems for urology and ophthalmology. LEONI dominates automotive-derived fiber know-how repurposed for medical-grade cabling, while Timbercon, Inc. specializes in custom patch cord assemblies for OEM device manufacturers.
Medical fiber optics denotes silica or fluoride glass filaments with core diameters from 50 to 1000 micrometers, clad with lower-refractive-index material to transmit visible and near-infrared light with minimal attenuation for illumination, imaging, or laser energy delivery inside bodily cavities. Imaging fibers command mature margins in diagnostic gastroenterology, while laser fibers for interventional procedures represent the fastest-expanding application pool. Optical Coherence Tomography technology leads ophthalmic and intravascular diagnostics, whereas Fiber Laser Systems capture expanding share in dermatology and lithotripsy.
FDA 510(k) clearance pathways and EU MDR Class IIa/IIb device classifications govern biocompatibility, sterilization resilience, and optical performance claims for fiber-based instruments. ISO 10993 cytotoxicity testing and IEC 60601-1 electrical safety standards further constrain material selection and coating chemistry. Stakeholders must monitor evolving notified body capacity in Europe and FDA digital health pre-certification pilots that could accelerate software-integrated fiber imaging platforms.
Market Dynamics
Minimally invasive surgical suites are demanding fiber geometries that bend tighter radii without signal loss, forcing manufacturers to reconfigure draw tower processes and cladding chemistries around procedure-specific illumination and laser delivery requirements.
Growth Catalysts
- EU MDR Class IIb pathway acceleration:Streamlined conformity assessments for reusable endoscopic fibers are compressing time-to-market for European OEMs.
- Lithotripsy laser adoption:Urology departments in United States academic medical centers are replacing Holmium systems with Thulium fiber laser platforms requiring specialized silica-silica delivery fibers.
- Cleanroom capacity expansion:German manufacturing clusters are adding ISO 5-rated draw towers dedicated to medical-grade multimode fiber production.
Market Restraints
- High-purity silica precursor concentration:Synthetic quartz crucible supply concentrates among three Japanese chemical suppliers, exposing fiber manufacturers to input volatility.
- FDA 510(k) substantial equivalence barriers:Novel polymer cladding materials face extended predicate device searches, delaying iterative product improvements.
- Polymer optical fiber substitution:Short-haul illumination applications in disposable scopes are migrating to PMMA-based alternatives below 650 nanometer wavelengths.
Strategic Opportunities
- Intravascular imaging convergence:Optical Coherence Tomography catheter assembly houses seek integrated fiber-lens subassemblies combining imaging and therapeutic channels.
- India CDSCO manufacturing incentives:Production-linked incentive schemes for medical devices are attracting fiber pigtail and connector assembly investments near Mumbai and Chennai.
- Single-use endoscope fiber modules:OEMs are unbundling illumination bundles from capital equipment, creating aftermarket consumable revenue streams.
Industry Challenges
- Specialized fusion splicer technician scarcity:Precision alignment of dissimilar fiber cores for laser delivery systems requires skills concentrated among German and Japanese equipment operators.
- ISO 10993-5 cytotoxicity retesting burden:Minor coating formulation adjustments trigger full biocompatibility panel repetitions, consuming 14-18 month certification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Fiber Optics Market |
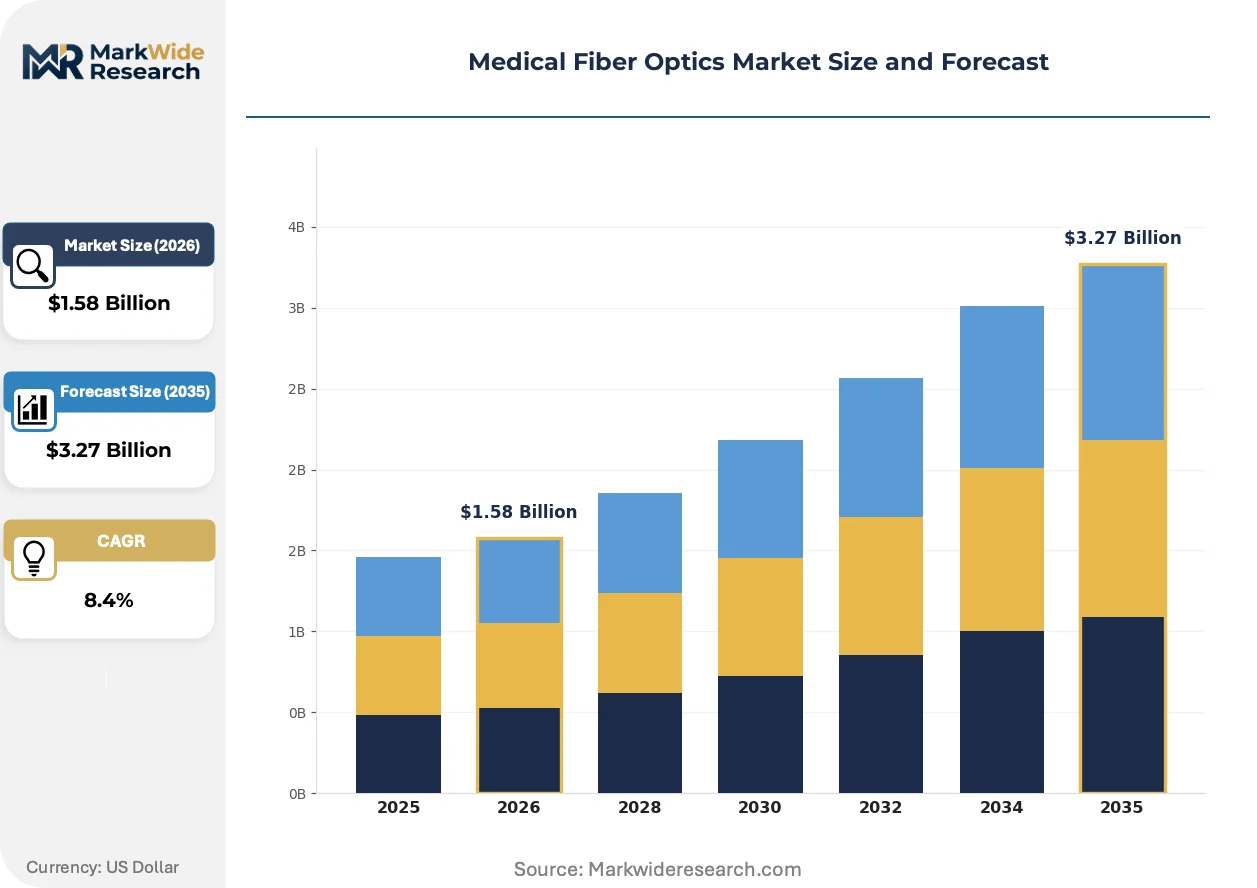
| Market Size in 2026 | $1.58 Billion |
| Market Size in 2035 | $3.27 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endoscopic Fibers, Imaging Fibers, Laser Fibers, Specialty Fibers Application: Interventional Procedures, Surgical Techniques, Diagnostic Imaging, Light Therapy End User: Hospitals, Clinics, Laboratories, Surgical Centers Technology: Optical Coherence Tomography, Fluorescence Imaging, Laser Ablation, Fiber Laser Systems |
| Companies Covered | Fiberoptics Technology Incorporated, Timbercon, Inc., Coherent, Inc., Schott AG, Integra LifeSciences, MKS Instruments, LEONI, Gulf Fiberoptics, Thorlabs, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Fiber Optics Market Strategic Shifts & Innovations
Active alignment between fiber imaging modalities and surgical robotics is compressing development cycles for OEM-integrated illumination engines. Device manufacturers now specify fiber subassemblies earlier in system architecture, embedding optical performance into mechanical design rather than retrofitting.
Photonic crystal fiber is migrating from telecom research into medical laser delivery, offering hollow-core light guidance that eliminates nonlinear effects in high-peak-power urology applications. Systems integrators at United States ambulatory surgery centers are piloting these fibers for stone fragmentation procedures. The shift is compressing acceptable bending diameter specifications from 50 millimeters toward 20 millimeters without power degradation.
EU MDR Article 10 technical documentation requirements are forcing fiber suppliers to maintain design dossiers traceable to raw material lots. Notified body capacity constraints in Germany and the Netherlands are extending audit queues, prompting manufacturers to front-load clinical evaluation reports. Rigid endoscope fiber bundles face the steepest compliance burden due to reusable device classification and sterilization validation demands.
Hospital procurement committees are consolidating fiber-based device purchasing under capital equipment agreements rather than separate consumable contracts. Integrated delivery networks in United States metropolitan markets are negotiating multi-year illumination engine supply arrangements that bundle service, replacement, and upgrade pathways. This consolidation is marginalizing independent fiber assembly houses lacking OEM certification depth.
Medical Fiber Optics Market Segmentation
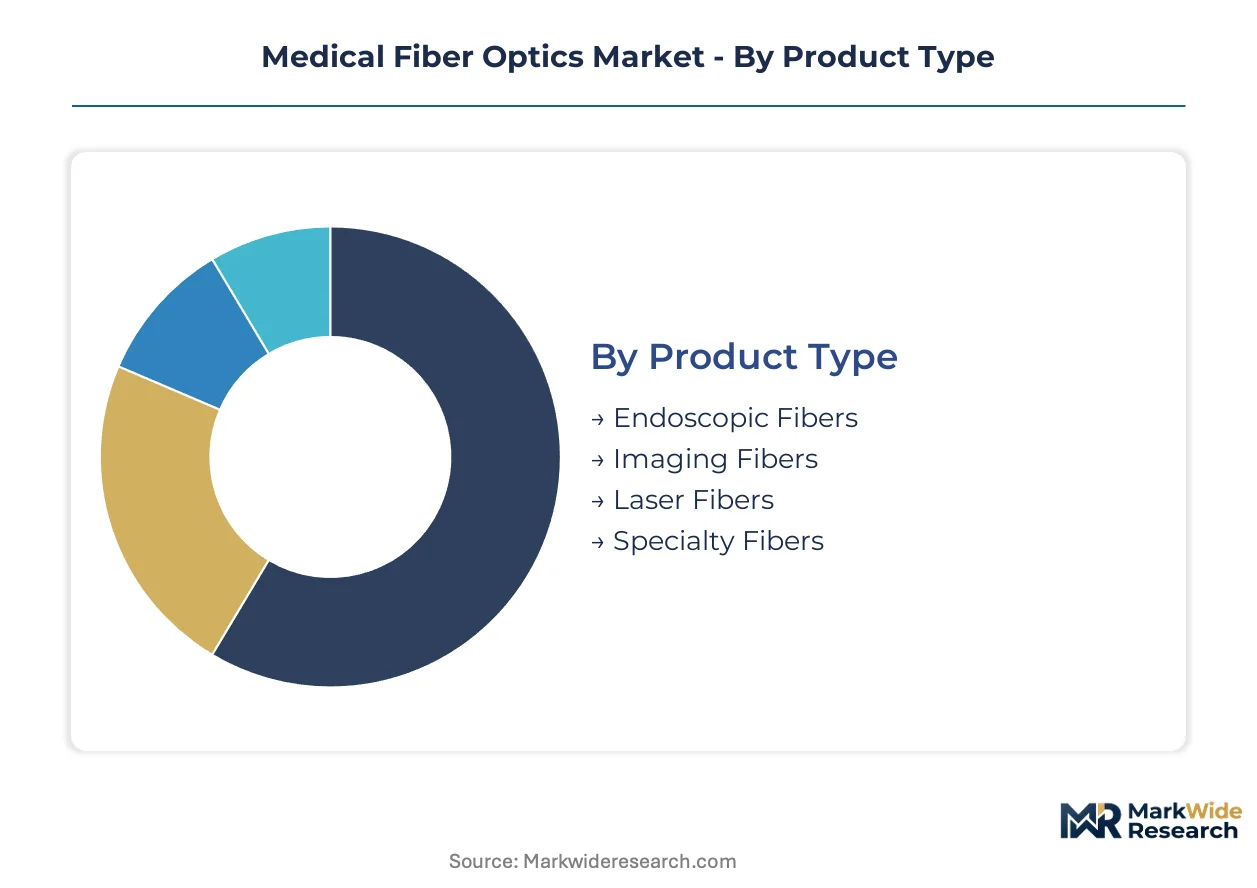
Medical fiber optics segmentation reveals stark contrasts in replacement cycles, with single-use laser fibers turning over in days while rigid endoscopic bundles persist for years. Understanding these velocity differentials shapes inventory planning and margin capture strategies across the supply chain.
Product Type:
Laser fibers rotate through hospital supply chains fastest, measured in procedure counts rather than calendar quarters, while endoscopic bundles amortize over capital equipment lifecycles.
- Laser Fibers:Silica-silica step-index constructions with core diameters of 200-600 micrometers deliver Holmium and Thulium laser energy for lithotripsy and tissue ablation. United States academic medical centers are converting to Thulium fiber laser platforms faster than European installations, driving demand for fibers rated above 100 watts average power.
- Imaging Fibers:Coherent fiber bundles with 10,000-50,000 pixel elements transmit diagnostic images from distal lens assemblies to camera processors. Diagnostic gastroenterology suites in Germany and Japan maintain the densest installed bases, though replacement rates lag laser fibers by an order of magnitude.
- Endoscopic Fibers:Rigid rod-lens systems with fused fiber illumination bundles for surgical suites.
- Specialty Fibers:Photonic crystal and fluoride glass variants for niche wavelength transmission.
Imaging fibers dominate installed base. Laser fibers are where expansion concentrates.
Application:
Interventional procedures command premium pricing per procedure, while diagnostic imaging generates volume through screening program scale.
- Interventional Procedures:Percutaneous laser ablation and lithotripsy require fibers with precise energy coupling and thermal management. United States urology departments are standardizing on single-use disposable laser fibers to eliminate reprocessing validation burdens.
- Diagnostic Imaging:Optical coherence tomography and fluorescence-guided visualization for early lesion detection. Japanese ophthalmology clinics deploy the highest per-capita density of OCT imaging fibers, supported by national screening reimbursement frameworks.
- Surgical Techniques:Illumination and targeting fibers for minimally invasive suites.
- Light Therapy:Photobiomodulation and photodynamic therapy delivery fibers.
Diagnostic imaging commands procedure volume. Interventional applications are climbing the fastest.
End User:
Hospitals consolidate fiber procurement under capital equipment contracts, while surgical centers favor disposable-heavy models with minimal sterilization infrastructure.
- Hospitals:Integrated delivery networks negotiate multi-year illumination engine agreements bundling service, replacement, and upgrade pathways. German hospital procurement committees are migrating toward total-cost-of-ownership contracts that internalize fiber replacement schedules.
- Surgical Centers:Ambulatory facilities in United States metropolitan markets prioritize single-use fiber modules to minimize reprocessing labor and FDA 510(k) compliance documentation. These sites generate disproportionate laser fiber consumption per procedure slot.
- Clinics:Outpatient diagnostic settings with intermittent imaging fiber demand.
- Laboratories:Research and pathology applications with specialized wavelength requirements.
Hospitals anchor revenue stability. Surgical centers are gaining share fastest.
Technology:
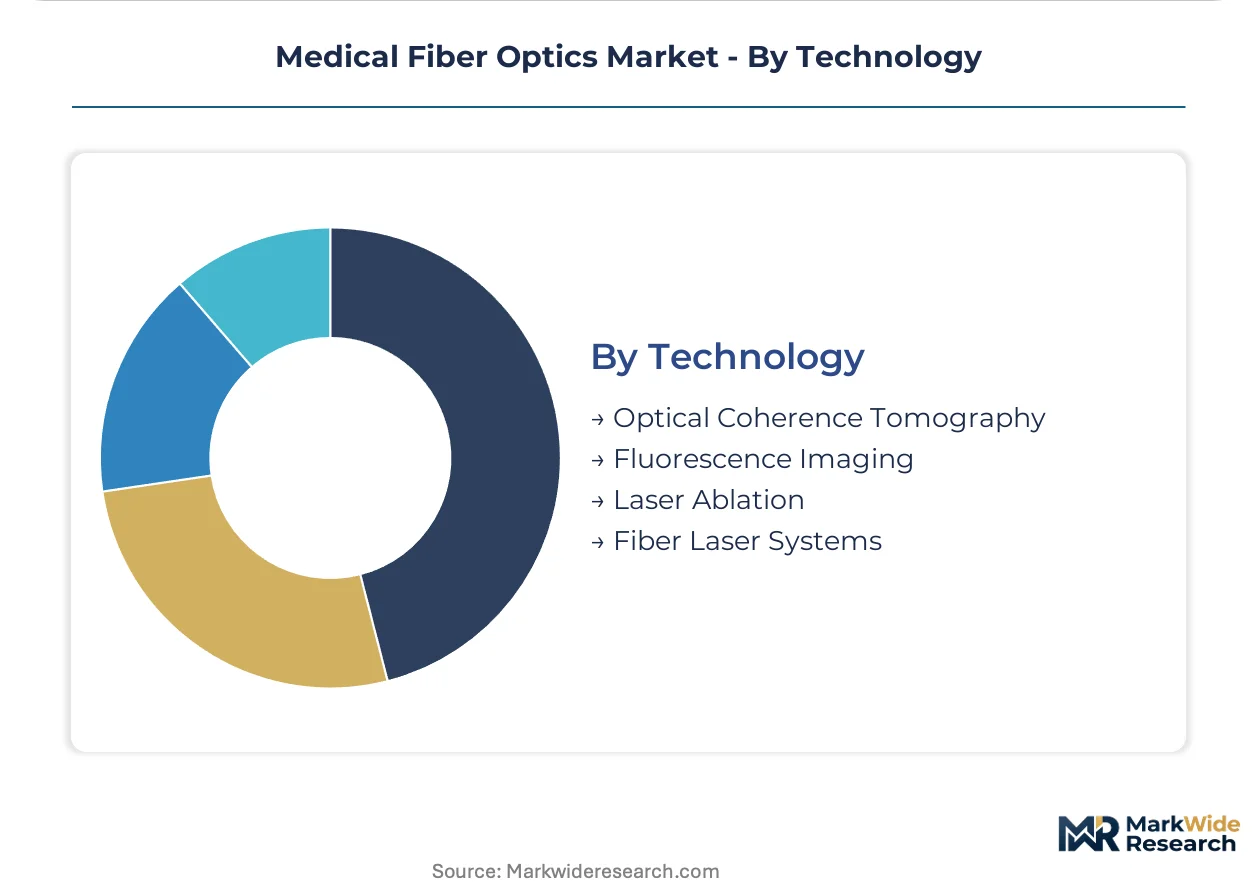
Fiber laser systems and OCT platforms are diverging in architecture, with the former demanding power-handling geometries and the latter prioritizing image fidelity at tight bend radii.
- Fiber Laser Systems:Thulium and erbium-doped fiber amplifiers for surgical ablation with tunable pulse parameters. United States dermatology practices are adopting these platforms for precise tissue vaporization with reduced thermal collateral zones.
- Optical Coherence Tomography:Single-mode fiber interferometers with swept-source or spectral-domain detection for micron-scale resolution. Intravascular OCT catheter assembly houses in Japan seek integrated fiber-lens subassemblies combining imaging and therapeutic channels.
- Laser Ablation:Direct energy delivery without amplification for stone fragmentation.
- Fluorescence Imaging:Filtered excitation and emission fiber paths for molecular contrast agents.
OCT dominates diagnostic technology deployment. Fiber laser systems are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty glass precursor supply concentrates among Japanese chemical suppliers, exposing fiber manufacturers to input volatility while endoscopic procedure demand clusters in United States, German, and Japanese hospital systems.
United States
Academic medical centers in Boston and Baltimore are converting urology departments to Thulium fiber laser platforms faster than European installations. FDA 510(k) clearance pathways govern biocompatibility claims for reusable endoscopic fibers. Minneapolis and Phoenix surgical centers generate disproportionate single-use laser fiber consumption per procedure slot.
Germany
Hospital procurement committees in Munich and Stuttgart are migrating toward total-cost-of-ownership contracts that internalize fiber replacement schedules. EU MDR Class IIb pathway acceleration is compressing time-to-market for reusable endoscopic fibers. Cleanroom manufacturing clusters in Mainz and Jena are adding ISO 5-rated draw towers dedicated to medical-grade multimode fiber production.
Japan
Ophthalmology clinics in Tokyo and Osaka deploy the highest per-capita density of OCT imaging fibers, supported by national screening reimbursement frameworks. PMDA device classifications constrain coating chemistry and sterilization validation requirements. Nagoya and Kyoto intravascular catheter assembly houses seek integrated fiber-lens subassemblies combining imaging and therapeutic channels.
India
Production-linked incentive schemes for medical devices are attracting fiber pigtail and connector assembly investments near Mumbai and Chennai. CDSCO manufacturing incentives are reshaping supplier geography for disposable scope illumination modules. Hyderabad and Bengaluru OEM integration facilities are embedding optical performance into mechanical design earlier in system architecture.
United Kingdom
London and Cambridge integrated delivery networks are negotiating multi-year illumination engine supply arrangements that bundle service, replacement, and upgrade pathways. MHRA post-Brexit regulatory alignment with EU MDR technical documentation requirements is extending audit preparation timelines. Glasgow and Manchester surgical centers prioritize single-use fiber modules to minimize reprocessing labor burdens.
Medical Fiber Optics Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying fiber subassemblies to OEM device manufacturers. The vendor base stratifies across three tiers: multinational glass and laser technology conglomerates with captive medical divisions, mid-cap fiber cable specialists repurposing automotive or telecom expertise, and regional custom assembly houses serving niche OEM certification requirements. Dominant competitive moves include cleanroom capacity expansion near hospital procurement clusters and strategic partnerships between fiber draw tower operators and endoscope OEMs for co-development of procedure-specific geometries.
Within the specialty glass tier, Schott AG and Coherent, Inc. anchor European and North American supply of rigid endoscopic and high-power laser delivery fibers respectively. LEONI exemplifies the cable-centric archetype, occupying a position between automotive-derived fiber know-how and medical-grade cabling requirements. Timbercon, Inc. represents the custom assembly specialist model, sitting within the OEM certification ecosystem for patch cord subassemblies.
| Leading Market Players |
|---|
| Fiberoptics Technology Incorporated |
| Timbercon, Inc. |
| Coherent, Inc. |
| Schott AG |
| Integra LifeSciences |
| MKS Instruments |
| LEONI |
| Gulf Fiberoptics |
| Thorlabs, Inc. |
| Others |
Cost & Logistics Intelligence
Freight corridors connecting German cleanroom clusters to United States hospital systems transmit cost volatility from silica precursor markets into tiered fiber pricing, amplifying spreads between premium laser delivery systems and commoditized illumination bundles as procurement committees consolidate purchasing power.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing structure across premium, standard, and economy levels in the medical fiber optics sector. Premium fibers carrying Thulium laser compatibility and ISO 10993-5 cytotoxicity certification command substantial markups over standard diagnostic bundles, while economy-tier PMMA-based alternatives for disposable scopes face the sharpest cost compression from polymer substitution. United States ambulatory surgical centers exhibit the highest price sensitivity due to single-use consumption models, whereas German hospital procurement committees prioritize total-cost-of-ownership contracts that internalize long-term replacement schedules.
Supply Chain Analysis
Tariff exposure between Japanese chemical suppliers and German draw tower operators dominates supply chain risk architecture for synthetic quartz crucible inputs. High-purity silica precursor production concentrates in Japan, while medical-grade fiber drawing clusters in Germany and the United States depend on this upstream concentration for core material feedstock. Distribution runs through OEM device manufacturers rather than direct hospital sales, with Schott AG and Coherent anchoring European and North American supply nodes respectively.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
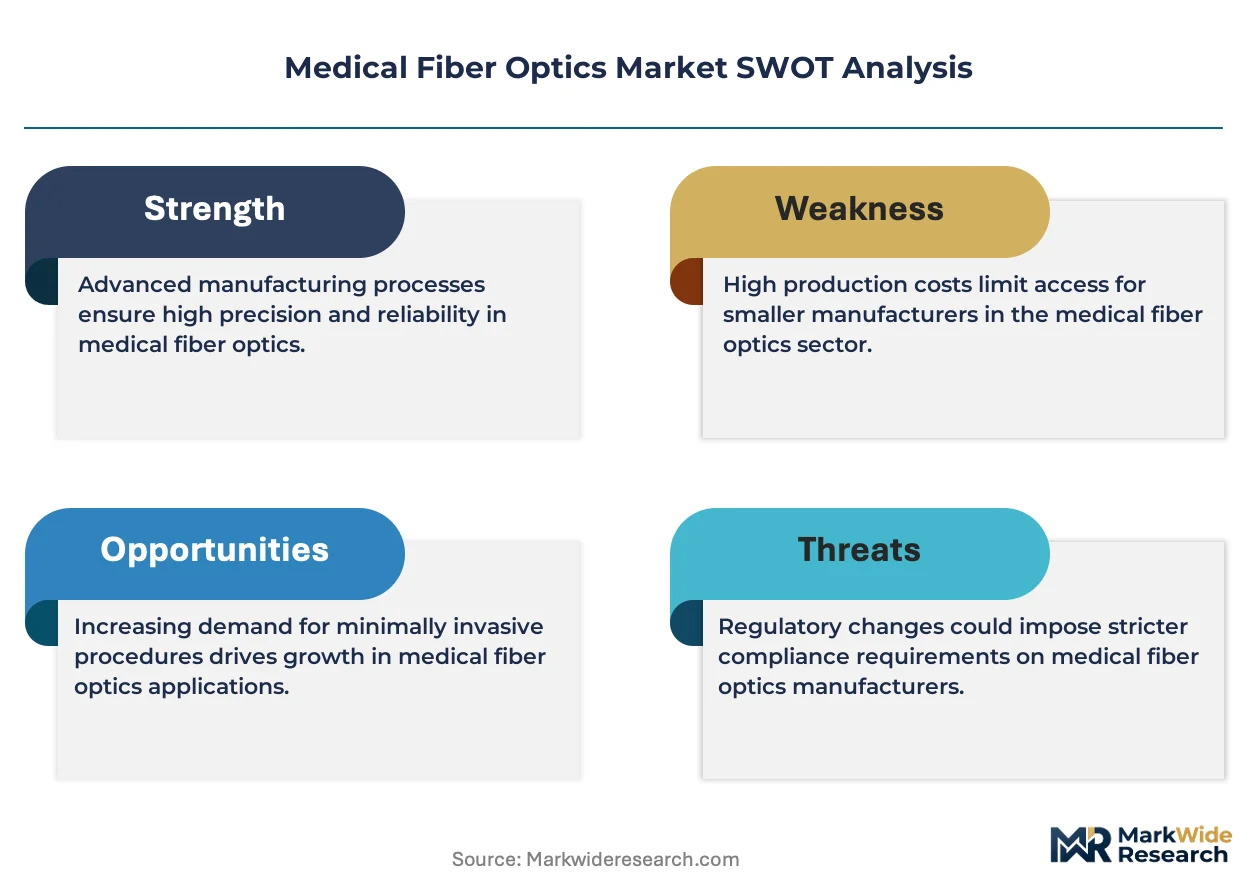
Fragmentation across procedure-specific fiber geometries creates defendable niches as minimally invasive surgical suites demand customized illumination and laser delivery configurations that resist commoditization.
For Market Incumbents: Pre-empt polymer optical fiber substitution in short-haul illumination by embedding silica-silica constructions into capital equipment contracts with multi-year service bundling. Deepen captive supply of high-purity silica precursors through strategic offtake arrangements with Japanese chemical suppliers to buffer input volatility. Fortify position against emerging photonic crystal fiber disruptors by accelerating co-development partnerships with surgical robotics OEMs for integrated fiber-lens subassemblies. For New Entrants and Emerging Players: Single-use laser fiber modules for United States ambulatory surgery centers represent the most penetrable entry point given minimal sterilization infrastructure requirements and rapid inventory turnover. Intravascular imaging convergence in Japanese catheter assembly houses offers a second white-space target, particularly for integrated fiber-lens subassemblies combining diagnostic and therapeutic channels. Pursue OEM certification depth through custom patch cord assembly contracts rather than competing directly with multinational glass conglomerates on scale. For Investors and Strategic Acquirers: Carve-out targets emerge from automotive-derived fiber cable specialists seeking medical-grade diversification to offset cyclical exposure in vehicle production. Long-term viability hinges on regulatory certification assets and cleanroom manufacturing infrastructure rather than pure technology differentiation. Monitor FDA digital health pre-certification pilot expansion as the inflection signal for software-integrated fiber imaging platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Capacity Expansion | ISO 5-rated draw towers in Mainz and Jena anchor European medical-grade multimode fiber supply security. |
| CE Marking Pathway Investment | EU MDR Class IIb technical documentation front-loading compresses audit queues for reusable endoscopic fibers. |
| Hospital System Partnership | Integrated delivery networks in Minneapolis and Phoenix consolidate fiber procurement under capital equipment agreements. |
| Software Companion Development | FDA digital health pre-certification pilots accelerate software-integrated OCT imaging platform market entry. |
| Reimbursement Strategy | Japanese national screening frameworks for ophthalmic diagnostics sustain per-capita OCT fiber deployment density. |
Research Approach
Operator-level perspectives from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and endoscope OEM integration specialists anchored the qualitative base for this analysis. Primary fieldwork combined with secondary validation from FDA 510(k) clearance databases, EU MDR notified body audit records, hospital procurement contract registries, and specialty glass trade flow data. Bottom-up fiber consumption modeling by procedure type and top-down market sizing through equipment installed base analysis were triangulated for convergence.
Scenario-bracketing around Thulium fiber laser adoption velocity and single-use endoscope penetration rates structured the analytical framework across the projection horizon. Segmentation dimensions included product type, application, end user, and technology platform, with CAGRs derived from procedure volume growth trajectories and replacement cycle compression factors. Forecast inputs incorporated cleanroom capacity expansion timelines and regulatory pathway acceleration effects without year-specific anchoring.
Macroeconomic conditions sit as an overlay; deviation in healthcare capital expenditure cycles or silica precursor pricing volatility would shift the trajectory substantially. Forecasts reflect documented assumptions regarding reimbursement stability and notified body capacity resolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Operating Microscopes Market
Medical Devices
At-Home Blood Collection Kits and Devices Market
Medical Devices
Multi-Channel Infusion Pumps Market
Medical Devices
High Intensity Focused Ultrasound (HIFU) Market
Medical Devices
Transcutaneous Oximetry Systems Market
Medical Devices
Medical Device Cros Market
Medical Devices
Breast Localization System Market
Medical Devices
Thermal Ablation Devices Market
Medical Devices
Non-Invasive Brain Trauma Monitoring Devices Market
Medical Devices
Mobile Operating Rooms Market
Medical Devices
Europe Artificial Organs and Bionic Implants Market
Medical Devices
US Medical Display Monitors Market
Medical Devices
Nerve Repair and Regeneration Market
Medical Devices
Medical Bionic Implants and Exoskeletons Market
Medical Devices
Pelvic Reconstruction Market
Medical Devices
Europe Mobility Aids Market