
 Therapeutic Support Surface Market | 2026-2036
Therapeutic Support Surface Market Size, Share, and Industry Trends Forecast 2026-2036
Therapeutic Support Surface Market Analytics
Modular mattress configurations is decoupling from full bed system sales, allowing hospitals to upgrade surfaces without capital equipment replacement. Stryker Corporation leverages its integrated bed-and-surface portfolio to anchor acute care contracts. Arjo competes through specialized bariatric and wound care positioning across European long-term care networks.
A therapeutic support surface is a pressure-redistribution device incorporating foam, air, or fluid-filled chambers engineered to maintain tissue perfusion and prevent pressure injury formation in immobilized patients. Foam mattresses incorporate viscoelastic and high-resilience polyurethane layers calibrated to immersion and envelopment standards. Alternating pressure systems command the largest revenue share due to established reimbursement codes, while lateral rotation surfaces represent the fastest-expanding category driven by ventilated patient protocols in critical care. Smart sensor integration is shifting margin pools toward technology-enabled surfaces that capture compliance data for quality reporting.
The FDA regulates therapeutic support surfaces as Class II medical devices under 21 CFR 880.5500, requiring 510(k) clearance for alternating pressure and low air loss systems. The EU MDR and ISO 10993 biocompatibility standards shape market access timelines and clinical evidence requirements for surface materials. Stakeholders must monitor how CMS pressure injury prevention quality metrics and evolving MDR notified body capacity will reshape procurement specifications and competitive positioning across acute and post-acute channels.
Market Dynamics
Smart sensor integration is decentralizing control over pressure injury prevention from centralized nursing protocols to autonomous surface-level monitoring, compressing response times and reshaping procurement specifications toward data-enabled contract terms.
Growth Catalysts
- EU MDR compliance deadlines:Active therapeutic surfaces face heightened clinical evidence requirements under the Medical Device Regulation, accelerating hospital replacement cycles for legacy equipment and expanding the addressable market for certified premium systems.
- ICU ventilation protocols:Lateral rotation surfaces are gaining adoption in critical care units managing ventilated patients, driven by established protocols linking automated repositioning to reduced ventilator-associated pneumonia incidence.
- Germany's reimbursement clarity:The country's structured Diagnosis-Related Group coding for pressure injury prevention creates predictable payment pathways that support premium surface uptake in acute and long-term care settings.
Market Restraints
- Polyurethane foam price volatility:Viscoelastic and high-resilience foam inputs face petrochemical feedstock cost swings that compress manufacturer margins and complicate long-term contract pricing.
- Notified body capacity constraints:EU MDR implementation has created bottlenecks in conformity assessment capacity, extending time-to-market for new active surface submissions and freezing product pipeline velocity.
- Static foam substitution:Basic foam mattresses retain share in price-sensitive post-acute channels where reimbursement constraints override clinical performance differentiation.
Strategic Opportunities
- Home care channel expansion:Aging-in-place demographics and hospital-at-home reimbursement pilots in the United States are creating demand for portable alternating pressure overlays outside institutional settings.
- Sensor-EMR convergence:Integration of surface pressure mapping with electronic medical record systems enables automated quality reporting for CMS Hospital-Acquired Condition reduction programs.
- Bariatric specialization:Rising obesity prevalence across OECD markets supports premium positioning for surfaces engineered to higher weight capacity and immersion standards.
Industry Challenges
- Biomedical engineering talent scarcity:Cross-functional expertise combining pressure mapping algorithms, materials science, and clinical workflow design remains concentrated among a limited pool of specialists.
- Legacy bed fleet incompatibility:Modular surface upgrades often require interface validation with installed bed frames from multiple manufacturers, complicating sales cycles and installation logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Therapeutic Support Surface Market |
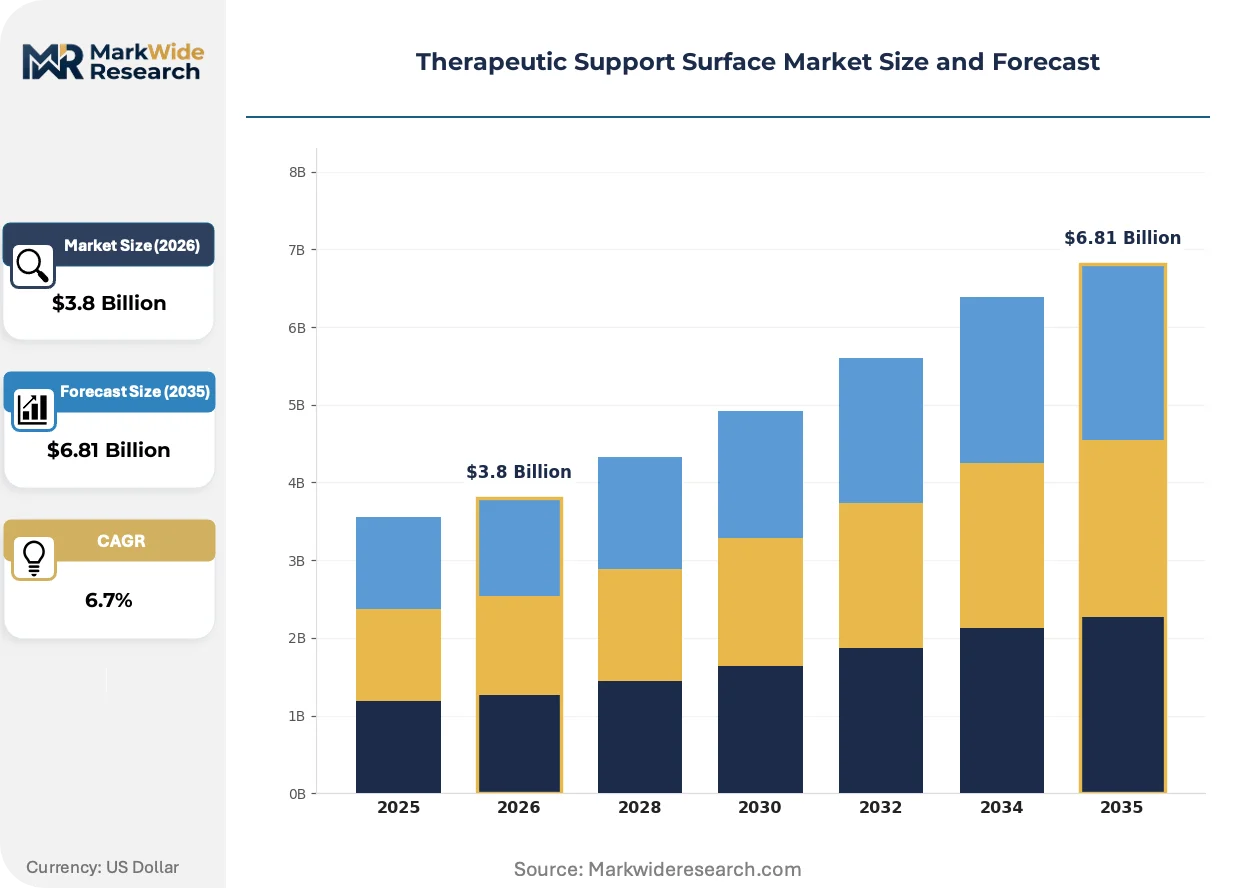
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alternating Pressure, Low Air Loss, Foam Mattresses, Lateral Rotation End User: Hospitals, Long-term Care Facilities, Home Care, Rehabilitation Centers Technology: Smart Sensors, Solenoid Valves, Microcontrollers, Pressure Mapping Distribution Channel: Direct Sales, Online Retail, Medical Supply Stores, Distributors |
| Companies Covered | Hill-Rom Holdings, Stryker Corporation, Invacare Corporation, Arjo, GF Health Products Inc, Apex Medical Corp, Drive DeVilbiss Healthcare, Joerns Healthcare, LINET Group SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Therapeutic Support Surface Market Evolving Landscape
Digitalization of surface-level patient monitoring is collapsing the information lag between pressure event occurrence and clinical intervention, embedding therapeutic support surfaces into broader hospital quality infrastructure.
Capacitive pressure sensing arrays are decentralizing tissue perfusion monitoring from periodic nurse assessments to continuous automated surveillance. Critical care units in tertiary hospitals are deploying these systems at accelerating rates. This technology is decentralizing accountability for pressure injury outcomes from nursing staff to integrated device-ecosystem vendors.
The EU MDR's post-market surveillance requirements are mandating systematic clinical follow-up data for active therapeutic surfaces. Manufacturers must now maintain vigilance systems capturing real-world performance evidence. Long-term care networks across Germany and France are prioritizing suppliers with established MDR technical documentation and notified body relationships.
Hospital purchasing consortia are consolidating surface procurement through multi-year enterprise agreements that bundle mattresses, beds, and service contracts. Independent distributors and regional equipment lessors are losing share to manufacturer-direct sales organizations. This concentration is most pronounced in the United States, where health system consolidation has created super-regional buyers with standardized formulary requirements.
Therapeutic Support Surface Market Segmentation
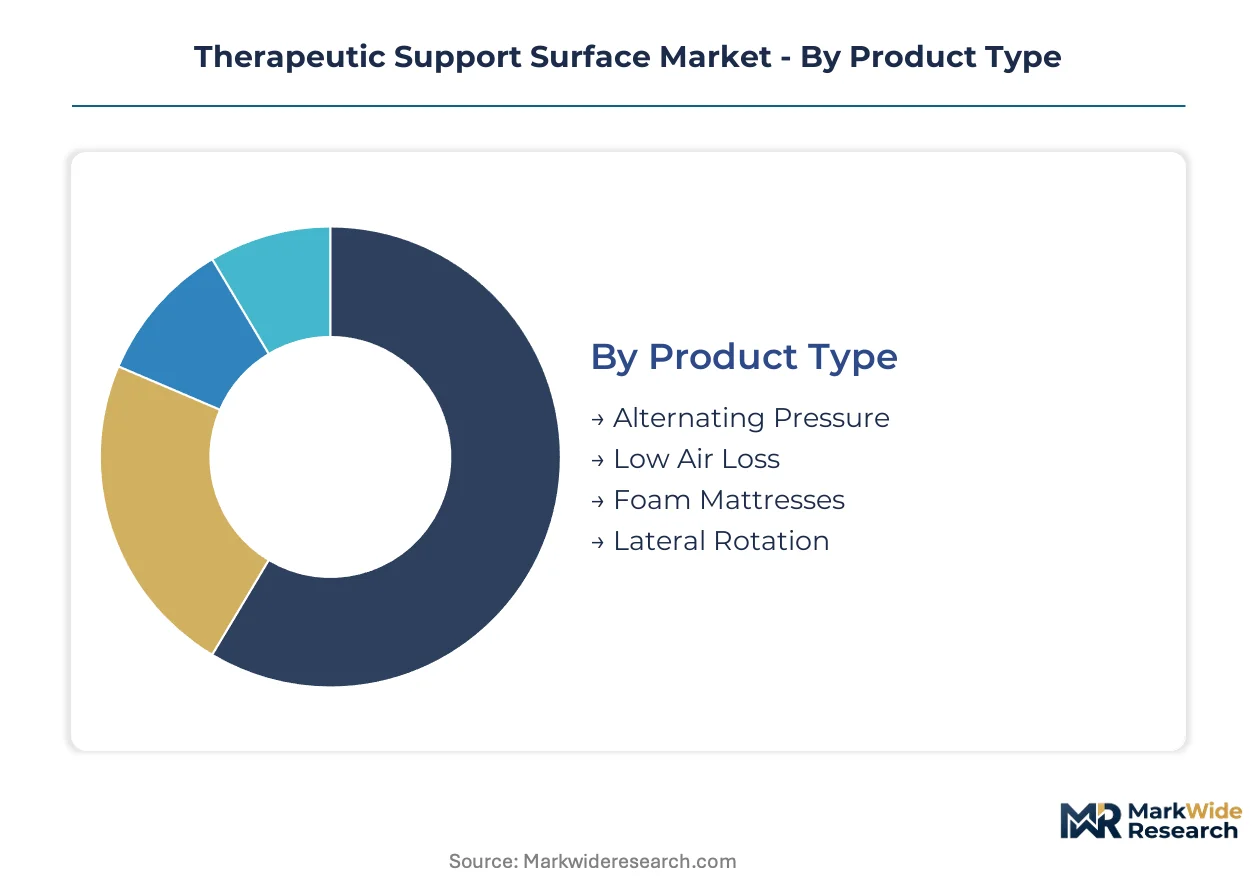
Segmentation in therapeutic support surfaces reveals how procurement specifications diverge across care settings and technology tiers. Understanding these splits enables manufacturers to align R&D investment with reimbursement pathways and clinical workflow requirements.
Product Type:
Capital intensity varies sharply across surface technologies, with active pneumatic systems requiring embedded electronics and precision valve engineering while foam-based products demand materials science expertise and molding infrastructure.
- Alternating Pressure:Cyclical inflation-deflation chambers powered by programmable pump units redistribute tissue loading through timed pressure relief cycles. German acute care networks and US hospital purchasing consortia dominate procurement volumes for these systems, driven by established DRG and CMS reimbursement codes that recognize their clinical efficacy in ICU settings.
- Lateral Rotation:Automated turning surfaces tilt patients at programmed intervals to maintain pulmonary drainage and prevent ventilator-associated complications. Critical care units managing mechanically ventilated patients in France and tertiary US medical centers are expanding deployment fastest, linking automated repositioning to reduced pneumonia incidence and shorter ventilation duration.
- Low Air Loss:Perforated air cells with continuous microclimate management prevent moisture accumulation and shear forces.
- Foam Mattresses:Viscoelastic and high-resilience polyurethane layers calibrated to immersion and envelopment standards serve cost-constrained post-acute channels.
Alternating pressure systems absorb the bulk of installed capacity; lateral rotation is expanding most quickly.
End User:
Procurement authority concentrates differently across channels, with hospitals exercising centralized capital budgeting while home care relies on patient-directed purchasing and third-party reimbursement.
- Hospitals:Acute care institutions command the largest contract values through enterprise agreements bundling surfaces, beds, and service coverage. US health system consolidation and EU hospital alliance purchasing have shifted negotiation leverage toward super-regional buyers with standardized formulary requirements.
- Long-term Care Facilities:Nursing homes and skilled nursing facilities prioritize durability and infection control in high-turnover environments. German and French networks are prioritizing suppliers with established EU MDR technical documentation and notified body relationships.
- Home Care:Aging-in-place demographics and hospital-at-home reimbursement pilots are creating demand for portable alternating pressure overlays.
- Rehabilitation Centers:Post-acute therapy settings require surfaces supporting early mobilization protocols and bariatric weight capacities.
Hospitals command the dominant share of contract value; home care is climbing the fastest as reimbursement pilots expand.
Technology:
Margin pools are shifting toward data-enabled components that capture compliance metrics for quality reporting and autonomous monitoring.
- Smart Sensors:Capacitive pressure sensing arrays enable continuous tissue perfusion surveillance and automated alert generation. Tertiary hospital critical care units in the United States and Germany are deploying these systems at accelerating rates.
- Pressure Mapping:Real-time visualization of pressure distribution supports clinical decision-making and documentation for CMS Hospital-Acquired Condition reduction programs.
- Solenoid Valves:Precision pneumatic control components regulate airflow in alternating pressure and low air loss systems.
- Microcontrollers:Embedded processing units execute pressure cycling algorithms and interface with EMR systems.
Smart sensors claim the steepest expansion trajectory; solenoid valves and microcontrollers constitute the embedded base.
Distribution Channel:
Channel economics reflect contract scale complexity, with direct sales capturing enterprise agreements while distributors serve fragmented regional buyers.
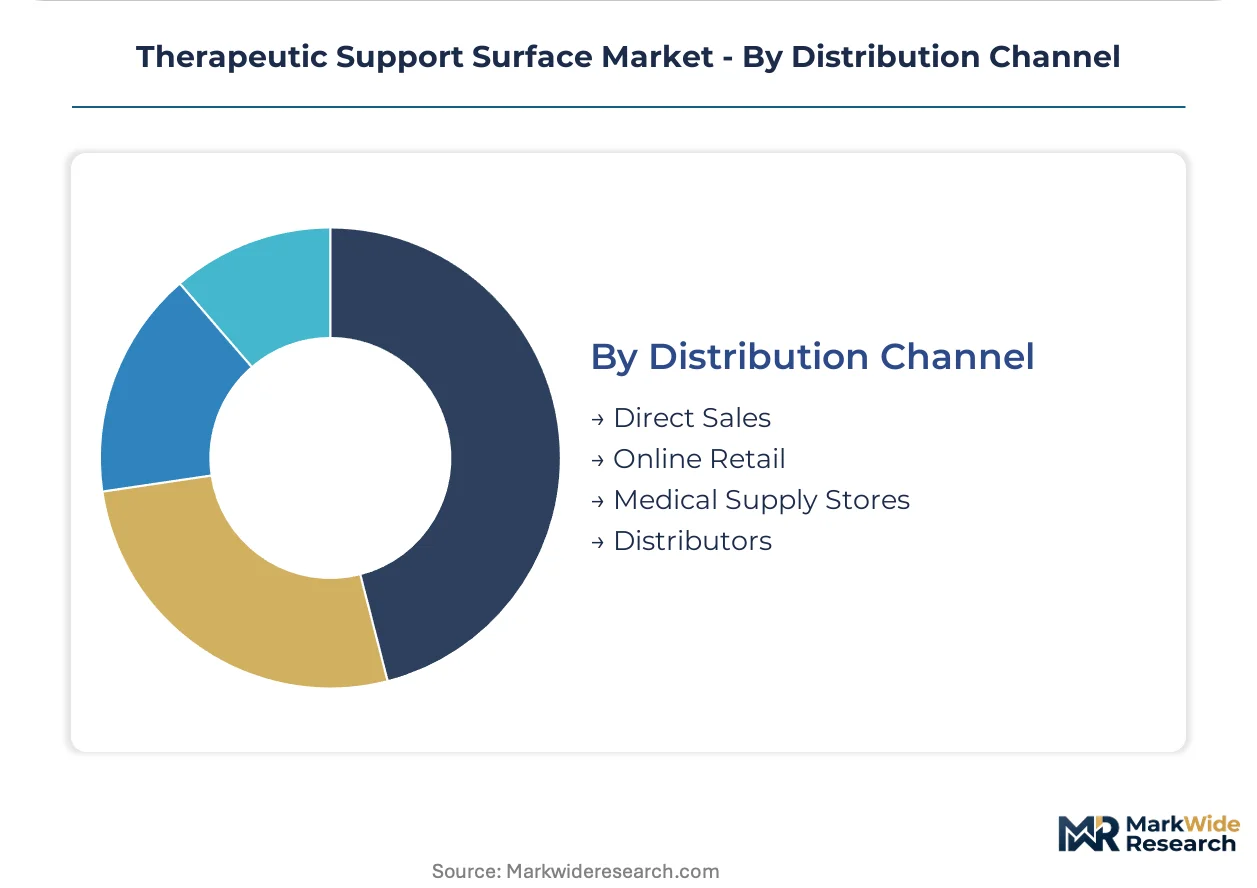
- Direct Sales:Manufacturer-direct organizations negotiate multi-year enterprise agreements bundling mattresses, beds, and service contracts. US health system consolidation has concentrated procurement through super-regional buyers with standardized formulary requirements.
- Distributors:Regional medical equipment lessors and independent distributors are losing share to direct sales but retain relevance in post-acute and home care segments.
- Medical Supply Stores:Local retail channels serve cash-pay home care customers and small facility replenishment.
- Online Retail:E-commerce platforms are emerging for standard foam overlays and consumer-grade pressure relief products.
Direct sales channels capture the majority of contract value; online retail is gaining share fastest in consumer-accessible segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical technology special economic zones in Ireland and Puerto Rico concentrate therapeutic surface manufacturing through tax-advantaged structures that anchor European and North American supply chains.
United States
Hospital purchasing consortia and health system consolidation dominate procurement through enterprise agreements bundling surfaces and service contracts. FDA 510(k) clearance pathways under 21 CFR 880.5500 structure competitive access for alternating pressure systems. The Minneapolis-St. Paul corridor hosts concentrated medical device engineering talent developing sensor-integrated surfaces.
Germany
Structured Diagnosis-Related Group coding for pressure injury prevention creates predictable reimbursement pathways supporting premium surface uptake. EU MDR notified body relationships and technical documentation capabilities filter supplier eligibility for acute care networks. The Baden-Württemberg industrial cluster concentrates precision pneumatic component manufacturing for active therapeutic systems.
France
Critical care units in tertiary medical centers drive lateral rotation surface deployment for ventilated patient protocols. ANSM post-market surveillance requirements align with EU MDR vigilance systems for active therapeutic devices. The Lyon-Grenoble medical technology corridor anchors automated repositioning system development and clinical validation.
United Kingdom
NHS procurement frameworks standardize therapeutic surface specifications across acute and community care settings. MHRA convergence with EU MDR technical standards shapes market access timelines for imported active systems. The Cambridge-Oxford-London triangle concentrates digital health integration expertise for sensor-enabled surfaces.
Japan
Super-aging demographics and long-term care insurance expansion sustain demand for pressure injury prevention in institutional and home settings. PMDA medical device classification and QMS ministerial ordinances govern active surface market entry. The Kansai region around Osaka maintains specialized polyurethane foam processing capabilities for high-performance mattress cores.
Therapeutic Support Surface Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers, creating a bifurcated structure where integrated bed-surface portfolios anchor hospital contracts while modular specialists penetrate post-acute channels. The vendor base concentrates around three strategic archetypes: diversified medical technology conglomerates with full capital equipment portfolios, dedicated wound care and surface specialists, and regional fabricators serving price-sensitive segments. Competitive dynamics center on M&A activity consolidating distribution networks and strategic partnerships embedding sensor technology into legacy surface platforms.
Within the diversified conglomerate tier, Stryker Corporation and Hill-Rom Holdings occupy positions anchoring acute care contract negotiations through integrated bed-and-surface bundles. Arjo exemplifies the focused specialist archetype with concentrated positioning across European long-term care networks.
| Leading Market Players |
|---|
| Hill-Rom Holdings |
| Stryker Corporation |
| Invacare Corporation |
| Arjo |
| GF Health Products Inc |
| Apex Medical Corp |
| Drive DeVilbiss Healthcare |
| Joerns Healthcare |
| LINET Group SE |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up surface specialists have consolidated regional distribution networks across the United States and Germany, tightening pricing discipline through volume commitments to polyurethane foam suppliers while extracting procurement leverage from hospital purchasing consortia seeking bundled bed-and-surface contracts.
Pricing Analysis
Premium pricing for sub-48-hour lead times on MDR-certified active surfaces commands 15-25 percent spreads over standard delivery windows, while spot inventory of legacy alternating pressure systems clears at distressed levels. Three-tier pricing structure across premium sensor-integrated, standard pneumatic, and economy foam tiers tracks certification grade and EMR integration depth. Cost compression in the foam mattress tier is intensifying because petrochemical feedstock volatility erodes manufacturer margins. Post-acute channels exhibit acute price sensitivity; ICU procurement committees prioritize clinical performance metrics over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese microcontroller foundries supplying precision valve control systems for alternating pressure pumps. Manufacturing concentrates in Germany, the United States, and China, with Baden-Württemberg anchoring pneumatic component fabrication and Guangdong province housing molded foam substrate operations. Supply chains draw from viscoelastic polyurethane, medical-grade silicone bladders, and capacitive sensor arrays. Tariff exposure on Chinese electronics components threatens cost structures for US-based surface assemblers. Distribution runs through manufacturer-direct sales organizations capturing enterprise hospital contracts, with regional distributors retaining post-acute and home care access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where control over sensor-embedded firmware and EMR interoperability layers determines contract renewal rates and margin sustainability across acute care networks.
For Market Incumbents:Lock in long-term supply agreements for medical-grade polyurethane foam to hedge petrochemical volatility, while acquiring specialized sensor-software firms to defend against modular surface competitors disaggregating mattress sales from full bed systems. Threat substitution from low-cost Asian foam producers demands backward integration into foam formulation capabilities.
For New Entrants and Emerging Players:Capture the home care channel where hospital-at-home reimbursement pilots create unmet demand for portable alternating pressure overlays outside institutional procurement frameworks. The bariatric specialization segment offers the most penetrable white space, with obesity prevalence climbing across OECD markets and incumbent portfolios underweight in higher-capacity surfaces. A direct-to-patient rental model bypasses GPO contract lock-in.
For Investors and Strategic Acquirers:Distressed-cycle entries favor EU MDR-compliant mid-cap specialists in Germany and France where notified body bottlenecks have frozen pipeline velocity and compressed valuations. Long-term viability hinges on software-enabled recurring revenue streams from compliance data subscriptions rather than hardware margins alone. Watch FDA 510(k) clearance timelines for sensor-integrated surfaces as an inflection indicator for technology adoption curves.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Notified body relationships unlock German and French acute care procurement channels. |
| Sensor-EMR Integration Development | CMS Hospital-Acquired Condition reporting requirements automate quality compliance documentation. |
| Bariatric Capacity Line Extension | OECD obesity prevalence supports premium positioning for higher-weight-capacity surfaces. |
| Home Care Channel Direct Sales Buildout | Hospital-at-home pilots in the United States bypass institutional GPO contract structures. |
| Foam Substrate Backward Integration | Captive polyurethane supply hedges petrochemical feedstock cost volatility compressing margins. |
Research Methodology
Independent corroboration across hospital procurement databases, GPO contract filings, and CMS Medicare reimbursement data underwrites the qualitative findings. Primary interviews with biomedical engineers, hospital purchasing committee chairs, GPO contracts managers, and long-term care facility administrators combined with secondary validation from FDA 510(k) clearances, EU MDR notified body registrations, and ISO 10993 biocompatibility certifications. Bottom-up surface shipment estimates triangulate against top-down healthcare capital expenditure surveys.
Comparable-period anchoring to historical ICU bed installation cycles and pressure injury prevalence epidemiology structured the projection horizon. Segmentation modeling spans product technology tier, end-user care setting, sensor integration level, and regional reimbursement pathway. CAGRs derive from installed base replacement velocity analysis and penetration curve fitting for emerging lateral rotation protocols. Forecast inputs incorporate EU MDR compliance deadline impacts and polyurethane foam price elasticity assumptions.
The model holds under stable reimbursement coding and notified body capacity; deviation in MDR enforcement intensity or CMS quality metric weighting would shift replacement cycle timing. Forecasts reflect documented assumptions regarding sensor adoption curves and hospital consolidation trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Global Smart Inhaler Technology Market
Diagnostic and Therapeutic Devices
Anti Neurofilament L Antibody Market
Diagnostic and Therapeutic Devices
Global Smart Healthcare Products Market
Diagnostic and Therapeutic Devices
Venous Diseases Treatment Market
Diagnostic and Therapeutic Devices
Global Aspiration and Biopsy Needles Market
Diagnostic and Therapeutic Devices
Positive Patient Identification Market
Diagnostic and Therapeutic Devices
Leukocytapheresis Device Market
Diagnostic and Therapeutic Devices
Smart Drug Delivery Systems Market
Diagnostic and Therapeutic Devices
Global Far Infrared Therapy Device Market
Diagnostic and Therapeutic Devices
Sustained Acoustic Medicine Market
Diagnostic and Therapeutic Devices
US Cancer Contrast Media Market
Diagnostic and Therapeutic Devices
Skin Biopsy Market
Diagnostic and Therapeutic Devices
Smart Inhalers Market
Diagnostic and Therapeutic Devices
Therapeutic Apheresis Market
Diagnostic and Therapeutic Devices
Global Cold Plasma in Healthcare Market
Diagnostic and Therapeutic Devices
Cruciate Ligament Diagnosis Treatment Market