
 Global Kidney Stone Retrieval Devices Market | 2026-2036
Global Kidney Stone Retrieval Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Kidney Stone Retrieval Devices Market Foresight
The capital-intensity divergence between integrated manufacturers and component assemblers is rotating competitive advantage toward firms with captive nitinol processing and laser welding capabilities. Boston Scientific Corporation leverages in-house alloy fabrication to sustain margin structures across its basket retriever portfolio. Olympus Corporation anchors its position through endoscope-integrated retrieval systems that dominate Japanese hospital procurement. Cook Medical differentiates via specialized guidewire geometries that navigate complex renal anatomies.
Kidney stone retrieval devices encompass minimally invasive instruments designed to capture, fragment, or extract calculi from the urinary tract, typically employing nitinol baskets with radial expansion diameters of 10–25 mm, balloon dilators rated to 12–20 atmospheres, or lithotripters generating shock waves at 20–24 kV. These instruments serve the primary commercial purpose of enabling single-session stone clearance while preserving renal function. Lithotripsy devices command the largest revenue pool due to capital equipment attach rates and disposable electrode recurring revenue, while basket retrievers represent the fastest-growing segment as outpatient ureteroscopy volumes expand. Ureteral stents constitute a mature category with compressed margins, though anti-migration coatings sustain premium positioning.
The FDA's 510(k) premarket notification framework governs device clearance in the United States, while the EU Medical Device Regulation imposes strengthened clinical evidence requirements for Class IIa and IIb urological instruments. Japan's PMDA maintains distinct biological safety testing protocols that extend registration timelines for foreign manufacturers. Stakeholders must monitor reimbursement parity between inpatient and ambulatory surgical center settings, as site-of-service differentials increasingly dictate procurement volumes.
Market Dynamics
The migration of ureteroscopy procedures from inpatient settings to ambulatory surgical centers is compressing device procurement cycles and forcing manufacturers to reconfigure service models around same-day discharge protocols.
Growth Catalysts
- EU MDR Clinical Evidence Requirements:Strengthened post-market surveillance mandates for Class IIb urological instruments are accelerating portfolio rationalization among manufacturers, concentrating procurement toward suppliers with robust clinical data packages.
- Holmium Laser Lithotripsy:Fiber-optic delivery systems generating 20–24 kV shock waves are expanding single-session stone clearance rates, driving replacement demand for aging pneumatic and electrohydraulic units.
- Japanese Hospital Consolidation:Metropolitan procurement alliances in Tokyo and Osaka are standardizing on endoscope-integrated retrieval systems, creating volume commitments that favor multi-year supply contracts.
Market Restraints
- Nitinol Price Volatility:Nickel-titanium alloy feedstock concentrates among a limited supplier base in the United States and Germany, exposing device margins to raw material cost swings.
- FDA 510(k) Pathway Complexity:Evolving substantial equivalence determinations for basket retriever design modifications are extending clearance timelines and elevating regulatory compliance expenditures.
- Extracorporeal Shock Wave Lithotripsy:Non-invasive stone fragmentation for select calyceal stones retains reimbursement advantages in certain European markets, limiting invasive retrieval device penetration for sub-10 mm calculi.
Strategic Opportunities
- India Tier-2 City Expansion:Underpenetrated urology infrastructure in Pune, Jaipur, and Lucknow presents whitespace for disposable basket systems as domestic device manufacturing scales under PLI scheme incentives.
- Anti-Migration Coating Convergence:Integration of heparin-based surface treatments with biodegradable stent platforms addresses encrustation complications, opening premium positioning in stone-stent combination procedures.
- Direct-to-Hospital Digital Procurement:Cloud-based inventory management platforms are disintermediating traditional distributor networks in Australian and Canadian hospital systems, compressing working capital requirements for mid-tier manufacturers.
Industry Challenges
- Nitinol Laser Welding Expertise:Specialized microjoining capabilities for basket filament construction concentrate among a narrow technical workforce, constraining production scaling for emerging device entrants.
- Legacy EHR Integration:Retrieval device utilization tracking within hospital information systems requires customized HL7 interface development, complicating outcome data collection for value-based contracting.
- Multi-Jurisdictional Registration Synchronization:Divergent biological safety testing protocols between Japan's PMDA and Health Canada's PMRA force redundant preclinical studies, inflating go-to-market costs for novel device geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Kidney Stone Retrieval Devices Market |
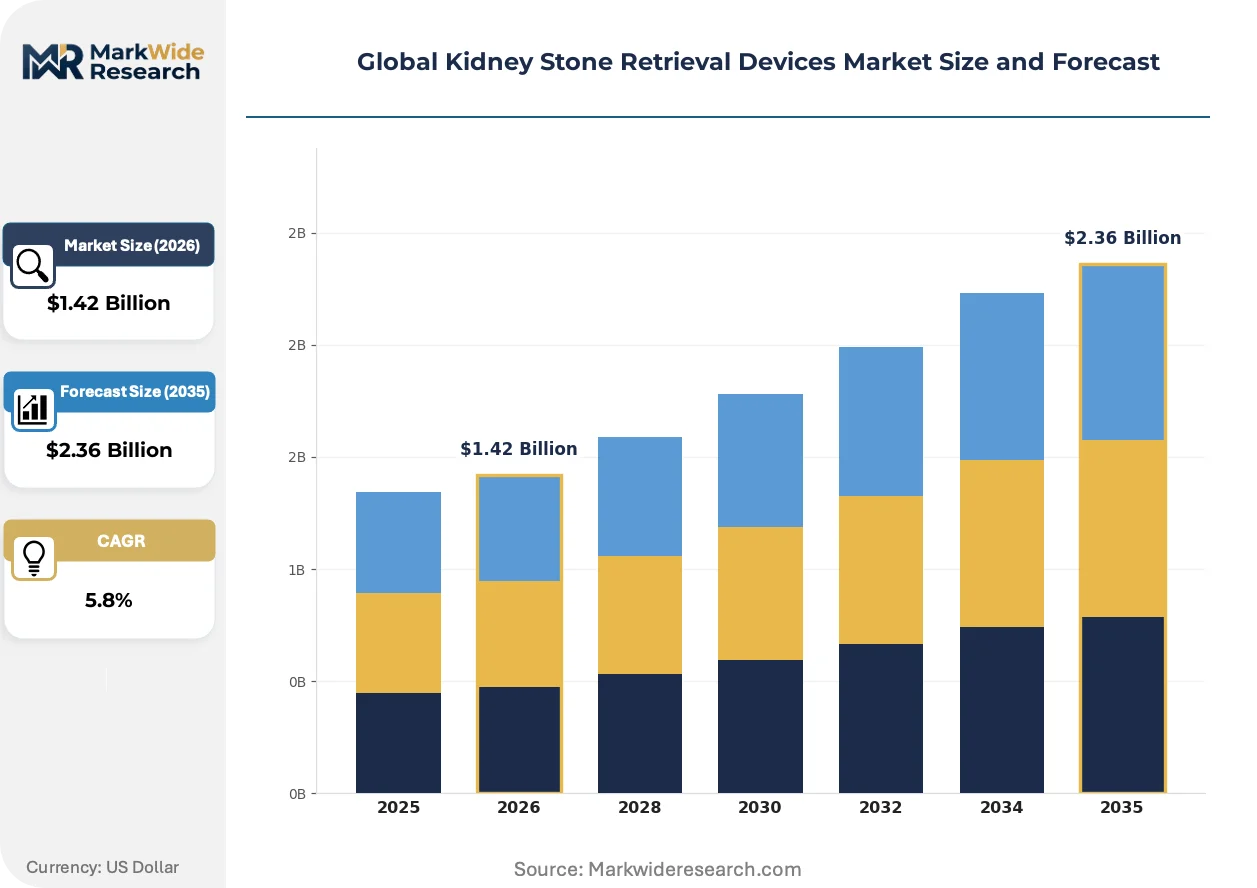
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Basket Retrievers, Balloon Catheters, Lithotripsy Devices, Guidewires, Ureteral Stents Technology: Ultrasonic, Laser, Mechanical, Electrohydraulic, Pneumatic Application: Ureteroscopy, Percutaneous Nephrolithotomy, Extracorporeal Shock Wave Lithotripsy, Retrograde Intrarenal Surgery End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Diagnostic Laboratories |
| Companies Covered | Boston Scientific Corporation, Olympus Corporation, Becton, Dickinson and Company, Cook Medical, KARL STORZ SE & Co. KG, STORZ MEDICAL AG, Dornier MedTech, Coloplast Group, Richard Wolf GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Kidney Stone Retrieval Devices Market Shifts & Advancements
Active technological substitution is reshaping competitive positioning across retrieval modalities, with regulatory frameworks and procurement behaviors accelerating the displacement of established device categories.
Single-use flexible ureteroscopes incorporating integrated irrigation channels and working ports are displacing reusable endoscope service models in high-volume stone centers. Ambulatory surgical centers in the United States and Germany are adopting these devices to eliminate reprocessing infrastructure costs and cross-contamination liability. The shift is compressing capital equipment sales cycles while expanding disposable component attach rates.
The EU Medical Device Regulation's enhanced clinical evidence requirements for Class IIa and IIb urological instruments are elevating barriers to market entry. Manufacturers must now submit post-market clinical follow-up plans and systematic literature reviews that exceed predecessor Medical Device Directive standards. Japanese and Australian regulators are referencing these MDR dossier templates, harmonizing evidentiary burdens across developed markets.
Site-of-service economics are driving hospital procurement committees to mandate device compatibility with same-day discharge protocols. Integrated retrieval systems that combine lithotripsy, irrigation, and basket extraction in single-platform configurations are displacing modular device purchases in United States health systems. This preference concentrates purchasing authority within value analysis committees rather than individual urologist preference cards.
Global Kidney Stone Retrieval Devices Market Segmentation
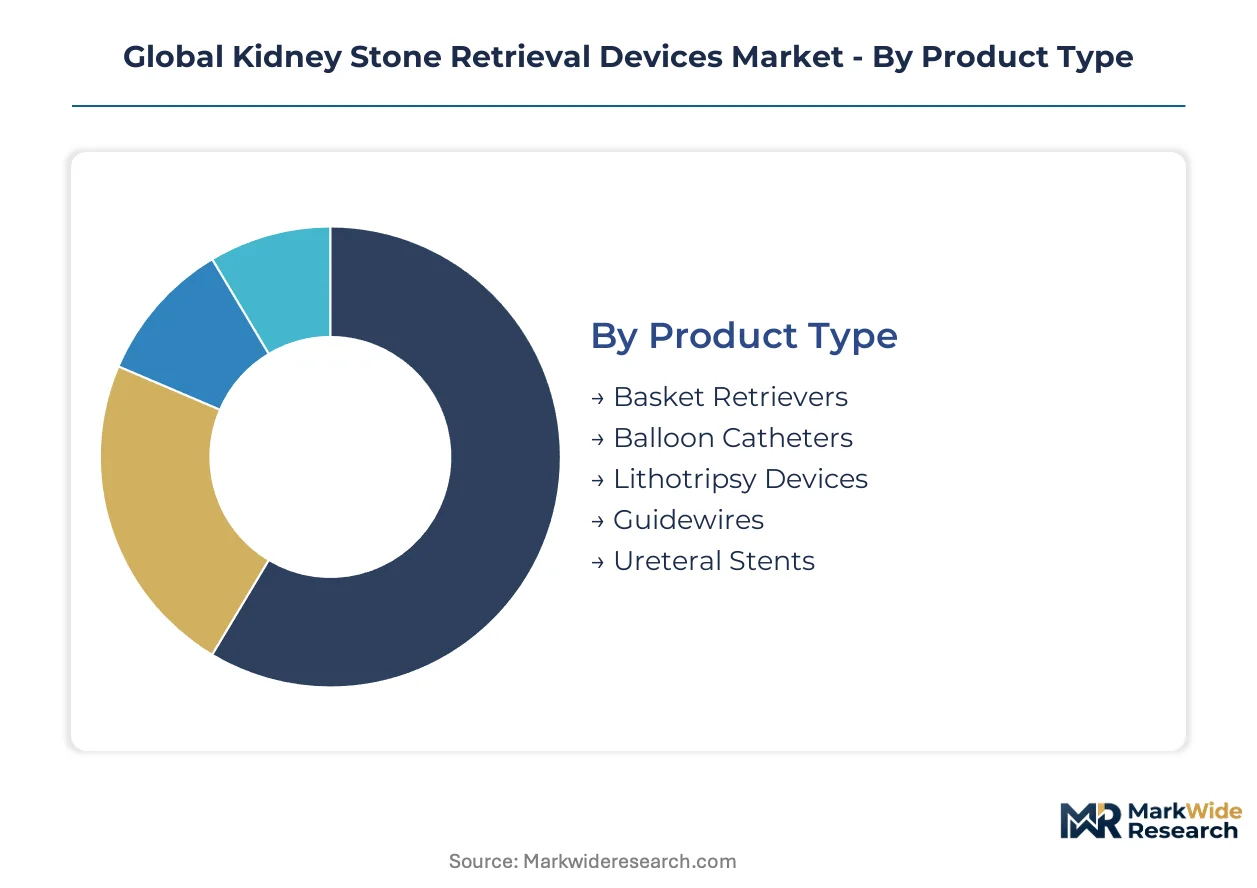
Segmentation in kidney stone retrieval devices reveals how procurement authority, reimbursement structures, and clinical workflows reshape competitive boundaries across product categories. Manufacturers configure portfolios around specific intervention settings rather than pursuing horizontal coverage.
Product Type:
Basket retrievers and lithotripsy devices anchor domestic demand in the United States and Germany, while balloon catheters and guidewires see heavier export orientation toward Asia-Pacific markets.
- Lithotripsy Devices:Capital equipment systems generating shock waves at 20–24 kV command the largest revenue pool through disposable electrode recurring attach rates. United States hospital systems concentrate procurement around integrated platforms that combine fragmentation with irrigation capabilities.
- Basket Retrievers:Nitinol instruments with radial expansion diameters of 10–25 mm are expanding most quickly as outpatient ureteroscopy volumes rise in ambulatory surgical centers. Same-day discharge protocols favor single-use configurations over reusable alternatives.
- Balloon Catheters:Dilators rated to 12–20 atmospheres serve percutaneous tract establishment in nephrolithotomy procedures.
- Guidewires:Specialized geometries navigate complex renal anatomies during multi-stage interventions.
- Ureteral Stents:Anti-migration coatings sustain premium positioning despite mature category margins.
Lithotripsy devices hold the largest share; momentum sits with basket retrievers.
Technology:
Cost tier stratification separates premium laser systems from standard mechanical and pneumatic alternatives, with electrohydraulic units occupying a contracting mid-market position.
- Laser:Holmium fiber-optic delivery systems achieving single-session stone clearance command premium pricing in United States academic medical centers. Fiber degradation rates drive recurring revenue streams that exceed capital equipment depreciation cycles.
- Ultrasonic:Probe-based fragmentation integrates with suction evacuation in percutaneous procedures, concentrating demand in German and Japanese hospital systems with established nephrolithotomy volumes.
- Mechanical:Direct-capture basket systems serve cost-constrained settings without capital equipment requirements.
- Pneumatic:Ballistic lithotripters retain penetration in price-sensitive emerging markets despite clearance rate limitations.
- Electrohydraulic:Spark-gap systems face displacement as laser fiber costs decline and durability improves.
Laser technology captures the premium tier; ultrasonic applications gain share in integrated surgical platforms.
Application:
Volume concentration in ureteroscopy reflects the procedure's migration toward ambulatory settings, while percutaneous approaches remain hospital-anchored due to anesthesia and monitoring requirements.
- Ureteroscopy:Flexible endoscope-based retrieval dominates United States procedural volumes with same-day discharge protocols compressing device procurement cycles. Disposable scope adoption eliminates reprocessing infrastructure costs.
- Percutaneous Nephrolithotomy:Tract dilation and large-fragment extraction sustain demand for balloon dilators and mechanical lithotripters in hospital-based settings across Germany and Japan.
- Extracorporeal Shock Wave Lithotripsy:Non-invasive fragmentation for sub-10 mm calyceal stones retains reimbursement advantages in select European markets.
- Retrograde Intrarenal Surgery:Upper tract access techniques expand flexible ureteroscope utilization for renal pelvis calculi.
Ureteroscopy commands procedural volume leadership; retrograde intrarenal surgery shows steepest expansion trajectory among minimally invasive alternatives.
End User:
Customer type determines pricing tolerance and service model requirements, with ambulatory surgical centers forcing working capital compression through just-inventory protocols.
- Hospitals:Integrated delivery networks in the United States consolidate procurement authority within value analysis committees rather than individual urologist preference cards. Multi-year supply contracts favor vendors with comprehensive portfolio coverage.
- Ambulatory Surgical Centers:Same-day discharge mandates drive adoption of single-use devices and disposable endoscopes to eliminate cross-contamination liability and reprocessing labor costs.
- Specialty Clinics:Focused urology practices in urban clusters concentrate lithotripsy device utilization for select patient populations.
- Diagnostic Laboratories:Stone composition analysis services support treatment planning but represent minimal direct device demand.
Hospitals retain the largest procurement volume; ambulatory surgical centers are gaining share fastest through site-of-service migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. United States hospital systems absorb premium pricing for integrated lithotripsy platforms, while Indian and Brazilian procurement remains acutely sensitive to disposable basket unit costs.
United States
Ambulatory surgical center expansion and aging demographics sustain procedural volumes. FDA 510(k) clearance pathways for basket retriever modifications continue evolving, extending regulatory timelines. Boston Scientific Corporation anchors manufacturing in Massachusetts, leveraging in-house nitinol processing for margin control.
Germany
Established nephrolithotomy volumes and ultrasonic lithotripsy adoption concentrate hospital procurement. EU MDR clinical evidence requirements for Class IIb urological instruments mandate strengthened post-market surveillance. Richard Wolf GmbH maintains headquarters in Knittlingen, anchoring Baden-Württemberg's urology device cluster.
Japan
Metropolitan hospital consolidation in Tokyo and Osaka standardizes endoscope-integrated retrieval systems. PMDA biological safety testing protocols extend registration timelines for foreign manufacturers. Olympus Corporation dominates domestic procurement through multi-year supply contracts with procurement alliances.
India
Tier-2 city urology infrastructure expansion in Pune, Jaipur, and Lucknow presents whitespace for disposable systems. PLI scheme incentives accelerate domestic device manufacturing scale. CDSCO regulatory harmonization efforts streamline import substitution for nitinol basket assemblies.
Australia
Cloud-based inventory management platforms disintermediate traditional distributor networks in hospital systems. TGA referencing of EU MDR dossier templates harmonizes evidentiary burdens. Direct-to-hospital digital procurement compresses working capital requirements for mid-tier manufacturers serving Sydney and Melbourne clusters.
Global Kidney Stone Retrieval Devices Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the retrieval device spectrum. The vendor base concentrates among integrated manufacturers with captive alloy processing and specialized component assemblers dependent on external nitinol feedstock. Three archetypes dominate: diversified medtech conglomerates with endoscope integration capabilities, mid-cap specialists with laser welding expertise, and emerging domestic manufacturers in Asia leveraging PLI incentives. Competitive moves center on backward integration into nitinol supply and strategic partnerships for EHR outcome tracking.
Among diversified medtech conglomerates, Boston Scientific Corporation and Olympus Corporation exemplify contrasting geographic anchoring strategies, with the former representing North American integrated manufacturing and the latter Japanese endoscope-integrated system dominance. Cook Medical occupies a position within the mid-cap specialist tier, while KARL STORZ SE & Co. KG and Richard Wolf GmbH anchor German precision engineering archetypes. Coloplast Group represents the diversified healthcare conglomerate model with urology division integration.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Olympus Corporation |
| Becton, Dickinson and Company |
| Cook Medical |
| KARL STORZ SE & Co. KG |
| STORZ MEDICAL AG |
| Dornier MedTech |
| Coloplast Group |
| Richard Wolf GmbH |
| Others |
Supply & Pricing Matrix
Multi-year supply contracts with procurement alliances in Tokyo and Osaka lock in nitinol basket volumes while capping annual price escalations at raw material index rates. These arrangements give Japanese hospital systems visibility into device costs across three-year procurement cycles while securing manufacturers against nickel-titanium alloy feedstock volatility.
Pricing Analysis
After-sales revenue from disposable holmium laser fibers and single-use ureteroscope components drives lifetime customer value beyond capital equipment margins. Three-tier pricing structure across premium laser-integrated platforms, standard pneumatic systems, and economy mechanical baskets separates academic medical centers from ambulatory surgical centers and cost-constrained emerging markets. Pricing pressure stems from ambulatory surgical center migration forcing same-day discharge protocols that compress device reimbursement. Ambulatory surgical centers exhibit highest price sensitivity due to working capital constraints, while United States academic medical centers absorb premium positioning for integrated lithotripsy platforms.
Supply Chain Analysis
Inbound logistics costs from German nitinol feedstock suppliers through Rotterdam port congestion have elevated landed costs for basket filament assemblies. Manufacturing concentrates in United States, Germany, and Japan for precision laser welding of nitinol constructs, while India scales domestic assembly under PLI scheme incentives. Raw material dependencies center on nickel-titanium alloy feedstock, holmium laser fiber bundles, and specialized balloon elastomers. Single-source vulnerability concentrates in United States and German nitinol suppliers, exposing margins to commodity price swings. Distribution runs through regional distributor networks in developed markets and direct-to-hospital digital platforms in Australian and Canadian systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Kidney Stone Retrieval Devices Market sits at a technology-substitution inflection as single-use flexible ureteroscopes displace reusable endoscope service models and EU MDR clinical evidence requirements reshape competitive barriers.
For Market Incumbents: Shield market position through backward integration into captive nitinol processing capabilities that insulate margins from raw material volatility, and accelerate FDA 510(k) clearance pathway investments to defend against emerging entrants facing extended regulatory timelines. The threat of single-use disposable scope adoption by ambulatory surgical centers demands service model reconfiguration around just-inventory protocols. For New Entrants and Emerging Players: Differentiate on specialized guidewire geometries for complex renal anatomies that navigate procurement committee standardization in Japanese hospital systems, and target India's tier-2 city whitespace in Pune and Jaipur where domestic PLI manufacturing scales create cost advantages. The most penetrable segment lies in disposable basket systems for outpatient ureteroscopy volumes. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-cap specialists with laser welding expertise and robust clinical data packages. Long-term viability over the next decade hinges on regulatory dossier depth rather than manufacturing scale alone. The signal to watch is EU MDR portfolio rationalization announcements indicating which suppliers possess sustainable post-market surveillance infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements for Class IIb urological instruments mandate strengthened post-market surveillance dossiers exceeding prior directive standards. |
| Hospital System Partnership | Multi-year supply contracts with Tokyo-Osaka procurement alliances standardize endoscope-integrated retrieval system volumes. |
| Backward Integration | In-house nitinol alloy fabrication insulates Boston Scientific's margin structures from nickel-titanium feedstock price volatility. |
| Software Companion Development | HL7 interface integration for retrieval device utilization tracking enables outcome data collection for value-based hospital contracting. |
| Reimbursement Strategy | Site-of-service parity between inpatient and ambulatory surgical center settings dictates procurement volume allocation across United States health systems. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with urologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers across United States, German, and Japanese health systems; and secondary validation through FDA 510(k) clearance databases, EU MDR notified body submissions, hospital procurement contract filings, and CMS Medicare reimbursement schedules. Bottom-up triangulation across device shipment data and top-down validation against lithotripsy procedure volumes anchored market sizing.
Across the analysis window, the forecasting framework modeled volume and value trajectories through segmentation by product type, technology tier, application setting, and end-user archetype. CAGRs derived from procedure volume elasticity coefficients, device replacement cycles, and reimbursement parity assumptions between inpatient and ambulatory settings. Industry-specific inputs incorporated holmium laser fiber degradation rates and single-use ureteroscope adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained EU MDR compliance investment, nitinol price stability, or ambulatory surgical center reimbursement parity would require recalibration. Forecasts reflect documented assumptions regarding procedural migration patterns and regulatory timeline evolution. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Veterinary Glucometers Market
Medical Devices
Airway Management Tubes Market
Medical Devices
US Intrauterine Devices Market
Medical Devices
Indian Laparoscopy Devices Market
Medical Devices
Contrast Injection Lines Market
Medical Devices
Electroencephalography (EEG) Amplifier System Market
Medical Devices
Anterior Cervical Fixation Devices Market
Medical Devices
Cardiac Poc Testing Devices Market
Medical Devices
Nonvascular Interventional Radiology Devices Market
Medical Devices
Asthma Device Market
Medical Devices
Australia General Surgical Devices Market
Medical Devices
Global Medical Device Contract Manufacturing Market
Medical Devices
Breast Prosthesis Market
Medical Devices
Extremity Reconstruction Market
Medical Devices
Brazil Clear Aligners Market
Medical Devices
Mucus Clearance Devices Market