
 Global Medical Cannula Market | 2026-2036
Global Medical Cannula Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Cannula Market Foresight
Single-source reliance on Chinese polymer feedstock is rebalancing toward multi-source procurement across Southeast Asian and European resin suppliers. B. Braun SE anchors its cannula portfolio through backward integration into precision extrusion, while Medtronic competes via technology leadership in arterial cannula design for cardiopulmonary bypass. Terumo Corporation specializes in thin-wall polyurethane catheter systems that sustain premium positioning in Japanese and North American hospital networks.
A medical cannula is a hollow tube inserted into body cavities, ducts, or vessels to drain fluids, administer treatments, or deliver gases, typically manufactured through extrusion or injection molding with tip-grinding tolerances below 0.05 millimeters. Nasal cannula demand leads in volume due to chronic obstructive pulmonary disease and home oxygen therapy expansion, while arterial cannula commands higher margins tied to cardiac surgical complexity. Material selection increasingly favors silicone and latex-free formulations as regulatory scrutiny intensifies on patient allergen exposure.
FDA 510(k) clearance pathways and EU MDR Class IIa certification requirements shape product development timelines and sterilization validation burdens for manufacturers seeking market access. The EPA regulates ethylene oxide sterilization emissions, pressuring facilities toward alternative terminal sterilization methods. Stakeholders must monitor evolving biocompatibility testing standards and supply chain qualification protocols to preserve commercial positioning across regulated jurisdictions.
Market Dynamics
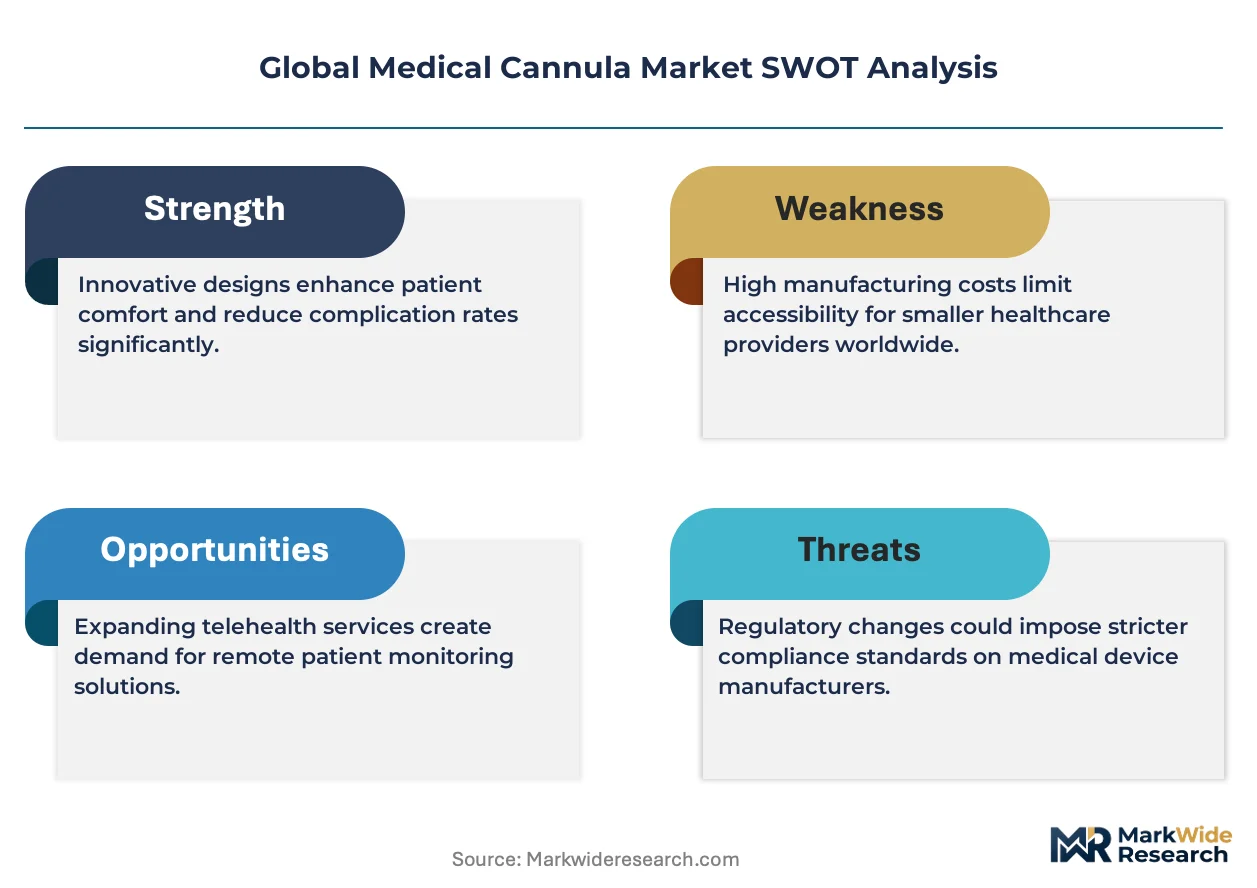
EU MDR sterilization mandates and EPA ethylene oxide emission limits are forcing material transitions toward silicone and polyurethane variants while compressing supplier qualification timelines for manufacturers serving cardiac surgery and home oxygen therapy segments.
Growth Catalysts
- Japan's aging demographic:Chronic obstructive pulmonary disease prevalence sustains nasal cannula utilization across hospital and homecare settings, with METI reimbursement policies supporting oxygen therapy device procurement.
- EU MDR Class IIa certification:Upgraded biocompatibility testing requirements accelerate latex-free formulation adoption, creating replacement cycles across European hospital networks.
- Thin-wall polyurethane extrusion:Precision manufacturing advances enable reduced-profile arterial cannula designs that minimize vessel trauma during cardiopulmonary bypass procedures.
Market Restraints
- Polymer feedstock concentration:Historical reliance on Chinese resin suppliers creates vulnerability to export licensing volatility and freight cost spikes.
- Sterilization infrastructure limits:EPA ethylene oxide emission caps constrain terminal sterilization capacity, forcing facilities toward gamma irradiation with higher capital requirements.
- Biocompatibility testing burdens:ISO 10993 cytotoxicity and sensitization protocols extend validation timelines for new material introductions.
Strategic Opportunities
- Southeast Asian resin diversification:Thailand and Vietnam polymer producers offer alternative feedstock sourcing as manufacturers rebalance supply chains away from single-origin dependence.
- Home oxygen therapy expansion:Ambulatory care settings in Germany and the United States present underpenetrated demand for lightweight nasal cannula with extended wear comfort.
- Digital health integration:Sensor-embedded cannula designs that interface with remote patient monitoring platforms create premium positioning in accountable care organizations.
Industry Challenges
- Precision extrusion talent scarcity:Tip-grinding tolerances below 0.05 millimeters require specialized machining expertise that outpaces vocational training pipeline output.
- Legacy sterilization asset stranding:Ethylene oxide facility conversions demand capital deployment while revenue continuity depends on maintaining dual-method certification during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Cannula Market |
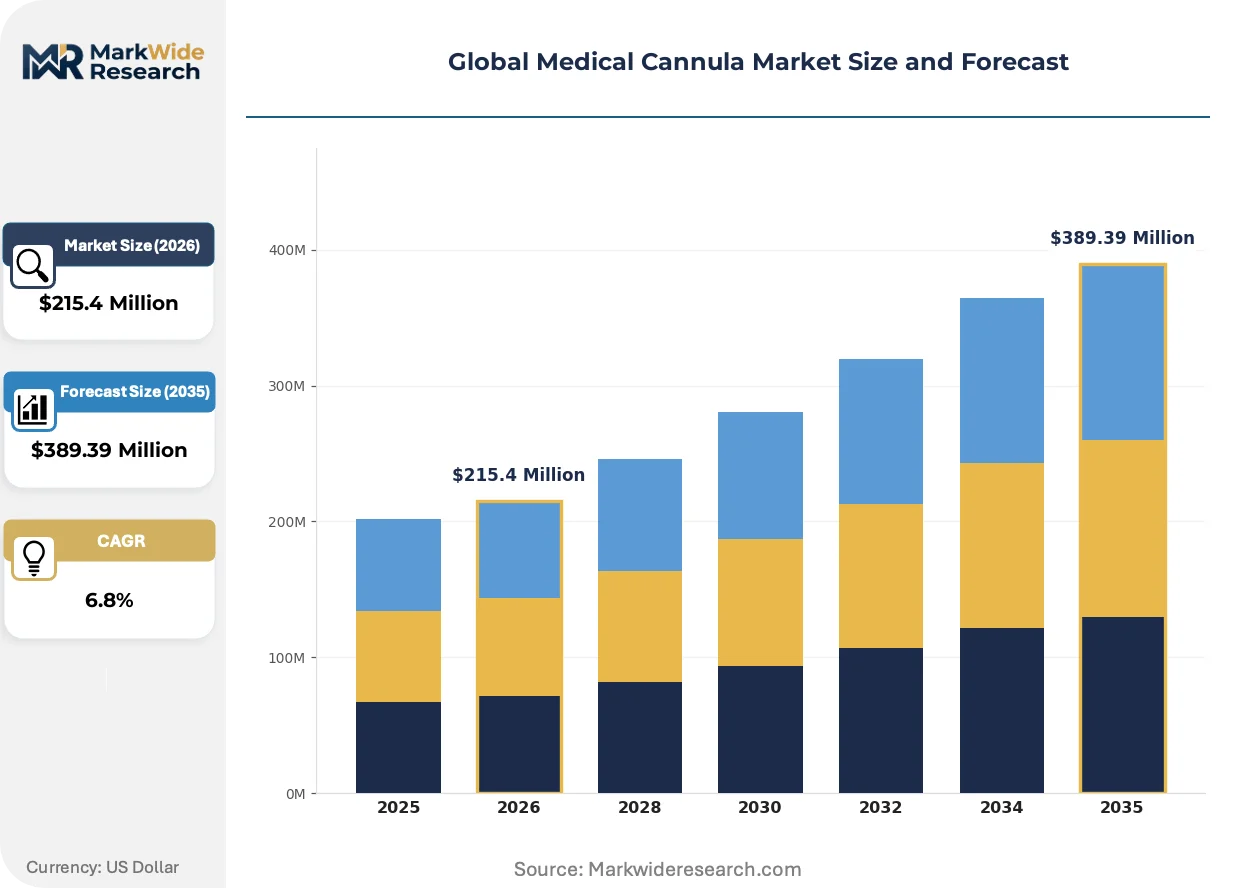
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $389.39 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intravenous Cannula, Arterial Cannula, Suprapubic Cannula, Nasal Cannula, Epidural Cannula Application: Intravenous Therapy, Blood Sampling, Regional Anesthesia, Oxygen Therapy, Fluid Removal End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Home Healthcare Providers, Specialty Clinics Material: Polyvinyl Chloride, Polyurethane, Silicone, Teflon, Latex-Free |
| Companies Covered | Boston Scientific Corporation, B. Braun SE, LivaNova PLC, Teleflex Incorporated, Conmed Corporation, Medtronic, Terumo Corporation, BD, Edwards Lifesciences Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Cannula Market Shifts & Advancements
Material science advances and sterilization method transitions are compressing product development cycles while regulatory harmonization efforts across FDA and EU MDR frameworks reshape competitive qualification barriers.
Antimicrobial surface coatings integrated during polyurethane extrusion are electrifying infection prevention protocols in cardiac surgery suites. Hospital procurement committees in the United States and Japan are prioritizing coated arterial cannula despite 15-20% price premiums. This technology is electrifying supplier differentiation strategies as uncoated commoditized products face margin compression.
EU MDR Annex I general safety and performance requirements now mandate enhanced clinical evidence for Class IIa devices including cannula systems. Manufacturers must submit post-market surveillance data that extends technical documentation burdens. German notified bodies are experiencing backlog delays that stretch certification timelines for thin-wall catheter innovations.
Consolidated buying by United States hospital networks is displacing fragmented distributor relationships with direct manufacturer contracts tied to volume commitments. Group purchasing organizations are unbundling after-sales service from device pricing, forcing suppliers to articulate standalone service value. This concentration is most visible in cardiac surgery centers across Texas and Florida where multi-hospital systems negotiate enterprise-wide arterial cannula supply agreements.
Global Medical Cannula Market Segmentation
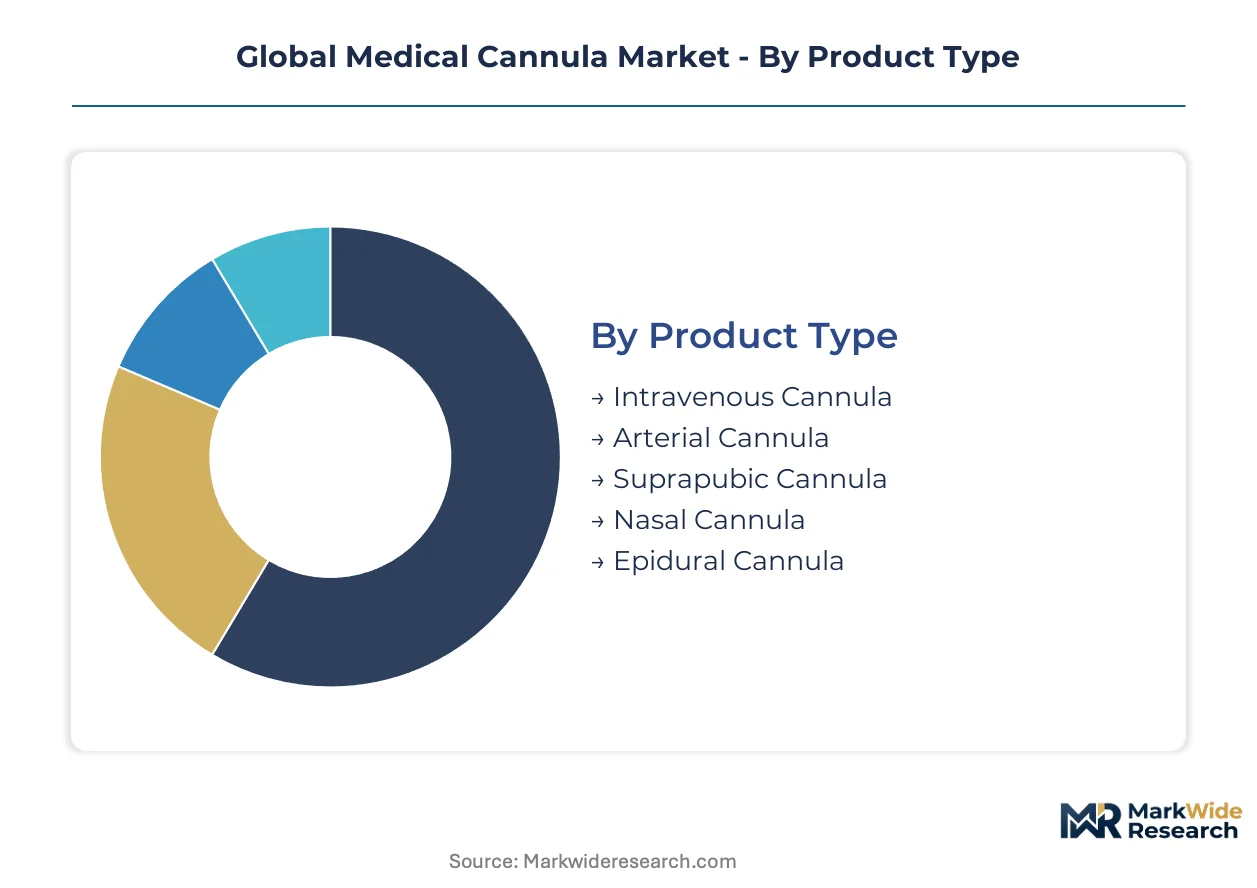
Medical cannula segmentation reveals divergent capital requirements across product architectures. Material selection and sterilization compliance create tiered investment thresholds that reshape competitive entry barriers.
Product Type:
Capital intensity peaks in arterial cannula manufacturing due to precision extrusion tolerances below 0.05 millimeters and biocompatibility validation burdens.
- Arterial Cannula:Multi-lumen polyurethane construction demands specialized tip-grinding equipment and ISO 10993 cytotoxicity testing. Cardiac surgery centers in Germany and the United States source these for cardiopulmonary bypass, with FDA 510(k) clearance timelines extending development cycles.
- Nasal Cannula:High-volume extrusion of polyvinyl chloride and silicone variants serves chronic obstructive pulmonary disease management. Japan's aging population and METI reimbursement policies sustain hospital and homecare procurement.
- Intravenous Cannula:Standard-gauge peripheral access devices dominate procedural volume across emergency departments.
- Suprapubic Cannula:Specialized drainage applications require antimicrobial coatings for urological interventions.
- Epidural Cannula:Flexible catheter designs target regional anesthesia protocols in obstetric and surgical settings.
Most installed capacity flows through nasal cannula. Expansion is steepest in arterial cannula.
Application:
Revenue concentration varies by clinical setting reimbursement intensity and procedure complexity.
- Oxygen Therapy:Nasal cannula deployment for chronic respiratory disease spans acute hospitals and ambulatory settings. Germany's home healthcare expansion and United States Medicare durable medical equipment coverage sustain demand.
- Regional Anesthesia:Epidural and nerve block catheter systems command premium pricing tied to surgical outcome metrics. Japanese hospital networks prioritize thin-wall polyurethane designs for reduced trauma.
- Intravenous Therapy:Peripheral and central venous access represents the highest procedural frequency across emergency medicine.
- Blood Sampling:Arterial and venous puncture applications require heparin-coated variants for coagulation management.
- Fluid Removal:Thoracentesis and paracentesis cannula serve interventional radiology and nephrology departments.
Procedure volume concentrates in intravenous therapy. Value capture is expanding most quickly in regional anesthesia.
End User:
Procurement scale and sterilization infrastructure requirements segment the customer base.
- Hospitals:Integrated delivery networks negotiate enterprise-wide contracts for cardiac surgery and intensive care units. Texas and Florida multi-hospital systems displace distributor relationships with direct manufacturer agreements.
- Home Healthcare Providers:Lightweight nasal cannula for chronic oxygen therapy bypasses institutional sterilization requirements. United States durable medical equipment suppliers and German homecare networks drive procurement.
- Ambulatory Surgical Centers:Same-day procedure volumes favor single-use disposable economics.
- Diagnostic Laboratories:Blood collection cannula serve high-throughput phlebotomy operations.
- Specialty Clinics:Pain management and wound care centers source specialized catheter configurations.
Purchasing volume aggregates in hospitals. Customer base diversification is accelerating fastest in home healthcare.
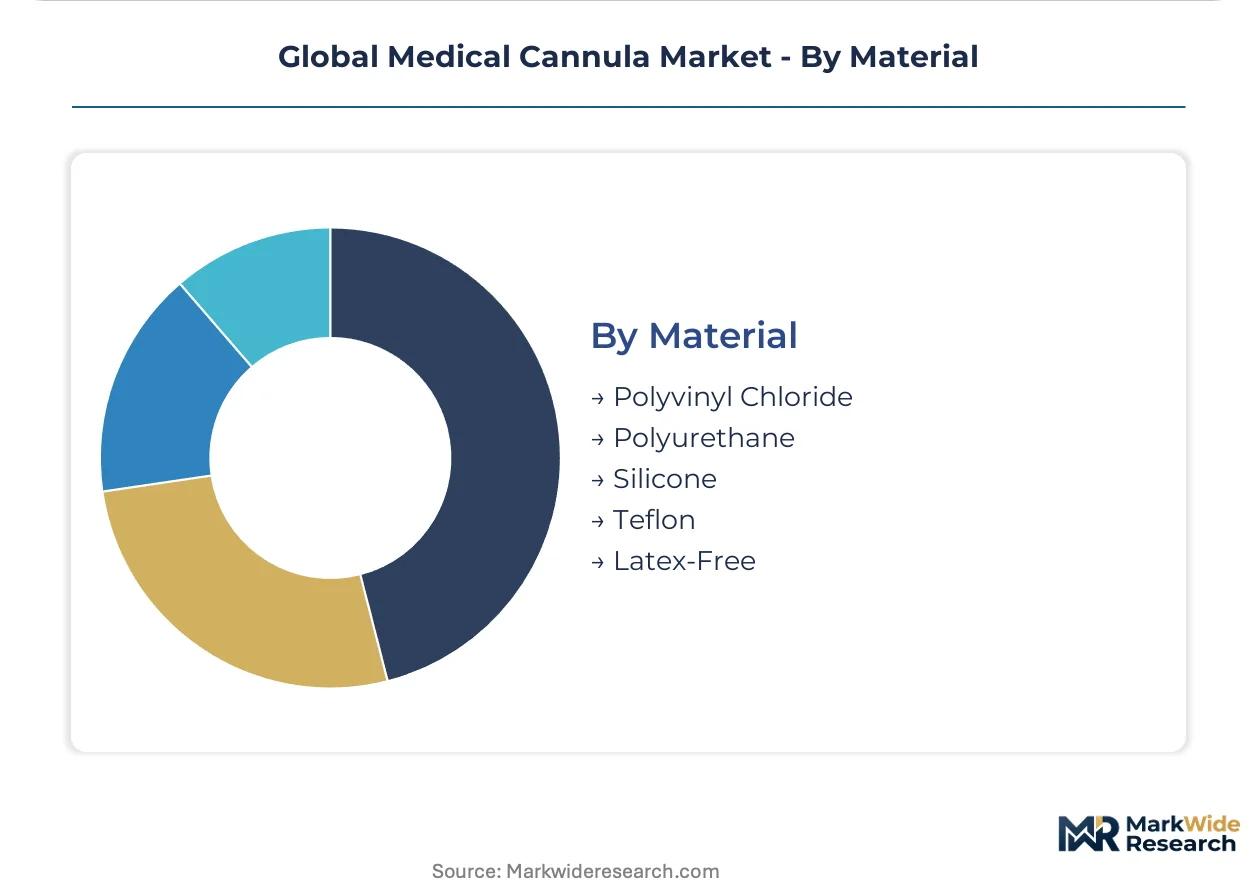
Material:
Regulatory migration toward latex-free and silicone formulations rebalances supplier qualification timelines.
- Silicone:Platinum-cured extrusion for arterial and epidural applications meets EU MDR biocompatibility mandates. German notified bodies enforce Annex I general safety requirements that extend technical documentation.
- Polyurethane:Thin-wall catheter systems enable reduced-profile designs for minimally invasive procedures. Terumo Corporation's precision extrusion capabilities anchor supply to Japanese and North American networks.
- Polyvinyl Chloride:Cost-optimized formulations dominate high-volume nasal and intravenous cannula production.
- Teflon:Low-friction coatings reduce vessel trauma in arterial access applications.
- Latex-Free:Formulation shifts respond to FDA and EU MDR allergen exposure scrutiny.
Production throughput runs heaviest through polyvinyl chloride. Reformulation investment is climbing the fastest in silicone.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision extrusion clusters anchor arterial cannula supply chains serving cardiac surgery centers across Western Europe and North America. FDA 510(k) clearance pathways and EU MDR Class IIa certification requirements create divergent qualification timelines that reshape procurement geography.
United States
Texas and Florida multi-hospital systems drive consolidated procurement for cardiopulmonary bypass procedures. FDA sterilization validation requirements and EPA ethylene oxide emission caps pressure manufacturers toward gamma irradiation alternatives. Minneapolis and Boston medical device corridors concentrate arterial cannula design expertise.
Germany
Chronic obstructive pulmonary disease prevalence and home oxygen therapy expansion sustain nasal cannula demand across hospital and ambulatory networks. EU MDR Annex I biocompatibility mandates accelerate latex-free formulation transitions. Baden-Württemberg precision polymer clusters supply thin-wall catheter systems to European notified bodies.
Japan
METI reimbursement policies support oxygen therapy device procurement for aging demographics. PMDA quality management system inspections enforce post-market surveillance for Class IIa devices. Tokyo-Osaka medical device corridors specialize in polyurethane extrusion for reduced-profile arterial designs.
China
NMPA medical device registration reforms streamline market access for imported cannula systems. Ningbo and Suzhou polymer processing hubs serve domestic hospital procurement while export licensing volatility constrains feedstock reliability. Domestic manufacturers advance silicone formulation capabilities for regional anesthesia applications.
India
CDSCO medical device rules implementation creates compliance thresholds for imported arterial and intravenous cannula. Maharashtra and Gujarat pharmaceutical manufacturing corridors diversify into disposable catheter production. Price-sensitive hospital procurement favors polyvinyl chloride formulations for high-volume peripheral access.
Global Medical Cannula Market Competitive Landscape
Global majors compete with regional champions across sterilization certification and precision extrusion capabilities. The vendor base stratifies into three tiers: integrated multinationals with captive polymer supply, specialized catheter manufacturers with notified body relationships, and regional distributors with hospital network contracts. Dominant competitive moves include backward integration into resin compounding and strategic partnerships with gamma irradiation facilities.
Among Germany-based integrated manufacturers, B. Braun SE exemplifies the backward-integrated archetype through precision extrusion capabilities. Medtronic occupies a position representing technology leadership in arterial cannula design for cardiac surgical applications. Terumo Corporation anchors the thin-wall polyurethane specialist tier serving Japanese and North American hospital networks.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| B. Braun SE |
| LivaNova PLC |
| Teleflex Incorporated |
| Conmed Corporation |
| Medtronic |
| Terumo Corporation |
| BD |
| Edwards Lifesciences Corporation |
| Others |
Supply & Pricing Matrix
Backward integration into precision extrusion anchors both supply security and pricing power for arterial cannula manufacturers serving cardiac surgery centers in Germany and the United States. B. Braun SE's captive polymer compounding capabilities insulate margin structures from Chinese resin export licensing volatility while supporting premium positioning for multi-lumen designs.
Pricing Analysis
Polymer feedstock cost pass-through runs through contract structures with quarterly adjustment clauses tied to Southeast Asian resin indices. Three-tier pricing structure across premium, standard, and economy levels separates antimicrobial-coated arterial systems from uncoated commodity variants and high-volume PVC nasal lines. Price differentiation hinges on ISO 10993 certification tier and after-sales technical support bundling. Cost compression in standard-grade intravenous cannula intensifies as Indian manufacturers expand polyvinyl chloride extrusion capacity. Home healthcare providers exhibit highest price sensitivity, while German hospital networks prioritize biocompatibility compliance over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore orchestrate hub-and-spoke patterns for just-in-time delivery to European and Asia-Pacific hospital networks. Manufacturing concentrates in Germany, Japan, and China, with Baden-Württemberg precision clusters supplying thin-wall catheter systems and Ningbo polymer processors serving high-volume disposable demand. Raw material dependencies rest on Thai and Vietnamese polyurethane resin, platinum-cured silicone from Japanese suppliers, and medical-grade PVC from domestic Chinese compounding. Single-source vulnerability in gamma irradiation capacity creates bottleneck risk as EPA ethylene oxide emission caps force sterilization method transitions. Distribution runs through direct manufacturer contracts with United States group purchasing organizations and specialized European medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medical cannula market reads as a late-cycle quality story where antimicrobial surface coatings and thin-wall polyurethane extrusion command persistent premiums amid chronic respiratory disease prevalence and cardiac surgical complexity.
For Market Incumbents: Extend sterilization certification breadth to capture gamma irradiation capacity before competitor lock-in, while deepening backward integration into Southeast Asian resin sourcing to hedge Chinese export licensing exposure. Defensive positioning requires maintaining dual-method sterilization qualifications during ethylene oxide facility transitions to preserve revenue continuity with Texas and Florida multi-hospital systems. For New Entrants and Emerging Players: Ambulatory surgical centers in Germany's home oxygen therapy expansion represent an underserved buyer archetype with lower regulatory barriers than hospital procurement committees. White-space capture targets lightweight nasal cannula with extended-wear comfort specifications for United States durable medical equipment suppliers, leveraging direct-to-patient digital health integration as the primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for specialized catheter manufacturers with notified body relationships because EU MDR Class IIa certification backlogs create scarcity value for technical documentation capabilities. The five-to-ten year viability window favors acquisition of thin-wall polyurethane extrusion specialists serving Japanese PMDA quality management requirements. Watch German notified body processing timelines as the inflection indicator for certification bottleneck resolution.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class IIa Certification Investment | Accelerates latex-free formulation adoption across German hospital networks facing Annex I safety mandates. |
| Gamma Irradiation Facility Partnership | Secures terminal sterilization capacity as EPA ethylene oxide emission caps constrain legacy infrastructure. |
| Hospital System Direct Contracting | Displaces fragmented distributor relationships with volume-commitment agreements in Texas cardiac surgery centers. |
| Antimicrobial Coating Integration | Commands 15-20% price premiums in United States and Japan cardiac surgery procurement committees. |
| Southeast Asian Resin Diversification | Rebalances feedstock sourcing toward Thai and Vietnamese suppliers to reduce Chinese licensing exposure. |
Research Methodology
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region's hospital procurement landscape. The analysis combines interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and precision extrusion specialists with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare durable medical equipment data, and Japanese METI reimbursement policy records. Bottom-up demand modeling triangulates against top-down market sizing across product architectures.
Granularity-level framing models arterial, nasal, intravenous, and epidural cannula at the SKU level with material-grade disaggregation for silicone, polyurethane, and polyvinyl chloride variants. Application segmentation distinguishes oxygen therapy, regional anesthesia, intravenous therapy, blood sampling, and fluid removal with end-user splits across hospitals, home healthcare providers, ambulatory surgical centers, diagnostic laboratories, and specialty clinics. CAGRs derive from procedure volume elasticity to chronic disease prevalence, reimbursement policy shifts, and sterilization infrastructure capacity constraints. Forecast inputs incorporate PMDA quality management inspection timelines and German notified body backlog projections.
Underlying measurement precision varies by segment; arterial cannula with precision extrusion tolerances below 0.05 millimeters carry tighter precision than high-volume nasal lines where commoditization compresses data granularity. Forecasts reflect assumptions about regulatory harmonization progress, polymer feedstock trade flow stability, and sterilization method transition pace. Stakeholders should weight assumptions against their own operating context across certification timelines and supply chain qualification protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Intraoral Scanners Market
Medical Devices
Middle East and Africa Non-Surgical Procedures Market
Medical Devices
Peritoneal Catheter Systems Market
Medical Devices
Brazil Contraceptive Devices Market
Medical Devices
Neurovascular Stent Market
Medical Devices
Image-Based Cytometer Market
Medical Devices
Germany Ultrasound Devices Market
Medical Devices
Europe Intraocular Lens Market
Medical Devices
Antibiotic-Loaded Bone Cement Market
Medical Devices
Intracranial Pressure (ICP) Monitoring Devices Market
Medical Devices
Hormonal Implants Market
Medical Devices
Skin Revitalizing Handheld Devices Market
Medical Devices
Medical Laser Cutting Device Market
Medical Devices
Connected Drug Delivery Devices Market
Medical Devices
North America Portable Medical and Healthcare Devices Market
Medical Devices
Transcatheter Pacing System Market