
 Digital Intraoral Sensors and Consumables Market | 2026-2036
Digital Intraoral Sensors and Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Intraoral Sensors and Consumables Market Analysis
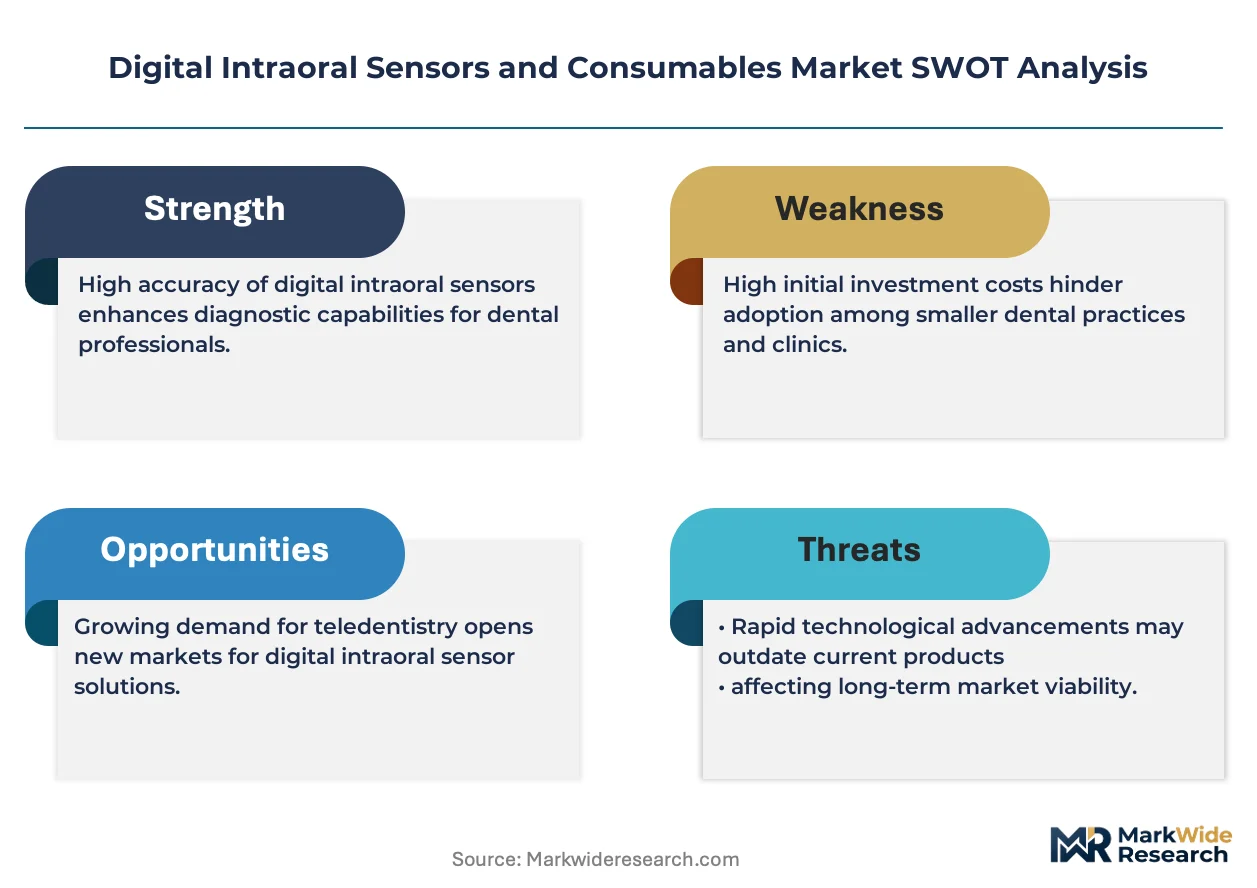
CE marking under the EU Medical Device Regulation is recalibrating compliance costs for sensor manufacturers seeking European market access. Dentsply Sirona leverages its integrated imaging portfolio to sustain channel dominance across dental clinics. Envista anchors its position through specialized R&D in wireless sensor architectures. Planmeca Oy differentiates via vertical control over Nordic manufacturing and distribution networks.
Digital intraoral sensors and consumables comprise solid-state photodetectors—typically CMOS or CCD arrays coupled with scintillator layers—that convert X-ray energy into digital images for chairside diagnostic review. These systems eliminate chemical processing, reduce patient radiation exposure by approximately half versus film, and integrate directly with practice management software for immediate treatment visualization. Wireless sensors command premium positioning due to ergonomic advantages and cable-free operatory workflow, while CMOS technology leads unit shipments through superior low-dose performance and lower manufacturing cost structures. Dental clinics represent the dominant end-user channel, though hospital-based dentistry programs are expanding procurement of surgical assistance configurations.
FDA 510(k) clearance timelines and ISO 13485 quality system requirements shape product development cycles and capital recovery horizons for manufacturers. EMA notified body capacity constraints under MDR are extending certification durations for European market entrants. Japan's PMDA pharmaceutical and medical device agency maintains distinct technical documentation standards that influence regional product configuration decisions. Stakeholders must monitor evolving cybersecurity guidance from FDA and harmonized IEC 62304 software lifecycle standards as connected imaging systems proliferate in clinical environments.
Market Dynamics
CMOS sensor architectures are compressing CCD legacy installations across dental operatories, while FDA cybersecurity guidance and EU MDR recertification cycles simultaneously extend product development timelines and capital recovery horizons for manufacturers.
Growth Catalysts
- Japan's PMDA diagnostic imaging reimbursement:National health insurance frameworks incentivize film-to-digital conversion in hospital-based dentistry programs, accelerating sensor procurement cycles.
- Wireless ergonomic workflows:Cable-free CMOS configurations reduce operator fatigue and enable flexible operatory layouts, driving replacement demand among established digital practices.
- ISO 13485 quality system harmonization:Standardized documentation requirements streamline multi-market registration pathways for manufacturers targeting concurrent FDA and CE marking.
Market Restraints
- Scintillator crystal supply concentration:Rare-earth phosphor processing capacity clusters in Chinese manufacturing zones, exposing sensor producers to input volatility and export control friction.
- EMA notified body capacity constraints:MDR technical documentation review queues extend certification timelines, delaying European revenue recognition for new market entrants.
- Film residual installed base:Analog radiography persists in cost-sensitive rural clinics and developing markets, creating substitution resistance and elongated replacement cycles.
Strategic Opportunities
- India's CDSCO medical device registration pathway:Streamlined import licensing for Class B diagnostic equipment opens access to a dental clinic base undergoing rapid private-sector expansion.
- AI-integrated diagnostic software convergence:Chairside radiographic analysis tools bundled with sensor hardware create differentiated value propositions and recurring revenue attachments.
- Direct-to-clinic distribution platforms:E-procurement portals bypass traditional dental dealer networks, capturing margin compression benefits and real-time demand signals.
Industry Challenges
- IEC 62304 software lifecycle compliance:Connected imaging systems require validated cybersecurity controls and documented risk management files, extending engineering headcount requirements.
- Legacy practice management integration:Proprietary DICOM implementations and non-standard API architectures complicate seamless data flow between new sensors and existing clinic IT infrastructure.
- Specialized field service technician scarcity:CMOS array calibration and scintillator replacement procedures demand trained personnel, constraining geographic service coverage expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Intraoral Sensors and Consumables Market |
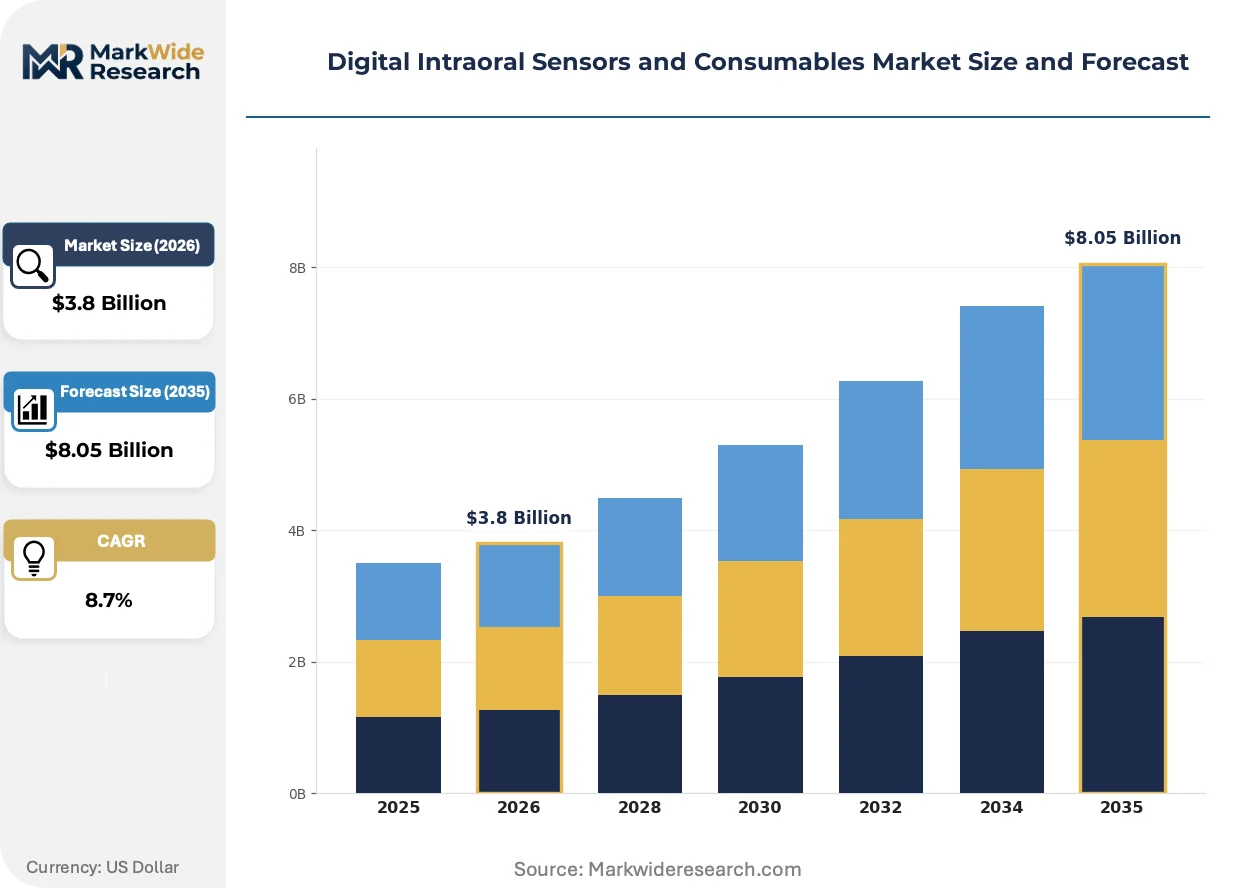
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Sensors, Wired Sensors, Image Sensors, Consumables Technology: CCD, CMOS, Digital X-Ray, Fluorescence Imaging End User: Dental Clinics, Hospitals, Research Labs, Academic Institutions Application: Diagnostic Imaging, Treatment Planning, Patient Monitoring, Surgical Assistance |
| Companies Covered | Dentsply Sirona, Envista, Planmeca Oy, Carestream Dental, Danaher Corporation, FONA Dental, Suni Medical Imaging, Dürr Dental, Acteon Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Intraoral Sensors and Consumables Market Emerging Trajectories
Digital intraoral imaging is experiencing simultaneous hardware miniaturization, software intelligence embedding, and procurement model rationalization that together compress traditional equipment lifecycle assumptions.
CMOS active pixel sensor technology is overtaking CCD architectures through superior low-dose quantum efficiency and simplified on-chip integration. Dental clinics in Germany and Japan are standardizing CMOS configurations for pediatric and orthodontic applications where radiation reduction carries premium patient value. This displacement is compressing CCD manufacturing scale economies and accelerating component supplier consolidation toward semiconductor foundries with CMOS-specific process nodes.
EU MDR Article 10 technical documentation requirements and post-market surveillance obligations are elevating compliance investment thresholds for sensor manufacturers. Small and mid-tier producers face capital allocation trade-offs between European market maintenance and alternative geography prioritization. German and French notified bodies are experiencing 14-18 month review queues, forcing manufacturers to sequence market entry timelines with cash flow planning.
Subscription-based equipment access models are displacing capital purchase structures in North American dental service organizations. Multi-location clinic groups negotiate fleet-wide sensor refresh programs with bundled maintenance and software upgrade entitlements. This pattern concentrates procurement authority at corporate headquarters, reducing individual practitioner discretion and compressing traditional dealer relationship value.
Digital Intraoral Sensors and Consumables Market Segmentation
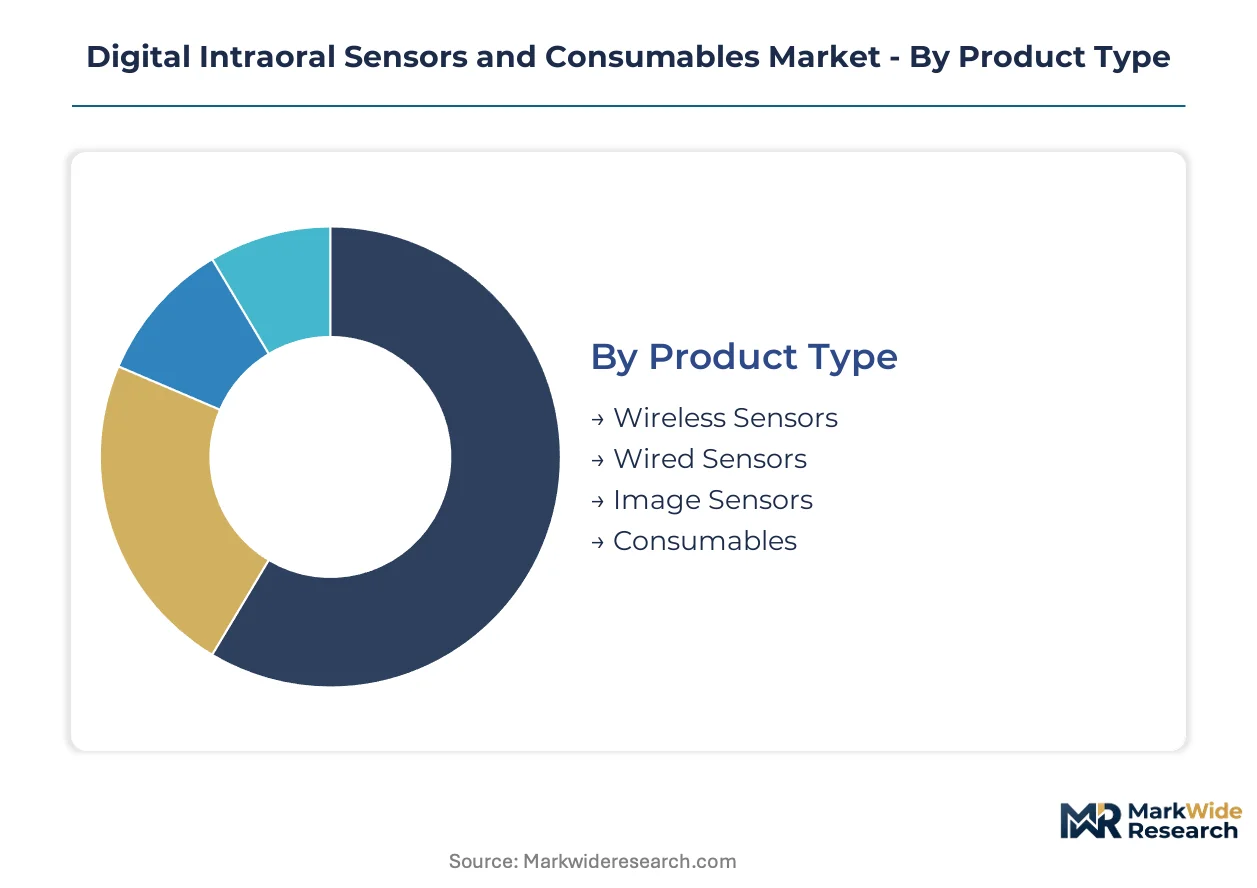
Segmentation in the Digital Intraoral Sensors and Consumables Market reveals divergent technology maturities and procurement patterns across clinical settings. CMOS architectures and wireless configurations command premium positioning while wired legacy systems sustain volume in cost-constrained installations.
Product Type:
Volume concentrates in wired installations; premium growth gravitates toward cable-free configurations that reduce operatory clutter.
- Wireless Sensors:CMOS arrays with integrated battery modules and Bluetooth transmission eliminate cable fatigue and enable flexible patient positioning. Dental clinics in Germany and Japan prioritize these configurations for pediatric applications where radiation reduction and patient comfort drive purchasing decisions.
- Wired Sensors:Tethered USB or proprietary cable connections deliver stable data throughput at lower unit economics. These systems dominate replacement cycles in rural North American clinics and developing markets where capital budgets constrain technology refresh rates.
- Image Sensors:Solid-state photodetector subassemblies—CMOS or CCD arrays coupled with scintillator layers—form the core imaging engine.
- Consumables:Protective sheaths, calibration phantoms, and scintillator replacement units generate recurring revenue attachments.
Today's leader: Wired Sensors. Tomorrow's challenger: Wireless Sensors.
Technology:
Application requirements determine sensor architecture selection, with dose sensitivity and integration complexity as primary trade-offs.
- CMOS:Active pixel sensor technology with on-chip analog-to-digital conversion delivers superior quantum efficiency at reduced radiation doses. FDA 510(k) clearance pathways favor CMOS submissions for pediatric and orthodontic indications where ALARA principles govern clinical practice.
- CCD:Charge-coupled device architectures with external digitization persist in installed base maintenance but face contracting manufacturing scale economies as semiconductor foundries retire legacy process nodes.
- Digital X-Ray:Broad category encompassing direct and indirect conversion sensor architectures.
- Fluorescence Imaging:Specialized optical detection for caries and bacterial biofilm visualization applications.
CMOS holds installed base dominance; Fluorescence Imaging climbs fastest in specialized diagnostic niches.
End User:
Procurement authority fragments across organizational types with diverging integration requirements and budget cycles.
- Dental Clinics:Independent and group practice settings drive unit volume through chairside immediacy requirements and practice management software compatibility demands.
- Hospitals:Japan's PMDA reimbursement frameworks accelerate film-to-digital conversion in hospital-based dentistry programs, concentrating demand for surgical assistance configurations with PACS integration.
- Research Labs:Academic medical centers and dental schools require validated imaging protocols for longitudinal studies.
- Academic Institutions:Training programs prioritize durable, standardized equipment for student operatories.
Dental Clinics anchor current procurement; Hospitals represent the steepest expansion trajectory through national diagnostic imaging upgrades.
Application:
Clinical use case determines sensor specification requirements from resolution to sterilization compatibility.
- Diagnostic Imaging:Routine radiographic examination for caries, periodontal assessment, and endodontic evaluation constitutes the core volume application across all end-user segments.
- Treatment Planning:Orthodontic and implant case preparation demands high-resolution sensors with measurement calibration tools.
- Patient Monitoring:Progress documentation for chronic conditions or orthodontic therapy.
- Surgical Assistance:Real-time intraoperative imaging for implant placement and endodontic procedures requires rapid image acquisition and specialized sensor sheathing.
Diagnostic Imaging commands present volume; Surgical Assistance gains share fastest through procedural integration demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized dental equipment engineers cluster in manufacturing centers across Germany, Japan, and the United States, anchoring regional innovation capacity for sensor development and calibration expertise.
United States
FDA 510(k) clearance pathways accelerate CMOS sensor introductions for pediatric dental applications where radiation reduction protocols dominate purchasing criteria. Dental service organizations in Texas and California negotiate fleet-wide procurement contracts that consolidate buying authority at corporate headquarters. The Greater Boston corridor hosts imaging software developers integrating AI diagnostic tools with sensor hardware platforms.
Germany
EMA notified body capacity constraints under MDR extend certification timelines to 14-18 months, forcing manufacturers to sequence European market entry with cash flow planning. Bavaria's precision manufacturing clusters supply scintillator assembly components to sensor producers across the continent. Frankfurt and Munich dental schools drive validation protocols for next-generation wireless configurations in academic settings.
Japan
PMDA reimbursement frameworks incentivize film-to-digital conversion in hospital-based dentistry programs, concentrating demand for surgical assistance sensor configurations. Tokyo and Osaka metropolitan areas host the highest density of digital radiography installations per dental practice in Asia. METI industrial policy supports domestic CMOS foundry capacity for medical imaging semiconductor production.
China
NMPA medical device registration requirements for Class II diagnostic equipment create structured pathways for imported sensor market access. Shenzhen and Shanghai manufacturing zones concentrate rare-earth phosphor processing capacity for scintillator crystal production. Yangtze River Delta dental clinic chains are expanding private-sector procurement of wireless sensor configurations amid rapid market development.
India
CDSCO streamlined import licensing for Class B diagnostic equipment opens market access as private dental clinic networks undergo rapid expansion. Maharashtra and Karnataka host the highest concentration of digital radiography installations among Indian metro dental markets. Central government PLI scheme incentives for medical device manufacturing are attracting component assembly investments to Gujarat industrial corridors.
Digital Intraoral Sensors and Consumables Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base separates into three strategic archetypes: integrated dental equipment conglomerates with imaging portfolios, specialized sensor technology developers, and regional fabrication specialists serving price-sensitive installations. Consolidation pressure operates through acquisition of wireless technology capabilities and backward integration into scintillator crystal supply chains. Geographic expansion into India's private clinic networks and subscription-based fleet refresh programs represent dominant competitive vectors.
Within the integrated conglomerate tier, Dentsply Sirona and Danaher Corporation occupy positions spanning full dental equipment portfolios. Envista exemplifies the specialized sensor technology archetype with concentrated R&D allocation toward wireless architectures. Planmeca Oy anchors the regional vertical integration model through Nordic manufacturing and distribution network control. These three company structures represent distinct strategic postures for navigating FDA, CE marking, and PMDA regulatory pathways simultaneously.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Envista |
| Planmeca Oy |
| Carestream Dental |
| Danaher Corporation |
| FONA Dental |
| Suni Medical Imaging |
| Dürr Dental |
| Acteon Group |
| Others |
Supply Flow & Price Mechanics
Specialized CMOS calibration engineers concentrated in Bavaria and Greater Boston drive labor-cost differentials that widen pricing-tier spreads between premium wireless configurations and economy wired alternatives. Manufacturing scale economies at semiconductor foundries in Taiwan and South Korea compress mid-tier pricing while FDA and CE marking compliance investments sustain premium positioning for validated sensor architectures.
Pricing Analysis
The bundled-versus-unbundled service split separates capital-purchase sensors from subscription-based fleet refresh programs with bundled maintenance and software upgrade entitlements. Pricing stratifies across premium wireless CMOS configurations, standard wired systems, and economy CCD legacy replacements based on certification tier and after-sales service bundling. Cost compression in the standard tier is intensifying as dental service organizations consolidate procurement authority and negotiate volume discounts. Rural independent clinics exhibit highest price sensitivity, while hospital-based dentistry programs in Japan demonstrate lowest sensitivity due to PMDA reimbursement coverage.
Supply Chain Analysis
Regional distribution centers in Frankfurt, Chicago, and Singapore anchor hub-and-spoke patterns that position finished sensors within 48-hour delivery windows of major dental markets. Scintillator crystal production draws from rare-earth phosphor processing capacity concentrated in China, with secondary sourcing from German specialty chemical manufacturers. Semiconductor wafer fabrication rests on Taiwan and South Korea foundries for CMOS array production. Single-source vulnerability in Chinese rare-earth processing exposes sensor producers to export control friction and input volatility. Distribution runs through authorized dental dealer networks, though direct-to-clinic e-procurement portals are capturing share among multi-location practice groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Digital Intraoral Sensors and Consumables Market functions as a stable compounder anchored by irreversible film-to-digital conversion tailwinds in hospital dentistry and orthodontic applications. Regulatory validation requirements and specialized calibration expertise create durable competitive moats around incumbent positions.
For Market Incumbents: Anticipate wireless technology displacement by securing captive scintillator supply through backward integration into rare-earth phosphor processing or long-term offtake agreements with Chinese suppliers. Dentsply Sirona and Envista should deepen software companion development for AI-integrated diagnostic tools that create switching costs and recurring revenue attachments. Channel control through exclusive distribution partnerships defends margin position against direct-to-clinic e-procurement encroachment.
For New Entrants and Emerging Players: Rural North American clinics represent an underserved buyer archetype with elongated replacement cycles and unmet demand for affordable wired CMOS configurations with simplified practice management integration. India's rapidly expanding private dental clinic networks offer the most penetrable geography, with CDSCO streamlined import licensing reducing regulatory barriers. A focused go-to-market angle targets group practice formations with subscription-based equipment access models that bypass capital budget constraints.
For Investors and Strategic Acquirers: Dental equipment conglomerates are the most active acquirer in this space, seeking wireless sensor capabilities and AI diagnostic software assets to complete integrated imaging portfolios. The market sustains long-term viability through procedural volume expansion and radiation reduction mandates that perpetuate technology refresh demand. Acquisition targets should demonstrate validated cybersecurity frameworks and ISO 13485 quality system documentation that accelerate multi-market registration. The signal to watch is EMA notified body queue lengths, as extended MDR certification timelines may force smaller producers toward distressed exit scenarios.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA notified body capacity constraints extend certification timelines to 14-18 months, requiring cash flow sequencing. |
| Wireless Sensor Development | CMOS arrays with Bluetooth transmission command premium positioning in German and Japanese pediatric applications. |
| Scintillator Supply Agreement | Captive rare-earth phosphor sourcing mitigates export control exposure from Chinese processing concentration. |
| Software Companion Development | AI-integrated diagnostic tools bundled with sensor hardware create recurring revenue and switching costs. |
| Hospital System Partnership | Japan's PMDA reimbursement frameworks accelerate film-to-digital conversion in hospital-based dentistry programs. |
Methodological Framework
Direct dialogue with dental equipment procurement managers, biomedical engineers at hospital dentistry programs, CMOS sensor R&D directors, and GPO contracts managers grounded qualitative findings in operational reality. Secondary validation drew from FDA 510(k) clearance databases, EMA MDR technical documentation submissions, PMDA reimbursement bulletins, and dental clinic procurement records. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions derived from manufacturer revenue disclosures and distributor channel audits.
Bottom-up modeling segmented volume and value across the projection horizon by product type, technology architecture, end-user setting, and clinical application. The analytical framework incorporated CMOS wafer foundry capacity utilization, scintillator crystal pricing indices, and dental clinic formation rates as industry-specific forecast inputs. CAGRs were derived from logistic diffusion curves fitted to technology substitution patterns and regulatory milestone impacts.
Inputs from PMDA reimbursement schedules and EMA notified body queue reports were available through the study window; gaps in real-time dental service organization fleet refresh contract terms introduce uncertainty bands around subscription model penetration assumptions. Forecasts reflect documented assumptions regarding wireless sensor battery longevity improvements and AI diagnostic software regulatory clearance pathways. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Craniomaxillofacial Fixation Devices Market
Medical Devices
Implantable Medical Devices Market
Medical Devices
Concentrator O2 Devices Market
Medical Devices
Cardiac Rhythm Management (CRM) Devices Batteries Market
Medical Devices
Bandage Contact Lenses Market
Medical Devices
High Viscosity Bone Cement Market
Medical Devices
Saudi Arabia Artificial Organs and Bionic Implants Market
Medical Devices
Neurointerventional Devices Market
Medical Devices
Hydrogen Inhalers Market
Medical Devices
North America General Surgical Devices Market
Medical Devices
Global Scleral Lens Market
Medical Devices
Global Vein Illuminator Market
Medical Devices
Europe Smart Medical Devices Market
Medical Devices
Global Acetabular Prostheses Market
Medical Devices
Brazil Aesthetic Devices Market
Medical Devices
Home-Use Water Flosser Market