
 Global Prosthetics Market | 2026-2036
Global Prosthetics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Prosthetics Market Foresight
Prosthetist workforce shortages in rural markets is rotating demand toward centralized fabrication labs and telehealth fitting protocols. Ottobock leverages its German engineering base to sustain premium myoelectric hand production. Össur anchors Nordic innovation in carbon fiber socket systems. Hanger Inc. competes across the United States through its owned clinic network and in-house fabrication capacity.
Prosthetics are custom-fabricated medical devices that replace missing body segments, typically combining carbon fiber laminates, titanium components, and silicone liners measured to sub-millimeter residual limb topography for load distribution and gait normalization. Lower limb products dominate volume due to vascular disease and trauma incidence, while microprocessor-controlled technology captures disproportionate value through computerized knee hydraulics that adapt to terrain in real time. Upper limb myoelectric systems remain a specialized margin pool where signal processing fidelity determines clinical outcomes and pricing power.
FDA 510(k) clearance pathways govern powered prosthetic introductions in the United States, while EMA medical device regulation and CE marking shape European commercialization timelines for novel socket materials. Japan's PMDA reviews myoelectric systems under pharmaceutical and medical device law, creating staggered approval calendars across major markets. Stakeholders must monitor reimbursement recalibrations by CMS and Germany's G-BA as these bodies weigh functional gain metrics against device acquisition costs for next-generation bionic limbs.
Market Dynamics
Microprocessor-controlled prosthetic systems are compressing fabrication timelines while elevating reimbursement scrutiny, forcing manufacturers to demonstrate functional gain metrics alongside hardware costs.
Growth Catalysts
- Diabetic limb loss prevalence:Vascular disease and diabetes-related amputations in the United States are expanding the addressable patient pool for advanced lower-limb devices.
- EMA MDR pathway acceleration:Streamlined CE marking processes for novel socket materials are shortening European commercialization cycles for carbon fiber laminates.
- Myoelectric signal processing:Advances in electromyography fidelity are enabling intuitive hand control, broadening clinical indications for upper-limb bionic systems.
Market Restraints
- Titanium supply concentration:Aerospace and medical device competition for titanium mill products creates input cost volatility for prosthetic component fabricators.
- PMDA review timelines:Japan's pharmaceutical and medical device law imposes extended approval calendars for powered prosthetic introductions, delaying market entry.
- Passive mechanical substitution:Low-cost body-powered hooks and mechanical knees retain share in price-sensitive segments, capping premium bionic penetration.
Strategic Opportunities
- Rural telehealth protocols:Prosthetist workforce gaps in the United States are creating demand for remote fitting and centralized fabrication models.
- CMS functional gain frameworks:Outcome-based reimbursement pilots for microprocessor knees reward demonstrated mobility improvement over device cost alone.
- Silicone liner customization:3D scanning and additive manufacturing convergence enables patient-specific socket topography without manual casting labor.
Industry Challenges
- Certified prosthetist scarcity:Clinical training program bottlenecks limit workforce expansion, constraining clinic network scaling and patient throughput.
- FDA 510(k) predicate navigation:Powered prosthetic innovators face complex substantial equivalence determinations when no direct predicate exists for novel knee hydraulic architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Prosthetics Market |
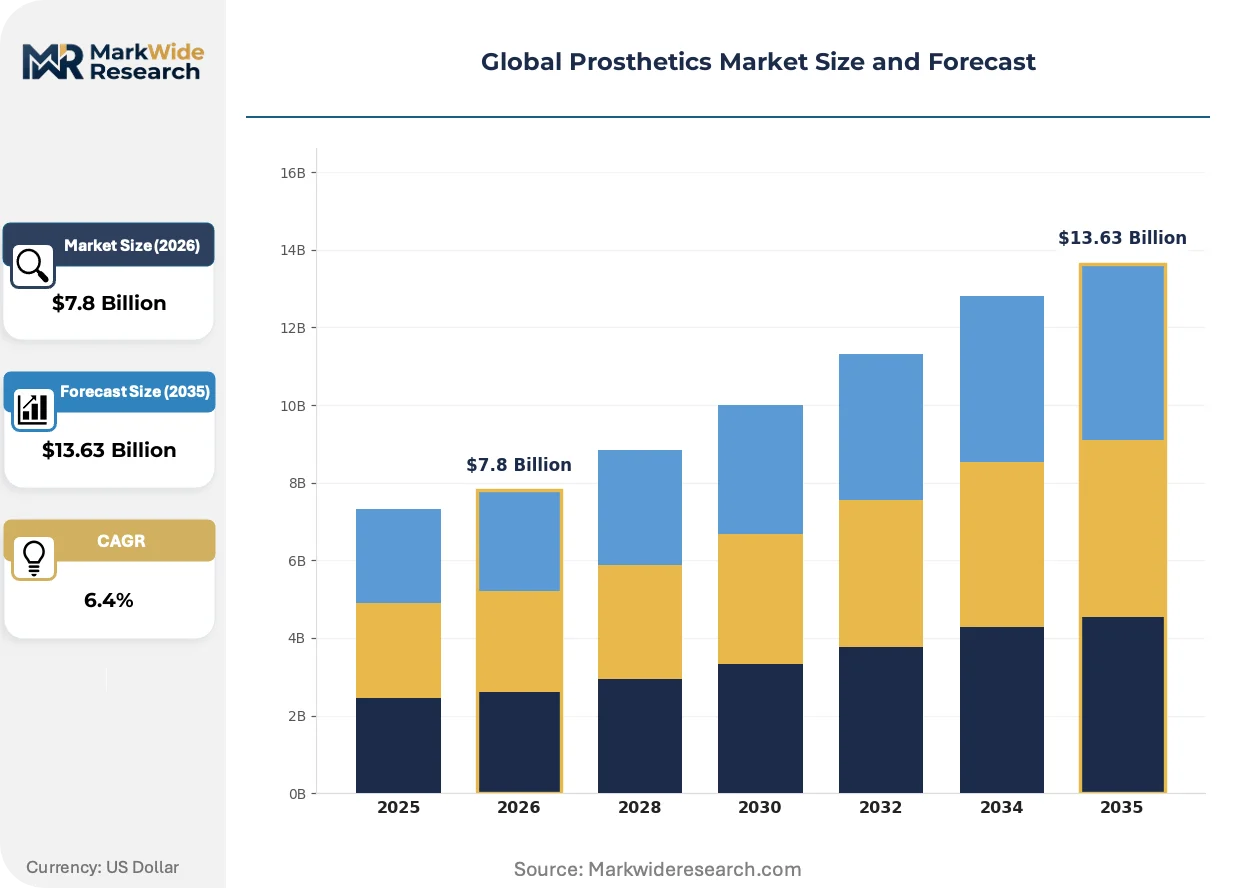
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Upper Limb, Lower Limb, Craniofacial, Spinal, Cosmetic Technology: Myoelectric, Body-Powered, Hybrid, Passive, Microprocessor-Controlled Application: Post-Traumatic, Congenital Deficiency, Vascular Disease, Cancer Reconstruction, Burn Injuries End User: Specialized Clinics, Rehabilitation Centers, Orthotic Facilities, Prosthetic Labs |
| Companies Covered | Össur, Ottobock, Hanger Inc., Blatchford Limited, Fillauer LLC, DJO Global, WillowWood Global LLC, Stryker Corporation, Smith & Nephew, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Prosthetics Market Shifts & Advancements
Prosthetic technology trajectories are diverging between premium bionic systems and streamlined mechanical alternatives, with regulatory and reimbursement frameworks determining viable commercialization paths.
Osseointegration technology is bifurcating the socket interface market. Titanium implant systems that directly anchor prostheses to bone eliminate traditional socket-skin friction. Veterans Affairs healthcare systems and select Nordic hospital networks are piloting these procedures for transfemoral amputees. The technology is bifurcating residual limb care protocols, creating parallel specialist tracks for surgical implantation versus conventional socket fitting.
EU MDR recalibration is compressing notified body capacity for prosthetic device reviews. Stricter clinical evidence requirements for Class IIa and IIb devices are extending CE marking timelines. German and French manufacturers with established quality management systems are absorbing compliance costs more readily than mid-tier competitors, consolidating European market access.
Hospital procurement consolidation is centralizing prosthetic device purchasing across integrated delivery networks. Large health systems in the United States are negotiating direct contracts with manufacturers, bypassing traditional distributor relationships. This concentration is most visible in the southeastern and midwestern states where regional hospital alliances dominate rehabilitation service provision.
Global Prosthetics Market Segmentation
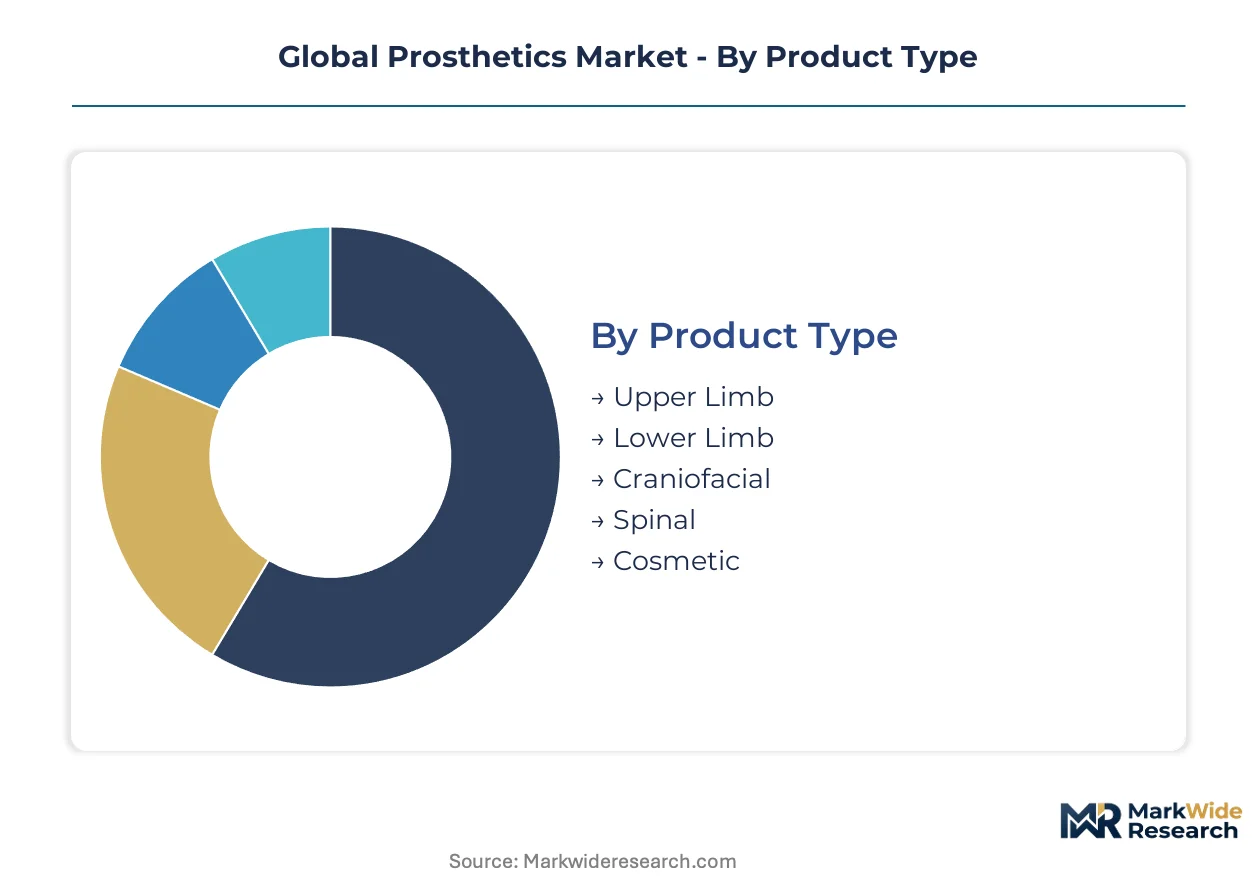
Prosthetic device categories diverge sharply in reimbursement pathways, fabrication complexity, and geographic demand concentration. Each segment carries distinct regulatory requirements and clinical training prerequisites that shape commercialization strategy.
Product Type:
Lower limb systems dominate domestic fabrication volumes across OECD markets, while upper limb and craniofacial categories concentrate in specialized export-led manufacturing hubs.
- Lower Limb:Carbon fiber pylons and titanium pylons absorb ground reaction forces across transfemoral and transtibial configurations. Demand clusters in Germany, Japan, and the United States where vascular disease amputations drive prescription volume and microprocessor knee reimbursement.
- Upper Limb:Myoelectric hand systems with multi-articulating digits require precision electromyography signal processing. Export-led manufacturing from Iceland and Germany supplies clinical programs in Australia and South Korea seeking advanced bionic functionality.
- Craniofacial:Silicone facial prosthetics replicate aesthetic contours for orbital and nasal defects.
- Spinal:Orthotic stabilization systems address scoliosis and post-surgical support.
- Cosmetic:Passive aesthetic replacements prioritize appearance over active function.
Lower limb commands the established base. The steepest expansion runs through upper limb myoelectric systems.
Technology:
Cost tier stratification separates premium computerized systems from mechanical alternatives, with hybrid architectures occupying mid-tier positioning.
- Microprocessor-Controlled:Computerized knee hydraulics adapt stance-phase resistance to terrain and gait velocity in real time. Veterans Affairs programs in the United States and statutory health insurance in Germany cover these devices where functional gain metrics demonstrate mobility improvement.
- Myoelectric:Surface electromyography electrodes capture residual muscle signals to activate motorized hand and wrist components. Pediatric applications in France and the Netherlands are broadening as signal processing algorithms reduce calibration burden.
- Body-Powered:Cable-operated harness systems harness shoulder movement for hook or hand actuation.
- Hybrid:Combined myoelectric and body-powered control suits transitional amputees.
- Passive:Non-articulating limbs provide structural support without powered movement.
Microprocessor-controlled technology captures premium value concentration. Myoelectric systems are gaining share fastest in pediatric and bilateral indications.
Application:
Volume concentration tracks trauma incidence in emerging markets against vascular disease prevalence in aging OECD populations.
- Vascular Disease:Diabetic foot complications and peripheral arterial disease generate transtibial amputations requiring definitive prosthetic fitting. United States Medicare and Germany's G-BA reimburse advanced socket systems where healing permits early mobilization.
- Post-Traumatic:Industrial accidents and traffic injuries dominate demand in India, Brazil, and Southeast Asian manufacturing corridors. Mechanical knee and foot systems retain share where reimbursement infrastructure remains underdeveloped.
- Congenital Deficiency:Pediatric limb absence from genetic or developmental conditions requires iterative prosthetic replacement through growth.
- Cancer Reconstruction:Oncologic amputations demand durable temporary and definitive solutions.
- Burn Injuries:Thermal and electrical trauma necessitate specialized socket interface management.
Vascular disease anchors volume in reimbursed markets. Post-traumatic applications represent the fastest volume growth in price-sensitive geographies.
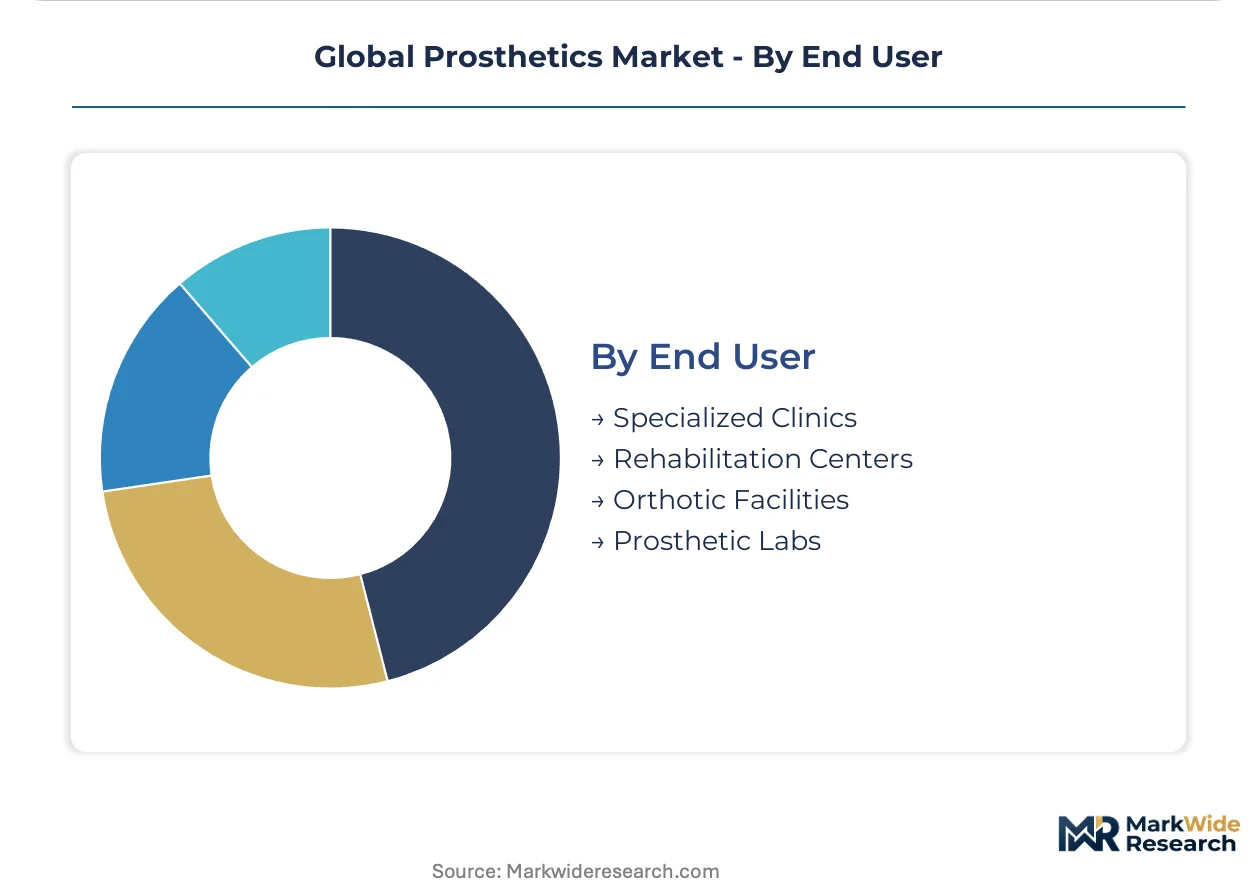
End User:
Customer type fragmentation separates hospital-integrated procurement from independent specialist networks.
- Specialized Clinics:Physician-owned prosthetic practices combine diagnostic, casting, and fitting in single-site delivery. United States integrated delivery networks in Texas and Florida are consolidating these assets under regional health system ownership.
- Rehabilitation Centers:Inpatient and outpatient therapy facilities coordinate prosthetic provision with gait training. Japan's Ministry of Health certifies designated rehabilitation hospitals for myoelectric device dispensing.
- Orthotic Facilities:Limb and brace specialists serve overlapping patient populations with socket and spinal orthosis expertise.
- Prosthetic Labs:Centralized fabrication shops supply componentry to satellite fitting locations.
Specialized clinics command the established base. Rehabilitation centers are expanding fastest through hospital network integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major markets, with Germany and the United States prioritizing microprocessor-controlled reimbursement while emerging economies retain mechanical device dominance due to cost constraints and infrastructure gaps.
United States
Veterans Affairs healthcare systems and Medicare drive demand for computerized knee systems among diabetic and vascular disease patients. FDA 510(k) clearance pathways govern powered prosthetic introductions, creating structured approval timelines. Texas and Florida host consolidated clinic networks where hospital procurement alliances negotiate direct manufacturer contracts.
Germany
Statutory health insurance through G-BA covers advanced bionic devices where functional gain metrics justify acquisition costs. EMA MDR and CE marking requirements shape European commercialization for novel socket materials. Engineering clusters in Bavaria and North Rhine-Westphalia sustain premium myoelectric hand production for export markets.
Japan
Aging demographics and peripheral arterial disease expand the addressable patient pool for definitive prosthetic fitting. PMDA reviews myoelectric systems under pharmaceutical and medical device law, imposing extended approval calendars. Designated rehabilitation hospitals in Tokyo and Osaka coordinate prosthetic provision with certified gait training protocols.
Iceland
Specialized manufacturing concentrates on carbon fiber socket systems and microprocessor knee exports to OECD markets. EU regulatory alignment through EEA membership streamlines CE marking for Nordic innovation. Reykjavik-based fabrication serves clinical programs in Australia and South Korea seeking advanced bionic functionality.
India
Post-traumatic applications from industrial accidents and traffic injuries dominate volume demand in manufacturing corridors. CDSCO regulates medical device imports while domestic production scales for mechanical knee and foot systems. Maharashtra and Gujarat host prosthetic component fabricators serving price-sensitive segments with body-powered alternatives.
Global Prosthetics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with German and Nordic engineering bases commanding premium positioning against North American clinic-network operators. The structure stratifies across three archetypes: vertically integrated manufacturers with in-house fabrication, specialist component suppliers focused on carbon fiber or silicone technologies, and service-integrated distributors owning patient-facing clinic networks. Competitive moves concentrate on M&A consolidation of regional clinic assets and strategic partnerships to secure titanium supply agreements.
Among European integrated manufacturers, Ottobock GmbH and Össur hf exemplify the engineering-led archetype with sustained focus on myoelectric and microprocessor systems. Hanger Inc. occupies a distinct position as a United States-based service-integrated operator combining owned clinic networks with centralized fabrication capacity. These three represent the dominant competitive vectors: German precision manufacturing, Nordic carbon fiber innovation, and American vertical integration into patient delivery.
| Leading Market Players |
|---|
| Össur |
| Ottobock |
| Hanger Inc. |
| Blatchford Limited |
| Fillauer LLC |
| DJO Global |
| WillowWood Global LLC |
| Stryker Corporation |
| Smith & Nephew |
| Others |
Supply & Pricing Matrix
Carbon fiber laminate substitution for traditional thermoplastic socket materials is redrawing procurement geography toward Icelandic and German engineering clusters while compressing per-unit fabrication economics for premium lower-limb systems.
Pricing Analysis
Long-term offtake agreements between German manufacturers and statutory health insurers anchor pricing stability for microprocessor-controlled knees, while spot-market titanium transactions inject volatility into component costs. Three-tier pricing structure across premium computerized systems, standard mechanical devices, and economy body-powered alternatives segments buyer budgets. Price differentiation hinges on FDA 510(k) clearance tier and after-sales calibration service bundling. Cost compression in the mechanical tier is intensifying because Indian fabricators scale domestic production for price-sensitive trauma applications.
Supply Chain Analysis
Inventory buffers for titanium mill products stretch to six months given aerospace competition for forged bar stock, forcing prosthetic component fabricators into advance purchasing commitments. Supply concentrates in Germany for myoelectric hand systems, Iceland for carbon fiber socket laminates, and the United States for centralized fabrication lab networks. Raw material dependencies span titanium alloys from Russian and Ukrainian feedstock, carbon fiber prepregs from Japanese Toray facilities, and medical-grade silicone from German Wacker Chemie operations. Single-source vulnerability in titanium sponge processing creates exposure to export restriction shocks. Distribution runs through hospital procurement alliances in Texas and Florida, bypassing traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement consolidation across United States integrated delivery networks is shifting negotiating leverage toward buyers, compressing manufacturer margins and rewarding scale-backed contract bidders.
For Market Incumbents: Consolidate regional clinic assets in the southeastern and midwestern United States to defend against direct manufacturer contracting by hospital alliances. Deepen backward integration into titanium component forging to offset aerospace demand spikes and secure input cost predictability. Ottobock and Össur should prioritize EMA MDR quality management system investments to absorb compliance costs that mid-tier European competitors cannot shoulder. For New Entrants and Emerging Players: Rural prosthetist workforce gaps in the United States present service-layer white space for remote fitting platforms and centralized fabrication partnerships. Target post-traumatic applications in Maharashtra and Gujarat manufacturing corridors with body-powered mechanical knees priced below imported computerized alternatives. Pursue CDSCO domestic manufacturing registration to capture Indian government procurement contracts for trauma-center supply. For Investors and Strategic Acquirers: The market sits at a reimbursement-recalibration phase that favors vertically integrated operators with owned clinic networks and in-house fabrication capacity. Five-to-ten year viability rests on CMS functional gain framework alignment and G-BA outcome-based contracting adoption. Watch for PMDA accelerated review pathway announcements for myoelectric systems as the inflection signal for Japanese market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | CMS functional gain pilots reward demonstrated mobility improvement over device acquisition cost alone. |
| CE Marking Pathway | EMA MDR streamlined processes shorten European commercialization cycles for novel socket materials. |
| Hospital System Partnership | Direct contracts with Texas and Florida integrated delivery networks bypass traditional distributor relationships. |
| Backward Integration | In-house titanium component forging insulates against aerospace competition for mill products. |
| Software Companion Development | Telehealth fitting protocols address prosthetist workforce gaps in rural United States markets. |
Research Methodology
Initial hypotheses were tested against primary input from certified prosthetists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers and refined through secondary validation across FDA 510(k) filings, EMA MDR notified body decisions, CMS Medicare reimbursement databases, and G-BA benefit assessment documents. Bottom-up patient volume modeling by amputation etiology and top-down expenditure analysis by statutory insurance program were triangulated against manufacturer shipment data.
Variance decomposition across product type, technology tier, application indication, and end-user channel shaped the analytical framework over the projection horizon. CAGRs were derived from segmented volume projections calibrated to diabetic limb loss prevalence trajectories and microprocessor knee reimbursement expansion curves. Modeled inputs incorporated PMDA review timeline assumptions, titanium price elasticity estimates, and rural telehealth adoption scenarios.
Forecasts assume regulatory continuity in FDA 510(k) clearance pathways, EMA MDR enforcement patterns, and Japan's PMDA pharmaceutical and medical device law; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Cervical Total Disc Replacement (CTDR) Market
Medical Devices
Hand and Wrist Devices Market
Medical Devices
Cardiac Catheters and Guidewires Market
Medical Devices
Global Medical Suction Devices Market
Medical Devices
Global Cosmetic Implants Market
Medical Devices
Laparoscopic Electrodes Market
Medical Devices
Motorized Prosthesis Market
Medical Devices
Single-Lead ECG Monitors Market
Medical Devices
Global Smart Wearable Healthcare Devices Market
Medical Devices
Cholecystectomy Devices Market
Medical Devices
Americas Wearable Medical Device Market
Medical Devices
Transportable Ventilator Market
Medical Devices
Cast Removal Devices Market
Medical Devices
Focused Ultrasound System Market
Medical Devices
Artificial Implants Market
Medical Devices
Robotic Angiography Systems Market