
 Global Low Molecular Weight Heparin Market | 2026-2036
Global Low Molecular Weight Heparin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Low Molecular Weight Heparin Market Foresight
Chinese API manufacturers are pivoting toward European pharmacopoeia compliance to secure downstream contracts with formulation giants. Sanofi leverages its vertically integrated heparin supply chain from porcine sourcing to finished dosage forms. Pfizer Inc. competes through hospital-centric distribution networks across North America and Western Europe. Amphastar Pharmaceuticals Inc. specializes in complex generic enoxaparin with preserved biological activity profiles.
Low molecular weight heparin comprises depolymerized unfractionated heparin chains with mean molecular weights between 3,500 and 5,500 daltons, administered subcutaneously for predictable anticoagulant response without routine coagulation monitoring. The molecule inhibits factor Xa preferentially over thrombin, making it standard prophylaxis for post-surgical venous thromboembolism. Enoxaparin dominates product type revenue due to decades of clinical validation and broad formulary inclusion across payer systems. Pre-filled syringes command the formulation margin pool through convenience premiums and reduced medication error liability. Home healthcare providers represent the fastest-growing end user channel as payers push for outpatient thromboprophylaxis.
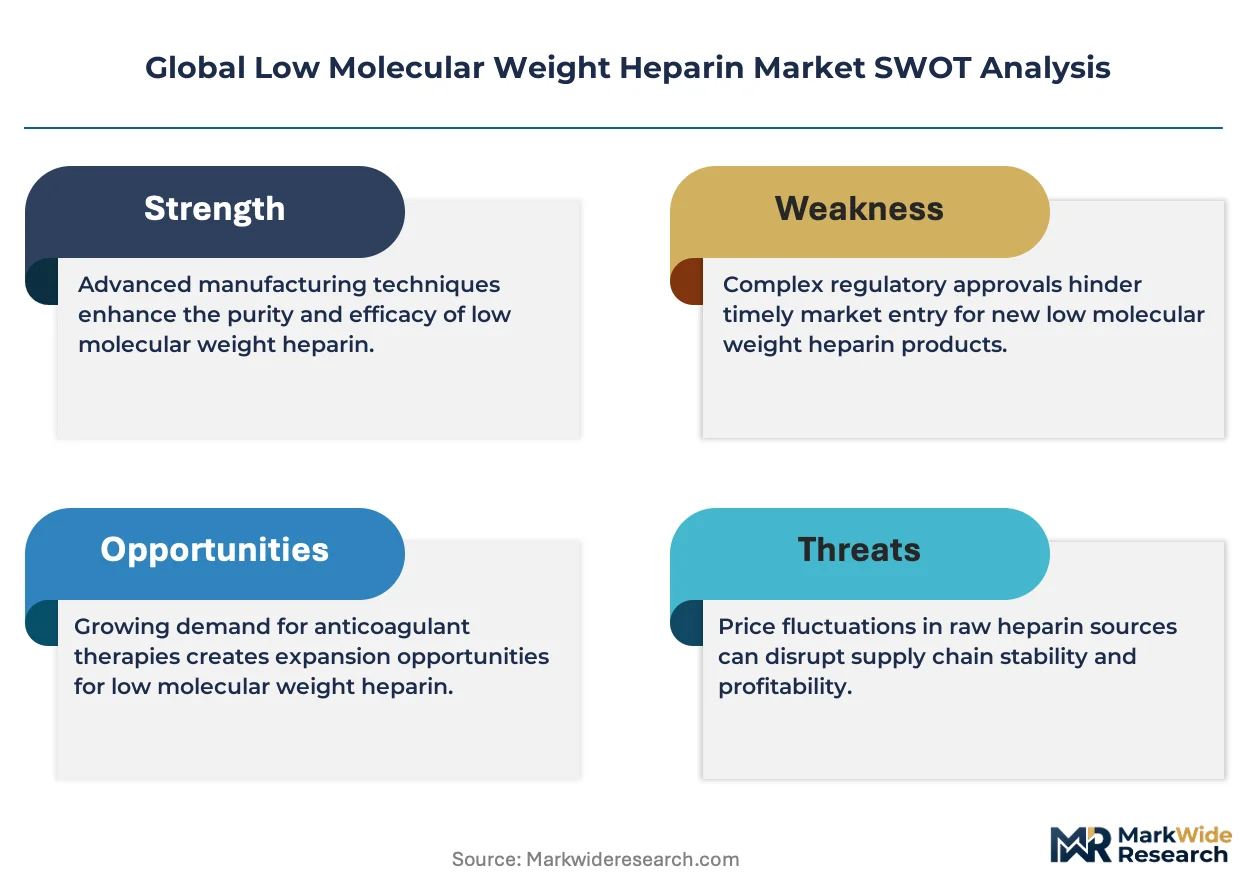
The FDA enforces immunogenicity testing standards that constrain biosimilar entry, while the EMA's MDR requirements elevate post-market surveillance obligations for heparin device combinations. China's NMPA has tightened crude heparin sourcing documentation following prior contamination events, reshaping supplier qualification timelines. Stakeholders must monitor evolving pharmacovigilance mandates that link manufacturing traceability to reimbursement access across major prescribing markets.
Market Dynamics
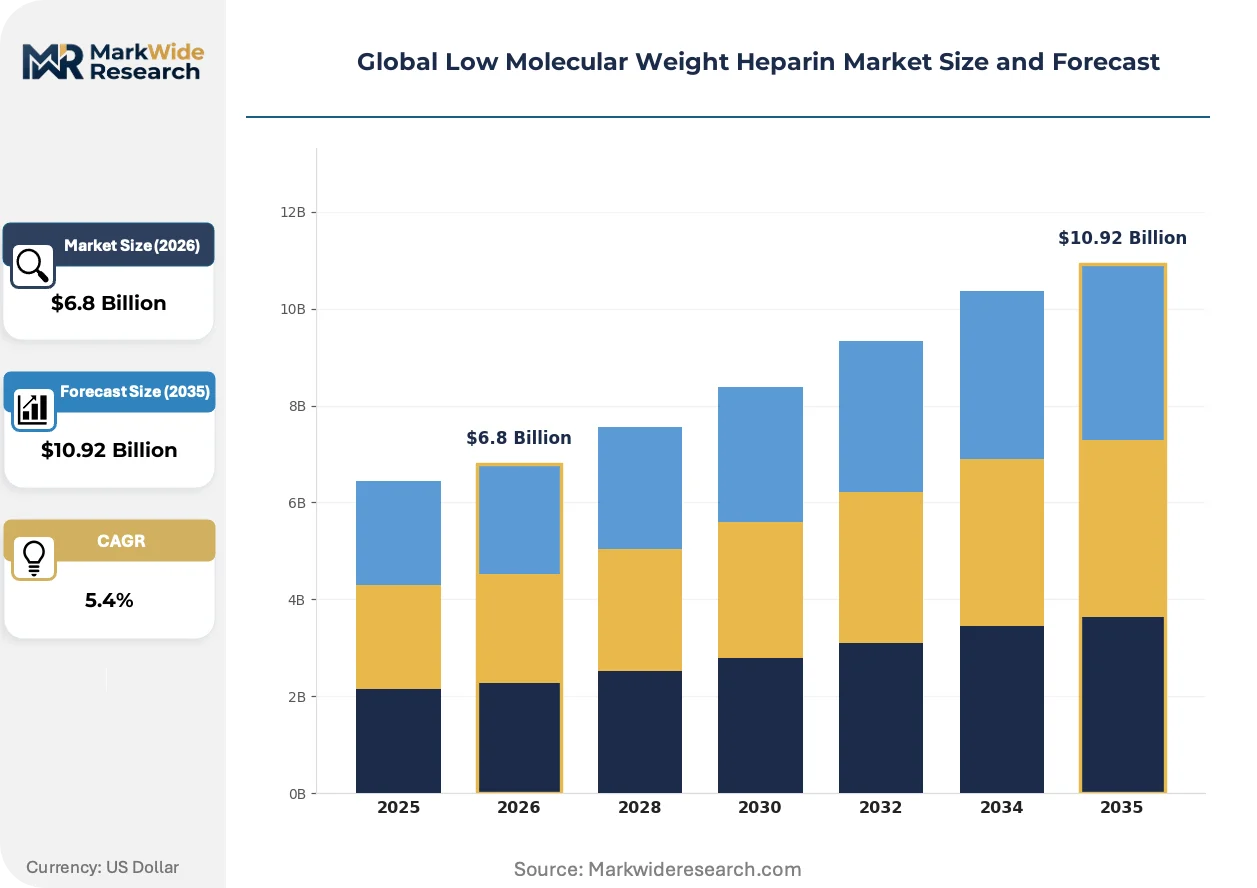
Hospital procurement of anticoagulant therapies is intensifying as surgical volumes rebound post-pandemic, while FDA bioequivalence guidelines for heparin derivatives reshape generic substitution patterns and concentrate purchasing power among integrated health systems.
Growth Catalysts
- EMA MDR Surveillance Mandates:Elevated post-market obligations for heparin device combinations accelerate adoption of pre-filled syringe formats with embedded safety features across Western European hospital networks.
- Home Healthcare Channel Expansion:Payer pressure for outpatient thromboprophylaxis drives demand for patient-administered subcutaneous formulations, reducing institutional bed-day costs.
- China's Thrombosis Protocol Expansion:National clinical guideline updates in tertiary hospitals standardize LMWH prophylaxis across orthopedic and oncological surgical departments.
Market Restraints
- Porcine-Derived Input Volatility:Crude heparin sourcing depends on livestock supply cycles and veterinary health events, creating raw material cost instability for API manufacturers.
- FDA Immunogenicity Barriers:Stringent biosimilar entry requirements for heparin derivatives limit generic competition and sustain originator pricing power in the United States.
- Substitution Threat from DOACs:Direct oral anticoagulants displace LMWH in certain ambulatory indications where routine monitoring is acceptable.
Strategic Opportunities
- Brazilian Hospital Sector Modernization:ANVISA regulatory harmonization with ICH standards opens pathways for European and North American suppliers to access Latin America's largest surgical market.
- Pre-filled Syringe Device Convergence:Integration of needle-stick prevention mechanisms with connected health data capture creates premium positioning for safety-engineered combination products.
- India's PLI Scheme for APIs:Domestic production incentives for critical starting materials reduce import dependence and enable regional formulation hubs to serve Southeast Asian markets.
Industry Challenges
- Analytical Methodology Talent Scarcity:Characterization of complex polysaccharide molecular weight distributions requires specialized chromatography expertise that outpaces current training pipeline output.
- Legacy ERP Integration Friction:Batch-level traceability requirements for heparin sourcing documentation strain manufacturing execution systems not designed for agricultural supply chain visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Low Molecular Weight Heparin Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enoxaparin, Dalteparin, Nadroparin, Tinzaparin, Reviparin Therapy Area: Venous Thromboembolism, Coronary Artery Disease, Stroke Prevention, Deep Vein Thrombosis, Pulmonary Embolism End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Diagnostic Laboratories, Home Healthcare Providers Formulation: Pre-filled Syringes, Multi-dose Vials, Lyophilized Powder, Injectable Solution, Auto-injectors |
| Companies Covered | Aspen Holdings, Changzhou Qianhong Bio-Pharma, B. Braun Medical Inc., Pfizer Inc., Dr. Reddy's Laboratories Limited, Sanofi, LEO Pharma A/S, Teva Pharmaceutical Industries Ltd, Amphastar Pharmaceuticals Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Low Molecular Weight Heparin Market Shifts & Advancements
Biological activity preservation technologies and connected delivery devices are reshaping competitive differentiation in anticoagulant administration, while regulatory convergence around pharmacovigilance traceability reconfigures supplier qualification protocols.
Biosimilar analytical platforms are integrating advanced orthogonal methods for molecular weight profiling and anti-Xa activity correlation. Contract research organizations serving generic developers are adopting these capabilities to accelerate ANDA submission timelines. The technology is integrating quality-by-design principles that compress development cycles from characterization to commercial validation.
China's NMPA has tightened crude heparin sourcing documentation requirements following prior contamination events, extending supplier qualification timelines by 12-18 months for non-vertically integrated manufacturers. This regulatory friction favors API producers with captive porcine processing capabilities. European formulation giants are responding by consolidating supplier panels and demanding real-time supply chain transparency.
Hospital purchasing consortia are consolidating anticoagulant procurement under centralized pharmacy and therapeutics committees, displacing individual physician preference as the primary volume determinant. Group purchasing organizations negotiate sole-source or dual-source contracts with rebate structures tied to adherence metrics. This concentration is most visible in United States integrated delivery networks and German hospital federations seeking to standardize formulary compliance.
Global Low Molecular Weight Heparin Market Segmentation
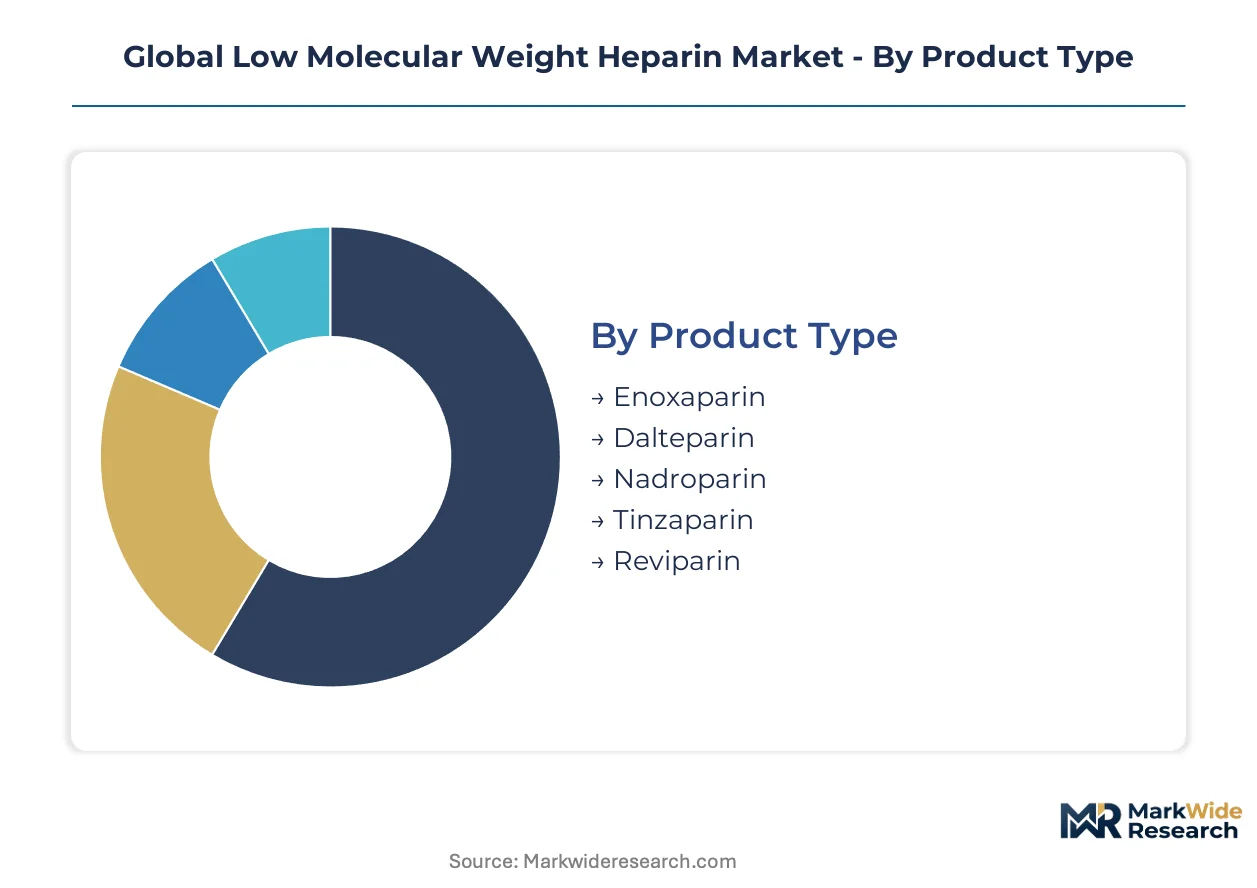
Segmentation in the LMWH market reveals how regulatory pathways, clinical protocols, and reimbursement structures fragment commercial opportunity across product formats and care settings. Each dimension carries distinct certification burdens and margin profiles that determine competitive positioning.
Product Type:
Certification requirements vary sharply across molecular entities: enoxaparin faces the most stringent FDA immunogenicity testing, while newer derivatives navigate abbreviated pathways where bioequivalence frameworks remain unsettled.
- Enoxaparin:The most clinically validated LMWH derivative with decades of formulary inclusion across United States, German, and Chinese hospital systems. Demand concentrates in tertiary surgical centers where thromboprophylaxis protocols mandate predictable anti-Xa activity profiles; FDA bioequivalence guidelines sustain originator pricing power despite generic entry.
- Dalteparin:Longer half-life enables once-daily dosing in oncology-associated thrombosis indications. Oncology departments in United States academic medical centers drive volume; EMA post-market surveillance requirements for extended-duration therapy elevate documentation burdens for suppliers.
- Nadroparin:European pharmacopoeia compliance requirements shape competitive access for this calcium salt formulation.
- Tinzaparin:Sodium-based derivative with distinct molecular weight distribution requiring specialized analytical validation.
- Reviparin:Narrower approved indication set limits commercial scale outside select European markets.
Leading the category by volume: enoxaparin. Growing fastest: dalteparin in oncology thromboprophylaxis protocols.
Therapy Area:
Clinical guidelines and reimbursement codes determine which indications support premium pricing versus commodity substitution, with surgical prophylaxis commanding tighter margins than complex medical thrombosis management.
- Venous Thromboembolism:Post-surgical prophylaxis represents the foundational indication with standardized dosing protocols. Orthopedic and general surgery departments in German hospital federations drive institutional procurement; bundled payment structures compress per-dose margins while elevating volume commitments.
- Coronary Artery Disease:Acute coronary syndrome applications require precise anti-Xa monitoring in catheterization laboratories. United States interventional cardiology suites concentrate demand; American College of Cardiology guideline updates directly influence formulary placement cycles.
- Stroke Prevention:Atrial fibrillation bridging therapy faces displacement pressure from DOACs in ambulatory settings.
- Deep Vein Thrombosis:Standardized treatment algorithms limit differentiation opportunity across product types.
- Pulmonary Embolism:Hospital admission requirements sustain inpatient administration despite outpatient thrombolysis advances.
Volume concentration: venous thromboembolism prophylaxis. Steepest expansion trajectory: coronary artery disease in Asian tertiary centers.
End User:
Procurement authority and reimbursement mechanisms diverge sharply across institutional versus outpatient channels, with group purchasing organizations reshaping vendor selection criteria.
- Hospitals:Integrated delivery networks and German hospital federations consolidate purchasing under pharmacy and therapeutics committees. Centralized procurement with sole-source contracts tied to adherence metrics displaces physician preference; safety-engineered device combinations command premium positioning.
- Home Healthcare Providers:Patient-administered subcutaneous formulations reduce institutional bed-day costs under United States Medicare bundled payment models. Home infusion agencies represent the channel gaining share fastest; training requirements and remote monitoring capabilities determine supplier selection.
- Ambulatory Surgical Centers:Same-day discharge protocols limit LMWH exposure to prophylactic dosing windows.
- Specialty Clinics:Hematology and oncology practices drive dalteparin volume in extended-duration therapy.
- Diagnostic Laboratories:Anti-Xa activity testing supports therapeutic drug monitoring in complex cases.
Dominant procurement channel: hospitals. Expanding most quickly: home healthcare providers under payer cost-containment pressure.
Formulation:
Device complexity and safety engineering differentiate margin tiers, with regulatory convergence on needle-stick prevention accelerating format transitions.
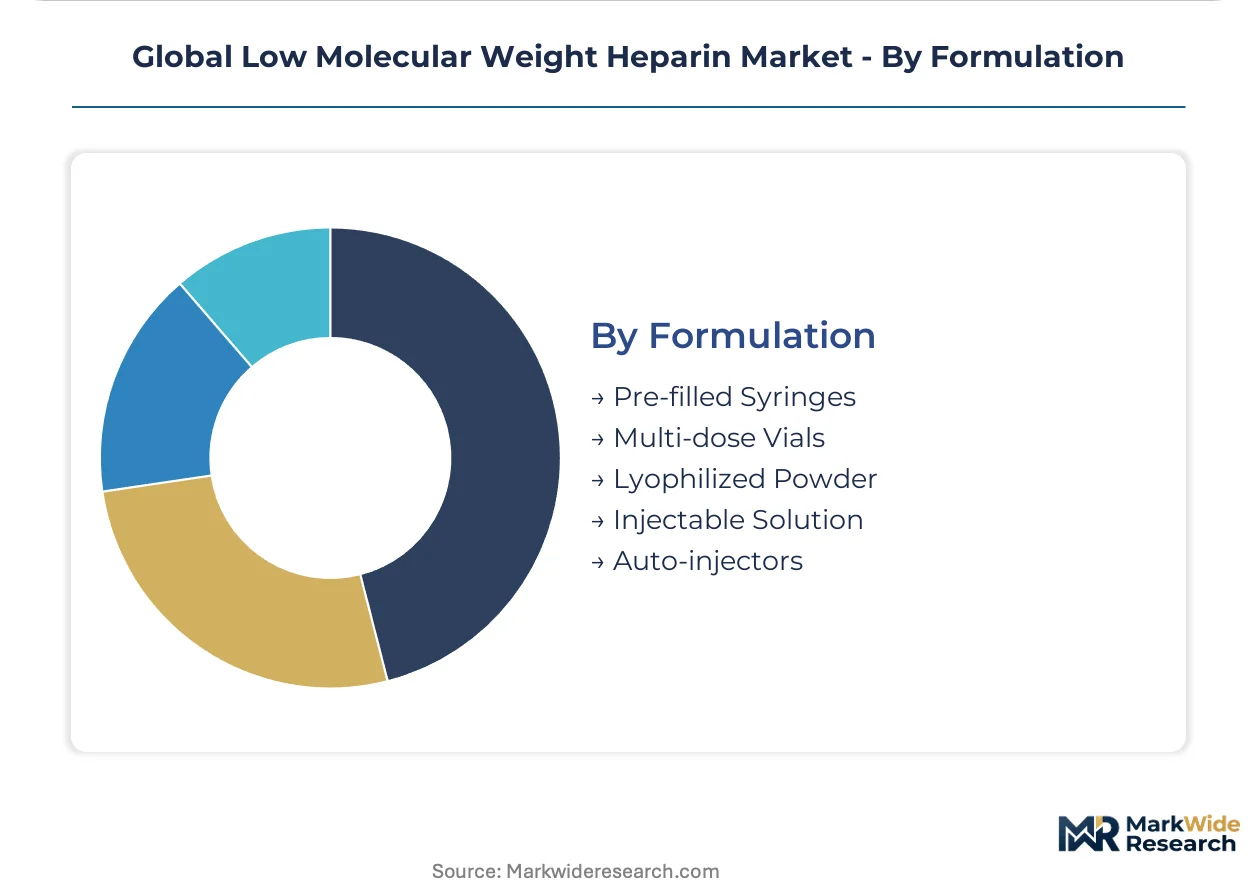
- Pre-filled Syringes:Convenience premiums and reduced medication error liability sustain margin leadership. EMA MDR surveillance mandates for heparin device combinations accelerate adoption of formats with embedded safety features across Western European hospital networks; connected health data capture integration creates additional value layers.
- Auto-injectors:Needle-stick prevention mechanisms with patient-friendly actuation expand outpatient thromboprophylaxis feasibility. United States home healthcare agencies drive pilot adoption; real-world evidence requirements for reimbursement coverage extend validation timelines.
- Multi-dose Vials:Cost-sensitive institutional procurement favors this format for high-volume surgical services.
- Lyophilized Powder:Extended shelf stability supports stockpiling requirements in national strategic reserves.
- Injectable Solution:Compounding pharmacy applications face tightening USP <797> sterile preparation standards.
Highest margin pool: pre-filled syringes. Climbing the fastest: auto-injectors with connected device capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Porcine heparin sourcing clusters in Shandong Province and Jiangsu Province anchor Chinese API production, while formulation manufacturing concentrates in the United States, Germany, and China as these countries expand thrombosis management protocols and tighten regulatory oversight.
United States
Hospital procurement consortia and integrated delivery networks drive anticoagulant volume as surgical volumes rebound post-pandemic. The FDA enforces immunogenicity testing standards that constrain biosimilar entry and sustain originator pricing power. New Jersey and Massachusetts host formulation manufacturing clusters where companies navigate ANDA submission timelines for complex generic enoxaparin.
Germany
German hospital federations consolidate purchasing under pharmacy and therapeutics committees, standardizing formulary compliance across orthopedic and general surgery departments. The EMA's MDR requirements elevate post-market surveillance obligations for heparin device combinations. The Rhine-Ruhr and Bavarian medical technology corridors concentrate pre-filled syringe manufacturing with embedded safety features.
China
Tertiary hospitals in Beijing and Shanghai expand thrombosis prophylaxis protocols across orthopedic and oncological surgical departments following national clinical guideline updates. The NMPA has tightened crude heparin sourcing documentation, extending supplier qualification timelines by 12-18 months. Shandong and Jiangsu provinces dominate API production as manufacturers pivot toward European pharmacopoeia compliance.
India
Domestic production incentives under the PLI scheme for critical starting materials reduce import dependence and enable regional formulation hubs. CDSCO regulatory pathways support export-oriented manufacturing for Southeast Asian markets. Hyderabad and Ahmedabad clusters specialize in complex polysaccharide characterization and chromatography expertise.
Brazil
ANVISA regulatory harmonization with ICH standards opens pathways for European and North American suppliers to access Latin America's largest surgical market. Hospital sector modernization drives demand for safety-engineered anticoagulant delivery devices. São Paulo and Rio de Janeiro medical centers concentrate procurement authority for thromboprophylaxis protocols.
Global Low Molecular Weight Heparin Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance capabilities and supply chain traceability. The vendor base stratifies into three tiers: vertically integrated heparin specialists with captive porcine sourcing, formulation-focused pharmaceutical conglomerates with hospital-centric distribution networks, and complex generic developers with preserved biological activity expertise. Strategic moves center on backward integration into crude heparin supply and consolidation of supplier panels under real-time transparency mandates.
Among the vertically integrated tier, Sanofi exemplifies upstream control from porcine sourcing through finished dosage forms. Pfizer Inc. anchors the hospital-centric distribution archetype across North American and Western European networks. Amphastar Pharmaceuticals Inc. occupies a position within the complex generic specialist tier, focusing on enoxaparin with preserved biological activity profiles. These three entities represent distinct competitive vectors: supply chain security, institutional channel dominance, and analytical differentiation.
| Leading Market Players |
|---|
| Aspen Holdings |
| Changzhou Qianhong Bio-Pharma |
| B. Braun Medical Inc. |
| Pfizer Inc. |
| Dr. Reddy's Laboratories Limited |
| Sanofi |
| LEO Pharma A/S |
| Teva Pharmaceutical Industries Ltd |
| Amphastar Pharmaceuticals Inc. |
| Others |
Supply & Pricing Matrix
Crude heparin procurement costs from Shandong and Jiangsu provinces cascade through API manufacturing, formulation finishing, and hospital procurement tiers, with each handoff layering compliance documentation premiums that separate originator from generic pricing bands. Payer rebate structures in United States integrated delivery networks compress margins at the formulary level while rewarding volume commitments that favor suppliers with captive porcine sourcing.
Pricing Analysis
Device safety engineering bundled into pre-filled syringe formats commands premium positioning against unbundled multi-dose vials across Western European hospital networks. Three-tier pricing structure across premium, standard, and economy levels separates safety-engineered combination products with connected health capabilities from basic pre-filled formats and commodity vials. Cost compression in the multi-dose vial tier is intensifying because group purchasing organizations negotiate sole-source contracts with adherence-metric rebates. Ambulatory surgical centers exhibit the highest price sensitivity due to same-day discharge protocols, while interventional cardiology suites in United States academic medical centers accept premium positioning for precise anti-Xa activity profiles.
Supply Chain Analysis
Product returns and temperature excursions in heparin cold-chain logistics create reverse-flow complexity that API manufacturers address through batch-level traceability systems. Supply concentrates in China for crude heparin extraction, the United States for formulation finishing, and Germany for device-integrated safety engineering. Raw material flows draw from porcine intestinal mucosa, pharmaceutical-grade sodium hydroxide, and depolymerization catalysts. Single-source vulnerability in Shandong Province crude heparin clusters exposes the upstream tier to veterinary health events and livestock supply cycles. Distribution runs through hospital purchasing consortia and group purchasing organizations that consolidate procurement authority under pharmacy and therapeutics committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into porcine sourcing and downstream control over hospital formulary placement constitute the decisive competitive race in this market, with NMPA documentation requirements and FDA immunogenicity barriers rewarding players who own both ends of the value chain.
For Market Incumbents: Hedge against direct oral anticoagulant substitution by deepening analytical differentiation in complex generic enoxaparin with preserved biological activity profiles. Secure captive crude heparin supply through acquisition of Shandong or Jiangsu province processing facilities before NMPA qualification timelines extend further. Channel control through exclusive contracts with United States integrated delivery networks protects volume against biosimilar entry. For New Entrants and Emerging Players: Biosimilar analytical platforms with advanced orthogonal molecular weight profiling offer entry leverage into the United States market where FDA immunogenicity testing standards constrain competition. Target Brazilian hospital sector modernization under ANVISA-ICH harmonization as the most penetrable geography, where European and North American suppliers face limited incumbent presence. Pursue partnership pathways with Indian PLI scheme beneficiaries to access Southeast Asian formulation hubs without vertical infrastructure investment. For Investors and Strategic Acquirers: NMPA supplier qualification timeline extensions are the leading indicator that backward integration premiums will widen for non-captive manufacturers across the analysis window. Acquire mid-cap API producers with existing European pharmacopoeia compliance and Shandong province porcine processing capabilities. Monitor EMA MDR surveillance mandate implementation rates in German hospital federations as the signal for safety-engineered device combination product adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crude Heparin Sourcing | NMPA documentation requirements reward captive Shandong and Jiangsu province processing capabilities with 12-18 month qualification advantages. |
| Safety-Engineered Device Combination Development | EMA MDR surveillance mandates accelerate Western European hospital network adoption of needle-stick prevention mechanisms with embedded features. |
| Connected Health Data Capture Integration | United States home healthcare agencies select auto-injector formats with remote monitoring capabilities under Medicare bundled payment models. |
| European Pharmacopoeia Compliance Investment | Chinese API manufacturers pivot certification to secure downstream contracts with German formulation giants demanding real-time supply chain transparency. |
| Hospital System Partnership Consolidation | Group purchasing organization sole-source contracts with adherence-metric rebate structures displace physician preference in United States integrated delivery networks. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs that were cross-validated through primary interviews with hospital procurement managers, formulary directors, regulatory affairs leads at API manufacturers, and GPO contracts specialists. FDA ANDA submission databases, EMA MDR surveillance reports, NMPA crude heparin sourcing documentation requirements, and Chinese customs export records provided quantitative foundations. Bottom-up volume estimates from individual country surgical procedure databases reconciled against top-down pharmaceutical market audits through iterative triangulation.
Product type, therapy area, end user channel, and formulation format were modeled at the country level across the projection horizon, with regional regulatory clusters treated as distinct adoption envelopes. CAGRs derived from logistic curve fitting to historical volume data adjusted for surgical volume rebound trajectories and thrombosis protocol expansion timelines. Anti-Xa activity testing penetration rates and home healthcare channel migration velocities served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including veterinary disease outbreaks affecting porcine supply, abrupt DOAC guideline expansions displacing LMWH indications, and trade policy disruptions affecting Shandong Province API exports. Forecasts reflect documented assumptions about surgical volume recovery persistence and payer cost-containment pressure continuity. Practitioners should monitor NMPA supplier qualification timeline extensions and EMA MDR implementation enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Asia-Pacific Gastrointestinal Drugs Market
Pharmaceuticals
Critical Care Antiarrhythmic Drugs Market
Pharmaceuticals
Mucosolvan (Ambroxol) Market
Pharmaceuticals
North America Travel Vaccines Market
Pharmaceuticals
Efinaconazole Market
Pharmaceuticals
Global Pediatric Drugs Market
Pharmaceuticals
Beta Blockers Market
Pharmaceuticals
Asia-Pacific Contraceptive Drugs and Devices Market
Pharmaceuticals
Japan Diabetes Drugs Market
Pharmaceuticals
Myasthenia Gravis Therapeutics Market
Pharmaceuticals
Naproxen Market
Pharmaceuticals
Global HPMC Capsules Market
Pharmaceuticals
Dystonia Drugs Market
Pharmaceuticals
Hepatitis - B Therapeutics Market
Pharmaceuticals
Fibroblast Growth Factor Receptor Inhibitor Market
Pharmaceuticals
Global Caspofungin Market